
 Windshield Repair Kit Market | 2026-2036
Windshield Repair Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Windshield Repair Kit Market Analytics
The EU Green Deal is decoupling European windshield repair demand from traditional replacement cycles by embedding circular economy mandates into automotive service protocols. Permatex leverages its adhesive chemistry heritage to dominate professional kit formulations across North American auto parts channels. GlasWeld anchors its position through specialized resin injection systems designed for high-volume service center workflows.
Windshield repair kits comprise curated assemblies of UV-curable resins, precision injectors, curing lamps, and surface preparation tools engineered to restore laminated glass structural integrity without full panel replacement. DIY kits command volume leadership through retail accessibility, while professional kits capture margin concentration via calibrated equipment and warranty-backed performance claims. Service centers represent the fastest-growing end user segment as fleet maintenance contracts standardize chip repair protocols.
FDA oversight of UV-curing lamp safety classifications intersects with EPA VOC emission limits to shape resin formulation compliance burdens across US distribution channels. REACH chemical registration requirements in Europe impose substance transparency obligations on adhesive system suppliers seeking CE-marked market access. Stakeholders must track evolving insurance industry loss-cost methodologies, as reimbursement rate adjustments directly alter service center procurement thresholds and consumer price sensitivity.
Market Dynamics
Fleet maintenance contracts are consolidating procurement decisions around standardized chip repair protocols, compressing supplier margins while elevating warranty-backed performance requirements across North American service networks.
Growth Catalysts
- Insurance Deductible Structures:United States policy designs incentivize policyholders toward repair-over-replacement decisions, directly expanding addressable kit demand among collision centers and mobile service operators.
- REACH Chemical Registration:European substance transparency obligations are filtering non-compliant adhesive suppliers from CE-marked distribution channels, creating protected market space for registered formulation providers.
- UV-Curing Lamp Safety Classifications:FDA oversight categories are professionalizing equipment standards across US retail and commercial channels, accelerating replacement cycles for non-compliant legacy systems.
Market Restraints
- Resin Raw Material Volatility:Petrochemical feedstock fluctuations for acrylate and epoxy formulations compress margin predictability for kit assemblers serving price-sensitive DIY segments.
- Supplier Concentration in Adhesive Chemistry:North American professional kit channels depend on a narrow base of specialty chemical providers with captive resin production capabilities.
- Structural Integrity Uncertainty:Repair durability skepticism among certain fleet risk managers limits penetration of high-mileage commercial vehicle contracts despite proven field performance data.
Strategic Opportunities
- EU Green Deal Circular Economy Mandates:Embedded automotive service protocols are decoupling European windshield demand from traditional replacement cycles, expanding preventive repair authorization rates.
- Mobile Service Channel Expansion:On-demand repair platforms are capturing urban commuter convenience preferences, creating direct-to-consumer equipment procurement relationships outside traditional parts distribution.
- Dual Carbon Goals in China:National emission reduction frameworks are elevating repair-over-replacement incentives in provincial vehicle inspection regimes, opening formulation licensing opportunities for compliant suppliers.
Industry Challenges
- Technician Certification Bottlenecks:Insurance-backed warranty programs require documented resin injection competency, constraining service center expansion velocity where training infrastructure lags.
- Cross-Border Formulation Harmonization:Divergent EPA VOC limits and REACH substance restrictions complicate single-SKU strategies for suppliers serving parallel North American and European distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windshield Repair Kit Market |
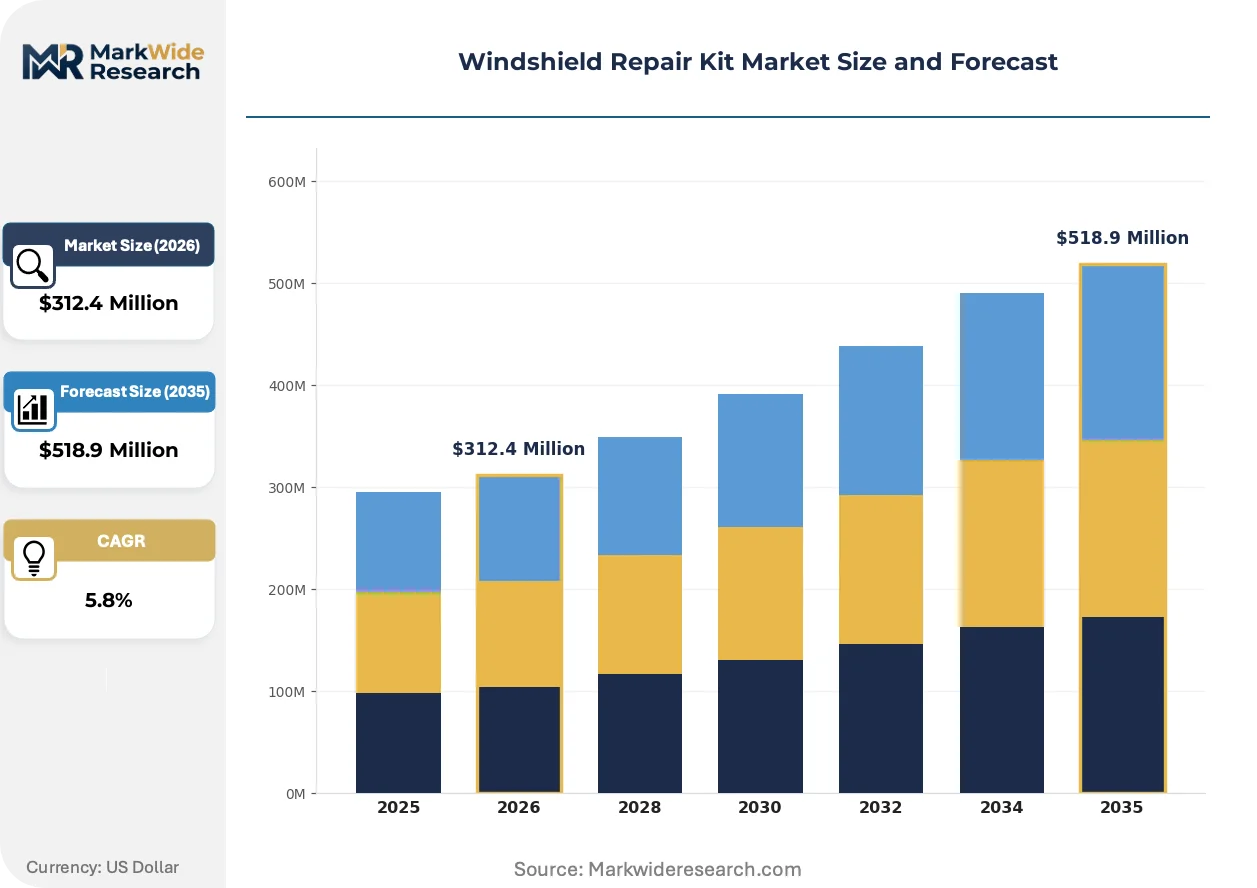
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DIY Kits, Professional Kits, Adhesive Systems, Resin Systems Application: Automobile, Aircraft, Marine, Home End User: Consumers, Service Centers, Fleet Operators, Insurance Companies Distribution Channel: Online Retail, Specialty Stores, Auto Parts Stores, Distributors |
| Companies Covered | 3M Company, Permatex, Rain-X, Blue-Star, GlasWeld, Delta Kits, ITW, ATG GmbH, AEGIS Tool International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windshield Repair Kit Market Evolving Landscape
Portable precision equipment is collapsing the capability gap between professional service centers and advanced DIY users, redistributing repair volume across fragmented channel structures while elevating baseline performance expectations.
LED-based UV curing systems are decentralizing equipment ownership patterns across the windshield repair market. Mobile service operators and high-volume fleet maintenance units are adopting compact, battery-powered curing platforms that eliminate generator dependency. This technology is decentralizing repair execution from fixed bay environments toward roadside and parking-lot service models, compressing response times and expanding addressable incident capture rates.
EPA volatile organic compound emission limits are tightening adhesive formulation standards across US automotive aftermarket channels. Manufacturers must reformulate resin chemistries to maintain cure speed and optical clarity while reducing solvent content. Professional kit suppliers serving insured repair networks face the most acute compliance burdens, as warranty programs require documented formulation certifications that lag regulatory publication cycles by 12-18 months.
Outcome-based performance guarantees are displacing equipment-centric procurement models among national fleet operators. Service contracts now specify minimum clarity retention and crack arrestment rates rather than kit specifications, forcing suppliers to bundle training, consumable replenishment, and quality audit services. This shift is most visible in United States commercial vehicle leasing programs where total cost-per-repair metrics dominate supplier selection criteria.
Windshield Repair Kit Market Segmentation
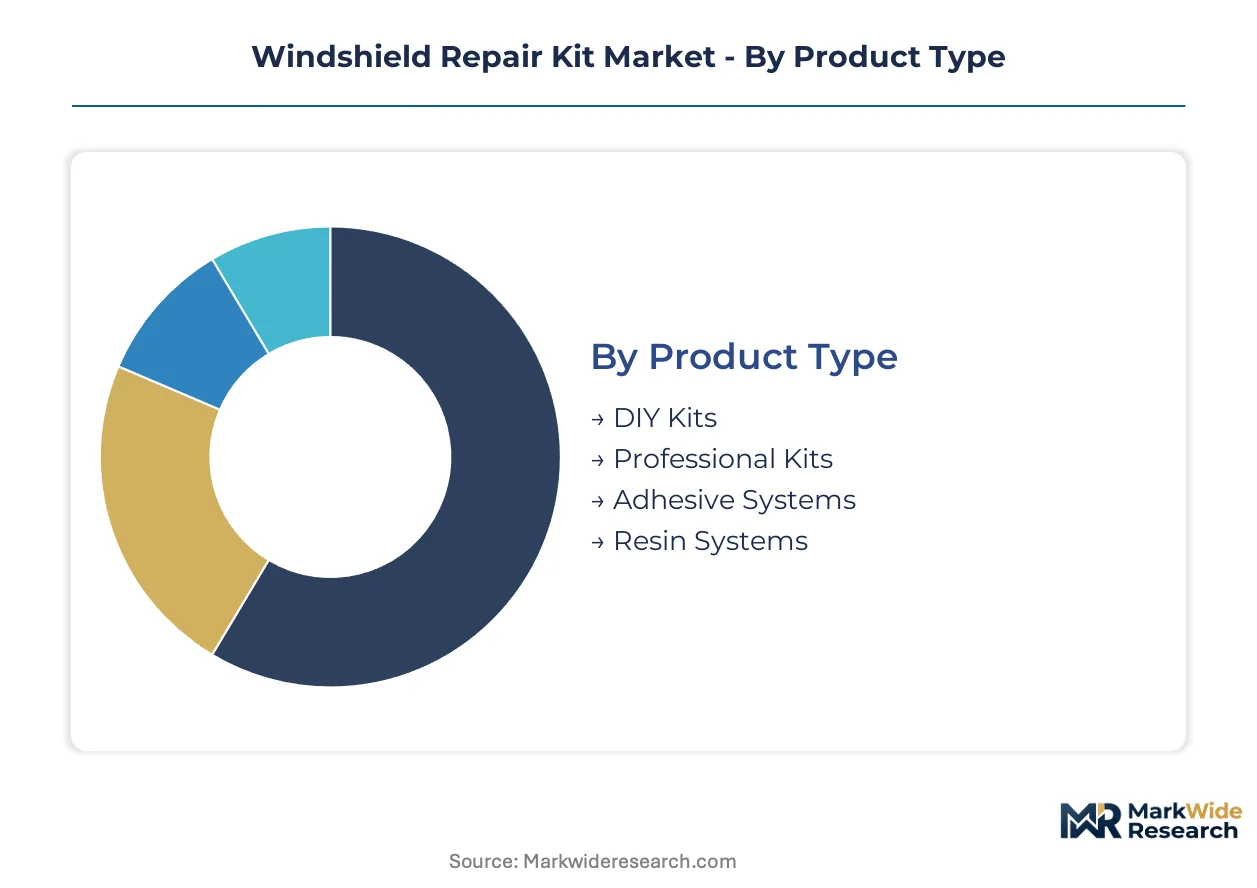
Windshield repair kit segmentation reveals how formulation chemistry, equipment calibration, and procurement authority split demand across divergent price-performance tiers. Technical specifications and channel access patterns determine supplier positioning strategies within each category boundary.
Product Type:
UV-curable resin chemistry and injector precision specifications differentiate kit performance across the price-performance spectrum.
- DIY Kits:Pre-measured resin syringes paired with basic curing films target consumer accessibility over optical precision. Volume concentrates in United States retail auto parts channels where insurance deductible structures drive repair-over-replacement decisions.
- Professional Kits:Vacuum-assisted injection systems with calibrated pressure gauges and high-intensity UV lamps deliver warranty-backed clarity retention. Demand clusters in North American fleet maintenance contracts requiring documented structural integrity compliance.
- Adhesive Systems:Two-part structural bonding agents for edge-seal restoration and delamination repair.
- Resin Systems:Bulk acrylate and epoxy formulations supplied to high-volume service centers with captive mixing equipment.
Mature deployment sits with Professional Kits. Newer deployment is concentrated in Adhesive Systems as edge-seal protocols expand beyond chip repair.
Application:
Glass laminate specifications and regulatory certification requirements fragment demand across mobility modes.
- Automobile:Laminated windshield chip and crack repair dominates kit consumption across passenger and commercial vehicle fleets. United States collision centers represent the primary procurement channel.
- Aircraft:FAA-certified optical clarity standards govern resin selection for cockpit and cabin window restoration. Regulatory burden limits supplier participation to specialty chemical providers with documented aerospace pedigree.
- Marine:Saltwater-resistant formulations address polycarbonate and glass windshield damage in recreational and commercial vessels.
- Home:Architectural glass repair applications extend kit utility beyond mobility contexts.
Volume concentration remains with Automobile. Steepest expansion trajectory appears in Aircraft as maintenance cost pressures intensify.
End User:
Procurement sophistication and warranty liability exposure determine kit specification requirements across buyer types.
- Consumers:Price-sensitive retail purchasers prioritize single-use convenience over optical performance metrics.
- Service Centers:Insured repair networks demand calibrated equipment with batch traceability and technician certification documentation. Fleet maintenance contract consolidation is elevating procurement scale and standardization pressure.
- Fleet Operators:Preventive maintenance program standardization across light commercial vehicle pools is expanding authorized repair protocols.
- Insurance Companies:Loss-cost methodology adjustments directly influence reimbursement rates and service center kit procurement thresholds.
Established procurement discipline sits with Service Centers. Emerging volume concentration is shifting toward Fleet Operators.
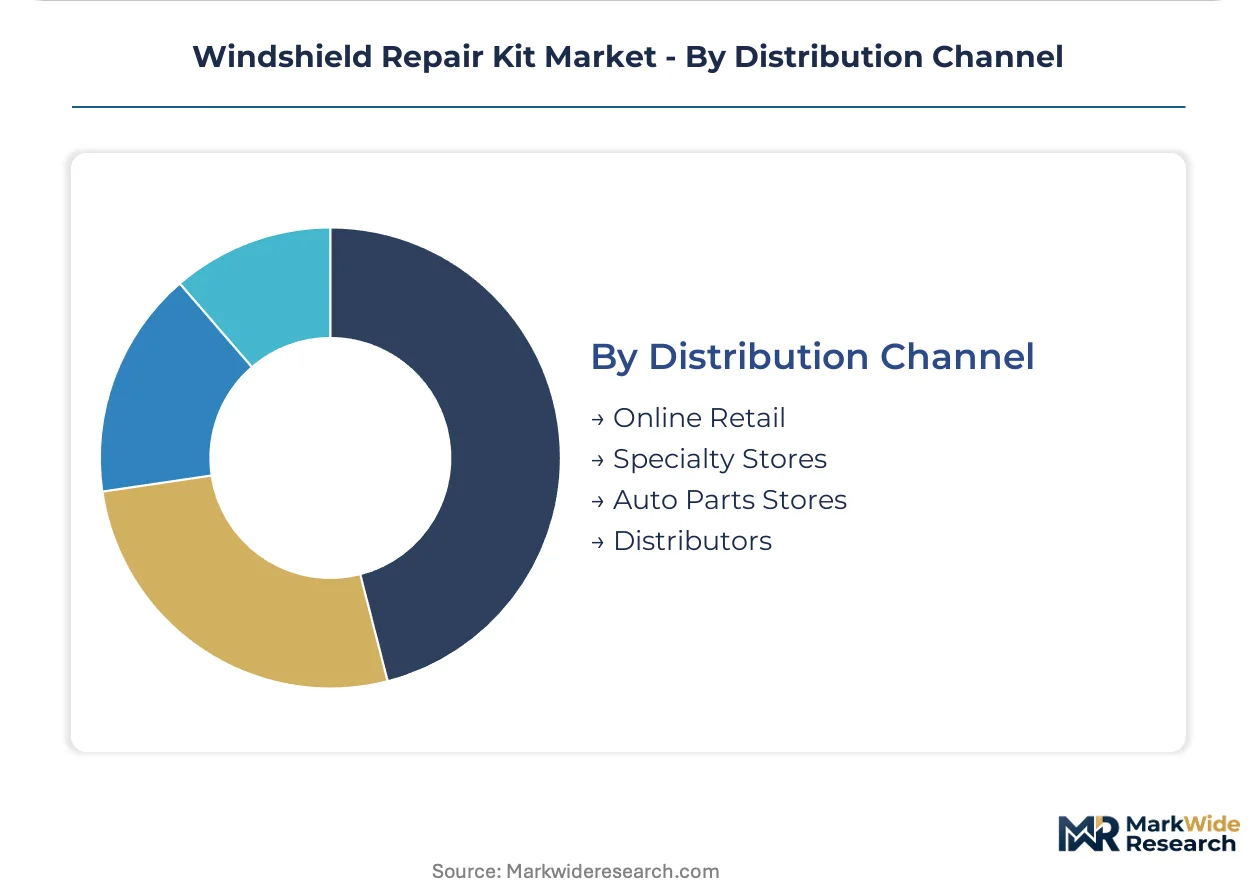
Distribution Channel:
Channel selection determines kit specification transparency and technical support access for end users.
- Online Retail:E-commerce platforms aggregate DIY kit demand through price comparison and review-driven selection.
- Specialty Stores:Dedicated automotive glass retailers provide hands-on equipment demonstration and resin compatibility guidance.
- Auto Parts Stores:Permatex and comparable brands dominate shelf space through adhesive chemistry heritage and channel relationships.
- Distributors:Wholesale networks supply professional kit configurations to service centers with volume pricing and technical training bundles.
Traditional volume sits with Auto Parts Stores. Channel expansion is accelerating through Online Retail as mobile service operators bypass conventional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor anchors North American windshield repair kit procurement through concentrated fleet maintenance operations and collision center networks serving legacy and electric vehicle manufacturers.
United States
Insurance deductible structures and EPA VOC emission limits on automotive adhesives dominate procurement criteria. Fleet operators across Michigan, Ohio, and Texas are standardizing preventive chip repair protocols for light commercial vehicle pools. Chicago and Dallas service centers represent the densest procurement clusters for professional-grade resin injection systems.
Germany
REACH chemical registration requirements and the EU Green Deal's circular economy mandates are reshaping formulation sourcing decisions. KBA vehicle inspection standards increasingly authorize repair-over-replacement for minor windshield damage. Stuttgart and Munich host the highest concentration of specialized automotive glass service networks in Europe.
China
Dual carbon goals and provincial emission reduction frameworks are elevating repair authorization rates in vehicle inspection regimes. MIIT standards for automotive aftermarket chemicals are tightening resin formulation transparency. Shanghai and Guangzhou manufacturing zones supply UV-curable resin components to domestic kit assemblers.
Japan
METI industrial standards for automotive maintenance materials govern professional kit specifications. JIS certification requirements for optical clarity in laminated glass repair limit supplier participation. Nagoya and Osaka metropolitan areas concentrate high-volume fleet maintenance contracts for commercial vehicle operators.
Canada
Health Canada oversight of UV-emitting devices intersects with provincial vehicle safety inspection protocols. PMRA chemical registration requirements for automotive adhesives filter distribution channel access. Ontario's Golden Horseshoe region hosts the densest network of insured repair service centers.
Windshield Repair Kit Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and equipment calibration tiers. The vendor base clusters around three strategic archetypes: adhesive chemistry specialists with heritage automotive channel relationships, precision equipment fabricators serving high-volume service workflows, and diversified industrial conglomerates leveraging cross-sector resin capabilities. Consolidation pressure concentrates among mid-scale kit assemblers lacking captive resin production or certified training infrastructure. Geographic expansion through distributor partnerships and outcome-based service contracting represent the dominant competitive vectors.
Within the adhesive chemistry tier, Permatex anchors North American professional kit distribution through auto parts channel heritage. GlasWeld occupies a position exemplifying specialized resin injection system design for calibrated service center workflows. 3M Company represents diversified industrial capability spanning UV-curable formulations and precision application equipment across multiple regional markets.
| Leading Market Players |
|---|
| 3M Company |
| Permatex |
| Rain-X |
| Blue-Star |
| GlasWeld |
| Delta Kits |
| ITW |
| ATG GmbH |
| AEGIS Tool International |
| Others |
Value Network & Pricing Analysis
Captive resin production among North American specialty chemical providers anchors both supply security and premium pricing power for professional-grade kit suppliers serving insured repair networks.
Pricing Analysis
Outcome-based pricing tied to clarity retention guarantees dominates fleet maintenance contracts, displacing equipment-centric procurement. Three-tier pricing structure across premium, standard, and economy levels separates warranty-backed professional systems from retail DIY kits and bulk resin formulations. Cost compression in DIY segments intensifies because petrochemical feedstock volatility squeezes margin predictability for kit assemblers. Fleet operators exhibit lowest price sensitivity due to total cost-per-repair metrics, while retail consumers drive aggressive price comparison.
Supply Chain Analysis
Single-source vulnerability sits with acrylate monomer suppliers concentrated in Texas and Louisiana petrochemical corridors. Resin formulation draws from epoxy precursors sourced in Germany, Japan, and domestic Gulf Coast facilities. Supply chain risk centers on EPA VOC regulatory lag, where certification documentation trails publication cycles by 12-18 months. Distribution runs through auto parts wholesalers and direct distributor relationships with service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty chemical production capacity constraints prop pricing power for registered formulation providers, insulating compliant suppliers from commodity-tier competition.
For Market Incumbents: Deepen captive resin production capabilities to defend margin position against petrochemical volatility. Secure backward integration into UV-curable monomer supply through long-term offtake agreements with Gulf Coast producers. Prioritize EPA pre-registration documentation to compress certification lag cycles ahead of regulatory publication. For New Entrants and Emerging Players: The price-point gap between premium professional systems and economy DIY kits offers white-space entry through mobile service operator channels. Target on-demand repair platforms in urban commuter corridors where equipment procurement bypasses traditional distribution. Pursue formulation licensing arrangements with established adhesive chemistry providers rather than greenfield resin development. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking automotive aftermarket exposure. Mid-scale kit assemblers lacking certified training infrastructure represent viable targets over a 5-10 year consolidation horizon. Monitor EPA VOC limit publication timing as inflection indicator for compliance-driven valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Gulf Coast petrochemical corridor access secures supply continuity against feedstock volatility. |
| EPA Pre-Certification Investment | Early documentation submission compresses 12-18 month regulatory lag cycles for warranty programs. |
| Mobile Service Channel Partnership | Battery-powered LED curing platforms enable roadside execution outside fixed bay infrastructure. |
| Outcome-Based Service Contracting | Fleet maintenance consolidation demands bundled training, consumables, and quality audit services. |
| REACH Registration Completion | CE-marked market access filters non-compliant competitors from European distribution channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet maintenance directors, collision center procurement managers, adhesive chemistry R&D leads, and auto parts distribution channel heads combined with EPA registration databases, REACH substance inventories, and automotive aftermarket trade statistics. Bottom-up service center demand modeling and top-down resin production capacity assessments provided triangulation.
Data-stream reconciliation across shipment volumes, formulation certifications, and insured repair network procurement records shaped the analytical framework. Segmentation dimensions spanned product type, application, end user, and distribution channel across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating insurance deductible structure changes and fleet maintenance contract standardization trends.
Inputs from EPA pre-registration filings and REACH substance inventories were available through the study window; gaps in proprietary fleet maintenance contract terms introduce uncertainty bands around service center procurement velocity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Europe Ball Bearings Market