
 Crank Trigger System Market | 2026-2036
Crank Trigger System Market Size, Share, and Industry Trends Forecast 2026-2036
Crank Trigger System Market Analytics
Aluminum alloy housings are repositioning crank trigger system economics by replacing heavier cast-iron enclosures in high-RPM applications. Holley Performance Products leverages its vertical integration in ignition electronics to sustain margin control across the racing channel. MSD Ignition anchors its position through manufacturing scale in aftermarket distribution. Denso Corporation competes via technology leadership in Hall Effect sensing architectures for OEM supply contracts.
A crank trigger system is an engine timing device that detects crankshaft position and rotational speed through magnetic, optical, or Hall Effect sensors, typically operating within 0.1-degree accuracy to synchronize fuel injection and ignition events. Its primary purpose is to eliminate timing drift under extreme thermal and vibrational loads in performance and industrial engines. Electronic Trigger systems command the dominant margin pool as OEMs phase out mechanical distributors, while Hall Effect Sensing technology leads growth due to its immunity to oil contamination and temperature fluctuation. Magnetic Trigger configurations remain mature in marine applications where saltwater corrosion resistance outweighs precision requirements. Racing Vehicles application segment concentrates the fastest specification upgrades as sanctioning bodies tighten engine control mandates.
EPA tailpipe regulations and NHTSA engine control mandates in the United States force OEMs to adopt closed-loop timing systems with diagnostic redundancy. EMA in Europe enforces Euro 7 readiness protocols that demand crank position accuracy below 0.05 degrees for real-time emissions calibration. Stakeholders must monitor how MIIT in China integrates crank timing data into vehicle cybersecurity frameworks before committing to platform redesigns.
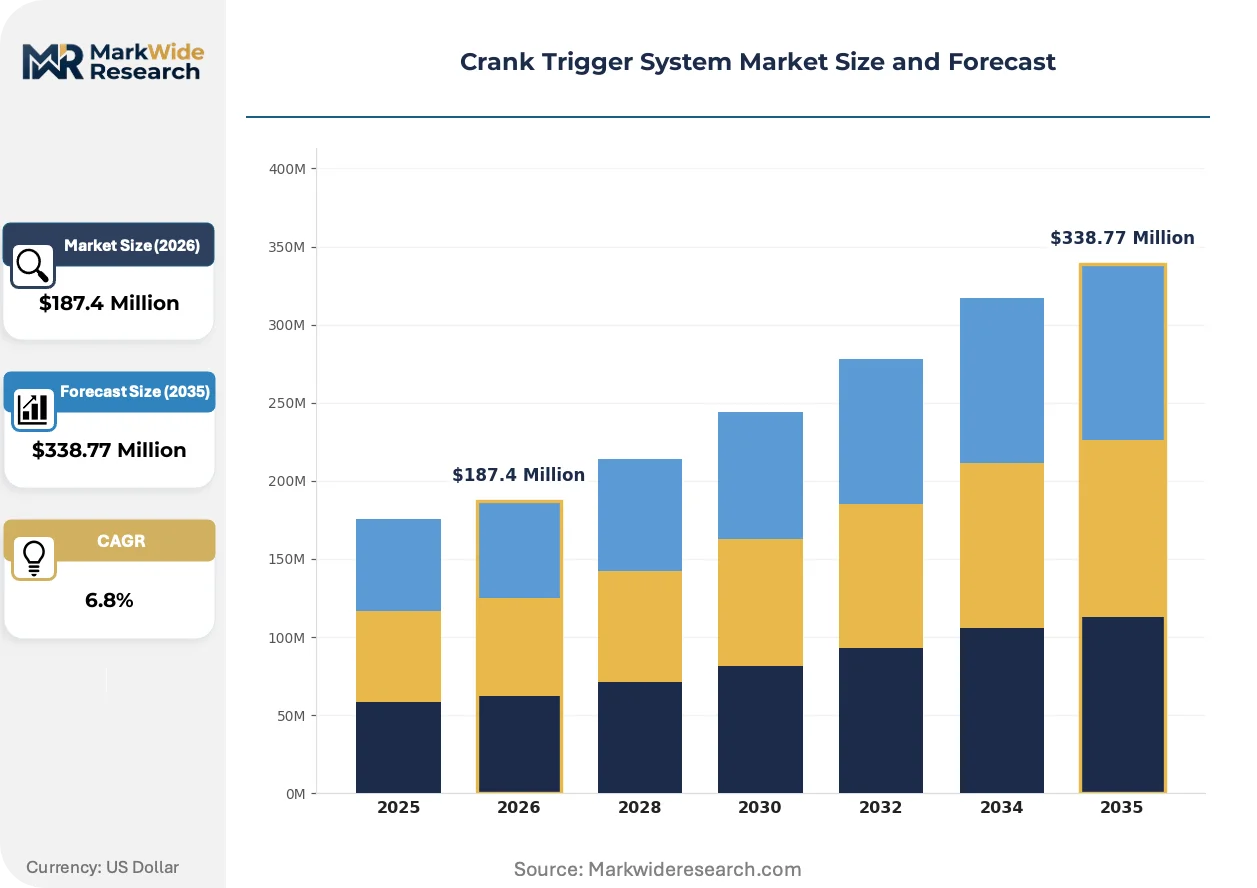
Market Dynamics
The crank trigger system market is undergoing structural recalibration as Hall Effect sensing architectures displace magnetic trigger configurations in high-precision applications, driven by tightening emissions calibration mandates across automotive OEM supply chains.
Growth Catalysts
- EPA Tailpipe Regulations:United States OEMs must achieve closed-loop timing with diagnostic redundancy, forcing wholesale replacement of mechanical distributors in light-duty vehicle platforms.
- Stuttgart Motorsport Cluster:Germany's precision engineering concentration establishes specification benchmarks that cascade into commercial automotive procurement requirements globally.
- Electronic Trigger Systems:These architectures now dominate OEM margin pools as manufacturers phase out distributor-based ignition timing entirely.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and samarium sourcing dependence on Chinese processing infrastructure creates input cost volatility for magnetic trigger manufacturers.
- Euro 7 Readiness Protocols:EMA's sub-0.05-degree accuracy mandates require sensor recalibration infrastructure that smaller aftermarket suppliers cannot fund.
- Optical Sensor Contamination:Oil mist intrusion in high-mileage engines limits optical trigger adoption to controlled-environment industrial applications.
Strategic Opportunities
- MIIT Cybersecurity Integration:China's vehicle cybersecurity frameworks will mandate encrypted crank timing data transmission, opening retrofit markets for authenticated sensor modules.
- Marine Saltwater Applications:Corrosion-resistant magnetic trigger configurations face minimal Hall Effect competition in outboard engine segments.
- Inductive-Hall Hybrid Architectures:Convergence of inductive pickup reliability with Hall Effect precision targets industrial genset applications requiring 50,000-hour maintenance intervals.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time signal processing expertise for 0.1-degree accuracy algorithms concentrates in Stuttgart, Detroit, and Nagoya, limiting supplier scaling.
- ISO 26262 Functional Safety Certification:ASIL-D qualification timelines for crank position sensors extend 18-24 months, delaying platform launches.
- Legacy Engine Control Unit Integration:Backward compatibility with 1990s-era ECU architectures requires analog signal emulation that increases unit cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crank Trigger System Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Trigger, Electronic Trigger, Hybrid Trigger, Magnetic Trigger Application: Automotive Engines, Racing Vehicles, Marine Engines, Industrial Machinery Technology: Optical Sensing, Hall Effect Sensing, Capacitive Sensing, Inductive Sensing End User: OEMs, Aftermarket Providers, Workshops, Motorsport Teams |
| Companies Covered | Holley Performance Products, Chevrolet Performance, Mopar Performance, COMP Performance Group, Moroso Performance Products, MSD Ignition, AEM Electronics, Chongqing Guanglian Qingling Auto Parts, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crank Trigger System Market Evolving Landscape
Sensor fusion architectures and materials substitution are compressing traditional technology lifecycles, while regulatory precision mandates accelerate specification turnover across OEM and aftermarket channels.
Aluminum alloy housings are electrifying crank trigger system economics by replacing cast-iron enclosures in high-RPM racing applications. NASCAR and Formula 1 teams have adopted these lightweight configurations since 2022. This materials shift is electrifying supplier margin structures and enabling sensor packaging density previously impossible with ferrous housings.
EMA's Euro 7 readiness protocols now mandate crank position accuracy below 0.05 degrees for real-time emissions calibration. This precision floor eliminates magnetic trigger systems from new European passenger vehicle platforms. OEMs in Germany, France, and Italy are responding by consolidating Hall Effect supplier contracts with firms holding captive semiconductor fabrication.
Fleet operators now specify outcome-based sensor lifecycle contracts rather than unit procurement, unbundling hardware from predictive maintenance analytics. Commercial vehicle leasing channels in the United States are adopting this model fastest. This restructuring concentrates buying power with telematics-integrated suppliers and marginalizes pure hardware vendors.
Crank Trigger System Market Segmentation
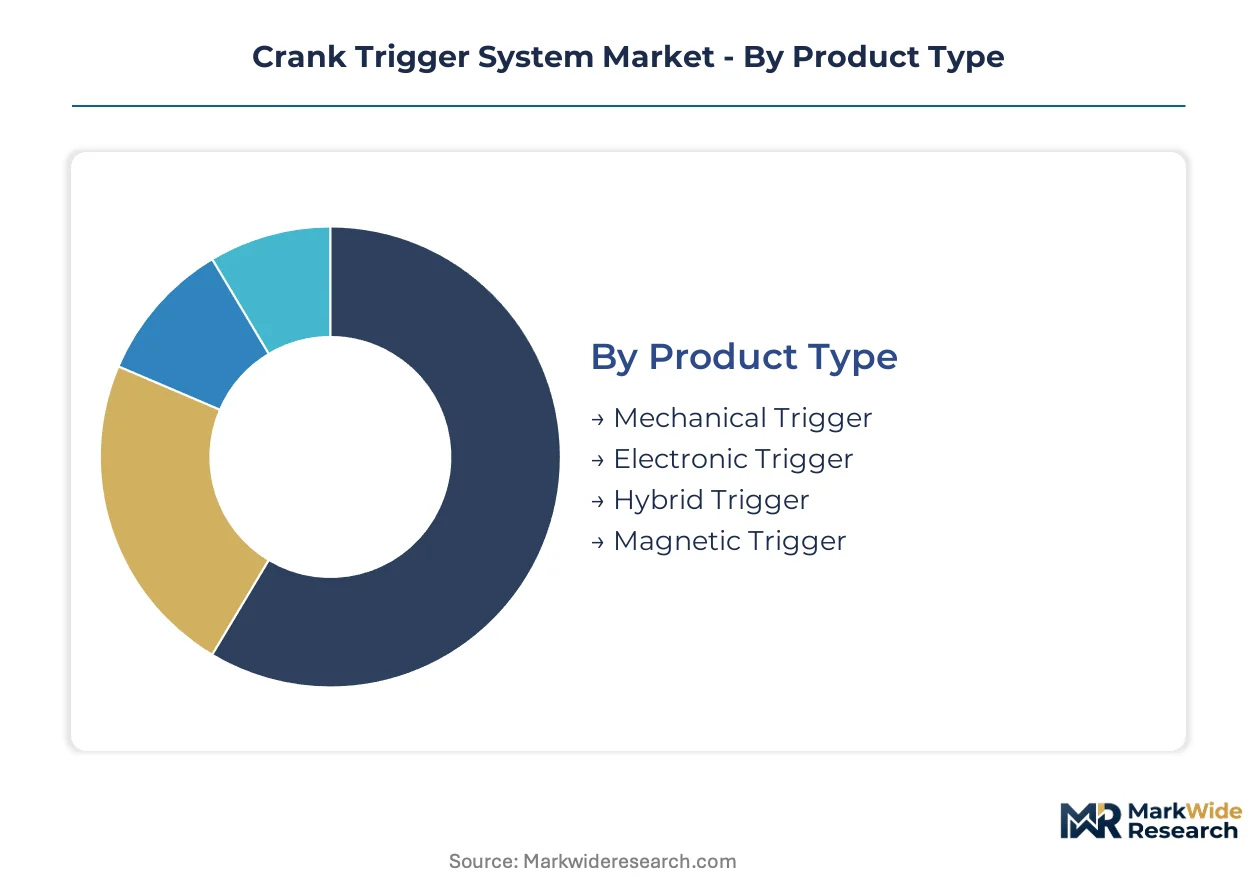
Crank trigger system procurement splits across four distinct dimensions, each governing different margin structures and certification requirements. Product type determines semiconductor content and firmware complexity. Application dictates thermal tolerance specifications and warranty terms. Technology selection locks in contamination immunity profiles. End user category governs volume pricing and technical support intensity.
Product Type:
Electronic Trigger architectures demand the heaviest upfront capital commitment due to ASIC development and ISO 26262 qualification infrastructure. Mechanical Trigger configurations require minimal R&D fixed costs but face declining OEM procurement volumes.
- Electronic Trigger:Solid-state architectures with embedded signal processing eliminate mechanical wear entirely. OEMs in Germany and the United States concentrate procurement here as EPA and Euro 7 mandates phase out distributor-based ignition systems entirely.
- Hybrid Trigger:Combines redundant magnetic pickup with electronic conditioning circuits for fail-safe operation. Motorsport teams in Stuttgart specify these for endurance racing where single-point sensor failure terminates competition.
- Mechanical Trigger:Legacy distributor-derived architectures with contact-breaker or optical interruption mechanisms. Remains viable only in vintage vehicle restoration channels with minimal firmware requirements.
- Magnetic Trigger:Variable reluctance sensors detecting ferrous target wheel disturbances. Marine engine manufacturers favor these for saltwater corrosion resistance despite lower precision ceilings.
Most installed capacity flows through Electronic Trigger. Expansion is steepest in Hybrid Trigger.
Application:
Volume concentration and specification stringency diverge sharply across use cases, with racing applications demanding sub-0.05-degree accuracy while industrial machinery prioritizes maintenance interval extension.
- Racing Vehicles:Sanctioning bodies mandate encrypted crank position data with tamper-evident logging. Formula 1 and NASCAR procurement in the United States drives specification cascades into commercial automotive channels.
- Automotive Engines:Light-duty and heavy-duty OEM platforms require diagnostic redundancy for OBD-II compliance. Production volumes here absorb Hall Effect sensor foundry capacity in Japan and Germany.
- Marine Engines:Outboard and inboard configurations face salt spray and galvanic corrosion exposure. Magnetic trigger configurations dominate as Hall Effect packaging struggles with sealing cost targets.
- Industrial Machinery:Genset and compressor applications specify 50,000-hour maintenance intervals. Inductive sensing architectures with passive component reliability satisfy these lifecycle requirements.
Automotive Engines absorbs the largest unit volumes. Racing Vehicles posts the steepest specification upgrade frequency.
Technology:
Semiconductor process node requirements and signal conditioning complexity separate high-investment architectures from commodity sensor categories.
- Hall Effect Sensing:Monolithic integration of magnetic field detection and temperature compensation on single die. OEMs in France and Italy consolidate supplier contracts with captive semiconductor fabrication for Euro 7 compliance.
- Inductive Sensing:Passive coil architectures requiring no active electronics at the sensing element. Industrial genset manufacturers specify these for electromagnetic immunity in high-voltage environments.
- Optical Sensing:LED-photodiode pairs detecting slotted or coded target wheels. Oil mist intrusion limits adoption to sealed industrial enclosures with controlled atmospheres.
- Capacitive Sensing:Electrode arrays detecting metallic target proximity through dielectric variation. Emerging in electric vehicle motor position sensing where magnetic interference from high-current cables corrupts Hall Effect signals.
Hall Effect Sensing commands dominant OEM procurement share. Capacitive Sensing gains share fastest in electrified powertrain applications.
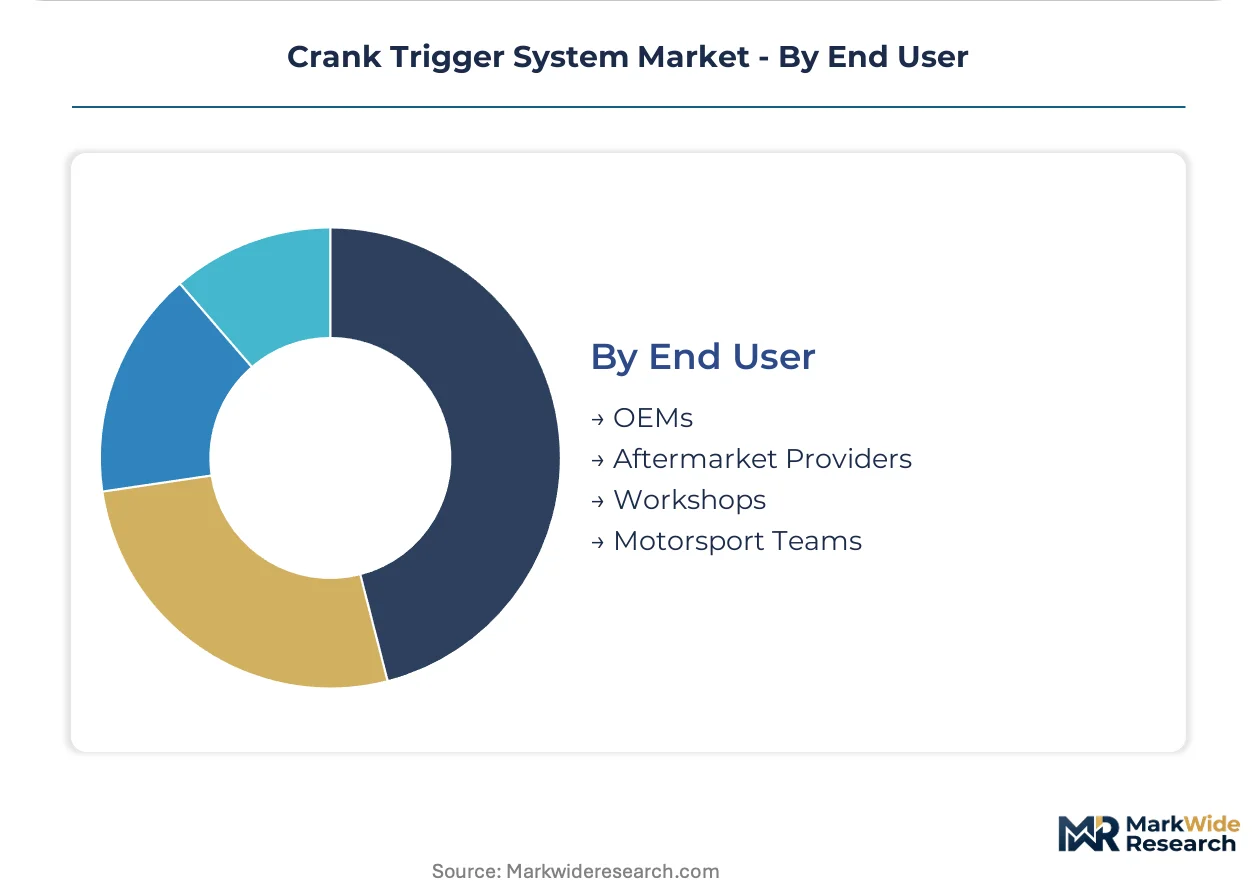
End User:
Technical support intensity and contract structure vary from multi-year platform supply agreements to transactional workshop procurement.
- OEMs:Platform-integrated supply with 10-year part availability guarantees. NHTSA and EMA regulations mandate diagnostic traceability throughout vehicle lifecycle.
- Motorsport Teams:Custom calibration services with trackside engineering support. Stuttgart-based engineering clusters concentrate specification-setting for high-performance trigger technologies.
- Aftermarket Providers:Catalog distribution through performance retail channels. Requires backward compatibility with 1990s-era ECU architectures driving analog signal emulation costs.
- Workshops:Diagnostic-driven replacement of failed sensors with minimal technical specification. Price sensitivity here marginalizes suppliers lacking scale economies.
OEMs absorb the majority of production volume. Motorsport Teams drive the fastest specification turnover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's motorsport engineering cluster establishes specification benchmarks that cascade into commercial automotive procurement requirements across multiple continents. Crank trigger system demand concentrates in Germany, the United States, Japan, China, and Italy, each governed by distinct regulatory frameworks and industrial specializations.
United States
EPA tailpipe regulations and NHTSA engine control mandates force OEMs to adopt closed-loop timing systems with diagnostic redundancy. The country's national automotive safety regulator requires wholesale replacement of mechanical distributors in light-duty vehicle platforms. Detroit's automotive engineering base absorbs Hall Effect sensor foundry capacity for OBD-II compliance.
Germany
EMA enforces Euro 7 readiness protocols demanding crank position accuracy below 0.05 degrees for real-time emissions calibration. Stuttgart's precision engineering concentration drives specification-setting for high-performance trigger technologies that penetrate commercial channels. Bavaria-based suppliers consolidate captive semiconductor fabrication for OEM supply contracts.
Japan
METI industrial policy prioritizes semiconductor process node advancement for automotive sensor applications. The country's national standards body mandates electromagnetic compatibility testing that favors monolithic Hall Effect integration. Nagoya's automotive supplier cluster specializes in temperature compensation algorithms for extreme thermal environments.
China
MIIT vehicle cybersecurity frameworks will mandate encrypted crank timing data transmission, opening retrofit markets for authenticated sensor modules. The ministry's dual carbon goals accelerate electrified powertrain development where capacitive sensing architectures gain share. Chongqing's automotive parts manufacturing base expands domestic sourcing for magnetic trigger configurations.
Italy
EMA Euro 7 protocols eliminate magnetic trigger systems from new passenger vehicle platforms through sub-0.05-degree precision mandates. The country's national automotive engineering cluster in Turin and Modena concentrates motorsport specification development. Northern Italian suppliers specialize in hybrid trigger architectures for endurance racing applications.
Crank Trigger System Market Competitive Landscape
Global majors compete with regional champions across technology licensing and semiconductor fabrication capacity. The supplier base stratifies into three tiers: integrated ignition electronics manufacturers, specialized sensor fabricators, and catalog distributors serving aftermarket channels. Strategic archetypes include vertically integrated performance brands, captive semiconductor foundries, and telematics-integrated fleet service providers. Competitive moves concentrate on backward integration into ASIC design and geographic expansion through motorsport engineering partnerships.
Among performance-oriented manufacturers, Holley Performance Products exemplifies vertical integration in ignition electronics, while MSD Ignition anchors scale-driven aftermarket distribution. Denso Corporation occupies a position representing technology leadership in semiconductor-intensive sensing architectures for OEM supply contracts. These three players illustrate how supplier positioning diverges across racing, aftermarket, and platform-integrated procurement channels.
| Leading Market Players |
|---|
| Holley Performance Products |
| Chevrolet Performance |
| Mopar Performance |
| COMP Performance Group |
| Moroso Performance Products |
| MSD Ignition |
| AEM Electronics |
| Chongqing Guanglian Qingling Auto Parts |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
EMA's sub-0.05-degree accuracy mandates for Euro 7 compliance are forcing OEM procurement teams to consolidate supplier contracts with Hall Effect foundry operators, compressing magnetic trigger margins while amplifying pricing power for semiconductor-integrated architectures.
Pricing Analysis
Input-cost pass-through from rare earth magnet volatility and ASIC fabrication capacity constraints shapes tiered pricing across the market. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified modules from diagnostic-redundant configurations and basic aftermarket replacements. Pricing pressure stems from neodymium supply concentration in Chinese processing infrastructure, with cost compression running through magnetic trigger tiers. Aftermarket workshops exhibit highest price sensitivity, while OEM platform engineers prioritize certification grade over unit cost.
Supply Chain Analysis
ISO 26262 ASIL-D qualification timelines gating supplier access concentrate Hall Effect die fabrication in Germany, Japan, and the United States. Raw material flows draw from Taiwanese semiconductor foundries, Chinese rare earth processing facilities, and Bavarian precision machining clusters. Single-source vulnerability in neodymium supply creates exposure to export restriction shocks. Distribution runs through Tier 1 supplier integration with OEM platform engineering teams, bypassing traditional component wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA precision mandates in Europe command 40-60% pricing premiums over EPA-compliant configurations in the United States, rewarding suppliers with dual-certification capacity.
For Market Incumbents: Hedge against Hall Effect commoditization by securing captive semiconductor fabrication in Stuttgart or Nagoya clusters. Defensive consolidation through backward integration into ASIC design eliminates foundry margin extraction, while channel control via trackside engineering contracts with motorsport teams insulates specification-setting authority from emerging sensor fusion competitors. For New Entrants and Emerging Players: Begin with authenticated sensor modules targeting MIIT cybersecurity retrofit demand in China's Chongqing automotive base, where domestic sourcing requirements favor local assembly partnerships. Marine magnetic trigger applications face minimal Hall Effect competition due to saltwater sealing cost thresholds, offering the most penetrable segment for inductive sensing specialists without semiconductor fab investments. For Investors and Strategic Acquirers: Asymmetric upside sits with telematics-integrated fleet service providers unbundling hardware from predictive maintenance analytics. Long-term viability favors acquisition targets holding embedded firmware talent for real-time signal processing alongside ISO 26262 qualification infrastructure. Watch for inflection when commercial vehicle leasing channels in the United States convert majority procurement to outcome-based lifecycle contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | ASIL-D qualification timelines extend 18-24 months, locking OEM supply relationships. |
| Motorsport Engineering Partnership | Stuttgart cluster specifications cascade into commercial automotive procurement requirements globally. |
| Telematics Integration Development | Fleet operators now specify outcome-based contracts separating hardware from analytics. |
| Cybersecurity Module Authentication | MIIT frameworks mandate encrypted crank timing data transmission in Chinese vehicles. |
| Hybrid Trigger Architecture R&D | Inductive-Hall convergence targets industrial genset 50,000-hour maintenance intervals. |
Research Methodology
Coverage spans Germany, the United States, Japan, China, and Italy, with primary inputs from each market combining interviews with OEM platform engineers, Tier 1 supplier procurement leads, motorsport calibration specialists, and aftermarket distribution managers. Secondary validation draws from EPA enforcement actions, EMA technical documentation, MIIT cybersecurity draft protocols, METI industrial policy filings, and vehicle production registration databases. Bottom-up sensor unit demand triangulates against top-down OEM platform content analysis.
Granularity-level modeling disaggregates volume and value across product type, application, technology, and end user dimensions, with additional segmentation by regional regulatory cluster and certification tier. CAGRs derive from unit shipment trajectories applied to semiconductor content value per module. Forecast inputs incorporate Euro 7 readiness protocol implementation timing, EPA tailpipe regulation enforcement intensity, and electrified powertrain sensor architecture displacement curves.
Several conditions sit outside the modeled scope, including unannounced regulatory precision threshold revisions, rare earth export restriction events, and breakthrough capacitive sensing cost reductions. Forecasts reflect documented assumptions regarding OEM platform redesign cycles and motorsport specification cascade velocity. A model refresh is warranted upon material change in EMA Euro 7 final technical specifications or MIIT cybersecurity framework ratification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive AHSS Market