
 Camphor Market | 2026-2036
Camphor Market Size, Share, and Industry Trends Forecast 2026-2036
Camphor Market Intelligence
The European Union's REACH regulation, which governs the registration and evaluation of chemical substances, is shifting sourcing preferences towards well-documented and sustainably produced camphor. Mangalam Organics Ltd. leverages its integrated production of terpene chemicals to supply both natural and synthetic grades. Meanwhile, Fujian Green Pine Co., Ltd. dominates the global synthetic camphor supply chain through its massive production scale. Kanchi Karpooram Ltd. specializes in producing camphor for the pharmaceutical and spiritual ritual segments in India.
Camphor is a waxy, flammable, white or transparent solid with a strong aromatic odor, chemically classified as a bicyclic monoterpene ketone. It is derived either from the wood of the camphor laurel tree or synthesized from turpentine oil, serving primarily as a plasticizer, topical medication, and fragrance component. The pharmaceutical application segment commands a significant share, driven by camphor's use in topical analgesics and cold remedies. While synthetic camphor leads in volume due to cost-effectiveness, the natural camphor product type is gaining traction in high-value cosmetics and personal care products.
Regulatory oversight from bodies like the US FDA and the European Medicines Agency (EMA) dictates purity standards for pharmaceutical-grade camphor. In India, the FSSAI also regulates its use as a flavoring agent, imposing limits on concentration in food products. Navigating the cost-performance trade-off between natural and synthetic camphor sources will be a central strategic decision for manufacturers and end-users.
Market Dynamics
The central tension shaping the camphor market is the divergence between the high-volume, cost-driven synthetic supply chain and the value-driven demand for sustainably sourced natural camphor. This is amplified by regulatory frameworks like the EU's REACH, which prioritize chemical transparency and favor well-documented, bio-based alternatives. This dynamic forces a strategic choice between scale-based cost leadership and certification-based value differentiation.
Growth Catalysts
- Pharmaceutical Formulations:Expanding use in topical analgesics, balms, and cold remedies, particularly for over-the-counter products, provides a stable demand base for pharmaceutical-grade camphor.
- Bio-Based Chemical Policies:Government frameworks, including the EU Green Deal, promote a circular bioeconomy, creating favorable conditions and potential incentives for producers of natural camphor derived from renewable resources.
- Cultural Demand in India:The extensive and consistent use of camphor in Hindu spiritual rituals in India creates a large, non-discretionary demand segment, complementing its use in the domestic pharmaceutical industry.
Market Restraints
- Feedstock Price Volatility:The cost of synthetic camphor is directly tied to the price of turpentine oil, a byproduct of the pulp industry, exposing producers to price fluctuations outside their control.
- Synthetic Supply Concentration:The global supply of synthetic camphor is heavily concentrated in China, creating potential bottleneck risks and price sensitivity related to the country's domestic industrial policies.
- Stringent Purity Regulations:Regulatory bodies like the US FDA and European Medicines Agency impose strict purity and documentation requirements for pharmaceutical-grade camphor, acting as a barrier for non-compliant suppliers.
Strategic Opportunities
- High-Value Cosmetics:Natural camphor is finding new applications in premium cosmetics and personal care products, where its aromatic properties and "clean label" appeal can command higher price points. -
- Geographic Expansion in Wellness:Markets in Southeast Asia and Latin America with growing middle-class populations and an interest in natural wellness products represent an untapped opportunity for natural camphor applications. -
- Certified Sustainable Sourcing:Obtaining and marketing certifications for organic, fair-trade, or sustainably harvested natural camphor offers a clear path to differentiate products and capture environmentally conscious buyers.
Industry Challenges
-
-
- Navigating Grade-Specific Compliance:Manufacturers face the operational complexity of meeting distinct purity, testing, and labeling standards for different end markets, including pharmaceutical (USP), food (FSSAI), and industrial grades. -
- Cost-Performance Balancing Act:End-users, particularly in industrial applications like plastics, must constantly evaluate the cost-performance trade-off between cheaper synthetic grades and superior-fragrance natural grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camphor Market |
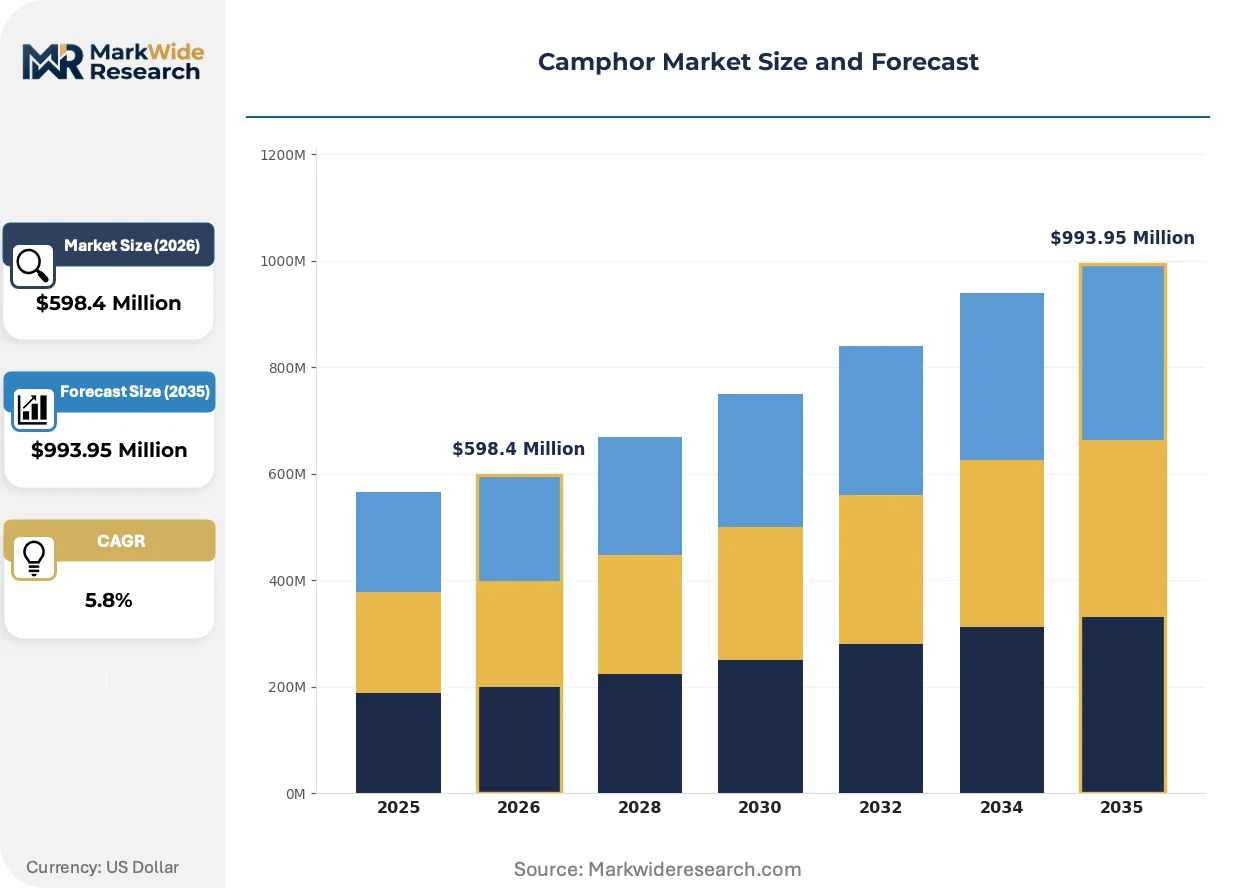
| Market Size in 2026 | $598.4 Million |
| Market Size in 2035 | $993.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Camphor, Synthetic Camphor, Blended Camphor, Microcrystalline Camphor Application: Pharmaceuticals, Cosmetics, Pest Control, Flavoring Agents, Spiritual Rituals End User: Pharmaceutical Companies, Personal Care Manufacturers, Agriculture Providers, Religious Institutions Packaging Type: Bulk Bags, Retail Packs, Sachets, Bottles, Blister Packs |
| Companies Covered | Kanchi Karpooram Ltd., Taiwan Tekho Camphor Co., Ltd., Saptagir Camphor Ltd., Uttam Exports Corporation, Camphor & Allied Products Ltd., Mangalam Organics Ltd., Fujian Green Pine Co., Ltd., Arora Aromatics Pvt. Ltd., Oriental Aromatics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camphor Market Strategic Shifts & Innovations
A fundamental re-evaluation of chemical sourcing is underway, driven by a convergence of technological capability and regulatory pressure for greater sustainability. This shift is redefining value, moving it from pure cost-efficiency towards lifecycle transparency. The market is adapting to a future where a product's origin story is as important as its chemical purity.
Technology and Product Evolution
Advanced terpene chemistry provides the foundation for producing high-purity synthetic camphor from turpentine oil. Chemical manufacturers are adopting more efficient catalytic processes to improve yields and reduce waste. This refined synthetic production is converging with emerging bio-fermentation techniques, which use engineered microbes to produce nature-identical camphor, blurring the traditional lines between natural and synthetic sources.
Regulatory and Policy Shift
The European Union's REACH regulation mandates comprehensive registration, evaluation, and authorization for all chemical substances manufactured or imported into the EU. This policy increases the administrative and testing burden for all camphor suppliers, regardless of origin. It particularly affects non-EU producers of synthetic camphor, forcing them to invest in extensive data generation to maintain market access and favoring suppliers with pre-existing robust safety dossiers.
Demand-Side and Behavioral Shift
End-user preference in consumer-facing segments is increasingly influenced by product certifications that validate sustainability claims. This disrupts traditional procurement models based solely on price and purity, elevating the importance of supply chain transparency. The trend is most visible in the North American and European cosmetics and personal care sectors, where brands use certifications like ECOCERT or USDA Organic to appeal to environmentally conscious consumers.
Camphor Market Segmentation
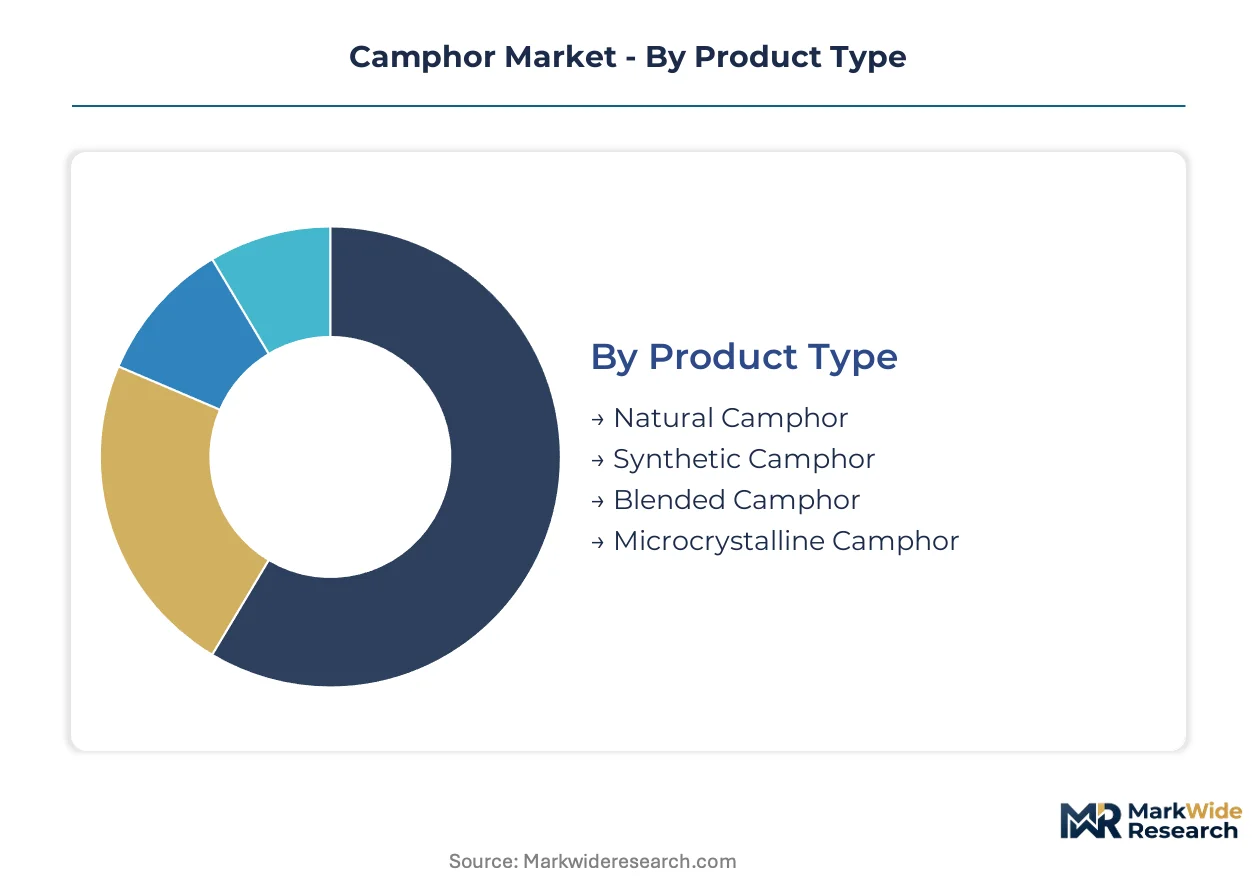
The camphor market exhibits distinct segmentation based on its chemical composition, intended application, end-user profile, and packaging format. Understanding these divisions reveals specific demand drivers and regulatory influences shaping procurement and consumption patterns across various industries.
Product Type:
Camphor's fundamental chemical structure and origin determine its product type segmentation, influencing purity, cost, and end-use suitability.
- Natural Camphor:Derived from the camphor laurel tree, it is a bio-based bicyclic monoterpene ketone, often perceived as premium. Demand concentrates in high-value cosmetics and personal care sectors, driven by "clean label" consumer preferences in North America.
- Synthetic Camphor:Synthesized from turpentine oil through advanced terpene chemistry, offering a cost-effective alternative with consistent purity. Volume demand is high in industrial applications like plastics, primarily due to its lower production cost and scalability.
- Blended Camphor:This product type combines natural and synthetic forms to balance cost-effectiveness with specific functional properties or aromatic profiles.
- Microcrystalline Camphor:Processed into fine crystalline powder, this form enhances dissolution and surface area for specific pharmaceutical and cosmetic preparations.
Mature deployment sits with Synthetic Camphor. Newer deployment is concentrated in Natural Camphor.
Application:
The diverse functional properties of camphor drive its segmentation across various end-use applications, each demanding specific purity and form.
- Pharmaceuticals:Utilized as an active pharmaceutical ingredient in topical analgesics, anti-itch creams, and decongestant balms. Demand is stable for over-the-counter cold remedies and muscle pain relief, particularly in the US and Europe, driven by regulatory approval.
- Spiritual Rituals:Consumed as a combustible offering or symbolic element in religious ceremonies, particularly within Hinduism. This segment generates significant non-discretionary volume in India, driven by deep cultural and religious traditions.
- Cosmetics:Incorporated into skincare products and fragrances for its aromatic and cooling properties, appealing to premium segments in Europe.
- Pest Control:Functions as a natural insect repellent and moth deterrent in household and agricultural settings, particularly in tropical regions.
- Flavoring Agents:Used in small concentrations to impart a distinctive taste and aroma in certain food products, regulated by bodies like India's FSSAI.
Pharmaceuticals exert significant influence on purity standards. Spiritual Rituals drive consistent volume demand in specific geographies.
End User:
Differentiation in end-user categories reflects specialized procurement needs and product specifications across industrial and institutional buyers.
- Pharmaceutical Companies:These entities procure pharmaceutical-grade camphor, requiring strict adherence to pharmacopoeial standards like USP and European Pharmacopoeia. Procurement patterns are dictated by batch consistency and rigorous regulatory compliance for their drug formulations.
- Religious Institutions:These organizations purchase camphor for ceremonial use, prioritizing purity and traditional sourcing for spiritual practices. Demand remains steady in India, driven by consistent cultural practices and community engagement.
- Personal Care Manufacturers:Integrate camphor into lotions, balms, and fragrances, seeking specific aromatic profiles and skin benefits for consumer products.
- Agriculture Providers:Utilize camphor in certain pest deterrent formulations for crop protection and storage, particularly in developing economies.
Procurement complexity is highest for Pharmaceutical Companies. Personal Care Manufacturers prioritize aesthetic and functional integration.
Packaging Type:
Packaging solutions for camphor vary significantly, optimizing for volume, shelf-life, and consumer convenience across diverse distribution channels.
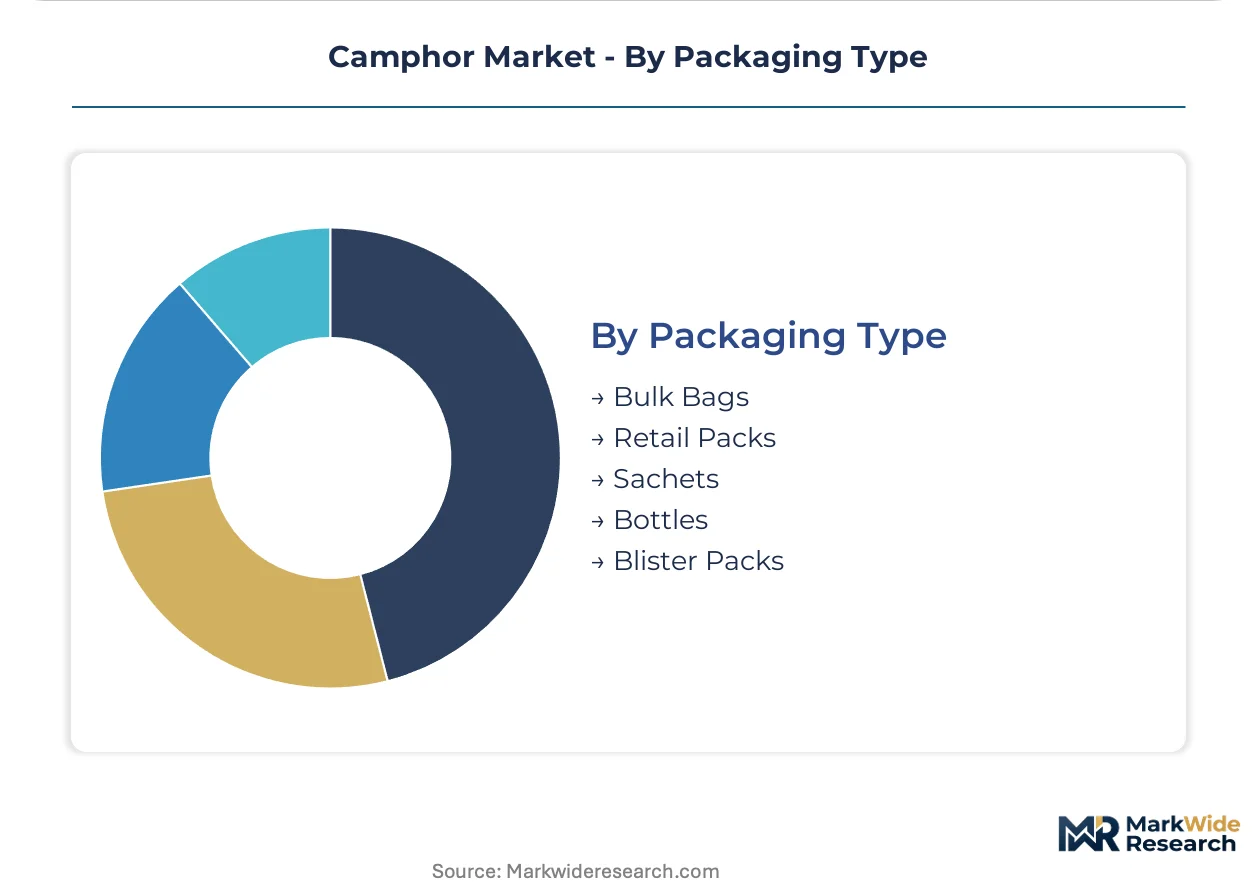
- Bulk Bags:Large-format packaging designed for industrial clients, facilitating efficient transport and storage of high volumes. Pharmaceutical companies and large-scale manufacturers procure camphor in bulk to minimize per-unit costs.
- Retail Packs:Smaller, consumer-oriented packaging formats, including boxes or small containers, designed for direct sale. These cater to individual consumers for household or personal use, driven by accessibility and brand visibility in countries like India.
- Sachets:Small, single-use pouches, often for individual portions or specific ritualistic applications, common in Asian markets.
- Bottles:Typically used for liquid camphor products or larger quantities of solid camphor in consumer markets, offering resealability.
- Blister Packs:Common for pharmaceutical-grade camphor tablets or small, precise doses, ensuring product integrity and tamper-evidence for medical applications.
Bulk Bags serve industrial supply chains. Retail Packs expand camphor's reach into consumer households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai, India, represents a significant hub for camphor trade, driven by extensive domestic demand for spiritual rituals and pharmaceutical applications. The global camphor market navigates diverse regional dynamics. Regulatory frameworks across key consumption zones influence sourcing preferences and product specifications.
India
India exhibits robust demand for camphor, driven by its expansive pharmaceutical industry and deeply ingrained spiritual practices. The FSSAI imposes limits on camphor concentration in food products, ensuring consumer safety. Chennai, a prominent industrial hub, supports a concentrated network of camphor manufacturers and suppliers serving both local and international needs.
China
China's market is characterized by its massive synthetic camphor production, primarily for industrial applications and global export. Domestic industrial policies in China significantly impact the global availability and pricing of synthetic camphor. Fujian province, with its large chemical manufacturing base, serves as a critical epicenter for synthetic camphor manufacturing.
United States
The United States generates substantial demand for camphor in pharmaceutical formulations and premium cosmetic products. The US FDA enforces stringent purity and documentation requirements for all pharmaceutical-grade camphor imports. New Jersey's pharmaceutical manufacturing corridor actively procures high-purity camphor for its diverse range of over-the-counter remedies.
Germany
Germany represents a key European market for camphor, particularly in pharmaceutical-grade applications and high-end personal care products. The EU's REACH regulation influences sourcing preferences towards well-documented and sustainably produced camphor. Bavaria's chemical industry cluster actively seeks compliant and traceable camphor for its diverse manufacturing processes.
Japan
Japan maintains consistent demand for camphor within its pharmaceutical sector and for specialized fragrance applications. Japanese pharmacopoeial standards govern the quality and purity of medicinal camphor products. Osaka, a prominent center for chemical and pharmaceutical innovation, utilizes high-purity camphor in its advanced product development.
Camphor Market Key Industry Players
The competitive structure tilts toward a tiered system, encompassing large-scale synthetic producers and specialized natural camphor suppliers. The market exhibits a clear segmentation between cost-driven volume players, who prioritize efficiency, and value-driven differentiation specialists, who focus on purity and sustainability. Strategic archetypes include integrated chemical manufacturers with diverse product portfolios and regional suppliers deeply embedded in ritual-focused segments. Capacity expansion in synthetic production and certified sustainable sourcing are dominant competitive moves shaping the market.
At the scale-driven end, Fujian Green Pine Co., Ltd. exemplifies a major global synthetic camphor supplier, leveraging massive production capabilities to serve industrial markets worldwide with cost-effective solutions. Mangalam Organics Ltd. represents an integrated producer of terpene chemicals, offering both natural and synthetic grades, thereby catering to a broad spectrum of end-user requirements across different value propositions. Kanchi Karpooram Ltd. occupies a specialized position, focusing its camphor production primarily for India's pharmaceutical and extensive spiritual ritual segments, underscoring its regional market expertise and cultural alignment.
| Leading Market Players |
|---|
| Kanchi Karpooram Ltd. |
| Taiwan Tekho Camphor Co., Ltd. |
| Saptagir Camphor Ltd. |
| Uttam Exports Corporation |
| Camphor & Allied Products Ltd. |
| Mangalam Organics Ltd. |
| Fujian Green Pine Co., Ltd. |
| Arora Aromatics Pvt. Ltd. |
| Oriental Aromatics Ltd. |
| Others |
Cost & Logistics Intelligence
Labor cost differentials in key manufacturing hubs, particularly in China and India, directly influence the pricing-tier spreads for synthetic and natural camphor. This cost structure impacts the competitive landscape for diverse end-user segments.
Pricing Analysis
Value-based pricing anchors pharmaceutical-grade camphor, reflecting its critical role in topical analgesics and cold remedies. This market primarily utilizes a per-unit transactional model, with some long-term contract-based offtake agreements for industrial buyers. Price differentiation stems from quality grade, specific regulatory certifications like US FDA or EU REACH compliance, and volume scale. Pricing softness emerges from feedstock price volatility and the concentrated synthetic supply chain in China. Industrial applications like plastics exhibit high price sensitivity, while pharmaceutical companies and spiritual ritual segments prioritize purity and consistent supply over cost.
Supply Chain Analysis
Single-source vulnerability sits with the highly concentrated synthetic camphor production in China, particularly Fujian province. The global camphor supply chain draws heavily from China for synthetic grades and from India for natural camphor. Synthetic production depends on turpentine oil, a byproduct of the pulp industry, exposing producers to commodity price volatility. Regulatory restrictions, such as the EU's REACH, introduce compliance hurdles for non-EU suppliers. Distribution runs through bulk industrial channels for large manufacturers and specialized retail packs for consumer-facing segments in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The camphor market presents a cost-of-compliance story, where stringent regulations like the EU's REACH create a significant barrier-to-entry moat for compliant players.
For Market Incumbents:
Lock in long-term supply agreements for bio-based feedstock to mitigate feedstock price volatility, particularly for natural camphor producers. Incumbents must invest in advanced catalytic processes for synthetic production to improve yields and reduce waste, countering the threat of emerging bio-fermentation techniques. Pursue comprehensive certification investments, including US FDA and EMA approvals, to maintain market access and differentiate against non-compliant suppliers. Deepen vertical integration into turpentine oil sourcing for synthetic grades to control input costs.
For New Entrants and Emerging Players:
Underserved wellness product manufacturers in Southeast Asia and Latin America represent a clear white space for natural camphor applications. Focus on developing high-purity natural camphor for premium cosmetics and personal care products, leveraging "clean label" appeal. Target specific niches in traditional medicine or aromatherapy with certified organic or sustainably harvested offerings. A go-to-market angle emphasizing transparent sourcing and environmental stewardship can capture environmentally conscious buyers.
For Investors and Strategic Acquirers:
Re-rating potential sits with integrated terpene chemical manufacturers given the increasing regulatory push for bio-based alternatives. Long-term viability is anchored in the consistent demand from pharmaceutical and spiritual ritual segments, alongside the high-value growth in cosmetics. Target specialized natural camphor producers with robust sustainability certifications and strong regional market penetration in India. A key signal to watch is the broader adoption of bio-fermentation techniques blurring the lines between natural and synthetic sources.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases Fujian Green Pine Co., Ltd.'s ability to meet global industrial demand for synthetic camphor. |
| Green Manufacturing Transition | Reduces environmental footprint for Mangalam Organics Ltd., aligning with EU Green Deal objectives. |
| Long-term Supply Agreement | Secures stable turpentine oil input for synthetic producers, mitigating feedstock price volatility. |
| Certified Sustainable Sourcing | Differentiates natural camphor products for Kanchi Karpooram Ltd. in high-value cosmetics segments. |
| Regulatory Approval Pathway | Ensures pharmaceutical-grade camphor from Saptagir Camphor Ltd. meets US FDA and EMA purity standards. |
Research Approach
Multi-period observation of market growth rates and regulatory shifts anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved in-depth conversations with pharmaceutical procurement leads, chemical R&D directors, FSSAI compliance officers, and spiritual ritual suppliers. Secondary validation drew from customs and trade data, company financial reports, regulatory body publications from the US FDA and EMA, and industry association reports. This approach facilitated bottom-up and top-down triangulation of market data.
Segment-weighting across product type, application, end-user, and packaging format informed the quantitative market forecast. The analytical framework integrated historical data extrapolation with market driver analysis over the projection horizon. Compound annual growth rates were derived from a detailed assessment of demand-side factors and supply-side capabilities. Key industry-specific forecast inputs included turpentine oil price trends and regional bio-based chemical policies.
Revisions become necessary when significant geopolitical shifts or unforeseen regulatory changes materialize in key camphor-producing regions. Forecasts reflect assumptions regarding market dynamics and technological advancements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Europe Deodorants Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Herbal Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market