
 Estragole Market | 2026-2036
Estragole Market Size, Share, and Industry Trends Forecast 2026-2036
Estragole Market Analytics
Pharmaceutical applications is expanding as a priority vertical for estragole suppliers, shifting historical reliance on traditional fragrance markets. Firmenich leverages its integrated flavor and fragrance platform to secure long-term supply agreements with drug manufacturers. Givaudan sustains R&D intensity in natural extraction methods that meet evolving pharmaceutical purity thresholds. Arora Aromatics anchors its position through specialized distillation capabilities serving bulk active pharmaceutical ingredient producers in South Asia.
Estragole is a phenylpropanoid compound, also known as 1-allyl-4-methoxybenzene, characterized by a boiling point of approximately 215°C and a characteristic anise-like odor profile; it serves primarily as a precursor in fragrance compounding and as a building block in pharmaceutical synthesis. Natural Estragole commands premium positioning due to traceability requirements from basil and tarragon sources, while Synthetic Estragole dominates volume through cost-advantaged petrochemical routes. The Food & Beverage end user segment represents a mature demand pool with stable offtake, whereas Pharmaceuticals generates the fastest-growing application trajectory as API intermediates gain regulatory traction.
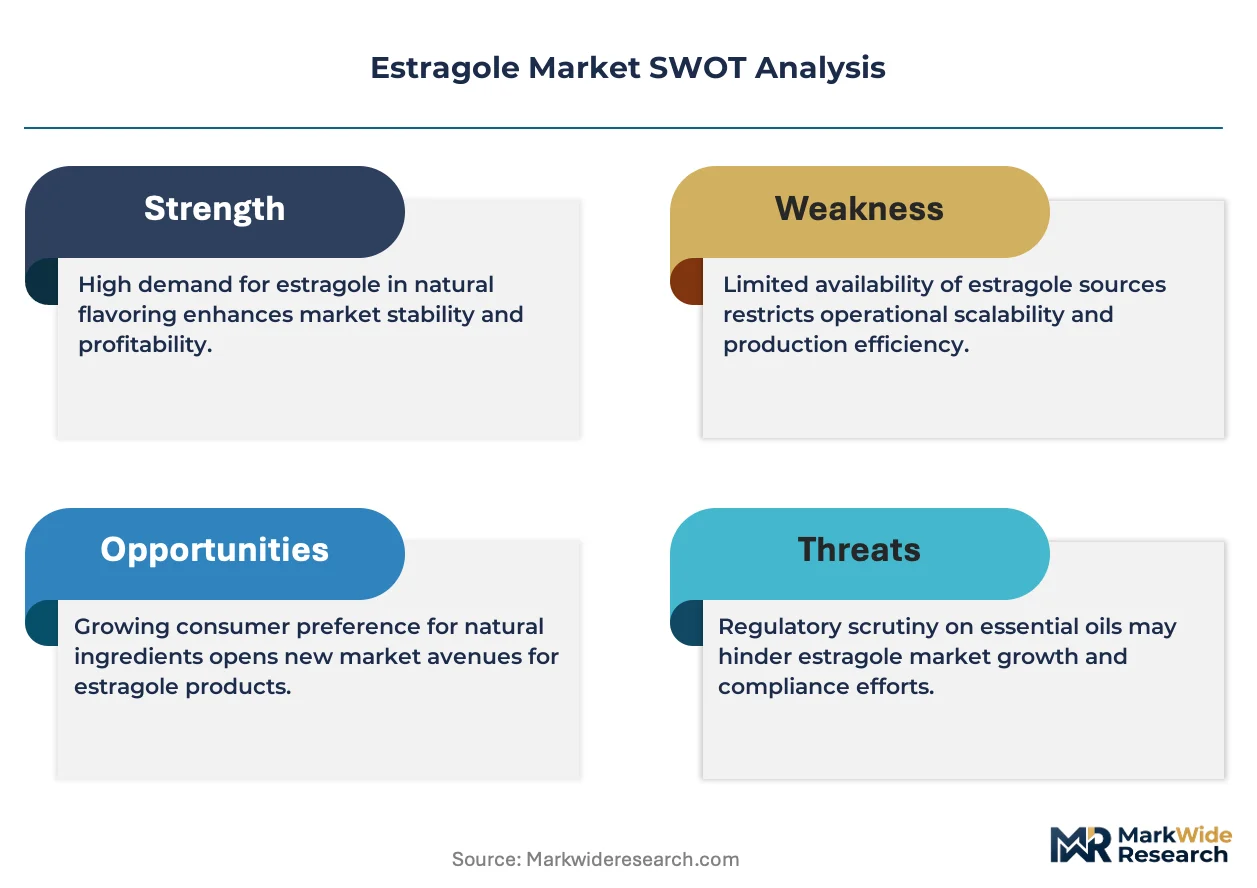
REACH in Europe mandates full substance registration and toxicity documentation, compelling suppliers to invest in analytical testing infrastructure or exit the market. FDA maintains oversight of estragole as a food additive through its Generally Recognized As Safe framework, with ongoing toxicological reviews influencing permissible exposure levels. India's BIS certification requirements for essential oil derivatives add a compliance layer for exporters targeting domestic formulators. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Pharmaceutical formulators are redirecting estragole procurement toward higher-purity intermediates, compressing legacy fragrance-grade margins while elevating documentation and traceability requirements across supplier tiers.
Growth Catalysts
- API Intermediate Demand:Synthetic chemistry routes for antihistamine and anxiolytic active ingredients now specify estragole-derived building blocks, pulling volume from traditional fragrance applications.
- REACH Registration Thresholds:ECHA's full substance dossier requirements for volumes above one tonne annually filter out undercapitalized suppliers, concentrating compliant capacity among established registrants.
- India:Domestic essential oil processors in Uttar Pradesh and Karnataka are scaling fractional distillation units to serve both export fragrance houses and local pharmaceutical formulators.
Market Restraints
- Feedstock Volatility:Petrochemical-derived anisole and allyl chloride feedstocks expose synthetic estragole producers to benzene price swings that natural extraction routes avoid.
- Supplier Concentration:Bulk pharmaceutical-grade supply clusters among three Indian distillation specialists, creating single-source vulnerability for European formulators.
- Substitution Pressure:Anethole from star anise oil displaces estragole in certain anise-flavor applications where regulatory scrutiny of estragole metabolites intensifies.
Strategic Opportunities
- Pharmaceutical-Grade Certification:ICH Q7-compliant manufacturing infrastructure opens contract synthesis opportunities with generic API producers seeking backward integration into phenylpropanoid intermediates.
- Carbon Accounting Integration:EU Green Deal border adjustment mechanisms reward natural extraction routes with verified supply chain emissions data, disadvantaging petrochemical competitors.
- Biocatalytic Conversion:Enzymatic biotransformation of eugenol to estragole is expanding into pilot-scale production, offering route diversification beyond traditional chemical synthesis.
Industry Challenges
- Analytical Capability Gap:Gas chromatography-mass spectrometry expertise for distinguishing estragole stereoisomers and metabolite profiles remains scarce among mid-tier contract manufacturers.
- Dual-Use Documentation:Suppliers must maintain parallel batch records satisfying both FSSAI food-additive specifications and CDSCO pharmaceutical intermediate standards for Indian customers serving both end markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estragole Market |
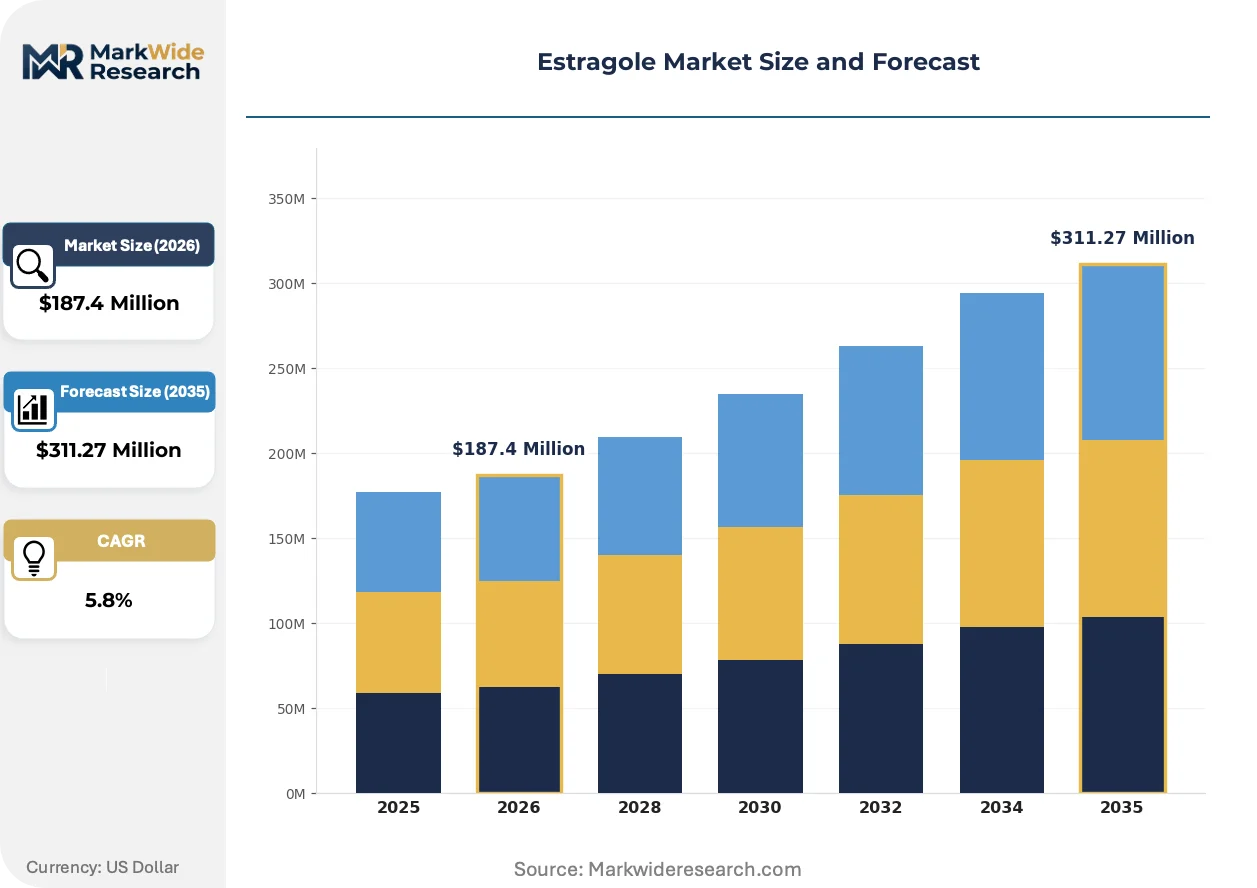
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Estragole, Synthetic Estragole, Concentrates, Blends End User: Food & Beverage, Cosmetics, Pharmaceuticals, Fragrances Application: Flavoring Agent, Fragrance Permutations, Aromatherapy, Food Preservative Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Firmenich, Givaudan, Arora Aromatics, Indenta Chemicals, AOS Products, De Monchy, Inter, Kelvin Natural Mint, Emery Oleochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estragole Market Evolving Landscape
Supercritical fluid extraction and continuous-flow synthesis are reconfiguring cost structures across natural and synthetic production routes, while regulatory data requirements force consolidation in analytical capabilities.
Supercritical CO2 extraction from basil and tarragon biomass is expanding into commercial-scale deployment, replacing steam distillation for select premium fragrance applications. European flavor houses with captive botanical sourcing are adopting this technology to meet tightening residual solvent specifications. The process is expanding into pharmaceutical-grade production as manufacturers seek to eliminate hexane traces that complicate API intermediate qualification.
REACH's extended one substance, one registration framework now requires estragole suppliers to submit updated carcinogenicity and genotoxicity dossiers or face volume restrictions. This regulatory pressure is accelerating exits among smaller traders lacking in-house toxicology departments. Indian exporters targeting EU pharmaceutical formulators are absorbing third-party testing costs or ceding share to REACH-registered European competitors.
Long-term offtake agreements now dominate procurement between API manufacturers and estragole suppliers, displacing spot-market purchasing that prevailed in fragrance-grade trading. This contractual shift locks in volume commitments spanning three to five years with indexed pricing clauses. The pattern is most pronounced among generic drug producers in India and contract manufacturing organizations in Western Europe seeking supply security for regulatory filings.
Estragole Market Segmentation
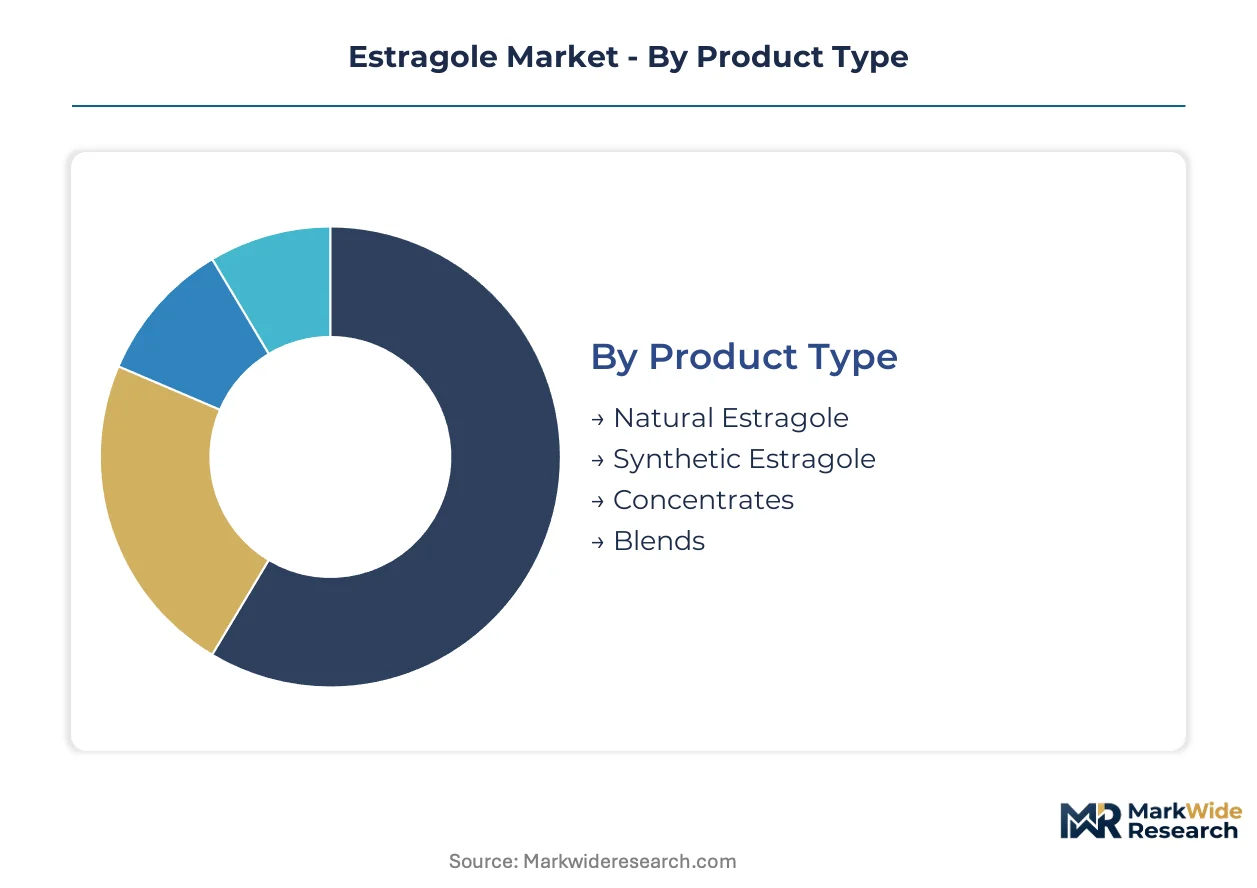
Segmentation in the estragole market tracks divergent purity requirements between fragrance-grade commodity supply and pharmaceutical-grade certified streams. Procurement patterns split sharply across end-use verticals, with documentation burdens and pricing tiers stratifying supplier relationships.
Product Type:
Integration depth varies substantially — natural extraction routes serve standalone premium positioning while synthetic pathways embed into cost-sensitive bulk formulations.
- Natural Estragole:Derived from basil and tarragon essential oils through fractional distillation, this grade carries full botanical traceability documentation required by EU fragrance houses. Demand concentrates in Swiss and French flavor compounders seeking REACH-compliant natural positioning for premium anise-type flavor profiles.
- Synthetic Estragole:Manufactured via petrochemical routes from anisole and allyl chloride precursors, this segment dominates volume throughput for industrial fragrance applications. Indian bulk chemical producers in Gujarat and Maharashtra anchor global supply, serving both domestic formulators and export markets with cost-advantaged tonnage.
- Concentrates:Standardized at higher purity thresholds for pharmaceutical intermediate synthesis, these grades require batch-specific COA documentation.
- Blends:Pre-formulated mixtures with anethole or methyl chavicol for customized odor profiles in commercial fragrance applications.
Volume placements concentrate in Synthetic Estragole; the faster expansion belongs to Natural Estragole.
End User:
Customer archetypes segment by regulatory exposure — food and fragrance buyers face FSSAI and IFRA compliance, while pharmaceutical offtakers navigate CDSCO and ICH Q7 mandates.
- Food & Beverage:Mature demand pool with stable offtake for anise-flavored confectionery and beverage applications. Major processors in Maharashtra and Karnataka maintain long-term contracts with Uttar Pradesh distillation units for consistent supply security.
- Pharmaceuticals:API intermediate specifications now specify estragole-derived building blocks for antihistamine and anxiolytic synthesis. European generic drug producers in Germany and Italy are redirecting procurement toward ICH Q7-certified Indian suppliers, compressing legacy fragrance-grade margins while elevating documentation requirements.
- Cosmetics:Personal care formulators in South Korea and Japan utilize estragole in niche fragrance accords for premium skincare lines.
- Fragrances:Traditional anchor segment for bulk estragole consumption in fine fragrance and functional perfumery applications.
Revenue concentration sits with Fragrances; Pharmaceuticals climbs the fastest as regulatory filings multiply.
Application:
Functional deployment separates commodity flavoring from specialized therapeutic and preservation uses with divergent purity thresholds.
- Flavoring Agent:Direct food additive applications in confectionery, chewing gum, and alcoholic beverages require FSSAI compliance in India and FDA GRAS recognition in the United States. Major flavor houses in Switzerland maintain dual-source strategies spanning natural extraction and synthetic routes.
- Fragrance Permutations:Base note construction in fine fragrance compounding, particularly for anise and fennel odor profiles. French and German perfumery houses specify estragole content in regulatory filings under IFRA concentration limits.
- Aromatherapy:Niche therapeutic applications in essential oil blends for wellness products.
- Food Preservative:Antimicrobial properties in traditional food preservation systems, primarily in South Asian culinary applications.
Commercial scale favors Fragrance Permutations; Flavoring Agent gains share fastest as clean-label positioning intensifies.
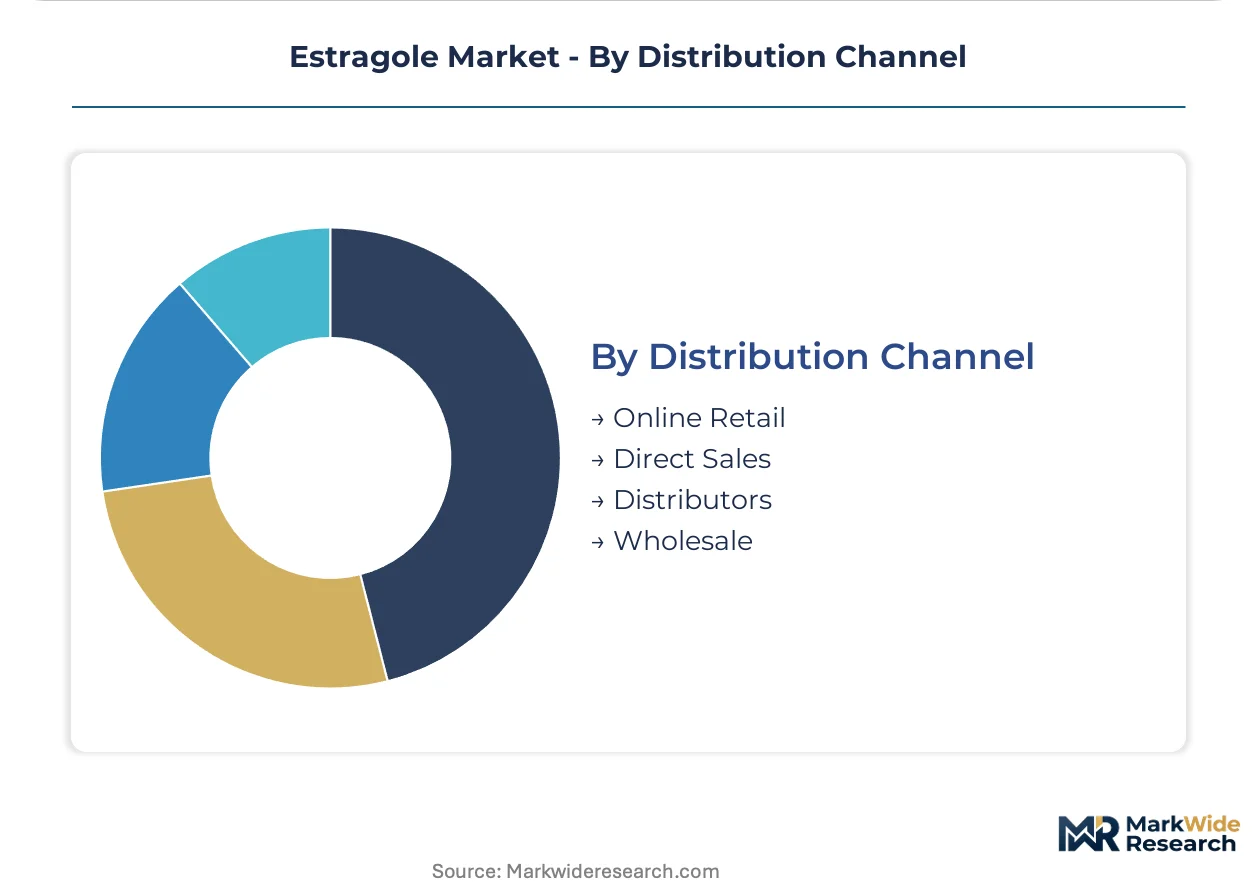
Distribution Channel:
Channel selection correlates with batch size and documentation intensity — pharmaceutical-grade streams bypass intermediaries while fragrance commodities flow through wholesale networks.
- Direct Sales:Long-term offtake agreements dominate pharmaceutical-grade procurement, with three-to-five-year contracts locking in volume commitments between API manufacturers and specialized Indian distillers. Indexed pricing clauses protect margin positions against benzene feedstock volatility.
- Distributors:Regional chemical distributors in Mumbai and Rotterdam maintain inventory positions for fragrance-grade spot purchasing, serving mid-tier European compounders with shorter lead time requirements.
- Online Retail:Small-volume specialty chemical platforms serving research institutions and artisan perfumers.
- Wholesale:Bulk commodity flow for industrial fragrance applications with standardized specifications.
Transaction value concentrates in Direct Sales; Distributors show the steepest expansion trajectory as European formulators seek supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Maharashtra concentrate synthetic estragole capacity through tax-advantaged petrochemical processing. Uttar Pradesh's essential oil belt anchors natural extraction supply chains. Regulatory divergence across jurisdictions reshapes trade flows and compliance investments.
India
Domestic pharmaceutical formulators in Hyderabad and Mumbai drive API intermediate demand for antihistamine synthesis. CDSCO mandates ICH Q7 compliance for pharmaceutical-grade estragole, filtering supplier资格. Fractional distillation units in Kannauj and Mysore scale capacity to serve both export fragrance houses and local drug manufacturers.
Germany
Generic drug producers in Frankfurt and Leverkusen redirect procurement toward REACH-registered Indian suppliers. ECHA's updated carcinogenicity dossier requirements for volumes above one tonne annually compress spot-market participation. Chemical distributors in Hamburg maintain inventory buffers for fragrance-grade spot purchasing.
Switzerland
Premium fragrance compounders in Geneva demand full botanical traceability documentation for natural estragole positioning. Swissmedic oversight of pharmaceutical intermediates elevates batch-specific COA requirements. Flavor houses with captive botanical sourcing adopt supercritical CO2 extraction to eliminate residual solvent traces.
United States
FDA's GRAS framework for food additive applications maintains stable offtake from confectionery processors. EPA oversight of petrochemical feedstock emissions influences synthetic route economics. Specialty chemical distributors in New Jersey serve mid-tier compounders with shorter lead time requirements.
France
Fine fragrance houses in Grasse specify estragole content in regulatory filings under IFRA concentration limits. ANSM pharmaceutical intermediate standards align with EMA guidelines for API building blocks. Perfumery compounders maintain dual-source strategies spanning natural extraction and synthetic routes.
Estragole Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fragrance-grade commodities flowing through wholesale networks while pharmaceutical streams bypass intermediaries entirely. The supplier base concentrates among three Indian distillation specialists for bulk pharmaceutical-grade supply, creating single-source vulnerability for European formulators. Two strategic archetypes dominate: integrated flavor and fragrance platforms with captive R&D infrastructure, and specialized regional distillers with fractional purification capabilities. Competitive moves center on long-term offtake agreements with indexed pricing clauses and ICH Q7 certification investments for API contract synthesis.
Among Swiss-integrated flavor and fragrance platforms, Firmenich occupies a position exemplifying backward integration into phenylpropanoid intermediate supply chains. Givaudan represents the R&D-intensive archetype sustaining natural extraction method development. Arora Aromatics anchors the specialized Indian distiller tier serving bulk active pharmaceutical ingredient producers in South Asia.
| Leading Market Players |
|---|
| Firmenich |
| Givaudan |
| Arora Aromatics |
| Indenta Chemicals |
| AOS Products |
| De Monchy |
| Inter |
| Kelvin Natural Mint |
| Emery Oleochemicals |
| Others |
Value Network & Pricing Analysis
API manufacturers in Germany and Italy concentrate procurement through long-term offtake agreements, locking in three-to-five-year volume commitments with indexed pricing clauses that buffer against benzene feedstock swings.
Pricing Analysis
Short lead-time premiums distinguish spot-market fragrance-grade purchases from contract-structured pharmaceutical streams. Three-tier pricing structure across pharmaceutical-grade, fragrance-grade, and industrial-blend levels separates ICH Q7-certified batches from FSSAI-compliant food additive volumes. Cost compression in fragrance-grade supply is intensifying as Indian distillation specialists absorb REACH registration testing expenses. Pharmaceutical formulators show least price sensitivity due to regulatory filing dependencies, while confectionery processors exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Indian distillation specialists in Kannauj and Mysore that anchor bulk pharmaceutical-grade capacity for European formulators. Synthetic production draws from petrochemical feedstocks concentrated in Gujarat and Maharashtra, while natural extraction sources from Uttar Pradesh's essential oil belt. Tariff exposure on EU-bound shipments creates inventory positioning risks for Rotterdam distributors. Distribution runs through direct sales channels for API intermediates and regional chemical distributors for fragrance-grade spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocatalytic conversion of eugenol to estragole is displacing traditional chemical synthesis routes, creating technology-transition positioning for suppliers investing in enzymatic pilot-scale infrastructure.
For Market Incumbents: Deepen backward integration into phenylpropanoid feedstock supply through captive basil and tarragon sourcing agreements in Uttar Pradesh. Expand ICH Q7-certified manufacturing footprint to defend against REACH-registered European competitors capturing API intermediate share. Lock in five-year offtake agreements with Frankfurt and Leverkusen generic drug producers before biocatalytic routes achieve commercial scale. For New Entrants and Emerging Players: The price-point gap between premium natural estragole and economy synthetic grades offers entry positioning for mid-tier biocatalytic producers. Target Swiss fragrance compounders in Geneva seeking verified supply chain emissions data under EU Green Deal border adjustment mechanisms. Lead with carbon-accounting documentation as the go-to-market wedge against petrochemical incumbents. For Investors and Strategic Acquirers: The window for entry favors specialized Indian distillation specialists with fractional purification capabilities and existing CDSCO relationships. Long-term viability rests on regulatory filing volume expansion across European generic API producers. Watch ECHA carcinogenicity dossier updates as the signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Frankfurt generic drug producers secure three-year volume commitments against benzene volatility. |
| Backward Integration | Firmenich's captive botanical sourcing eliminates hexane trace complications for Swissmedic filings. |
| Green Manufacturing Transition | Supercritical CO2 extraction replaces steam distillation to meet tightening residual solvent specifications. |
| Capacity Expansion | Kannauj fractional distillation units scale to serve both export fragrance houses and Mumbai pharmaceutical formulators. |
| Joint Venture | Gujarat petrochemical processors partner with European REACH registrants to share toxicology dossier costs. |
Research Methodology
Trade databases, CDSCO regulatory filings, and ECHA registration records formed the secondary backbone for supply-side mapping. Primary interviews with essential oil distillation plant managers, API procurement leads at German generic drug producers, fragrance compounder technical directors, and Mumbai-based chemical distributors validated production capacity and pricing structures. Bottom-up volume estimates from Indian state-level production clusters were triangulated against top-down demand calculations from end-use consumption patterns.
Historical trendline analysis of estragole trade flows and purity-grade pricing spreads established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, end-user vertical, application function, and distribution channel dimensions. CAGRs were derived from regression analysis of volume trajectories indexed to pharmaceutical intermediate demand expansion and REACH compliance cost absorption. Industry-specific forecast inputs included benzene price correlation coefficients and ICH Q7 certification penetration rates among Indian suppliers.
Inputs from CDSCO regulatory filings and ECHA dossier updates were available through the study window; gaps in real-time inventory positioning data from Rotterdam distributors introduce uncertainty bands around spot-market price volatility assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Alpha Ionone Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market