
 Citral Market | 2026-2036
Citral Market Size, Share, and Industry Trends Forecast 2026-2036
Citral Market Analysis
Aroma chemical synthesis expertise is reorganizing competitive dynamics as traditional perfumery hubs face shortages of trained flavorists and process chemists. Kuraray leverages captive isoprene chemistry to secure backward integration into citral precursors. Givaudan SA anchors its position through dedicated biotechnology R&D for natural-identical molecules. BASF sustains manufacturing scale across Ludwigshafen and Kuantan, Malaysia, competing on volume reliability for multinational fragrance accounts.
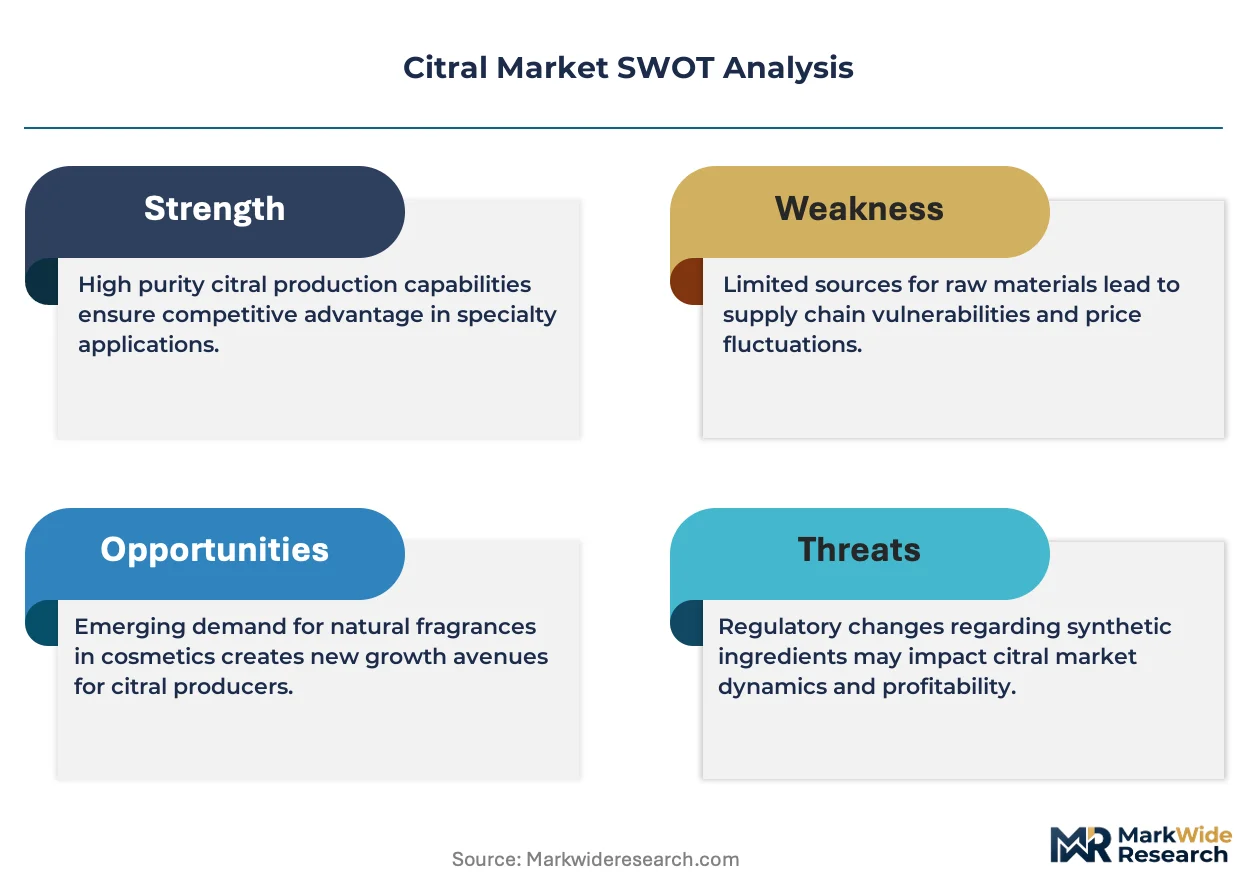
Citral denotes a pair of geometric isomers, geranial and neral, that together constitute a lemon-scented aldehyde with a characteristic citrus odor profile and typical purity grades ranging from 92% to 98% depending on end-use specifications; manufacturers produce it via steam distillation from lemongrass or petrochemical routes from isobutene and formaldehyde, primarily serving as a precursor for ionones, vitamins, and direct fragrance compounding. Synthetic citral dominates volume flows due to cost efficiency and consistent supply, while natural citral commands premium positioning in clean-label fragrance and organic flavoring segments where Food & Beverage end users validate provenance documentation. Pharmaceutical-grade specifications are tightening as manufacturers isolate higher-purity lots for vitamin A synthesis, concentrating margin pools in the isolated product category.
EMA guidelines on fragrance allergen labeling, REACH registration thresholds for imports above one tonne annually, and FDA FEMA GRAS status determinations for food-grade citral all shape formulation choices and market access conditions across the value chain. ECHA's evolving restrictions on sensitizing substances are pushing compounders toward refined grades with documented purity certificates. Stakeholders must monitor regulatory divergence between EU hazard classification and FDA GRAS self-affirmation pathways to avoid reformulation costs.
Market Dynamics
REACH compliance in the European Union is tightening purity specifications for flavor and fragrance chemicals, forcing manufacturers to isolate higher-purity lots and document provenance chains across multinational supply networks.
Growth Catalysts
- Biotechnology R&D:Dedicated programs for natural-identical molecules are pulling investment from traditional petrochemical routes into fermentation-derived precursors for premium fragrance formulations.
- Vitamin A synthesis demand:Pharmaceutical-grade specifications are concentrating margin pools in isolated high-purity citral categories as vitamin manufacturers secure dedicated supply contracts.
- Clean-label validation:Food and beverage end users are mandating provenance documentation for organic flavoring segments, creating pull-through for natural-derived grades with traceable lemongrass sourcing.
Market Restraints
- Isoprene supply concentration:Captive chemistry control by integrated petrochemical majors limits independent access to synthetic citral precursors, compressing margin flexibility for non-integrated compounders.
- Fragrance allergen labeling:EMA guidelines on sensitizing substances are forcing reformulation cycles and documentation burdens that extend product development timelines for European-market formulations.
- Natural feedstock volatility:Lemongrass harvest yields in tropical growing regions fluctuate with monsoon patterns, creating raw material cost instability for steam-distilled natural citral production.
Strategic Opportunities
- Malaysian manufacturing scale:Kuantan-based production complexes offer volume reliability for multinational fragrance accounts seeking supply security outside traditional European hubs.
- FEMA GRAS pathway expansion:FDA self-affirmation mechanisms for food-grade citral create faster market access conditions compared to European REACH registration thresholds above one tonne annually.
- Biotechnology convergence:Integration of precision fermentation with traditional aroma chemical synthesis expertise is opening white space for natural-identical production at synthetic cost structures.
Industry Challenges
- Flavorist and process chemist scarcity:Traditional perfumery hubs face acute shortages of trained technical personnel capable of managing both natural extraction and petrochemical synthesis operations.
- Dual regulatory divergence:Compounders must maintain parallel compliance systems for EU hazard classification and FDA GRAS affirmation pathways, multiplying certification overhead without harmonization mechanisms.
- Legacy equipment retrofitting:Isolation technology for higher-purity pharmaceutical grades requires capital-intensive distillation column upgrades that strain mid-scale manufacturer balance sheets.
Report Scope
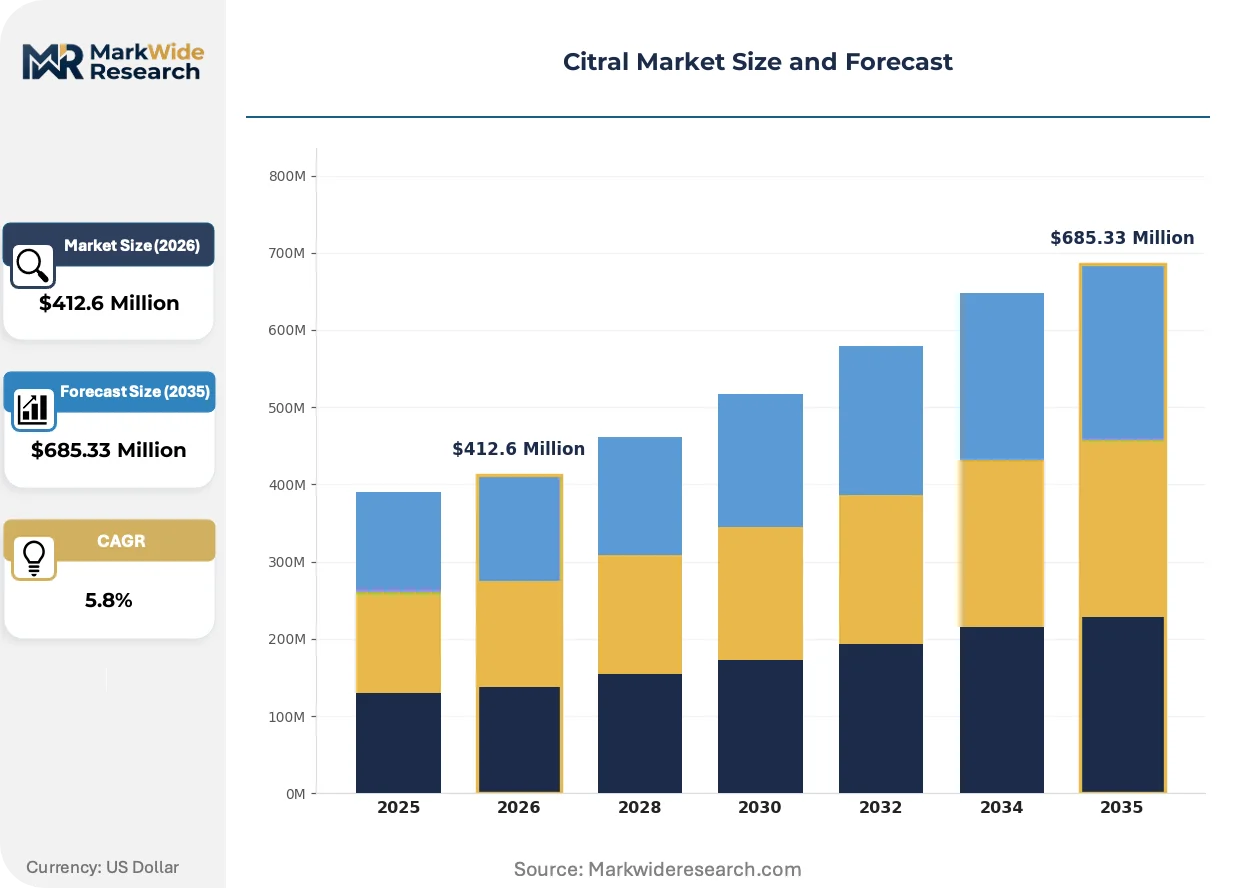
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citral Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Isolated, Blends Application: Fragrance, Flavoring, Pharmaceuticals, Agrochemicals End User: Food & Beverage, Personal Care, Household Products, Chemical Manufacturing Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Kuraray, Givaudan SA, Wanhua Chemical, Zhejiang Medicine Co. Ltd., Firmenich SA, BASF, Symrise AG, Privi Specialty Chemicals Limited, Zhejiang NHU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citral Market Emerging Trajectories
Biotechnology platforms are actively reorganizing competitive dynamics in aroma chemical synthesis as traditional manufacturing hubs confront capability gaps and regulatory documentation burdens intensify across multiple jurisdictions.
Precision fermentation for natural-identical citral is fragmenting the historical dichotomy between premium-priced natural extracts and cost-efficient petrochemical routes. Fragrance houses in Europe and Asia are piloting microbial production systems at commercial scale. This technology is fragmenting established supply relationships by enabling new entrants to bypass captive isoprene chemistry and lemongrass cultivation networks simultaneously.
REACH registration thresholds for imports above one tonne annually are tightening documentation requirements for synthetic citral entering European Union markets. ECHA's evolving restrictions on sensitizing substances are pushing compounders toward refined grades with certified purity certificates. Fragrance formulators serving EU markets are responding by consolidating supplier relationships around manufacturers with established registration dossiers and analytical capabilities.
Direct procurement relationships between fragrance houses and citral manufacturers are compressing traditional distributor intermediaries in premium segments. Multinational fragrance accounts are negotiating long-term supply contracts with integrated producers in Malaysia and China, displacing spot-market purchasing through regional chemical distributors. This pattern is most visible in Asia-Pacific markets where volume reliability commands pricing premiums over transactional flexibility.
Citral Market Segmentation
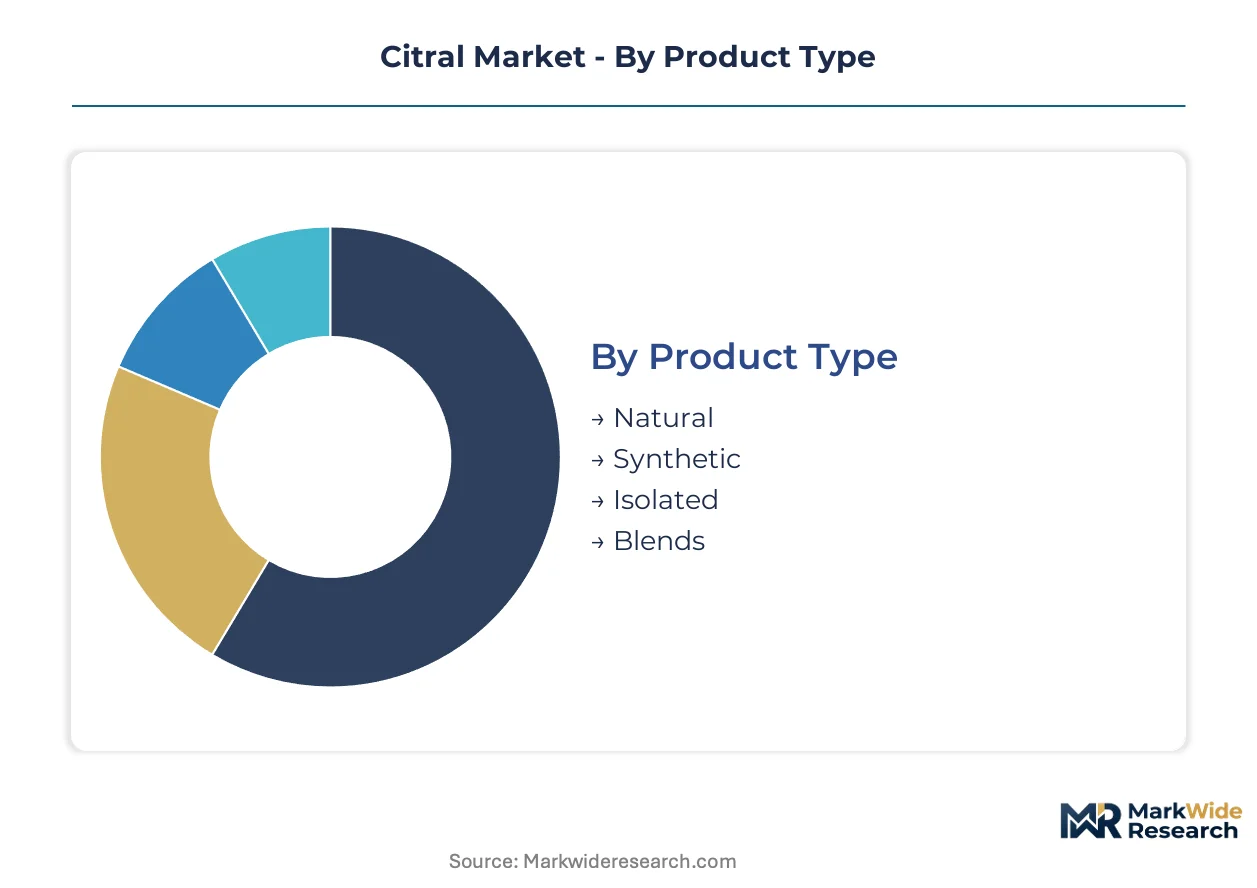
Citral supply chains fragment across distinct purity grades and sourcing methodologies, each commanding different validation protocols and margin structures. Procurement channels diverge sharply between multinational fragrance houses negotiating direct contracts and regional compounders relying on distributor networks for smaller lot sizes.
Product Type:
Channel-mix dynamics split sharply: natural and isolated grades flow predominantly through direct sales to fragrance houses with provenance documentation requirements, while synthetic volumes move through distributors serving mid-scale compounders.
- Natural:Steam-distilled from lemongrass biomass with typical purity of 92-96%, this grade carries organic certification premiums and traceable sourcing documentation mandated by European fragrance houses. Demand concentrates in premium perfume formulations from France and Switzerland where REACH-compliant provenance chains justify price multiples over synthetic alternatives. Monsoon-dependent harvests in India and Vietnam create supply volatility that fragrance formulators hedge through long-term offtake agreements.
- Synthetic:Petrochemical-derived via isobutene-formaldehyde chemistry achieving 96-98% purity with batch-to-batch consistency unattainable in natural extraction. Volume flows concentrate through Kuantan, Malaysia and Ludwigshafen, Germany manufacturing complexes supplying multinational fragrance accounts with tonnage reliability for vitamin A precursor synthesis. Captive isoprene chemistry control by integrated majors limits independent producer participation in this segment.
- Isolated:Pharmaceutical-grade lots separated through fractional distillation for vitamin synthesis applications requiring documented impurity profiles.
- Blends:Custom-formulated mixtures balancing cost and sensory performance for mid-tier household product applications.
By volume, synthetic leads. By growth pace, natural is ahead.
Application:
Cost-tier stratification separates fragrance and pharmaceutical applications commanding purity premiums from agrochemical uses tolerating broader specification ranges.
- Fragrance:Direct compounding into fine perfumes and functional fragrances leverages citral's characteristic lemon aldehyde profile; EMA allergen labeling requirements are forcing reformulation cycles toward refined grades with certified low-sensitizing potential. European fragrance houses in Grasse and Geneva anchor demand for natural-derived lots with full documentation packages.
- Flavoring:FEMA GRAS status for food-grade citral enables faster FDA market access compared to European REACH thresholds, concentrating procurement through US-based flavor houses with self-affirmation capabilities.
- Pharmaceuticals:Vitamin A synthesis demands highest-purity isolated lots with dedicated supply contracts.
- Agrochemicals:Intermediate applications in pesticide synthesis absorb lower-grade synthetic overflow.
Fragrance commands the highest unit margins. Flavoring is expanding most quickly on clean-label validation trends.
End User:
Customer-type concentration drives channel selection: multinational Food & Beverage and Personal Care players negotiate direct manufacturer relationships while Household Products and Chemical Manufacturing segments rely on distributor intermediaries.
- Food & Beverage:Organic flavoring segments mandate traceable lemongrass sourcing with third-party certification; procurement teams validate provenance documentation through dedicated supplier audits in Indian and Vietnamese growing regions. Clean-label positioning in premium beverage categories is pulling natural citral volumes away from synthetic alternatives despite cost differentials.
- Personal Care:Fine fragrance and skincare formulations in European and Asian markets specify natural-derived citral for premium positioning; ECHA restrictions on sensitizing substances are pushing compounders toward refined grades with documented purity certificates and analytical dossiers.
- Household Products:Functional fragrance applications in cleaning products prioritize cost efficiency over provenance documentation.
- Chemical Manufacturing:Intermediate synthesis for ionones and vitamins operates on volume-contracted synthetic supply.
Personal Care generates the highest revenue per kilogram. Food & Beverage is gaining share fastest on organic validation requirements.
Distribution Channel:
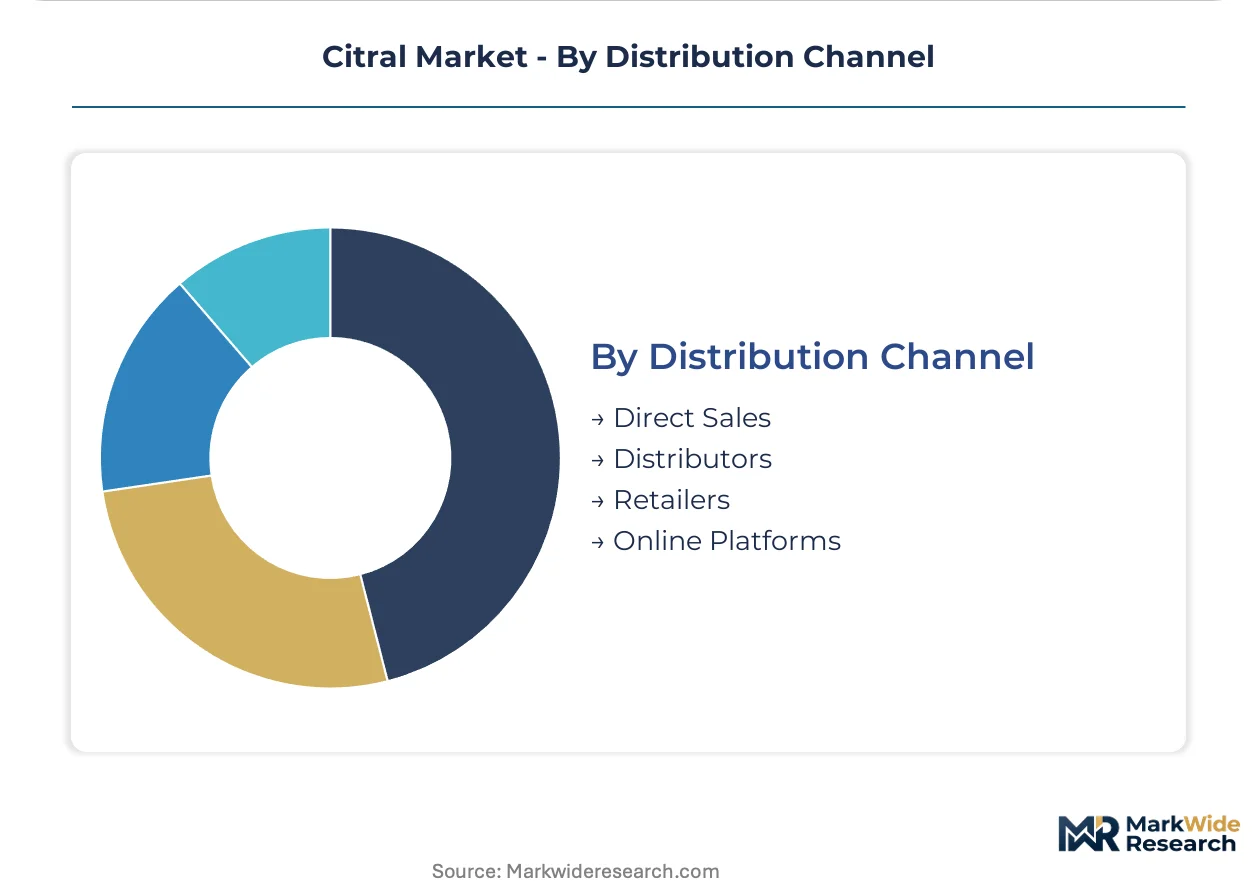
Volume scale determines channel access: direct sales relationships require minimum offtake commitments that exclude smaller compounders, fragmenting procurement patterns across the value chain.
- Direct Sales:Long-term supply contracts between integrated producers and multinational fragrance accounts displace spot-market purchasing; BASF and Kuraray leverage manufacturing scale in Malaysia and Germany to secure volume commitments from Givaudan and Firmenich with pricing indexed to raw material baskets. This channel captures premium segments with documentation burdens too complex for distributor intermediaries.
- Distributors:Regional chemical distributors serve mid-scale compounders lacking procurement scale for direct manufacturer negotiations; inventory pooling and technical service support justify margin extraction in fragmented European and Asian markets where lot sizes fall below direct-sales thresholds.
- Retailers:Limited specialty chemical retail serves small-scale artisan perfumers and research laboratories.
- Online Platforms:Digital procurement channels are emerging for standardized synthetic grades with published specifications.
Direct Sales dominates value capture. Online Platforms are climbing the fastest on digital procurement adoption in mid-scale segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration thresholds for imports above one tonne annually anchor European regulatory stringency, while FDA FEMA GRAS pathways accelerate US market access. Production complexes in Malaysia and Germany supply multinational fragrance accounts with volume-contracted reliability.
Germany
Ludwigshafen manufacturing complexes anchor synthetic citral supply for vitamin A precursor synthesis. ECHA restrictions on sensitizing substances push compounders toward refined grades with documented purity certificates. The Rhineland-Palatinate chemical corridor concentrates backward-integrated isoprene chemistry controlled by BASF.
China
Zhejiang and Jiangsu provinces concentrate new capacity additions for synthetic grades serving fragrance and pharmaceutical intermediates. GB standards and SAMR oversight shape domestic purity specifications for food-grade and pharmaceutical applications. Ningbo and Hangzhou chemical parks host integrated producers leveraging captive formaldehyde-isobutene routes.
United States
FDA FEMA GRAS self-affirmation mechanisms enable faster flavor house market entry compared to European REACH documentation burdens. New Jersey and New York metro area fragrance compounders validate natural-derived provenance for clean-label beverage positioning. EPA oversight of petrochemical precursor emissions shapes synthetic production economics.
Malaysia
Kuantan production complexes offer volume reliability for multinational fragrance accounts seeking supply security outside European hubs. The country's central bank and investment promotion agencies facilitated petrochemical infrastructure buildout. Pahang state manufacturing zones export synthetic grades to Asia-Pacific fragrance houses in Singapore and Japan.
India
Karnataka and Tamil Nadu lemongrass cultivation belts supply steam-distilled natural citral with organic certification premiums. FSSAI food safety standards and DGFT export documentation requirements shape provenance validation protocols. Bangalore and Chennai processing clusters serve European fragrance houses with traceable sourcing dossiers.
Citral Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with biotechnology R&D specialists competing against petrochemical scale operators. The vendor base splits between integrated majors with captive precursor chemistry and mid-scale compounders dependent on distributor networks. Three archetypes dominate: backward-integrated petrochemical giants, fermentation-based natural-identical innovators, and regional natural extraction specialists. Capacity expansion in Malaysia and China and strategic partnerships for biotechnology licensing represent the dominant competitive moves.
Among integrated petrochemical operators, BASF and Kuraray exemplify archetypes combining captive isoprene chemistry with multinational fragrance account relationships. Within the biotechnology tier, Givaudan SA occupies a position representing natural-identical molecule R&D investment. Chinese chemical manufacturers including Wanhua Chemical and Zhejiang NHU sit within the scale-driven synthetic production segment, supplying volume-contracted tonnage to Asia-Pacific and European markets.
| Leading Market Players |
|---|
| Kuraray |
| Givaudan SA |
| Wanhua Chemical |
| Zhejiang Medicine Co. Ltd. |
| Firmenich SA |
| BASF |
| Symrise AG |
| Privi Specialty Chemicals Limited |
| Zhejiang NHU |
| Others |
Supply Flow & Price Mechanics
Captive isoprene chemistry at Ludwigshafen and Kuantan manufacturing complexes creates scale economies that compress synthetic citral price floors while simultaneously concentrating supply power among integrated petrochemical majors. This structural asymmetry between backward-integrated producers and distributor-dependent compounders fragments margin capture across the value chain, with pharmaceutical-grade isolation capabilities commanding premium positioning independent of feedstock origin.
Pricing Analysis
Geographic price spreads between Malaysian synthetic exports and Indian natural-distilled grades reflect divergent cost structures rather than quality equivalence. Three-tier pricing structure across pharmaceutical-isolated, natural-certified, and synthetic-standard levels stratifies the market, with ECHA REACH documentation burdens and FEMA GRAS self-affirmation pathways serving as key differentiation drivers. Cost compression in synthetic grades is intensifying because Chinese capacity additions in Zhejiang and Jiangsu provinces expand volume availability. Fragrance houses in Grasse and Geneva exhibit lowest price sensitivity due to provenance mandates, while household product compounders remain most responsive to per-kilogram differentials.
Supply Chain Analysis
Malaysia and Germany anchor synthetic citral production through Kuantan and Ludwigshafen manufacturing complexes, while India and Vietnam concentrate natural steam-distillation operations in Karnataka and Tamil Nadu lemongrass belts. Raw material flows draw from isobutene-formaldehyde petrochemical streams and monsoon-dependent tropical biomass harvests simultaneously. Single-source vulnerability around captive isoprene chemistry controlled by BASF and Kuraray creates concentration risk for non-integrated compounders seeking synthetic feedstock. Distribution runs through direct long-term offtake agreements for multinational fragrance accounts and regional chemical distributors serving mid-scale compounders with inventory pooling services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-derived natural-identical production is fragmenting the historical natural-synthetic dichotomy, creating asymmetric disruption opportunities as precision fermentation achieves cost parity with petrochemical routes while satisfying clean-label validation requirements.
For Market Incumbents: Fortify backward integration into isoprene precursor chemistry or biotechnology R&D capabilities to defend against fermentation-based entrants bypassing traditional feedstock networks. Prioritize capacity utilization at Kuantan and Ludwigshafen complexes through long-term vitamin A synthesis contracts. Invest in REACH-compliant analytical dossiers to maintain European market access as ECHA restrictions on sensitizing substances tighten documentation requirements. For New Entrants and Emerging Players: Differentiate on fermentation-derived natural-identical positioning to capture clean-label fragrance and organic flavoring premiums without lemongrass cultivation exposure. Target mid-scale European compounders lacking direct manufacturer relationships as the most penetrable customer segment. Pursue FEMA GRAS self-affirmation pathways for accelerated US market entry compared to European registration burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive precursor chemistry and multinational fragrance account relationships. Long-term viability across the analysis window favors biotechnology licensing specialists and Malaysian manufacturing scale operators over distributor-dependent natural extraction players. Watch for fermentation yield improvements as the inflection signal indicating cost-parity achievement with synthetic routes.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Licensing Agreement | Precision fermentation partnerships enable natural-identical production without agricultural feedstock exposure. |
| Capacity Expansion in Malaysia | Kuantan complex additions secure volume reliability for Asia-Pacific fragrance house procurement. |
| Backward Integration into Isoprene | Captive precursor chemistry control limits supplier dependency and stabilizes synthetic citral margins. |
| Long-term Supply Agreement | Direct offtake contracts with Givaudan and Firmenich displace spot-market purchasing through distributors. |
| Green Manufacturing Transition | Fermentation-based routes satisfy REACH-compliant sustainability documentation for European premium segments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fragrance house procurement directors, flavor compounder technical managers, lemongrass cultivation cooperative representatives, and petrochemical plant operations heads. Secondary validation drew from customs and trade flow databases, ECHA REACH registration dossiers, FEMA GRAS determination records, and SEC filings of listed aroma chemical manufacturers. Bottom-up volume modeling across grade tiers and applications was triangulated against top-down market sizing derived from downstream consumption patterns in vitamin synthesis and fragrance compounding.
Across the analysis window, the forecasting framework modeled citral demand through segmentation dimensions including purity grade, sourcing methodology, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted consumption trajectories incorporating biotechnology adoption curves and REACH compliance cost pass-through assumptions. Industry-specific inputs included lemongrass harvest yield volatility indices and isoprene spot price correlation models.
Material uncertainties — monsoon pattern disruption, ECHA restriction expansion, fermentation yield breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization stability and synthetic-natural price convergence velocity. Recalibration cycles align with material shifts in biotechnology commercialization timelines and European fragrance allergen classification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Semiochemicals Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Alpha Ionone Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Camphor Market