
 Asia Pacific Essential Oils Market | 2026-2036
Asia Pacific Essential Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Essential Oils Market Outlook
Buyer concentration across Asia Pacific cosmetic manufacturers is shifting as mid-sized clean beauty brands fragment procurement while multinational personal care houses consolidate supply contracts. Symrise AG leverages its integrated botanical extraction network across Indonesia and India to secure raw material consistency. Young Living Essential Oils LC anchors its position through direct sales channels that bypass traditional retail markups in Japan and Australia. Takasago International Corporation competes via specialized fermentation-derived aroma molecules that complement its natural essential oils portfolio.
Essential oils comprise volatile aromatic compounds extracted through steam distillation, cold pressing, or solvent extraction from plant materials such as flowers, leaves, bark, and roots, with terpene profiles and specific gravity serving as key quality benchmarks for industrial grading. These oils function primarily as functional ingredients in fragrances, therapeutic formulations, and natural preservatives across consumer and industrial applications. Lavender oil and tea tree oil dominate volume flows due to established aromatherapy and antiseptic applications, while food-grade peppermint oil commands premium positioning within the food and beverage segment where clean-label momentum strengthens. The spa industry end-user category sustains above-average growth as wellness tourism infrastructure expands across Thailand, Bali, and Sri Lanka.
India's FSSAI mandates natural flavor labeling disclosures that essential oil suppliers must document through supply chain traceability systems, while Australia's TGA regulates therapeutic claims for aromatherapy products sold through pharmacy channels. Japan's Ministry of Health, Labour and Welfare enforces strict residual solvent limits that favor steam-distilled over solvent-extracted grades in cosmetic applications. Stakeholders must monitor evolving botanical sourcing regulations and invest in certified organic cultivation partnerships to secure long-term supply access.
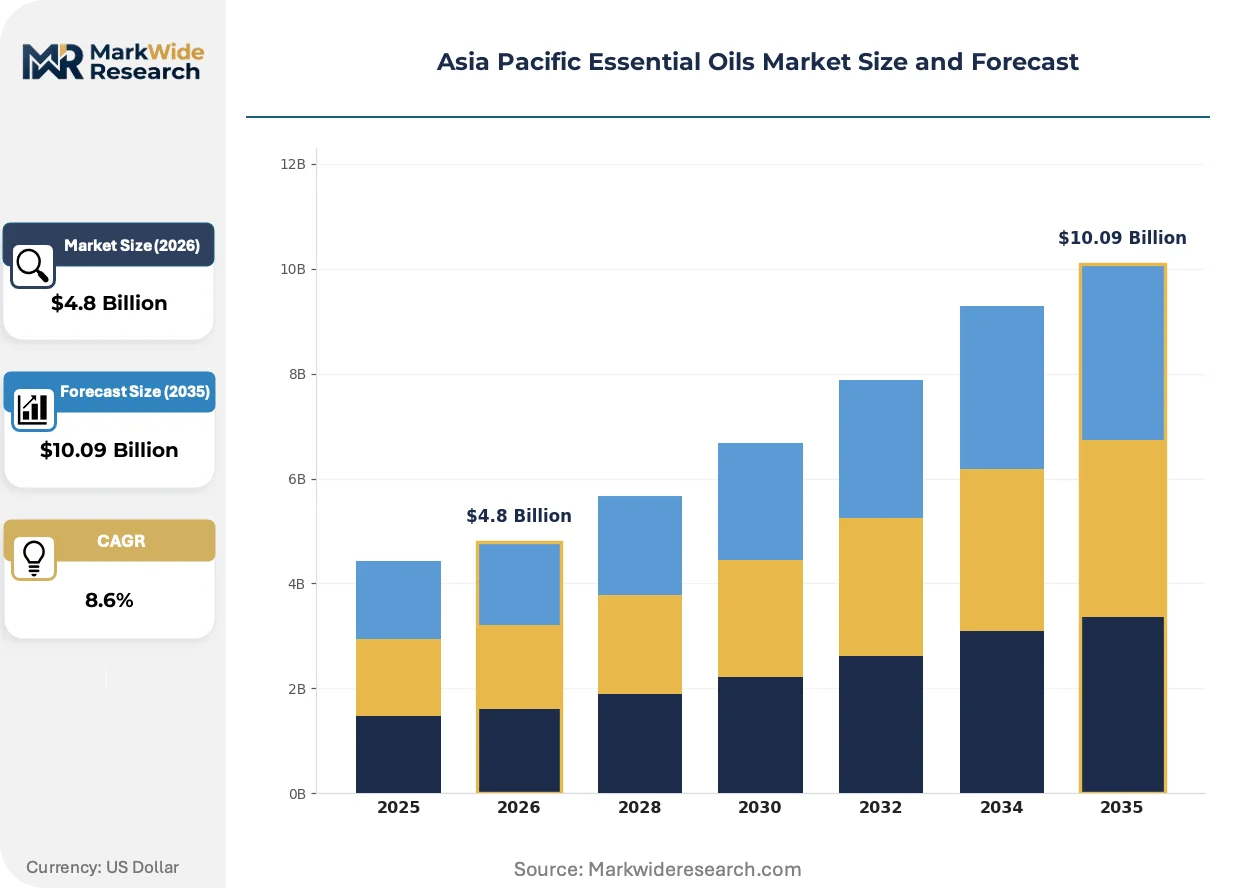
Market Dynamics
Clean-label cosmetic formulation mandates across Southeast Asia are compressing synthetic fragrance substitution timelines while concentrating raw botanical procurement around certified organic cultivation networks in Indonesia and southern India.
Growth Catalysts
- FSSAI Natural Ingredient Labeling:India's tightened disclosure standards for natural flavor claims force documented supply chain traceability, accelerating certified organic partnerships between Maharashtra contract farmers and domestic distillers.
- Spa Industry Expansion:Wellness tourism infrastructure development across Thailand, Bali, and Sri Lanka sustains above-average volume pull for lavender and tea tree oils in therapeutic applications.
- Steam Distillation Preference:Japan's Ministry of Health, Labour and Welfare residual solvent limits favor steam-distilled grades over solvent-extracted alternatives in cosmetic formulations.
Market Restraints
- Raw Botanical Price Volatility:Climate-sensitive lavender and tea tree harvests in Karnataka and Maharashtra expose processors to input cost swings that compress distiller margins.
- Geographic Supply Concentration:Maharashtra and Karnataka states dominate India's raw botanical flows, creating single-region dependency risks for export houses and domestic formulators.
- Regulatory Fragmentation:Divergent therapeutic claim standards between Australia's TGA pharmacy-channel requirements and Japan's cosmetic-grade solvent limits force multi-jurisdiction compliance architectures.
Strategic Opportunities
- Underpenetrated Indonesian Cultivation:Symrise AG's integrated extraction network demonstrates scalable organic botanical sourcing potential outside India's dominant growing regions.
- Direct Sales Channel Innovation:Bypassing traditional retail markups through direct-to-consumer models in Japan and Australia captures margin otherwise lost to distributor layers.
- Fermentation-Derived Complement:Specialized aroma molecules produced via fermentation processes blend with natural essential oils to meet clean-label expectations while ensuring batch consistency.
Industry Challenges
- Organic Certification Timelines:FSSAI and export-market organic standards require multi-year field conversion periods that delay revenue recognition for contract farming networks.
- Traceability System Integration:Supply chain documentation platforms must interface with legacy distillery inventory management systems across fragmented SME processor bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Essential Oils Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lavender Oil, Tea Tree Oil, Peppermint Oil, Eucalyptus Oil Application: Aromatherapy, Personal Care, Food & Beverage, Household Products Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Households, Spa Industry, Cosmetic Manufacturers, Food Industry |
| Companies Covered | Symrise AG, Ultra International, doTERRA International LLC, India Essential Oils, Organic Harvest, Young Living Essential Oils LC, Takasago International Corporation, Aroma Treasures, Givaudan SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Essential Oils Market Strategic Shifts
Extraction technology refinement and regulatory disclosure mandates are reconfiguring quality benchmarks across Asia Pacific essential oils processing, with sustainability verification emerging as a non-negotiable buyer criterion.
Supercritical CO2 extraction is absorbing market share from conventional steam distillation in premium cosmetic applications across Japan and South Korea. High-end fragrance houses in Tokyo and Seoul adopt CO2-derived oils for terpene profile precision that steam methods cannot replicate. This technology is absorbing capital investment that would otherwise flow toward solvent extraction capacity expansion.
Australia's TGA therapeutic claim regulations for aromatherapy products sold through pharmacy channels now require substantiated efficacy documentation. The framework compresses marketing flexibility for suppliers targeting wellness-positioned SKUs. Australian and New Zealand formulators respond by segregating cosmetic-grade and therapeutic-grade product lines with distinct labeling architectures.
Mid-sized clean beauty brands fragment procurement contracts while multinational personal care houses consolidate supply agreements, reversing historical buyer concentration patterns. Direct sales models disintermediate traditional retail layers in Japan's mature aromatherapy market. This behavioral shift concentrates most visibly in Australia's pharmacy channel where TGA-regulated therapeutic positioning commands shelf access premiums over general cosmetic distribution.
Asia Pacific Essential Oils Market Segmentation
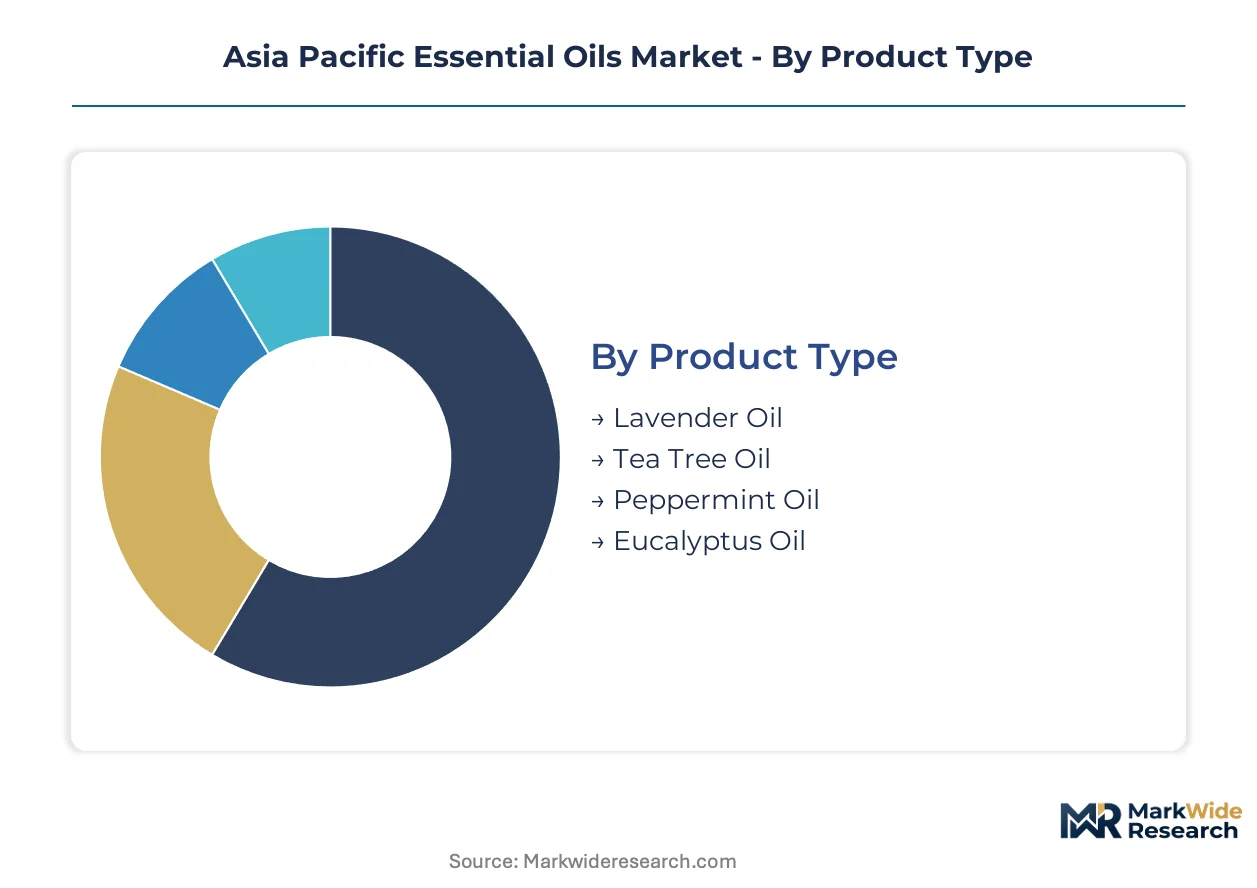
Essential oil processors configure production assets around terpene profile precision and batch volume requirements. Segmentation reveals where capital deployment concentrates and which buyer categories command pricing premiums.
Product Type:
Steam distillation equipment represents the dominant capital outlay across all four oil categories, though supercritical CO2 systems command higher unit investment for premium-grade output.
- Lavender Oil:Rich in linalool and linalyl acetate, this oil requires extended distillation cycles that tie up boiler capacity. Maharashtra contract farmers supply raw botanicals to domestic distillers serving cosmetic manufacturers across Southeast Asia, where clean-label mandates compress synthetic substitution timelines.
- Tea Tree Oil:Terpinen-4-ol content defines pharmaceutical-grade specifications. Karnataka cultivation networks feed export houses targeting Australia's TGA-regulated pharmacy channel, where therapeutic claim documentation creates entry barriers for unverified suppliers.
- Peppermint Oil:Menthol crystallization adds downstream processing complexity. Food-grade specifications command premium positioning within India's FSSAI-regulated natural flavor segment.
- Eucalyptus Oil:Cineole concentration determines industrial versus therapeutic grades. Steam distillation dominates extraction given solvent residue restrictions in Japanese cosmetic applications.
Most installed capacity flows through Lavender Oil. Expansion is steepest in Tea Tree Oil.
Application:
Regulatory documentation requirements vary sharply across these four use cases, with therapeutic positioning demanding the most extensive compliance investment.
- Aromatherapy:Wellness tourism infrastructure across Thailand, Bali, and Sri Lanka sustains volume pull for therapeutic-grade oils. Australia's TGA mandates substantiated efficacy documentation for pharmacy-channel products, compressing marketing flexibility.
- Personal Care:Clean-label cosmetic formulations drive procurement from certified organic cultivation networks. Japan's Ministry of Health, Labour and Welfare enforces residual solvent limits that favor steam-distilled grades.
- Food & Beverage:India's FSSAI tightening of natural ingredient labeling standards reshapes product certification requirements for flavor applications.
- Household Products:Antiseptic positioning in surface cleaners leverages tea tree oil's established antimicrobial profile.
Personal Care absorbs the largest share of premium-grade output. Food & Beverage applications are climbing the fastest as clean-label momentum strengthens.
Distribution Channel:
Margin capture differs substantially across these four pathways, with disintermediated models preserving value otherwise lost to distributor layers.
- Online Retail:Direct-to-consumer platforms bypass traditional retail markups in Japan's mature aromatherapy market. Young Living Essential Oils LC anchors position through this channel.
- Specialty Stores:Curated assortment and staff expertise support premium pricing for certified organic grades.
- Supermarkets:Volume placement for standard-grade oils in mass-market personal care and household product lines.
- Direct Sales:Multi-level marketing networks concentrate in Australia and Japan, capturing margin through relationship-based customer acquisition.
Direct Sales channels retain the highest margin per liter. Online Retail is gaining share fastest as digital penetration deepens across Asia Pacific.
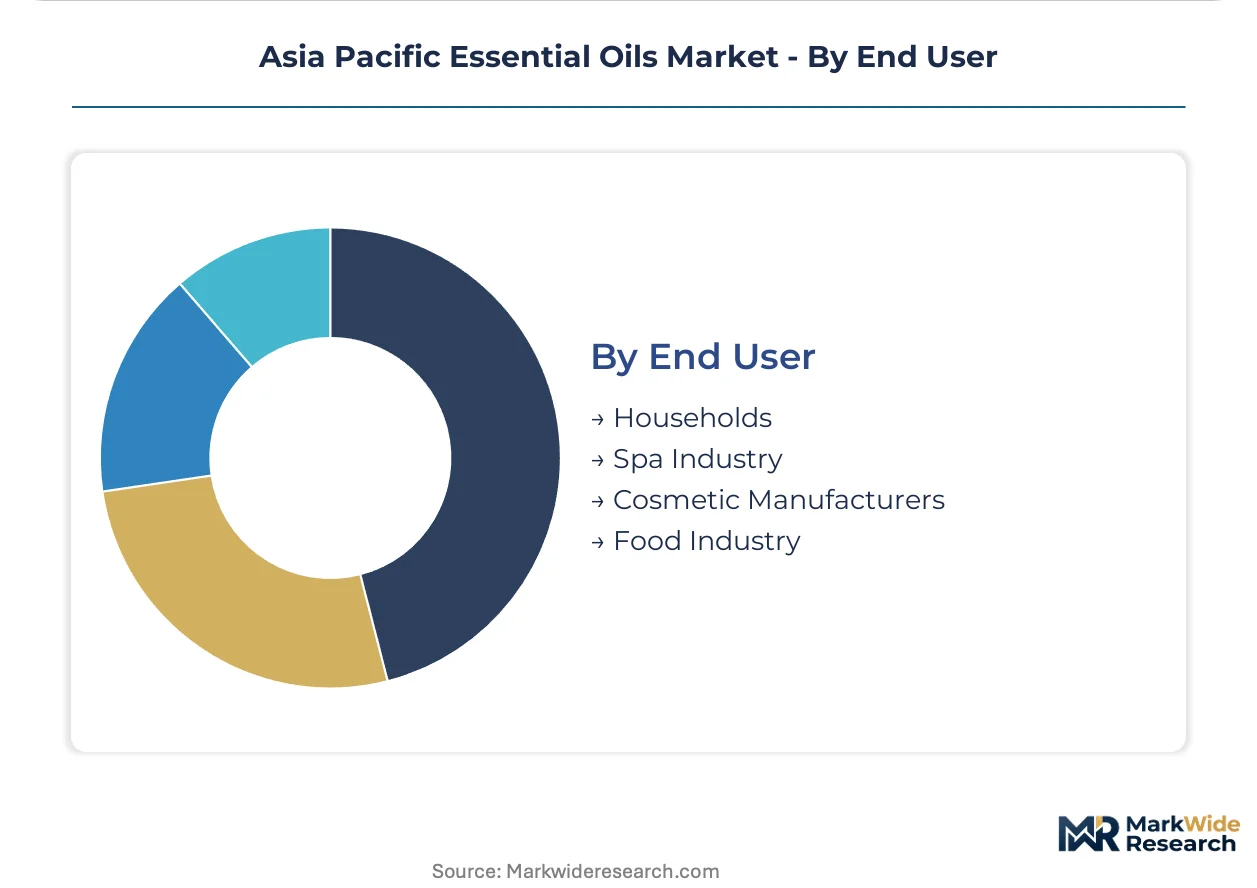
End User:
Buyer scale and specification sophistication create tiered demand profiles across these four categories.
- Households:Diffuser applications and DIY formulations drive retail-packaged volume through online and specialty channels.
- Spa Industry:Wellness tourism infrastructure development across Thailand, Bali, and Sri Lanka sustains above-average growth for therapeutic-grade lavender and tea tree oils.
- Cosmetic Manufacturers:Mid-sized clean beauty brands fragment procurement contracts while multinational personal care houses consolidate supply agreements.
- Food Industry:Natural flavor applications require FSSAI-compliant supply chain traceability systems for documented botanical sourcing.
Cosmetic Manufacturers represent the largest volume offtake. Spa Industry demand is expanding most quickly as wellness tourism infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's contract farming networks supply raw botanicals at scale, while Japan's residual solvent regulations favor steam-distilled grades over solvent-extracted alternatives. This regulatory divergence shapes procurement patterns across the region.
India
Maharashtra and Karnataka states anchor raw botanical cultivation for lavender and tea tree oils. FSSAI mandates natural ingredient labeling disclosures that force documented supply chain traceability systems. Domestic distillers in these states feed both export houses and cosmetic manufacturers expanding clean-label procurement.
Japan
High-end fragrance houses in Tokyo and Seoul drive demand for terpene-profile precision in premium cosmetic applications. The Ministry of Health, Labour and Welfare enforces strict residual solvent limits that disfavor solvent-extracted grades. Supercritical CO2 extraction systems absorb capital investment that would otherwise expand conventional distillation capacity.
Australia
TGA therapeutic claim regulations for pharmacy-channel aromatherapy products require substantiated efficacy documentation. This framework compresses marketing flexibility for wellness-positioned SKUs. Formulators segregate cosmetic-grade and therapeutic-grade product lines with distinct labeling architectures.
Indonesia
Symrise AG's integrated botanical extraction network demonstrates scalable organic sourcing potential outside India's dominant growing regions. Clean-label cosmetic mandates across Southeast Asia concentrate procurement around certified organic cultivation partnerships. Contract farming networks in Java and Sumatra supply raw materials to regional distillers.
Thailand
Wellness tourism infrastructure expansion sustains above-average volume pull for therapeutic-grade lavender and tea tree oils. Spa industry demand concentrates in Bangkok and resort destinations across Phuket and Chiang Mai. Domestic formulators serve both hospitality channels and export markets.
Asia Pacific Essential Oils Market Competitive Environment
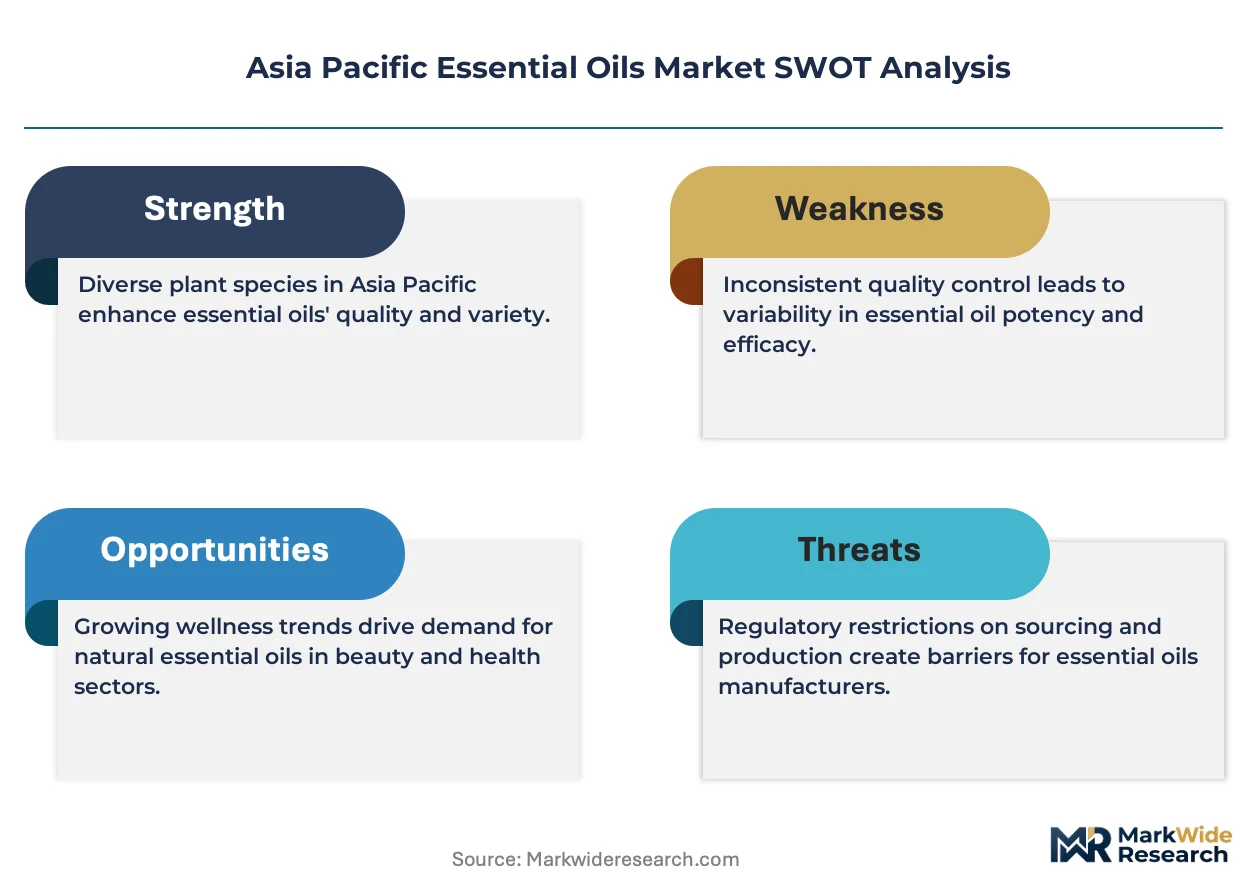
Indian producers anchor one tier; Japanese specialists hold premium extraction technology positions. The vendor base separates into three structural tiers: multinational flavor houses with integrated supply chains, direct-sales specialists bypassing retail markups, and regional distillers serving contract manufacturing relationships. Two dominant competitive moves define current positioning: certified organic cultivation partnerships securing long-term raw material access, and supercritical CO2 technology licensing for terpene-profile precision.
Within the integrated extraction tier, Symrise AG exemplifies geographic diversification beyond single-source dependency. Among direct-sales specialists, Young Living Essential Oils LC occupies a position that disintermediates traditional distributor layers in mature aromatherapy markets. Takasago International Corporation represents the fermentation-derived complement archetype, blending natural essential oils with specialized aroma molecules for batch consistency.
| Leading Market Players |
|---|
| Symrise AG |
| Ultra International |
| doTERRA International LLC |
| India Essential Oils |
| Organic Harvest |
| Young Living Essential Oils LC |
| Takasago International Corporation |
| Aroma Treasures |
| Givaudan SA |
| Others |
Value Chain & Pricing Dynamics
Clean-label cosmetic procurement mandates across Southeast Asia are compressing synthetic substitution timelines while forcing supply chains toward certified organic cultivation networks in Maharashtra and Karnataka, elevating price floors for traceable botanical inputs.
Pricing Analysis
Capacity additions in Indonesia are reshaping price floors for tea tree and lavender oils as Symrise AG's integrated extraction network diversifies supply beyond India's dominant growing regions. Three-tier pricing structure across premium certified-organic, standard steam-distilled, and economy solvent-extracted levels separates FSSAI-compliant traceable grades from undocumented alternatives. Cost compression in standard grades is intensifying because contract farming networks absorb organic certification conversion costs without immediate revenue recognition. Mid-sized clean beauty brands exhibit highest price sensitivity, while multinational personal care houses prioritize batch consistency over unit economics.
Supply Chain Analysis
FSSAI natural ingredient labeling disclosures and Japan's Ministry of Health, Labour and Welfare residual solvent limits function as certification gates that filter supplier participation. Raw botanical flows center on India, Indonesia, and Thailand, with Maharashtra and Karnataka contract farmers supplying lavender and tea tree biomass to domestic distillers and export houses. Distillation capacity draws from boiler equipment, certified organic seed stock, and traceability documentation platforms. Single-region dependency in India's western states creates vulnerability to monsoon-driven harvest volatility. Distribution runs through direct sales networks in Japan and Australia, specialty retail channels in urban Southeast Asian markets, and contract manufacturing relationships serving cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific essential oils market functions as a stable compounder anchored by wellness tourism infrastructure expansion across Thailand, Bali, and Sri Lanka that sustains structural demand for therapeutic-grade outputs.
For Market Incumbents: Hedge against raw botanical price volatility by securing backward integration into certified organic cultivation partnerships in underpenetrated Indonesian growing regions. Diversify distillation asset deployment toward supercritical CO2 systems that capture premium cosmetic-grade pricing in Tokyo and Seoul fragrance houses, insulating margin from standard-grade commodity pressure.
For New Entrants and Emerging Players: Launch via direct-to-consumer digital platforms in Australia's TGA-regulated pharmacy channel, where therapeutic claim documentation creates entry barriers for unverified competitors. Target spa industry procurement relationships in Thai wellness tourism clusters, leveraging relationship-based customer acquisition models that bypass established distributor layers.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional distillers possessing FSSAI-compliant traceability infrastructure and captive contract farming networks. Long-term viability rests on organic certification asset bases that compound through regulatory tightening across the analysis window. Watch for TGA therapeutic claim standard harmonization with ASEAN regulatory frameworks as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Cultivation Partnership | FSSAI traceability mandates force documented supply chain documentation that locks in premium pricing tiers. |
| Supercritical CO2 Extraction Licensing | Tokyo fragrance houses pay terpene-profile precision premiums that steam distillation cannot replicate. |
| Direct-to-Consumer Channel Expansion | Young Living's Japan-Australia model captures margin otherwise lost to retail distributor markups. |
| Fermentation-Derived Aroma Integration | Takasago's specialized molecules blend with natural oils for batch consistency in clean-label formulations. |
| Wellness Tourism Spa Contracting | Thai resort infrastructure expansion sustains above-average volume pull for therapeutic-grade lavender and tea tree. |
Study Parameters
Direct dialogue with essential oil distillery operators, FSSAI regulatory compliance officers, cosmetic manufacturer procurement leads, and wellness tourism spa directors grounded qualitative insights in operational reality. Secondary validation drew from customs trade databases, FSSAI labeling guidance documents, TGA therapeutic goods registers, and Japan's Ministry of Health, Labour and Welfare cosmetic safety standards. Bottom-up volume estimates from Maharashtra and Karnataka contract farming networks triangulated against top-down essential oil consumption patterns across Southeast Asian cosmetic manufacturers.
Bottom-up modeling aggregated distiller capacity utilization, organic certification conversion timelines, and spa industry procurement volumes across product type, application, and distribution channel segments. Top-down validation cross-referenced wellness tourism infrastructure investment pipelines and clean-label cosmetic formulation adoption curves. CAGRs derived from segment-level growth differential analysis incorporating regulatory enforcement intensity and buyer procurement consolidation patterns. Forecast inputs included FSSAI disclosure mandate implementation pace and supercritical CO2 technology adoption rates in Japanese premium cosmetic applications.
Several conditions sit outside the modeled scope, including extreme weather events disrupting Maharashtra lavender harvests, abrupt TGA therapeutic claim standard revisions, and currency volatility affecting Indian export house competitiveness. Forecasts reflect documented assumptions regarding organic certification timeline completion and spa industry infrastructure buildout continuity. A model refresh is warranted upon material change in FSSAI enforcement intensity or Japan's residual solvent limit regulatory amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market