
 Anisic Aldehyde Market | 2026-2036
Anisic Aldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Anisic Aldehyde Market Analysis
Green chemistry process innovation is reshaping anisic aldehyde production pathways, replacing conventional petroleum-derived routes with biomass-based catalytic hydrogenation. BASF leverages its integrated aroma chemicals platform to secure feedstock advantages across European and Asian production nodes. Atul anchors its position through backward integration into cresol derivatives, while Solvay competes on pharmaceutical-grade certification standards for intermediate applications.
Anisic aldehyde (4-methoxybenzaldehyde) is an aromatic aldehyde with a molecular formula of C8H8O2, characterized by a sweet, floral odor profile and a boiling point near 248°C; it serves primarily as a building block for fragrance compounding, flavor formulation, and active pharmaceutical ingredient synthesis. Synthetic anisic aldehyde dominates volume flows due to cost scalability, though natural-derived variants command premium positioning in clean-label fragrance portfolios. Pharmaceutical intermediate applications are expanding fastest as contract manufacturers seek GMP-certified supply chains, while essential oil isolates occupy niche positions in artisanal perfumery channels.
REACH registration requirements in the European Union and FDA food additive regulations in the United States enforce stringent purity thresholds and toxicological documentation, directly influencing supplier qualification timelines and capital allocation toward analytical testing infrastructure. India's BIS standards for food-grade aromatic chemicals and China's GB standards for fragrance raw materials add further compliance layers for cross-border trade. Stakeholders must monitor evolving biobased labeling criteria and carbon accounting rules that will determine which production routes retain cost-competitive market access.
Market Dynamics
Green chemistry catalytic pathways are compressing cost differentials between petroleum-derived and biomass-based anisic aldehyde, forcing incumbents to reconfigure feedstock sourcing or surrender margin.
Growth Catalysts
- REACH purity mandates:ECHA registration requirements for fragrance intermediates are accelerating supplier consolidation toward GMP-certified producers capable of documenting toxicological profiles.
- Pharmaceutical API demand:Contract manufacturers serving antihistamine and antipyretic synthesis are qualifying dedicated anisic aldehyde supply chains to secure intermediate continuity.
- India flavor house expansion:Domestic compounding capabilities in Mumbai and Hyderabad are absorbing technical-grade volumes previously imported from European suppliers.
Market Restraints
- Cresol feedstock volatility:Ortho-cresol and para-cresol pricing oscillations transmit directly to anisic aldehyde production economics, compressing margin predictability for non-integrated producers.
- Chinese supply concentration:Over half of technical-grade capacity resides in Shandong and Jiangsu provinces, creating geographic risk exposure for buyers lacking dual-source strategies.
- Natural isolate substitution:Artisanal perfumers in Grasse and Geneva are reformulating around star anise and fennel essential oil isolates, eroding synthetic share in premium fragrance segments.
Strategic Opportunities
- Brazilian clean-label penetration:ANVISA's evolving natural ingredient labeling criteria are opening procurement windows for certified biobased anisic aldehyde in São Paulo's cosmetics cluster.
- Carbon accounting integration:EU Green Deal carbon border adjustment mechanisms will reward biomass-hydrogenation routes with preferential market access against petrochemical alternatives.
- Direct-to-compounder digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume fragrance house orders in Southeast Asia.
Industry Challenges
- Analytical chemistry talent scarcity:GC-MS and chiral separation expertise required for REACH-compliant impurity profiling commands premium compensation, constraining smaller producers' qualification timelines.
- Multi-jurisdiction certification overlap:Simultaneous FDA food additive, ECHA REACH, and BIS food-grade filings demand redundant toxicological studies, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anisic Aldehyde Market |
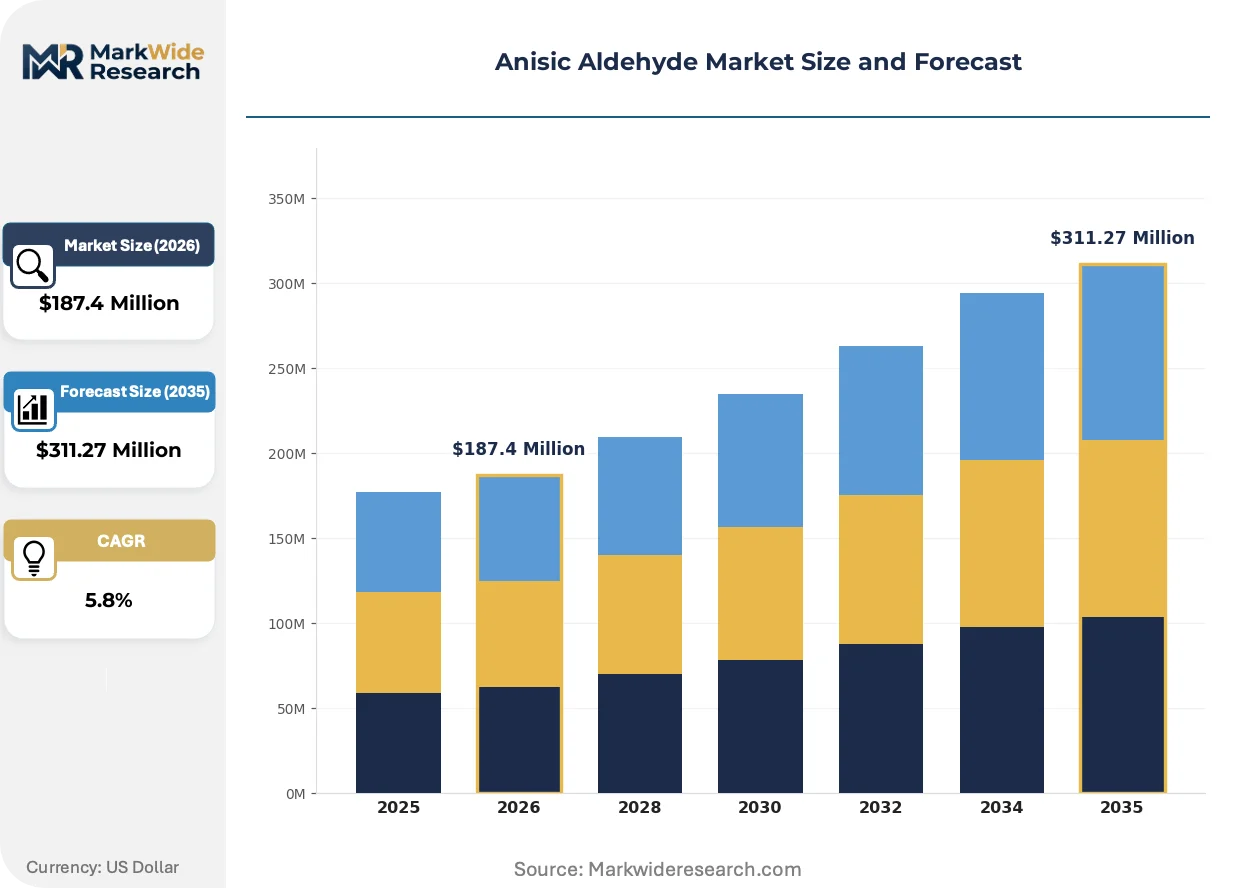
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Anisic Aldehyde, Synthetic Anisic Aldehyde, Isolated Anisic Aldehyde, Essential Oil Application: Fragrance Manufacturing, Flavoring Agent, Pharmaceutical Intermediate, Agrochemical Production End User: Cosmetics Industry, Food and Beverage, Pharmaceuticals, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Brokers |
| Companies Covered | BASF, Atul, Nandolia Chemical, Vigon, Charkit, Solvay, Merck, Kao Corporation, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anisic Aldehyde Market Emerging Trajectories
Biocatalytic reduction pathways and carbon footprint verification protocols are rewriting qualification criteria for anisic aldehyde procurement, privileging producers with documented sustainability credentials over legacy cost leaders.
Continuous-flow hydrogenation of p-methoxytoluene using supported palladium catalysts is collapsing batch reactor economics for synthetic anisic aldehyde. Fragrance compounders in Germany and Switzerland are qualifying these outputs for high-volume fine fragrance applications. The technology is collapsing minimum efficient scale thresholds, enabling regional production nodes to challenge centralized Asian supply.
REACH authorization requirements for Substances of Very High Concern are tightening impurity thresholds for aromatic aldehydes entering EU cosmetic and food contact applications. ECHA's 2024 updated guidance on respiratory sensitizers is forcing reformulation documentation for sprayable fragrance products. Suppliers are responding by investing in chiral separation capabilities to isolate enantiomer-specific odor profiles with cleaner toxicological footprints.
Compounders are consolidating supplier panels around vertically integrated producers capable of delivering carbon-intensity certificates alongside material safety data sheets. Direct procurement teams at major fragrance houses are bypassing traditional distributors for annual volume contracts tied to Scope 3 emission reduction targets. This concentration is most visible in Netherlands and France, where sustainability-linked procurement policies now govern intermediate sourcing decisions.
Anisic Aldehyde Market Segmentation
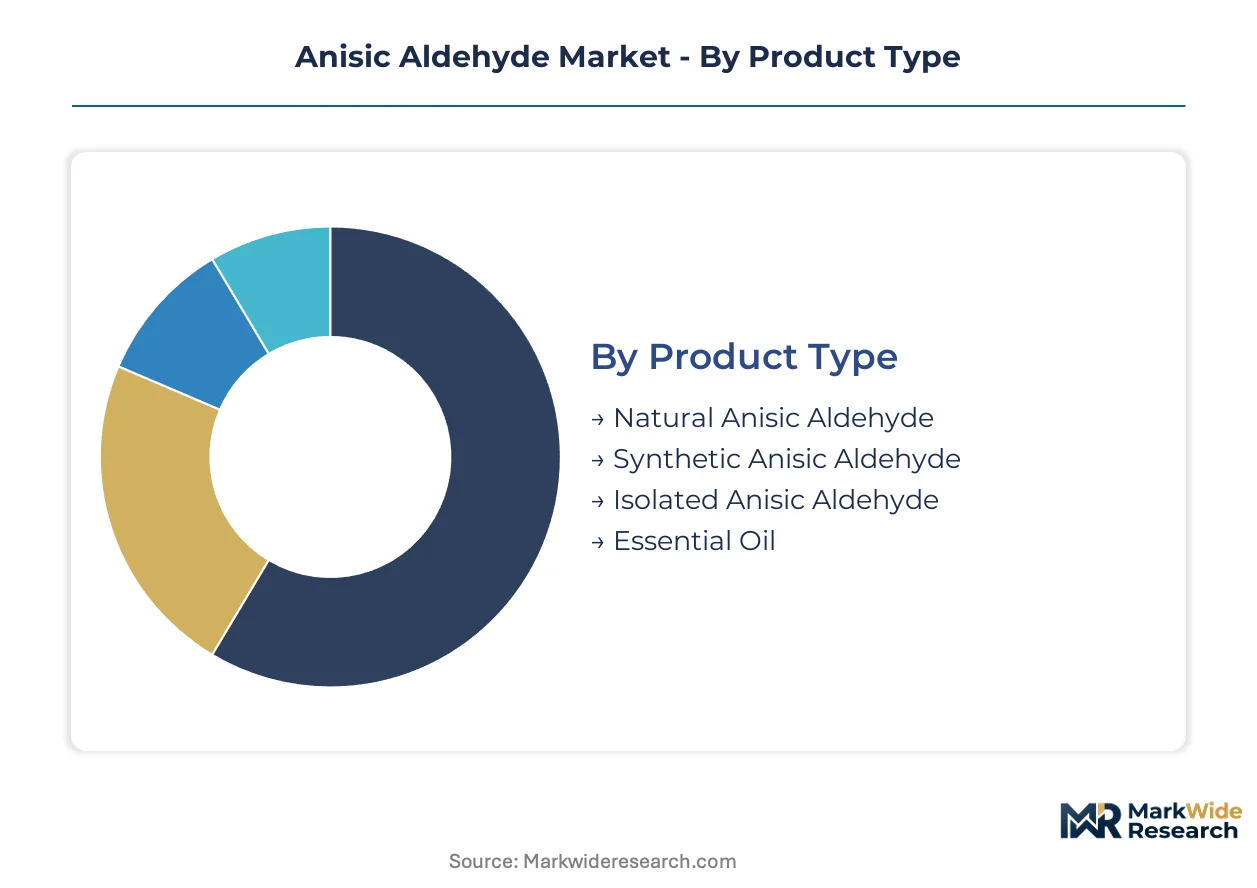
Segmentation in the anisic aldehyde market reveals how purity grades, application specifications, and channel economics create distinct competitive arenas. Procurement teams at fragrance houses and pharmaceutical manufacturers prioritize different attributes, fragmenting supplier strategies across these dimensions.
Product Type:
Cost tiers separate product types, with feedstock origin and purification intensity determining price positioning and regulatory qualification pathways.
- Natural Anisic Aldehyde:Derived from star anise or fennel essential oil through fractional distillation and selective oxidation. European clean-label fragrance portfolios in Grasse and Geneva absorb premium-priced volumes as ECHA biobased labeling criteria tighten. REACH-compliant toxicological documentation extends supplier qualification timelines beyond synthetic alternatives.
- Synthetic Anisic Aldehyde:Manufactured via catalytic hydrogenation of p-methoxytoluene using supported palladium catalysts. High-volume fragrance compounders in Germany and Switzerland qualify these outputs for fine fragrance applications where cost scalability outweighs natural provenance claims. Continuous-flow reactor technology is collapsing minimum efficient scale thresholds.
- Isolated Anisic Aldehyde:Purified from crude essential oil fractions through molecular distillation. Artisanal perfumers in niche channels specify these grades for enantiomer-specific odor profiles.
- Essential Oil:Unfractionated star anise or fennel oil containing anisic aldehyde as a constituent. Regional aromatherapy and traditional medicine applications in India and China consume these unpurified forms.
Synthetic grades command the established base. The steepest expansion runs through natural variants as biobased certification requirements proliferate.
Application:
Application segments reflect divergent purity mandates, with pharmaceutical and food-contact specifications enforcing stricter impurity thresholds than industrial fragrance uses.
- Fragrance Manufacturing:Fine fragrance and functional perfumery applications demand odor consistency and regulatory compliance for skin contact. German and Swiss compounders are consolidating supplier panels around producers delivering carbon-intensity certificates alongside material safety data sheets.
- Flavoring Agent:Food-grade specifications require FDA food additive clearance or EFSA positive listings, with toxicological documentation spanning reproductive and developmental endpoints. Indian BIS standards and Chinese GB standards add further compliance layers for cross-border trade.
- Pharmaceutical Intermediate:GMP-certified supply chains serve antihistamine and antipyretic API synthesis. Contract manufacturers are qualifying dedicated anisic aldehyde supply chains to secure intermediate continuity.
- Agrochemical Production:Technical-grade material enters pesticide and fungicide synthesis where odor profile matters less than cost efficiency.
Fragrance manufacturing anchors volume consumption. Pharmaceutical intermediate applications are climbing the fastest as GMP certification requirements concentrate procurement toward qualified suppliers.
End User:
End user categories map to distinct regulatory jurisdictions, with cosmetics and pharmaceuticals facing the most stringent multi-jurisdiction certification burdens.
- Cosmetics Industry:EU cosmetic regulation and FDA cosmetic guidance govern skin contact applications. ECHA's updated respiratory sensitizer guidance is forcing reformulation documentation for sprayable fragrance products.
- Food and Beverage:Flavor houses in Mumbai and Hyderabad are scaling technical compounding capabilities, absorbing volumes previously imported from European suppliers.
- Pharmaceuticals:API manufacturers require chiral separation capabilities and enantiomer-specific toxicological profiles.
- Agriculture:Technical-grade anisic aldehyde serves crop protection chemistry with less stringent purity requirements.
Cosmetics and food and beverage end users dominate procurement. Pharmaceutical applications are gaining share fastest as contract manufacturing organizations expand GMP-qualified supply chains.
Distribution Channel:
Channel structure reflects order scale and technical service intensity, with large fragrance houses bypassing intermediaries while smaller compounders rely on distributor inventory and regulatory support.
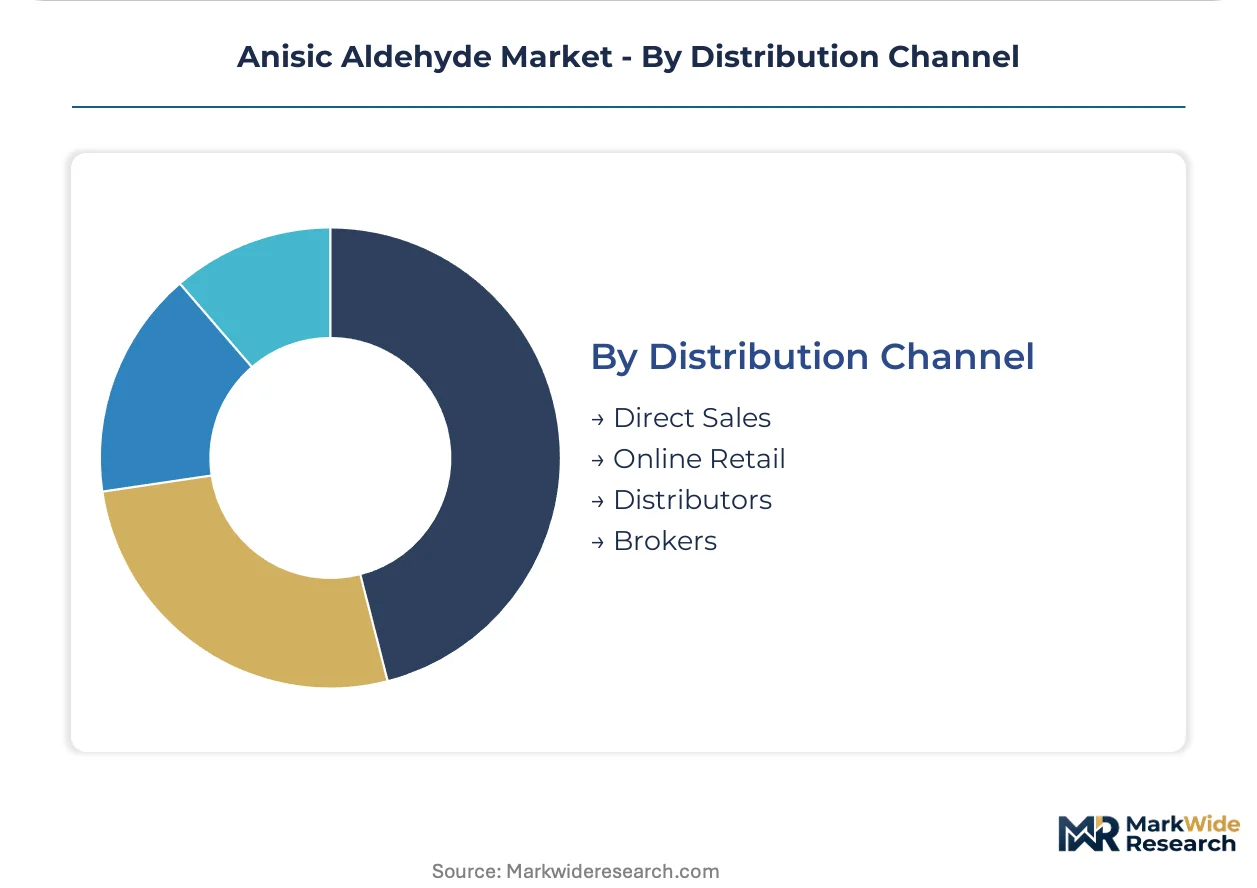
- Direct Sales:Annual volume contracts tie major fragrance houses to integrated producers with documented Scope 3 emission reduction targets. Netherlands and France show the most concentrated direct procurement policies.
- Online Retail:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume fragrance house orders in Southeast Asia.
- Distributors:Regional inventory positions and regulatory documentation support serve smaller compounders lacking in-house toxicological expertise.
- Brokers:Spot market liquidity for technical-grade material serves agrochemical and industrial applications with flexible timing requirements.
Direct sales channels capture the largest transaction values. Online retail platforms are expanding most quickly as digital procurement penetrates mid-tier compounder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese exports of technical-grade anisic aldehyde flow predominantly to fragrance compounders in Germany and Switzerland, while Indian manufacturers supply flavor houses across Southeast Asia and the Middle East. This trade pattern reflects divergent specialization: Shandong and Jiangsu provinces dominate cost-driven volume production, whereas Mumbai and Hyderabad concentrate on food-grade certification for export markets.
China
Shandong and Jiangsu provinces host over half of global technical-grade capacity, serving antihistamine API manufacturers and agrochemical formulators. MEE enforcement of dual carbon goals is pressuring petrochemical-based hydrogenation routes toward biomass alternatives. The Yangtze River Delta cluster is consolidating around producers with integrated carbon accounting systems for EU-bound exports.
Germany
Fine fragrance compounders in Cologne and Düsseldorf drive premium-grade procurement, prioritizing REACH-compliant toxicological documentation. KBA-aligned chemical safety protocols extend qualification timelines for imported intermediates. The North Rhine-Westphalia corridor is attracting continuous-flow reactor investments to compress batch economics for regional supply security.
India
Domestic flavor houses in Mumbai and Hyderabad are scaling technical compounding capabilities, displacing volumes previously imported from European suppliers. FSSAI and BIS standards for food-grade aromatic chemicals add compliance layers for cross-border trade. The Gujarat chemical belt is backward-integrating into cresol derivatives to buffer feedstock volatility.
Switzerland
Geneva-based artisanal perfumers specify enantiomer-specific isolates for luxury fragrance portfolios, commanding premium positioning over synthetic alternatives. Swissmedic pharmaceutical-grade certification requirements concentrate procurement toward GMP-qualified suppliers. The Basel pharmaceutical cluster is qualifying dedicated anisic aldehyde supply chains for antipyretic API synthesis.
Brazil
São Paulo's cosmetics cluster is absorbing certified biobased anisic aldehyde as ANVISA tightens natural ingredient labeling criteria. The country's national pharmaceutical regulator is harmonizing impurity thresholds with ECHA guidance for imported intermediates. The southeastern industrial corridor is emerging as a procurement hub for clean-label fragrance formulations serving Latin American markets.
Anisic Aldehyde Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated producers capable of delivering carbon-intensity certificates alongside material safety data sheets. The vendor base stratifies across three tiers: multinational chemical conglomerates with integrated aroma platforms, regional specialists with backward integration into cresol feedstocks, and niche isolators serving artisanal perfumery channels. Dominant competitive moves include capacity expansion in low-carbon hydrogenation routes and strategic partnerships with fragrance houses for Scope 3 emission reduction targets.
Among European-based chemical conglomerates, BASF and Solvay occupy positions anchored by pharmaceutical-grade certification standards and integrated production networks. Atul represents the regional specialist archetype with upstream control over cresol derivatives. These three exemplify divergent strategic postures: multinational platform breadth versus feedstock integration depth versus certification-focused intermediates positioning.
| Leading Market Players |
|---|
| BASF |
| Atul |
| Nandolia Chemical |
| Vigon |
| Charkit |
| Solvay |
| Merck |
| Kao Corporation |
| Tokyo Chemical Industry |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu province concentration in technical-grade production anchors margin capture at the cresol-to-aldehyde conversion stage, while downstream fragrance compounders in Germany and Switzerland absorb premium-grade markups tied to REACH documentation and carbon certification.
Pricing Analysis
Continuous-flow reactor technology gaps separate synthetic pricing tiers: legacy batch hydrogenation commands standard-grade positioning, while continuous-flow outputs qualify for premium fragrance contracts. Three-tier pricing structure across premium natural isolates, certified synthetic grades, and technical agrochemical material reflects purity and documentation intensity. Cost compression in standard synthetic tiers is intensifying because Chinese capacity additions outpace demand growth in functional perfumery. Agrochemical formulators exhibit highest price sensitivity; artisanal perfumers in Geneva tolerate premium multiples for enantiomer-specific isolates.
Supply Chain Analysis
Extended payment terms from European fragrance houses now stretch 90-120 days, forcing mid-tier producers to rely on supply-chain finance facilities anchored by receivables. Manufacturing concentrates in China, India, and Germany, with raw material flows drawing from ortho-cresol and para-cresol streams, palladium catalyst supply, and star anise essential oil harvests. Single-source vulnerability runs through Shandong province technical-grade concentration, where environmental enforcement disruptions ripple downstream. Distribution runs through direct annual contracts for major compounders, specialty chemical platforms for mid-volume orders, and regional distributors serving smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocatalytic reduction pathways and EU carbon border adjustment mechanisms are disrupting qualification criteria faster than legacy producers can reconfigure, compressing the window for competitive repositioning.
For Market Incumbents: Harden GMP-certified supply chain continuity through captive cresol derivative production or long-term offtake agreements with Shandong and Jiangsu producers. Deepen analytical chemistry capabilities—GC-MS and chiral separation expertise—to compress REACH qualification timelines as ECHA impurity thresholds tighten. Defensive consolidation around carbon-accounting infrastructure will separate survivors from margin-squeezed commodity suppliers. For New Entrants and Emerging Players: Brazilian clean-label cosmetics clusters offer the most penetrable white-space, where ANVISA natural ingredient criteria outrun local biobased supply capacity. Target pharmaceutical intermediate qualification in Basel and Mumbai, where GMP-certified supply chain gaps create procurement windows for dedicated producers. A direct-to-compounder digital channel strategy—bypassing traditional distributor networks—captures mid-volume fragrance house orders with lower customer acquisition cost than legacy field sales models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists possessing cresol backward integration but lacking carbon certification infrastructure. Five-to-ten-year viability hinges on biomass-hydrogenation route conversion and Scope 3 emission documentation capabilities. The signal to watch is EU Green Deal implementation pace, which will determine whether petrochemical-derived inventory becomes stranded or retains cost-competitive market access.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass-Based Hydrogenation Capacity Expansion | MEE dual carbon enforcement in China and EU border adjustments privilege low-carbon routes. |
| Backward Integration into Cresol Derivatives | Atul's Gujarat chemical belt model buffers feedstock volatility for margin stability. |
| GMP-Certified Supply Chain Qualification | Swissmedic and CDSCO pharmaceutical-grade requirements concentrate procurement toward qualified suppliers. |
| Carbon Intensity Certification Investment | Netherlands and France sustainability-linked procurement policies now govern intermediate sourcing decisions. |
| Direct-to-Compounder Digital Platform Launch | Southeast Asian specialty chemical platforms disintermediate traditional distributor networks for mid-volume orders. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, ECHA REACH registration databases, BIS and GB standards filings, and fragrance house annual procurement disclosures. Plant managers at Shandong and Jiangsu production facilities, procurement leads at German and Swiss compounders, distribution channel partners in Mumbai and São Paulo, and technical R&D directors at integrated aroma platforms provided operational validation. Bottom-up capacity and demand modeling triangulates against top-down trade flow analysis to constrain estimate variance.
Forecast inputs span grade tier differentiation, end-use industry absorption rates, regional production hub competitiveness, and certification pathway timelines. Segmentation across natural, synthetic, and isolated product types; fragrance, flavor, pharmaceutical, and agrochemical applications; and direct, distributor, and digital channels informs volume allocation. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity commissioning schedules, with pharmaceutical intermediate growth rates calibrated to antihistamine and antipyretic API pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-supported Chinese producers or PE-backed consolidation platforms would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Citronellol Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Aroma Chemicals Market
Flavor and Fragrance Chemicals
Linalool Market