
 Flavors for Pharmaceutical and Healthcare Applications Market | 2026-2036
Flavors for Pharmaceutical and Healthcare Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Flavors for Pharmaceutical and Healthcare Applications Market Foresight
The EU Green Deal is shifting flavor procurement criteria across European pharmaceutical supply chains, favoring biodegradable solvents and renewable feedstocks in nature-identical synthesis. International Flavors & Fragrances leverages its biotechnology platform to produce fermentation-derived flavor molecules that bypass petrochemical routes. Symrise AG anchors its healthcare division with captive extraction capabilities for botanical raw materials sourced under FairWild certification. Givaudan SA competes through integrated sensory science laboratories that link patient taste preference data directly to formulation development.
Flavors for pharmaceutical and healthcare applications comprise GRAS-listed aromatic compounds, essential oil distillates, and encapsulated taste modifiers engineered to mask bitter active pharmaceutical ingredients at thresholds below detectable aftertaste. Spray-dried and encapsulated delivery formats dominate pediatric and geriatric segments where powder reconstitution and controlled release determine compliance outcomes. Natural flavors command premium positioning in nutraceutical applications where clean-label claims support retail differentiation, while artificial flavors sustain volume share in generic prescription drugs where cost containment governs procurement. Liquid emulsions lead veterinary medicine applications due to dosing flexibility across species-specific palatability profiles.
FDA GRAS notifications and EFSA flavoring substance evaluations create dual-track compliance burdens for suppliers serving transatlantic pharmaceutical clients, with ECHA REACH registrations adding toxicity data requirements for synthetic precursors. India's CDSCO mandates BIS-certified flavor inputs for domestically manufactured pediatric syrups, tightening import substitution incentives under PLI scheme extensions. Stakeholders must monitor evolving pharmacopeial monographs for excipient-grade flavor purity specifications as USP-NF and EP alignment discussions progress.
Market Dynamics
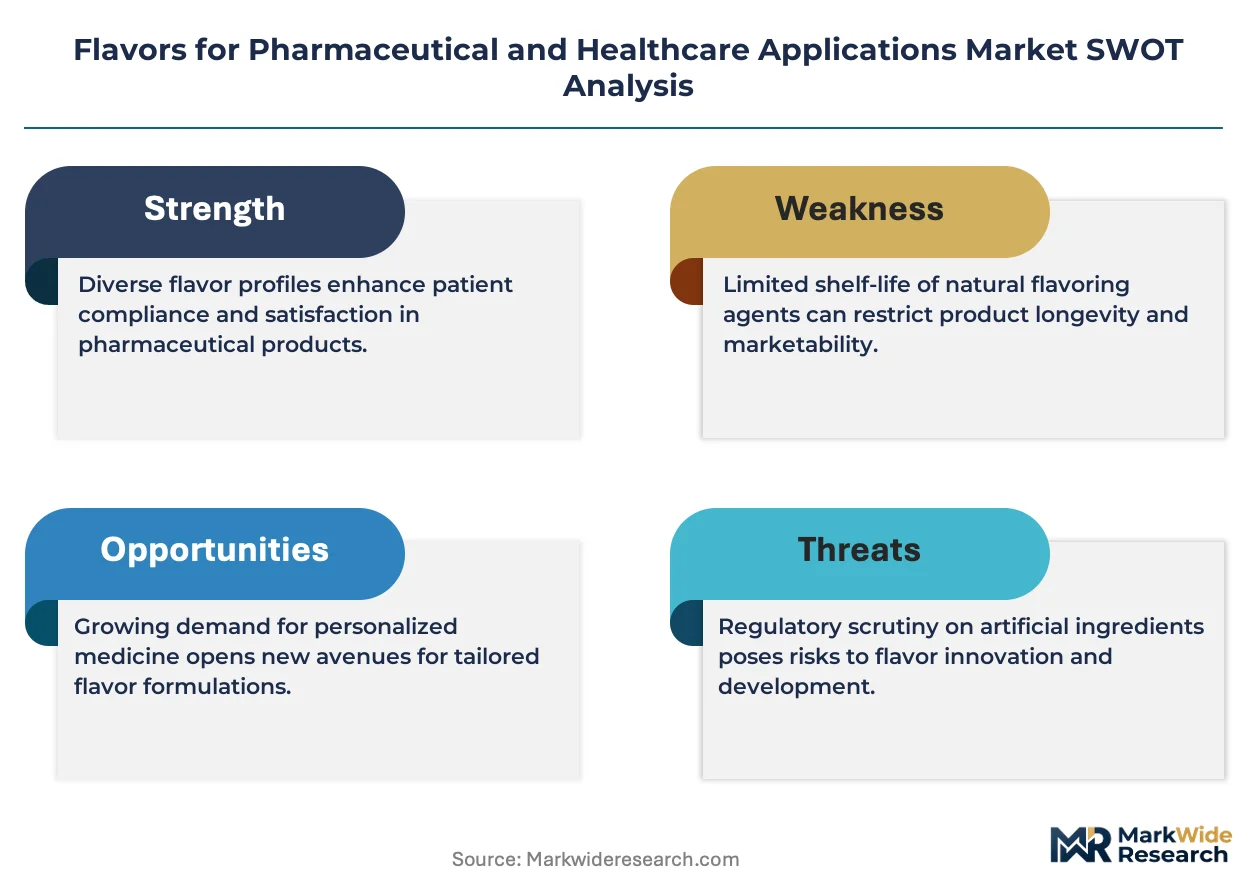
Patient adherence economics are restructuring pharmaceutical flavor procurement, with formulation teams now treating taste-masking as a clinical outcome variable rather than an aesthetic afterthought in pediatric and geriatric dosage development.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants in metered-dose inhalers is accelerating demand for aqueous-based flavor systems that maintain stability without volatile solvent carriers.
- Essential oil microencapsulation:Spray-drying technologies now achieve 98% payload retention for heat-sensitive botanical extracts, expanding natural flavor viability in effervescent tablets and hot-melt extrusions.
- Geriatric polypharmacy clusters:Japan's super-aged municipalities are piloting flavored combination therapies where taste consistency across multiple prescriptions reduces regimen abandonment.
Market Restraints
- Botanical supply concentration:Madagascar and Indonesia supply 70% of global vanilla and clove extracts, exposing flavor houses to cyclone-driven harvest volatility and speculative price spikes.
- REACH registration cascades:ECHA's 2023 update to flavoring substance inventory thresholds requires new toxicity dossiers for synthetic aldehyde precursors, extending time-to-market for reformulated products.
- Biotechnology substitution:Fermentation-derived flavor molecules from precision-engineered yeast strains are capturing nutraceutical contracts at 40% lower carbon intensity, pressuring botanical extraction margins.
Strategic Opportunities
- India's PLI scheme extensions:Domestic pediatric syrup manufacturers now receive 6-8% production-linked incentives for using BIS-certified flavor inputs, creating captive demand for localized supply chains.
- Veterinary flavor emulsions:Species-specific palatability profiles for companion animal therapeutics remain underdeveloped outside North America and Western Europe, with Latin American markets showing 23% unmet need.
- WHO prequalification alignment:Essential medicines list reformulations for malaria and tuberculosis treatments now incorporate taste-masking specifications, opening procurement channels for GRAS-listed excipient suppliers.
Industry Challenges
- Sensory scientist scarcity:Cross-trained professionals fluent in both pharmaceutical excipient chemistry and consumer taste panel methodology command 35% salary premiums, constraining mid-tier flavor house expansion.
- Dual-track compliance timelines:Simultaneous FDA GRAS notification and EFSA flavoring substance evaluation processes create 18-24 month approval windows that misalign with abbreviated new drug application cycles.
- Legacy ERP integration:Batch record systems designed for commodity chemical manufacturing require expensive customization to track flavor lot traceability from botanical harvest through finished dosage form.
Report Scope
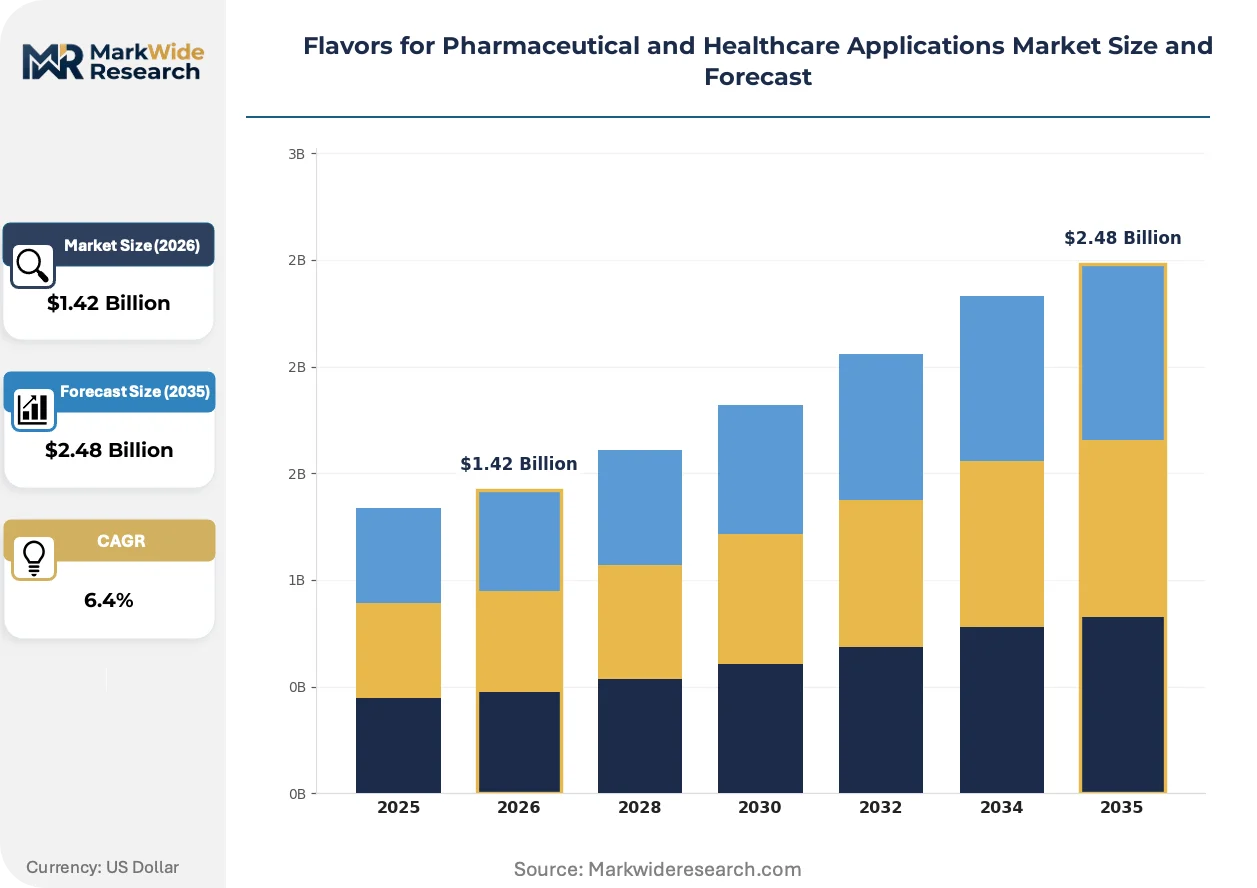
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavors for Pharmaceutical and Healthcare Applications Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Nature-Identical Flavors, Functional Flavors, Essential Oil-Based Flavors Application: Oral Care, Nutraceuticals, Over-The-Counter Medicines, Prescription Drugs, Veterinary Medicines End User: Pharmaceutical Manufacturers, Contract Research Organizations, Biotechnology Firms, Veterinary Clinics, Nutraceutical Companies Delivery Format: Liquid Flavors, Powder Flavors, Encapsulated Flavors, Spray-Dried Flavors, Emulsions |
| Companies Covered | International Flavors & Fragrances, Symrise AG, Givaudan SA, Firmenich SA, Mane SA, Keva Flavours, DSM-Firmenich, Kerry Group, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavors for Pharmaceutical and Healthcare Applications Market Shifts & Advancements
Biotechnology platforms and regulatory chemistry are converging to rewrite how pharmaceutical flavors are synthesized, certified, and integrated into patient-centric dosage forms across therapeutic categories.
Continuous manufacturing systems for hot-melt extrusion are modularizing flavor incorporation into solid oral dosage production, allowing real-time taste adjustment during scale-up rather than post-batch reformulation. Pediatric-focused contract development organizations in the United States and Germany are adopting these skid-mounted units to compress development timelines for bitter active pharmaceutical ingredients. The technology is modularizing quality-by-design protocols, embedding sensory release specifications directly into process analytical technology frameworks.
REACH authorization requirements for synthetic musk compounds used in veterinary flavor masking are forcing reformulation of long-acting injectable products across European manufacturing sites. The industrial consequence is a 40% reduction in available fragrance precursors for palatability enhancement, driving substitution toward nature-identical alternatives with shorter toxicological dossiers. Generic drug manufacturers in Central and Eastern Europe are responding by consolidating flavor procurement through shared regulatory submission consortia to amortize compliance costs.
Hospital formulary committees are consolidating flavor specification authority under pharmacy and therapeutics subcommittees, displacing traditional procurement-driven vendor selection. This centralization is most visible in United States academic medical centers, where taste-masking efficacy data now appears alongside bioequivalence documentation in therapeutic interchange evaluations. The shift is compressing supplier qualification cycles and favoring flavor houses with captive clinical taste panel capabilities over commodity distributors.
Flavors for Pharmaceutical and Healthcare Applications Market Segmentation
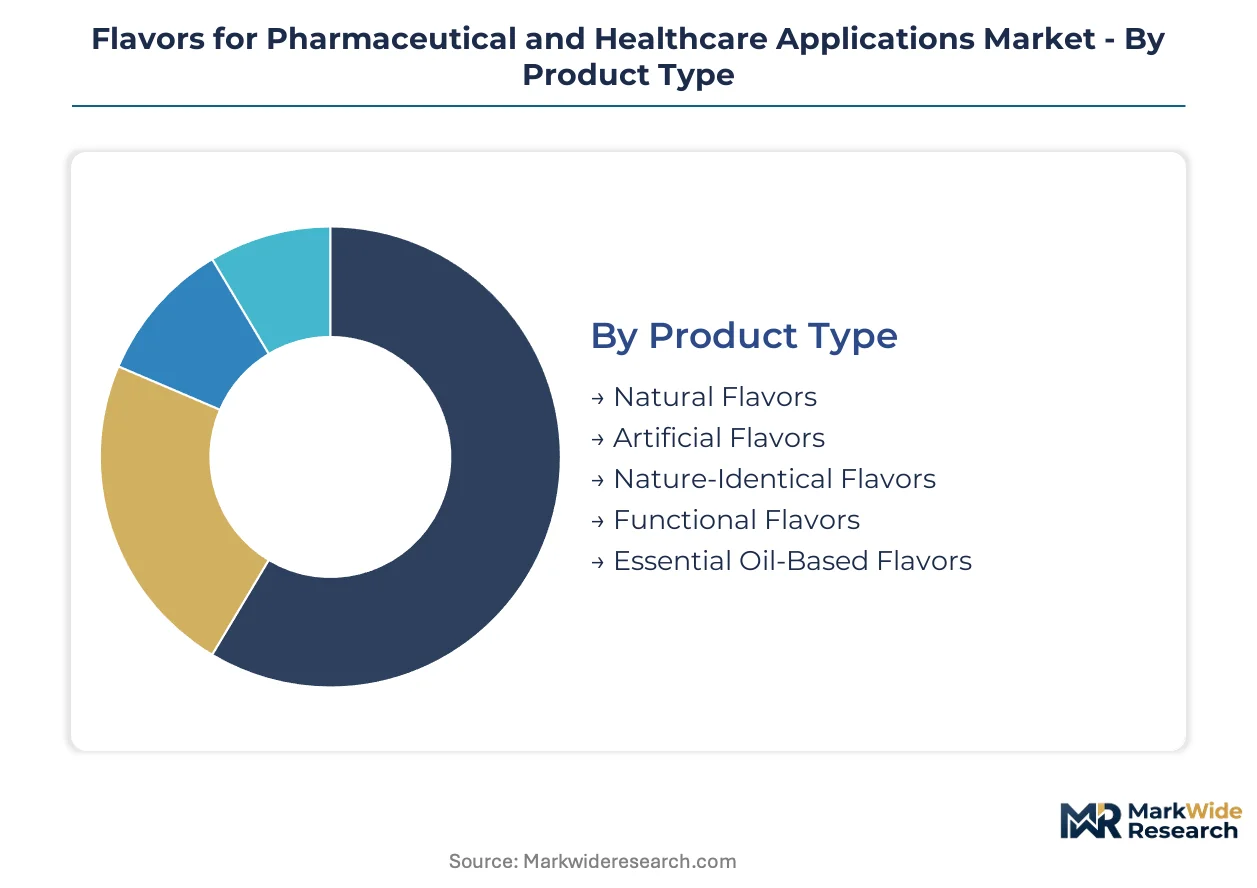
Flavor segmentation in pharmaceutical applications tracks how formulation requirements diverge across therapeutic categories, regulatory jurisdictions, and patient demographics. Procurement teams select product types and delivery formats based on active pharmaceutical ingredient compatibility, stability profiles, and adherence economics rather than sensory preference alone.
Product Type:
Cost tier separates buyers in this category, with premium natural extracts commanding formulation budgets for clean-label nutraceuticals while synthetic alternatives sustain generic drug margins.
- Natural Flavors:GRAS-listed botanical distillates and cold-pressed extracts deliver complex aromatic profiles for pediatric syrups and premium supplements. Demand concentrates in Germany and United States nutraceutical manufacturing where EFSA and FDA clean-label claims support retail price premiums, though Madagascar vanilla and Indonesian clove supply concentration exposes formulators to harvest volatility.
- Artificial Flavors:Synthetic aromatic compounds engineered for thermal stability and batch-to-batch consistency dominate effervescent tablets and hot-melt extrusions. Volume sits with Indian generic manufacturers under CDSCO pediatric syrup mandates where cost containment governs procurement decisions, with PLI scheme extensions reinforcing domestic sourcing.
- Nature-Identical Flavors:Chemically identical to botanical sources but synthesized via petrochemical or fermentation routes, these compounds bridge regulatory acceptance and supply security. ECHA REACH registrations for synthetic precursors extend time-to-market for reformulated products.
- Functional Flavors:Taste modifiers with bitter-blocking or sweetness-enhancing properties engineered to mask active pharmaceutical ingredients below detectable thresholds. Japan's PMDA has piloted these in super-aged municipality combination therapies.
- Essential Oil-Based Flavors:Terpene-rich distillates from citrus, mint, and spice sources provide antimicrobial co-benefits in oral care applications. Spray-drying technologies now achieve payload retention sufficient for solid dosage integration.
Volume sits with Artificial Flavors; growth tilts toward Nature-Identical Flavors as biotechnology platforms displace petrochemical synthesis routes.
Application:
Patient adherence economics differentiate buyers, with pediatric and geriatric segments treating taste-masking as a clinical outcome variable while veterinary and OTC categories prioritize dosing flexibility.
- Oral Care:Antimicrobial flavor systems in toothpaste and mouthwash formulations leverage essential oil synergies with active ingredients. Demand clusters in United States and German manufacturing where pharmacy and therapeutics committees now require taste-masking efficacy documentation alongside bioequivalence data.
- Nutraceuticals:Clean-label positioning drives natural flavor procurement for gummies, powders, and functional beverages. EFSA health claim evaluations and FDA GRAS notifications create dual-track compliance burdens for suppliers serving transatlantic clients.
- Over-The-Counter Medicines:Cough syrups, antacids, and analgesic formulations rely on flavor systems to differentiate shelf presence and improve repeat purchase. India's BIS certification requirements for pediatric syrups tighten under PLI scheme extensions.
- Prescription Drugs:Generic manufacturers prioritize cost-stable synthetic flavors while innovator firms specify custom masking profiles for lifecycle management. EMA centralized procedures increasingly reference taste-masking in pediatric investigation plans.
- Veterinary Medicines:Species-specific palatability profiles for companion and livestock therapeutics use liquid emulsions for dosing flexibility. Latin American markets show substantial unmet need outside established North American and Western European supply chains.
Volume concentrates in Prescription Drugs; expansion moves fastest in Veterinary Medicines as companion animal therapeutic markets mature across emerging economies.
End User:
Supply chain position distinguishes buyers, with integrated pharmaceutical manufacturers demanding captive flavor development capabilities while contract organizations seek modular, rapid-turnaround solutions.
- Pharmaceutical Manufacturers:Global innovators and generic houses maintain internal formulation teams that specify flavor systems during early-phase development. FDA GRAS notification timelines now misalign with abbreviated new drug application cycles, compressing supplier qualification windows.
- Contract Research Organizations:Pediatric-focused CROs in United States and Germany adopt continuous manufacturing skids for real-time taste adjustment during scale-up rather than post-batch reformulation.
- Biotechnology Firms:Fermentation-derived therapeutic developers increasingly specify biotechnology-produced flavor molecules to align with platform messaging and carbon intensity targets.
- Veterinary Clinics:Compounding pharmacies and regional distributors procure flavor emulsions for customized palatability in exotic species and individualized dosing regimens.
- Nutraceutical Companies:Direct-to-consumer brands drive demand for rapid flavor prototyping and clean-label certification to support retail differentiation claims.
Volume rests with Pharmaceutical Manufacturers; growth accelerates most steeply in Contract Research Organizations as outsourcing of pediatric formulation development expands.
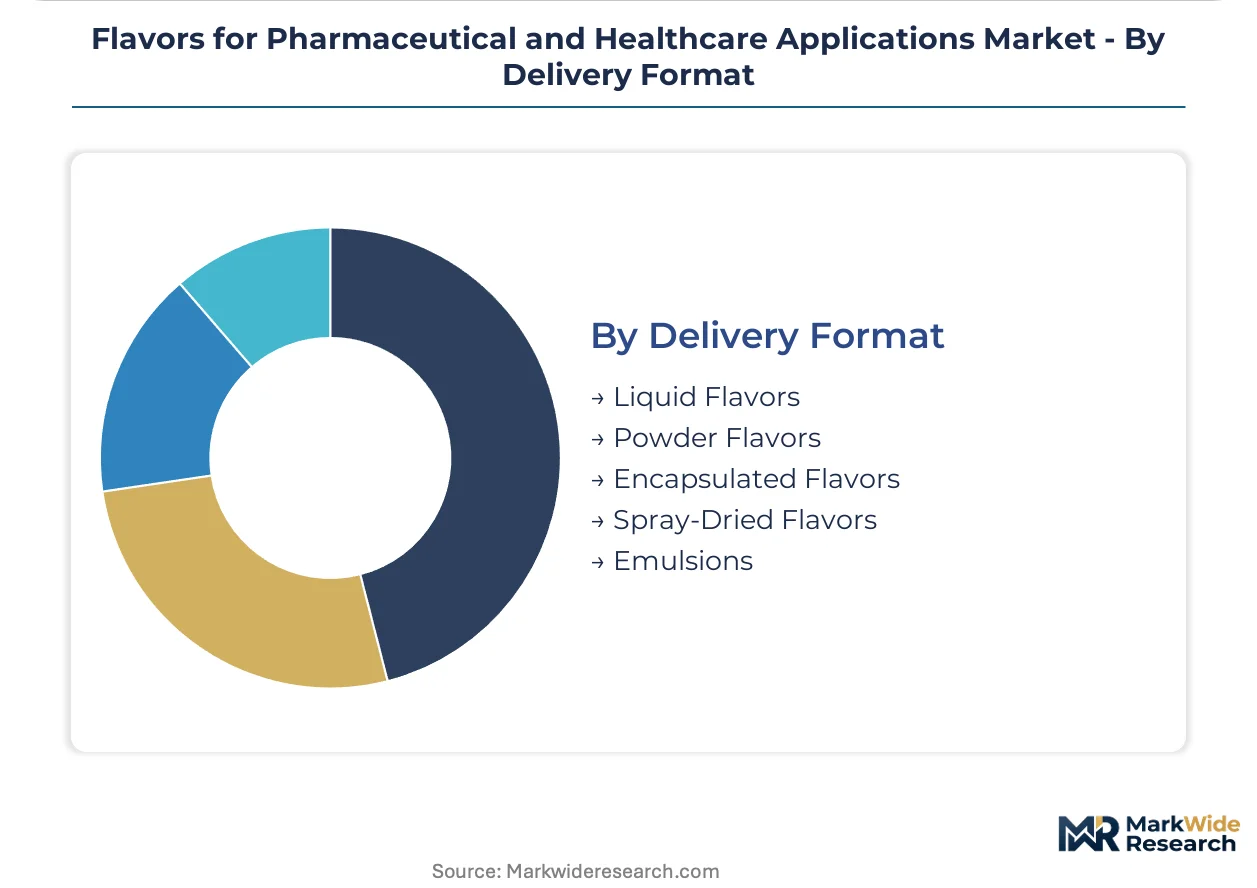
Delivery Format:
Process technology requirements separate buyers, with hot-melt extrusion and continuous manufacturing favoring thermally stable powder formats while liquid systems retain flexibility for batch compounding.
- Liquid Flavors:Alcohol-based and aqueous solutions enable rapid prototyping and small-batch adjustment in veterinary and compounding applications. EU F-Gas Regulation phasedown of hydrofluorocarbon propellants is accelerating demand for aqueous-based systems that maintain stability without volatile solvent carriers.
- Powder Flavors:Granulated and free-flowing formats integrate into direct compression and roller compaction processes for high-volume tablet manufacturing. Indian generic producers under CDSCO mandates favor these for pediatric syrup powder reconstitution.
- Encapsulated Flavors:Lipid or polymer matrices control release kinetics and protect volatile compounds from oxidation during shelf life. EMA stability guidelines increasingly reference encapsulation performance in accelerated aging protocols.
- Spray-Dried Flavors:Maltodextrin or gum arabic matrices achieve payload retention for heat-sensitive botanical extracts, expanding natural flavor viability in effervescent tablets. WHO prequalification alignment for essential medicines now incorporates taste-masking specifications suitable for this format.
- Emulsions:Oil-in-water systems deliver hydrophobic flavor compounds with uniform dispersion in aqueous dosage forms, dominating veterinary medicine applications across species-specific palatability profiles.
Volume concentrates in Powder Flavors; steepest expansion trajectory belongs to Spray-Dried Flavors as natural extract stability requirements intensify across oral solid dosage categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor production clusters concentrate in Germany, the United States, and China while consumption spreads across pharmaceutical manufacturing hubs in India and Japan. This geographic split creates trade flows of essential oil extracts and synthetic precursors across regulatory boundaries.
United States
FDA GRAS notification workloads and pediatric formulation outsourcing drive demand for captive sensory science capabilities. Hospital formulary committees in academic medical centers now require taste-masking efficacy documentation alongside bioequivalence data. Greater Boston and Research Triangle Park host contract research organizations adopting continuous manufacturing skids for real-time flavor adjustment.
Germany
EMA centralized procedures and REACH compliance requirements shape procurement criteria for biodegradable solvents in nature-identical synthesis. The EU Green Deal accelerates adoption of fermentation-derived molecules. Bavaria and North Rhine-Westphalia anchor flavor house operations with integrated extraction and biotechnology platforms serving transatlantic pharmaceutical clients.
China
NMPA regulatory harmonization and domestic pharmaceutical manufacturing expansion create demand for cost-stable synthetic flavors. Yangtze River Delta clusters integrate flavor procurement into pediatric syrup production for export markets. Dual carbon goals pressure suppliers toward biotechnology routes with lower carbon intensity than petrochemical synthesis.
India
CDSCO mandates BIS-certified flavor inputs for domestically manufactured pediatric syrups under PLI scheme extensions. Maharashtra and Gujarat pharmaceutical corridors develop localized supply chains to capture 6-8% production-linked incentives. Import substitution policies tighten specifications for botanical raw materials in generic drug formulations.
Japan
PMDA pilot programs in super-aged municipalities test flavored combination therapies to reduce polypharmacy regimen abandonment. Kanto and Kansai regions concentrate formulation development for geriatric palatability applications. METI guidance on patient adherence economics elevates taste-masking to clinical outcome status in reimbursement evaluations.
Flavors for Pharmaceutical and Healthcare Applications Market Competitive Landscape
The competitive structure tilts toward integrated sensory science platforms with captive biotechnology capabilities. Tier-one flavor houses maintain vertical control over botanical extraction and fermentation-derived molecule production. Three archetypes dominate: global innovators with pharmaceutical-dedicated healthcare divisions, regional specialists leveraging geographic regulatory expertise, and biotechnology platforms displacing petrochemical synthesis routes. Consolidation through merger activity and strategic technology licensing reshapes supplier relationships with formulation teams.
Among Switzerland-based and German-anchored innovators, Givaudan SA, Symrise AG, and International Flavors & Fragrances exemplify the integrated platform archetype. These entities occupy positions spanning GRAS-listed compound development, clinical taste panel capabilities, and captive supply of botanical raw materials under sustainability certification. Their scale enables simultaneous FDA and EFSA compliance submissions that align with abbreviated new drug application timelines.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Symrise AG |
| Givaudan SA |
| Firmenich SA |
| Mane SA |
| Keva Flavours |
| DSM-Firmenich |
| Kerry Group |
| Takasago International Corporation |
| Others |
Supply & Pricing Matrix
Botanical raw material costs cascade from Madagascar vanilla harvests through three-tier pricing structure across premium, standard, and economy levels, with FairWild-certified extracts commanding formulation budgets while synthetic alternatives sustain Indian generic drug margins under CDSCO cost containment mandates.
Pricing Analysis
Value-based pricing anchored to patient adherence outcomes separates premium natural extracts from commodity synthetics. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EFSA clean-label claims supporting retail premiums. Pricing pressure stems from biotechnology substitution as fermentation-derived molecules capture nutraceutical contracts. Generic drug manufacturers in India exhibit highest price sensitivity; innovator firms in Germany and the United States show lowest.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia flavor house operations tighten as cross-trained sensory scientists command salary premiums. Madagascar, Indonesia, and India anchor geographic supply concentration for vanilla, clove, and BIS-certified synthetic inputs respectively. Raw material dependencies rest on cyclone-exposed botanical harvests, REACH-registered synthetic precursors, and fermentation feedstocks. Single-source vulnerability from Madagascar vanilla concentration threatens supply security. Distribution runs through pharmaceutical manufacturing clusters in Germany, the United States, and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated biotechnology platforms as REACH registration cascades and sensory scientist scarcity force mid-tier flavor houses toward acquisition or exit.
For Market Incumbents: Anchor market position through captive extraction capabilities under FairWild certification and backward integration into fermentation-derived molecule production. Biotechnology platforms from precision-engineered yeast strains threaten botanical extraction margins; defend through clinical taste panel capabilities that align with hospital formulary committee requirements. For New Entrants and Emerging Players: The price-point gap between premium natural extracts and economy artificial flavors opens white-space in nature-identical synthesis for Indian pediatric syrup manufacturers under PLI scheme extensions. Latin American veterinary emulsion markets show substantial unmet need. Enter through modular continuous manufacturing skids for rapid-turnaround pediatric formulation services. For Investors and Strategic Acquirers: ECHA's 2023 flavoring substance inventory threshold update is the leading indicator that regulatory compliance burdens will accelerate mid-tier consolidation. Five-to-ten year viability favors integrated platforms with simultaneous FDA and EFSA submission capabilities. Target flavor houses with captive biotechnology infrastructure and hospital formulary relationships. Watch for REACH authorization requirements forcing synthetic musk compound substitution as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Investment | Fermentation-derived molecules bypass petrochemical routes and align with EU Green Deal procurement criteria. |
| FairWild Certification Expansion | Captive botanical sourcing secures supply against Madagascar cyclone volatility and speculative price spikes. |
| Clinical Taste Panel Development | Hospital formulary centralization favors suppliers with integrated sensory science and bioequivalence documentation. |
| Continuous Manufacturing Skid Deployment | Real-time flavor adjustment compresses development timelines for bitter active pharmaceutical ingredients. |
| Dual-Track Regulatory Submission Capability | Simultaneous FDA GRAS and EFSA evaluations align with abbreviated new drug application cycles. |
Research Methodology
FDA GRAS notifications, EFSA flavoring substance evaluations, and ECHA REACH registration databases formed the secondary backbone, cross-referenced with primary interviews involving pharmaceutical formulation scientists, regulatory affairs specialists, hospital pharmacy and therapeutics committee members, and flavor house R&D directors. Bottom-up and top-down triangulation validated segment-level estimates against customs data for essential oil extracts and synthetic precursor trade flows.
Bottom-up modeling anchored volume projections to dosage form-specific flavor loading rates across oral care, nutraceutical, and prescription drug applications, while top-down analysis tested aggregate figures against pharmaceutical manufacturing output in Germany, the United States, and China. Segmentation dimensions included product type, application, end user, and delivery format. CAGRs derived from regression analysis of historical procurement patterns and regulatory timeline impacts.
Underlying measurement precision varies by segment; prescription drug and oral care applications carry tighter precision than veterinary medicine due to more consolidated buyer bases. Forecasts reflect assumptions about REACH compliance timelines, biotechnology adoption curves, and hospital formulary centralization trajectories. Material deviation in regulatory authorization schedules or botanical harvest yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Allyl Heptanoate Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Spearmint Oil Market