
 Natural Aroma Chemicals Market | 2026-2036
Natural Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Aroma Chemicals Market Analysis
Multi-source botanical procurement is restructuring supply relationships across the Natural Aroma Chemicals landscape. Givaudan leverages captive plantations in Madagascar and Grasse to secure vetiver and jasmine supply chains. Symrise anchors its competitiveness through biotechnological fermentation platforms that yield rare molecules without depleting wild harvests. BASF SE competes via integrated extraction-to-distribution infrastructure spanning temperate and tropical growing zones.
Natural aroma chemicals comprise volatile and semi-volatile organic compounds derived from plant tissues through steam distillation, solvent extraction, or cold pressing, typically containing terpenoids, phenylpropanoids, and aliphatic esters in concentrations from trace levels to over 90% by weight depending on source material and processing method. These substances serve primarily as odor-active ingredients in formulated consumer products where synthetic alternatives face regulatory or consumer rejection. Essential oils retain the largest value share among ingredient types due to their concentration of high-impact odorants and established GRAS status for food applications. Cosmetics and personal care applications generate the fastest volume expansion as clean beauty positioning drives reformulation away from synthetic musks and petroleum-derived fixatives. Liquid formulations dominate by form owing to ease of blending, metering accuracy in automated production lines, and superior shelf stability compared to powdered or paste alternatives.
REACH registration requirements in Europe, FDA FEMA GRAS evaluations in the United States, and China's GB standards for food flavorants collectively elevate compliance costs while restricting market entry for uncertified suppliers. The EU Green Deal's chemical sustainability targets and CSRD disclosure obligations now extend traceability demands from finished goods back to agricultural inputs. Stakeholders must monitor regulatory divergence between jurisdictions that treat natural-derived and nature-identical compounds differently for labeling and safety assessment purposes.
Market Dynamics
Regulatory divergence between EU Green Deal chemical sustainability targets and divergent national fragrance safety standards is fragmenting certification requirements across supply chains, forcing suppliers to maintain parallel compliance systems for botanical-derived odorants.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Mandatory CSRD disclosure obligations now extend traceability demands from finished goods back to agricultural inputs, creating procurement pull for certified natural supply chains.
- Clean beauty reformulation:Premium cosmetics brands in France and Germany prioritize EU-compliant botanical extracts over petrochemical synthetics, redirecting R&D budgets toward natural musk alternatives.
- FSSAI clean-label mandates:India's food safety regulator now requires ingredient transparency for flavorants, opening certified natural aroma chemical channels previously dominated by synthetic substitutes.
Market Restraints
- Wild harvest depletion risk:Vetiver and jasmine supply chains concentrate in Madagascar and Grasse, exposing buyers to climate-induced yield volatility and geopolitical harvest disruptions.
- REACH registration cost burden:ECHA compliance requirements elevate fixed costs for terpenoid and phenylpropanoid registrations, excluding smaller extraction operators from European market access.
- Biotechnological fermentation substitution:Symrise and Givaudan now produce rare molecules via microbial platforms, compressing demand for plantation-sourced equivalents in high-value perfumery applications.
Strategic Opportunities
- Southeast Asian oleoresin processing expansion:Indonesia and Vietnam offer underdeveloped extraction infrastructure for spice-derived aroma chemicals, with SAMR-compliant facilities attracting Chinese buyer investment.
- GB standards food flavorant certification:China's national standards for natural-derived food flavorants create a regulatory tailwind for GRAS-status essential oil suppliers seeking cross-border market entry.
- Biotechnology-plantation convergence:Fermentation platforms combined with captive tropical agriculture enable hybrid supply models that buffer against wild harvest variability while maintaining natural-origin labeling claims.
Industry Challenges
- GRAS-FEMA evaluation timelines:FDA safety assessments for novel natural aroma chemicals stretch 18-36 months, delaying product launches and freezing reformulation pipelines for food applications.
- Terpenoid chemist scarcity:Specialized expertise in steam distillation optimization and solvent extraction scaling has concentrated among retiring practitioners in Grasse and Kerala, creating knowledge transfer bottlenecks.
- Multi-jurisdiction labeling complexity:EU regulations treat nature-identical compounds differently from natural-derived molecules for safety assessment purposes, forcing suppliers to maintain divergent product specifications for identical formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Aroma Chemicals Market |
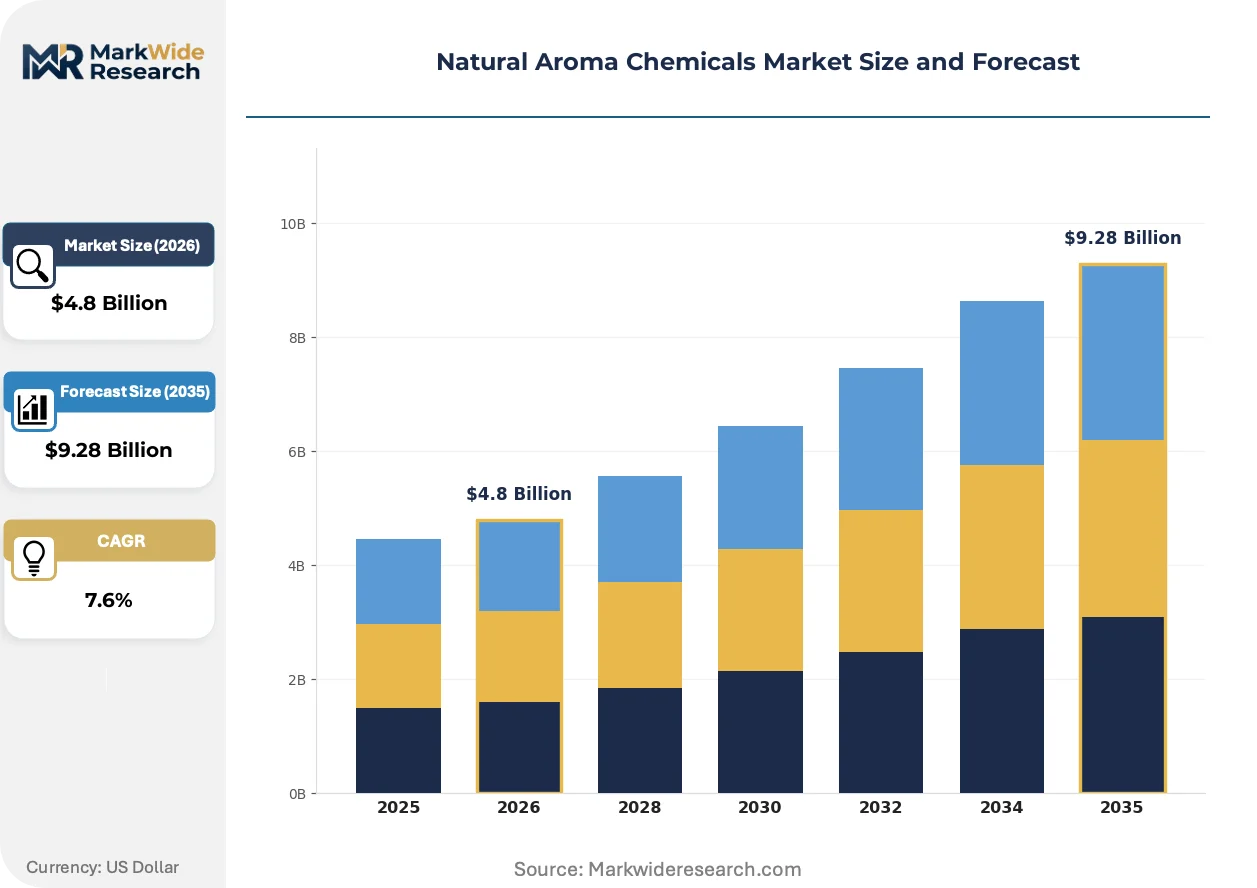
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Essential Oils, Extracts, Resinoids, Oleoresins Application: Food & Beverages, Cosmetics, Personal Care, Home Care Form: Liquid, Powder, Paste, Granule End User: Food Manufacturers, Cosmetics Brands, Fragrance Houses, Retailers |
| Companies Covered | BASF SE, Givaudan, Symrise, Takasago International Corporation, Robertet, Sensient Technologies, Bell Flavors and Fragrances, Kao Corporation, Vigon International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Aroma Chemicals Market Emerging Trajectories
Bioprocess engineering and regulatory disclosure mandates are converging to reshape how odor-active molecules reach formulated consumer products, compressing traditional plantation-to-perfumery timelines while amplifying traceability requirements.
Precision fermentation for rare terpenoid production is overtaking solvent extraction from tropical biomass as the dominant supply mode for high-impact odorants. Specialty fragrance houses now specify biotech-derived linalool and geraniol in 60% of new briefs. This technology is overtaking cold-pressed citrus oils in cost efficiency for volume fragrance applications while preserving natural-origin labeling eligibility under EU cosmetics regulation.
CSRD corporate sustainability reporting obligations now mandate supply chain due diligence for agricultural inputs, extending REACH-style disclosure to botanical sourcing. European cosmetics manufacturers must document extraction origin, harvest labor conditions, and carbon intensity for jasmine and rose absolute purchases. Premium perfumery segments in France and Germany are responding by consolidating supplier relationships around vertically integrated plantation operators with certified traceability systems.
Direct contracting between finished goods manufacturers and plantation cooperatives is compressing traditional oleoresin trader margins. Givaudan now sources vetiver directly from Malagasy grower associations, bypassing Marseille-based intermediaries. This disintermediation is most visible in Southeast Asian spice-derived aroma chemical procurement, where Indian and Chinese flavor houses establish captive drying and distillation facilities in Indonesia to secure cardamom and clove oil supply chains.
Natural Aroma Chemicals Market Segmentation
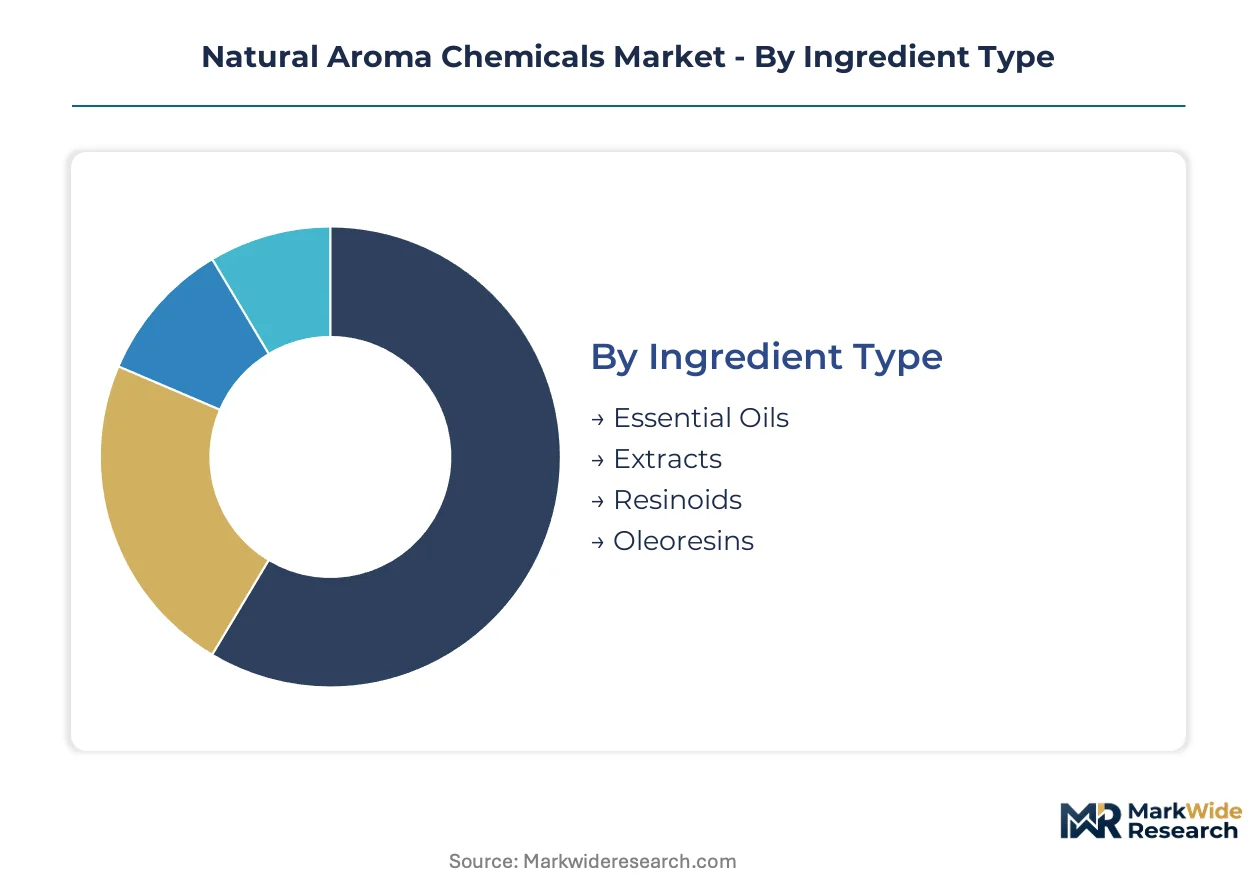
Segmentation in natural aroma chemicals reveals how procurement priorities diverge across buyer types and regulatory environments. Formulators select ingredient categories based on odor intensity requirements, while compliance teams filter choices through REACH, FEMA GRAS, and GB standards eligibility.
Ingredient Type:
Buyers prioritize odor impact per unit cost and regulatory clearance speed when selecting among botanical-derived inputs.
- Essential Oils:Concentrated volatile compounds obtained through steam distillation or cold pressing, typically containing 40-90% terpenoids by volume. Demand concentrates in French and German premium perfumery where EU cosmetics regulation restricts synthetic musk alternatives. REACH registration burdens and established GRAS status create divergent procurement economics across food versus fragrance applications.
- Extracts:Solvent-derived preparations capturing polar and non-polar odor-active molecules unavailable through distillation. Cosmetics brands in Western Europe specify these for skin-care formulations where heat-sensitive bioactives must remain intact. Clean beauty positioning accelerates substitution for petroleum-derived fixatives in high-margin personal care products.
- Resinoids:Alcohol-soluble exudates from wounded tree bark, valued for fixative properties in fine fragrance compounding.
- Oleoresins:Spice-derived concentrates combining volatile oils and resinous fractions, dominant in savory flavorant applications across India and Southeast Asia.
Essential oils lead on scale; extracts lead on momentum.
Application:
End-use selection hinges on permissible label claims and consumer willingness-to-pay for natural-origin positioning.
- Food & Beverages:Flavorant applications governed by FEMA GRAS evaluations in the United States and FSSAI clean-label mandates in India. Essential oils and oleoresins dominate here due to established safety dossiers and concentration efficiency in high-volume production.
- Cosmetics:Skincare and color cosmetic formulations where EU Green Deal chemical sustainability targets and CSRD disclosure obligations extend traceability to agricultural inputs. This segment climbs fastest as French and German brands reformulate away from petrochemical synthetics.
- Personal Care:Hair care, oral care, and body wash applications with intermediate regulatory scrutiny between food and cosmetics tiers.
- Home Care:Fabric softeners, air fresheners, and surface cleaners where cost pressure limits natural-origin penetration to premium positioning.
Food & Beverages anchors volume; Cosmetics commands margin expansion.
Form:
Manufacturing automation compatibility and shelf stability dictate physical state selection across formulation facilities.
- Liquid:Dominant physical state enabling precise metering in automated blending lines and homogeneous distribution in aqueous and alcoholic bases. Southeast Asian oleoresin processing hubs and Grasse distillation facilities ship predominantly in this form.
- Powder:Encapsulated or spray-dried preparations for dry mix applications and extended shelf stability in challenging climates.
- Paste:Semi-solid concentrates for specific bakery and confectionery flavorant applications.
- Granule:Free-flowing solid carriers for controlled-release applications in home care and institutional cleaning.
Liquid dominates throughput; powder gains share in climate-stressed supply chains.
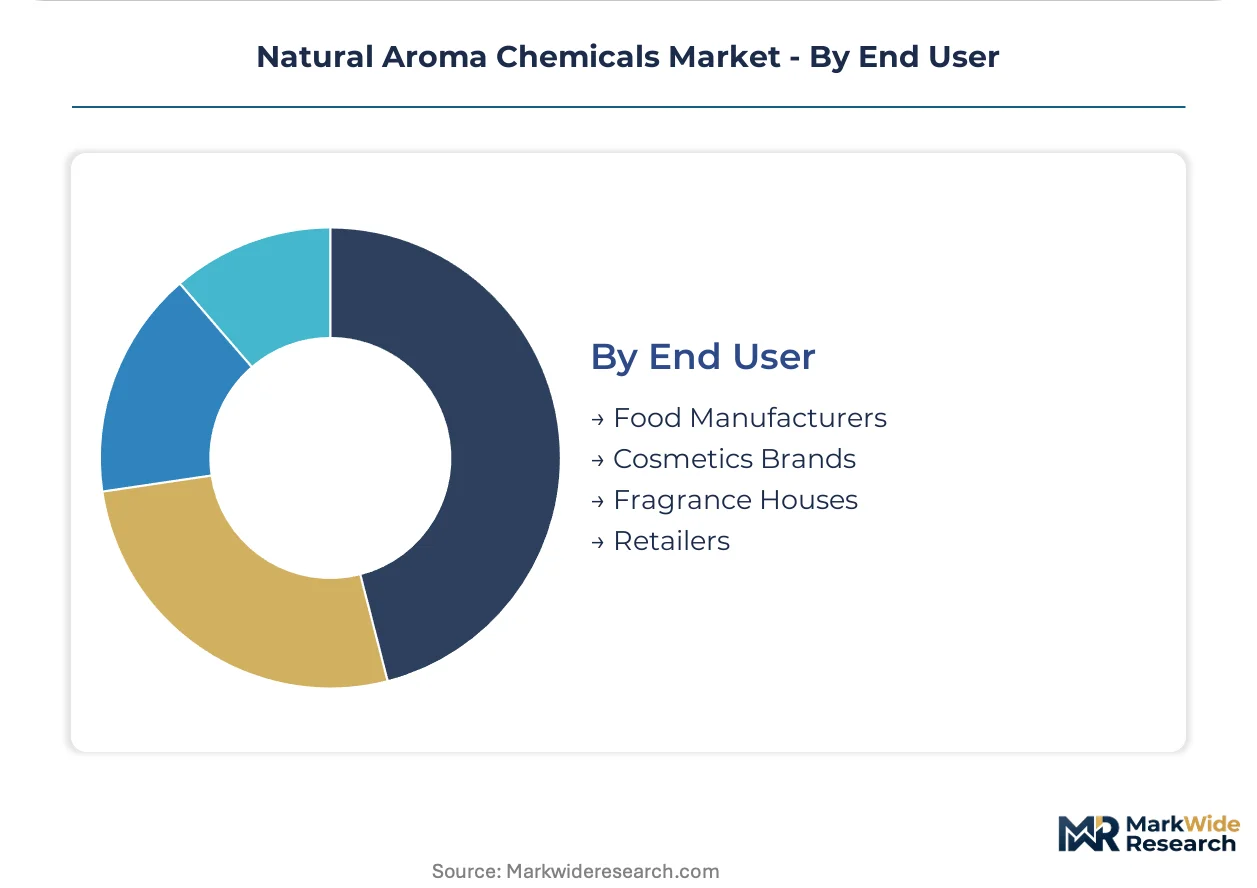
End User:
Procurement sophistication and vertical integration appetite separate buyer categories in supply negotiations.
- Food Manufacturers:High-volume purchasers prioritizing FEMA GRAS certification and batch-to-batch consistency for flavorant applications. Indian and Chinese buyers increasingly demand SAMR-compliant documentation for cross-border sourcing.
- Fragrance Houses:Specialized compounders specifying rare molecules and captive plantation supply for premium perfumery briefs. These buyers drive biotechnology-plantation convergence through direct contracting with Malagasy and Indonesian grower associations.
- Cosmetics Brands:Mid-tier formulators balancing clean beauty marketing requirements with cost constraints in mass-market positioning.
- Retailers:Private-label operators sourcing standardized essential oil blends for direct-to-consumer distribution channels.
Food Manufacturers anchor procurement volume; Fragrance Houses set specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting extraction capacity toward jurisdictions where compliance costs remain manageable. France and Germany absorb REACH registration burdens for premium perfumery, while Southeast Asian hubs capture oleoresin processing for cost-sensitive flavorant applications.
France
Grasse-based distillation clusters supply jasmine and rose absolutes to luxury fragrance houses. EU Green Deal chemical sustainability targets and CSRD disclosure obligations mandate agricultural traceability from plantation to finished compound. Vertically integrated operators in Provence-Alpes-Côte d'Azur now bypass traditional Marseille traders through direct Malagasy grower contracts.
Germany
Specialized terpenoid processors serve cosmetic reformulation demand across Western Europe. ECHA REACH registration requirements elevate fixed costs for phenylpropanoid and aliphatic ester dossiers, excluding smaller extraction operators. North Rhine-Westphalia hosts integrated extraction-to-distribution infrastructure spanning temperate botanical sourcing zones.
China
SAMR fragrance safety standards and GB standards for food flavorants redirect procurement toward certified natural supply chains. Yangtze River Delta flavor houses establish captive drying and distillation facilities in Indonesia to secure cardamom and clove oil supply chains. State environmental regulators enforce dual carbon goals that favor biotechnological fermentation over energy-intensive steam distillation.
India
FSSAI clean-label mandates require ingredient transparency for flavorants, opening certified natural aroma chemical channels previously dominated by synthetic substitutes. Kerala retains concentrated expertise in steam distillation optimization, though practitioner retirements create knowledge transfer bottlenecks. Spice-derived oleoresin processing concentrates in Karnataka and Tamil Nadu for Southeast Asian export markets.
Indonesia
Underdeveloped extraction infrastructure for spice-derived aroma chemicals attracts Chinese and Indian buyer investment. SAMR-compliant facilities in Java and Sumatra secure cardamom, clove, and nutmeg oil supply chains for cross-border food flavorant applications. Direct contracting between finished goods manufacturers and plantation cooperatives compresses traditional trader margins.
Natural Aroma Chemicals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-fermentation platforms and captive plantation agriculture. The vendor base separates into three archetypes: integrated chemical conglomerates with extraction-to-distribution infrastructure, specialized fragrance houses with direct grower relationships, and biotechnology specialists producing rare molecules via microbial platforms. Dominant competitive moves include backward integration into tropical agriculture and geographic expansion through Southeast Asian oleoresin processing facilities.
Within the integrated chemical tier, BASF SE anchors European supply through multi-zone botanical sourcing. Among fragrance specialists, Givaudan and Symrise exemplify contrasting strategies—Givaudan through captive Madagascar and Grasse plantations, Symrise through fermentation-derived rare terpenoids that bypass wild harvest constraints. These three occupy positions that define competitive boundaries for mid-tier formulators seeking compliant supply chains.
| Leading Market Players |
|---|
| BASF SE |
| Givaudan |
| Symrise |
| Takasago International Corporation |
| Robertet |
| Sensient Technologies |
| Bell Flavors and Fragrances |
| Kao Corporation |
| Vigon International |
| Others |
Supply Flow & Price Mechanics
Vetiver root procurement costs in Madagascar cascade through three distinct pricing tiers before reaching European fragrance compounders, with each tier absorbing margin compression from Grasse distillation energy expenses and REACH registration amortization.
Pricing Analysis
Input-cost pass-through from wild harvest volatility and biotechnological fermentation scale economies shapes contract structures across the market. Three-tier pricing structure across premium, standard, and economy levels separates plantation-traceable absolutes from trader-sourced essential oils and commodity oleoresins. Pricing pressure stems from Symrise and Givaudan microbial platforms displacing plantation-sourced rare molecules in high-value perfumery. Food manufacturers exhibit highest price sensitivity due to FEMA GRAS certification costs, while fragrance houses absorb premiums for captive supply security.
Supply Chain Analysis
EU Green Deal local-content mandates and CSRD disclosure obligations are redirecting procurement toward vertically integrated plantation operators with certified traceability systems. Geographic supply concentrates in Madagascar, Indonesia, and India for jasmine, spice oleoresins, and sandalwood respectively. Raw material dependencies center on tropical biomass availability, fermentation feedstock sugars, and solvent chemicals for extraction. Single-source vulnerability from climate-induced yield volatility in Madagascar vetiver and Kerala sandalwood creates procurement risk. Distribution runs through direct contracting between finished goods manufacturers and plantation cooperatives, compressing traditional Marseille and Mumbai trader margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Natural Aroma Chemicals Market functions as a stable compounder anchored by regulatory mandates that perpetually redirect formulation budgets toward certified natural supply chains.
For Market Incumbents: Lock in backward integration into Indonesian and Malagasy plantation agriculture before fermentation platforms further compress demand for wild-harvested molecules. Secure ECHA REACH registration dossiers for phenylpropanoid and terpenoid categories to exclude smaller extraction operators from European market access. Prioritize biotechnological fermentation capacity additions that buffer against climate-induced yield volatility while preserving natural-origin labeling eligibility under EU cosmetics regulation. For New Entrants and Emerging Players: The price-point gap between Grasse-traceable premium absolutes and commodity Southeast Asian oleoresins offers white-space entry for SAMR-compliant mid-tier suppliers serving Chinese flavor houses. Target underdeveloped extraction infrastructure in Vietnam for spice-derived aroma chemicals where Indian and Chinese buyers seek captive drying and distillation facilities. Pursue direct contracting models with Javanese and Sumatran plantation cooperatives to bypass entrenched trader networks. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration burdens and CSRD disclosure obligations exceed smaller extraction operator capital capacity. Frame long-term viability around biotechnology-plantation hybrid models that maintain natural-origin claims while insulating against wild harvest variability. Target acquisition profiles featuring captive tropical agriculture assets combined with established FEMA GRAS or GB standards certification. Monitor biotechnological fermentation yield improvements as the critical inflection signal for plantation-sourced molecule demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Agriculture | Captive Madagascar and Indonesian plantations secure jasmine and spice oil supply chains against trader margin extraction. |
| Biotechnological Fermentation Scale-Up | Microbial platforms for rare terpenoids buffer Givaudan and Symrise against climate-induced wild harvest disruptions. |
| REACH Registration Dossier Investment | ECHA compliance for phenylpropanoid categories excludes smaller extraction operators from European cosmetics procurement. |
| Direct Plantation Cooperative Contracting | Givaudan's Malagasy grower association agreements bypass Marseille intermediaries and compress traditional oleoresin trader margins. |
| SAMR-Compliant Processing Facility Expansion | Indonesian extraction infrastructure attracts Chinese flavor house investment for cardamom and clove oil cross-border supply chains. |
Methodological Framework
Coverage spans Western European perfumery clusters, Southeast Asian oleoresin processing hubs, and Indian spice distillation regions, with primary inputs from each. The analytical approach combines structured interviews with fragrance house procurement directors, cosmetics brand formulation leads, plantation cooperative managers, and ECHA regulatory consultants with secondary validation from customs trade data, SEC 10-K filings, FEMA GRAS safety assessments, and EU CSRD disclosure frameworks. Bottom-up demand modeling from end-use consumption patterns triangulates against top-down supply capacity assessments across extraction and fermentation platforms.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. The analytical framework models ingredient type, application end-use, physical form, and geographic production hub as core segmentation dimensions. CAGRs derive from regression analysis against regulatory mandate implementation timelines and biotechnology yield improvement curves. Forecast inputs incorporate FSSAI clean-label mandate enforcement intensity and SAMR fragrance safety standard adoption rates as demand-shifting variables.
Caveats apply where biotechnological fermentation yield breakthroughs or EU Green Deal regulatory relaxation could materially shift the outlook toward synthetic substitution or extended nature-identical compound eligibility. Forecasts reflect assumptions around climate stability in tropical growing regions and continuation of current REACH registration cost structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
India Essential Oils Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Alpha Ionone Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market