
 Asia-Pacific Deodorants Market | 2026-2036
Asia-Pacific Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Deodorants Market Outlook
ISO 16128 certification for natural and organic cosmetic ingredients is unwinding competitive access across the Asia-Pacific deodorants landscape. Unilever Plc leverages its Hindustan Unilever subsidiary to dominate mass-market distribution in India, while Kao Corporation anchors premium roll-on positioning through sustained innovation in sweat-sensing formulations. Beiersdorf Global AG competes on dermatological credibility, extending its Nivea brand equity into sensitive-skin segments across Southeast Asian pharmacy channels.
Asia-Pacific deodorants comprise topical formulations—typically aerosol suspensions, hydroalcoholic solutions, or waxy solids—designed to inhibit bacterial decomposition of apocrine secretions and mask or prevent body odor through antimicrobial actives, fragrance encapsulation, or aluminum-based astringent salts. Spray formats retain volume leadership in Australia and Japan due to convenience preferences, though natural and organic formulations capture accelerating margin pools as consumers scrutinize ingredient transparency. Online sales channels now outpace supermarkets in growth velocity across South Korea and urban China, reshaping how brands build trial and loyalty.
Japan's Ministry of Health, Labour and Welfare quasi-drug framework and China's National Medical Products Administration cosmetic registration requirements impose distinct compliance burdens that filter market entrants by testing capacity and documentation sophistication. India's Central Drugs Standard Control Organization and Bureau of Indian Standards jointly govern antiperspirant claims and aerosol propellant safety, creating multi-layered approval pathways. Stakeholders must monitor regulatory divergence between Association of Southeast Asian Nations harmonization efforts and country-specific ingredient bans, as compliance strategy increasingly determines which portfolios can scale across borders versus remain trapped in single-market positions.
Market Dynamics
ISO 16128 certification requirements for natural and organic cosmetic ingredients are restructuring competitive access across the Asia-Pacific deodorants landscape, forcing reformulation investments and filtering supplier bases by documentation sophistication.
Growth Catalysts
- China NMPA cosmetic registration streamlining:The National Medical Products Administration's simplified filing pathways for general cosmetics reduce time-to-market for imported deodorant brands entering tier-one cities.
- Young urban professionals in metropolitan India:Rising disposable incomes and hygiene consciousness among this demographic expand the addressable consumer base for premium-positioned products.
- Spray format convenience preference:Aerosol suspensions retain volume leadership in Australia and Japan due to workplace reapplication habits and compact portability demands.
Market Restraints
- Aluminum salt supply concentration:Astringent active sourcing clusters with Chinese specialty chemical producers, exposing formulators to input volatility and trade policy friction.
- Japan quasi-drug classification burden:The Ministry of Health, Labour and Welfare framework imposes clinical efficacy documentation requirements that extend approval timelines for antiperspirant claims.
- Natural ingredient substitution complexity:Plant-derived antimicrobial alternatives struggle to match synthetic efficacy at equivalent cost points, limiting mass-market penetration.
Strategic Opportunities
- Tier-two and tier-three Indian cities:Underpenetrated distribution infrastructure in these geographies offers first-mover advantage for brands building pharmacy and modern trade presence.
- South Korean e-commerce channel acceleration:Online sales velocity now outpaces supermarkets, enabling direct-to-consumer trial models and subscription-based loyalty programs.
- Fragrance encapsulation technology convergence:Microencapsulation systems combined with sweat-sensing formulations create differentiated premium positioning in humid climate markets.
Industry Challenges
- Multi-jurisdiction compliance talent scarcity:Shortage of regulatory affairs specialists capable of navigating divergent ASEAN harmonization efforts alongside country-specific ingredient bans.
- Aerosol propellant safety certification timelines:Bureau of Indian Standards testing protocols for flammability and pressure stability extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Deodorants Market |
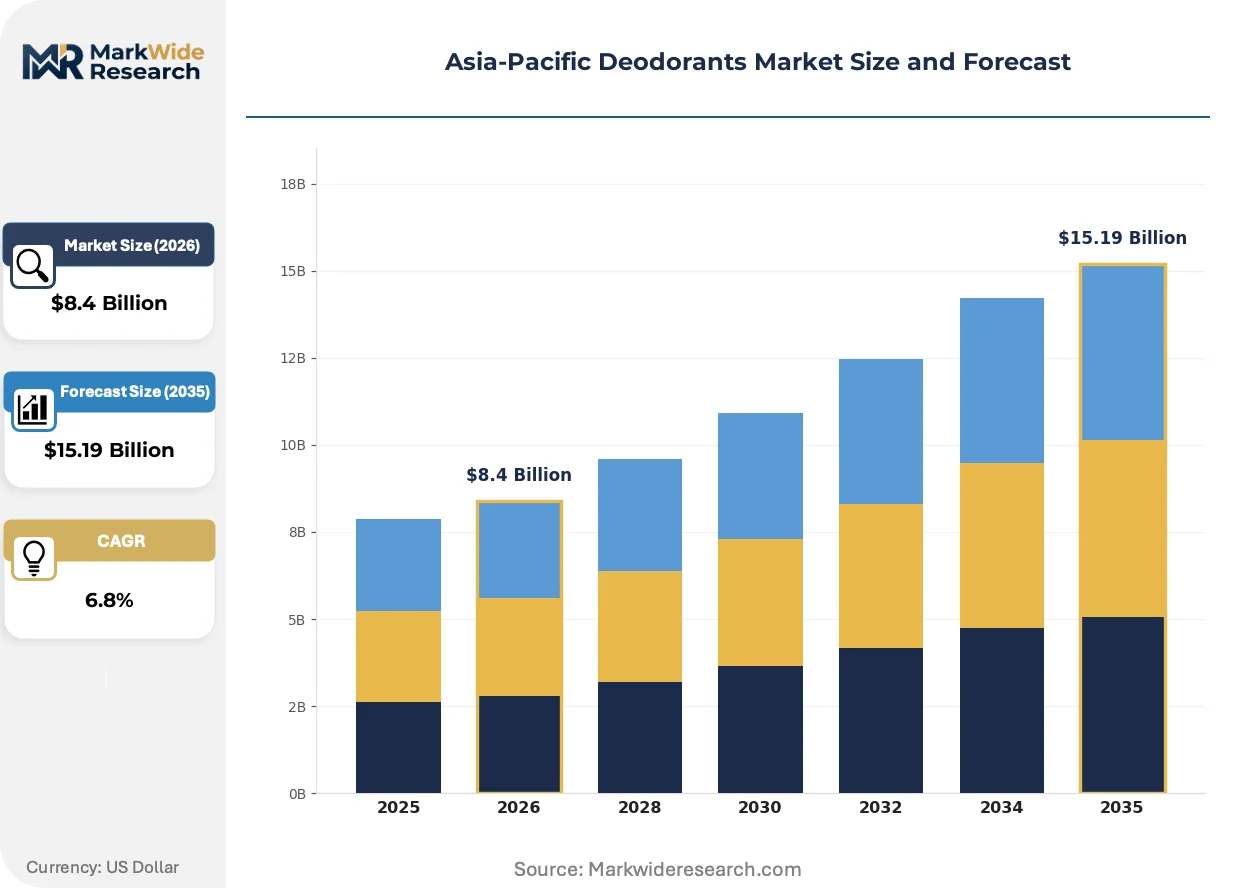
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-On, Spray, Stick, Cream Gender: Men, Women, Unisex, Children Formulation: Natural, Antiperspirant, Organic, Conventional Sales Channel: Online, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Procter & Gamble Co., Unilever Plc, L'Oréal S.A., Beiersdorf Global AG, L'Occitane International SA, ITC Limited, Kao Corporation, Godrej Consumer Products, Colgate-Palmolive Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Deodorants Market Strategic Shifts
Formulation transparency demands and digital channel migration are actively restructuring how deodorant brands build consumer trust and capture margin across the Asia-Pacific region.
Biodegradable fragrance carriers derived from cyclodextrin complexes are displacing synthetic fixatives in premium roll-on formulations. Urban Chinese consumers aged 25-35 are adopting these products at accelerating rates through cross-border e-commerce platforms. This technology is displacing conventional ethanol-heavy bases that previously dominated the natural-positioned segment.
Japan's quasi-drug framework amendments now require substantiated 24-hour efficacy claims for antiperspirant classification. Manufacturers must submit clinical study protocols to the Ministry of Health, Labour and Welfare before market authorization. Roll-on formats targeting sensitive-skin segments face the steepest documentation burdens, driving portfolio simplification among mid-tier competitors.
Ingredient transparency scanning via mobile applications is reshaping purchase validation in physical retail environments. South Korean consumers increasingly verify ISO 16128 compliance and propellant safety ratings before checkout, compressing the traditional trial-to-purchase cycle. Pharmacy channels in Seoul and Busan report the highest adoption intensity, forcing brands to redesign packaging for instant digital readability.
Asia-Pacific Deodorants Market Segmentation
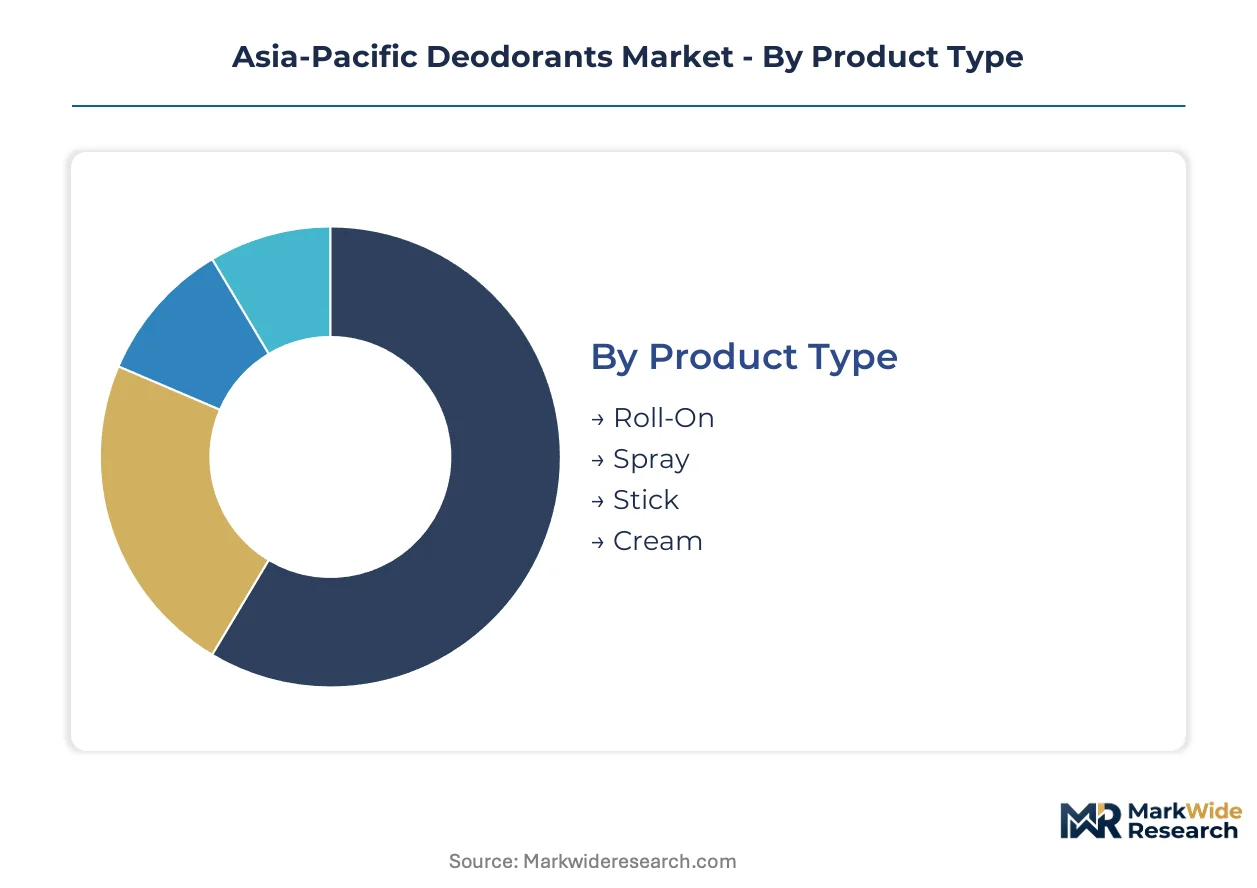
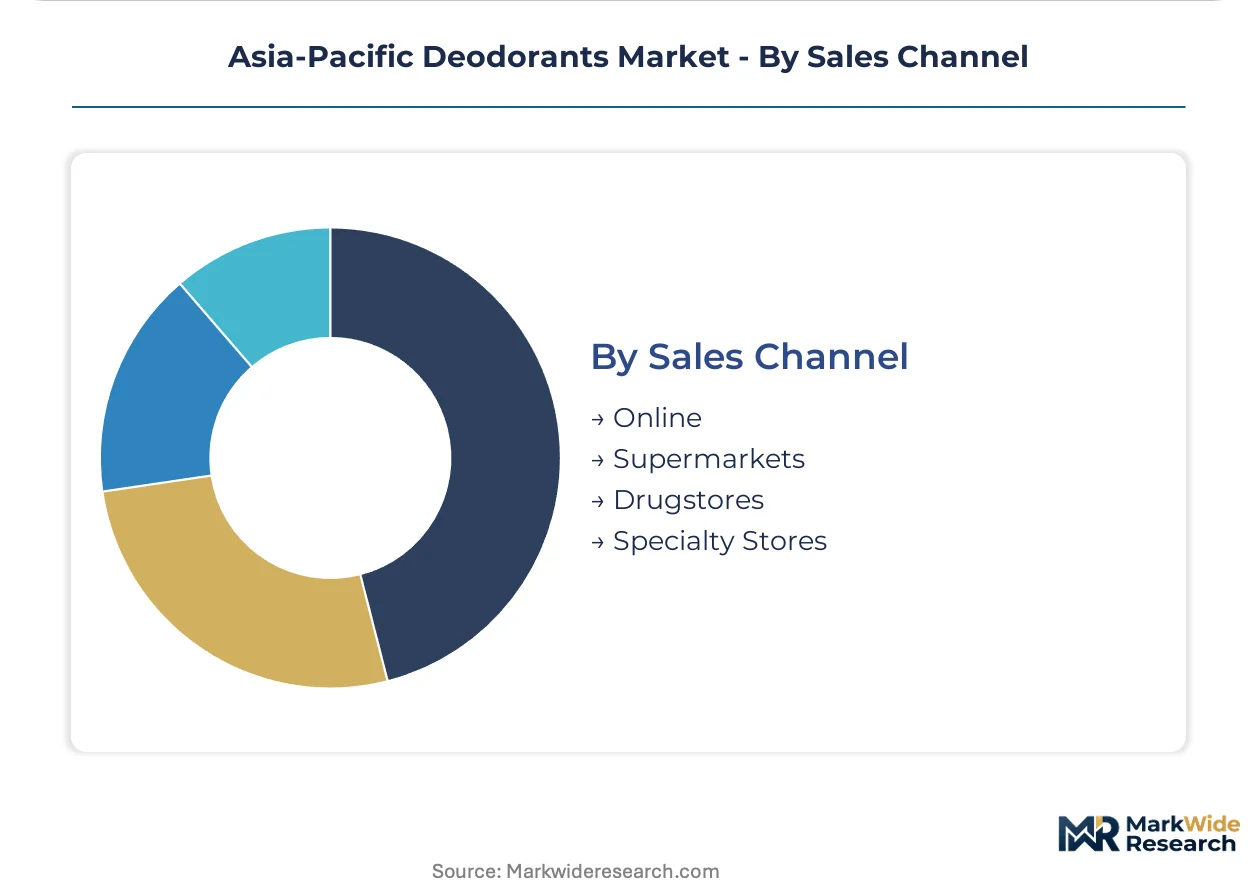
Deodorant purchasing patterns across the Asia-Pacific region fragment sharply across product format preferences and channel access. Understanding where margin pools concentrate within each dimension enables portfolio prioritization for brands navigating divergent regulatory and consumer sophistication levels.
Product Type:
Margin pools concentrate most densely in formats that balance convenience with formulation flexibility for humid climate performance.
- Roll-On:Hydroalcoholic solutions with aluminum-based astringent salts dominate pharmacy channel positioning in Japan and South Korea. Sweat-sensing formulations from Kao Corporation anchor premium pricing in Tokyo and Seoul metro areas, where workplace reapplication habits sustain volume.
- Spray:Aerosol suspensions retain volume leadership in Australia and Japan due to compact portability demands and workplace hygiene norms. Convenience preferences in Sydney and Melbourne sustain mass-market penetration despite aluminum salt supply concentration risks from Chinese specialty chemical producers.
- Stick:Waxy solid formats with fragrance encapsulation technology gain traction in premium Indian tier-one cities, though high summer temperatures limit year-round adoption.
- Cream:Thick emulsion bases serve sensitive-skin segments across Southeast Asian pharmacy channels, where dermatological credibility commands price premiums.
The dominant share belongs to Spray, while Roll-On is closing the gap fastest through premium positioning in East Asian metropolitan markets.
Gender:
Addressable consumer base expansion tracks urban professional demographic growth, with unisex positioning capturing efficiency-minded younger cohorts.
- Men:Formulations emphasizing 24-hour efficacy claims dominate in Japan's quasi-drug framework, where clinical documentation requirements filter mid-tier competitors. Male urban professionals in metropolitan India drive premium trial through modern trade channels.
- Women:Natural and organic ingredient positioning captures accelerating margin pools as ISO 16128 certification becomes a purchase validator. South Korean consumers aged 25-35 verify compliance via mobile applications before checkout in Seoul pharmacy channels.
- Unisex:Fragrance-neutral formulations with biodegradable cyclodextrin carriers displace synthetic fixatives in urban Chinese cross-border e-commerce. This segment climbs fastest among young professionals seeking simplified personal care routines.
- Children:Hypoallergenic formulations with minimal antimicrobial actives serve niche demand in Australia's pharmacy channels, where parental ingredient scrutiny is most intense.
Women's segments command the deepest margin structure, though Unisex positioning is expanding most quickly through digital channel migration.
Formulation:
Regulatory documentation burdens and ingredient transparency demands are restructuring competitive access across formulation types.
- Natural:Plant-derived antimicrobial alternatives with ISO 16128 certification gain shelf space in India's tier-one cities faster than mass alternatives. Documentation sophistication requirements filter supplier bases and extend approval timelines.
- Antiperspirant:Aluminum-based astringent salts face Japan's Ministry of Health, Labour and Welfare quasi-drug classification burden, where 24-hour efficacy claims require clinical study protocol submission. Roll-on formats targeting sensitive-skin segments face the steepest documentation requirements.
- Organic:Cyclodextrin-derived biodegradable fragrance carriers displace ethanol-heavy bases in premium Chinese cross-border e-commerce. Urban consumers aged 25-35 adopt these products at accelerating rates through digital trial models.
- Conventional:Synthetic antimicrobial actives retain cost advantages in mass-market penetration across Southeast Asia, though natural ingredient substitution complexity limits pricing power.
Antiperspirant formulations hold the largest volume position, while Natural certification is gaining share fastest through premium channel expansion.
Sales Channel:
Digital migration velocity now outpaces traditional retail across multiple Asia-Pacific markets, reshaping trial and loyalty economics.
- Online:Direct-to-consumer models and subscription-based loyalty programs accelerate in South Korea and urban China, where sales velocity now outpaces supermarkets. Cross-border platforms enable Japanese and Australian brand access to Chinese tier-one cities.
- Supermarkets:Mass-market spray formats retain volume leadership in Australia's convenience-oriented retail environment, though growth rates lag digital channels.
- Drugstores:Pharmacy channels in Seoul and Busan report the highest mobile verification adoption intensity, forcing packaging redesign for instant digital readability. Dermatological credibility commands premium positioning in Southeast Asian pharmacy networks.
- Specialty Stores:Premium roll-on and natural-positioned brands build presence in India's tier-one modern trade, where shelf space allocation favors documented ingredient transparency.
Supermarkets retain the broadest reach, though Online channels are climbing fastest through subscription models and cross-border platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young urban professionals in metropolitan India and Southeast Asia are expanding the core consumer base for deodorant products. China's updated cosmetic safety regulations and Japan's quasi-drug classification system are reshaping formulation requirements and import compliance. Demand concentrates most visibly in India's tier-one cities, where premium and natural-positioned brands gain shelf space faster than mass alternatives.
China
Tier-one city consumers aged 25-35 are adopting premium roll-on formats through cross-border e-commerce platforms. NMPA cosmetic registration streamlining reduces time-to-market for imported brands entering Shanghai and Beijing. The Yangtze River Delta manufacturing cluster supplies cyclodextrin-derived biodegradable fragrance carriers to domestic formulators.
Japan
Workplace reapplication habits in Tokyo and Osaka sustain volume leadership for aerosol spray formats. The Ministry of Health, Labour and Welfare quasi-drug framework imposes clinical efficacy documentation requirements for 24-hour antiperspirant claims. Kao Corporation anchors premium positioning in the Kanto region through sustained innovation in sweat-sensing formulations.
India
Rising disposable incomes among male urban professionals in Mumbai and Delhi drive premium trial through modern trade channels. CDSCO and BIS jointly govern antiperspirant claims and aerosol propellant safety, creating multi-layered approval pathways. Tier-two and tier-three cities offer first-mover advantage for brands building pharmacy distribution infrastructure.
South Korea
Consumers aged 25-35 verify ISO 16128 compliance via mobile applications before checkout in Seoul pharmacy channels. MFDS regulations shape ingredient transparency requirements for natural-positioned products. Online sales velocity now outpaces supermarkets, enabling direct-to-consumer trial models and subscription-based loyalty programs.
Australia
Convenience preferences in Sydney and Melbourne sustain mass-market spray penetration despite aluminum salt supply concentration risks. TGA oversight intersects with workplace hygiene norms to reinforce aerosol format dominance. Pharmacy channels report intense parental ingredient scrutiny driving hypoallergenic formulation demand.
Asia-Pacific Deodorants Market Competitive Environment
Player mix skews toward multinational consumer goods conglomerates with established distribution infrastructure and local subsidiary operations. Market structure concentrates around three to four dominant holding companies controlling mass-market shelf space, with mid-tier competitors filtered by regulatory documentation burdens. Strategic archetypes include dermatological credibility builders, mass-market volume leaders, and premium natural-positioned specialists. Competitive moves center on portfolio diversification into sensitive-skin segments and geographic expansion through cross-border e-commerce platforms.
Within the mass-market volume tier, Unilever Plc and Procter & Gamble Co. occupy positions anchored by subsidiary operations in high-growth metropolitan markets. Kao Corporation exemplifies the premium innovation archetype through sustained formulation advancement in East Asian humidity conditions. Beiersdorf Global AG represents dermatological credibility positioning, extending brand equity into pharmacy-channel sensitive-skin segments across Southeast Asian markets.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Unilever Plc |
| L'Oréal S.A. |
| Beiersdorf Global AG |
| L'Occitane International SA |
| ITC Limited |
| Kao Corporation |
| Godrej Consumer Products |
| Colgate-Palmolive Company |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for aluminum-based astringent salts concentrate pricing power with Chinese specialty chemical producers, while Japanese and Indian formulators absorb carry-cost volatility to maintain tier-one city shelf presence. This lead-time exposure filters mid-tier competitors from premium positioning and anchors cost-plus contracting around commodity-indexed raw material clauses.
Pricing Analysis
Cost-plus contracts with aluminum salt indexation dominate procurement between Chinese producers and Asia-Pacific formulators. Three-tier pricing structure across premium ISO 16128-certified, standard antiperspirant, and economy conventional formulations separates margin pools by documentation burden. Pricing pressure stems from natural ingredient substitution complexity, as plant-derived antimicrobials struggle to match synthetic efficacy at equivalent cost points. Mass-market spray buyers in Australia exhibit highest price sensitivity, while pharmacy-channel consumers in Seoul and Tokyo accept premiums for dermatological credibility.
Supply Chain Analysis
Strait of Malacca transit underwrites cyclodextrin-derived fragrance carrier flows from Yangtze River Delta manufacturers to Japanese and South Korean formulators. Active ingredient concentration centers on China for aluminum salts, Japan for sweat-sensing formulation technologies, and India for herbal extract processing. Single-source vulnerability concentrates in Chinese specialty chemical producers, exposing downstream brands to input volatility and trade policy friction. Distribution runs through modern trade and pharmacy channels in tier-one cities, with cross-border e-commerce platforms capturing accelerating velocity in urban China and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers: Japan's quasi-drug framework and China's NMPA registration requirements filter entrants by clinical documentation capacity and testing infrastructure investment.
For Market Incumbents: Compound brand equity into sensitive-skin segments through ISO 16128 certification investments that mid-tier competitors cannot replicate. Extend Hindustan Unilever-style subsidiary infrastructure into India's tier-two pharmacy channels before local challengers consolidate distribution. Defensive priority centers on controlling aluminum salt supply relationships through long-term offtake agreements with Yangtze River Delta producers.
For New Entrants and Emerging Players: NMPA streamlined filing pathways offer fastest regulatory onboarding for imported brands targeting Shanghai and Beijing cross-border e-commerce. White-space concentration sits in South Korean subscription-based direct-to-consumer models, where online velocity already outpaces supermarket growth. Entry angle should leverage biodegradable cyclodextrin fragrance carriers to capture urban Chinese consumers aged 25-35 through digital trial platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory documentation burdens and multi-jurisdiction compliance talent scarcity favor scaled holding companies with established testing infrastructure. Acquisition target archetype: mid-tier natural-positioned brands with ISO 16128 certification but underdeveloped pharmacy channel presence in Southeast Asia. Signal to watch is Bureau of Indian Standards aerosol propellant safety certification timeline compression, which would accelerate launch schedules for prepared entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16128 Certification Investment | Documentation sophistication filters supplier bases and unlocks premium shelf space in Seoul and Mumbai pharmacy channels. |
| Tier-Two Indian Pharmacy Expansion | Underpenetrated distribution infrastructure in cities like Pune and Ahmedabad offers first-mover positioning before local consolidation. |
| Sweat-Sensing Formulation R&D | Kao Corporation's sustained innovation in humidity-responsive actives anchors premium pricing in Tokyo and Osaka metro areas. |
| Cross-Border E-Commerce Platform Entry | Direct-to-consumer models bypass supermarket gatekeepers and capture Chinese urban professional trial through Tmall Global and similar channels. |
| Biodegradable Carrier Transition | Cyclodextrin-derived fragrance systems displace ethanol-heavy bases and align with South Korean mobile verification adoption patterns. |
Study Parameters
The analysis maps spray, roll-on, stick, and cream format segments, each validated through brand managers at multinational consumer goods conglomerates, category buyers at modern trade retailers, regulatory affairs specialists navigating NMPA and MHLW frameworks, and supply planners managing aluminum salt procurement. Primary interview findings triangulate against secondary sources including NMPA cosmetic registration filings, Bureau of Indian Standards aerosol safety protocols, MFDS ingredient transparency guidelines, and customs records tracking cyclodextrin carrier trade flows. Bottom-up volume builds from city-tier demand modeling converge with top-down holding company revenue allocation analysis.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions span product format, gender positioning, formulation type, and sales channel, with additional modeling for regulatory framework clusters distinguishing quasi-drug from general cosmetic classifications. CAGRs derive from trend extrapolation of urban professional demographic expansion, channel migration velocity, and certification adoption curves. Industry-specific inputs include workplace reapplication frequency data from Japanese occupational hygiene surveys and Indian modern trade shelf-space allocation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained NMPA streamlining and stable aluminum salt supply concentration; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ASEAN harmonization efforts and country-specific ingredient bans evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Allyl Heptanoate Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market