
 Europe Deodorants Market | 2026-2036
Europe Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Deodorants Market Foresight
A widening capital-intensity gap between mass-market and premium-positioned players is reorganizing competitive dynamics across the Europe Deodorants Market. Unilever PLC leverages its integrated supply chain to sustain cost leadership in spray formats across multiple European markets. Beiersdorf AG anchors its position through specialized R&D intensity in antiperspirant technologies. L'Oréal SA differentiates via premium fragrance-layered formulations that command higher shelf positioning in drugstores and salons.
Deodorants comprise topical personal-care formulations designed to neutralize or mask body odor through antimicrobial agents, fragrance compounds, or aluminum-based sweat-blocking mechanisms, typically delivered via aerosol propellant, liquid roll-on ball, solid wax stick, or transparent gel matrix. Spray formats retain volume leadership due to convenience and lower per-unit cost, though natural and alcohol-free segments accelerate fastest as consumers migrate toward skin-sensitive and clean-label alternatives. Stick and gel categories occupy concentrated margin pools through travel-size portability and dermatological positioning in pharmacy channels.
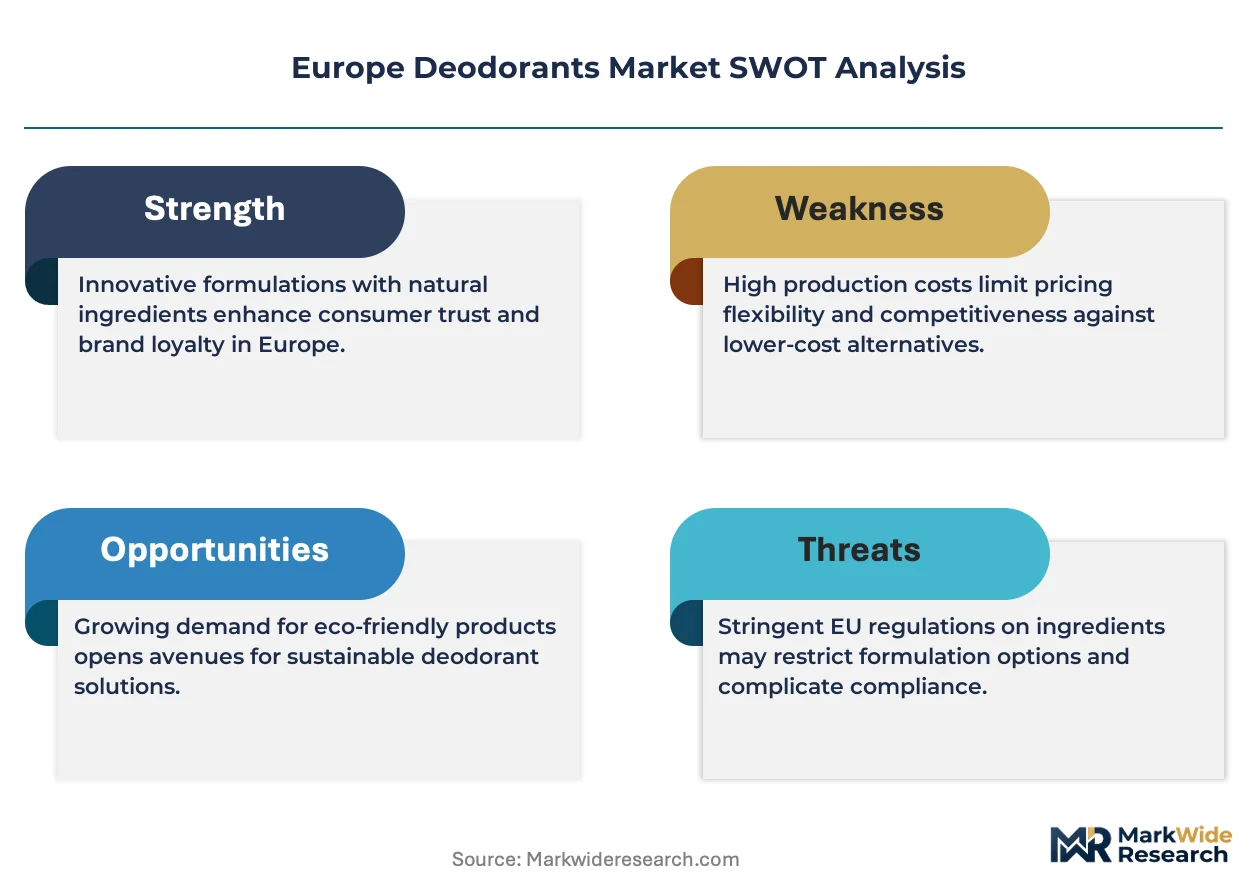
EMA cosmetic ingredient guidelines, REACH chemical registration requirements, and the EU Green Deal sustainability frameworks collectively reshape product standards by restricting certain aluminum salts and mandating biodegradability disclosures. These regulations elevate compliance costs for imported formulations while creating market-access advantages for European manufacturers with established regulatory affairs capabilities. Stakeholders must monitor evolving substance restriction lists and decide whether to accelerate reformulation investments or retreat toward conventional antiperspirant portfolios with narrower geographic distribution.
Market Dynamics
REACH substance restriction lists and the EU Green Deal's biodegradability mandates are forcing simultaneous reformulation across aluminum salt actives and aerosol propellant systems, compressing R&D timelines while elevating compliance spend.
Growth Catalysts
- Aluminum-free antiperspirant technologies:German and French consumers drive demand for mineral salt and enzyme-based alternatives that bypass ECHA scrutiny on aluminum chlorohydrate safety profiles.
- Pharmacy channel expansion:Dermatological positioning in Boots, DM, and Marionnaud stores captures premium price points for sensitive-skin roll-on formats.
- EU Green Deal sustainability frameworks:Mandatory biodegradability disclosures create first-mover advantages for manufacturers with established life-cycle assessment capabilities.
Market Restraints
- Isopropyl myristate supply concentration:Three specialty chemical suppliers control European feedstock for emollient bases, exposing formulators to input cost volatility.
- Compressed gas propellant technical limitations:Nitrogen and air-based systems deliver shorter spray duration than hydrocarbon alternatives, degrading user experience in high-humidity climates.
- REACH registration friction:New active ingredient approvals require 18-24 month ECHA evaluation windows, blocking rapid formulation pivots.
Strategic Opportunities
- Poland and Romania underpenetration:Eastern European markets show 40% lower per-capita deodorant consumption than Western benchmarks, with pharmacy channel buildout still nascent.
- Refillable stick formats:Reusable applicator systems align with CSRD extended producer responsibility requirements while locking in recurring consumable revenue.
- Subscription direct-to-consumer channels:Birchbox and local equivalents enable trial-to-loyalty conversion for niche natural brands bypassing retail slotting fees.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural actives and stable shelf-life performance concentrates in Basel and Paris clusters, constraining geographic expansion.
- Propellant-free packaging capex intensity:Pump spray and squeeze tube lines require $2-4 million per production line retrofit, straining mid-tier manufacturers.
- ISO 16128 natural certification complexity:Multi-source botanical supply chains complicate traceability documentation for organic percentage claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Deodorants Market |
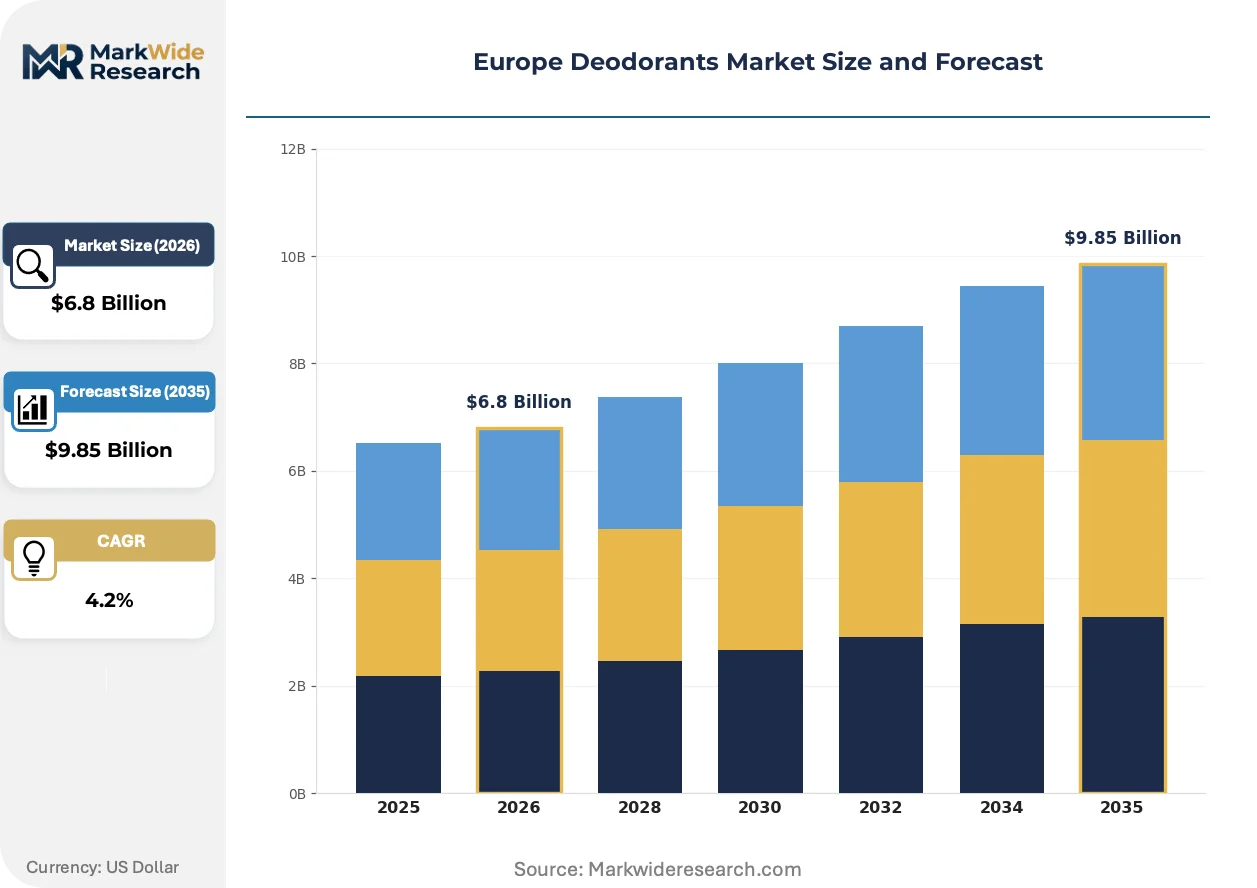
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Roll-on, Stick, Gel Customer Type: Men, Women, Teens, Seniors Formulation: Natural, Antiperspirant, Alcohol-free, Scented Distribution Channel: Supermarkets, Drugstores, Online, Salons |
| Companies Covered | Unilever PLC, Beiersdorf AG, Procter & Gamble Company, L'Oréal SA, Henkel AG & Co. KGaA, Coty Inc., Colgate-Palmolive Company, Church & Dwight Co. Inc., Estée Lauder Companies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Deodorants Market Shifts & Advancements
Biotechnology-derived actives and packaging format innovation are compressing traditional competitive moats while regulatory transparency mandates recalibrate brand-consumer trust mechanisms across European markets.
Prebiotic and postbiotic antimicrobial systems are supplanting traditional triclosan and aluminum-based odor control in premium roll-on and stick formats. Young adult men in urban Germany and the Netherlands adopt these formats fastest, with pharmacy渠道 positioning accelerating trial rates. This biological approach is supplanting legacy chemical blocks by enabling "skin microbiome-friendly" marketing claims that command 15-30% shelf price premiums.
REACH Annex XIV authorization requirements for siloxanes and certain aluminum salts are compressing formulation freedom for aerosol manufacturers. ECHA's 2024-2025 substance evaluation roadmap forces either costly substitution investments or geographic portfolio narrowing. Spray format specialists in Spain and Italy face the steepest compliance cliffs, with several accelerating plant-based active partnerships to maintain market access.
Urban French and British consumers now prioritize ingredient transparency over fragrance intensity, reversing two decades of scent-centric positioning. Clean beauty retailers such as Content Beauty and Oh My Cream curate assortments around EWG-verified and COSMOS-standard products, displacing conventional drugstore discovery. This preference shift concentrates in London, Paris, and Berlin metropolitan zones where digital-native brands capture share through educational social content rather than traditional advertising.
Europe Deodorants Market Segmentation
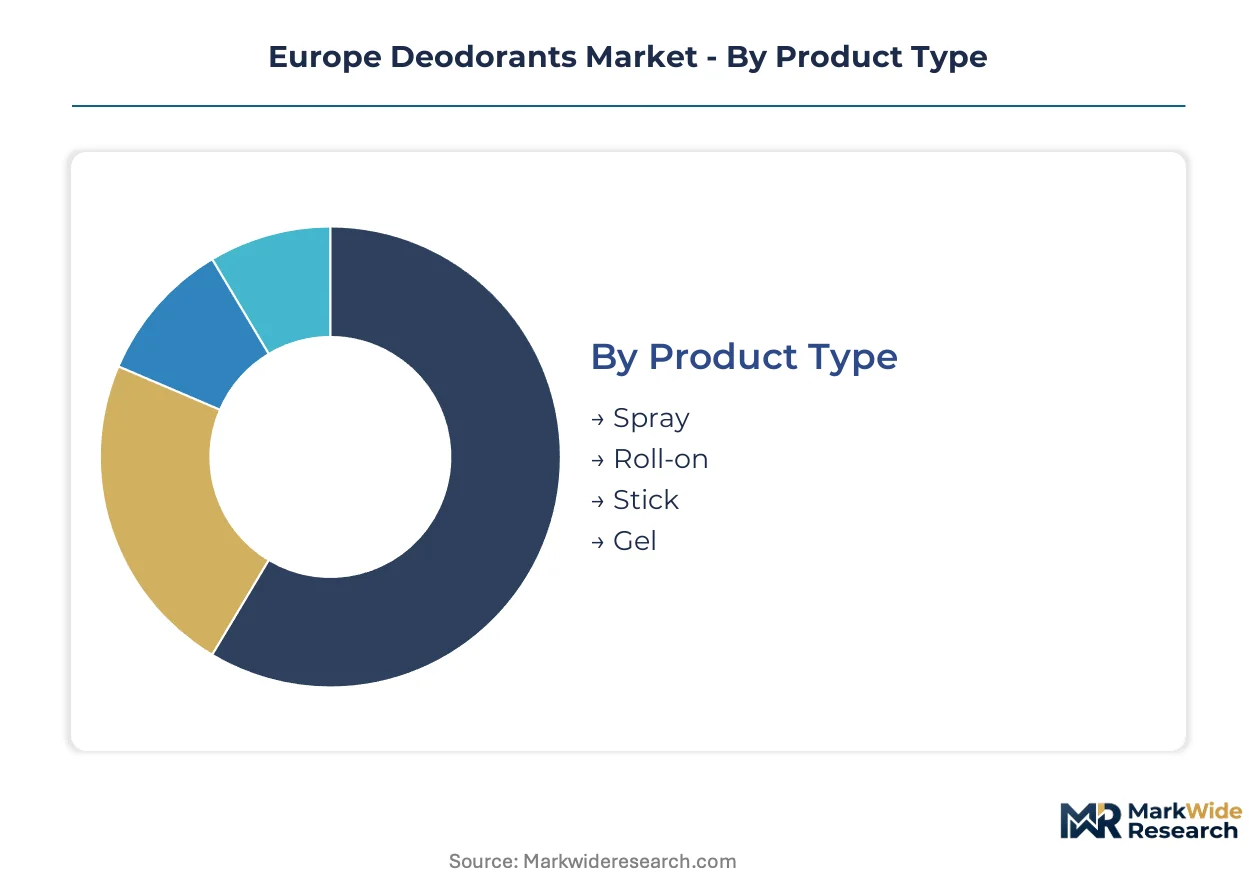
Deodorant manufacturers in Europe must align product architecture with divergent regulatory pressures and channel economics. Each segmentation dimension carries distinct substitution vulnerabilities and margin structures that reshape portfolio priorities.
Product Type:
Spray formats face the steepest substitution pressure from compressed gas alternatives as REACH propellant restrictions tighten, while solid formats exploit refillable packaging exemptions under CSRD extended producer responsibility rules.
- Spray:Aerosol systems deliver aluminum-based actives through hydrocarbon or compressed gas propellants. German and French mass-market retailers still move the highest spray volumes, though ECHA substance evaluations are forcing rapid reformulation toward nitrogen-based systems that degrade humid-climate performance.
- Roll-on:Liquid ball-applicator formats concentrate premium positioning in pharmacy and salon channels. Young adult men in urban Netherlands and Germany adopt aluminum-free roll-ons fastest, with mineral salt and enzyme-based alternatives commanding shelf price premiums of fifteen to thirty percent over conventional antiperspirants.
- Stick:Wax-based solid matrices enable travel-size portability and dermatological claims in Boots and DM stores.
- Gel:Transparent silicone or water-based carriers target sensitive-skin positioning with faster dry-down properties.
Spray anchors the volume base while roll-on gains share at the steepest rate.
Customer Type:
Gender-based targeting fragments across distinct channel strategies and price elasticity profiles, with male-oriented formats showing stronger pharmacy migration and female segments concentrating in supermarket and online discovery.
- Men:Young adult males in Germany and the Netherlands drive fastest adoption of prebiotic and postbiotic antimicrobial roll-ons. Pharmacy channel positioning accelerates trial rates for microbiome-friendly claims that bypass aluminum safety scrutiny.
- Women:Scented and fragrance-layered formulations dominate female-targeted assortments in Marionnaud and drugstore chains. London and Paris metropolitan consumers prioritize ingredient transparency over fragrance intensity, reversing decades of scent-centric positioning.
- Teens:First-purchase occasions concentrate in supermarket impulse zones and subscription box sampling.
- Seniors:Dermatological and alcohol-free positioning captures loyalty in pharmacy channels with higher repeat purchase rates.
Women anchor the volume base while men expand most quickly through premium format adoption.
Formulation:
Regulatory disclosure mandates are compressing the competitive window for conventional antiperspirants while creating first-mover advantages for manufacturers with established natural certification pipelines.
- Natural:Plant-derived actives and botanical bases require ISO 16128 traceability documentation that complicates multi-source supply chains. Clean beauty retailers in London, Paris, and Berlin curate assortments around EWG-verified and COSMOS-standard products, displacing conventional drugstore discovery.
- Antiperspirant:Aluminum chlorohydrate and aluminum zirconium compounds face ECHA safety profile evaluations that extend registration timelines. Spanish and Italian spray specialists confront the steepest compliance cliffs as REACH Annex XIV authorization requirements compress formulation freedom.
- Alcohol-free:Elimination of ethanol carriers targets sensitive-skin and post-shave applications in pharmacy channels.
- Scented:Synthetic fragrance compounds retain mass-market cost advantages despite shifting consumer preference toward ingredient minimalism.
Antiperspirant anchors the volume base while natural climbs the fastest through clean beauty channel expansion.
Distribution Channel:
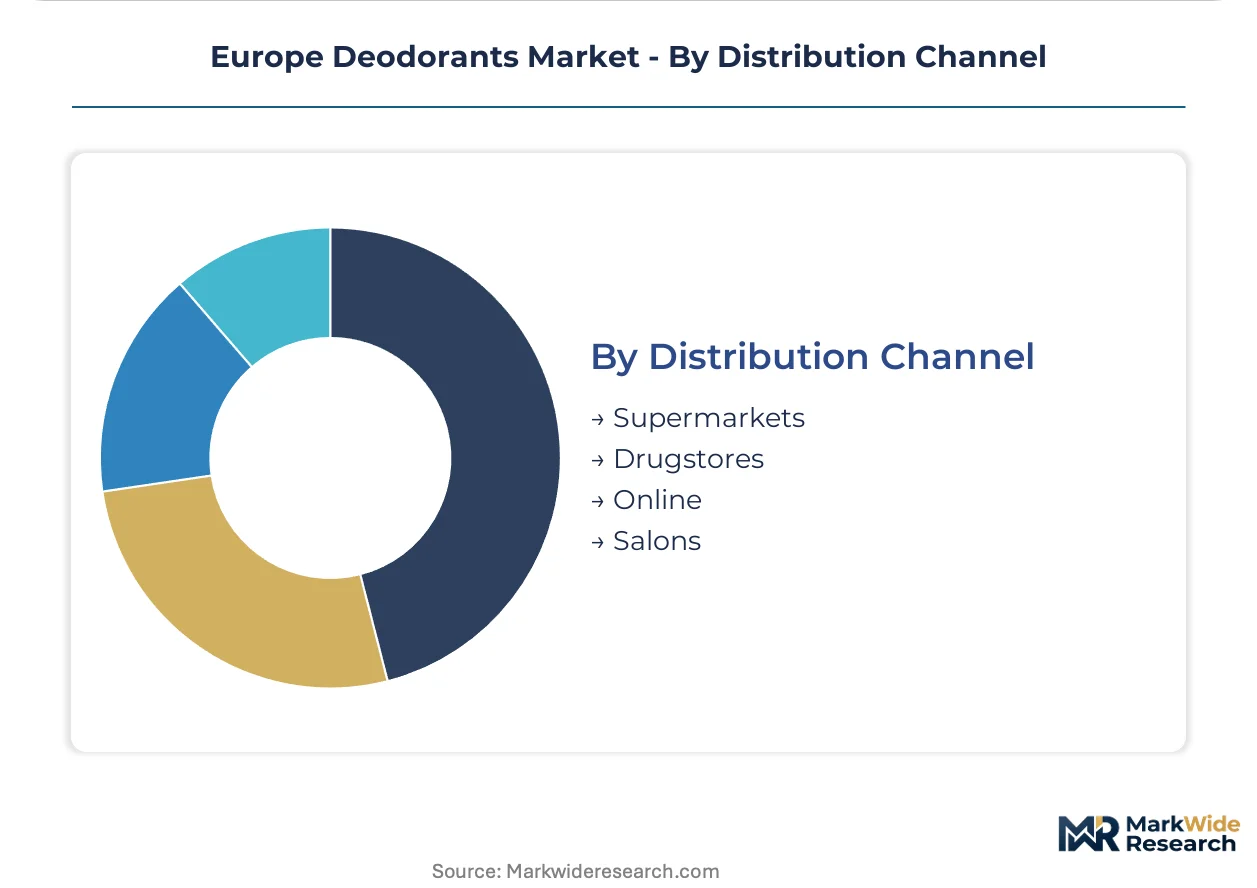
Channel economics diverge sharply between high-frequency supermarket replenishment and high-margin pharmacy positioning, with online subscription models capturing trial-to-loyalty conversion for niche natural brands.
- Supermarkets:Mass-volume spray and stick formats dominate shelf space in Carrefour, Tesco, and Rewe chains. Lower per-unit pricing and promotional intensity sustain cost-leadership positions for integrated manufacturers with captive supply chains.
- Drugstores:Boots, DM, and Marionnaud stores capture premium price points for sensitive-skin roll-ons and dermatological stick formats. Pharmacy channel buildout remains nascent in Poland and Romania, creating whitespace for format-specific entrants.
- Online:Birchbox and local subscription equivalents enable trial-to-loyalty conversion for niche natural brands bypassing retail slotting fees.
- Salons:Professional service channels concentrate fragrance-layered and premium positioning with higher staff recommendation influence.
Supermarkets anchor the volume base while online gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across European deodorant markets, with Eastern European consumers showing higher sensitivity to per-unit costs while German and French buyers absorb premiums for natural-certified formulations.
Germany
Young adult males in Berlin and Hamburg drive fastest adoption of prebiotic roll-on formats through pharmacy channels. REACH registration timelines for new aluminum salt alternatives compress product development cycles for domestic formulators. The Rhine-Main manufacturing corridor hosts concentrated R&D facilities where biotechnology-derived actives undergo stability testing.
France
Paris metropolitan consumers prioritize ingredient transparency over fragrance intensity, reversing decades of scent-centric positioning. ANSM cosmetic safety guidelines enforce stricter disclosure requirements than baseline EU directives. Lyon-based specialty chemical clusters supply enzyme-based odor control systems to premium roll-on manufacturers.
United Kingdom
Clean beauty retailers in London curate assortments around EWG-verified and COSMOS-standard products, displacing conventional drugstore discovery. Post-Brexit regulatory divergence from REACH creates compliance friction for imported formulations. The Manchester-Leeds industrial belt houses contract manufacturing capacity serving subscription direct-to-consumer brands.
Spain
Spray format specialists confront steepest compliance cliffs as ECHA Annex XIV authorization requirements restrict siloxane usage in aerosol propellant systems. Barcelona and Madrid urban consumers show accelerating migration toward stick formats with refillable packaging. Andalusian botanical suppliers expand cultivation of plant-derived antimicrobial feedstocks for natural certification pipelines.
Poland
Per-capita deodorant consumption runs forty percent below Western European benchmarks, with pharmacy channel buildout still nascent in Warsaw and Kraków metropolitan zones. EU Green Deal sustainability frameworks create first-mover advantages for manufacturers establishing local life-cycle assessment capabilities. Silesian industrial zones attract contract packaging investment serving underpenetrated Eastern European distribution networks.
Europe Deodorants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe Deodorants Market, creating tiered competitive dynamics rather than consolidated dominance. Mass-market scale operators leverage integrated supply chains to sustain price positioning in spray formats across supermarket channels. Premium-positioned specialists concentrate R&D intensity in antiperspirant technologies and microbiome-friendly formulations. Strategic moves cluster around portfolio diversification toward natural-certified segments and geographic expansion into underpenetrated Eastern European markets.
Among Anglo-Dutch and German personal care conglomerates, Unilever PLC and Beiersdorf AG exemplify divergent strategic archetypes—one optimizing cost leadership through supply chain integration, the other anchoring premium positioning through specialized antiperspirant research. French beauty multinationals L'Oréal SA occupy the fragrance-layered formulation tier, commanding higher shelf positioning in drugstore and salon channels through premium scent architecture.
| Leading Market Players |
|---|
| Unilever PLC |
| Beiersdorf AG |
| Procter & Gamble Company |
| L'Oréal SA |
| Henkel AG & Co. KGaA |
| Coty Inc. |
| Colgate-Palmolive Company |
| Church & Dwight Co. Inc. |
| Estée Lauder Companies |
| Others |
Supply & Pricing Matrix
REACH registration timelines and CSRD biodegradability disclosures gate both supplier qualification and shelf-price premiums simultaneously. European manufacturers with established regulatory affairs capabilities capture margin advantages while importers face extended ECHA evaluation windows that compress pricing flexibility.
Pricing Analysis
Recurring consumable revenue through refillable stick systems anchors lifetime value calculations for premium-positioned players. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel positioning. Cost compression in mass-market spray tiers intensifies as hydrocarbon propellant restrictions force nitrogen-based retrofits. Supermarket buyers in Germany and France show highest price sensitivity while pharmacy channel consumers absorb fifteen to thirty percent premiums for dermatological positioning.
Supply Chain Analysis
Inventory buffers for isopropyl myristate emollient bases extend lead times as three specialty chemical suppliers concentrate European feedstock control. Formulation expertise clusters in Basel and Paris while botanical antimicrobial sourcing expands through Andalusian cultivation zones. Single-source vulnerability runs through compressed gas propellant systems where nitrogen infrastructure remains underdeveloped. Distribution runs through integrated supermarket chains, pharmacy networks, and direct-to-consumer subscription platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, CSRD, and national pharmacy standards creates niche entry points for specialized formulators. Clean beauty preference shifts in London, Paris, and Berlin metropolitan zones reward transparency-first positioning over scale economies.
For Market Incumbents: Fortify pharmacy channel control through dermatological certification investments that preempt aluminum-free substitution threats. Accelerate backward integration into botanical supply chains to secure ISO 16128 traceability documentation before disclosure mandates tighten. Lock in Silesian contract packaging capacity to serve underpenetrated Eastern European distribution networks before mid-tier competitors establish footholds. For New Entrants and Emerging Players: Differentiate on microbiome-friendly claims targeting young adult men in urban Netherlands and Germany where pharmacy adoption curves remain steepest. Exploit whitespace in Polish and Romanian markets where per-capita consumption trails Western benchmarks by forty percent. Deploy subscription direct-to-consumer trials through Birchbox equivalents to bypass retail slotting fees and build loyalty before shelf presence. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across propellant-free packaging retrofits where pump spray lines demand two to four million per production line. Long-term viability favors acquisition targets with established life-cycle assessment capabilities and regulatory affairs bandwidth rather than pure brand assets. Watch ECHA substance evaluation roadmaps for aluminum salt restriction announcements as inflection signals for portfolio reallocation toward mineral salt and enzyme-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Partnership | Biotechnology-derived active collaborations bypass REACH registration friction for spray format specialists. |
| Pharmacy Channel Expansion | DM and Boots positioning captures premium price points for sensitive-skin roll-on formats in Germany. |
| Refillable Packaging Launch | Reusable applicator systems align with CSRD extended producer responsibility requirements. |
| Subscription Platform Integration | Birchbox trials enable loyalty conversion for niche natural brands without retail slotting costs. |
| Botanical Supply Integration | Andalusian antimicrobial feedstock sourcing secures ISO 16128 certification pipeline advantages. |
Research Methodology
Desk research of ECHA substance evaluation databases, customs trade records, and pharmacy retail audit data preceded structured interviews with cosmetic formulation directors, regulatory affairs managers, and category buyers at DM and Boots chains. Primary fieldwork with supply chain planners at specialty chemical producers and sustainability officers at packaging converters cross-validated secondary inputs. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Variance decomposition separated volume, price, and mix effects across product type, customer segment, formulation category, and distribution channel dimensions. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue contributions. Forecast inputs incorporated REACH Annex XIV authorization timelines, CSRD disclosure phase-in schedules, and pharmacy channel buildout trajectories in Eastern European markets.
Material uncertainties — ECHA substance restriction announcements, propellant system technical breakthroughs, and Eastern European retail consolidation patterns — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and consumer preference migration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Allyl Heptanoate Market
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market