
 Fragrance Wax Melts Market | 2026-2036
Fragrance Wax Melts Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Wax Melts Market Analysis
Buyer concentration among online shoppers is hardening as e-commerce platforms capture a disproportionate share of fragrance wax melt volume. Scentsy anchors its position through direct sales channel control and independent consultant networks. Yankee Candle Company leverages its brand strength and retail footprint to compete across brick-and-mortar and digital storefronts. S. C. Johnson & Son sustains manufacturing scale advantages in mass-market distribution through its established household products infrastructure.
Fragrance wax melts are scented wax formulations, typically composed of paraffin, soy, or beeswax bases infused with fragrance oils at concentrations between 6% and 12%, designed to release aroma when warmed in electric or tea-light melters without open flame combustion. The primary commercial purpose centers on delivering controlled, flameless home fragrance for residential and hospitality environments. Eco-friendly and organic product types command premium positioning as ingredient transparency becomes a decisive purchase factor. Clamshell form dominates shelf economics in mass retail, while bar and tart formats occupy specialty and artisan channels where customization drives margin pools.
EPA indoor air quality guidelines and REACH chemical registration requirements in Europe constrain synthetic fragrance formulations and mandate phased ingredient disclosure. The EU Green Deal and state-level clean air statutes in California and New York are accelerating reformulation toward plant-derived wax bases and natural essential oil blends. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to pursue unified global formulations or region-specific product architectures.
Market Dynamics
Flameless home fragrance adoption is compressing traditional candle demand as millennial and Gen Z consumers prioritize safety-conscious, customizable scent delivery systems across residential and hospitality environments.
Growth Catalysts
- REACH chemical registration:European phased ingredient disclosure mandates are accelerating reformulation toward plant-derived wax bases and natural essential oil blends, creating premium positioning for compliant manufacturers.
- Hospitality sector expansion:Boutique hotels and Airbnb hosts are standardizing wax melt systems for consistent brand scenting without fire safety liability concerns.
- Soy and beeswax cultivation:Agricultural supply chain maturation in the United States and Brazil is reducing raw material cost volatility for eco-positioned product lines.
Market Restraints
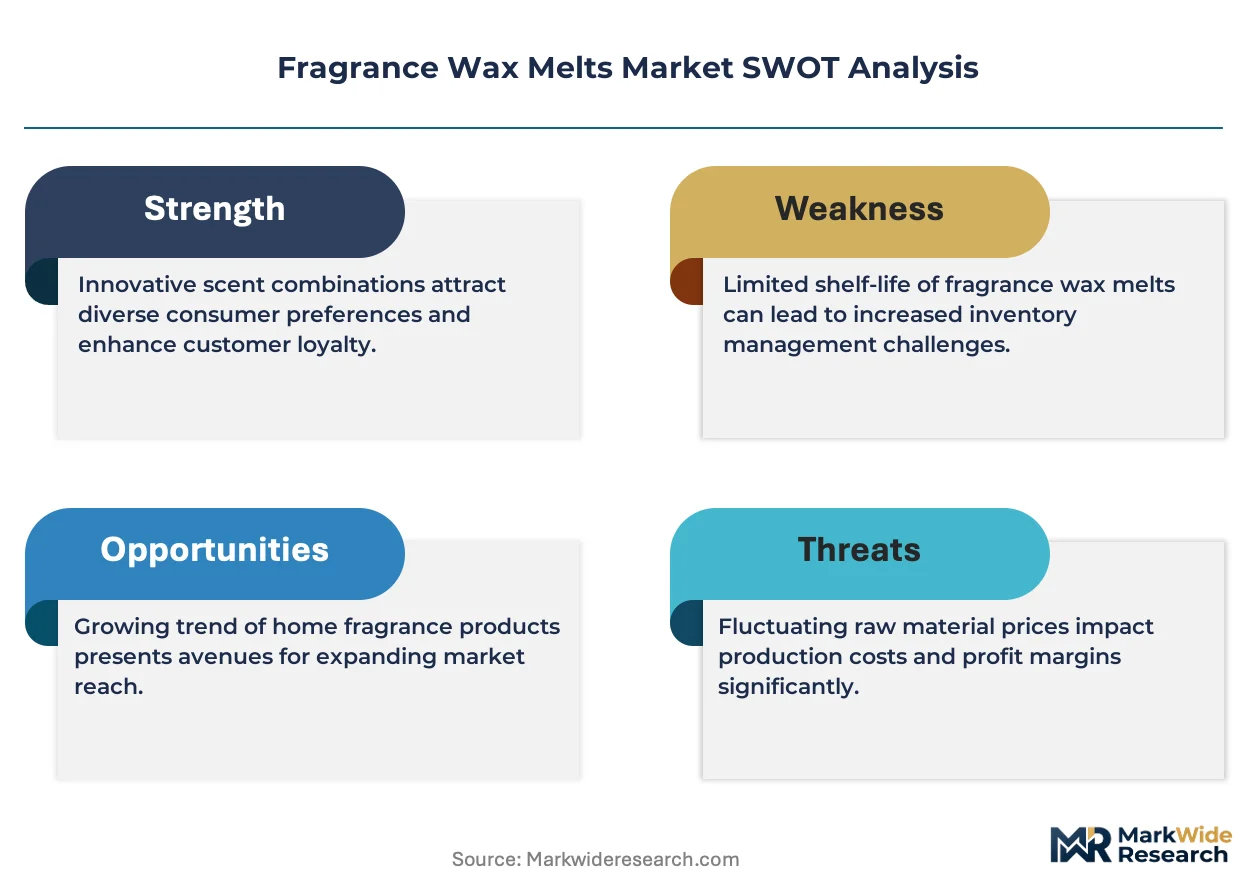
- Petrochemical feedstock volatility:Paraffin wax price sensitivity to crude oil fluctuations constrains margin stability for mass-market producers dependent on synthetic bases.
- Chinese manufacturing concentration:Melter hardware and packaging component sourcing clusters in Guangdong and Zhejiang provinces expose brands to geopolitical trade friction and shipping disruption.
- Diffuser technology substitution:Ultrasonic essential oil diffusers and smart home-integrated scent systems are capturing safety-conscious consumers seeking programmable fragrance delivery.
Strategic Opportunities
- Subscription commerce penetration:Curated scent-of-the-month models through direct-to-consumer platforms are capturing recurring revenue from digitally native households in the United Kingdom and Germany.
- EU Green Deal alignment:Carbon-neutral certification pathways and circular packaging mandates are creating first-mover advantage for brands investing in biodegradable clamshell alternatives.
- Smart home convergence:Integration with Alexa and Google Home ecosystems for scheduled warming cycles is opening premium pricing tiers among tech-forward millennial homeowners.
Industry Challenges
- Fragrance chemist talent scarcity:Formulation expertise combining IFRA compliance with natural oil stability is concentrating among a limited pool of specialized compounders in Grasse and New Jersey.
- California Proposition 65 litigation exposure:Warning label requirements for trace chemical constituents are forcing defensive reformulation investments ahead of scientific consensus on risk thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Wax Melts Market |
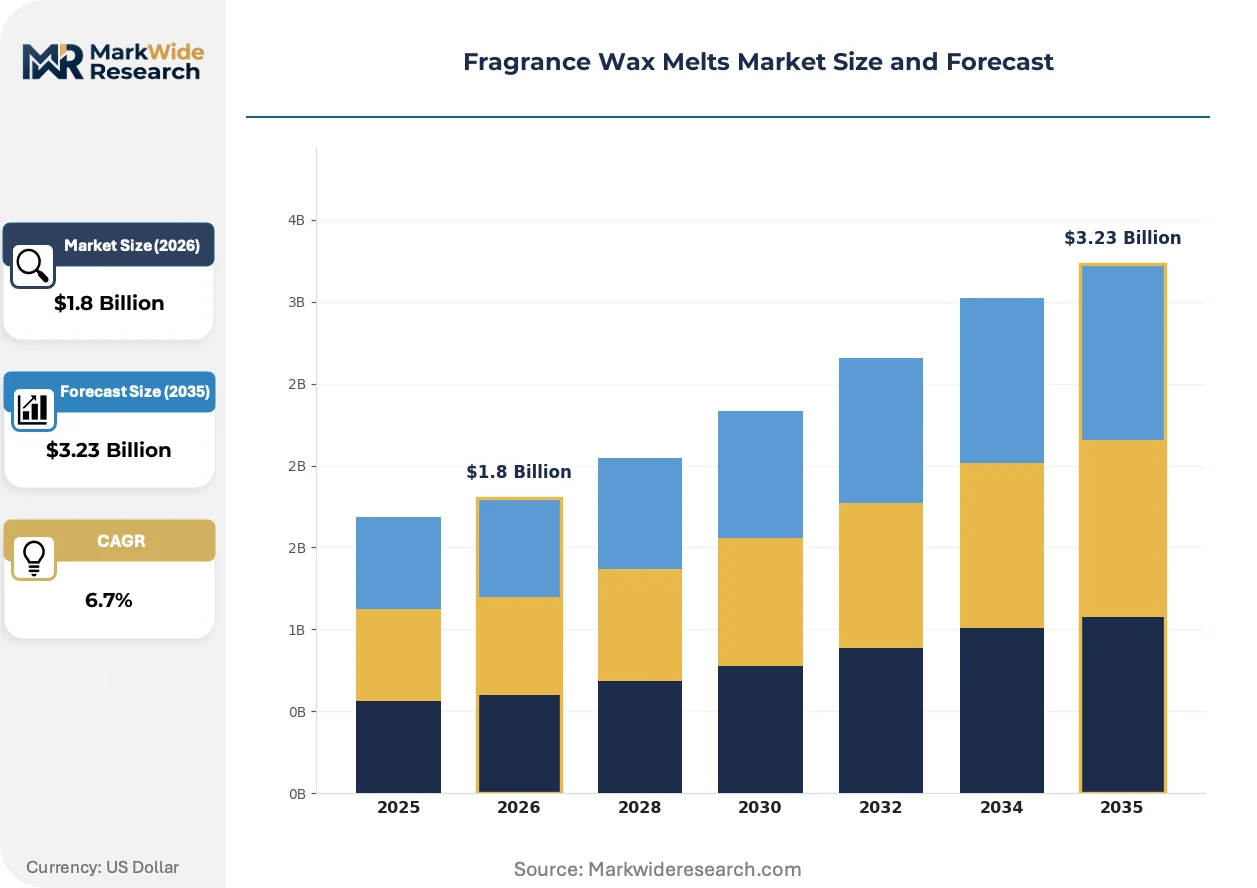
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Highly Scented, Eco-Friendly, Organic, Aromatherapy Form: Clamshell, Bar, Tart, Pillar Customer Type: Retail Consumers, Wholesale Buyers, Specialty Stores, Online Shoppers Distribution Channel: Online Marketplaces, Brick-and-Mortar Stores, Specialty Shops, Direct Sales |
| Companies Covered | Yankee Candle Company, Scentsy, S. C. Johnson & Son, Candle Warmers Etc., Bridgewater Candle Company, ScentSationals, Happy Wax, NEST Fragrances, East Coast Candles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Wax Melts Market Emerging Trajectories
Wax melt innovation is pivoting toward ingredient transparency and connected hardware as regulatory pressure and consumer scrutiny converge on formulation chemistry and usage safety.
Coconut-soy hybrid wax bases are unifying the performance characteristics of paraffin with the marketing appeal of plant-derived ingredients. Premium artisan producers in Oregon and Vermont are adopting these blends at accelerating rates. The technology is unifying previously separate consumer segments—eco-conscious buyers and performance-focused traditionalists—into a single addressable premium tier.
EPA indoor air quality guidance revisions are tightening permissible volatile organic compound thresholds for heated fragrance products. Manufacturers serving the United States market are pre-emptively reducing synthetic musk and phthalate concentrations. Small-batch producers in California and New York are responding fastest, leveraging shorter reformulation cycles than mass-market competitors.
Direct-to-consumer sampling programs are displacing retail aisle discovery as the primary trial mechanism for new scent launches. Independent consultant networks and micro-influencer partnerships are capturing discovery-stage consumers before they enter physical stores. This channel rotation is most visible in suburban United States markets where home-based selling models retain cultural acceptance.
Fragrance Wax Melts Market Segmentation
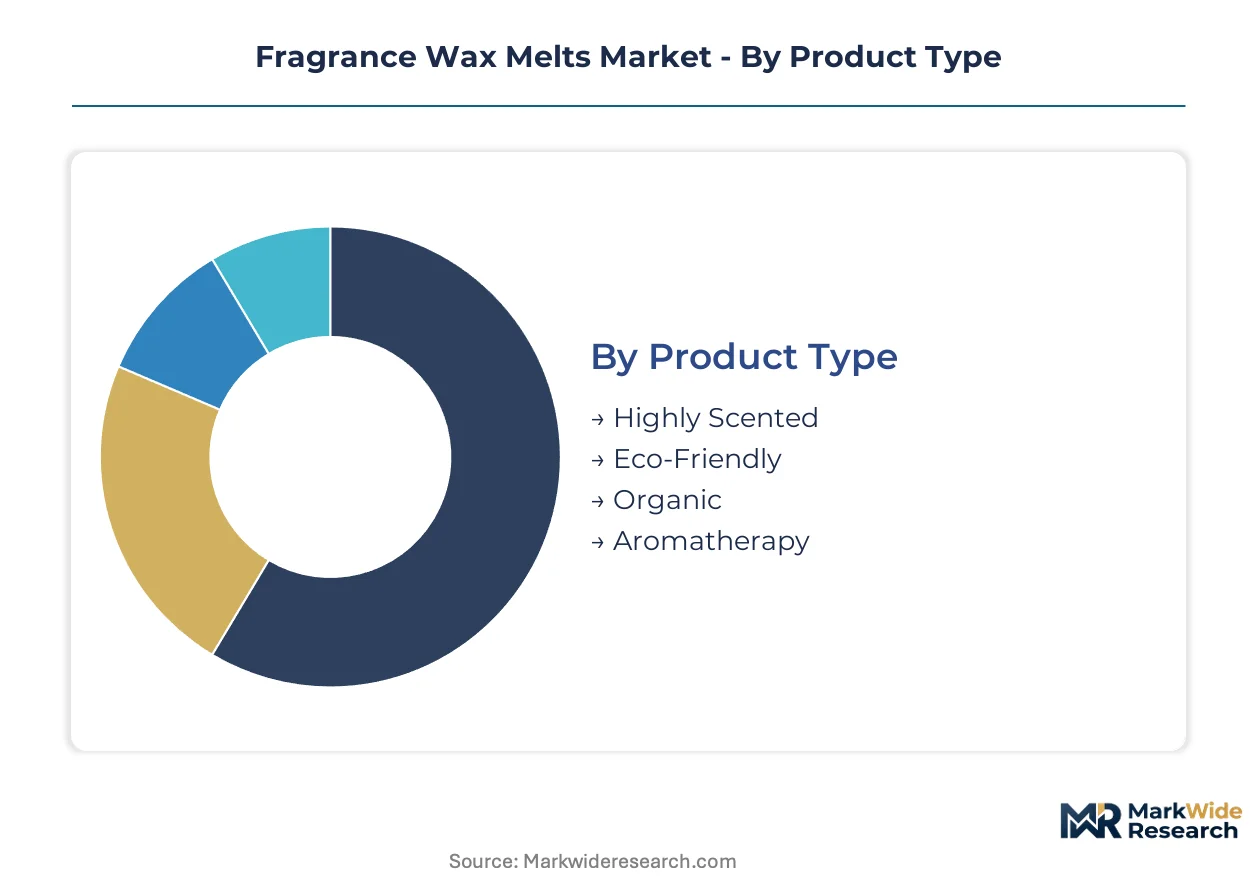
Fragmentation across product chemistry, physical form, and purchase channel creates distinct margin architectures for fragrance wax melt producers. Each segment demands specialized formulation expertise, packaging investment, and route-to-market discipline that shapes competitive positioning.
Product Type:
Capital intensity peaks with organic certification pathways and essential oil stability testing, while highly scented variants leverage existing paraffin infrastructure with lower compliance overhead.
- Highly Scented:Synthetic fragrance oil formulations at 10-12% concentration deliver maximum throw performance for mass-market consumers prioritizing intensity over ingredient provenance. Demand concentrates in suburban United States households through big-box retail channels where price elasticity remains high. Reformulation pressure from EPA volatile organic compound guidance is compressing margins for legacy producers.
- Eco-Friendly:Plant-derived wax bases blended with responsibly sourced fragrance oils target millennial and Gen Z online shoppers in the United Kingdom and Germany. REACH compliance costs and carbon-neutral certification requirements elevate upfront investment versus conventional lines. Premium positioning sustains 40-60% price deltas over paraffin equivalents.
- Organic:USDA or Soil Association certified formulations with full supply chain traceability.
- Aromatherapy:Essential oil-based products with therapeutic positioning and wellness marketing claims.
Most installed capacity flows through highly scented lines. Expansion is steepest in eco-friendly formulations.
Form:
Manufacturing equipment requirements and packaging automation rates vary dramatically by physical configuration, dictating which producers can compete across multiple formats.
- Clamshell:Thermoformed plastic packaging with six-cavity standardization dominates mass retail shelf economics and inventory turnover metrics. Walmart and Target distribution in the United States demands this format exclusively. Mold tooling amortization across high volumes creates barrier to entry for artisan competitors.
- Bar:Hand-poured or slab-cut formats with minimal packaging support premium artisan positioning and customization. Oregon and Vermont producers exploit this flexibility for limited-batch releases. Direct-to-consumer shipping economics favor lower cube density versus clamshell alternatives.
- Tart:Small individual pieces designed for sampler assortments and multi-scent discovery sets.
- Pillar:Freestanding wax forms requiring specialized release agents and cooling protocols.
Clamshell production lines absorb the majority of fixed capital deployment. Bar formats are climbing the fastest as subscription commerce penetration deepens.
Customer Type:
Procurement behavior and order economics diverge sharply between fragmented retail demand and concentrated wholesale contracting.
- Retail Consumers:Individual purchasers through digital and physical storefronts with high scent variety preferences and low per-transaction volumes. Amazon and Etsy algorithms in the United States and United Kingdom drive discovery toward bestseller rankings and review velocity. Customer acquisition costs through paid social channels are eroding lifetime value calculations for direct brands.
- Wholesale Buyers:Hospitality procurement teams at boutique hotel chains and Airbnb property management companies standardizing signature scent programs. Fire safety liability elimination and brand consistency requirements favor long-term supply agreements. Volume commitments justify dedicated production runs and custom formulation development.
- Specialty Stores:Curated independent retailers with localized assortment strategies and education-heavy selling environments.
- Online Shoppers:Digital-native consumers with subscription propensity and influencer-driven trial behavior.
Wholesale relationships anchor manufacturing capacity planning. Online shoppers are expanding most quickly as platform algorithms reshape category visibility.
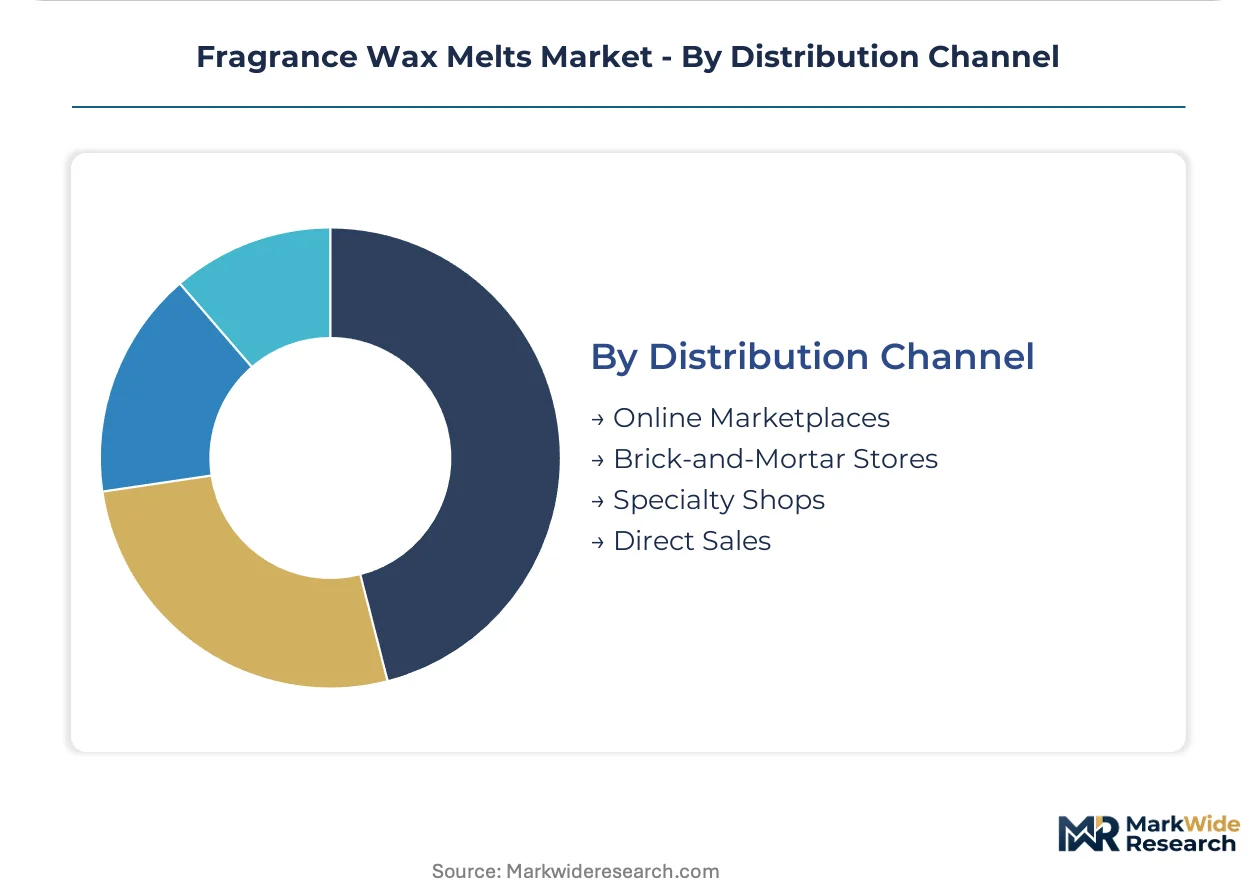
Distribution Channel:
Route-to-market selection determines margin retention, brand control, and customer data access with irreversible strategic consequences.
- Online Marketplaces:Amazon, Etsy, and Walmart.com capture disproportionate volume in the United States and United Kingdom through search dominance and fulfillment infrastructure. Commission structures and advertising auction dynamics extract 25-35% of gross revenue at typical price points. Algorithm changes create demand volatility beyond producer control.
- Brick-and-Mortar Stores:Target, Walmart, and specialty retail chains provide tactile discovery and impulse purchase conversion. Slotting fees and promotional calendar compliance strain working capital for emerging brands. Geographic concentration in California, Texas, and Florida retail corridors shapes regional demand patterns.
- Specialty Shops:Independent retailers with curated assortments and staff-trained selling environments.
- Direct Sales:Consultant networks and brand-owned digital storefronts with full margin retention.
Brick-and-mortar fixtures command the largest capital deployment for fixture programs and inventory guarantees. Direct sales channels are gaining share fastest as platform dependency risks mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium scent innovation while Germany enforces the strictest chemical disclosure regimes, creating divergent competitive requirements across Atlantic markets.
United States
Millennial homeowners in suburban Texas and Florida markets are standardizing flameless fragrance systems as primary scent delivery. EPA indoor air quality guidance revisions are pressuring reformulation away from synthetic musks and phthalates. Portland and Vermont artisan clusters are accelerating coconut-soy hybrid wax adoption ahead of mass-market competitors.
Germany
REACH phased disclosure mandates are elevating compliance costs for imported fragrance formulations. The EU Green Deal carbon-neutral certification pathways are creating first-mover advantage for domestic brands investing in biodegradable packaging. Cologne and Hamburg specialty retailers are curating localized assortments emphasizing supply chain transparency.
United Kingdom
Subscription commerce penetration is deepest among digitally native households in Greater London and Manchester. Soil Association organic certification requirements are constraining ingredient sourcing for premium-positioned entrants. Bristol and Brighton artisan producers are exploiting direct-to-consumer shipping economics for bar-format specialty lines.
France
Boutique hotel chains in Paris and Provence are standardizing signature scent programs to eliminate fire safety liability. ANSM cosmetic ingredient oversight is extending to home fragrance categories with therapeutic positioning claims. Grasse fragrance compounders are concentrating scarce formulation expertise combining IFRA compliance with natural oil stability.
China
Guangdong and Zhejiang manufacturing clusters dominate melter hardware and packaging component supply. Dual carbon goals are pressuring energy-intensive paraffin wax refiners toward efficiency investments. Shanghai and Shenzhen e-commerce platforms are capturing outbound volume to Southeast Asian markets through cross-border fulfillment infrastructure.
Fragrance Wax Melts Market Vendor Landscape
United States producers anchor the premium direct-sales tier; European specialists hold compliance-advantaged positions in natural formulations. Market structure concentrates around three strategic archetypes: consultant-network direct sellers, mass-market household brands with retail footprint scale, and artisan specialists with subscription-commerce velocity. Dominant competitive moves include portfolio diversification into connected hardware and backward integration into captive wax supply.
Within the direct-sales archetype, Scentsy exemplifies channel control through independent consultant networks. Yankee Candle Company occupies a position spanning brick-and-mortar fixture programs and digital storefronts. S. C. Johnson & Son represents manufacturing scale advantages in mass-market distribution infrastructure.
| Leading Market Players |
|---|
| Yankee Candle Company |
| Scentsy |
| S. C. Johnson & Son |
| Candle Warmers Etc. |
| Bridgewater Candle Company |
| ScentSationals |
| Happy Wax |
| NEST Fragrances |
| East Coast Candles |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between USDA Organic and conventional paraffin lines manifests in both pricing power and supplier selection. REACH disclosure mandates in Germany and EPA guidance revisions in the United States force dual-track sourcing strategies that segment procurement teams by compliance tier rather than volume scale.
Pricing Analysis
Capacity additions in Brazil and the United States are reshaping price floors for plant-derived wax bases while paraffin remains tethered to crude volatility. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with Soil Association and USDA labels commanding 40-60% deltas. Cost compression in mass-market paraffin lines is intensifying because of petrochemical feedstock volatility. Big-box retail consumers in suburban United States markets exhibit highest price sensitivity; boutique hospitality procurement in France shows lowest.
Supply Chain Analysis
Returns and refurbishment flows for electric melter hardware are concentrated in Guangdong province reverse-logistics hubs. Wax base production draws from United States soy cultivation, Brazilian palm operations, and Chinese paraffin refining. Fragrance oil compounding rests on Grasse and New Jersey specialist clusters. Single-source vulnerability in Guangdong and Zhejiang melter component sourcing exposes brands to geopolitical friction. Distribution runs through Amazon and Walmart.com fulfillment networks in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH phased disclosure and EPA indoor air quality revisions are accelerating reformulation demand across premium tiers.
For Market Incumbents: Deploy captive wax supply integration to secure soy and beeswax volumes ahead of agricultural constraint periods. Consolidate formulation expertise through exclusive contracts with Grasse compounders to lock scarce IFRA-compliance talent. Ultrasonic diffuser substitution and smart home scent systems threaten flameless wax positioning; preemptive connected-hardware partnerships with Alexa and Google Home ecosystems defend channel relevance. For New Entrants and Emerging Players: Enter via subscription-commerce velocity in Greater London and Manchester where digitally native households show highest recurring-revenue propensity. Target Soil Association certification gaps among United Kingdom artisan producers lacking capital for full supply-chain traceability. White-space exists in biodegradable clamshell alternatives aligned with EU Green Deal mandates. Direct-to-consumer sampling programs offer lowest customer-acquisition friction versus Amazon algorithm dependency. For Investors and Strategic Acquirers: Asymmetric upside sits with coconut-soy hybrid specialists combining performance parity with plant-derived marketing appeal. Long-term viability favors brands with backward integration into United States agricultural supply rather than petrochemical exposure. Monitor EPA volatile organic compound threshold announcements and California Proposition 65 litigation filings as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Wax Supply | Secures soy and beeswax volumes from United States and Brazilian agricultural networks ahead of constraint periods. |
| Connected Hardware Partnership | Integrates wax melt warmers with Alexa and Google Home ecosystems for scheduled warming cycles. |
| Biodegradable Packaging Transition | Aligns clamshell formats with EU Green Deal circular packaging mandates for first-mover certification. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from Greater London and Manchester digitally native households. |
| Grasse Compounder Exclusive Contract | Locks scarce IFRA-compliance expertise combining natural oil stability with regulatory adherence. |
Methodological Framework
Direct dialogue with fragrance compounders, hospitality procurement directors, retail category buyers, and agricultural supply coordinators grounded qualitative findings. Secondary validation drew from EPA indoor air quality guidance documents, REACH registration databases, ECHA substance evaluations, and United States customs trade records. Bottom-up and top-down triangulation reconciled production capacity estimates with channel shipment data.
Bottom-up modeling aggregated segment-level volume assumptions across product type, physical form, and distribution channel dimensions; top-down validation cross-checked against regional household penetration rates and e-commerce platform transaction data. CAGRs were derived from normalized growth rate convergence across the projection horizon. Key inputs included soy and beeswax agricultural yield projections, paraffin refining capacity announcements, and hospitality sector occupancy recovery patterns.
Inputs from EPA guidance drafts and ECHA substance evaluations were available through the study window; gaps in proprietary fragrance oil formulation data introduce uncertainty bands around premium-tier growth assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and consumer willingness-to-pay for certification labels. Practitioners should monitor EPA volatile organic compound threshold announcements, REACH substance restriction proposals, and smart home device penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Encapsulated Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market