
 Herbal Fragrance Ingredients Market | 2026-2036
Herbal Fragrance Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Fragrance Ingredients Market Foresight
Grasse, France is rewriting the competitive map for botanical fragrance extraction as artisanal distilleries scale to industrial throughput. Givaudan SA leverages captive lavender and jasmine fields in Provence to secure raw material traceability. Symrise AG anchors its European natural fragrance portfolio through advanced supercritical CO2 extraction capabilities in Germany. Robertet Group specializes in solvent-free processes that preserve volatile terpene profiles for luxury perfume houses.
Herbal fragrance ingredients comprise plant-derived aromatic compounds obtained through steam distillation, solvent extraction, or enfleurage, typically containing complex terpenoid and phenylpropanoid mixtures at concentrations of 0.01% to 20% in finished formulations; these materials impart scent, mask base odors, and deliver perceived wellness benefits across personal care and home care products. Essential oils dominate volume throughput due to established supply chains for lavender, eucalyptus, and citrus peel feedstocks, while absolutes command premium positioning in fine fragrance applications where heat-sensitive floral notes require gentle extraction. Water-soluble formulations are gaining formulation share as clean-label personal care brands eliminate alcohol carriers, though oil-soluble variants still occupy the majority of perfume and aromatherapy applications.
EMA guidelines on natural product allergen labeling and REACH Annex XVII restrictions on sensitizing botanicals are forcing reformulation of classic herbal fragrance compounds across European manufacturing. FDA fragrance allergen disclosure rules and FEMA GRAS assessments for flavor-crossover botanicals create dual compliance burdens for suppliers serving both personal care and food-adjacent markets. Stakeholders must monitor evolving patch-testing requirements and bioprospecting regulations as novel plant sources enter commercial extraction pipelines.
Market Dynamics
REACH Annex XVII restrictions on sensitizing botanicals and EMA allergen labeling mandates are forcing wholesale reformulation of classic herbal fragrance portfolios across European manufacturing, compressing timelines for natural ingredient validation.
Growth Catalysts
- EU Green Deal compliance mandates:Premium personal care brands in France and Germany now specify botanical extracts meeting circular economy criteria, pulling demand toward certified sustainable supply chains.
- Water-soluble formulation expansion:Clean-label personal care brands eliminate alcohol carriers, creating formulation share gains for hydrosol-based fragrance systems in skincare and haircare applications.
- Grasse distillation cluster scaling:Traditional artisanal expertise in Provence anchors industrial throughput for high-value absolutes, concentrating premium extraction capacity in southern France.
Market Restraints
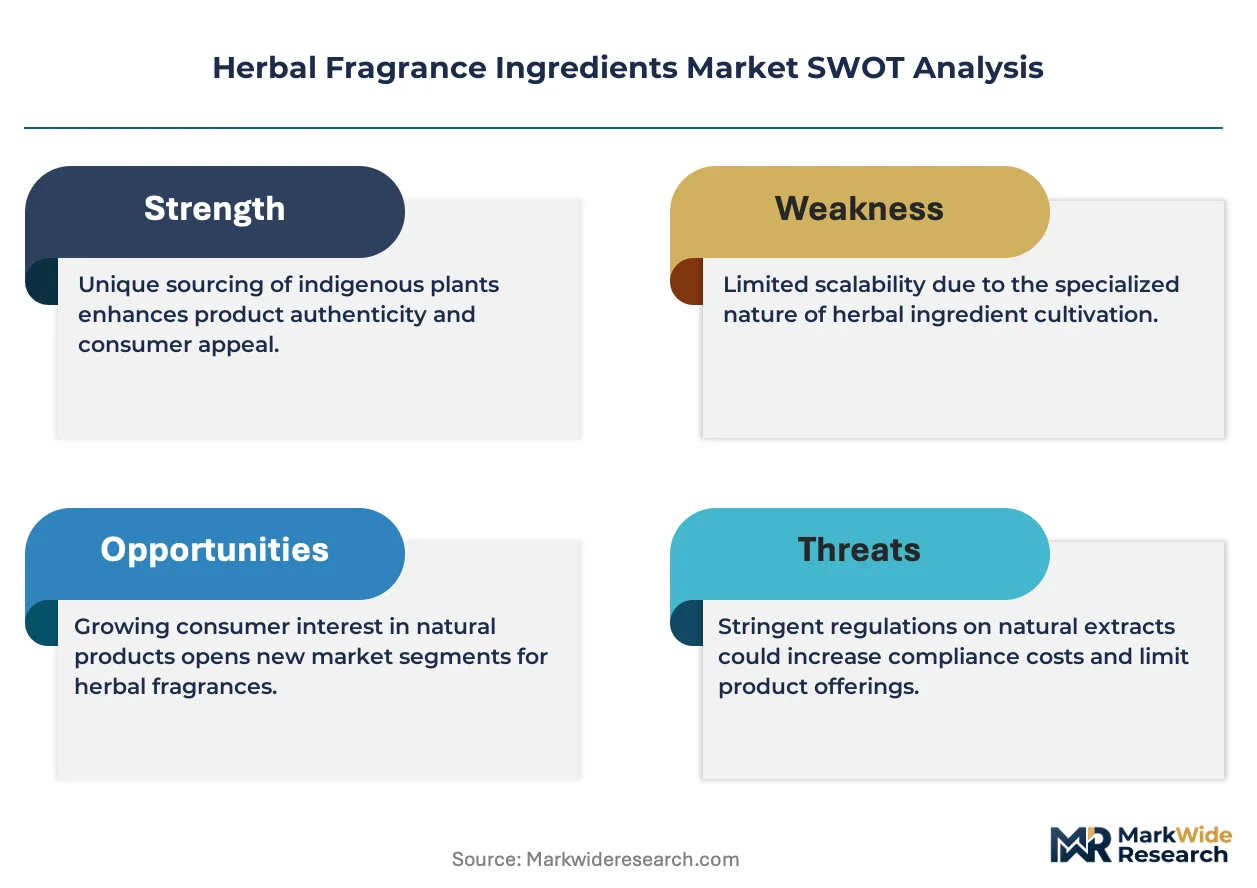
- Feedstock price volatility:Lavender and jasmine harvest yields fluctuate with Provençal climate patterns, compressing margin predictability for natural absolute producers.
- Single-region supply concentration:Steam distillation expertise and jasmine cultivation concentrate in Grasse, creating geographic vulnerability for luxury perfume house sourcing.
- Technical substitution pressure:Synthetic biology-derived aromatic molecules from fermentation platforms threaten premium positioning of field-grown botanical extracts.
Strategic Opportunities
- Supercritical CO2 extraction adoption:Advanced solvent-free technology preserves volatile terpene profiles for heat-sensitive floral notes, opening premium positioning in fine fragrance applications.
- Clean-label home care expansion:Aromatherapy and household product brands seek alcohol-free fragrance systems, creating channel innovation for water-soluble herbal concentrates.
- Novel botanical bioprospecting:Uncharacterized plant sources from Mediterranean and Alpine ecosystems offer proprietary compound discovery for differentiated scent portfolios.
Industry Challenges
- REACH registration timelines:Natural fragrance compound disclosure standards tighten continuously, extending compliance documentation cycles for novel botanical entrants.
- Cross-market regulatory duality:FDA fragrance allergen disclosure rules and FEMA GRAS assessments create parallel compliance burdens for suppliers serving personal care and food-adjacent markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Fragrance Ingredients Market |
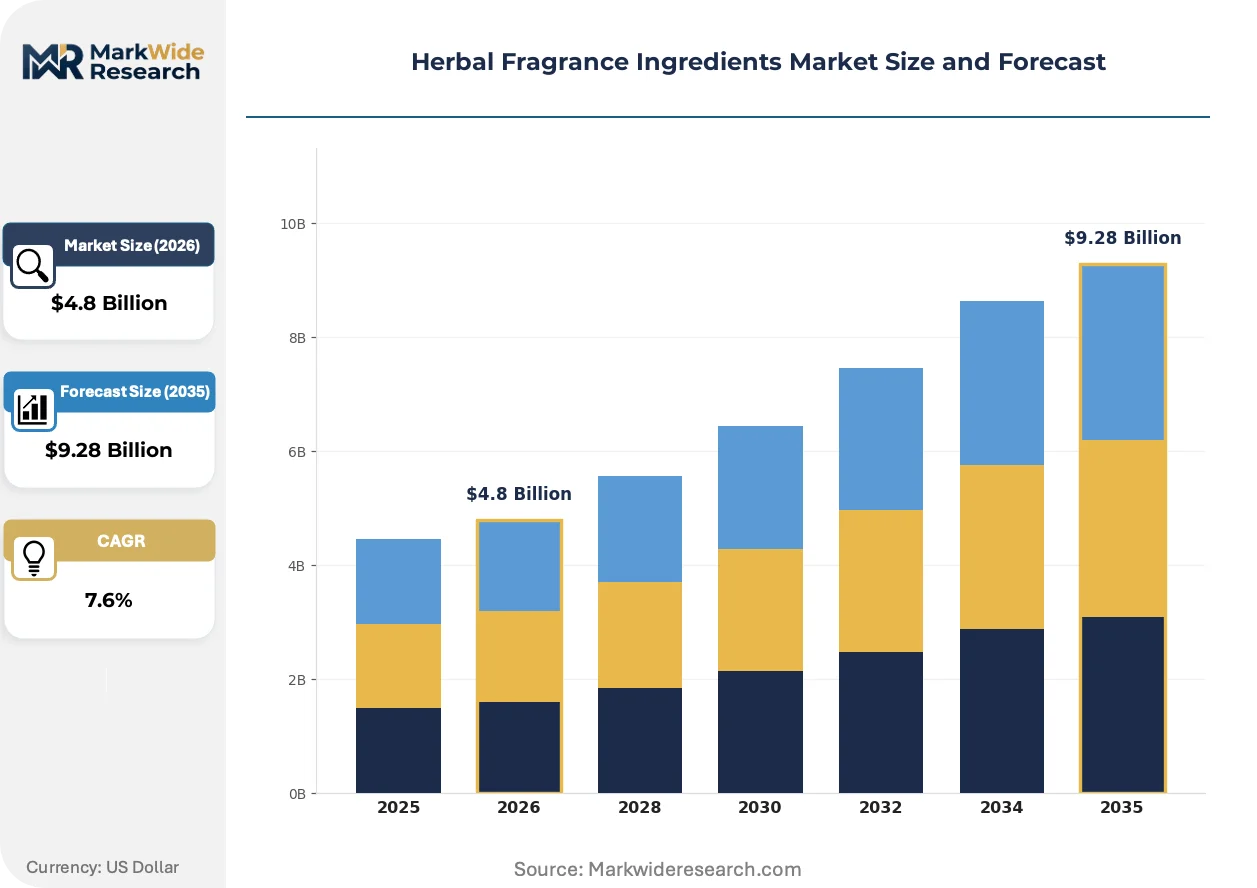
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Essential Oils, Absolutes, Extracts, Resinoids Application: Personal Care, Household Products, Cosmetics, Aromatherapy Formulation: Water-Soluble, Oil-Soluble, Powdered, Gelled Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Firmenich SA, Sensient Technologies Corporation, Symrise AG, Robertet Group, Takasago International Corporation, Givaudan SA, Mane SA, DSM-Firmenich, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Fragrance Ingredients Market Shifts & Advancements
Extraction technology convergence with regulatory disclosure mandates is reconfiguring how botanical fragrance compounds move from field to formulation, compressing the viable pathway for traditional processing methods.
Supercritical CO2 extraction is hybridizing with conventional steam distillation protocols in European processing facilities. Fine fragrance houses adopt these hybrid systems to preserve heat-sensitive floral terpenes while maintaining throughput scale. The technology is hybridizing cost structures across premium and mid-tier product lines, enabling broader access to previously artisan-only aromatic profiles.
REACH Annex XVII restrictions on sensitizing botanicals now mandate pre-market safety dossiers for 26 identified fragrance allergens. Cosmetic manufacturers reformulate classic lavender and jasmine compounds to reduce consumer patch-test reactions. Fine fragrance applications face the steepest compliance burden, driving investment in alternative solvent-free extraction methods.
Buyer concentration among clean-label personal care brands now dictates formulation specifications upstream. Direct sourcing contracts between Grasse distilleries and premium skincare houses displace traditional distributor networks. France and Germany exhibit the most pronounced channel consolidation, with personal care brands demanding captive field-to-flask traceability documentation.
Herbal Fragrance Ingredients Market Segmentation
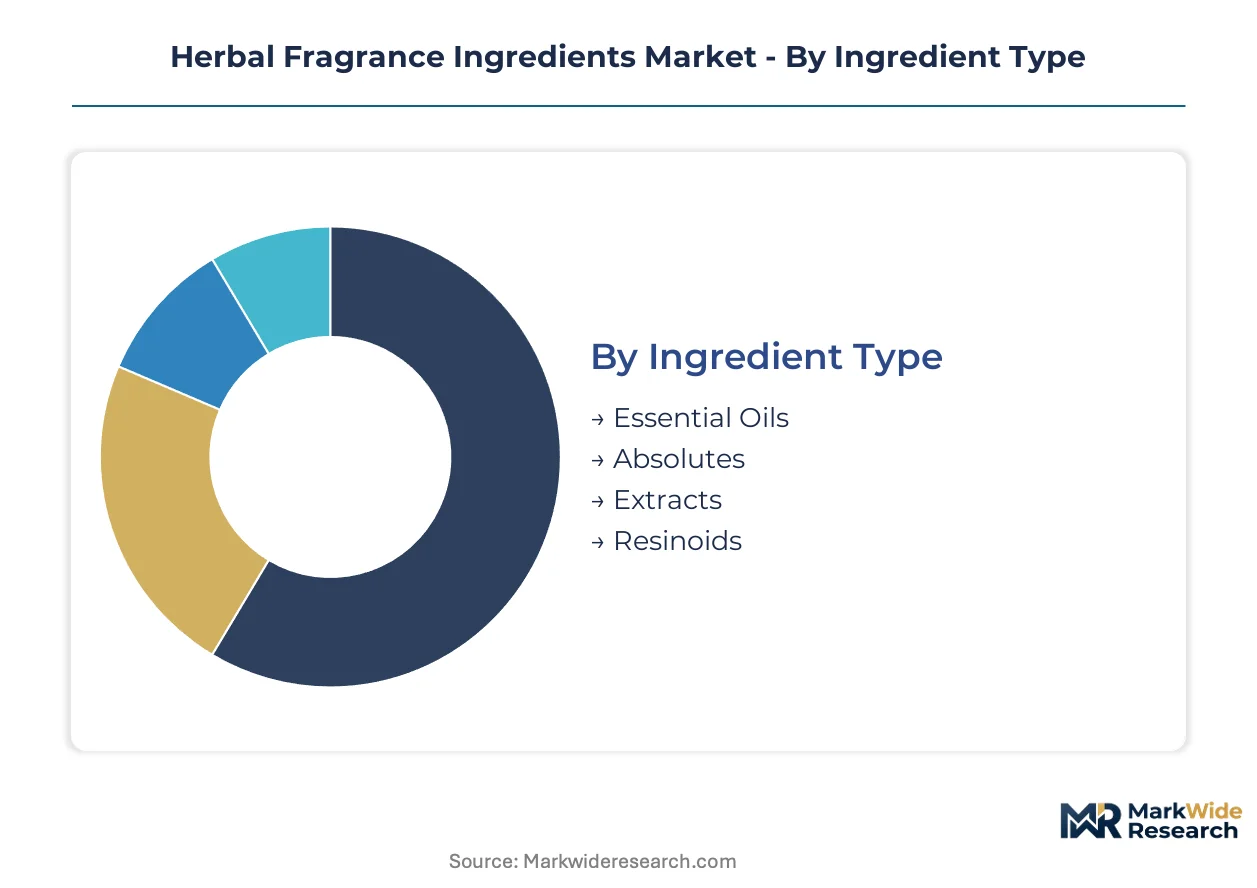
Segmentation in herbal fragrance ingredients reveals how extraction method, end-use specification, and channel economics create divergent margin profiles. Buyers sort across these dimensions based on formulation flexibility, regulatory documentation depth, and speed-to-market requirements.
Ingredient Type:
Cycle times vary dramatically: steam-distilled essential oils refresh inventory quarterly, while enfleurage-derived absolutes tie up working capital across harvest seasons.
- Essential Oils:Complex terpenoid and phenylpropanoid mixtures obtained through steam distillation of lavender, eucalyptus, and citrus peel feedstocks. Personal care brands in France specify these for volume fragrance applications where heat stability permits aggressive processing. Established supply chains dominate throughput.
- Absolutes:Solvent-extracted aromatic compounds preserving heat-sensitive floral notes from jasmine and rose. Fine fragrance houses in Grasse anchor premium positioning here, though Provençal climate volatility compresses margin predictability.
- Extracts:Concentrated botanical preparations using ethanol or glycerin carriers. Clean-label skincare brands in Germany are expanding procurement of these for alcohol-free formulation compatibility.
- Resinoids:Semi-solid aromatic materials from tree exudates via solvent or CO2 processing. Incense and niche perfumery applications in southern Europe concentrate demand for these historically traded materials.
Essential oils dominate installed base. Absolutes are where expansion concentrates for premium fragrance houses seeking differentiation through gentle extraction credentials.
Application:
Cost tier separation is pronounced: mass-market personal care operates on ingredient costs below fine fragrance thresholds by an order of magnitude.
- Personal Care:Skincare and haircare formulations incorporating herbal fragrances at 0.01% to 5% concentration. EU Green Deal compliance mandates in France and Germany are pulling procurement toward certified sustainable supply chains with full field-to-flask traceability.
- Household Products:Surface cleaners, laundry formulations, and air care systems using higher-load fragrance delivery. Aromatherapy-positioned subsegments are climbing fastest as wellness marketing displaces traditional functional positioning.
- Cosmetics:Color cosmetics and beauty products requiring stable scent profiles across variable pH and temperature exposure. Reformulation pressure from REACH Annex XVII allergen restrictions is compressing timelines for natural ingredient validation.
- Aromatherapy:Therapeutic-grade essential oil applications with purity specifications exceeding conventional fragrance grades. Direct-to-consumer brands are disintermediating traditional distributor networks in this channel.
Personal care commands volume concentration. Aromatherapy is gaining share fastest through wellness-positioned brand extensions.
Formulation:
Water-soluble variants turn formulation cycles fastest; oil-soluble and powdered formats require extended stability testing protocols.
- Water-Soluble:Hydrosol-based and microemulsion systems eliminating alcohol carriers. Clean-label personal care brands in Germany specify these for skincare applications, creating formulation share gains as alcohol-free positioning hardens into category standard.
- Oil-Soluble:Lipophilic fragrance compounds compatible with anhydrous and oil-phase product matrices. Traditional perfume and aromatherapy applications still occupy majority share, though water-based substitution pressure intensifies.
- Powdered:Encapsulated or spray-dried fragrance systems for dry shampoo, powder cosmetics, and detergent applications. Extended release profiles suit applications where immediate scent burst is undesirable.
- Gelled:Thixotropic fragrance delivery systems for solid perfumes and controlled-release home care devices. Niche positioning in premium candle and diffuser formats concentrates demand.
Oil-soluble formulations dominate installed base. Water-soluble systems are where expansion concentrates as clean-label elimination of alcohol carriers accelerates.
Distribution Channel:
Customer type stratification separates bulk industrial procurement from specification-intensive direct relationships.
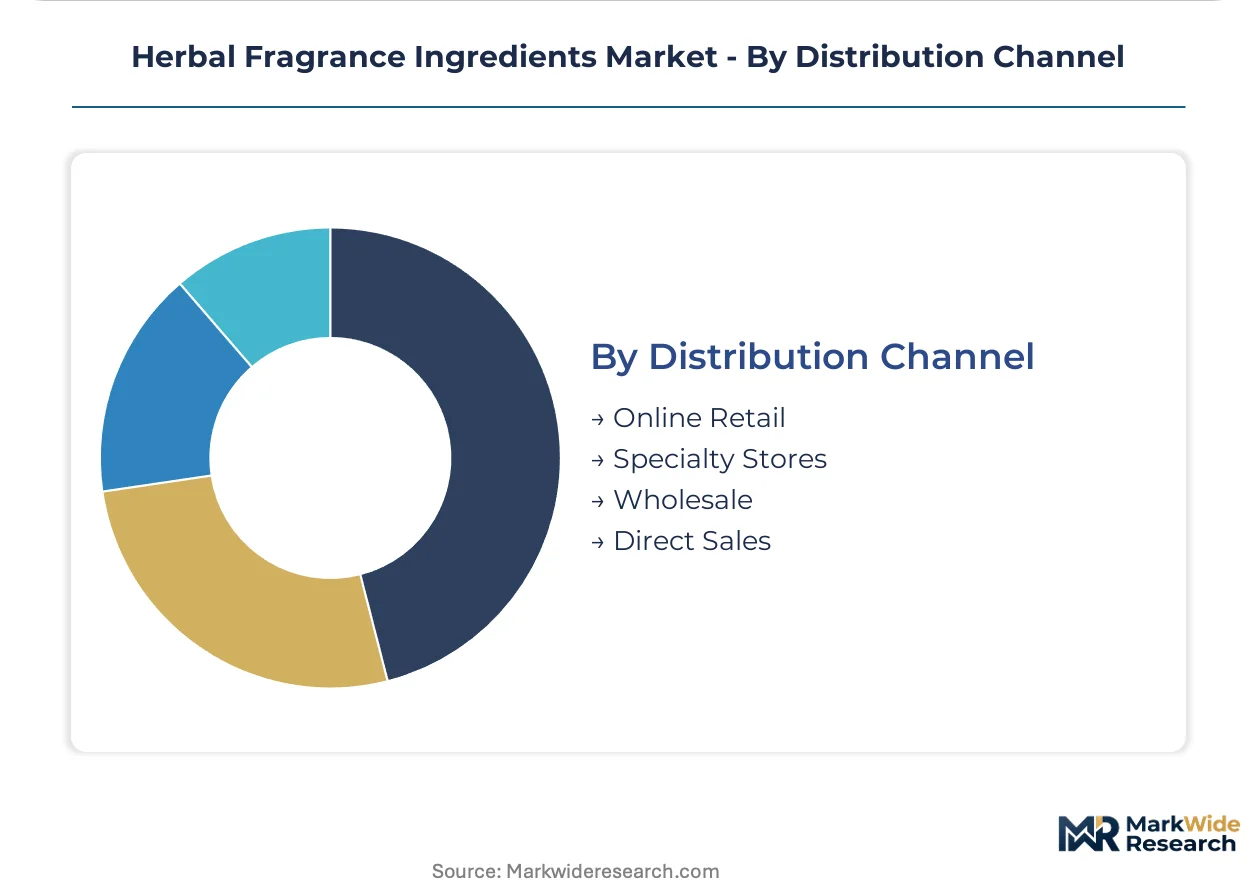
- Online Retail:E-commerce platforms serving small-batch formulators, indie beauty brands, and consumer aromatherapy markets. Minimum order quantities below wholesale thresholds democratize access to Grasse-origin materials previously locked behind distributor relationships.
- Specialty Stores:Brick-and-mortar retailers with trained staff serving hobbyist perfumers and professional aromatherapists. Tactile sampling requirements sustain physical channel relevance despite digital encroachment.
- Wholesale:Volume distributors supplying compounders, contract manufacturers, and multinational personal care houses. Traditional network structures face displacement as direct sourcing contracts between Grasse distilleries and premium brands consolidate.
- Direct Sales:Captive supply relationships with documentation packages satisfying REACH registration and EU Green Deal compliance. Fine fragrance houses in France and Germany exhibit the most pronounced channel consolidation here.
Wholesale channels dominate installed base. Direct sales are where expansion concentrates as traceability and compliance documentation become non-negotiable procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse anchors extraction expertise for high-value absolutes, while regulatory tightening across multiple jurisdictions reshapes procurement geography. Field-to-flask traceability requirements concentrate premium capacity in established distillation clusters.
France
EU Green Deal compliance mandates pull procurement toward certified sustainable supply chains. ANSM allergen labeling rules intersect with REACH Annex XVII restrictions on sensitizing botanicals. Grasse distilleries scale artisanal expertise to industrial throughput for luxury perfume houses.
Germany
Clean-label personal care brands specify alcohol-free hydrosol formulations for skincare applications. KBA-aligned chemical safety protocols reinforce ECHA disclosure standards for natural fragrance compounds. Symrise AG anchors supercritical CO2 extraction capabilities in specialized processing facilities.
United States
FDA fragrance allergen disclosure rules create compliance burdens for suppliers serving personal care markets. FEMA GRAS assessments govern flavor-crossover botanicals entering food-adjacent applications. Direct-to-consumer aromatherapy brands disintermediate traditional distributor networks.
India
CDSCO cosmetic safety guidelines and FSSAI standards create dual-track compliance for botanical extracts crossing personal care and wellness boundaries. Traditional distillation clusters in Kannauj and Kerala supply jasmine and sandalwood feedstocks. BIS quality certification requirements tighten for export-oriented processors.
China
NMPA cosmetic registration rules and GB standards for fragrance compounds extend documentation cycles for imported botanical materials. Guangdong and Zhejiang processing hubs concentrate hydrosol production for domestic skincare brands. SAMR market surveillance intensifies for natural product allergen claims.
Herbal Fragrance Ingredients Market Competitive Landscape
Vertically integrated fragrance houses and specialized extraction specialists split the market across premium and mid-tier positioning. Consolidation pressure intensifies as traceability documentation becomes non-negotiable procurement criteria. Three archetypes dominate: captive field-to-flask operators, advanced solvent-free technology licensors, and regional botanical sourcing specialists. Competitive moves center on backward integration into cultivation assets and supercritical extraction capacity expansion.
Among Swiss-anchored integrated players, Givaudan SA and Firmenich SA exemplify the captive supply archetype through controlled agricultural assets. Symrise AG represents the technology-forward tier with German-based advanced extraction infrastructure. Robertet Group occupies a specialist position emphasizing solvent-free process credentials for fine fragrance applications.
| Leading Market Players |
|---|
| Firmenich SA |
| Sensient Technologies Corporation |
| Symrise AG |
| Robertet Group |
| Takasago International Corporation |
| Givaudan SA |
| Mane SA |
| DSM-Firmenich |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
Grasse-based jasmine and lavender cultivation anchors upstream supply, concentrating margin capture with Provençal distilleries that command premium positioning for absolutes and essential oils in fine fragrance applications. REACH registration burdens and EU Green Deal compliance documentation inflate procurement costs for buyers lacking direct field relationships, widening spreads between integrated houses and distributor-dependent formulators.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across herbal fragrance ingredients, separating solvent-free absolutes certified for allergen compliance from conventional steam-distilled grades. Three-tier pricing structure across premium, standard, and economy levels reflects extraction method sophistication, field-to-flask traceability depth, and regulatory dossier completeness. Cost compression in mid-tier essential oils is intensifying because synthetic biology platforms threaten volume positioning of field-grown botanicals. Mass-market personal care brands exhibit highest price sensitivity, while fine fragrance houses prioritize terpene profile integrity over unit economics.
Supply Chain Analysis
Tariff exposure between India and European Union markets dominates supply chain risk planning for sandalwood and jasmine feedstocks crossing personal care and aromatherapy boundaries. Geographic supply concentration centers on France, India, and China, with Provençal distillation clusters, Kannauj traditional processors, and Guangdong hydrosol facilities anchoring throughput. Raw material dependencies rest on lavender harvests, jasmine flower collection, and citrus peel waste streams from juice processing. Single-region expertise concentration in Grasse creates geographic vulnerability for luxury perfume house sourcing. Distribution runs through direct sales contracts with compliance documentation packages, displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Herbal fragrance ingredients constitute a high-growth disruption as supercritical CO2 extraction technology converges with REACH Annex XVII allergen mandates, compressing viable pathways for traditional solvent-based processing and rewarding capital-intensive technology adopters.
For Market Incumbents: Entrench captive cultivation control through backward integration into Provençal lavender and jasmine fields, mirroring Givaudan SA's field-to-flask traceability model. Expand supercritical CO2 extraction capacity in Germany or southern France to preserve heat-sensitive terpene profiles as REACH restrictions intensify reformulation cycles. Defend against synthetic biology substitutes by emphasizing artisanal provenance and circular economy credentials in direct sourcing contracts with premium skincare houses. For New Entrants and Emerging Players: Pursue white-space positioning in water-soluble hydrosol formulations for German clean-label skincare brands eliminating alcohol carriers. Target aromatherapy direct-to-consumer channels where wellness marketing displaces traditional functional positioning and distributor disintermediation creates margin opportunity. Anchor go-to-market strategy through online retail platforms serving indie beauty brands with minimum order quantities below wholesale thresholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional botanical sourcing specialists in Mediterranean and Alpine ecosystems possessing proprietary compound libraries but lacking extraction technology scale. Long-term viability hinges on 5-10 year regulatory compliance moats rather than commodity feedstock positioning. Watch for inflection signals in novel botanical bioprospecting patent filings and supercritical CO2 equipment deployment announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Givaudan SA's captive lavender fields in Provence secure raw material traceability against climate volatility. |
| Supercritical CO2 Extraction Scale-Up | Symrise AG's German facilities preserve volatile terpenes for heat-sensitive floral notes in premium applications. |
| Direct Sourcing Contract Consolidation | Fine fragrance houses in France displace wholesale networks with field-to-flask documentation packages. |
| Novel Botanical Bioprospecting | Uncharacterized Mediterranean and Alpine plant sources offer proprietary compound discovery for differentiation. |
| Water-Soluble Formulation Expansion | Clean-label German skincare brands specify hydrosol systems as alcohol-free positioning hardens into standard. |
Research Methodology
Operator-level perspectives from extraction facility managers, procurement leads at premium personal care brands, regulatory affairs directors, and Grasse distillery technical directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through ECHA REACH registration databases, ANSM allergen labeling guidelines, EU Green Deal circular economy criteria, and customs trade data for botanical extract flows. Bottom-up volume modeling across ingredient type, application, and formulation segments triangulated against top-down market sizing from downstream personal care and fine fragrance consumption patterns.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning extraction method sophistication, end-use specification tier, formulation solubility profile, and channel relationship structure. CAGRs derived from installed base penetration curves, replacement demand cycles, and greenfield capacity announcements. Forecast inputs incorporated Provençal climate yield variability, REACH Annex XVII restriction expansion timelines, and supercritical CO2 technology adoption rates.
Sensitivities concentrate around synthetic biology platform maturation, EU Green Deal compliance deadline acceleration, and single-region supply concentration in Grasse. Forecasts reflect documented assumptions on regulatory enforcement intensity and clean-label brand commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
Anisole Market