
 Asia-Pacific Aroma Chemicals Market | 2026-2036
Asia-Pacific Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aroma Chemicals Market Analysis
Direct sales channels between aroma chemical producers and fragrance houses is tilting toward tighter technical partnerships and co-development agreements. BASF SE leverages its integrated petrochemical feedstock position to secure cost advantages in synthetic aroma molecule production across the region. S H Kelkar and Company Limited anchors its competitive stance through deep specialization in natural isolates and traditional Indian fragrance raw materials. Privi Speciality Chemicals Limited competes by sustaining backward integration into key terpene intermediates, reducing exposure to volatile import costs.
Aroma chemicals constitute purified organic compounds—alcohols, aldehydes, esters, ketones, and terpenoids—synthesized or extracted for olfactory functionality, typically specified by purity thresholds above 95 percent and defined boiling-point ranges to ensure batch consistency in fragrance formulation. Synthetic products dominate volume throughput due to cost scalability and reproducibility, while bio-based alternatives attract premium positioning as cosmetic and food brands reformulate to meet clean-label expectations. Fragrance manufacturing commands the largest application share, though food flavoring applications are gaining structural importance as processed-food consumption rises across Southeast Asian markets.
China's SAMR enforces GB standards for chemical purity and labeling that directly shape import requirements and domestic manufacturing specifications for aroma chemicals sold into food and cosmetic applications. India's BIS mandates certification for fragrance ingredients used in consumer products, creating compliance barriers that favor established suppliers with testing infrastructure. Japan's METI oversees chemical substance control under its industrial safety framework, influencing product registration timelines for new molecular entities. Stakeholders must monitor evolving bio-based certification schemes and regional chemical inventory updates to preempt supply disruptions and secure preferred supplier status with multinational fragrance houses.
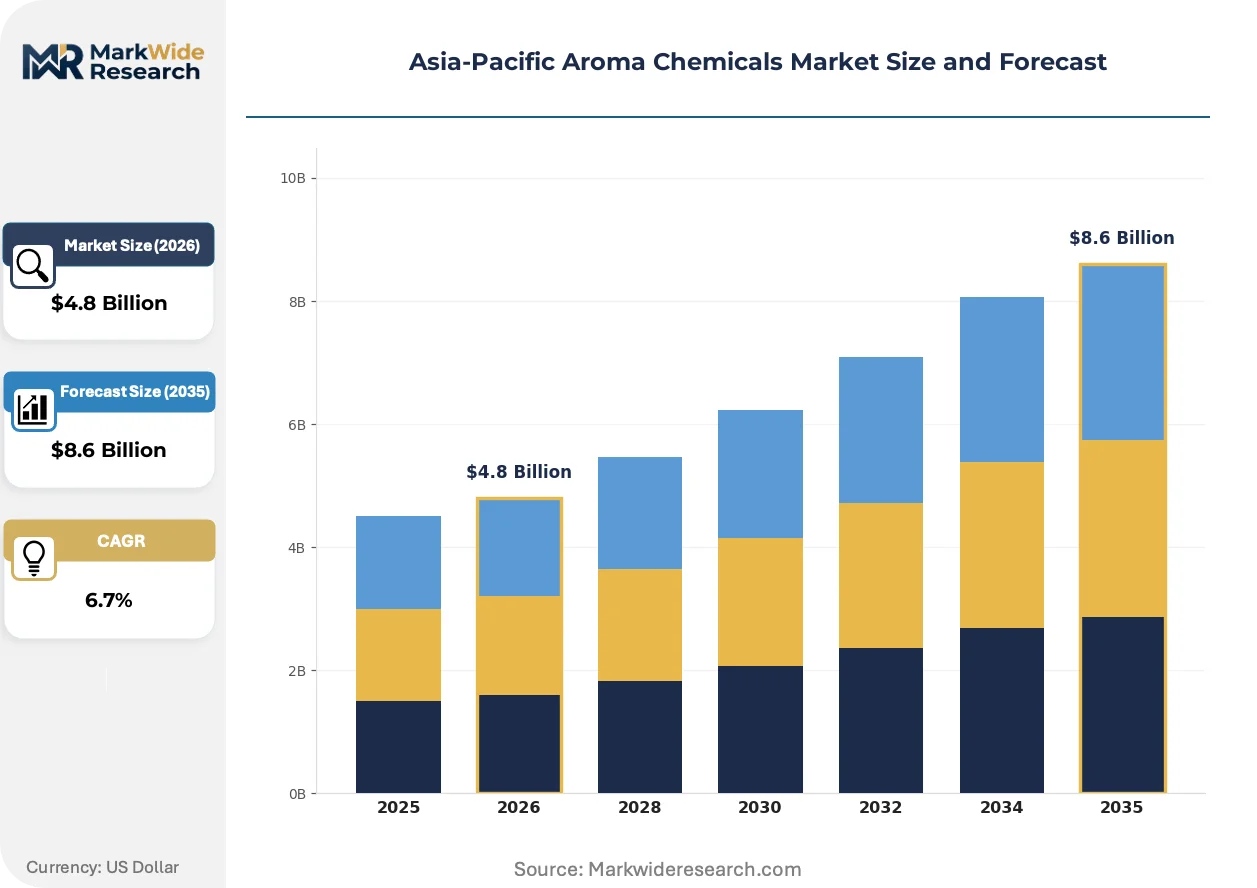
Market Dynamics
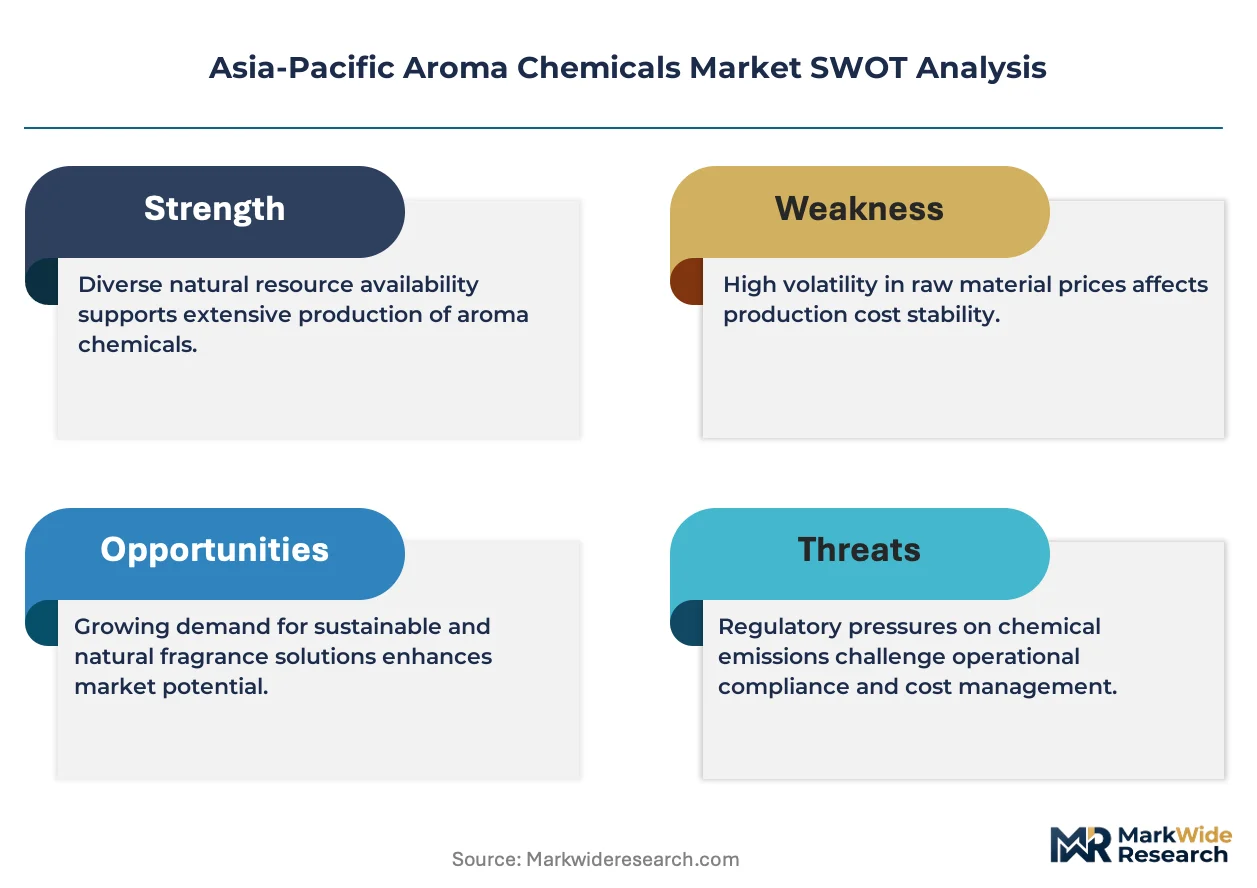
Fragmentation between synthetic petrochemical routes and bio-based fermentation pathways is creating divergent cost structures across the Asia-Pacific aroma chemicals value chain, forcing mid-scale producers to choose specialization over scale.
Growth Catalysts
- GB Standards Harmonization:China's SAMR is consolidating food-grade aroma chemical purity requirements, reducing testing redundancy for exporters and accelerating cross-border batch approvals.
- Fragrance House Consolidation:Southeast Asian personal care brands are consolidating supplier bases, creating volume commitments that justify dedicated production lines for regional aroma chemical manufacturers.
- Terpene Biotechnology:Microbial fermentation of limonene and pinene derivatives is achieving cost parity with citrus extraction in Indian and Thai production facilities.
Market Restraints
- Crude-Derived Feedstock Volatility:Benzene and xylene price swings from Middle Eastern supply disruptions transmit directly into synthetic aroma alcohol cost structures.
- BIS Certification Backlogs:India's fragrance ingredient testing queue now exceeds fourteen months, freezing new product introductions for unestablished suppliers.
- Natural Isolate Substitution:Food brands are reformulating away from vanillin toward maltol and ethyl maltol in cost-sensitive applications, compressing demand for traditional extraction-based products.
Strategic Opportunities
- Vietnamese Production Base:Underdeveloped domestic aroma chemical capacity creates first-mover advantage for fermentation-based terpene producers establishing coastal manufacturing.
- Clean-Label Certification Premiums:EU Green Deal-aligned bio-based verification schemes are unlocking price premiums of fifteen to twenty-five percent for compliant Asian exporters.
- Direct-to-Fragrance-House Digital Platforms:Blockchain-traceable batch documentation is enabling bypass of traditional distributor markups for qualified synthetic molecule suppliers.
Industry Challenges
- Specialized Fermentation Talent Scarcity:Industrial microbiology expertise for terpene pathway engineering concentrates in Shanghai and Bangalore, creating recruitment bottlenecks for second-tier production hubs.
- Legacy GC-MS Infrastructure:Smaller Indian and Indonesian producers face seven-figure capital requirements to upgrade purity verification equipment for METI-level import specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aroma Chemicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Bio-based, Aroma Chemicals Blends Application: Fragrance Manufacturing, Food Flavoring, Cosmetic Products, Household Products End User: Food Industry, Personal Care, Household Care, Pharmaceuticals Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | BASF SE, S H Kelkar and Company Limited, International Flavors & Fragrances Inc, Privi Speciality Chemicals Limited, Kao Corporation, Givaudan, Takasago International Corporation, Symrise AG, Firmenich, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aroma Chemicals Market Emerging Trajectories
Biotechnology and digital traceability systems are converging to redefine how aroma chemicals are manufactured, certified, and procured across Asia-Pacific value chains.
Continuous flow chemistry for high-value synthetic molecules is rendering obsolete traditional batch reactor operations in Japanese and South Korean fine chemical plants. Fragrance houses in Osaka and Seoul are adopting these systems for lilial and lyral production, achieving yield improvements that compress payback periods below four years.
China's GB standards for chemical substance notification are tightening disclosure requirements for aroma molecules used in food contact applications. SAMR now mandates full supply chain documentation for synthetic musks and polycyclic compounds, forcing reformulation in seasoning and beverage flavoring segments and accelerating migration toward fully characterized molecular structures.
Beauty and personal care brands are consolidating fragrance ingredient suppliers from an average of twelve to four per product line, privileging aroma chemical producers with integrated regulatory dossier management. This concentration is most visible in Thailand and Indonesia, where direct technical partnerships are displacing spot-market purchasing for base note materials.
Asia-Pacific Aroma Chemicals Market Segmentation
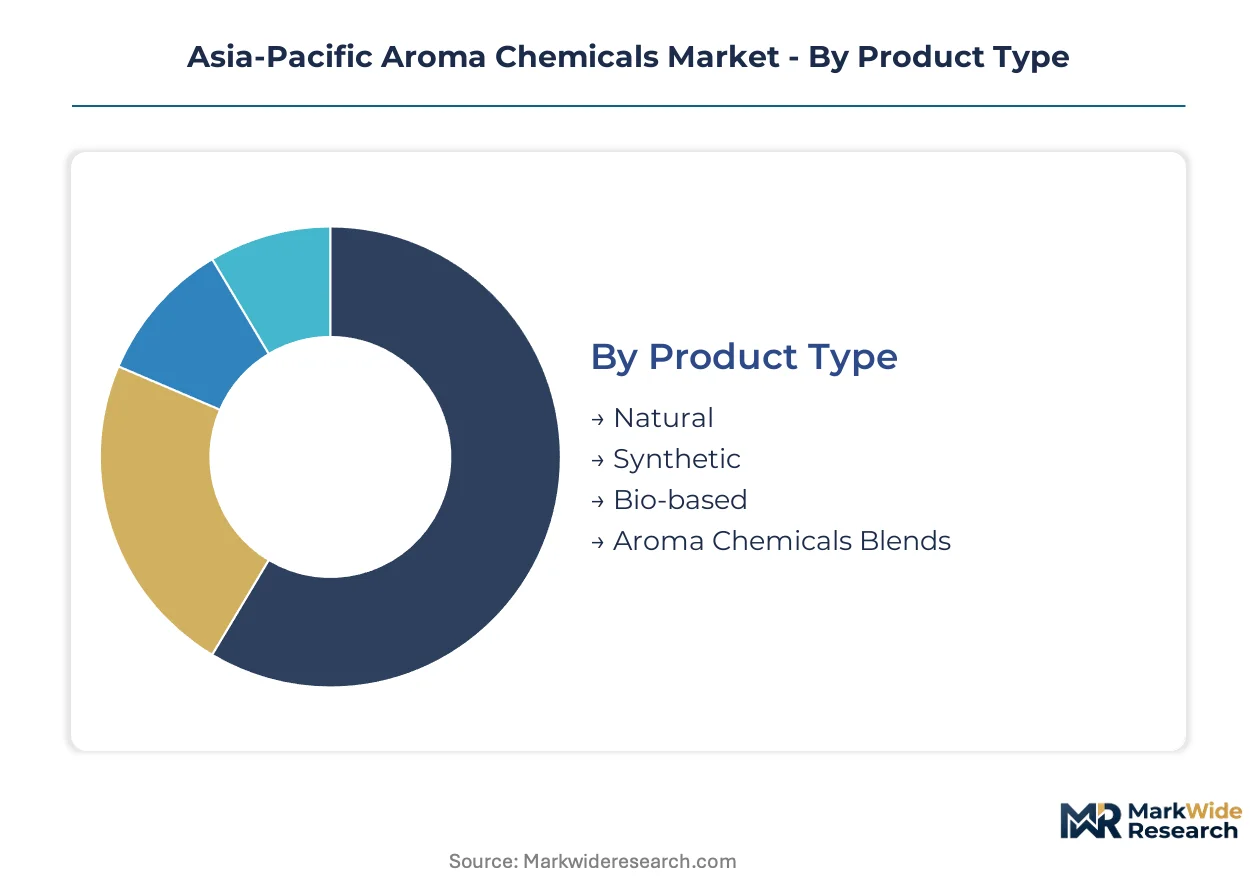
Aroma chemicals serve distinct functional requirements across fragrance compounding, food formulation, and industrial applications. Product origin and application specifications determine compliance pathways, cost structures, and supplier qualification criteria throughout Asia-Pacific procurement networks.
Product Type:
Application requirements span from cost-sensitive bulk fragrance bases to premium-positioned clean-label formulations, creating divergent specification tiers.
- Synthetic:Petrochemical-derived molecules achieve reproducible purity above 95 percent with defined boiling-point ranges. Fragrance houses in China and Japan rely on synthetic alcohols, aldehydes, and ketones for consistent batch performance in high-volume personal care lines.
- Natural:Isolates extracted from botanical sources—vanillin from clove or benzoin, limonene from citrus—command premium positioning. Indian and Thai producers concentrate natural isolate supply for traditional attar formulations and export to EU clean-label cosmetic brands.
- Bio-based:Microbial fermentation produces terpenoid structures with renewable feedstock credentials. Fermentation facilities in Shanghai and Bangalore scale limonene and pinene derivatives for brands targeting EU Green Deal-aligned verification schemes.
- Aroma Chemicals Blends:Pre-formulated accords reduce compounding complexity for mid-scale fragrance houses. Blended bases accelerate product development timelines for Southeast Asian personal care manufacturers with limited in-house formulation capabilities.
Established volume favors synthetic molecules; emerging adoption favors bio-based alternatives.
Application:
End-use concentration determines purity thresholds, regulatory filing requirements, and technical partnership intensity across the value chain.
- Fragrance Manufacturing:Base, heart, and top note materials require precise odor intensity and stability specifications. Personal care brands across Indonesia and Thailand consolidate supplier bases to four per product line, privileging producers with integrated regulatory dossier management.
- Food Flavoring:GB standards for chemical substance notification mandate full supply chain documentation for molecules used in food contact applications. Beverage and seasoning segments in China accelerate migration toward fully characterized synthetic structures.
- Cosmetic Products:Skin-safe certification under BIS and METI frameworks shapes ingredient selection for color cosmetics and skincare. Japanese and South Korean cosmetic manufacturers drive demand for high-purity synthetic musks with documented safety profiles.
- Household Products:Cost-optimized formulations for detergents and air fresheners prioritize volume-scale supply security. India's household care sector sources bulk terpene derivatives through distributor networks serving regional formulators.
Fragrance manufacturing captures the dominant revenue share; food flavoring applications are expanding most quickly as processed-food consumption rises across Southeast Asian markets.
End User:
Customer scale and technical sophistication determine procurement channel preferences and contract structuring.
- Food Industry:Processed-food manufacturers in Vietnam and the Philippines specify food-grade aroma chemicals with FSSAI-aligned import documentation. Flavor houses serving instant noodle and beverage segments demand consistent lot-to-lot quality for high-speed production lines.
- Personal Care:Beauty brands reformulate to reduce ingredient counts while maintaining sensory performance. Direct technical partnerships between aroma chemical producers and fragrance houses displace spot-market purchasing for base note materials in Thailand and Indonesia.
- Household Care:Detergent and cleaning product manufacturers prioritize cost-competitive supply with regional logistics coverage. India's BIS certification requirements for fragrance ingredients create compliance barriers favoring established suppliers with testing infrastructure.
- Pharmaceuticals:Excipient-grade aroma chemicals require GMP-aligned manufacturing and documented impurity profiles. Pharmaceutical applications represent a niche but high-margin segment with extended qualification timelines.
Personal care commands the steepest expansion trajectory; household care maintains the largest volume base.
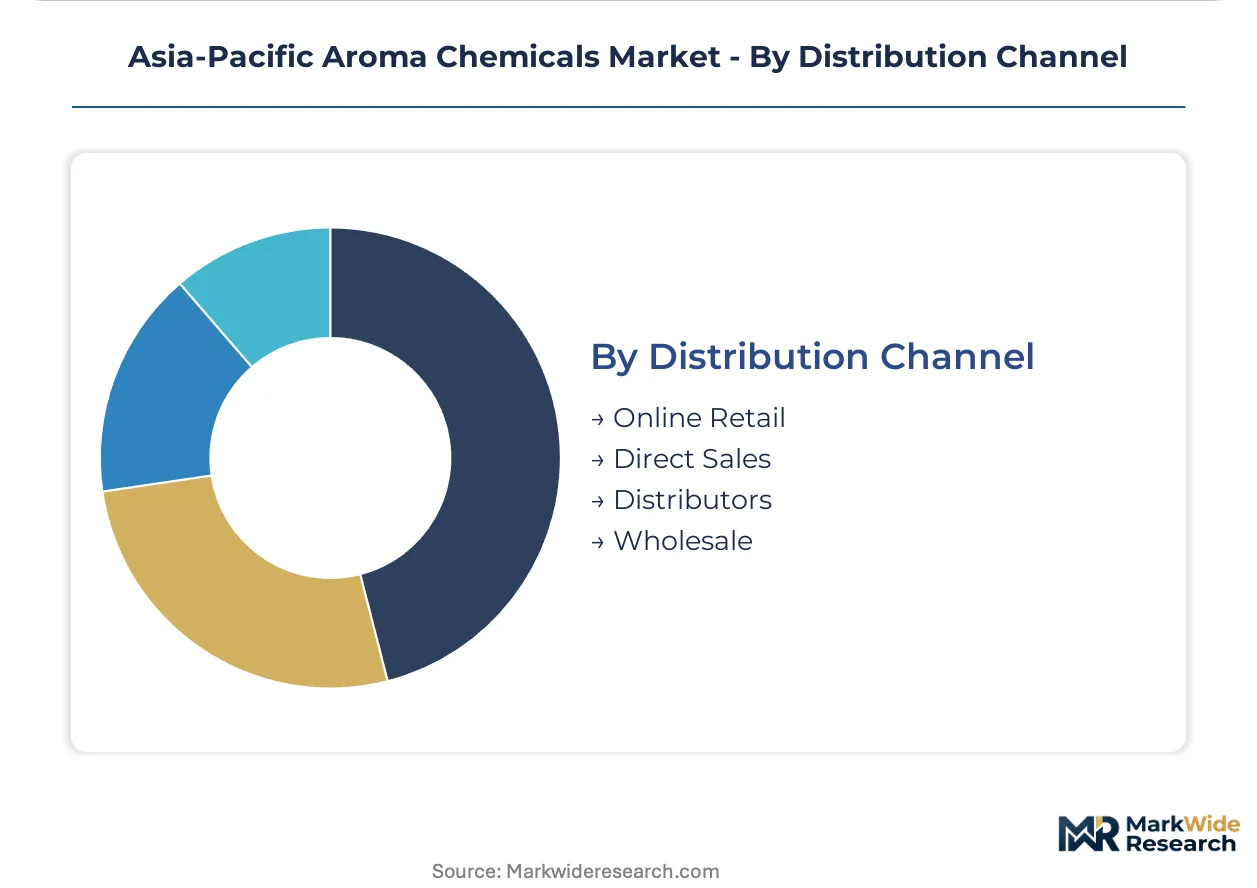
Distribution Channel:
Channel selection reflects customer technical capability, order scale, and documentation requirements.
- Direct Sales:Fragrance houses and multinational personal care brands negotiate co-development agreements with integrated producers. BASF SE leverages direct channels to secure technical partnerships across the region.
- Distributors:Regional chemical distributors serve mid-scale formulators with fragmented product requirements. Distributor networks dominate supply to Indonesian and Vietnamese manufacturers lacking dedicated procurement teams.
- Online Retail:Digital platforms enable small-batch sourcing for independent perfumers and cosmetic startups. Blockchain-traceable batch documentation is emerging for qualified synthetic molecule suppliers.
- Wholesale:Bulk terpene intermediates and standard-grade synthetics move through wholesale channels serving compounders. Wholesale volumes concentrate in China and India with established port infrastructure.
Direct sales deepen technical integration; distributor channels retain cost efficiency for fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China and Japan while India and Southeast Asian suppliers absorb margin compression from feedstock volatility and certification backlogs. The divergence reflects divergent regulatory infrastructure maturity and downstream customer consolidation patterns.
China
Personal care brands in Shanghai and Guangzhou drive demand for high-purity synthetic musks and polycyclic compounds. SAMR's GB standards for chemical substance notification mandate full supply chain documentation, accelerating migration toward fully characterized molecular structures. Yangtze River Delta fermentation facilities scale limonene and pinene derivatives for export markets.
India
Traditional attar formulations and natural isolates from clove and benzoin sustain premium export positioning to EU cosmetic brands. BIS certification requirements for fragrance ingredients create fourteen-month testing queues that freeze new product introductions for unestablished suppliers. Maharashtra-based producers concentrate natural isolate supply for traditional fragrance raw materials.
Japan
Osaka and Seoul fragrance houses adopt continuous flow chemistry systems for lilial and lyral production, achieving yield improvements that compress payback periods below four years. METI oversees chemical substance control under industrial safety frameworks, influencing product registration timelines for new molecular entities. Kanto region manufacturers drive demand for skin-safe certification under METI frameworks.
Indonesia
Personal care brands consolidate supplier bases from twelve to four per product line, privileging producers with integrated regulatory dossier management. Direct technical partnerships displace spot-market purchasing for base note materials in Jakarta and Surabaya manufacturing corridors. Processed-food consumption rises across instant noodle and beverage segments, expanding food flavoring applications.
Vietnam
Underdeveloped domestic aroma chemical capacity creates first-mover advantage for fermentation-based terpene producers establishing coastal manufacturing. FSSAI-aligned import documentation requirements shape food-grade aroma chemical specifications for processed-food manufacturers. Ho Chi Minh City and Hanoi corridors attract regional distributor networks serving fragmented formulator demand.
Asia-Pacific Aroma Chemicals Market Vendor Landscape
Integrated petrochemical conglomerates and specialized natural isolate producers split the market along feedstock-origin lines. The structure tilts toward technical partnership intensity rather than pure price competition, with fragrance houses consolidating supplier relationships into co-development agreements. Three archetypes dominate: global chemical majors with captive feedstock positions, regional specialists in traditional extraction methods, and biotechnology-anchored fermentation scale-ups. Competitive moves concentrate on backward integration into terpene intermediates and regulatory dossier co-development with downstream fragrance houses.
Within the integrated chemical major tier, BASF SE exemplifies the petrochemical-feedstock advantage model. Among India-based specialists, S H Kelkar and Company Limited occupies a position representing deep specialization in natural isolates. At the fermentation-technology end, Privi Speciality Chemicals Limited anchors the backward-integration archetype through captive terpene intermediate production. These three patterns illustrate how geographic feedstock access and regulatory infrastructure investment determine sustainable positioning across diverging cost structures.
| Leading Market Players |
|---|
| BASF SE |
| S H Kelkar and Company Limited |
| International Flavors & Fragrances Inc |
| Privi Speciality Chemicals Limited |
| Kao Corporation |
| Givaudan |
| Takasago International Corporation |
| Symrise AG |
| Firmenich |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta fermentation clusters anchor regional supply capacity, transmitting their scale advantages into pricing power for bio-based terpenoid producers while synthetic molecule manufacturers in Japan and South Korea absorb margin compression from benzene feedstock volatility.
Pricing Analysis
Configured-to-order pricing for custom fragrance accords commands fifteen to twenty-five percent premiums over standard-grade synthetic molecules, with price differentiation resting on certification tier and volume scale. Pricing pressure stems from crude-derived feedstock volatility transmitting directly into synthetic aroma alcohol cost structures. Small-scale Indonesian and Vietnamese formulators exhibit highest price sensitivity, while Japanese cosmetic manufacturers prioritize purity grades over unit economics.
Supply Chain Analysis
Contract manufacturing concentration for high-purity synthetic musks sits with Japanese and South Korean fine chemical plants adopting continuous flow chemistry systems. Geographic supply concentrates in China, India, and Japan, with raw material dependencies drawing from Middle Eastern benzene and xylene streams and Southeast Asian citrus terpene extractions. Single-source vulnerability around specialized fermentation talent in Shanghai and Bangalore creates recruitment bottlenecks. Distribution runs through direct technical partnerships for multinational fragrance houses and regional distributor networks for fragmented Southeast Asian formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiology expertise for terpene pathway engineering concentrates in Shanghai and Bangalore, leaving second-tier production hubs in Jakarta and Ho Chi Minh City structurally short of qualified fermentation talent.
For Market Incumbents: Harden regulatory dossier capabilities against BIS certification backlogs exceeding fourteen months by investing in captive testing infrastructure. Deepen backward integration into limonene and pinene intermediates to reduce exposure to volatile import costs. Consolidate supplier relationships with Southeast Asian personal care brands from twelve to four per product line before emerging biotechnology scale-ups capture technical partnership slots.
For New Entrants and Emerging Players: Vietnamese coastal manufacturing corridors represent the most penetrable entry point, where underdeveloped domestic aroma chemical capacity creates first-mover advantage for fermentation-based terpene producers. Blockchain-traceable batch documentation for qualified synthetic molecules enables bypass of traditional distributor markups. Direct-to-fragrance-house digital platforms unlock procurement channel disruption.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-anchored fermentation scale-ups with captive terpene intermediate production over legacy extraction-based specialists facing natural isolate substitution pressure. Long-term viability across the analysis window hinges on EU Green Deal-aligned bio-based verification scheme adoption rates. Monitor BIS certification queue clearance velocities as inflection indicator for Indian market access conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terpene Intermediates | Captive supply of limonene and pinene derivatives insulates margins from citrus extraction volatility. |
| Continuous Flow Chemistry Adoption | Osaka and Seoul plants achieve yield improvements that compress payback periods for lilial and lyral production. |
| BIS Certification Infrastructure Investment | Dedicated testing capabilities bypass fourteen-month queues freezing competitor product introductions. |
| EU Green Deal Verification Alignment | Bio-based certification unlocks fifteen to twenty-five percent price premiums for compliant Asian exporters. |
| Direct Technical Partnership Consolidation | Fragrance houses reducing supplier bases from twelve to four per product line privilege integrated dossier managers. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant managers at fermentation facilities, procurement leads at fragrance houses, distribution channel partners, and technical R&D directors; and secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR GB standards documentation. Bottom-up capacity assessments triangulated against top-down demand modeling from personal care and processed-food consumption trends.
Forecast inputs span synthetic versus bio-based production cost curves, regulatory filing velocity under BIS and METI frameworks, and fragrance house consolidation patterns across the projection horizon. Segmentation dimensions modeled include product origin tier, end-use application concentration, and regional production hub clustering. CAGRs derived from volume-weighted average growth across purity grades and application segments, with specific incorporation of GB standards harmonization timelines and terpene biotechnology cost parity achievement curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, Middle Eastern benzene supply disruptions, or EU bio-based certification scheme adoption rates would shift the trajectory. Forecasts reflect documented assumptions around regulatory queue clearance and fermentation scale-up velocities. Quarterly review of BIS certification backlogs, SAMR disclosure requirement updates, and fragrance house supplier consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market