
 US Institutional Cleaning Ingredients Market | 2026-2036
US Institutional Cleaning Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
US Institutional Cleaning Ingredients Market Analysis
Market Context
Premium enzymatic and peroxide-based formulations is rebalancing away from commodity bleach and quaternary ammonium compounds as end-users prioritize efficacy against resistant pathogens and surface compatibility. Stepan Company leverages its integrated surfactant manufacturing to anchor supply security for institutional formulators across North America. BASF SE competes through specialized amphoteric and non-ionic chemistries that sustain higher margins in healthcare and foodservice channels.
Technical Definition and Segment Structure
US institutional cleaning ingredients comprise surfactants, solvents, chelating agents, biocides, and builders blended at concentrations typically between five and twenty percent active content to achieve soil removal, microbial kill, or surface restoration in non-residential environments. Detergents dominate volume consumption across hospitality and commercial facilities, while enzymatic cleaners represent the fastest-expanding product type as cold-water cleaning protocols reduce energy costs. Liquid formulations capture the majority of value given their compatibility with automated dilution systems, though powder concentrates retain share in floor care applications where shipping economics favor reduced water content.
Regulatory Framework and Outlook
EPA registration requirements under FIFRA govern disinfectant efficacy claims and label compliance, while OSHA's Hazard Communication Standard mandates SDS transparency for worker chemical exposure in janitorial operations. State-level regulations, including California's Proposition 65 and the Safer Consumer Products program, restrict specific solvent and fragrance chemistries, compelling reformulation investments. Buyers and suppliers must monitor evolving PFAS restrictions at the federal and state level, as pending EPA action under TSCA Section 6 could eliminate fluorinated surfactants from multiple application categories without fully validated replacements.
Market Dynamics
EPA Safer Choice certification mandates are compressing formulation timelines for institutional cleaning ingredient suppliers, forcing accelerated transitions from petroleum-derived surfactants to bio-based alternatives before state-level green purchasing deadlines in California and New York take full effect.
Growth Catalysts
- Healthcare infection control protocols:Hospital-grade disinfectant procurement is intensifying across acute care networks as multidrug-resistant organism surveillance expands. Formulators are scaling peroxide and enzymatic active production to meet these specifications.
- California Safer Consumer Products program:State-level regulatory pressure is compelling reformulation investments that create first-mover advantages for compliant suppliers. Early certification unlocks preferred vendor status with municipal purchasers.
- Sun Belt commercial construction:Southeast population migration is generating new facility services contracts. Janitorial supply distributors are expanding warehousing capacity in Florida, Texas, and Georgia to capture this demand concentration.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and linear alkylbenzene price swings compress surfactant producer margins. Integrated manufacturers with captive oleochemical supply chains hold structural cost advantages over merchant purchasers.
- EPA FIFRA registration timelines:Disinfectant efficacy claim approvals require 12-18 month review cycles. New active ingredient entrants face capital lockup during regulatory limbo without revenue generation.
- PFAS substitution uncertainty:Pending TSCA Section 6 restrictions threaten fluorinated surfactant elimination before fully validated replacements achieve performance parity in floor finish and grease-resistant applications.
Strategic Opportunities
- Cold-water enzymatic protocols:Hospitality and commercial laundries are adopting low-temperature cleaning to reduce natural gas consumption. Enzyme suppliers can embed energy savings guarantees into performance contracts.
- Automated dilution system integration:Internet-connected dispensing hardware creates recurring chemical subscription revenue streams. Equipment-chemistry bundling locks out commodity competitors from large facility accounts.
- Federal green purchasing mandates:Executive Order 14057 directs federal agencies toward biobased products. USDA BioPreferred certification opens procurement pathways into government facilities management contracts.
Industry Challenges
- Formulation chemist talent scarcity:Green chemistry expertise sits concentrated among specialists trained after 2015. Legacy compounders struggle to hire professionals fluent in both microbial efficacy testing and lifecycle assessment protocols.
- Legacy equipment incompatibility:Concentrated enzymatic and peroxide formulations corrode traditional steel dispensing infrastructure. Facility managers face capex burdens to upgrade to stainless or polymer-compatible hardware.
- Multi-jurisdiction label compliance:California Proposition 65 warning requirements diverge from federal OSHA Hazard Communication Standard formats. National formulators maintain parallel SKU inventories to satisfy conflicting state mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Institutional Cleaning Ingredients Market |
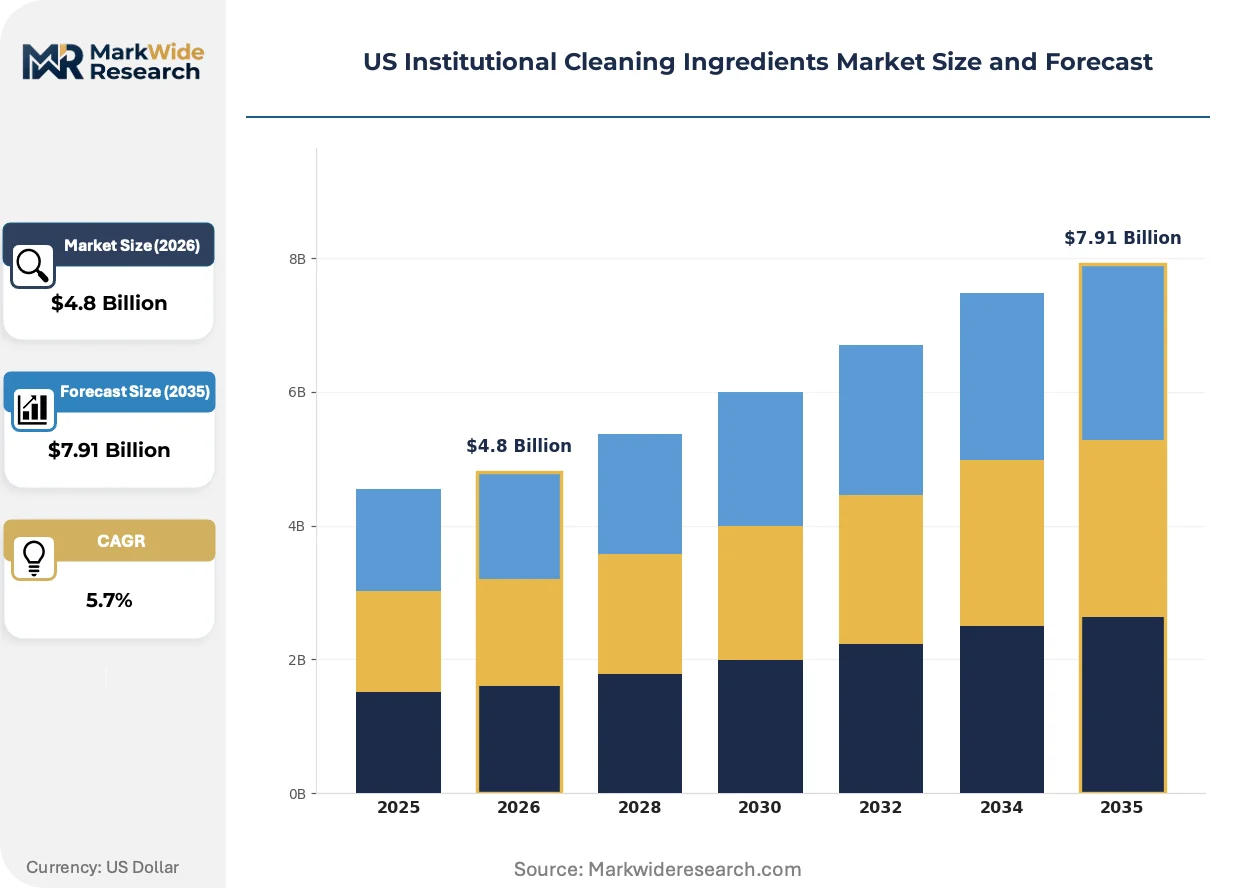
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Disinfectants, Degreasers, Enzymatic Cleaners End User: Hospitality, Healthcare, Education, Commercial Facilities Formulation: Liquid, Powder, Foam, Wipes Application: Surface Cleaning, Floor Care, Equipment Sanitization, Restroom Maintenance |
| Companies Covered | Stepan Company, BASF SE, Dow Inc., Evonik Industries AG, Solvay, Croda International Plc, Ashland Global Holdings Inc., Clariant AG, Pilot Chemical Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Institutional Cleaning Ingredients Market Emerging Trajectories
Bio-based surfactant manufacturing is displacing conventional petrochemical routes as renewable feedstock fermentation achieves cost parity. Formulation science now prioritizes cold-water efficacy and surface compatibility over raw sterilization power.
Enzymatic cleaning chemistry is converging with peroxide-based disinfection in single-step hybrid formulations. Healthcare environmental services departments are piloting these combinations to reduce labor cycles between cleaning and terminal disinfection. This convergence is compressing SKU counts for distributors while raising technical barriers for commodity bleach suppliers.
EPA Safer Choice and USDA BioPreferred label requirements are tightening permissible solvent and fragrance chemistries. Institutional purchasers now require third-party certification documentation before contract award, displacing self-declared green claims. Foodservice and hospitality segments exhibit the fastest certification-driven supplier switching as corporate sustainability reporting mandates reach operating units.
Facility management procurement departments are consolidating chemical spend under national purchasing agreements with integrated service providers. Regional janitorial distributors are losing direct supplier relationships as third-party facility management firms centralize specification authority. This concentration is most visible in healthcare systems and multinational hospitality chains with standardized property portfolios across multiple states.
US Institutional Cleaning Ingredients Market Segmentation
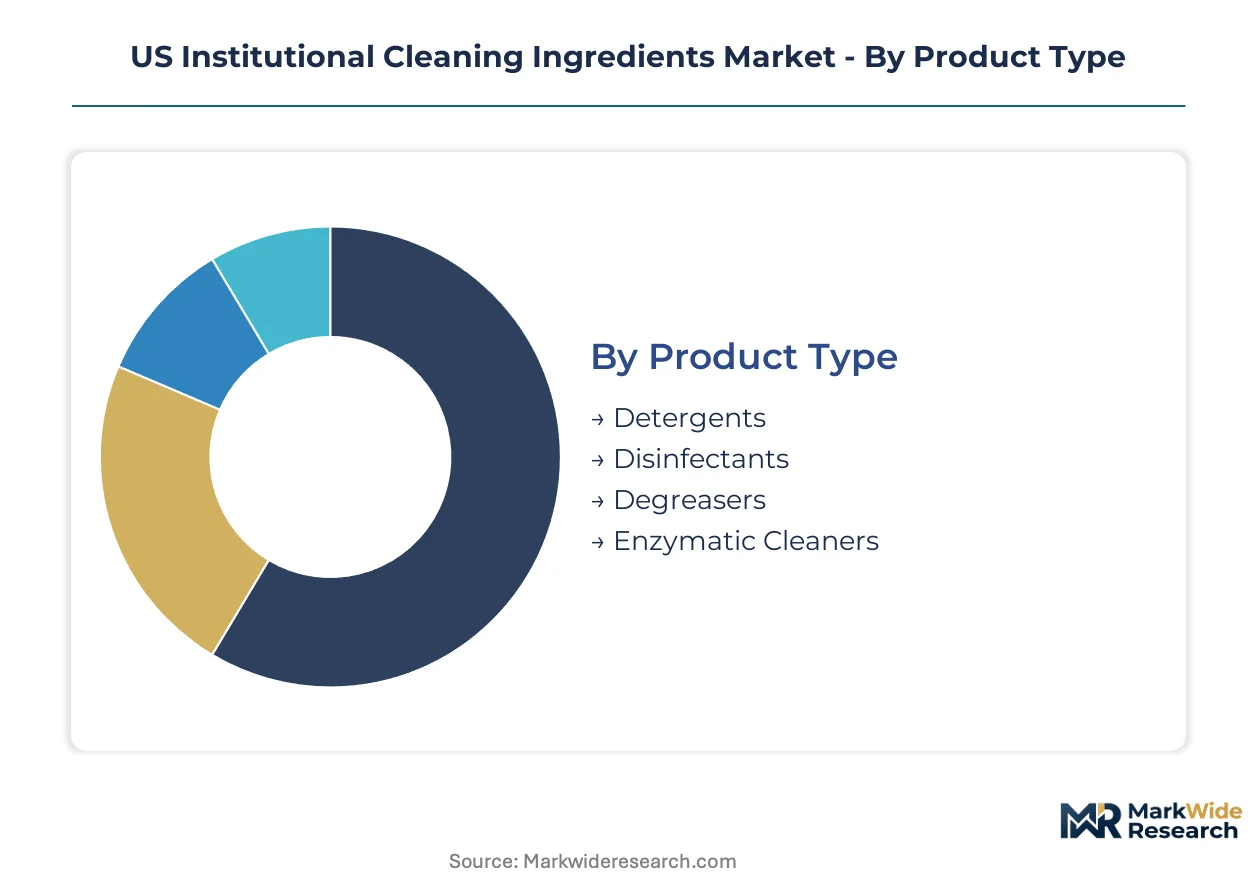
Segmentation in the US institutional cleaning ingredients market reveals how procurement priorities diverge across facility types and operational constraints. Buyers select formulations based on infection control mandates, labor automation compatibility, and state-level chemical restrictions rather than commodity pricing alone.
Product Type:
Cost tiers separate commodity purchasers from facilities willing to pay premium pricing for validated efficacy claims.
- Detergents:Surfactant blends at 5-20% active content handle routine soil removal across hospitality and commercial facilities. Southeast janitorial distributors stock concentrated variants to serve Sun Belt construction expansion where new facility contracts demand bulk supply security.
- Disinfectants:Hospital-grade formulations containing peroxides or quaternary ammonium compounds require EPA FIFRA registration for efficacy claims. Acute care networks in California and New York are expanding procurement as multidrug-resistant organism surveillance tightens infection control protocols.
- Degreasers:Heavy-duty solvent-based cleaners target foodservice equipment and industrial kitchen hood systems.
- Enzymatic Cleaners:Protein-targeting formulations enable cold-water cleaning protocols that reduce natural gas consumption in commercial laundries.
Volume sits with detergents; growth tilts toward enzymatic cleaners.
End User:
Application environments dictate chemical specification stringency and certification requirements.
- Hospitality:Hotels and resorts prioritize surface compatibility and rapid turnover protocols. Corporate sustainability mandates are accelerating EPA Safer Choice certification requirements for housekeeping chemical procurement.
- Healthcare:Acute care hospitals and long-term care facilities operate under CDC infection control guidelines. Terminal disinfection protocols consume hospital-grade disinfectants at volumes exceeding other institutional segments by order of magnitude.
- Education:K-12 districts and university facilities balance budget constraints with student safety regulations.
- Commercial Facilities:Office buildings and retail spaces favor automated dilution compatibility over maximum efficacy.
Procurement concentrates in healthcare; fastest expansion occurs in hospitality.
Formulation:
Physical state determines shipping economics, dilution infrastructure, and shelf stability requirements.
- Liquid:Pump-dispensed concentrates dominate automated dilution system installations. Compatibility with internet-connected dispensing hardware creates recurring subscription revenue opportunities for integrated service providers.
- Powder:Reduced water content favors floor care applications where shipping distances exceed 500 miles. Concentrated alkaline builders retain share in industrial scrubber operations.
- Foam:Cling properties extend contact time on vertical surfaces and restroom fixtures.
- Wipes:Pre-saturated substrates eliminate dilution error risks in high-turnover environments.
Liquids capture value share; powder formats defend volume in freight-sensitive segments.
Application:
Surface material compatibility and soil type define active ingredient selection and concentration thresholds.
- Surface Cleaning:General-purpose formulations balance efficacy across glass, stainless steel, and polymer substrates. California Proposition 65 restrictions on specific solvents are forcing reformulation investments for multi-surface products.
- Floor Care:High-pH strippers and polymer-compatible finishes require specialized surfactant packages. Pending EPA TSCA Section 6 restrictions threaten fluorinated surfactant elimination before validated replacements achieve performance parity.
- Equipment Sanitization:Food-contact surface approvals from the FDA govern active ingredient selection in commercial kitchens.
- Restroom Maintenance:Acidic bowl cleaners and enzymatic urinal treatments target biological soil degradation.
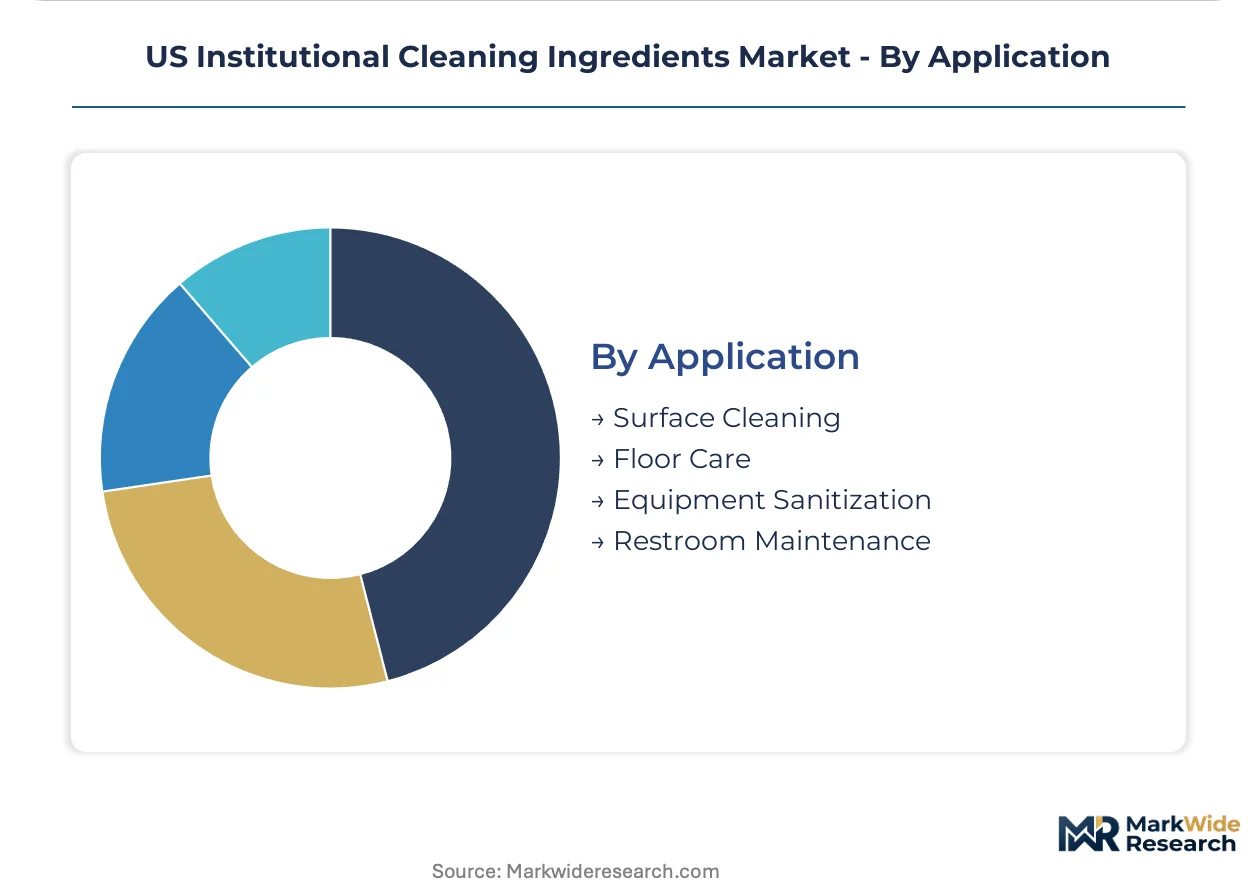
Surface cleaning generates baseline volume; equipment sanitization commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta anchors procurement activity for institutional cleaning ingredients across the Southeast, where Sun Belt population migration generates new facility services contracts and janitorial supply distributors expand warehousing capacity.
Southeast
Florida, Georgia, and Texas absorb the majority of new commercial construction starts. State procurement offices in Georgia prioritize EPA Safer Choice certification for public facility contracts. Atlanta-based distributors are consolidating chemical spend under national purchasing agreements with integrated service providers.
California
Healthcare networks in Los Angeles and San Francisco expand hospital-grade disinfectant procurement as multidrug-resistant organism surveillance tightens. The state's Safer Consumer Products program restricts specific solvent chemistries under Proposition 65. Formulators in the Bay Area accelerate bio-based surfactant transitions to meet green purchasing mandates.
New York
Acute care hospitals in New York City consume terminal disinfection volumes exceeding other metropolitan areas. State-level green purchasing mandates mirror California's regulatory pressure. Buffalo and Rochester manufacturing clusters supply concentrated alkaline builders for industrial floor care applications.
Midwest
Chicago and Detroit facility management firms balance budget constraints with automated dilution system compatibility. OSHA Hazard Communication Standard enforcement drives SDS transparency investments across Illinois and Ohio. Cleveland-area compounders serve foodservice equipment sanitization demand from regional commercial kitchen networks.
Pacific Northwest
Seattle and Portland hospitality chains accelerate EPA Safer Choice certification requirements for housekeeping chemical procurement. Corporate sustainability reporting mandates reach operating units in Washington and Oregon. Regional distributors lose direct supplier relationships as third-party facility management firms centralize specification authority.
US Institutional Cleaning Ingredients Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and formulation complexity, with integrated surfactant manufacturers holding structural cost advantages over merchant purchasers. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive oleochemical supply chains, specialized amphoteric and non-ionic chemistry specialists, and regional compounders dependent on spot market feedstock procurement. Dominant competitive moves include backward integration into renewable feedstock fermentation and equipment-chemistry bundling to lock out commodity competitors from large facility accounts.
Within the integrated manufacturing tier, Stepan Company and BASF SE exemplify divergent strategic positions. Stepan anchors supply security for institutional formulators across North America through its integrated surfactant manufacturing footprint. BASF SE occupies a position among European-based chemical conglomerates competing through specialized chemistries that sustain higher margins in healthcare and foodservice channels. Dow Inc. represents the scale-driven archetype among diversified material science corporations with broad industrial exposure.
| Leading Market Players |
|---|
| Stepan Company |
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Solvay |
| Croda International Plc |
| Ashland Global Holdings Inc. |
| Clariant AG |
| Pilot Chemical Corp. |
| Others |
Supply Flow & Price Mechanics
National healthcare procurement networks anchor pricing power in the US institutional cleaning ingredients market, compressing margins for commodity surfactant suppliers while rewarding EPA-registered disinfectant formulators with validated efficacy claims. Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade peroxide formulations from bulk hospitality detergents and spot-market bleach concentrates.
Pricing Analysis
Outcome-based pricing anchors value capture for enzymatic cold-water formulations that guarantee energy reduction in commercial laundry operations. Price differentiation separates EPA Safer Choice-certified products from self-declared green alternatives, with certification tier and automated dilution system compatibility driving premium capture. Cost compression in commodity bleach and quaternary ammonium compounds is intensifying because integrated oleochemical producers leverage captive feedstock supply. Budget-constrained K-12 education districts exhibit highest price sensitivity; acute care networks prioritize efficacy validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Atlanta, Chicago, and Los Angeles anchor hub-and-spoke patterns that feed janitorial supply networks across the Southeast, Midwest, and Pacific Coast. Manufacturing concentration centers on Texas and Louisiana petrochemical corridors for ethylene oxide derivatives, with bio-based surfactant fermentation expanding in Iowa and Minnesota agricultural processing zones. Raw material supply rests on ethylene oxide, linear alkylbenzene, and renewable fatty alcohol feedstocks. Single-source vulnerability runs through Gulf Coast oleochemical infrastructure exposed to hurricane disruption. Distribution runs through integrated facility management firms consolidating chemical spend under national purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US institutional cleaning ingredients market sits in a technology-transition phase as bio-based surfactant fermentation displaces conventional petrochemical routes. Enzymatic and peroxide-based hybrid formulations are replacing legacy bleach and quaternary ammonium compound protocols in healthcare terminal disinfection.
For Market Incumbents: Extend EPA Safer Choice certification portfolios to capture preferred vendor status with California and New York state procurement offices before green purchasing mandates fully take effect. Backward integration into renewable feedstock fermentation secures cost parity with petrochemical routes as ethylene oxide price volatility compresses merchant purchaser margins. Defend against commodity bleach suppliers by embedding chemistry-automation bundling contracts with internet-connected dispensing hardware. For New Entrants and Emerging Players: Enter via cold-water enzymatic protocol specialization targeting hospitality and commercial laundry segments where energy savings guarantees unlock performance-based contracting. The Southeast Sun Belt corridor offers the most penetrable geography, with Florida and Georgia facility services expansion outpacing established supplier warehousing capacity. Pursue USDA BioPreferred certification as the go-to-market angle for federal facilities management contracts under Executive Order 14057. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale bio-based surfactant compounders in the Midwest agricultural processing belt where fermentation infrastructure sits underutilized. Long-term viability over the next decade hinges on validated PFAS-free formulation portfolios ahead of pending EPA TSCA Section 6 restrictions. Watch EPA FIFRA registration approval timelines as the inflection signal—accelerated review cycles for novel active ingredients indicate regulatory pathway maturation for enzymatic-peroxide hybrid entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock Fermentation | Captive oleochemical supply insulates margin compression from ethylene oxide price swings. |
| EPA Safer Choice Certification Acceleration | Early compliance unlocks preferred vendor status with California and New York state purchasers. |
| Automated Dilution System Equipment-Chemistry Bundling | Recurring subscription revenue locks out commodity competitors from large facility accounts. |
| Cold-Water Enzymatic Protocol Development | Energy savings guarantees embed performance contracts in hospitality and commercial laundry segments. |
| PFAS-Free Formulation Portfolio Transition | Preemptive substitution ahead of EPA TSCA Section 6 restrictions eliminates regulatory obsolescence risk. |
Methodological Framework
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone for surfactant production capacity and pricing trend validation. Primary interviews with institutional formulator R&D directors, janitorial supply distributor procurement leads, healthcare environmental services managers, and EPA regulatory affairs specialists combined with bottom-up and top-down triangulation across product segment volumes and end-use consumption patterns.
Bottom-up modeling anchored volume projections by disaggregating detergent, disinfectant, degreaser, and enzymatic cleaner consumption across healthcare, hospitality, education, and commercial facility end uses. Segmentation dimensions included formulation type, active ingredient chemistry, certification tier, and regional facility construction activity. CAGRs were derived from regression analysis of historical consumption intensity ratios against commercial floor space expansion and infection control protocol adoption curves. Feedstock price elasticity and green purchasing mandate compliance timelines served as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction implementation or Gulf Coast petrochemical supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Cleaning Nozzles Market