
 Synthetic Camphor Market | 2026-2036
Synthetic Camphor Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Camphor Market Analysis
Pharmaceutical buyers are redrawing procurement patterns away from traditional fragrance houses toward dedicated chemical suppliers. Mangalam Organics leverages its integrated turpentine-to-camphor chain to serve drug producers with pharmacopeia-grade material. Fujian Green Pine anchors East Asian supply through large-scale fractional distillation capacity. Camphor & Allied Products specializes in high-purity crystalline grades that meet stringent pharmacopeial standards for topical formulations.
Synthetic camphor is a bicyclic monoterpene ketone manufactured primarily from alpha-pinene derived from turpentine oil through multi-step synthesis involving dehydrogenation and oxidation, yielding a white crystalline solid with a characteristic penetrating odor and melting point near 174-179°C. The compound functions as an active pharmaceutical ingredient, plasticizer intermediate, and fragrance modifier across industrial and consumer applications. Powder and granular product types dominate volume flows into chemical manufacturing and personal care compounding, while liquid formulations are gaining traction in specialized pharmaceutical processing where rapid dissolution matters. Pharmaceutical and personal care applications together absorb the majority of value, with food additive grades representing a smaller but specification-intensive niche where purity premiums command stronger margins.
FDA pharmacopeial standards, EPA chemical substance reporting under TSCA, and REACH registration requirements collectively define the compliance burden for synthetic camphor producers seeking multi-regional market access. These frameworks elevate testing and documentation costs for smaller manufacturers while rewarding operators with established quality management systems and regulatory dossiers. Stakeholders must track evolving purity specifications and substitution risks from natural camphor sources as sustainability preferences influence buyer qualification criteria across end-use segments.
Market Dynamics
Pharmaceutical procurement consolidation is compressing supplier margins while elevating purity certification requirements, forcing synthetic camphor manufacturers to reconfigure production lines around pharmacopeial-grade output rather than commodity fragrance volumes.
Growth Catalysts
- REACH RoHS tightening:European impurity thresholds for cosmetic and drug-grade camphor are elevating demand for certified high-purity production, rewarding compliant manufacturers with preferential offtake from multinational formulators.
- Tablet coating expansion:Pharmaceutical binders and film coatings now consume rising volumes of synthetic camphor as excipient specifications harden across oral solid dosage manufacturing.
- India domestic consumption:Religious ceremonial uses and traditional medicine applications are concentrating demand growth in Indian manufacturing clusters serving both local temples and export markets.
Market Restraints
- Alpha-pinene volatility:Turpentine oil feedstock prices fluctuate with pine resin harvest cycles and forestry policy shifts in major producing regions, compressing margin predictability for dehydrogenation-based synthesis.
- Natural camphor substitution:Sustainability-driven buyers in premium fragrance and wellness segments are qualifying Cinnamomum camphora-derived material as a carbon-accounted alternative to petrochemical routes.
- CDSCO pharmacopeial delays:Indian drug regulator certification timelines for new synthetic camphor production facilities extend 18-24 months, throttling capacity expansion responses to demand spikes.
Strategic Opportunities
- Brazil ANVISA pathway:Latin American pharmaceutical registration frameworks remain underpenetrated by Asian suppliers, creating first-mover advantages for manufacturers establishing local technical dossiers.
- Liquid formulation niche:Rapid-dissolution pharmaceutical processing is opening specialized demand for liquid camphor grades that bypass crystalline handling constraints in automated compounding systems.
- EU Green Deal chemistry:Bio-based feedstock verification schemes are creating premium pricing tiers for synthetic camphor producers demonstrating renewable carbon content in their alpha-pinene supply chains.
Industry Challenges
- Fractional distillation expertise:The specialized workforce capable of operating high-purity crystallization trains is concentrated in legacy turpentine processing regions, constraining geographic diversification of production.
- Multi-jurisdiction dossier maintenance:Simultaneous compliance with FDA pharmacopeial standards, REACH registration, and BIS certification requires dedicated regulatory affairs capacity that smaller manufacturers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Camphor Market |
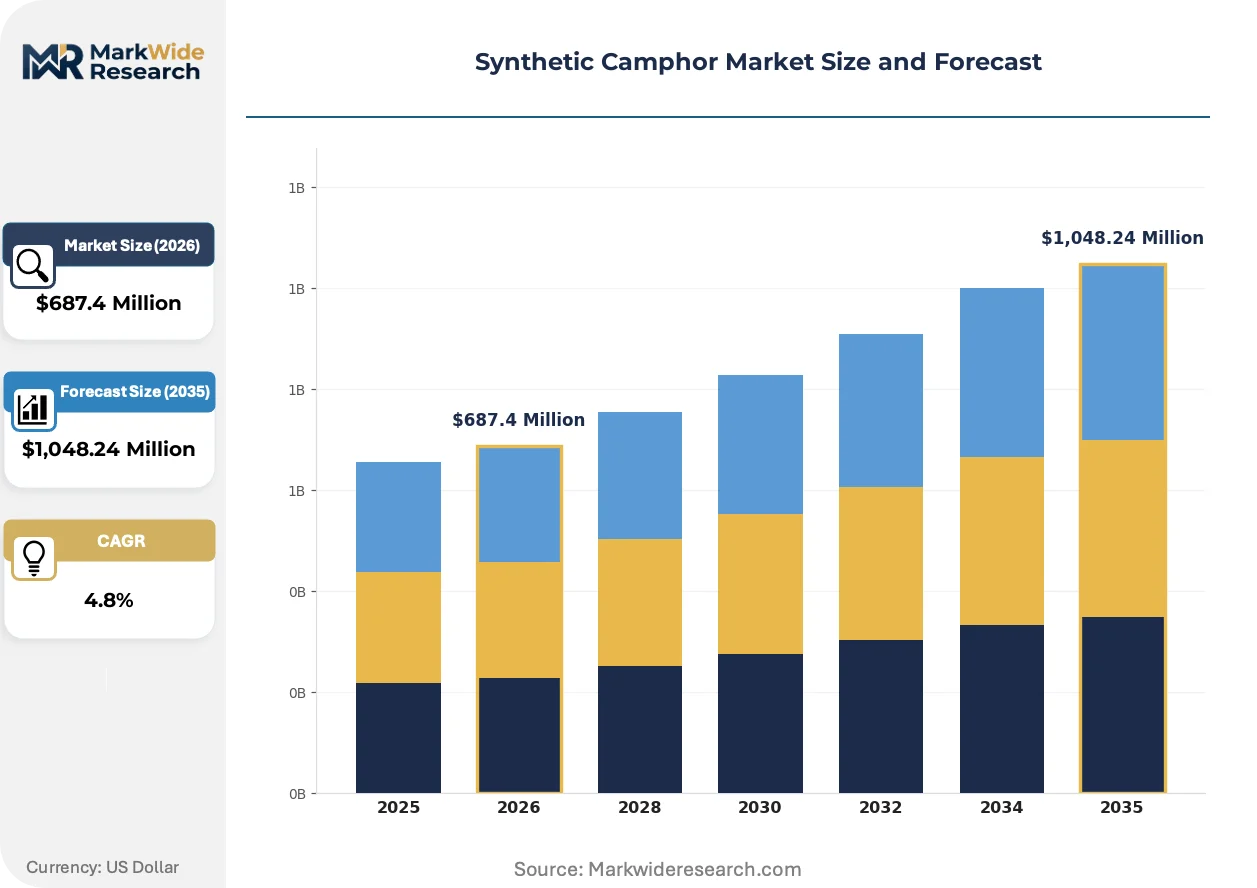
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,048.24 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Crystalline Application: Personal Care, Pharmaceuticals, Food Additives, Chemical Manufacturing End User: Cosmetic Manufacturers, Drug Producers, Food Processors, Industrial Users Packaging Type: Bags, Drums, Bottles, Totes |
| Companies Covered | Fujian Green Pine, Camphor & Allied Products, Mangalam Organics, Recochem, Hiya International, Saptagir Camphor, Kanchi Karpooram, Taiwan Tekho Camphor, Oriental Aromatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Camphor Market Emerging Trajectories
Continuous processing technologies and digital quality control systems are displacing batch manufacturing conventions, while regulatory data integrity requirements and buyer sustainability audits are reshaping how synthetic camphor producers document and differentiate their output.
Continuous dehydrogenation reactor designs are displacing traditional batch oxidation vessels in alpha-pinene processing, enabling pharmaceutical-grade camphor producers to achieve tighter purity distributions with reduced solvent waste. European and Japanese drug manufacturers are qualifying these continuous streams for validated supply chains. The technology is displacing smaller batch operators unable to fund reactor retrofit capex, concentrating pharmacopeial-grade supply among capital-rich integrated producers.
EU F-Gas Regulation amendments are tightening reporting requirements for fluorinated process gases used in some camphor purification steps, compelling manufacturers to retrofit thermal oxidation or adsorption recovery systems. The industrial consequence is elevated capital intensity for European production facilities serving cosmetic and drug markets. German and French chemical clusters are responding fastest, with several producers completing MEE verification of alternative purification routes ahead of enforcement deadlines.
Direct technical relationships between camphor manufacturers and pharmaceutical formulators are compressing traditional fragrance house intermediation, as drug producers seek documented supply chain transparency for FDA audit trails. This disintermediation is most visible in North American and European markets where quality agreements now specify batch-level genealogy requirements. Distributors without in-house analytical capabilities are losing share to suppliers offering CoA-standardized direct delivery programs.
Synthetic Camphor Market Segmentation
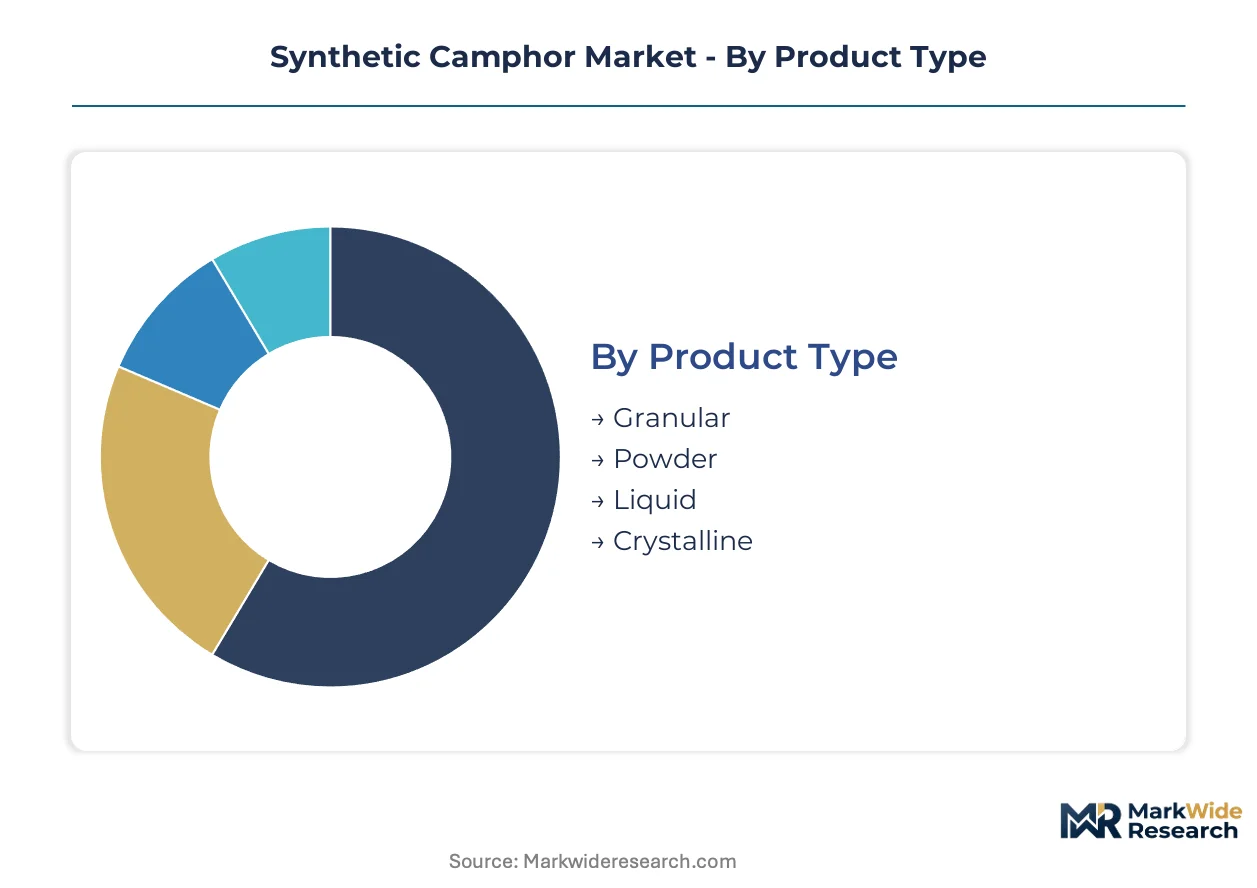
Synthetic camphor producers configure production lines around purity grades and physical forms that align with end-use certification requirements. Pharmaceutical and personal care formulators drive specification intensity, while industrial buyers prioritize handling efficiency and unit economics.
Product Type:
Premium margin pools concentrate in grades requiring fractional distillation expertise and pharmacopeial documentation.
- Crystalline:High-purity solid form meeting USP and EP monographs for tablet coatings and topical analgesic bases. FDA audit trails and REACH dossier completeness reward certified Indian and German producers with preferential offtake from multinational drug manufacturers.
- Powder:Finely milled particles optimized for rapid dissolution in pharmaceutical binders and fragrance compounding. CDSCO-certified facilities in Gujarat and Maharashtra capture expanding domestic demand for religious ceremonial applications.
- Granular:Free-flowing pellets suited to automated chemical manufacturing feed systems where dust containment matters.
- Liquid:Dissolved or molten formulations bypass crystalline handling constraints in continuous pharmaceutical processing lines.
The dominant share belongs to crystalline grades, while liquid formulations are closing the gap fastest.
Application:
Specification intensity varies sharply across end-uses, with pharmacopeial compliance commanding price premiums over industrial commodity tiers.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient roles in oral solid dosages, topical creams, and respiratory preparations. EMA and FDA pharmacopeial standards elevate testing burdens while consolidating procurement around dossier-complete suppliers.
- Personal Care:Fragrance modifier and cooling agent in cosmetics, toiletries, and wellness products. EU F-Gas Regulation amendments and RoHS impurity thresholds are disqualifying legacy batch producers from cosmetic supply chains.
- Chemical Manufacturing:Plasticizer intermediate and polymer additive serving industrial resin and cellulose derivative production.
- Food Additives:Flavoring agent in confectionery and beverages where FSSAI and FDA food-grade certifications create specification-intensive niche demand.
Pharmaceutical applications absorb the largest value share, with personal care segments expanding most quickly on regulatory compliance premiums.
End User:
Procurement sophistication divides buyers between quality-agreement pharmaceutical formulators and spot-market industrial consumers.
- Drug Producers:Oral solid dosage and topical formulation manufacturers requiring batch-level genealogy documentation for FDA and EMA audit readiness. Direct technical relationships with camphor producers are displacing fragrance house intermediation in North American and European markets.
- Cosmetic Manufacturers:Personal care compounders qualifying sustainable supply chains and bio-based feedstock verification under EU Green Deal chemistry frameworks.
- Industrial Users:Chemical and polymer processors prioritizing volume pricing and logistics efficiency over certification depth.
- Food Processors:Flavor houses and confectionery producers navigating FSSAI and FDA food additive approval pathways with extended regulatory timelines.
Drug producers command the dominant procurement volume, while cosmetic manufacturers are gaining share fastest on sustainability-driven specification upgrades.
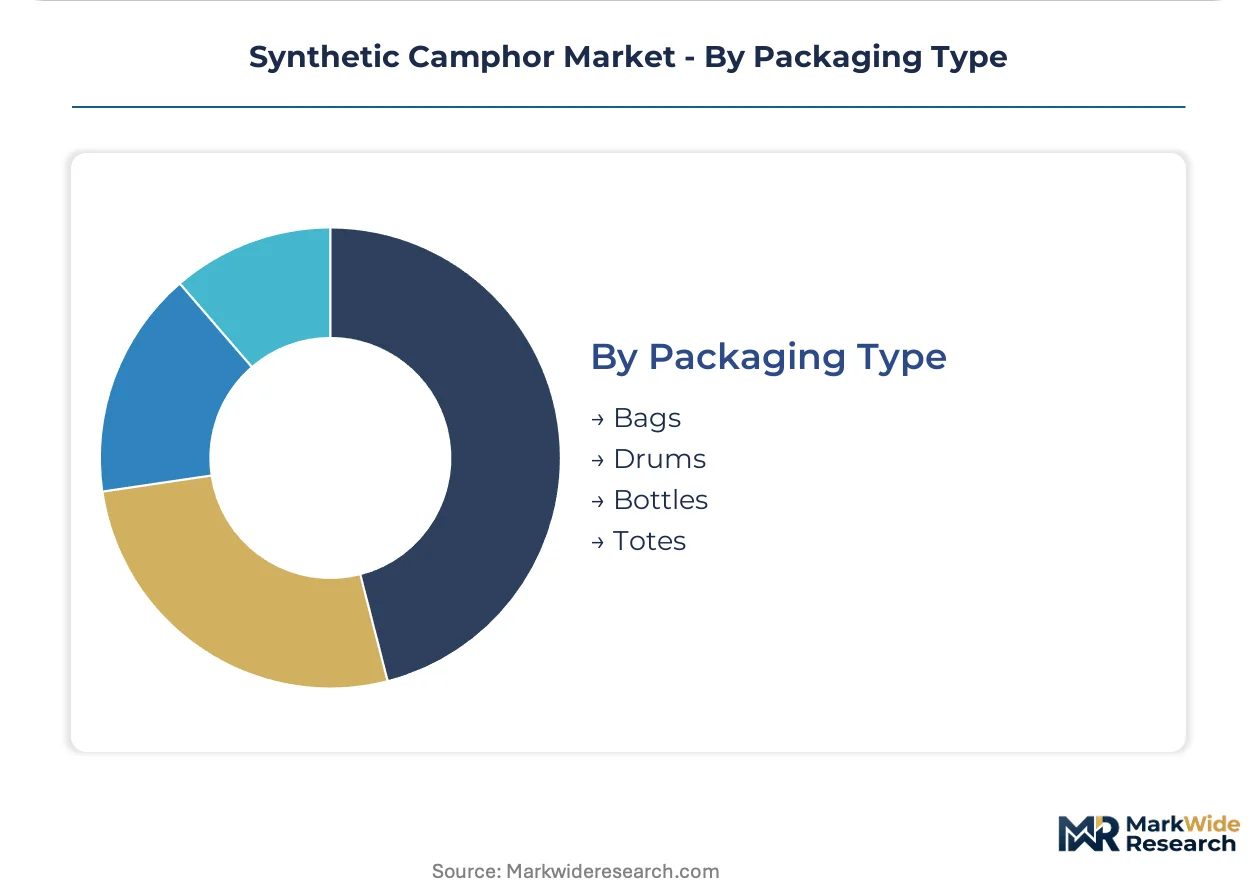
Packaging Type:
Handling automation and contamination control requirements shape packaging selection across customer tiers.
- Drums:Steel and fiber containers dominate pharmaceutical-grade shipments requiring tamper-evident seals and moisture barriers for crystalline camphor stability.
- Bags:Multi-layer polymer sacks serve powder and granular flows into high-volume chemical manufacturing where dust extraction systems manage handling exposure.
- Bottles:Amber glass and fluoropolymer containers protect liquid grades from photodegradation during pharmaceutical compounding operations.
- Totes:Intermediate bulk containers reduce per-unit logistics costs for industrial consumers with automated material handling infrastructure.
Drums retain the dominant shipment format, though totes are climbing fastest as chemical manufacturers consolidate purchasing volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian synthetic camphor manufacturers export pharmacopeia-grade material to European pharmaceutical formulators while serving accelerating domestic ceremonial and medicinal consumption. This trade corridor concentrates value capture in Gujarat and Maharashtra production clusters.
India
Religious temple ceremonies and Ayurvedic medicine preparation drive domestic offtake alongside export shipments to European drug manufacturers. CDSCO pharmacopeial certification timelines extending 18-24 months constrain capacity expansion responses. Gujarat and Maharashtra house integrated turpentine-to-camphor facilities serving both local temple supply chains and multinational pharmaceutical quality agreements.
Germany
EMA pharmacopeial standards and EU F-Gas Regulation amendments elevate compliance costs for cosmetic and drug-grade material. REACH registration requirements and RoHS impurity thresholds disqualify legacy batch producers from premium supply chains. Chemical clusters in North Rhine-Westphalia and Bavaria host producers completing MEE verification of alternative purification routes ahead of enforcement deadlines.
United States
FDA audit trail requirements for oral solid dosage formulations compress supplier qualification timelines while demanding batch-level genealogy documentation. EPA TSCA chemical substance reporting elevates testing burdens for imported material. New Jersey and Pennsylvania pharmaceutical manufacturing corridors source directly from certified producers, displacing fragrance house intermediation.
China
Alpha-pinene feedstock availability from pine resin processing anchors large-scale fractional distillation capacity serving East Asian pharmaceutical and personal care markets. MEE environmental compliance verification and dual carbon goals reshape purification technology selection. Fujian and Zhejiang production bases supply both domestic drug manufacturers and export markets across Southeast Asia.
Brazil
ANVISA pharmaceutical registration frameworks remain underpenetrated by Asian suppliers, creating first-mover opportunities for manufacturers establishing local technical dossiers. Domestic chemical manufacturing and personal care compounding absorb growing import volumes. São Paulo state industrial corridors concentrate formulation activity requiring excipient-grade material.
Synthetic Camphor Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory dossier completeness. The vendor base stratifies into three tiers: integrated turpentine processors with captive feedstock, standalone fractional distillation operators, and regional trading houses. Strategic archetypes include backward-integrated forest products conglomerates, pharmacopeia-grade purity specialists, and volume-focused commodity distributors. Competitive moves center on capacity expansion in CDSCO-certified Indian facilities and direct technical relationships with North American pharmaceutical formulators.
Within the integrated processing tier, Mangalam Organics and Fujian Green Pine exemplify contrasting geographic anchoring strategies. Mangalam Organics occupies a position representing Indian domestic market capture through turpentine-to-camphor chain control. Fujian Green Pine sits within the East Asian supply architecture, anchoring large-scale fractional distillation capacity. Camphor & Allied Products represents the purity-specialist archetype, with crystalline grade production aligned to pharmacopeial standards.
| Leading Market Players |
|---|
| Fujian Green Pine |
| Camphor & Allied Products |
| Mangalam Organics |
| Recochem |
| Hiya International |
| Saptagir Camphor |
| Kanchi Karpooram |
| Taiwan Tekho Camphor |
| Oriental Aromatics |
| Others |
Supply Flow & Price Mechanics
Natural camphor substitution from Cinnamomum camphora sources is compressing pricing power in premium fragrance tiers while simultaneously shifting supply geography toward Southeast Asian plantation zones and away from traditional petrochemical routes. This displacement dynamic rewards Indian and Chinese synthetic producers with pharmacopeial-grade capabilities while eroding commodity-grade margins.
Pricing Analysis
Batch-oxidation versus continuous-dehydrogenation reactor technologies command divergent price premiums, with legacy vessel operators facing cost compression against capital-rich integrated producers achieving tighter purity distributions. Three-tier pricing structure across pharmacopeia-grade, technical-grade, and industrial-grade levels reflects certification depth and FDA dossier completeness. Pricing pressure stems from alpha-pinene feedstock volatility tied to pine resin harvest cycles. Industrial chemical buyers exhibit highest price sensitivity, while drug producers prioritize batch-level genealogy documentation over unit economics.
Supply Chain Analysis
Strategic stockpiling of alpha-pinene feedstock dominates over just-in-time approaches among Indian and Chinese integrated producers managing turpentine oil harvest seasonality. Supply concentrates in India, China, and Germany, with Gujarat and Maharashtra clusters serving export pharmaceutical markets. Raw material flows draw from pine resin processing, turpentine oil fractional distillation, and catalytic dehydrogenation inputs. Single-source vulnerability runs through concentrated fractional distillation expertise in legacy turpentine regions. Distribution runs through direct technical relationships with pharmaceutical formulators, displacing fragrance house intermediation in North American and European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of pharmacopeial-grade fractional distillation expertise is concentrating value capture among legacy turpentine processing regions, creating defensive moats for incumbent operators while raising entry barriers for new capacity.
For Market Incumbents: Shield pharmacopeia-grade margin pools by completing MEE verification of alternative purification routes ahead of EU F-Gas Regulation enforcement deadlines. Backward integration into captive alpha-pinene supply from pine resin processing insulates against feedstock volatility and CDSCO certification delays throttling competitor expansion. For New Entrants and Emerging Players: CDSCO fast-track certification for Gujarat and Maharashtra production facilities offers a regulatory pathway into Indian domestic ceremonial demand and export pharmaceutical supply chains. Brazil ANVISA registration frameworks remain underpenetrated by Asian suppliers, creating first-mover positioning in Latin American excipient markets through local technical dossier establishment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian chemical conglomerates seeking exit liquidity from integrated turpentine-to-camphor operations. Long-term viability hinges on continuous processing technology deployment and EU Green Deal chemistry compliance. Watch for CDSCO certification timeline compression as the inflection signal triggering consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Dehydrogenation Reactor Deployment | Tighter purity distributions reduce solvent waste and qualify supply chains for FDA-validated pharmaceutical programs. |
| Backward Integration into Alpha-Pinene Supply | Captive turpentine oil processing insulates margin predictability against pine resin harvest cycle volatility. |
| CDSCO Certification Fast-Track Investment | Accelerated facility approval timelines unlock capacity expansion responses to Indian domestic demand spikes. |
| EU Green Deal Chemistry Verification | Bio-based feedstock documentation commands premium pricing tiers from sustainability-driven cosmetic manufacturers. |
| Direct Technical Relationship Programs | Batch-level genealogy documentation displaces fragrance house intermediation in North American pharmaceutical procurement. |
Methodological Framework
A spread of perspectives from pharmaceutical procurement directors, fractional distillation plant managers, regulatory affairs specialists at CDSCO and EMA, and fragrance house supply chain leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA pharmacopeial filings, REACH registration databases, customs trade flows, and SEC disclosures from listed chemical producers. Bottom-up capacity assessments and top-down demand triangulation anchored volume and value estimates.
Segmentation dimensions modeled include purity grade tier, physical form specification, end-use application intensity, and regional regulatory cluster across the analysis window. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with pharmaceutical excipient demand trajectories and personal care formulation trends serving as key industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable alpha-pinene feedstock availability and unchanged pharmacopeial certification timelines; material deviation would warrant model refresh. Revision becomes warranted when CDSCO approval velocity or EU F-Gas Regulation enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Asia-Pacific Organic Acid Market