
 Gel Air Fresheners Market | 2026-2036
Gel Air Fresheners Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Air Fresheners Market Foresight
Fragrance chemist shortages across European manufacturing hubs is reorganizing how gel air freshener supply chains allocate technical talent between formulation and regulatory compliance functions. Henkel AG leverages its captive R&D infrastructure in Düsseldorf to sustain proprietary encapsulation patents that anchor its position in commercial-grade scented gel systems. Church & Dwight competes through specialized odor-neutralization chemistry that differentiates its products in North American household channels. Procter & Gamble dominates mass-market distribution through retail partnerships that control shelf placement velocity across multiple fragrance categories.
Gel air fresheners comprise semi-solid matrices of gelling agents, fragrance oils, and volatile organic compound carriers that release scent through passive evaporation at controlled rates, typically formulated with carrageenan or polyacrylate bases to achieve 30-60 day duration profiles. These products serve commercial and residential environments requiring continuous ambient odor control without electrical power or aerosol propellants. Compact gel formats lead unit volume in hospitality applications where discreet placement and extended duration reduce maintenance labor, while refillable gel systems capture margin concentration among sustainability-focused commercial buyers. Electric gel variants represent the fastest-growing structural segment as integration with smart building HVAC systems enables programmable scent scheduling in premium office and hotel properties.
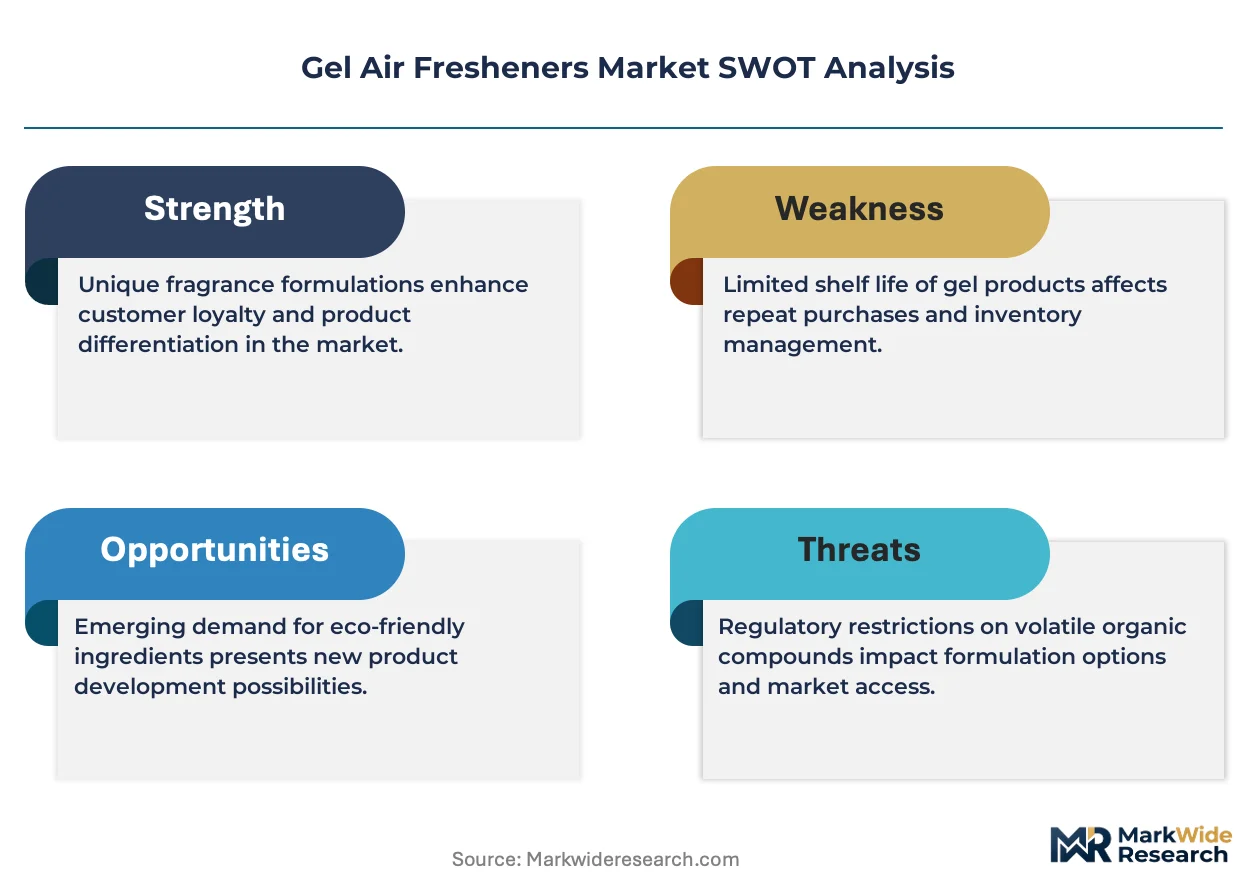
EPA regulations on indoor air quality and VOC emissions constrain permissible solvent concentrations in gel formulations sold across United States commercial channels, while EU REACH and the F-Gas Regulation shape material substitution patterns for European manufacturers. BIS certification requirements for household chemical products in India create divergent compliance pathways for exporters seeking access to emerging Asian markets. Stakeholders must monitor evolving fragrance disclosure mandates from ECHA and state-level California Air Resources Board rules that will determine which gel chemistries retain market access across major economies.
Market Dynamics
Water-based gel carriers and natural fragrance encapsulation technologies are reorganizing formulation priorities across commercial and residential supply chains as regulatory pressure on volatile organic compound emissions intensifies.
Growth Catalysts
- EU REACH VOC limits:The regulation accelerates reformulation toward compliant chemistries, opening procurement channels in LEED and BREEAM-rated commercial properties across Germany and the United States.
- Hospitality ambient scenting programs:Hotels and resorts in North America and Europe are expanding compact gel procurement as branded environmental design elements that reduce maintenance labor.
- Smart building integration:Electric gel variants are capturing new installations in premium office and hotel properties through programmable HVAC-linked scent scheduling systems.
Market Restraints
- Carrageenan supply volatility:Seaweed-derived gelling agent prices fluctuate with marine harvest conditions in Southeast Asia, compressing margin predictability for mid-tier manufacturers.
- Technical duration ceiling:Passive evaporation physics constrain gel matrices to 30-60 day release profiles, limiting value capture against electric diffusers with indefinite replenishment cycles.
- California Air Resources Board rules:State-level fragrance disclosure mandates create compliance fragmentation for national distribution strategies in the United States.
Strategic Opportunities
- India BIS certification pathway:Exporters establishing compliant household chemical product lines can access emerging Asian markets with limited incumbent competition in gel formats.
- Refillable system adoption:Sustainability-focused commercial buyers in Germany and the United States are concentrating procurement on reusable gel cartridges that shift revenue toward consumables.
- Natural encapsulation convergence:Combining water-based carriers with bio-derived fragrance oils opens premium positioning in wellness-oriented residential channels.
Industry Challenges
- Fragrance chemist scarcity:European manufacturing hubs face talent competition between formulation R&D and regulatory compliance functions, delaying product development timelines.
- Multi-jurisdiction certification lag:Parallel EPA, REACH, and BIS approval processes extend time-to-market for reformulated gel chemistries by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Air Fresheners Market |
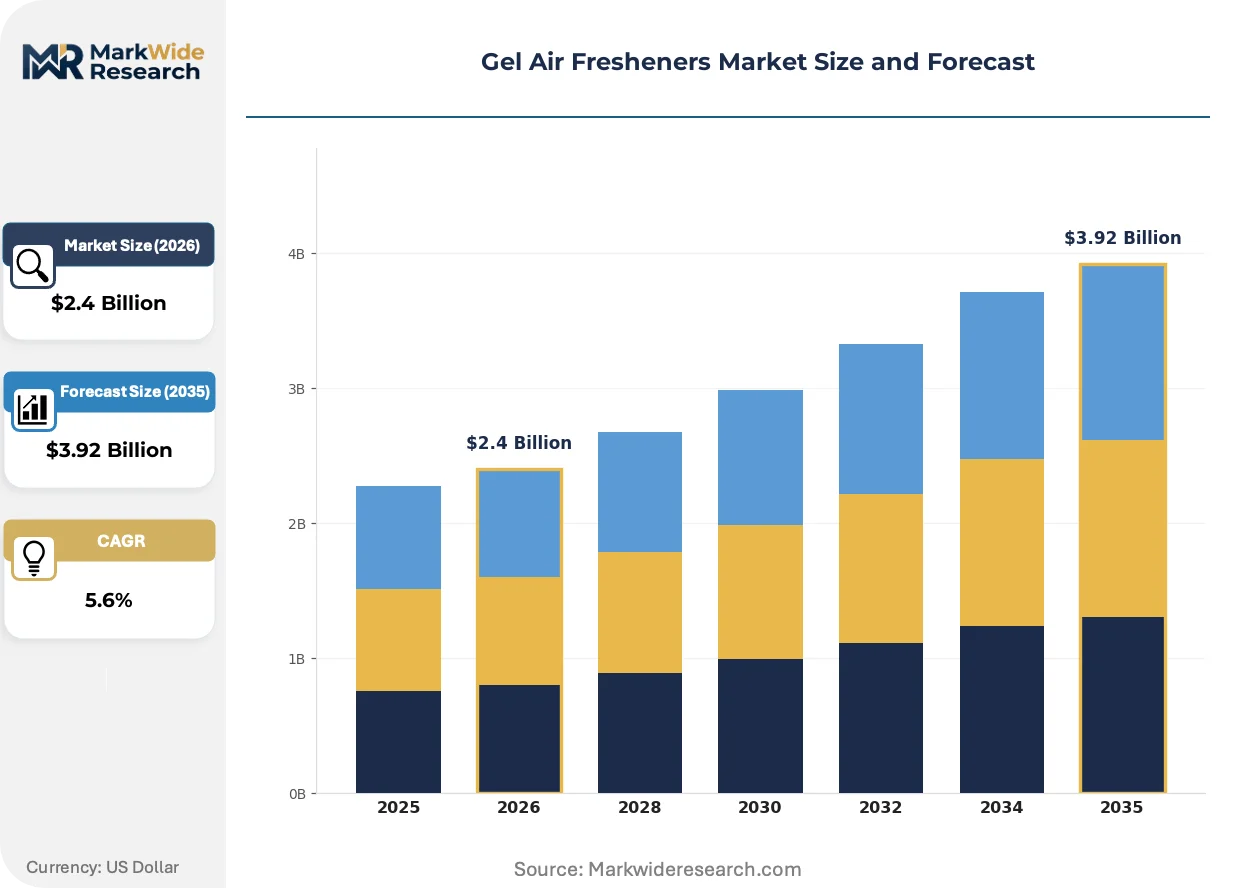
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Gel, Hanging Gel, Refillable Gel, Electric Gel, Scented Gel Fragrance Type: Floral, Citrus, Ocean Breeze, Musk, Herbal, Fruity Application: Residential Spaces, Commercial Offices, Hospitality Venues, Public Restrooms, Vehicle Interiors Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Convenience Stores, Household Product Dealers |
| Companies Covered | Henkel AG, Church & Dwight, Procter & Gamble, Poleview Group, Ocean Star Inc, Reckitt Benckiser Group, Newell Brands, Keva USA, SC Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Air Fresheners Market Shifts & Advancements
Active reformulation toward compliant chemistries, integration with building automation systems, and procurement preference shifts toward certified low-emission products are compressing traditional competitive advantages in gel air freshener supply chains.
Encapsulation technology is miniaturizing fragrance oil reservoirs within polyacrylate matrices to achieve more precise release kinetics. Hospitality procurement teams in Germany and the United States are specifying these systems for branded scent programs. The technology is miniaturizing hardware requirements and enabling discreet placement in compact commercial environments where aesthetic constraints limit traditional diffuser footprints.
EPA indoor air quality regulations are constraining permissible solvent concentrations in gel formulations sold through United States commercial channels. Manufacturers are substituting petroleum-derived carriers with water-based alternatives and reformulating fragrance loads to maintain olfactory performance. Commercial real estate operators in California and New York are now requiring third-party VOC certification as a procurement gate.
Facility managers are consolidating air care procurement under sustainability compliance officers rather than maintenance departments. This organizational shift elevates certified low-emission products over price-competitive alternatives in vendor selection. The pattern is most visible in LEED-rated office properties across the United States and BREEAM-certified buildings in the United Kingdom.
Gel Air Fresheners Market Segmentation
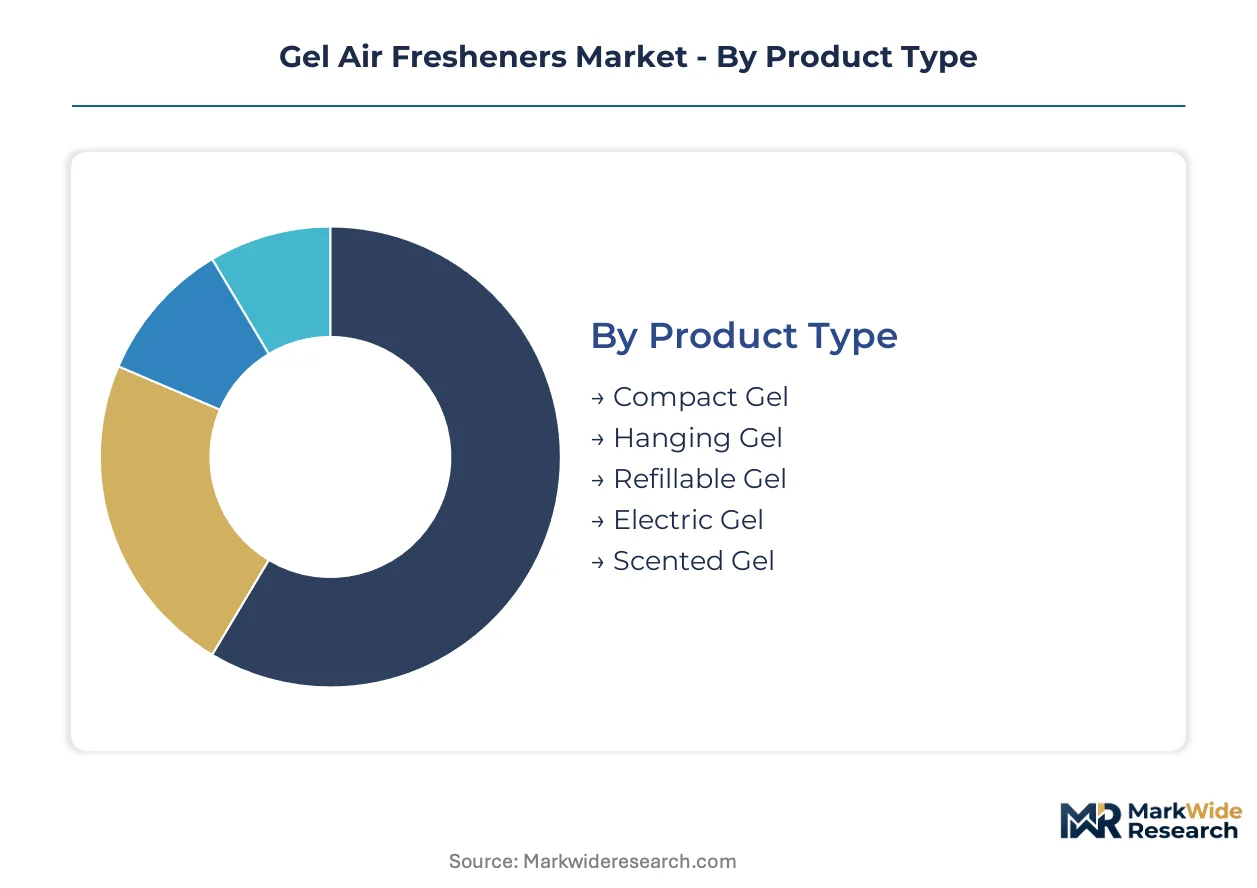
Gel air freshener segmentation reveals how formulation chemistry, fragrance engineering, and placement mechanics align with distinct procurement channels. Channel-specific requirements drive divergent product specifications across retail, commercial, and institutional buyers.
Product Type:
Channel mix varies sharply by product format, with hospitality and facilities management procurement favoring extended-duration systems while mass retail concentrates on disposable convenience formats.
- Compact Gel:Semi-solid matrices in discrete containers deliver 30-60 day passive release through carrageenan or polyacrylate bases. Hospitality venues across Germany and the United States specify these for branded ambient scenting programs that minimize maintenance labor in guest rooms and lobbies.
- Electric Gel:HVAC-integrated systems with programmable scent scheduling capture premium installations in LEED-rated office properties and luxury hotels. Smart building integration enables centralized control that passive formats cannot match.
- Hanging Gel:Suspended formats with exposed surface area for accelerated evaporation serve vehicle interiors and compact restrooms where placement flexibility outweighs duration requirements.
- Refillable Gel:Reusable cartridge systems concentrate procurement among sustainability-focused commercial buyers in Germany and the United States, shifting vendor revenue models toward consumable refills.
- Scented Gel:Standard passive formats with fixed fragrance loads dominate supermarket and convenience store channels through price-accessible positioning.
By volume, Scented Gel leads through mass retail penetration. By growth pace, Electric Gel is climbing the fastest on smart building adoption.
Fragrance Type:
Cost tier stratification separates premium bio-derived formulations from petroleum-based standard offerings, with certification requirements increasingly influencing procurement thresholds.
- Floral:Rose, jasmine, and lavender oil encapsulations command premium positioning in hospitality and wellness-oriented residential channels. EU REACH-compliant natural fragrance loads are displacing synthetic alternatives in German commercial properties.
- Citrus:Limonene and terpene-based formulations deliver high olfactory impact at moderate cost, capturing volume in North American household channels where odor-neutralization performance drives repeat purchase.
- Ocean Breeze:Ozonic and aquatic accords target hospitality procurement for coastal and resort properties seeking thematic environmental design alignment.
- Musk:Synthetic musk alternatives face regulatory pressure under EPA VOC constraints, constraining formulation flexibility for United States commercial distribution.
- Herbal:Eucalyptus, tea tree, and sage derivatives align with wellness positioning in specialty retail and natural product channels.
- Fruity:Berry and tropical fruit accords concentrate in mass-market retail formats targeting residential impulse purchase.
By volume, Citrus dominates through cost-performance optimization. By margin capture, Floral is expanding most quickly on natural encapsulation premiums.
Application:
Customer type determines specification rigor, with facilities management and procurement officers elevating certified low-emission requirements above price in commercial settings.
- Hospitality Venues:Hotels and resorts specify compact and electric gel systems as branded environmental design elements. Third-party VOC certification has become a procurement gate for premium properties in California and New York.
- Commercial Offices:LEED and BREEAM-rated buildings concentrate demand for certified low-emission products, with sustainability compliance officers now controlling air care procurement decisions.
- Residential Spaces:Standard scented and compact gel formats dominate through supermarket and online retail channels, with fragrance preference driving brand switching.
- Public Restrooms:High-traffic facilities prioritize odor-neutralization chemistry and extended duration to reduce maintenance frequency.
- Vehicle Interiors:Hanging gel formats with compact footprints and rapid scent release serve automotive aftermarket channels.
By volume, Residential Spaces leads through retail channel penetration. By specification value, Hospitality Venues is gaining share fastest on ambient scenting program expansion.
Distribution Channel:
Supply concentration varies by channel control, with consolidated retail partnerships determining shelf placement velocity in mass-market segments.
- Supermarkets:National retail partnerships control category placement and promotional scheduling, favoring suppliers with multi-fragrance portfolio breadth and replenishment reliability.
- Online Retailers:E-commerce channels enable direct-to-consumer subscription models for refillable systems, capturing recurring revenue from sustainability-focused buyers.
- Specialty Stores:Curated fragrance and home environment retailers concentrate premium and natural-positioned gel formats with educated sales assistance.
- Convenience Stores:Impulse-oriented formats with compact footprints and immediate olfactory appeal serve travel and emergency purchase occasions.
- Household Product Dealers:Institutional and janitorial supply channels serve facilities management procurement with volume pricing and technical specification support.
By volume, Supermarkets leads through physical retail dominance. By channel expansion, Online Retailers is climbing the fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States drive premium gel air freshener consumption through certified low-emission procurement mandates, while India and emerging Asian markets absorb volume-oriented formats with divergent regulatory compliance requirements.
United States
Commercial real estate operators in California and New York prioritize LEED-rated properties with third-party VOC certification as procurement gates. EPA indoor air quality regulations constrain permissible solvent concentrations in gel formulations sold through commercial channels. Facility managers in Manhattan and Los Angeles consolidate air care decisions under sustainability compliance officers rather than maintenance departments.
Germany
Hospitality venues across Bavaria and North Rhine-Westphalia specify compact gel systems for branded ambient scenting programs that minimize guest room maintenance labor. EU REACH regulation on volatile organic compound emissions accelerates reformulation toward water-based gel carriers and natural fragrance encapsulation technologies. Düsseldorf anchors captive R&D infrastructure sustaining proprietary encapsulation patents for commercial-grade scented gel systems.
United Kingdom
BREEAM-certified buildings in London and Manchester concentrate demand for certified low-emission air care products from sustainability-focused procurement officers. ECHA fragrance disclosure mandates shape which gel chemistries retain market access across British commercial channels. The Southeast England logistics corridor distributes reformulated compliant products to hospitality chains operating premium properties.
India
Emerging middle-class households in Maharashtra and Gujarat drive volume consumption of standard scented gel formats through retail channels. BIS certification requirements for household chemical products create divergent compliance pathways for exporters seeking market access. Mumbai and Ahmedabad manufacturing clusters serve domestic demand with cost-optimized formulations distinct from Western regulatory standards.
France
Luxury hospitality properties in Paris and the French Riviera specify electric gel variants with programmable scent scheduling as branded environmental design elements. ANSM and CNIL oversight of consumer chemical safety influences fragrance disclosure protocols for products distributed through French commercial channels. The Île-de-France region concentrates procurement decision-making for international hotel chains operating across European markets.
Gel Air Fresheners Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the gel air freshener market. Henkel AG and Procter & Gamble occupy positions with captive R&D infrastructure and retail partnership networks respectively. Church & Dwight competes through specialized odor-neutralization chemistry. The competitive dynamic centers on reformulation speed for regulatory compliance and smart building integration capabilities.
Among German-anchored multinationals, Henkel AG exemplifies the integrated leader archetype with proprietary encapsulation technology. Church & Dwight and Procter & Gamble represent North American competitors differentiated by odor-neutralization chemistry and mass-market distribution control respectively. These three companies anchor the competitive structure through divergent capability investments rather than convergent product strategies.
| Leading Market Players |
|---|
| Henkel AG |
| Church & Dwight |
| Procter & Gamble |
| Poleview Group |
| Ocean Star Inc |
| Reckitt Benckiser Group |
| Newell Brands |
| Keva USA |
| SC Johnson |
| Others |
Supply & Pricing Matrix
Capacity utilization at Southeast Asian carrageenan processing facilities fluctuates with marine harvest cycles, compressing margin predictability for mid-tier gel air freshener manufacturers and anchoring price floors for water-based gel carriers. This scale-driven supply concentration grants integrated leaders procurement leverage over fragmented competitors while forcing reformulation investments that reshape cost structures across premium and economy tiers.
Pricing Analysis
Long-term offtake agreements dominate procurement between hospitality chains and gel system suppliers, insulating premium tier pricing from spot volatility in fragrance oil markets. Three-tier pricing structure across premium, standard, and economy levels separates EU REACH-certified natural encapsulation systems from petroleum-derived standard offerings and unbranded economy formats. Price differentiation hinges on certification grade and volume scale, with California Air Resources Board compliance adding cost premiums that sustainability-focused buyers absorb. Cost compression in economy tiers intensifies because private-label retailers squeeze contract manufacturers on unit economics, while commercial facilities management shows lowest price sensitivity due to bundled maintenance service contracts.
Supply Chain Analysis
Strait of Malacca transit underwrites the majority of seaweed-derived carrageenan reaching European and North American gel formulation plants, exposing manufacturers to logistics chokepoint risks from seasonal piracy and port congestion. Raw material sourcing concentrates in Indonesia, the Philippines, and Malaysia for gelling agents, with fragrance oil encapsulation technology anchored in Germany and the United States. Formulation draws from polyacrylate resin supplies centered on South Korean and Japanese petrochemical complexes, creating multi-source dependencies for matrix chemistry. Single-source vulnerability persists in natural fragrance oil distillation from Grasse, France and Kannauj, India. Distribution runs through institutional janitorial supply channels for commercial buyers and consolidated retail partnerships for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragrance chemist scarcity across European manufacturing hubs constrains reformulation velocity for regulatory compliance, creating a capability gap that separates integrated leaders from mid-tier competitors dependent on outsourced technical talent.
For Market Incumbents: Fortify proprietary encapsulation patent portfolios through captive R&D infrastructure investments in Düsseldorf and Cincinnati research corridors. Accelerate backward integration into natural fragrance oil distillation to secure supply continuity against Grasse and Kannauj sourcing bottlenecks. Prioritize LEED and BREEAM certification maintenance as procurement gates tighten in California and New York commercial real estate channels. For New Entrants and Emerging Players: Lead with refillable gel cartridge systems targeting sustainability-focused commercial buyers in Germany and the United States where incumbent refill economics remain underdeveloped. Exploit BIS certification pathway advantages for household chemical products entering Maharashtra and Gujarat retail channels with limited gel format competition. Deploy direct-to-consumer subscription models through online retail to bypass supermarket shelf placement barriers controlled by established brand portfolios. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty encapsulation technology holders with regulatory compliance track records over commodity gel format manufacturers. Five-to-ten year viability concentrates on water-based carrier convergence and smart building HVAC integration capabilities. Acquisition target archetype: mid-scale European manufacturers with REACH-compliant formulation libraries and hospitality channel relationships. Signal to watch: EPA indoor air quality rulemaking expansion beyond California and New York into Texas and Florida commercial markets.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Encapsulation Patent Expansion | Henkel AG's Düsseldorf R&D infrastructure anchors proprietary technology moats in commercial-grade systems. |
| Refillable System Platform Launch | Reusable cartridge formats shift vendor revenue models toward recurring consumables in sustainability-focused procurement. |
| Smart Building HVAC Integration | Electric gel variants capture premium installations through programmable scent scheduling in LEED-rated properties. |
| India BIS Certification Pathway | Compliant household chemical product lines unlock emerging Asian markets with limited incumbent gel format presence. |
| EU REACH Reformulation Acceleration | Water-based carrier substitution opens procurement channels in BREEAM-certified buildings across Germany and the United Kingdom. |
Research Methodology
Initial hypotheses were tested against primary input from fragrance chemists, hospitality procurement directors, facilities management sustainability officers, and janitorial supply distributors, then refined against secondary validation from EPA regulatory filings, EU REACH substance databases, BIS certification records, and customs trade data for carrageenan and polyacrylate resin imports. Bottom-up demand modeling across hospitality, commercial office, and residential channels triangulated with top-down market sizing from retail audit databases and institutional procurement contract disclosures.
Variance decomposition across the projection horizon isolates volume drivers by product format, fragrance type, application segment, and distribution channel, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators and regulatory implementation timelines. Modeled inputs include EU REACH VOC limit phase-in schedules, EPA indoor air quality enforcement patterns, and smart building HVAC penetration rates in premium office and hotel properties.
Forecasts assume regulatory continuity in EPA, REACH, and BIS regimes; material policy shifts would require re-modeling of compliant chemistry adoption curves and market access pathways. Revision becomes warranted when marine harvest disruptions in Southeast Asia exceed historical variance bands or when California Air Resources Board rules expand disclosure mandates to additional fragrance categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
India Essential Oils Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Aroma Chemicals Market