
 X-Ray Systems Market | 2026-2036
X-Ray Systems Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Systems Market Intelligence
Hospital procurement channels across North America and Western Europe are rewriting how x-ray system vendors secure long-term service contracts and equipment refresh cycles. Siemens Healthineers AG leverages its installed base of angiography suites to sustain recurring revenue from software upgrades and remote monitoring services. GE Healthcare anchors its position through backward integration into tube and detector manufacturing, controlling critical component supply. Canon Medical Systems Corporation differentiates via specialized cardiovascular imaging configurations that command premium positioning in academic medical centers.
X-ray systems generate electromagnetic radiation in the 0.01 to 10 nanometer wavelength range, producing differential absorption images based on tissue electron density for diagnostic visualization of bone fractures, pulmonary infiltrates, and vascular pathologies. Digital radiography now leads product type demand as healthcare systems retire computed radiography cassettes to reduce chemical processing costs and accelerate workflow throughput. Portable systems represent the fastest-expanding equipment category, driven by emergency department throughput requirements and point-of-care imaging expansion in outpatient clinics. Fluoroscopy technology commands concentrated margin pools in interventional cardiology and surgical navigation applications where real-time guidance commands premium pricing.
FDA 510(k) clearance requirements and IEC 60601-1-3 dose safety standards shape product development priorities, forcing manufacturers to demonstrate diagnostic equivalence at reduced patient exposure levels. The EU Medical Device Regulation and CE marking obligations under MDR extend compliance burdens for software-as-medical-device features including AI-assisted image reconstruction. Stakeholders must monitor evolving reimbursement codes for remote image interpretation and teleradiology services, as payor policy will determine whether capital equipment investments translate into sustainable procedure economics.
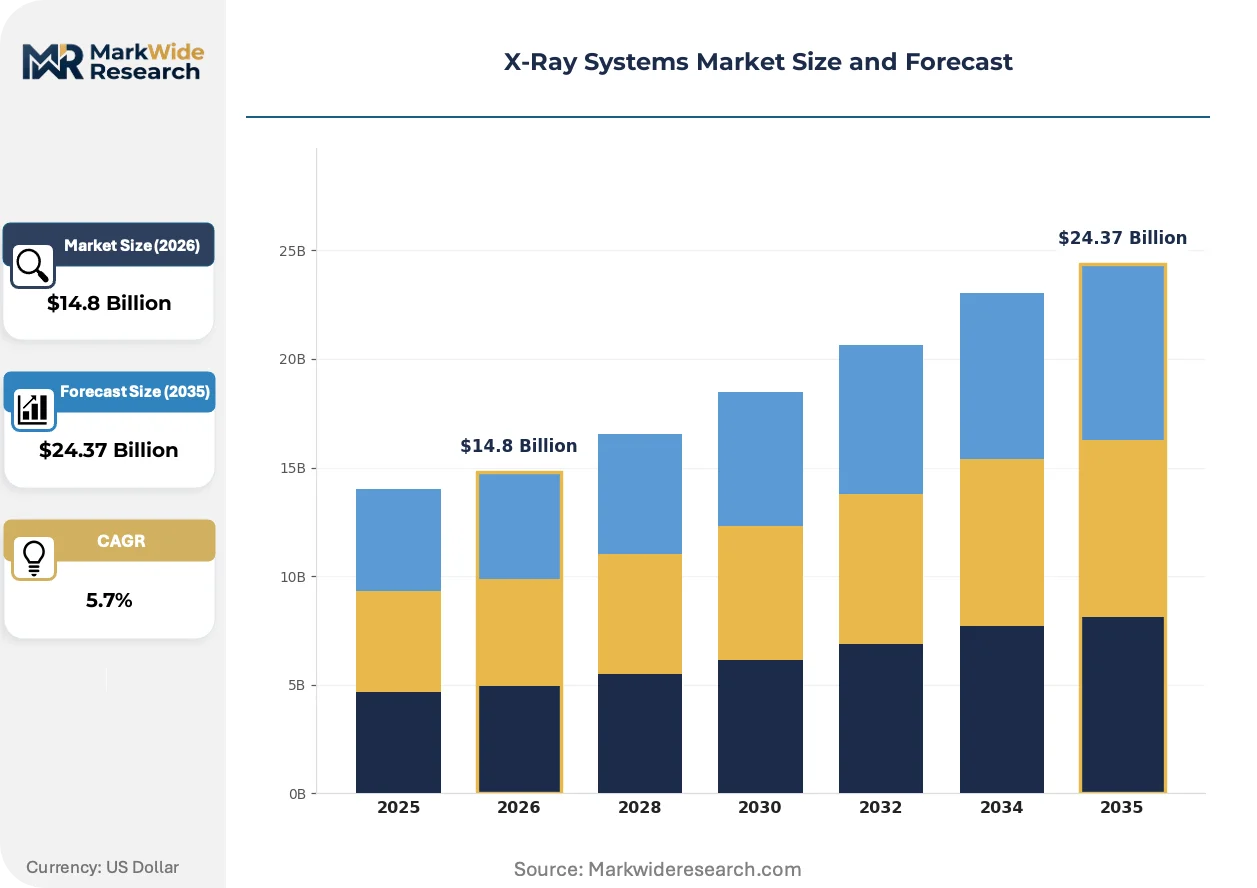
Market Dynamics
Hospital procurement channels are consolidating purchasing power through multi-year fleet modernization contracts, forcing equipment vendors to bundle software subscriptions and remote service capabilities into capital sales.
Growth Catalysts
- Computed radiography cassette retirement:Healthcare systems eliminate chemical processing infrastructure to reduce operating costs and accelerate image-to-diagnosis intervals.
- FDA 510(k) pathway streamlining:AI-enhanced diagnostic algorithms secure clearance faster, compressing commercialization timelines for algorithm developers.
- Emergency department throughput mandates:Portable x-ray deployment expands as hospitals prioritize bedside imaging to reduce patient transport delays.
Market Restraints
- Tungsten supply concentration:X-ray tube filament manufacturing depends on concentrated rare earth sourcing, exposing production schedules to geopolitical disruption.
- EU MDR compliance burden:Software-as-medical-device features face extended CE marking timelines under enhanced clinical evidence requirements.
- Flat-panel detector cost structure:Amorphous silicon substrate fabrication requires specialized semiconductor foundry capacity with limited second-source alternatives.
Strategic Opportunities
- Outpatient clinic point-of-care expansion:Miniaturized systems penetrate orthopedic and urgent care settings previously served by referral imaging centers.
- Interventional cardiology real-time guidance:Fluoroscopy-integrated surgical navigation commands premium positioning in electrophysiology labs.
- India PLI scheme localization:Component manufacturing incentives attract assembly operations to serve South Asian hospital procurement growth.
Industry Challenges
- Medical physicist certification scarcity:Dose optimization expertise gaps delay AI reconstruction algorithm validation and clinical deployment.
- Legacy PACS integration complexity:Digital radiography suites require custom middleware development to interface with decade-old hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Systems Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Systems, Digital Systems, Portable Systems, Stationary Systems Technology: Computed Radiography, Digital Radiography, Fluoroscopy, Mammography End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Application: Orthopedics, Dentistry, Chest Imaging, Cardiovascular |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Shimadzu Corporation, Carestream Health, Hologic, Inc., Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Systems Market Strategic Shifts & Innovations
Artificial intelligence reconstruction algorithms are compressing exposure requirements while maintaining diagnostic equivalence, fundamentally altering how manufacturers compete on dose-performance trade-offs.
Photon-counting detector technology is digitizing spectral imaging capabilities previously confined to research environments. Academic medical centers in Germany and the United States are piloting cadmium-zinc-telluride arrays for quantitative tissue characterization. This transition is digitizing the competitive basis for premium system positioning away from mechanical gantry speed toward computational imaging sophistication.
EU Medical Device Regulation enforcement is extending software lifecycle documentation obligations to AI-assisted image reconstruction modules. Manufacturers must maintain continuous post-market surveillance for algorithm drift and performance degradation. Interventional fluoroscopy systems face the steepest compliance cost escalation due to real-time processing complexity and patient safety criticality.
Hospital purchasing cooperatives are consolidating equipment procurement through standardized technical specifications and volume commitment frameworks. Regional health systems in North America negotiate enterprise-wide service agreements that unbundle preventive maintenance from capital acquisition. This concentration is most pronounced in integrated delivery networks spanning multiple states under unified capital budgeting authority.
X-Ray Systems Market Segmentation
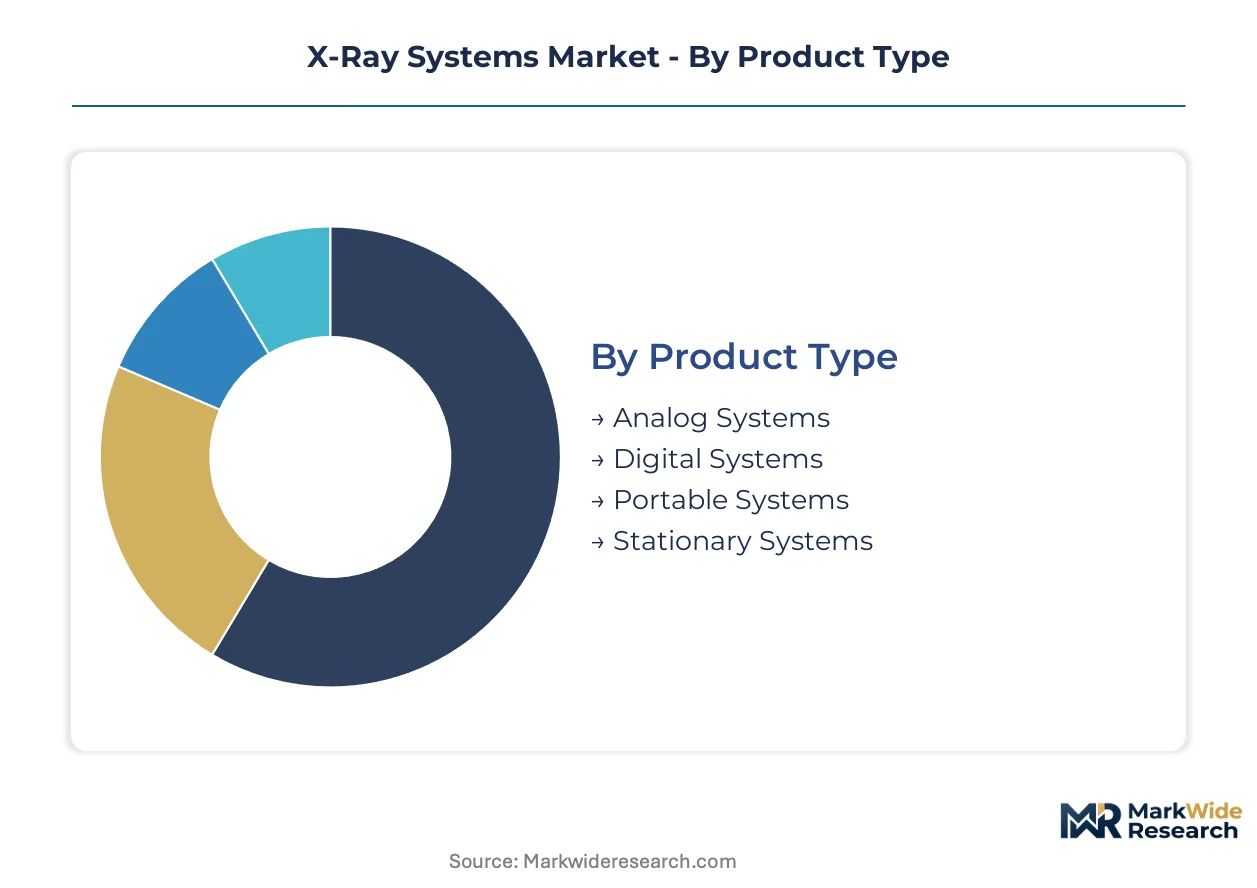
X-ray system segmentation reveals divergent replacement cycles across equipment categories. Digital platforms compress refresh intervals to software-driven upgrade rhythms. Analog fleets impose capital-intensive replacement decisions on procurement committees.
Product Type:
Stationary systems turn over every 10-15 years while portable units refresh every 5-7 years due to mechanical wear and battery degradation.
- Digital Systems:Flat-panel detector arrays capture images in sub-second intervals, eliminating chemical processing infrastructure. Hospital procurement committees in Germany prioritize these for fleet standardization to reduce per-exam operational costs and accelerate radiologist workflow throughput.
- Portable Systems:Battery-powered mobile units with wireless DICOM transmission enable bedside imaging in emergency departments and intensive care units. Demand concentrates in North American hospital networks seeking to eliminate patient transport delays and reduce fall-risk incidents during inter-departmental transfers.
- Analog Systems:Film-based radiography requiring chemical development persists in budget-constrained facilities and developing regions with unreliable power infrastructure.
- Stationary Systems:Fixed-room installations with ceiling-suspended tube stands dominate high-volume radiology departments and trauma centers.
Stationary systems dominate installed base. Portable systems are where expansion concentrates.
Technology:
Cost tiers separate premium spectral imaging from standard projection radiography, with reimbursement differentials determining hospital investment prioritization.
- Digital Radiography:Direct-capture flat-panel detectors convert x-ray photons to electrical signals without intermediate scintillation layers. Healthcare systems in the United States accelerate retirement of computed radiography cassettes to qualify for Medicare technical component reimbursement incentives tied to dose reduction documentation.
- Fluoroscopy:Continuous x-ray image acquisition enables real-time visualization for interventional procedures and surgical navigation. Academic medical centers command premium pricing for cardiac catheterization labs where electrophysiology mapping requires sub-millimeter spatial resolution at frame rates exceeding 30 per second.
- Computed Radiography:Photostimulable phosphor plates require laser scanning and erasure cycles, retaining foothold in low-volume settings where capital constraints delay detector array investments.
- Mammography:Dedicated low-dose systems with specialized compression paddles and tomographic capabilities address breast tissue imaging requirements under FDA quality standards.
Digital Radiography commands revenue concentration. Fluoroscopy delivers margin expansion.
End User:
Customer type determines procurement authority structure, with integrated delivery networks consolidating purchasing power differently than independent diagnostic operators.
- Hospitals:Multi-departmental imaging departments with centralized radiology information systems and enterprise PACS integration requirements. Capital budgeting committees negotiate multi-year service contracts bundling preventive maintenance, tube replacements, and software subscription renewals.
- Diagnostic Centers:Specialized outpatient facilities competing on appointment availability and report turnaround time. Volume-based equipment utilization drives preference for high-throughput digital platforms with automated exposure control.
- Outpatient Clinics:Point-of-care settings including urgent care and orthopedic practices requiring immediate imaging confirmation for fracture reduction and casting decisions.
- Research Institutions:Academic medical centers piloting photon-counting detector arrays and spectral imaging protocols for quantitative tissue characterization studies.
Hospitals anchor equipment shipments. Outpatient clinics are expanding most quickly.
Application:
Clinical use case dictates detector specification, with orthopedic trauma requiring different spatial resolution parameters than pulmonary screening protocols.
- Chest Imaging:High-kilovoltage techniques penetrate mediastinal structures for pneumonia detection and tuberculosis screening. Public health programs in India deploy mobile digital units to rural districts under national disease elimination targets.
- Orthopedics:Extremity and spine imaging with weight-bearing capabilities for joint alignment assessment. Sports medicine clinics command specialized C-arm configurations for intraoperative fracture fixation guidance.
- Cardiovascular:Coronary angiography and peripheral vascular assessment requiring rapid sequence acquisition and large field-of-view detectors.
- Dentistry:Intraoral and panoramic systems with reduced radiation output for periodontal and implant planning applications.
Chest Imaging dominates procedure volume. Orthopedics is where premium system placement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for hospital infrastructure modernization are reshaping procurement patterns across major healthcare markets, with regulatory pathways for AI-enhanced diagnostics accelerating deployment timelines in select jurisdictions.
United States
Medicare technical component reimbursement incentives drive computed radiography cassette retirement across hospital networks seeking dose reduction documentation. FDA 510(k) clearance pathways compress commercialization timelines for AI-enhanced diagnostic algorithms. The Texas Medical Center cluster in Houston anchors large-scale fleet modernization contracts with bundled software subscription frameworks.
Germany
Regional hospital networks consolidate purchasing power through multi-year enterprise agreements unbundling preventive maintenance from capital acquisition. EU Medical Device Regulation extends software lifecycle documentation obligations to AI-assisted reconstruction modules. Siemens Healthineers AG in Erlangen leverages installed base density to sustain recurring revenue from remote monitoring services and tube replacement programs.
China
Public hospital procurement committees accelerate digital radiography adoption under national healthcare infrastructure investment targets. NMPA regulatory harmonization with international standards streamlines clearance for imported detector arrays. The Yangtze River Delta cluster around Shanghai concentrates domestic assembly operations serving tier-one hospital procurement growth.
India
Public health programs deploy mobile digital units to rural districts under national tuberculosis elimination targets. PLI scheme localization incentives attract component manufacturing operations for South Asian hospital procurement expansion. The Maharashtra cluster around Mumbai anchors diagnostic center consolidation with volume-based equipment utilization driving high-throughput platform preference.
Japan
Academic medical centers pilot photon-counting detector arrays for quantitative tissue characterization under METI-funded research consortia. PMDA regulatory frameworks maintain stringent clinical evidence requirements for software-as-medical-device features. The Kansai region around Osaka concentrates precision manufacturing supply chains for amorphous silicon substrate fabrication.
X-Ray Systems Market Key Industry Players
On the supply side, the industry is consolidating around integrated manufacturers with captive component production and recurring service revenue streams. Tiered competitive positioning separates premium spectral imaging specialists from volume-driven digital radiography providers. Three archetypes dominate: diversified healthcare conglomerates with backward integration into tube manufacturing, specialized imaging equipment pure-plays with software subscription models, and regional assemblers leveraging localization incentives. M&A activity targets AI algorithm developers, while capacity expansion concentrates in semiconductor foundry partnerships for detector substrate fabrication.
Among diversified healthcare conglomerates, Siemens Healthineers AG and GE Healthcare exemplify the integrated archetype with upstream control over critical component supply. Canon Medical Systems Corporation occupies a specialized position exemplifying premium-tier cardiovascular imaging configuration. These three anchors demonstrate how competitive positioning digitizes around computational imaging sophistication rather than mechanical gantry specifications alone.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| Carestream Health |
| Hologic, Inc. |
| Hitachi, Ltd. |
| Others |
Cost & Logistics Intelligence
Tungsten supply concentration in Chinese and Russian mining operations determines both the pricing tier spreads across detector array grades and the geographic shape of tube manufacturing supply chains. Manufacturers with captive filament production command premium positioning while dependent assemblers absorb volatility through contract renegotiation.
Pricing Analysis
Certification level under IEC 60601-1-3 and FDA 510(k) pathways creates the primary spread between premium spectral imaging configurations and standard digital radiography platforms. Three-tier pricing structure across premium, standard, and economy levels reflects detector substrate quality, software subscription bundling, and remote service integration depth. Pricing pressure stems from hospital purchasing cooperative consolidation demanding unbundled maintenance contracts and extended warranty terms. Independent diagnostic centers exhibit highest price sensitivity due to volume-based utilization economics, while academic medical centers prioritize spectral imaging capabilities with reduced dose documentation.
Supply Chain Analysis
Amorphous silicon substrate fabrication feeds from specialized semiconductor foundry capacity concentrated in Japan, South Korea, and Taiwan. Cadmium-zinc-telluride crystal growth for photon-counting arrays rests on germanium and tellurium sourcing from China and Belgium. Single-source vulnerability in flat-panel detector manufacturing exposes production schedules to foundry allocation constraints and export licensing delays. Distribution runs through regional hospital procurement committees and group purchasing organizations with multi-year fleet standardization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital capital equipment procurement is recovering from deferred replacement cycles, with analog fleet retirement creating predictable demand windows for digital platform vendors.
For Market Incumbents: Insulate recurring revenue streams by deepening software subscription attach rates and remote monitoring service penetration. Siemens Healthineers AG and GE Healthcare should accelerate tube replacement program enrollment to lock hospital procurement committees into multi-year service frameworks. Captive detector substrate production remains the critical lever against foundry allocation risk. For New Entrants and Emerging Players: Build out point-of-care portable system portfolios targeting urgent care and orthopedic clinic expansion in India and Southeast Asia. Outpatient clinic settings present the most penetrable segment due to lower certification barriers and faster procurement cycles. A software-first go-to-market angle emphasizing AI-assisted reconstruction differentiates against established hardware-centric vendors. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors component-integrated specialists with recurring service revenue density. Five-to-ten year viability hinges on photon-counting detector transition timing and software-as-medical-device regulatory navigation. Acquisition targets should demonstrate installed base scale in Germany or North American hospital networks. The signal to monitor is FDA 510(k) clearance velocity for AI reconstruction algorithms as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Compresses commercialization timelines for AI-enhanced diagnostic algorithms seeking hospital procurement inclusion. |
| CE Marking Pathway under EU MDR | Extends software lifecycle documentation obligations for manufacturers serving German hospital network contracts. |
| Hospital System Partnership | Secures multi-year fleet modernization agreements with bundled preventive maintenance and tube replacement programs. |
| Software Companion Development | Enables subscription revenue streams for remote monitoring and AI-assisted image reconstruction modules. |
| Reimbursement Strategy | Aligns dose reduction documentation with Medicare technical component incentives for digital radiography adoption. |
Research Approach
The analysis maps digital radiography, fluoroscopy, portable systems, and spectral imaging sub-sectors, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and medical physicists. Primary interview data combines with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement contract registries, and IEC standards documentation. Bottom-up equipment shipment modeling triangulates against top-down healthcare capital expenditure surveys.
Fixed assumptions include regulatory pathway timelines under FDA and EU MDR frameworks, tungsten supply concentration patterns, and hospital procurement cooperative consolidation trajectories. Variables span AI algorithm adoption velocity, photon-counting detector cost curves, and India PLI scheme localization incentives. CAGRs derive from replacement cycle compression analysis across analog-to-digital transitions and portable system penetration rates. Forecast inputs incorporate Medicare reimbursement code evolution and NMPA regulatory harmonization progress.
Sensitivities concentrate around tungsten supply disruption, EU MDR software documentation enforcement intensity, and hospital capital budget reallocation toward AI infrastructure. Forecasts reflect these documented assumptions with explicit scenario boundaries. Cross-checking against hospital procurement database benchmarks and medical device trade flow records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America IP Camera Market
Imaging
Digital X-Ray Technology Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Microscope Digital Cameras Market
Imaging
Digitizer Market
Imaging
High-Power Objective Lens Market
Imaging
Global Panoramic Camera Market
Imaging
Camera Technology Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
Computer Aided Detection Market
Imaging
Virtual Reality Camera Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Global Ingaas Camera Market
Imaging
Underwater Camera Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Pico Projector Market