
 China Electron Microscopy Market | 2026-2036
China Electron Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
China Electron Microscopy Market Insights
Direct sales channels for electron microscopy systems is tilting toward bundled service contracts and localized technical support networks. Thermo Fisher Scientific leverages its cryo-EM installed base to sustain recurring revenue from academic consortia. JEOL anchors its position through dedicated application centers in tier-one science cities. Carl Zeiss competes on correlative microscopy workflows that bridge light and electron imaging modalities.
Electron microscopy deploys accelerated electron beams to achieve sub-angstrom spatial resolution, with modern field-emission sources operating at voltages from 80 to 300 kV for materials and biological specimen analysis. Scanning electron microscopes occupy the largest installed base across Chinese industrial quality-control floors, while cryo-electron microscopes represent the fastest-expanding segment as structural biology programs multiply. Semiconductor inspection applications concentrate margin pools where tool throughput and defect-review speed determine foundry qualification timelines.
NMPA device registration rules and MIIT industrial equipment standards jointly shape import pathways and localization requirements for electron microscopy vendors. GB standards for electromagnetic compatibility and radiation safety constrain system design choices for instruments deployed in Chinese facilities. Stakeholders must monitor how dual carbon goals from MEE recalibrate energy-efficiency benchmarks for high-voltage electron source manufacturing.
Market Dynamics
Domestic semiconductor self-sufficiency mandates from MIIT are compressing qualification timelines for high-resolution inspection tools, forcing foundries to prioritize throughput over capital efficiency in electron microscopy procurement decisions.
Growth Catalysts
- MIIT Localization Targets:Domestic chip fabrication expansion in Shanghai and Beijing is accelerating demand for sub-nanometer defect review systems as import substitution policies tighten.
- Structural Biology Initiatives:National laboratory clusters in Hefei and Shenzhen are scaling cryo-electron microscopy infrastructure to support regional biotech park development.
- Field-Emission Source Advancement:Voltage-stabilized electron guns operating at 300 kV are extending resolution limits for materials characterization in battery research facilities.
Market Restraints
- Superconducting Lens Supply Concentration:Precision electromagnetic coil fabrication remains concentrated among specialized Japanese and German component suppliers, creating single-source vulnerability.
- GB Radiation Safety Compliance:Electromagnetic shielding requirements under national standards extend installation timelines and constrain facility siting options.
- Helium Cryogen Dependency:Cryo-EM operational continuity requires liquid helium supply chains vulnerable to price volatility and export control friction.
Strategic Opportunities
- Correlative Microscopy Workflows:Integration of light-sheet fluorescence with electron imaging is opening service contracts in pharmaceutical development centers.
- Western China Expansion:Underpenetrated Chengdu and Xi'an research corridors offer first-mover positioning as central government R&D funding redistributes inland.
- Dual Carbon Equipment Standards:MEE energy-efficiency benchmarks for high-voltage sources are creating upgrade cycles for legacy installed bases.
Industry Challenges
- Cryo-EM Specialist Shortage:Vitrification protocol expertise and computational image reconstruction skills outpace domestic training program output.
- NMPA Registration Timelines:Medical device classification for diagnostic electron microscopy extends commercialization pathways by 18-24 months.
- Legacy System Integration:Proprietary data formats from 1990s-era instruments obstruct workflow standardization in multi-vendor facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electron Microscopy Market |
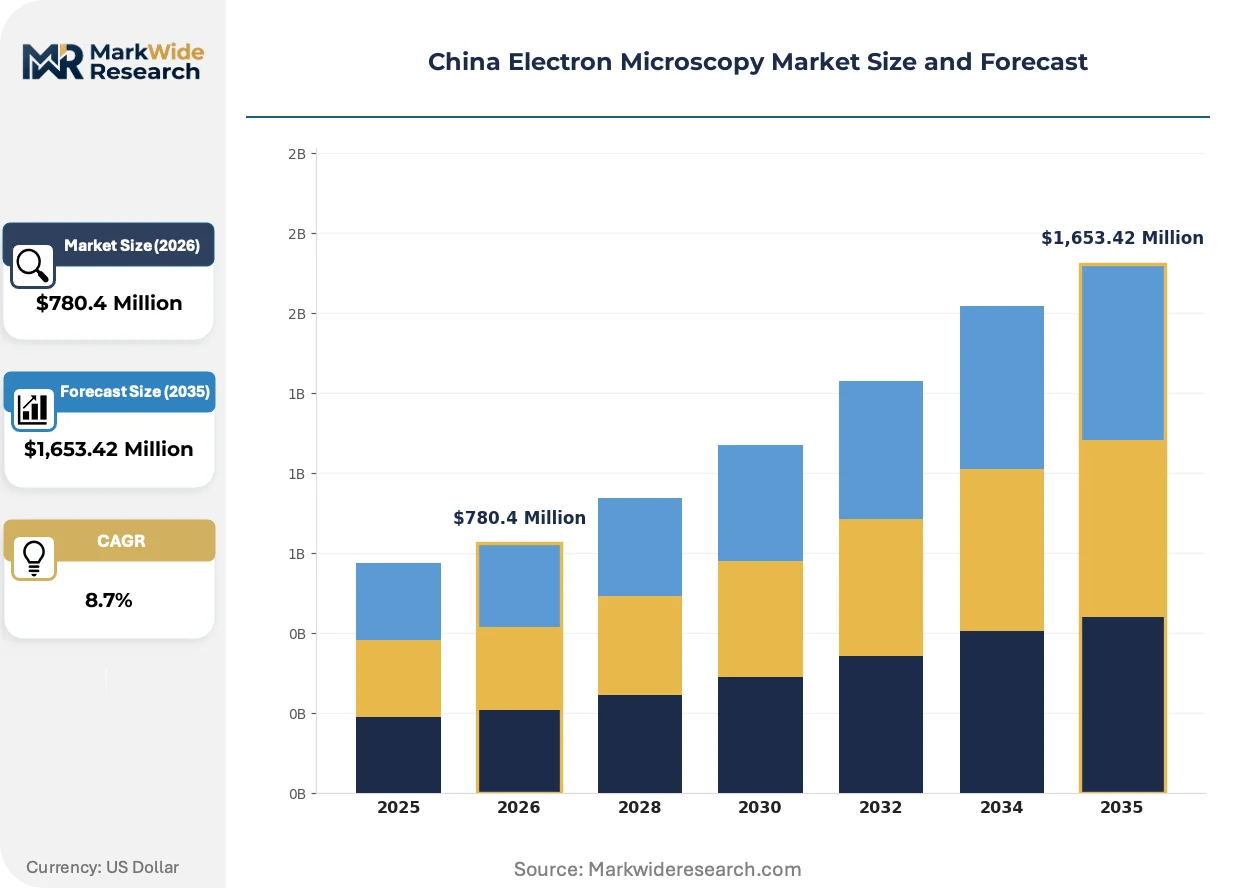
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,653.42 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Instrument Type: Transmission Electron Microscope, Scanning Electron Microscope, Scanning Transmission Electron Microscope, Cryo-Electron Microscope End User: Academic Research, Pharmaceutical Companies, Semiconductor Manufacturers, Material Science Laboratories Application: Nanotechnology, Biological Imaging, Material Characterization, Semiconductor Inspection Technology: Conventional Microscopy, High-Resolution Microscopy, Helium Ion Microscopy, X-ray Microanalysis |
| Companies Covered | Thermo Fisher Scientific, JEOL, Hitachi High-Tech, Carl Zeiss, Advantest Corporation, TESCAN Orsay Holding, Nikon Instruments, Oxford Instruments, Bioland Laboratory, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electron Microscopy Market Trends and Innovations
Electron microscopy architecture is fragmenting into specialized configurations as end-users reject general-purpose platforms in favor of application-optimized systems with embedded AI-assisted image analysis.
Direct electron detection sensors are hybridizing with complementary metal-oxide-semiconductor readout circuits to enable single-electron counting at frame rates exceeding 400 fps. Battery materials researchers at Tsinghua University and CAS institutes are adopting these hybridized detectors for in-situ lithiation studies. The convergence is compressing temporal resolution limits and displacing traditional CCD-based camera systems in dynamic process characterization.
MEE dual carbon implementation rules are recalibrating vacuum pump energy ratings and high-voltage power supply efficiency thresholds for electron source manufacturing. System vendors must redesign thermal management subsystems to meet new standby consumption limits. Semiconductor inspection applications face the steepest compliance costs due to continuous-operation duty cycles.
Academic consortia are consolidating procurement through shared-service facilities rather than individual laboratory ownership. Peking University and the Shenzhen Bay Laboratory operate joint cryo-EM centers with tiered access pricing. This pooling concentrates operator expertise and reduces per-sample costs for structural biology groups in tier-two cities.
China Electron Microscopy Market Segmentation
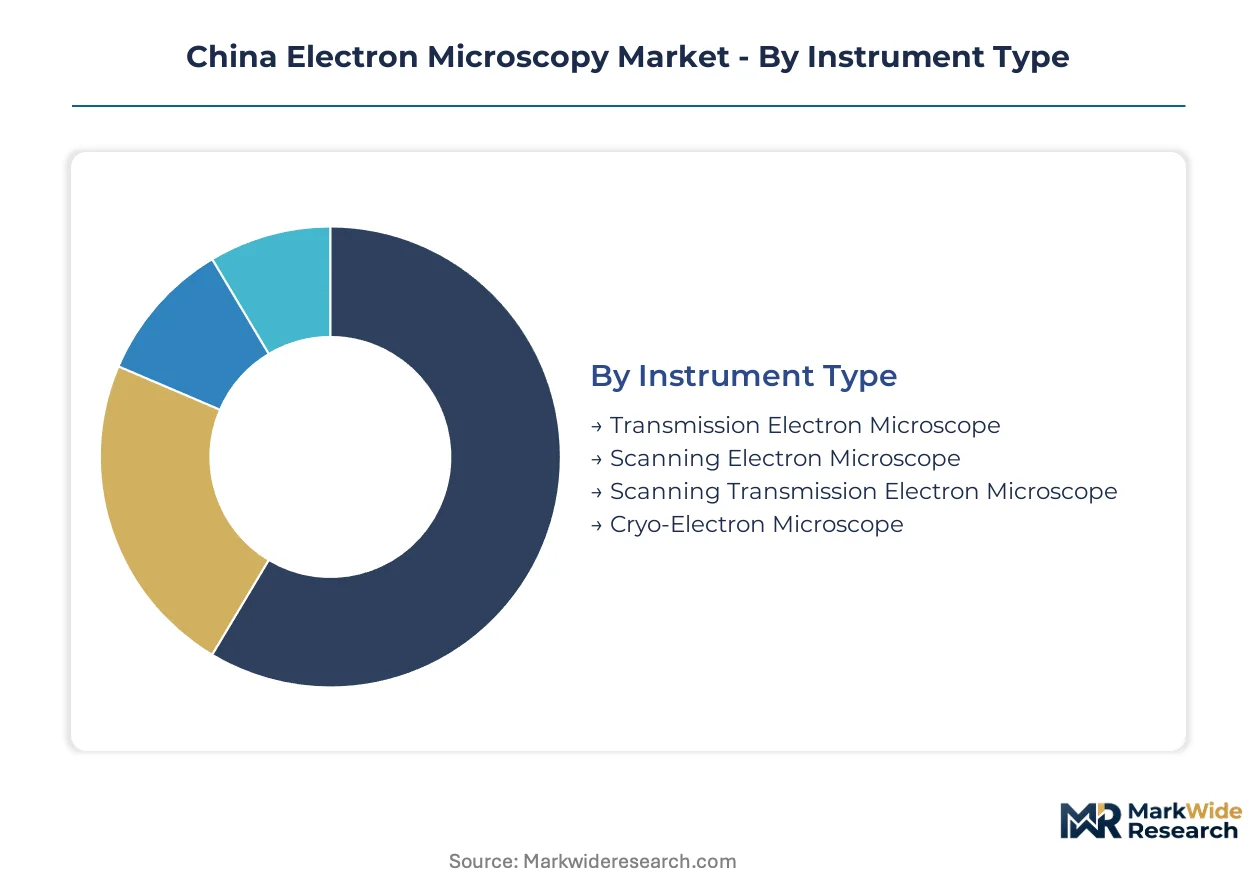
China's electron microscopy market fragments across instrument architectures, end-user sophistication, and application precision requirements. Each segmentation axis reveals distinct procurement patterns shaped by MIIT localization mandates and regional research infrastructure deployment.
Instrument Type:
The use-case spectrum spans routine industrial inspection to sub-angstrom structural biology, with voltage requirements and specimen preparation complexity determining facility investment priorities.
- Scanning Electron Microscope:Field-emission sources operating at 1-30 kV dominate quality-control floors across Shanghai and Suzhou semiconductor packaging houses. Foundries prioritize throughput metrics over resolution extremes as MIIT self-sufficiency targets compress qualification timelines.
- Cryo-Electron Microscope:Vitrification-compatible platforms with direct electron detectors anchor national laboratory clusters in Hefei and Shenzhen. Structural biology initiatives at CAS institutes drive procurement despite helium cryogen supply vulnerabilities and specialist training bottlenecks.
- Transmission Electron Microscope:200-300 kV systems serve battery materials research at Tsinghua University and CATL facilities.
- Scanning Transmission Electron Microscope:Aberration-corrected probes enable atomic-column imaging for semiconductor metrology.
Established volume favors Scanning Electron Microscope; emerging adoption favors Cryo-Electron Microscope.
End User:
Customer-type concentration varies sharply between state-funded research consortia and capital-constrained commercial laboratories, with procurement authority residing at different administrative levels.
- Semiconductor Manufacturers:SMIC and Hua Hong Semiconductor deploy high-resolution inspection tools under MIIT equipment localization guidelines. Defect-review speed determines foundry qualification timelines more than capital efficiency.
- Academic Research:Peking University and Shenzhen Bay Laboratory operate shared-service cryo-EM centers with tiered access pricing. Pooling concentrates operator expertise and reduces per-sample costs for structural biology groups in tier-two cities.
- Pharmaceutical Companies:WuXi AppTec and domestic biotechs adopt correlative microscopy for antibody characterization.
- Material Science Laboratories:CAS institutes prioritize in-situ TEM capabilities for battery lithiation studies.
Procurement scale concentrates with Semiconductor Manufacturers; facility expansion concentrates with Academic Research.
Application:
Application maturity correlates with regulatory pathway clarity—medical device registration under NMPA extends commercialization timelines for biological imaging relative to industrial metrology.
- Semiconductor Inspection:Sub-nanometer defect review systems face steepest MEE dual carbon compliance costs due to continuous-operation duty cycles. Vacuum pump energy ratings and high-voltage power supply efficiency thresholds force thermal management subsystem redesigns.
- Biological Imaging:Cryo-EM vitrification protocols and computational reconstruction skills outpace domestic training program output. NMPA medical device classification extends commercialization pathways by 18-24 months for diagnostic applications.
- Material Characterization:Battery research facilities adopt hybridized direct electron detectors for dynamic process characterization.
- Nanotechnology:GB electromagnetic compatibility standards constrain system design choices for instruments deployed in multi-vendor facilities.
Margin concentration aligns with Semiconductor Inspection; capability investment concentrates in Biological Imaging.
Technology:
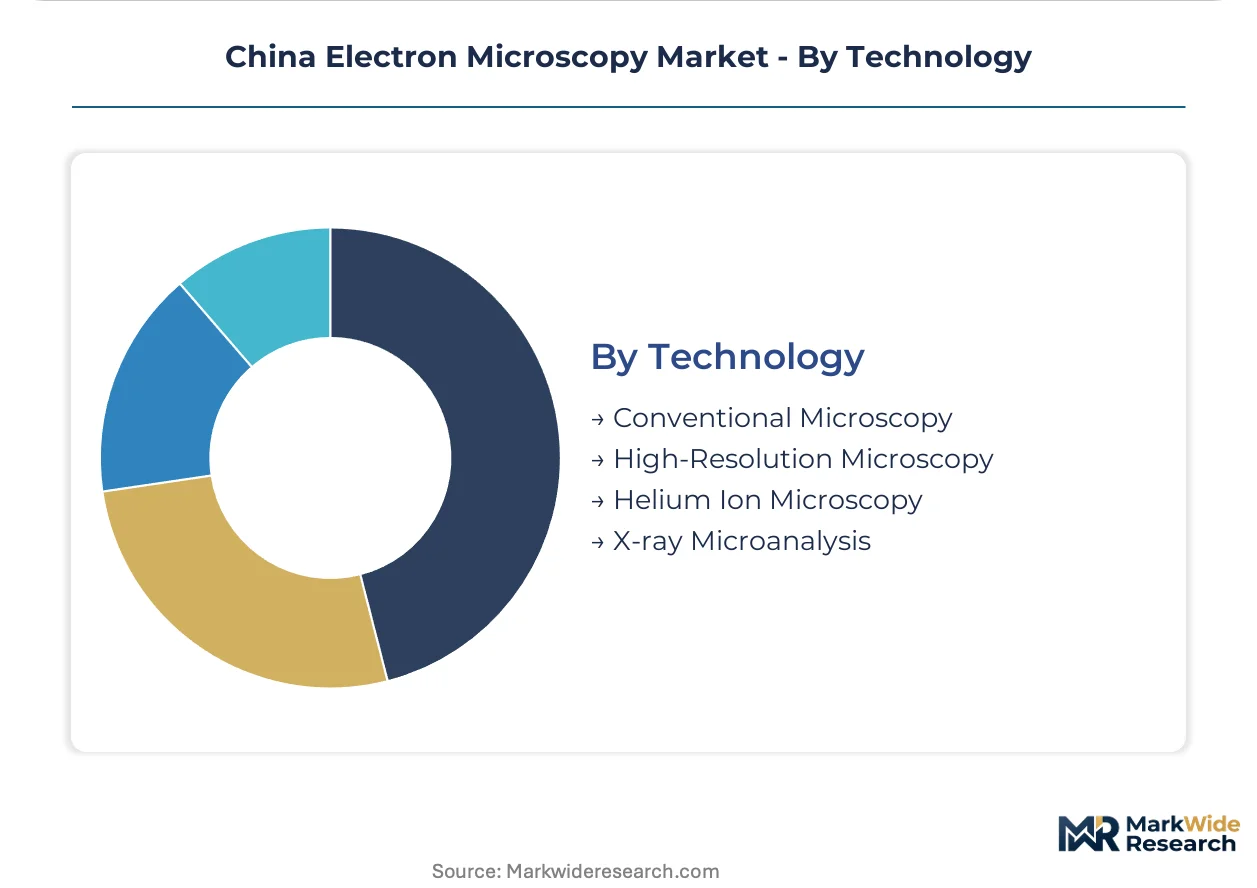
Technology tiering reflects a shift from general-purpose platforms toward application-optimized configurations with embedded AI-assisted image analysis.
- High-Resolution Microscopy:Aberration-corrected optics and monochromated electron sources extend information limits for materials characterization. Battery researchers at Tsinghua University adopt these platforms for in-situ lithiation studies.
- Conventional Microscopy:Tungsten filament and LaB6 source systems retain installed base across teaching laboratories and routine industrial QC. Cost constraints and legacy data format compatibility sustain demand despite displacement by field-emission alternatives.
- Helium Ion Microscopy:Sub-nanometer probe sizes enable surface imaging with secondary electron yield advantages for certain semiconductor metrology tasks.
- X-ray Microanalysis:Energy-dispersive spectrometer integration complements electron imaging for compositional mapping in failure analysis workflows.
Equipment refresh cycles favor High-Resolution Microscopy; installed base persistence favors Conventional Microscopy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai commands pricing premiums for high-resolution inspection systems while western provinces absorb cost-sensitive conventional microscopy deployments. This asymmetry reflects MIIT localization mandates concentrating advanced procurement in coastal semiconductor corridors. Provincial R&D funding disparities amplify the gap between tier-one science cities and inland research clusters.
Yangtze River Delta
Shanghai and Suzhou semiconductor packaging houses drive field-emission SEM procurement for quality-control floors. MIIT equipment localization guidelines compress qualification timelines for sub-nanometer defect review tools. Foundries prioritize throughput metrics over capital efficiency as domestic chip self-sufficiency targets tighten.
Pearl River Delta
Shenzhen biotech parks and national laboratory clusters scale cryo-EM infrastructure for structural biology initiatives. NMPA medical device registration rules extend commercialization pathways for diagnostic electron microscopy applications. CAS institutes in Guangzhou adopt correlative microscopy workflows for antibody characterization.
Beijing-Tianjin-Hebei
Tsinghua University and Peking University anchor battery materials research with 300 kV TEM systems for in-situ lithiation studies. MEE dual carbon goals recalibrate energy-efficiency benchmarks for high-voltage electron source manufacturing. Shared-service cryo-EM centers concentrate operator expertise through tiered access pricing models.
Sichuan-Chongqing
Chengdu research corridors offer underpenetrated positioning as central government R&D funding redistributes inland. GB electromagnetic compatibility standards constrain system design choices for multi-vendor facilities. Western China expansion targets material science laboratories seeking cost-advantaged infrastructure.
Anhui Province
Hefei national laboratory clusters concentrate cryo-electron microscopy demand driven by structural biology programs. Helium cryogen supply vulnerabilities and specialist training bottlenecks limit operational scale despite facility investment. Regional biotech park development depends on shared-service models to reduce per-sample costs.
China Electron Microscopy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electromagnetic lens and detector fabrication. The vendor base concentrates around four archetypes: full-system multinationals with cryo-EM installed bases, dedicated application center operators, correlative microscopy workflow providers, and precision component fabricators from Japan and Germany. Dominant competitive moves include strategic partnerships for localized technical support networks and portfolio diversification into bundled service contracts.
Among full-system providers, Thermo Fisher Scientific and JEOL exemplify contrasting geographic anchoring strategies. Thermo Fisher leverages recurring revenue from academic consortia through its cryo-EM installed base. JEOL anchors position through dedicated application centers in tier-one science cities. Carl Zeiss occupies a position on correlative microscopy workflows bridging light and electron imaging modalities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| JEOL |
| Hitachi High-Tech |
| Carl Zeiss |
| Advantest Corporation |
| TESCAN Orsay Holding |
| Nikon Instruments |
| Oxford Instruments |
| Bioland Laboratory |
| Others |
Pricing and Supply Chain Analysis
Helium cryogen supply volatility determines both the premium spread for cryo-EM service contracts and the geographic clustering of maintenance infrastructure around coastal import hubs. MIIT localization mandates compound this by forcing foundries to absorb qualification-cost premiums for sub-nanometer inspection tools while constraining alternative sourcing pathways.
Pricing Analysis
Configured-to-order pricing for aberration-corrected systems commands substantial premiums over standard field-emission SEM configurations. Three-tier pricing structure across premium, standard, and economy levels separates helium-cooled cryo-EM platforms from air-cooled teaching instruments and legacy tungsten-filament QC systems. Price differentiation centers on detector resolution grade and MIIT equipment certification tier. Cost compression in the standard tier is intensifying because foundries prioritize throughput metrics over capital efficiency under domestic chip self-sufficiency targets. Academic consortia exhibit highest price sensitivity due to shared-service pooling models, while semiconductor manufacturers demonstrate lowest sensitivity given qualification-timeline pressures.
Supply Chain Analysis
Export-control friction around precision electromagnetic coil fabrication limits flows from specialized Japanese and German component suppliers. Superconducting lens assemblies draw from Japan, direct electron detectors from the Netherlands and USA, and field-emission source materials from Germany. Raw material dependencies encompass high-purity copper for coil windings, rare-earth ceramics for magnetic circuits, and liquid helium for cryogenic cooling. Single-source vulnerability concentrates in aberration-correction controller modules. Distribution runs through authorized technical service networks anchored in Shanghai and Beijing, with secondary spare-part depots in Shenzhen and Hefei.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application-optimized configurations creates niches as end-users reject general-purpose platforms in favor of embedded AI-assisted imaging systems. This demand-side specialization opens positioning opportunities for focused technology providers.
For Market Incumbents: Pre-empt specialist training bottlenecks by embedding vitrification protocol expertise into application-center staffing models. Establish captive supply arrangements for superconducting lens assemblies to mitigate Japanese supplier concentration risk. Prioritize certification investment for NMPA medical device pathways to compress 18-24 month commercialization timelines for diagnostic applications.
For New Entrants and Emerging Players: Pursue correlative microscopy workflow integration as the most penetrable white-space target, specifically light-sheet fluorescence bridging for pharmaceutical development centers. Target Chengdu and Xi'an research corridors where central government R&D funding redistribution creates first-mover positioning. Deploy subscription-based service contracts with localized technical support as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at an equipment-refresh phase that favors component specialists with aberration-correction IP. Long-term viability across the five-to-ten year window hinges on MEE dual carbon compliance capabilities for high-voltage source manufacturing. Acquisition targets should demonstrate embedded AI-assisted image analysis development pipelines. The signal to watch is helium cryogen price volatility as an inflection indicator for cryo-EM operational cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Application Center Expansion | JEOL's tier-one science city anchoring model concentrates operator expertise and reduces per-sample service costs. |
| Correlative Microscopy Integration | Carl Zeiss bridges light and electron imaging modalities for antibody characterization at WuXi AppTec facilities. |
| Helium Recovery System Deployment | Cryo-EM centers in Hefei mitigate supply vulnerabilities through closed-loop liquefaction infrastructure investment. |
| AI-Assisted Image Analysis Embedding | Thermo Fisher sustains recurring revenue from academic consortia through automated reconstruction software subscriptions. |
| Western China Technical Service Network | Underpenetrated Chengdu corridors absorb cost-sensitive deployments as MIIT funding redistributes inland. |
Research Methodology
The analysis maps scanning electron microscope, cryo-electron microscope, transmission electron microscope, and scanning transmission electron microscope segments, each validated through procurement directors at semiconductor foundries, facility managers at national laboratory clusters, and application scientists at CAS institutes. Primary interviews with equipment localization officers at MIIT, NMPA regulatory affairs leads, and technical service heads at multinational vendors combined with secondary validation from customs import records, GB standards documentation, and MEE dual carbon implementation notices. Bottom-up instrument shipment tracking and top-down R&D expenditure triangulation anchored market sizing.
Assumptions held MIIT localization targets and NMPA registration timelines fixed while varying helium supply price scenarios and export-control friction intensity across the projection horizon. Segmentation dimensions encompassed instrument architecture, end-user sophistication tier, application precision requirements, and regional infrastructure maturity. CAGRs derived from equipment replacement cycle analysis and research funding allocation trajectories. Industry-specific forecast inputs included foundry qualification timeline compression rates and cryo-EM specialist training program output curves.
Sensitivities concentrate around helium cryogen export restrictions, superconducting lens supply disruptions, and MEE energy-efficiency benchmark revisions. Forecasts reflect documented assumptions regarding MIIT policy continuity and NMPA pathway stability. Cross-checking against CAS institute capital expenditure disclosures and SMIC equipment procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Video Processing Solutions Market
Imaging
Photoacoustic Imaging Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Webcam Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Holographic Imaging Market
Imaging
PET Imaging Systems Market
Imaging
Microscope Digital Cameras Market
Imaging
In Vivo Imaging Systems Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Low-Light Imaging Market
Imaging
Vision Processing Unit Market
Imaging
Handheld Imager Market
Imaging
Global Digital Photo Frame Market
Imaging
Virtual Reality Camera Market
Imaging
Uncooled Infrared Imaging Market