
 Vitamin Premix Market | 2026-2036
Vitamin Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Premix Market Outlook
Formulation chemist talent is rotating toward precision nutrition roles faster than universities can replenish pipelines, tightening R&D bandwidth across the industry. DSM-Firmenich leverages its integrated carotenoid and vitamin operations to lock in raw material security for high-specification animal nutrition clients. Glanbia PLC sustains competitive position through dedicated premix facilities serving dairy and sports nutrition end users. BASF SE anchors European supply with backward integration into citric acid and vitamin A intermediates.
Vitamin premix denotes a homogeneous blend of two or more vitamins, often combined with carriers, minerals, and excipients, manufactured through sequential dry mixing or spray-drying to achieve uniform potency distribution per gram. These formulations serve as standardized nutrient inputs across feed milling, dietary supplement tableting, and food fortification lines where manual dosing would introduce hazardous variability. Powdered Mix occupies the dominant volume position due to mechanical stability in pneumatic feed mill conveyance and lower moisture sensitivity during tropical storage. Liquid Blend is gaining fastest in aquaculture and young animal diets where palatability enhancement and reduced dust generation justify higher per-unit cost. The Pharmaceutical application segment commands the steepest margin pool, driven by USP-grade certification requirements and batch-level CoA documentation that few compounders can reliably deliver.
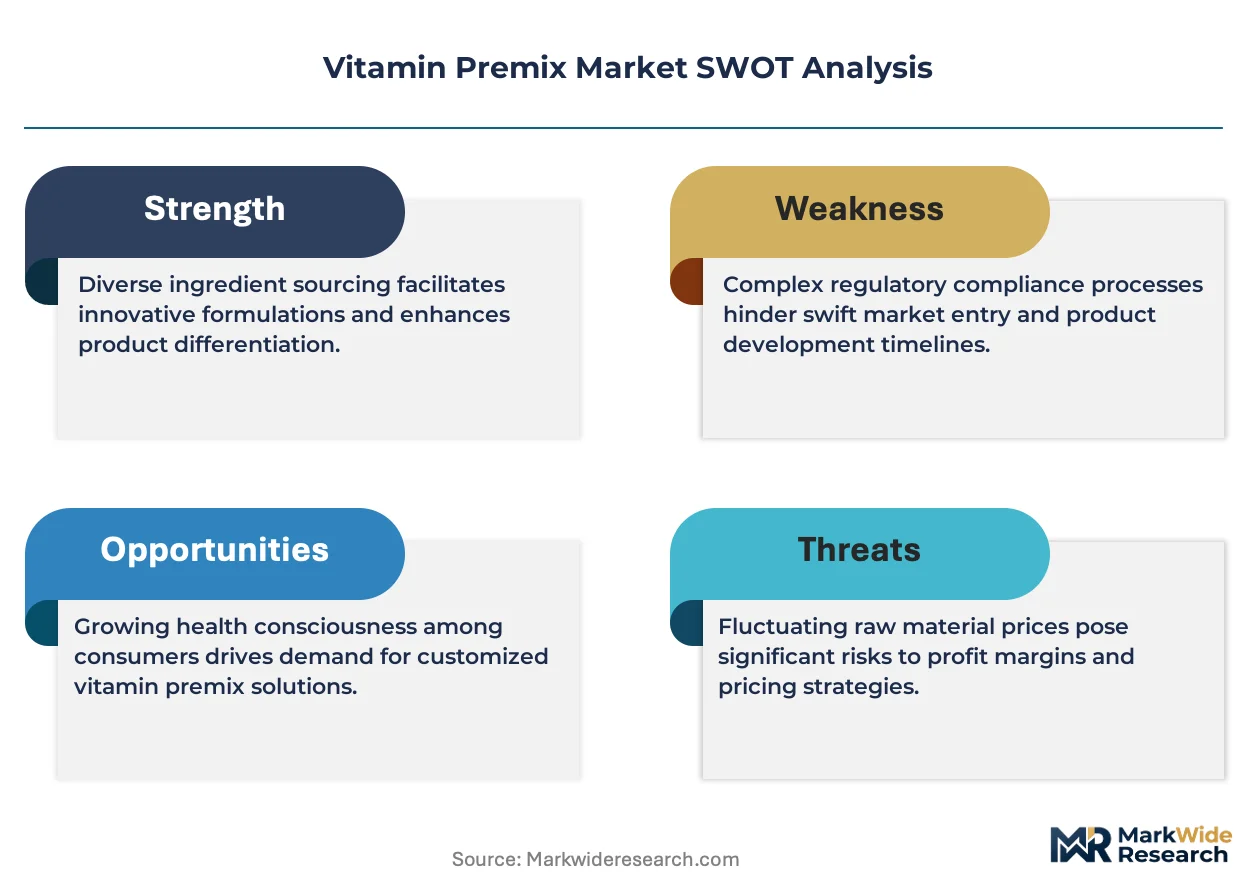
FDA oversight of dietary supplement cGMPs and the EU's Feed Hygiene Regulation jointly elevate barrier costs for new premix entrants, while FSSAI's tightened micronutrient labeling in India redirects demand toward certified suppliers with in-house analytical laboratories. The EU Green Deal's emerging feed sustainability criteria will likely extend carbon footprint disclosure requirements upstream to vitamin synthesis and formulation. Stakeholders must monitor how regulatory divergence between North American and European contaminant thresholds reshapes contract manufacturing location decisions.
Market Dynamics
The Vitamin Premix Market is being fundamentally restructured by feed mill consolidation in Southeast Asia and Brazil, where integrators are internalizing formulation capabilities to bypass merchant premix suppliers and capture margin previously held by compounders.
Growth Catalysts
- EU Feed Additives Regulation:Tightening purity mandates for imported premix formulations are redirecting procurement toward certified European compounders with in-house analytical validation.
- Aquaculture expansion:Southeast Asian shrimp and finfish operations are adopting liquid vitamin blends to improve bioavailability in high-density pond systems.
- Precision nutrition platforms:Real-time feed formulation software is enabling customized premix dosing at the batch level, reducing overfortification waste.
Market Restraints
- Retinol intermediate concentration:BASF SE and DSM-Firmenich control over 70% of citric acid and vitamin A precursor supply, creating single-source vulnerability for mid-tier formulators.
- FDA cGMP compliance costs:Dietary supplement-grade certification requires batch-level CoA documentation that excludes smaller compounders from pharmaceutical-margin pools.
- Spray-drying energy intensity:Natural gas price volatility in European manufacturing clusters is compressing margins for powder premix producers.
Strategic Opportunities
- FSSAI micronutrient labeling:India's tightened fortification disclosure rules are redirecting food and feed demand toward certified suppliers with accredited laboratories.
- Carbon footprint traceability:EU Green Deal emerging criteria will reward premix producers with verified upstream synthesis emissions data.
- Young animal nutrition:Palatability-optimized liquid blends for piglet and broiler starter feeds command 40-60% price premiums over standard powder formulations.
Industry Challenges
- Formulation chemist scarcity:Universities are failing to replenish precision nutrition R&D pipelines faster than talent rotates toward biotech and pharma roles.
- Multi-jurisdiction certification timelines:Simultaneous USP, EP, and FSSAI validation requires 18-24 month approval cycles that freeze product launch schedules.
- Legacy feed mill pneumatic systems:Mechanical conveying infrastructure in Southeast Asian facilities limits adoption of moisture-sensitive high-potency premix grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Premix Market |
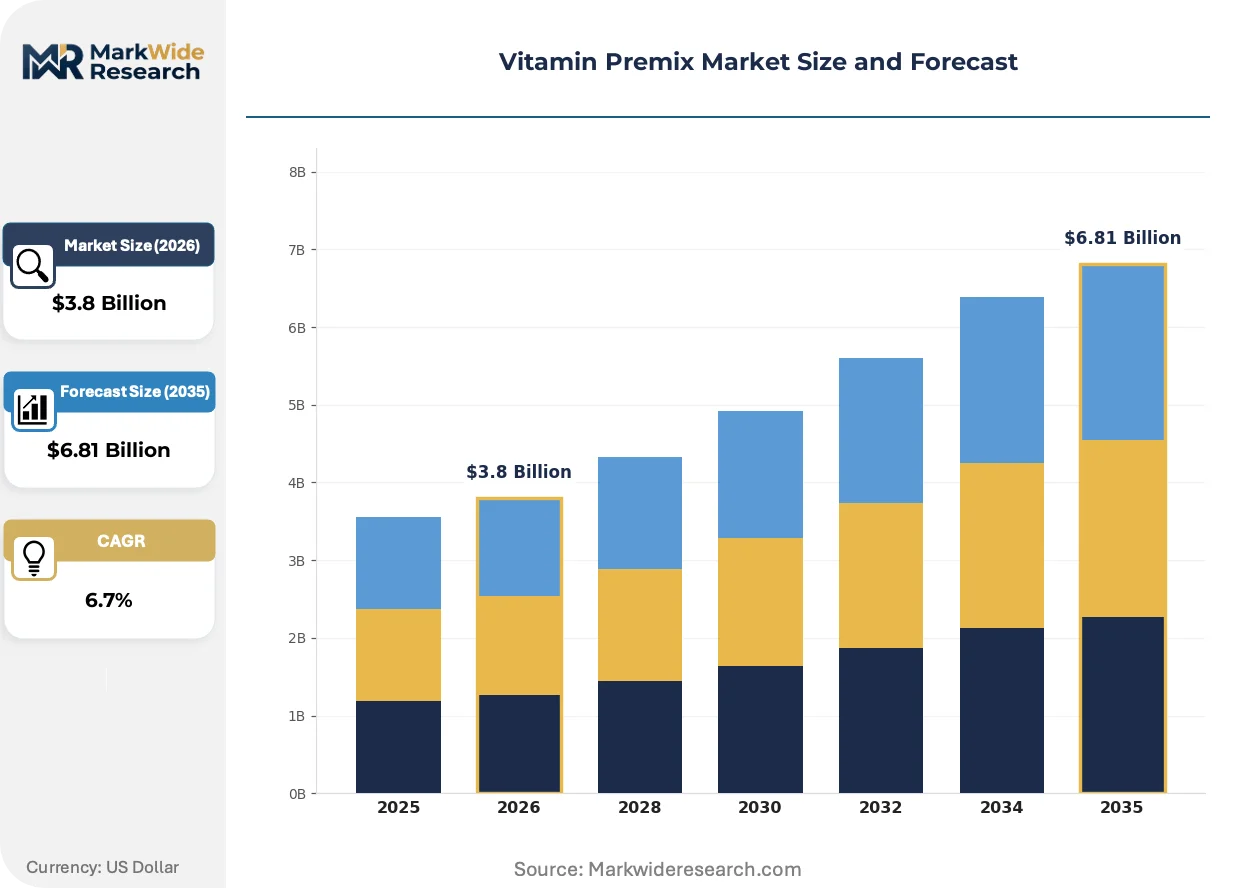
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Mix, Liquid Blend, Granulated Form, Tablets Application: Animal Feed, Nutritional Supplements, Food Industry, Pharmaceuticals End User: Agriculture, Healthcare, Food Manufacturers, Contract Manufacturers Distribution Channel: Online Retail, Distributors, Direct Sales, Bulk Suppliers |
| Companies Covered | DSM-Firmenich, Glanbia PLC, BASF SE, SternVitamin GmbH & Co. KG, Archer Daniels Midland Company, Corbion, Barentz International, Vitablend Nederland B.V., Prinova Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Premix Market Strategic Shifts
Encapsulation technologies and digital formulation platforms are converging to redefine how vitamin stability, bioavailability, and customization get delivered across feed, food, and pharmaceutical channels.
Microencapsulation using lipid matrices and cross-linked alginate shells is displacing conventional spray-dried powders in aquaculture and young animal applications. Thai and Vietnamese shrimp producers are adopting these formats at scale to prevent leaching in pond water. The technology is displacing commodity premix suppliers who lack pharmaceutical-grade encapsulation capability.
REACH and the EU Green Deal are jointly mandating upstream carbon disclosure for vitamin synthesis and formulation operations. German and Dutch compounders are deploying blockchain-tracked supply chain audits to document Scope 3 emissions from citric acid and carotenoid precursors. Pharmaceutical application segments face the steepest compliance burden, with batch-level sustainability certification now required for EU contract manufacturing eligibility.
Integrators in Brazil's poultry belt are consolidating vitamin procurement through captive premix facilities rather than merchant suppliers. JBS and BRF are building dedicated formulation plants in Paraná and Santa Catarina to secure supply chain stability against raw material volatility. This behavior is most visible in the southeastern states, where vertical control over retinol and tocopherol sourcing has become a competitive priority.
Vitamin Premix Market Segmentation
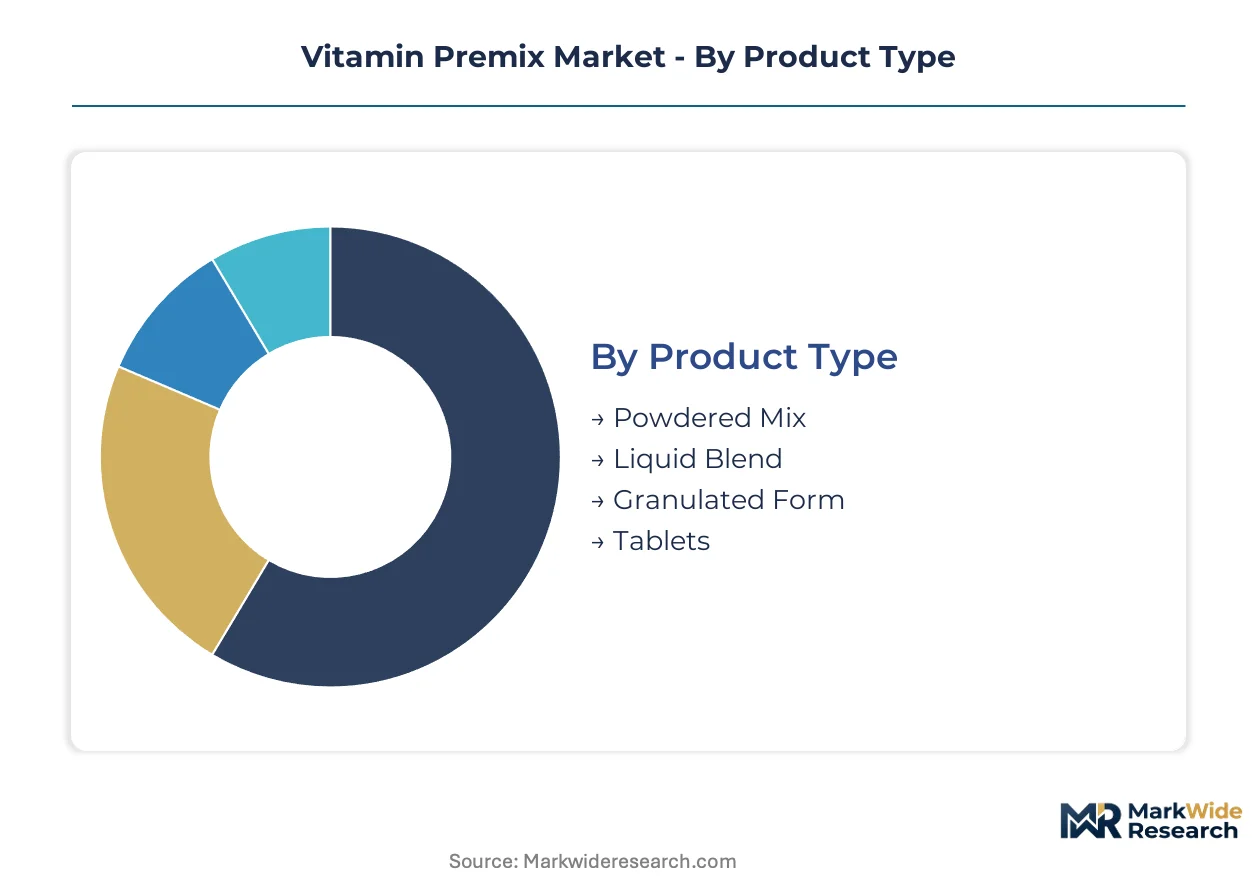
Vitamin premix segmentation reveals how formulation formats, application channels, and procurement pathways fragment value capture across feed milling, pharmaceutical compounding, and direct-to-manufacturer supply. Understanding these divisions exposes where margin pools concentrate and which customer configurations reward specialized capabilities over commodity supply.
Product Type:
Powdered Mix anchors domestic feed mill supply across Brazil's poultry belt and Southeast Asian livestock operations, while Liquid Blend pulls export-oriented aquaculture demand from Vietnamese shrimp integrators.
- Powdered Mix:Homogeneous dry blends achieve uniform potency distribution through sequential mixing or spray-drying, with mechanical stability optimized for pneumatic conveyance in tropical feed mills. Demand clusters in Brazil's vertically integrated poultry operations where JBS and BRF internalize procurement to bypass merchant suppliers and secure retinol supply chain stability.
- Liquid Blend:Oil-suspended or aqueous vitamin dispersions enhance palatability and reduce dust generation in young animal diets. Vietnamese and Thai shrimp producers are adopting these formats at scale to prevent nutrient leaching in high-density pond systems, commanding 40-60% price premiums over standard powders.
- Granulated Form:Agglomerated particles with controlled dissolution profiles serve pharmaceutical tableting lines requiring USP-grade flow characteristics.
- Tablets:Compressed single- or multi-vitamin units target dietary supplement channels with dose-precision requirements that powder premixes cannot satisfy.
Powdered Mix commands the established base. The steepest expansion runs through Liquid Blend.
Application:
Cost tier stratification separates commodity feed fortification from pharmaceutical-margin certification requirements, with nutritional supplements occupying a contested middle ground.
- Animal Feed:Standardized nutrient inputs for livestock and aquaculture operations where manual dosing would introduce hazardous variability. Brazil's integrators are consolidating procurement through captive premix facilities in Paraná and Santa Catarina to verticalize control over vitamin sourcing.
- Pharmaceuticals:USP-grade formulations with batch-level Certificate of Analysis documentation that excludes smaller compounders from the steepest margin pools. FDA cGMP compliance and EU Feed Additives Regulation purity mandates jointly elevate barrier costs for new entrants.
- Nutritional Supplements:Dietary fortification for human consumption bridging food-grade and pharmaceutical specification boundaries.
- Food Industry:Micronutrient enrichment of processed foods subject to FSSAI labeling requirements in India that redirect demand toward certified suppliers with in-house analytical laboratories.
Animal Feed absorbs the dominant volume. Pharmaceuticals capture the highest margin per kilogram.
End User:
Customer type determines whether procurement flows through specification-driven contract relationships or price-sensitive spot purchasing.
- Agriculture:Livestock producers and aquaculture operations across Southeast Asia expanding fortified feed programs to improve animal health outcomes. These end users prioritize supply security over formulation flexibility, driving integrator verticalization.
- Contract Manufacturers:Third-party compounders serving multiple brand owners with multi-jurisdiction certification requirements. Simultaneous USP, EP, and FSSAI validation demands 18-24 month approval cycles that freeze product launch schedules.
- Healthcare:Hospitals, clinics, and clinical nutrition providers with patient-specific dosing protocols.
- Food Manufacturers:Processed food producers integrating micronutrient fortification into production lines.
Agriculture represents the volume anchor. Contract Manufacturers face the most complex compliance burden.
Distribution Channel:
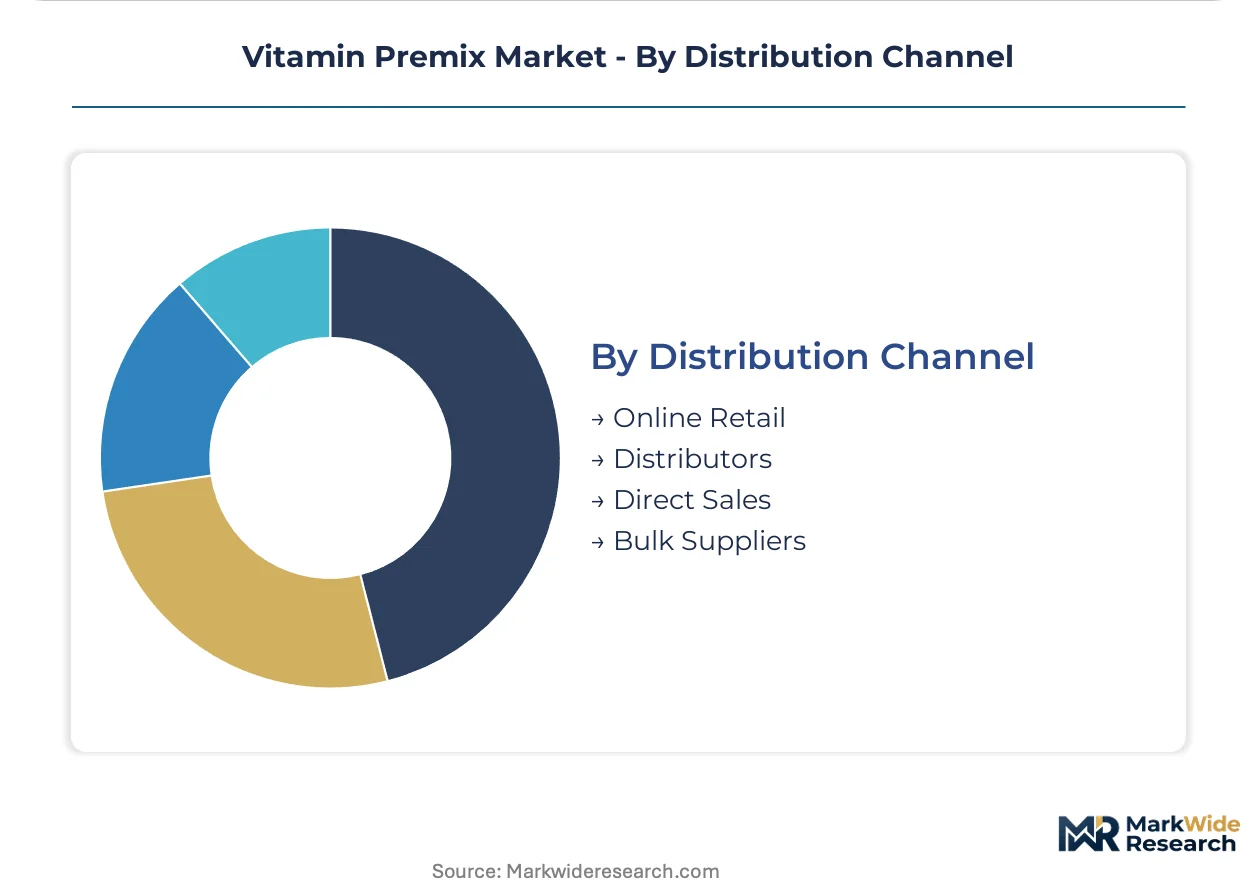
Supply concentration varies by channel, with direct sales capturing integrator accounts and distributors serving fragmented mid-tier formulators.
- Direct Sales:Manufacturer-to-end-user relationships dominating large-scale feed mill and pharmaceutical accounts. DSM-Firmenich and BASF SE leverage backward integration into citric acid and vitamin A intermediates to lock in raw material security for direct clients.
- Distributors:Regional stockists serving compounders lacking volume scale for direct procurement. These intermediaries absorb inventory risk but compress margins for premix suppliers competing on specification breadth.
- Bulk Suppliers:Volume-focused traders moving commodity-grade premixes with minimal technical support.
- Online Retail:E-commerce platforms emerging for small-lot dietary supplement and specialty feed ingredient procurement.
Direct Sales locks in the largest accounts. Distributors retain relevance for geographic coverage in fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP oversight anchors North American pharmaceutical-grade demand, while EU Green Deal carbon disclosure requirements and FSSAI fortification mandates reshape procurement patterns across their respective jurisdictions.
United States
Dietary supplement manufacturers drive USP-grade vitamin premix consumption through FDA-registered cGMP facilities. The agency's batch-level Certificate of Analysis requirements exclude smaller compounders from pharmaceutical-margin pools. New Jersey and North Carolina pharmaceutical corridors concentrate contract manufacturing capacity serving domestic and export markets.
Germany
REACH chemical registration and emerging EU Green Deal feed sustainability criteria elevate compliance costs for vitamin synthesis operations. ECHA documentation requirements for citric acid and carotenoid precursors favor compounders with integrated analytical laboratories. BASF SE's Ludwigshafen complex anchors European vitamin A intermediate supply.
Brazil
Integrators in Paraná and Santa Catarina are consolidating vitamin procurement through captive premix facilities rather than merchant suppliers. ANVISA feed additive registration timelines influence formulation sourcing decisions. JBS and BRF verticalization strategies in the southeastern poultry belt secure retinol and tocopherol supply chain stability.
India
FSSAI's tightened micronutrient labeling redirects food and feed demand toward certified suppliers with in-house analytical laboratories. CDSCO pharmaceutical-grade certification requirements segment the market between compounders and commodity traders. Maharashtra and Gujarat industrial clusters concentrate premix formulation capacity serving domestic fortification programs.
Vietnam
Shrimp and finfish aquaculture operations adopt liquid vitamin blends to improve bioavailability in high-density pond systems. The country's national feed regulator enforces import purity standards that favor accredited suppliers. Mekong Delta processing zones concentrate aquaculture feed milling capacity demanding moisture-stable nutrient inputs.
Vitamin Premix Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in vitamin premix supply. BASF SE and DSM-Firmenich control upstream citric acid and vitamin A precursor production, locking in raw material security. Mid-tier compounders compete on specification breadth and multi-jurisdiction certification speed. Strategic moves concentrate on backward integration into vitamin synthesis and geographic expansion into Southeast Asian feed mill clusters.
Among European-integrated chemical conglomerates, BASF SE and DSM-Firmenich exemplify the upstream-control archetype through citric acid and carotenoid operations. SternVitamin GmbH & Co. KG represents the specialist compounder model focused on custom formulation services. These three occupy positions spanning integrated synthesis, merchant premix supply, and technical specification expertise.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Glanbia PLC |
| BASF SE |
| SternVitamin GmbH & Co. KG |
| Archer Daniels Midland Company |
| Corbion |
| Barentz International |
| Vitablend Nederland B.V. |
| Prinova Group LLC |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at BASF SE's Ludwigshafen vitamin A intermediate complex shapes both European supply concentration and global price floors for retinol-dependent formulations. Scale economies in citric acid and carotenoid precursor production lock in cost advantages that mid-tier compounders cannot replicate, compressing margins for merchant premix suppliers across Brazil and Southeast Asia.
Pricing Analysis
Geographic price spreads between German pharmaceutical-grade formulations and Brazilian commodity feed premixes exceed three-to-one ratios. Three-tier pricing structure across USP-certified, food-grade, and feed-grade specifications drives differentiation, with FDA cGMP batch documentation commanding steepest premiums. Cost compression in standard powder formulations is intensifying because natural gas volatility in European spray-drying clusters erodes producer margins. Contract manufacturers exhibit highest price sensitivity due to multi-jurisdiction certification burdens, while captive integrator facilities in Paraná and Santa Catarina prioritize supply security over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor European vitamin synthesis and compounding capacity for pharmaceutical and feed additive applications. Production draws from citric acid intermediates, carotenoid precursors, and lipid matrix encapsulation materials as critical inputs. Single-source vulnerability concentrates in retinol precursor supply, where BASF SE and DSM-Firmenich control over seventy percent of upstream capacity. Distribution runs through direct manufacturer relationships with large integrators and pharmaceutical compounders, with regional distributors serving fragmented mid-tier formulators lacking volume scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon disclosure mandates and FSSAI fortification labeling are accelerating procurement consolidation toward certified suppliers with integrated analytical capabilities. This regulatory inflection compresses timelines for capability building across formulation, validation, and traceability systems.
For Market Incumbents: Fortify upstream control over citric acid and vitamin A intermediate supply through captive production or long-term offtake agreements with Ludwigshafen and Basel-based synthesis operations. Expand in-house analytical laboratory accreditation to capture FSSAI-redirected demand in India. Prioritize certification investment for simultaneous USP, EP, and FSSAI validation to freeze out mid-tier compounders facing eighteen-to-twenty-four month approval cycles.
For New Entrants and Emerging Players: Precision nutrition software integration gaps in Southeast Asian feed mill operations offer service-layer entry points where incumbents under-serve. Target Vietnamese and Thai aquaculture integrators adopting liquid vitamin blends for high-density shrimp pond systems. Pursue encapsulation technology partnerships with pharmaceutical-grade lipid matrix suppliers to bypass commodity powder competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with verified Scope 3 emissions data and blockchain-tracked supply chain audits. Long-term viability across the five-to-ten year window rests on backward integration depth and multi-jurisdiction certification speed. Watch for EU Green Deal feed sustainability criteria extension as the inflection signal triggering accelerated consolidation among merchant premix suppliers lacking carbon disclosure infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Synthesis | Captive retinol precursor production locks in raw material security against BASF SE and DSM-Firmenich supply dominance. |
| Encapsulation Technology Licensing | Pharmaceutical-grade lipid matrix capability opens aquaculture and young animal nutrition premium segments. |
| Multi-Jurisdiction Certification Investment | Simultaneous USP, EP, and FSSAI validation accelerates product launch timelines for contract manufacturing clients. |
| Blockchain Supply Chain Auditing | Verified Scope 3 emissions documentation satisfies EU Green Deal eligibility for pharmaceutical contract manufacturing. |
| Direct Sales Force Expansion in Southeast Asia | Manufacturer-to-integrator relationships bypass distributor margins in Vietnam and Thailand aquaculture clusters. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this vitamin premix analysis. Conversations with formulation chemists, feed mill procurement directors, pharmaceutical contract manufacturing executives, and FSSAI compliance officers combined with FDA cGMP guidance documents, ECHA REACH registration databases, EU Feed Additives Regulation purity mandates, and ANVISA feed additive registration timelines. Bottom-up segmentation modeling triangulates against top-down trade flow analysis from customs records and industrial cluster production surveys.
Sensitivity analysis across feed grade, food grade, and pharmaceutical grade specifications tests forecast robustness over the projection horizon. Segmentation dimensions include product format, application channel, end user type, and geographic procurement cluster. CAGRs derive from annualized growth rate fitting across historical volume trajectories and forward-looking capacity expansion announcements. Industry-specific inputs incorporate natural gas price volatility effects on European spray-drying economics and integrator verticalization trends in Brazil's southeastern poultry belt.
Material uncertainties — regulatory divergence between FDA and EU contaminant thresholds, formulation chemist talent pipeline depletion, and retinol intermediate supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and carbon disclosure mandate implementation pacing. Recalibration cycles align with material shifts in EU Green Deal criteria finalization and FSSAI enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Global Vitamins Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Vitamin B12 Drops Market