
 Calcium Market | 2026-2036
Calcium Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Market Intelligence
The European Union's REACH regulation is realigning the cost-of-entry calculus for calcium compound suppliers by mandating extensive chemical safety assessments. Minerals Technologies Inc. leverages its specialized portfolio of precipitated calcium carbonates to meet stringent pharmaceutical and food-grade specifications. In parallel, Omya AG sustains its market position through large-scale production capabilities and a global distribution network. Solvay competes on the basis of high-purity synthetic calcium carbonate grades for specialized applications.
Calcium is an alkaline earth metal, but commercially it is primarily traded as compounds like calcium carbonate, derived from sources such as limestone, marble, or chalk. These compounds serve as essential nutrients in food and pharmaceuticals, functional fillers in plastics and paper, and pH regulators in industrial processes. Calcium carbonate products dominate the market by volume for industrial uses, while higher-purity calcium citrate and gluconate command premium pricing in the dietary supplements segment. The pharmaceutical and food & beverage end-user segments exhibit the most stringent quality demands, influencing sourcing and production standards.
Regulatory frameworks from the U.S. FDA, the European Food Safety Authority (EFSA), and the Food Safety and Standards Authority of India (FSSAI) govern calcium's use as a food additive and fortificant. These bodies set purity standards, define acceptable daily intakes, and mandate labeling for nutritional content, directly shaping market access and product formulation. Future competitive advantage will hinge on a supplier's ability to document product traceability and consistently meet evolving purity monographs across multiple jurisdictions.
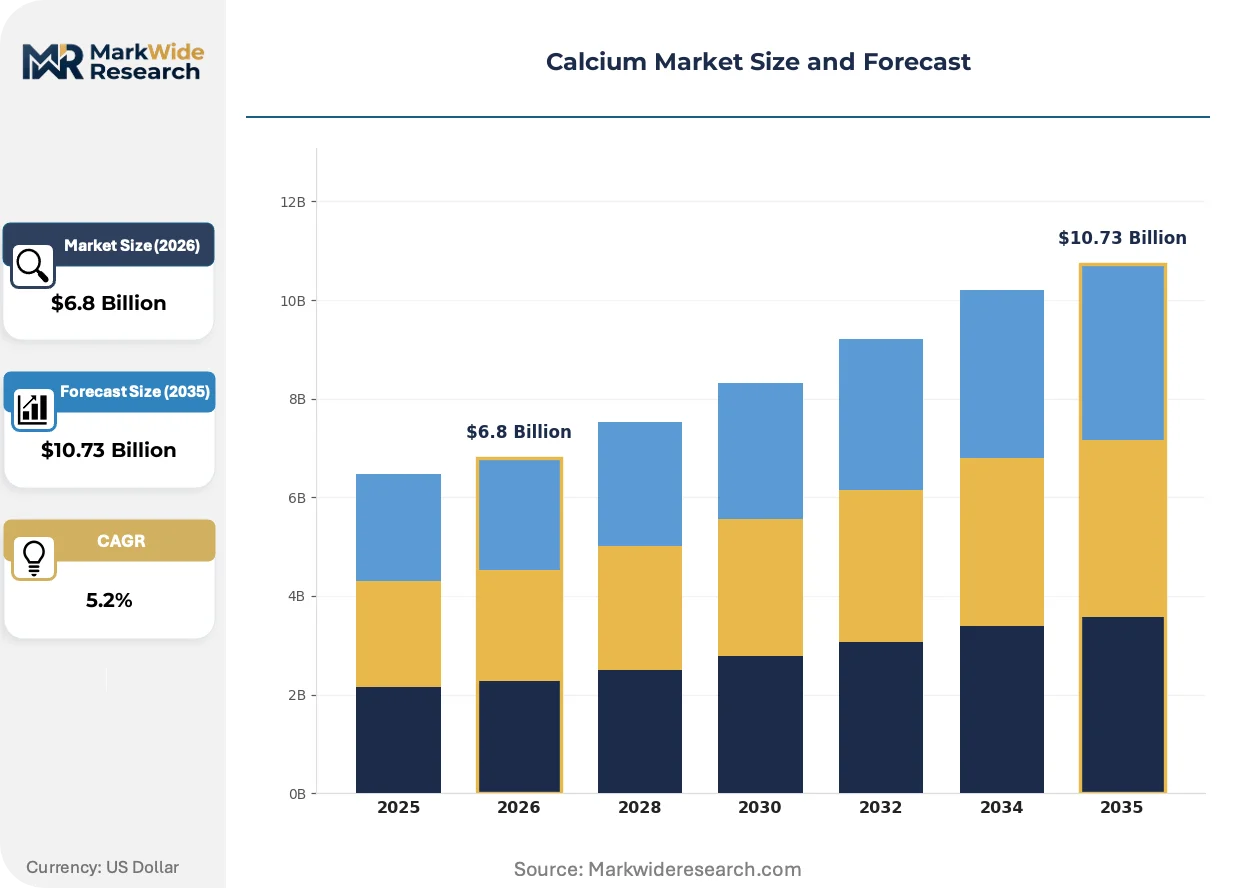
Market Dynamics
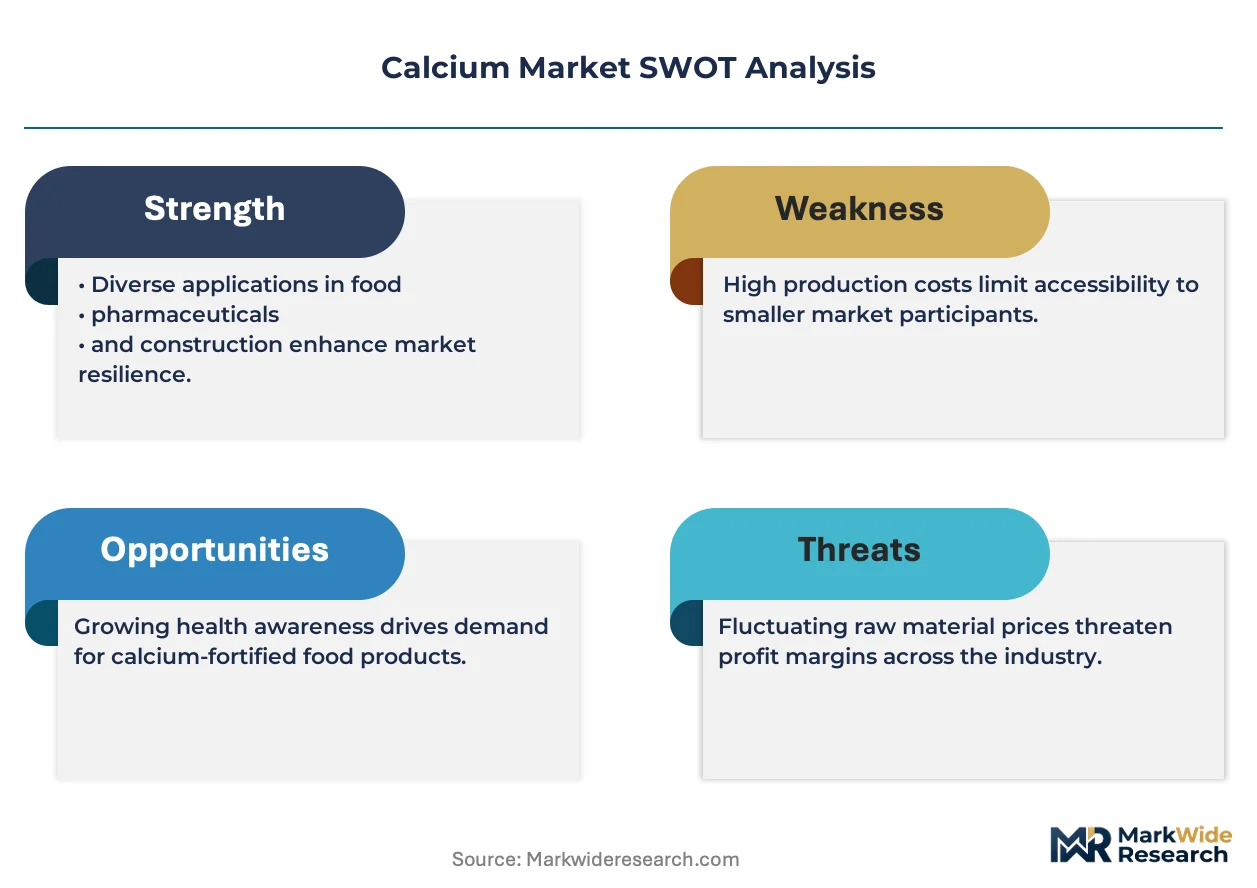
The calcium market's central dynamic is the growing bifurcation between high-volume industrial grades and high-purity specialty compounds. This split is driven by stringent regulatory frameworks in the food and pharmaceutical sectors, which demand verifiable purity and traceability, contrasting with the cost-focused industrial filler segment.
Growth Catalysts
- Food Fortification Mandates:National health initiatives, such as those governed by India's FSSAI, compel the addition of calcium to staple foods, creating steady, large-scale demand for food-grade calcium compounds.
- Dietary Supplement Expansion:Consumer focus on bone health and preventative care expands the market for high-bioavailability calcium forms like citrate and gluconate within the global nutraceuticals industry.
- Functional Filler Demand:The plastics and paper industries continue to utilize calcium carbonate as a cost-effective functional additive to increase rigidity, improve opacity, and reduce polymer content.
Market Restraints
- Energy Cost Volatility:The production of precipitated calcium carbonate (PCC) is an energy-intensive process, making its manufacturing costs highly susceptible to fluctuations in regional electricity and natural gas prices.
- Regulatory Entry Barriers:The European Union's REACH regulation imposes significant compliance costs and data requirements for chemical registration, acting as a substantial hurdle for new or smaller suppliers entering the market.
- Raw Material Purity Dependence:Access to high-purity limestone and marble deposits, which are geographically concentrated, constrains the production of premium-grade calcium carbonate suitable for pharmaceutical applications.
Strategic Opportunities
- Biodegradable Polymer Additives:Calcium carbonate can be incorporated as a functional filler in bioplastics like PLA, offering an opportunity to lower costs and modify material properties in the growing sustainable packaging sector.
- Nano-Calcium Carbonate Development:Engineering nano-scale precipitated calcium carbonates opens new applications in high-performance sealants, coatings, and medical composites where enhanced barrier properties are required.
- Southeast Asian Market Penetration:Rising disposable incomes and health awareness in countries like Vietnam and Indonesia present an underpenetrated market for dietary supplements and fortified food and beverage products.
Industry Challenges
- Multi-Jurisdictional Compliance:Suppliers face the operational challenge of aligning production and quality control to meet the differing purity standards and monograph specifications of the USP, Ph. Eur., and JP pharmacopeias.
- Supply Chain Traceability:Implementing and documenting full source-to-product traceability for pharmaceutical-grade calcium is a complex operational task required to satisfy regulatory and customer audits.
- High-Purity Production Capex:Upgrading or constructing facilities to produce pharmaceutical-grade compounds requires significant capital investment in non-corrosive reactors, cleanroom environments, and advanced purification equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Calcium Citrate, Calcium Phosphate, Calcium Gluconate End User: Food & Beverage, Pharmaceuticals, Dietary Supplements, Animal Feed Application: Food Fortification, Nutritional Supplements, Pharmaceutical Products, Industrial Uses Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Omya AG, Imerys, Sibelco, Huber Engineered Materials, Minerals Technologies Inc., Carmeuse, Solvay, Lhoist, Mississippi Lime Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from commodity extraction toward material science. Suppliers are increasingly differentiating through precise control over particle characteristics and documented purity, meeting demands from advanced industrial and life science applications that require specific performance attributes beyond bulk chemistry.
Precipitated calcium carbonate (PCC) technology enables the engineering of specific particle sizes, shapes, and surface areas. Pharmaceutical and specialty food ingredient formulators are rapidly adopting these customized grades for their unique functional properties. This advanced material science focus is converging with formulation science, enabling the creation of novel drug delivery mechanisms and texturally optimized fortified foods.
Regulatory frameworks like the Food Safety and Standards Authority of India (FSSAI) rules on food fortification are creating direct demand channels. These mandates necessitate the inclusion of specific micronutrients, including calcium, in widely consumed products, compelling manufacturers to reformulate. The food and beverage sector in India, particularly producers of flour, edible oils, and milk, is most directly affected by this public health-driven policy.
A notable behavioral shift is occurring in how life science end-users select suppliers, with a strong preference for documented quality systems over simple price metrics. This trend is disrupting the role of pure traders, who struggle to provide the quarry-to-customer traceability that buyers now demand. This procurement pattern is most visible in the North American and European dietary supplement markets, where regulatory and consumer scrutiny is most intense.
Calcium Market Segmentation
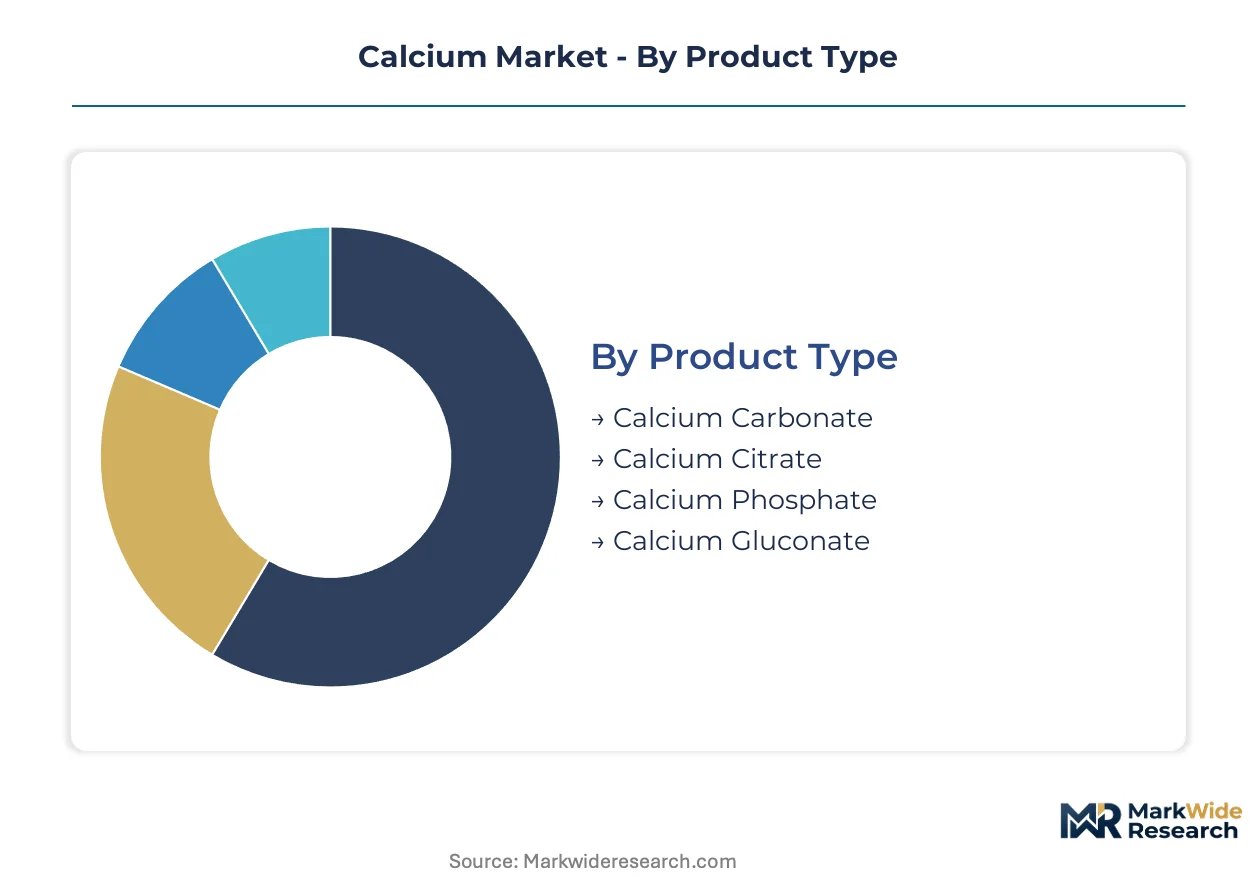
The calcium market's segmentation reveals the diverse applications and end-user requirements driving demand across industrial and high-purity sectors. Understanding these distinct segments is essential for suppliers to tailor product specifications and distribution strategies effectively.
Product Type:
The product type segmentation highlights the spectrum from highly standardized bulk compounds to precisely engineered specialty calcium forms.
- Calcium Carbonate:This naturally occurring compound, derived from sources like limestone and marble, is widely used for its cost-effectiveness and functional properties. Demand concentrates in industrial applications such as plastics, paper, and paints, where it acts as a filler, whitener, and pH regulator.
- Calcium Citrate:An organic calcium salt known for its high bioavailability and solubility, making it a preferred choice for human consumption. Demand is significant in the dietary supplements sector, particularly in North American and European markets, driven by consumer focus on bone health.
- Calcium Phosphate:An inorganic salt category including dicalcium and tricalcium phosphate, primarily used in food fortification and as a buffering agent in processed foods.
- Calcium Gluconate:An organic calcium salt often found in pharmaceutical preparations for intravenous calcium delivery and as a food additive due to its high purity.
Most installed capacity flows through Calcium Carbonate. Expansion is steepest in Calcium Citrate.
End User:
End-user segments reflect distinct demand drivers and regulatory compliance requirements for calcium compounds.
- Pharmaceuticals:This segment requires ultra-high purity calcium compounds that meet stringent pharmacopeial standards from bodies like the USP and Ph. Eur. Demand comes from drug formulations, excipients, and active pharmaceutical ingredients, driven by global health regulations.
- Dietary Supplements:This segment emphasizes high bioavailability and specific calcium forms like citrate and gluconate for human consumption. Demand is fueled by consumer focus on preventative health and bone density, particularly in developed markets.
- Food & Beverage:This sector utilizes food-grade calcium for fortification in products such as milk, flour, and juices, driven by public health initiatives and national mandates.
- Animal Feed:The animal feed industry incorporates calcium carbonate as a cost-effective mineral supplement for livestock, supporting bone development and eggshell quality.
The pharmaceutical and dietary supplement sectors impose the most rigorous quality standards, influencing sourcing across the market.
Application:
Application categories delineate the specific functional roles calcium compounds fulfill, from bulk fillers to specialized performance enhancers.
- Industrial Uses:This application employs commodity-grade calcium carbonate as a filler, whitener, and pH regulator across various industries. Demand stems from plastics, paper, paints, and construction materials, driven by cost-efficiency and functional benefits.
- Nutritional Supplements:This application focuses on highly bioavailable calcium forms for direct human consumption to support health. Demand supports bone health and overall wellness, with strong growth in markets like India and Southeast Asia.
- Food Fortification:This application involves adding calcium to staple foods to address public health deficiencies, often mandated by regulators like India's FSSAI.
- Pharmaceutical Products:This application utilizes pharmaceutical-grade calcium compounds as active ingredients or excipients in various drug formulations requiring strict purity and traceability.
The industrial segment accounts for the largest volume consumption, while nutritional supplements exhibit significant value growth.
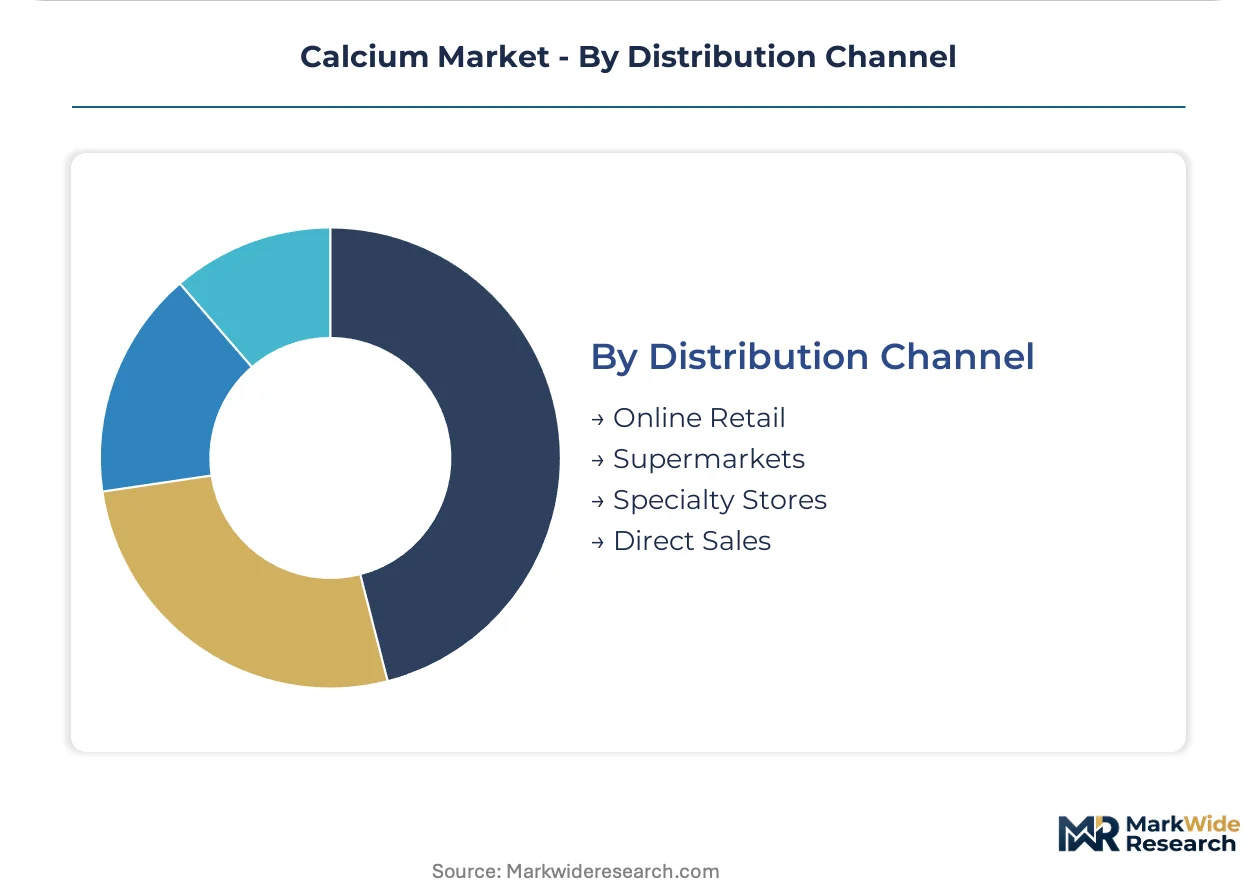
Distribution Channel:
Distribution channels reflect how calcium products reach end-users, balancing broad market access with specialized procurement needs.
- Direct Sales:This channel involves direct engagement between manufacturers and large industrial or pharmaceutical buyers, ensuring traceability, bulk delivery, and technical support. Demand is critical for high-volume or specialized orders where direct communication and quality assurance are paramount.
- Online Retail:This channel provides convenience and broad access for dietary supplements and consumer-packaged goods containing calcium. Demand is driven by e-commerce penetration and consumer preference for direct-to-consumer purchases in global markets.
- Supermarkets:These retail outlets distribute calcium-fortified food and beverage products, reaching a mass consumer base for everyday purchases.
- Specialty Stores:This channel includes health food stores and pharmacies, catering to consumers seeking specific dietary supplements or health-focused products.
Direct sales remain critical for industrial and pharmaceutical procurement, while online retail is reshaping consumer access for supplements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's specialized workforce in food processing and pharmaceuticals anchors a significant portion of the calcium market's growth, particularly for fortified food products. This concentration drives both demand for high-purity calcium compounds and innovation in application. Global players are increasingly focusing on this region to meet evolving consumer needs and regulatory mandates.
India
National health initiatives, such as those driven by the Food Safety and Standards Authority of India (FSSAI), compel the addition of calcium to staple foods, creating steady demand for food-grade compounds. Consumer focus on bone health further expands the market for high-bioavailability calcium forms in dietary supplements. Food and beverage manufacturers in Maharashtra are actively reformulating products to comply with fortification mandates.
United States
The U.S. market emphasizes high-purity calcium for pharmaceutical formulations and dietary supplements, driven by consumer health awareness and stringent Food and Drug Administration (FDA) standards. Demand for calcium citrate and gluconate is particularly strong due to their high bioavailability. Nutraceutical producers in California continue to innovate with new calcium delivery systems for an aging population.
Germany
European Union's REACH regulation imposes significant compliance costs for calcium compound suppliers, influencing raw material sourcing and processing for industrial and specialty applications. High-purity calcium carbonate finds extensive use in the pharmaceutical sector and as functional fillers in high-performance plastics. Chemical and pharmaceutical manufacturers in North Rhine-Westphalia are at the forefront of developing advanced calcium grades.
China
China's vast industrial base creates substantial demand for commodity-grade calcium carbonate as a functional filler in plastics, paper, and construction materials. National health policies and rising disposable incomes are also expanding the market for food-grade calcium and dietary supplements. Industrial chemical zones in the Yangtze River Delta are increasing production capacity for both industrial and specialty calcium compounds.
Calcium Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the calcium market, creating a dynamic competitive environment. The market exhibits a clear bifurcation between high-volume industrial grades and high-purity specialty compounds. Strategic archetypes include large-scale commodity producers, high-purity ingredient suppliers, and technology-driven material science innovators. Capacity expansion and strategic partnerships remain dominant competitive moves for market participants.
Scale-driven producers like Omya AG maintain their market position through extensive production capabilities and a global distribution network for both commodity and specialty grades. Minerals Technologies Inc. leverages its specialized portfolio of precipitated calcium carbonates to meet stringent pharmaceutical and food-grade specifications, exemplifying a focus on advanced material science. Solvay occupies a position in high-purity synthetic calcium carbonate grades, catering to specialized applications that demand exacting performance attributes.
| Leading Market Players |
|---|
| Omya AG |
| Imerys |
| Sibelco |
| Huber Engineered Materials |
| Minerals Technologies Inc. |
| Carmeuse |
| Solvay |
| Lhoist |
| Mississippi Lime Company |
| Others |
Cost & Logistics Intelligence
Diversified conglomerates and family-owned specialists influence calcium supply behavior, often dictating pricing discipline through extensive production capabilities and long-term contracts. Their capital structures enable strategic investments in high-purity production.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences calcium pricing, with high-purity grades often commanding value-based pricing for technical support and documented traceability. Industrial grades primarily operate on commodity spot or contract-based long-term offtake models. Price differentiation stems from quality grade, specific pharmacopeial certifications like USP, and volume scale. Cost compression in industrial calcium carbonate is intensifying due to energy cost volatility, making industrial users highly price-sensitive, contrasting with pharmaceutical buyers who prioritize quality and compliance.
Supply Chain Analysis
Certification and qualification gating profoundly shapes the calcium supply chain, particularly for pharmaceutical and food-grade compounds requiring USP or EFSA compliance. Geographic supply for high-purity limestone concentrates in regions like North America and Europe, while China dominates commodity-grade production. The market relies heavily on accessible, high-purity limestone deposits and energy for PCC, where energy cost volatility poses a structural risk. Distribution runs through direct sales for large industrial and pharmaceutical buyers, with online retail gaining for dietary supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium market acts as a regulatory compounder, with demand significantly amplified by mandates such as India's FSSAI rules on food fortification. These regulations compel manufacturers to reformulate products, ensuring steady, large-scale demand.
For Market Incumbents:Hedge against energy cost volatility by investing in energy-efficient PCC production technologies and securing long-term natural gas contracts. Incumbents should deepen vertical integration into high-purity raw material sourcing to mitigate supply chain traceability risks and ensure consistent quality for pharmaceutical clients. Focus R&D on particle engineering for nano-calcium carbonate applications to counter emerging specialized entrants. Reinforce market position through continuous certification investment to meet evolving purity monographs like USP and Ph. Eur.
For New Entrants and Emerging Players:India's FSSAI fortification mandates open a window for new entrants to supply food-grade calcium compounds, especially by partnering with local food and beverage manufacturers. Target the underpenetrated Southeast Asian dietary supplement market, specifically in Vietnam and Indonesia, where rising disposable incomes drive health awareness. Focus on developing calcium carbonate as a functional filler for biodegradable polymers, aligning with sustainable packaging trends.
For Investors and Strategic Acquirers:Valuations sit cheapest among commodity-grade producers facing energy cost volatility, offering potential for strategic consolidation. Long-term viability hinges on sustained demand from health and wellness trends and ongoing food fortification mandates. Target high-purity specialty compound producers with advanced particle engineering capabilities and established pharmaceutical certifications. A key signal to watch is the introduction of new or stricter purity monographs from regulators like the U.S. FDA or EFSA.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases supply of high-purity calcium compounds for growing dietary supplement markets. |
| Green Manufacturing Transition | Reduces energy costs and enhances sustainability profile for PCC production. |
| Long-term Supply Agreement | Secures consistent access to high-purity limestone deposits for specialty grades. |
| Joint Venture | Combines R&D expertise for nano-calcium carbonate development in advanced materials. |
| Distribution Channel Expansion | Reaches new consumer bases in Southeast Asia for fortified food products. |
Research Approach
Bottom-up pharmaceutical and food end-use modeling reconciled against top-down calcium compound supply-side tracking forms the analytical core of this study. Primary interviews with R&D directors, procurement leads, and regulatory affairs specialists across key regions informed market dynamics. Secondary validation drew from FSSAI reports, FDA filings, and customs data to ensure data integrity. This approach enabled robust triangulation of market size and growth projections.
An input-output matrix framework projects market evolution across the analysis window, integrating various segmentation dimensions. These include product type, end-user, application, and geographic region. Compound annual growth rates were derived from historical trends and projected demand drivers, such as population demographics and national food fortification mandates.
Revisions become necessary when geopolitical shifts, new regulatory frameworks, or significant technological breakthroughs materialize. Forecasts reflect assumptions regarding raw material availability and end-user adoption patterns. A model refresh is warranted upon material change in global health policies or energy prices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market