
 Esterified Vitamins Market | 2026-2036
Esterified Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Esterified Vitamins Market Foresight
Asset-light contract manufacturing partnerships are reconfiguring competitive entry barriers in the esterified vitamins sector. Lonza Group leverages its integrated fermentation and chemical synthesis platforms to supply pharmaceutical-grade vitamin esters across multiple continents. DSM Nutritional Products anchors its position through deep backward integration into vitamin precursor chemistry, while Zhejiang NHU Co. Ltd. competes aggressively on tocopherol acetate scale from its Zhejiang production base. BASF Vitamins Nutrition differentiates via dual-source supply architecture spanning European and Asian manufacturing nodes.
Esterified vitamins are lipid-soluble micronutrients chemically modified through esterification of hydroxyl groups with acetate or succinate moieties, yielding enhanced oxidative stability and controlled-release profiles in lipid matrices. The esterification process typically employs acetic anhydride or succinic anhydride reaction with tocopherols, retinol, or ascorbic acid under catalyzed conditions, producing acetate or palmitate derivatives standardized to pharmaceutical or food-grade purity specifications. Vitamin E acetate dominates product type revenue due to its ubiquity in dermatological and parenteral nutrition applications, while nutraceuticals application channels absorb the fastest volume growth as functional food brands seek heat-stable vitamin forms for fortified beverages and meal replacements. Pharmaceutical application segments retain the densest margin pools, where USP-grade vitamin A palmitate commands stringent impurity thresholds and batch certification requirements.
FDA cGMP regulations for dietary supplements under 21 CFR Part 111 and EFSA novel food assessments under EU Regulation 2015/2283 collectively elevate manufacturing documentation and stability-testing burdens for esterified vitamin suppliers seeking transatlantic market access. EPA and REACH chemical registration requirements further constrain raw material sourcing flexibility for acetate and succinate esterification reagents. Stakeholders must monitor evolving pharmacopeial monograph revisions and tightening residual solvent limits that could disqualify legacy production routes.
Market Dynamics
Pharmaceutical-grade purity benchmarks are compressing legacy production economics as nutraceutical buyers demand USP-grade certification for esterified vitamin E acetate and retinol palmitate derivatives.
Growth Catalysts
- EFSA Novel Food pathways:Accelerated health claim assessments under EU Regulation 2015/2283 are opening shelf-space for fortified beverages containing heat-stable vitamin esters.
- Parenteral nutrition expansion:Hospital formulary committees are standardizing vitamin E acetate in lipid emulsion protocols for premature infant and surgical recovery patients.
- Zhejiang production clustering:Tocopherol acetate capacity concentration in eastern China is driving feedstock cost advantages for acetate esterification reagents.
Market Restraints
- Acetic anhydride price volatility:Feedstock cost swings for esterification reagents compress margin predictability for acetate derivative manufacturers.
- REACH registration burdens:ECHA chemical substance notifications for succinate and palmitate esters impose documentation costs that disadvantage smaller compounders.
- Natural tocopherol substitution:Unesterified mixed tocopherol concentrates are capturing clean-label preference in premium skincare and organic food channels.
Strategic Opportunities
- India nutraceutical whitespace:FSSAI functional food regulations are creating first-mover advantage for heat-stable vitamin fortification in urban meal replacement products.
- Microencapsulation convergence:Spray-drying technology paired with lipid matrix engineering is enabling controlled-release vitamin A palmitate in hot-fill beverage applications.
- Direct-to-brand e-commerce channels:Supplement contract manufacturers are bypassing traditional distributor tiers through vertically integrated online procurement platforms.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC method development for residual solvent quantification requires specialized skill sets in short supply across quality control departments.
- Stability protocol capex intensity:ICH Q1A long-term and accelerated testing chambers demand capital outlays that strain mid-tier manufacturers.
- Pharmacopeial harmonization delays:Divergent USP, EP, and JP monograph specifications for vitamin ester purity create batch-release complexity for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esterified Vitamins Market |
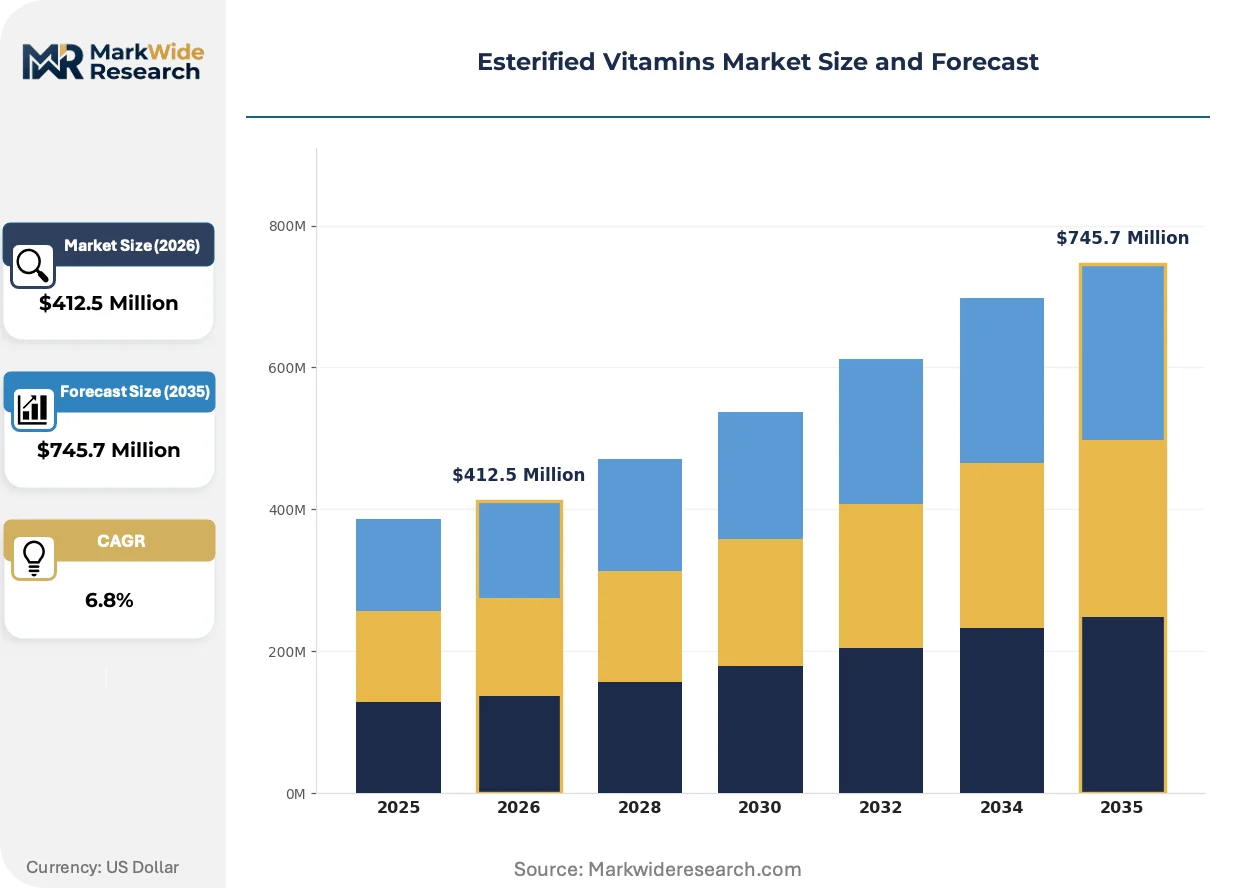
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin E, Vitamin D, Vitamin A, Vitamin C Application: Nutraceuticals, Food Supplements, Pharmaceutical, Cosmetics End User: Healthcare Providers, Retail Customers, Manufacturers, Researchers Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | Lonza Group, Bactolac Pharmaceutical, DSM Nutritional Products, Makers Nutrition, ENZ Pharmtech, BASF Vitamins Nutrition, Vitaquest, Zhejiang NHU Co. Ltd., Glanbia Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esterified Vitamins Market Shifts & Advancements
Enzymatic esterification methods are displacing traditional chemical catalysis as manufacturers seek to reduce residual solvent burdens and simplify downstream purification.
Continuous flow reactor technology for vitamin E acetate synthesis is migrating from pilot-scale demonstration to commercial deployment among European pharmaceutical ingredient suppliers. DSM Nutritional Products and Lonza Group have installed skid-mounted flow chemistry units at their Basel and Visp manufacturing nodes. This shift is compressing batch cycle times from 48 hours to sub-6-hour residence while tightening impurity profiles to meet USP-grade thresholds.
EPA chemical data reporting requirements under the Toxic Substances Control Act are tightening disclosure obligations for acetate and succinate esterification intermediates. Manufacturers must now submit production volume and exposure data for vitamin ester precursors previously exempt under low-volume exemptions. Dietary supplement contract manufacturers in the United States are responding by demanding certified supply chain documentation from Asian precursor suppliers.
Functional food brands are consolidating supplier relationships around single-source vitamin ester partnerships with integrated stability testing capabilities. Procurement teams at beverage fortification companies are replacing spot-market acetate purchases with multi-year toll manufacturing agreements. This concentration is most visible in Germany, where dairy alternative producers are locking in three-year vitamin A palmitate supply contracts with embedded quarterly stability certification.
Esterified Vitamins Market Segmentation
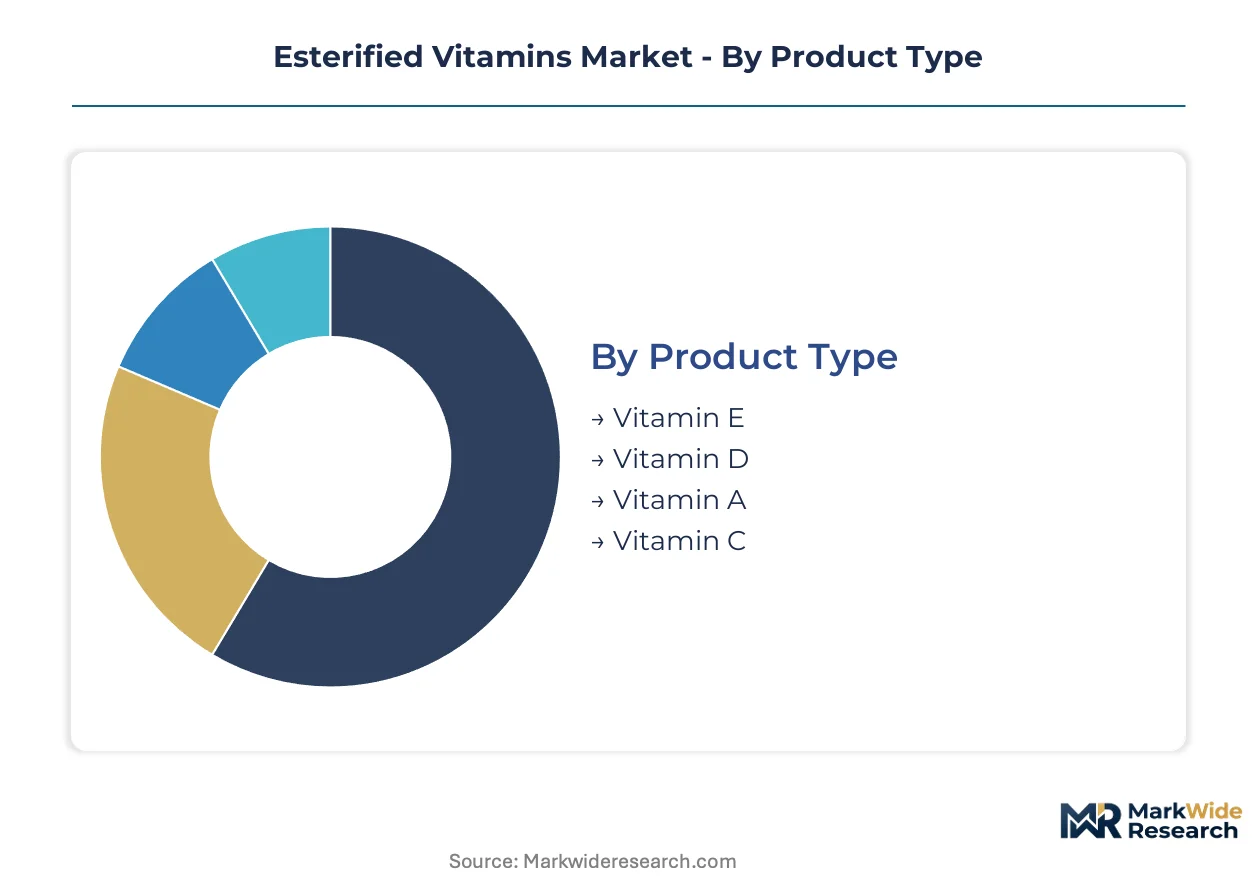
Esterified vitamin formulations fragment across multiple axes that determine pricing power, regulatory pathway, and customer procurement behavior. Product chemistry, application-grade certification, and channel access each create distinct margin pools and competitive moats for suppliers.
Product Type:
Mature acetate derivatives dominate commercial volumes while succinate and palmitate esters emerge in specialized pharmaceutical applications.
- Vitamin E:Tocopherol acetate constitutes the workhorse ester, prized for oxidative stability in lipid emulsions and dermatological bases. German parenteral nutrition compounders absorb the densest volumes as hospital formulary committees standardize vitamin E acetate in premature infant protocols.
- Vitamin A:Retinol palmitate commands premium pricing in USP-grade batches for ophthalmic and prenatal formulations. Indian nutraceutical contract manufacturers are accelerating uptake for fortified beverage applications under FSSAI functional food pathways.
- Vitamin D:Cholecalciferol esters serve niche stability requirements in high-temperature food processing.
- Vitamin C:Ascorbyl palmitate finds limited adoption in lipid-soluble antioxidant applications for cosmetic emulsions.
Vitamin E handles the majority of throughput; Vitamin A is gaining share fastest in premium certification tiers.
Application:
Application-grade purity requirements stratify suppliers into pharmaceutical, food, and cosmetic certification tiers with divergent analytical burdens.
- Nutraceuticals:Heat-stable vitamin esters enable hot-fill beverage fortification without degradation. Functional food brands in Germany and India are locking in multi-year supply agreements with embedded quarterly stability certification.
- Pharmaceutical:USP-grade vitamin A palmitate and E acetate demand residual solvent thresholds below ICH Q3C limits. FDA cGMP documentation under 21 CFR Part 111 elevates batch-release complexity for parenteral and ophthalmic applications.
- Food Supplements:Standard-grade acetate derivatives serve cost-sensitive tablet and capsule manufacturers.
- Cosmetics:Vitamin E acetate anchors dermatological formulations for oxidative protection in lipid-based delivery systems.
Pharmaceutical segments capture the densest margin pools; nutraceuticals are expanding most quickly as beverage fortification accelerates.
End User:
Procurement sophistication varies sharply across customer types, from institutional tender processes to direct-to-consumer subscription models.
- Healthcare Providers:Hospital formulary committees and parenteral nutrition compounding pharmacies drive pharmaceutical-grade demand. EMA and FDA inspections of active pharmaceutical ingredient suppliers determine qualified vendor lists.
- Manufacturers:Dietary supplement contract manufacturers and functional food processors absorb the broadest volume base. These buyers prioritize heat stability certificates and REACH-compliant supply chain documentation.
- Retail Customers:Direct purchasers of esterified vitamin supplements through e-commerce channels.
- Researchers:Academic and clinical trial sponsors requiring analytical-grade esters for method development.
Manufacturers transact the highest absolute volumes; healthcare providers command the most stringent purity specifications.
Distribution Channel:
Channel configuration determines working capital intensity and customer intimacy, with digital platforms eroding traditional wholesale tiers.
- Direct Sales:Long-term toll manufacturing agreements dominate pharmaceutical and large nutraceutical procurement. German dairy alternative producers exemplify this shift toward three-year vitamin A palmitate contracts with embedded stability testing.
- Online Retail:Vertically integrated e-commerce platforms enable supplement contract manufacturers to bypass distributor markups. Direct-to-brand procurement is concentrating supplier relationships around single-source partnerships.
- Pharmacies:Traditional dispensing channel for prescription-grade vitamin formulations.
- Health Stores:Specialty retail for premium and clean-label supplement positioning.
Direct sales channels handle the majority of value; online retail is climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA health claim assessments under EU Regulation 2015/2283 are tightening purity benchmarks for vitamin esters entering European markets. Nutraceutical manufacturers in Germany, India, China, and the United States are accelerating uptake of esterified forms for enhanced bioavailability. Hospital formulary committees across these markets are standardizing pharmaceutical-grade vitamin E acetate in parenteral nutrition protocols.
Germany
Pharmaceutical-grade vitamin E acetate consumption by dietary supplement producers continues to rise. EFSA Novel Food Regulation compliance requirements dominate procurement criteria for fortified beverage entrants. The Basel manufacturing cluster hosts continuous flow reactor installations producing USP-grade tocopherol acetate with sub-6-hour residence times.
United States
FDA cGMP regulations under 21 CFR Part 111 elevate batch-release documentation for parenteral and ophthalmic vitamin applications. EPA chemical data reporting under the Toxic Substances Control Act tightens disclosure obligations for acetate esterification intermediates. New Jersey and Pennsylvania pharmaceutical corridors absorb dense volumes of vitamin A palmitate for prenatal formulation compounding.
China
Zhejiang production clustering drives feedstock cost advantages for tocopherol acetate esterification reagents. NMPA pharmaceutical ingredient registration requirements constrain raw material sourcing flexibility for succinate and palmitate derivatives. The Hangzhou-Ningbo industrial belt concentrates acetate derivative capacity serving both domestic nutraceutical brands and export markets.
India
FSSAI functional food regulations create first-mover advantage for heat-stable vitamin fortification in urban meal replacement products. CDSCO active pharmaceutical ingredient oversight elevates documentation burdens for retinol palmitate imports. Maharashtra and Gujarat pharmaceutical hubs are locking in multi-year vitamin ester supply agreements with embedded quarterly stability certification.
Esterified Vitamins Market Competitive Landscape
On the supply side, the industry is consolidating around integrated fermentation and chemical synthesis platforms that compress batch cycle times and tighten impurity profiles. Tiered competitive positioning separates pharmaceutical-grade certification holders from standard-grade compounders. Three archetypes dominate: backward-integrated precursor producers, toll manufacturing specialists with flow chemistry capabilities, and regional scale players competing on tocopherol acetate throughput. Capacity expansion through continuous flow reactor installation and multi-year toll manufacturing agreements with embedded stability testing represent the dominant competitive moves.
Among European-anchored suppliers, Lonza Group and DSM Nutritional Products exemplify the integrated platform archetype with Basel-based manufacturing nodes. Zhejiang NHU Co. Ltd. represents the regional scale concentration model from its eastern China production base. BASF Vitamins Nutrition occupies a position spanning dual-source supply architecture across European and Asian manufacturing nodes.
| Leading Market Players |
|---|
| Lonza Group |
| Bactolac Pharmaceutical |
| DSM Nutritional Products |
| Makers Nutrition |
| ENZ Pharmtech |
| BASF Vitamins Nutrition |
| Vitaquest |
| Zhejiang NHU Co. Ltd. |
| Glanbia Nutritionals |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors transmit acetic anhydride cost volatility directly into tocopherol acetate landed pricing, compressing margin predictability for European compounders while amplifying spreads between pharmaceutical-grade and standard-grade certifications. This logistics-cost feedback loop rewards backward-integrated producers with captive esterification reagent supply.
Pricing Analysis
Certification level creates the primary spread between USP-grade vitamin E acetate and standard feed-grade derivatives. Three-tier pricing structure across pharmaceutical, nutraceutical, and industrial grades reflects divergent analytical burdens and stability-testing documentation. Pricing pressure stems from Zhejiang capacity expansion feeding acetate derivative spot markets. Nutraceutical contract manufacturers exhibit highest price sensitivity; parenteral nutrition compounders absorb premium tiers without volume elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Indian and German toll manufacturers purchasing Zhejiang-sourced tocopherol acetate. Supply concentrates in China, Germany, and India for acetate esterification and downstream compounding. Raw material dependencies center on acetic anhydride, succinic anhydride, and natural tocopherol feedstock. Single-source vulnerability runs through Zhejiang precursor chemistry. Distribution runs through direct toll manufacturing agreements with embedded stability certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stability-testing-as-a-service revenue layers are expanding faster than commodity vitamin ester sales as beverage fortifiers outsource quarterly certification burdens. This service-attach dynamic reconfigures supplier-customer relationships toward multi-year partnerships.
For Market Incumbents: Harden pharmaceutical-grade certification moats through continuous flow reactor investments at Basel and Visp manufacturing nodes. Defend against enzymatic esterification substitutes by locking three-year toll agreements with German dairy alternative producers. Prioritize in-house production of vitamin precursor chemistry to neutralize acetic anhydride price swings. For New Entrants and Emerging Players: Build out microencapsulation capabilities paired with lipid matrix engineering for hot-fill beverage applications. Target Indian FSSAI functional food whitespace before incumbent stability-testing networks mature. Deploy direct-to-brand e-commerce procurement platforms to bypass traditional distributor markups. For Investors and Strategic Acquirers: EFSA Novel Food Regulation 2015/2283 enforcement reshapes the acquisition landscape toward integrated stability-testing platforms. Long-term viability favors toll manufacturing specialists with flow chemistry capabilities over commodity acetate traders. Monitor CDSCO active pharmaceutical ingredient registration timelines as inflection signals for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Installation | Compresses batch cycle times to sub-6-hour residence at DSM Nutritional Products' Basel node. |
| Backward Integration into Precursor Chemistry | Neutralizes acetic anhydride volatility for Lonza Group's pharmaceutical-grade tocopherol acetate output. |
| Multi-Year Toll Manufacturing Agreement | Locks German dairy alternative producers into embedded quarterly stability certification. |
| Microencapsulation Technology Licensing | Enables controlled-release vitamin A palmitate in hot-fill beverage applications for Indian FSSAI entrants. |
| Direct-to-Brand E-Commerce Platform | Bypasses distributor markups for supplement contract manufacturers procuring from Zhejiang NHU. |
Research Methodology
Cross-validation between primary interviews with pharmaceutical procurement managers and secondary FDA 21 CFR Part 111 filings anchors the qualitative findings. Conversations with parenteral nutrition compounding pharmacists, nutraceutical contract manufacturing executives, EFSA regulatory affairs leads, and stability-testing laboratory directors informed supply-side dynamics. Secondary sources include EMA inspection reports, USP monograph revisions, REACH registration databases, and customs trade data for acetate esterification reagents. Bottom-up volume builds from individual production facility capacities triangulate against top-down market sizing from industry association aggregates.
Calibration against historical CAGRs from analogous pharmaceutical ingredient markets validates the projection framework across the analysis window. Segmentation dimensions span product chemistry, application-grade certification tier, end-user procurement sophistication, and distribution channel configuration. Forecast inputs incorporate ICH Q1A stability protocol adoption rates, EFSA Novel Food assessment timelines, and continuous flow reactor deployment curves. Growth rates derive from regression against precursor chemical pricing indices and beverage fortification penetration patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Zhejiang regional scale players or accelerated enzymatic esterification commercialization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Global Fortified Yogurt Market