
 Essential Micronutrients Market | 2026-2036
Essential Micronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Micronutrients Market Analytics
The gap between pharmaceutical-grade micronutrient formulations and commodity-grade agricultural blends is repositioning how suppliers allocate capital and technical resources. Nutrien Ltd. leverages its integrated potash and specialty nutrient infrastructure to control upstream mineral inputs for premium applications. Yara International ASA anchors its position through precision agriculture platforms that pair micronutrient delivery with digital farming tools. Haifa Group specializes in water-soluble and controlled-release formulations, competing on technical performance rather than bulk volume.
Essential micronutrients comprise organic and inorganic compounds required in minute quantities for metabolic, enzymatic, and physiological functions in humans, animals, and plants, typically measured in parts per million or microgram concentrations. Manufacturing involves chelation, microencapsulation, or crystallization to ensure bioavailability and stability against oxidation or leaching. Vitamins and trace elements command the highest margin pools where pharmaceutical and nutraceutical purity standards apply, while minerals and antioxidants in animal feed operate on scale economics with tighter specification bands. Dietary supplements and functional foods represent the fastest-expanding application channels as consumers shift from reactive healthcare to preventive nutrition protocols.
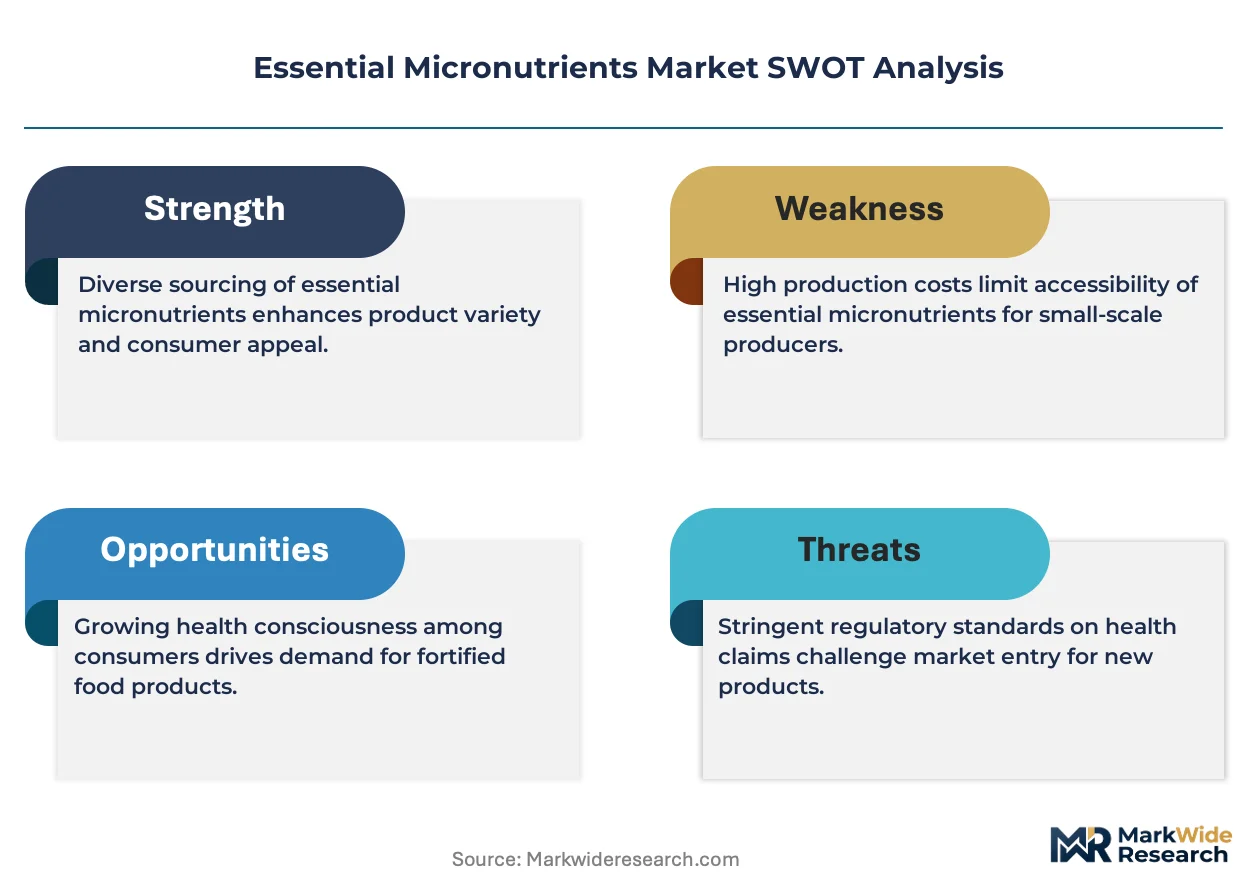
The FDA governs micronutrient labeling and health claims under DSHEA and subsequent guidance, while the EFSA sets population reference intakes that drive fortification levels across EU member states. REACH and related ECHA frameworks restrict certain inorganic carriers and processing aids, forcing reformulation of mineral premixes sold into European food and feed channels. Stakeholders must monitor evolving maximum permitted levels for iron, zinc, and selenium in fortified products, as regulatory tightening in one jurisdiction typically cascades into supplier qualification requirements across multiple export destinations.
Market Dynamics
Regulatory divergence between pharmaceutical-grade purity mandates and agricultural-scale bulk specifications is fragmenting supplier capabilities and forcing capital allocation decisions across incompatible production footprints.
Growth Catalysts
- Fortification Mandates:EFSA population reference intake revisions and FDA guidance on health claims under DSHEA are compelling food manufacturers to reformulate with standardized micronutrient premixes.
- Precision Livestock Nutrition:Dairy and poultry operations in the Netherlands and Denmark are deploying sensor-driven feeding systems that integrate trace mineral supplementation with real-time metabolic monitoring.
- Chelated Mineral Technology:Glycinate and methionine-complexed zinc, copper, and manganese are displacing inorganic sulfates in swine and aquaculture diets due to superior bioavailability and reduced environmental excretion.
Market Restraints
- Input Cost Volatility:Selenium and cobalt derived from copper and nickel mining byproduct streams face supply interruptions when base metal smelter output fluctuates with industrial demand cycles.
- Regulatory Friction:REACH authorization requirements for certain inorganic carriers force reformulation of mineral premixes destined for EU food and feed channels, extending qualification timelines.
- Technical Limitation:Microencapsulation stability remains problematic for heat-sensitive vitamins in extruded feed processing above 90°C, constraining application in high-temperature pelleting operations.
Strategic Opportunities
- Underpenetrated Geographies:Sub-Saharan African markets present expansion potential as national food fortification programs in Nigeria, Kenya, and Ethiopia scale micronutrient premix procurement for staple grain processing.
- Emerging Application:Cultivated meat and precision fermentation facilities require custom micronutrient media formulations that differ substantially from conventional animal nutrition specifications.
- Technology Convergence:Integration of controlled-release fertilizer coatings with foliar micronutrient delivery is creating dual-function products for high-value horticulture in Spain, Italy, and Morocco.
Industry Challenges
- Certification Timeline Compression:Pharmaceutical-grade GMP certification for vitamin manufacturing now requires 18-24 month validation cycles that delay market entry for new production facilities.
- Supply Chain Reconfiguration Friction:Shifting from Chinese-dominated mineral processing to alternative sulfate and oxide sources in Chile and Kazakhstan disrupts established logistics networks and specification matching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Micronutrients Market |
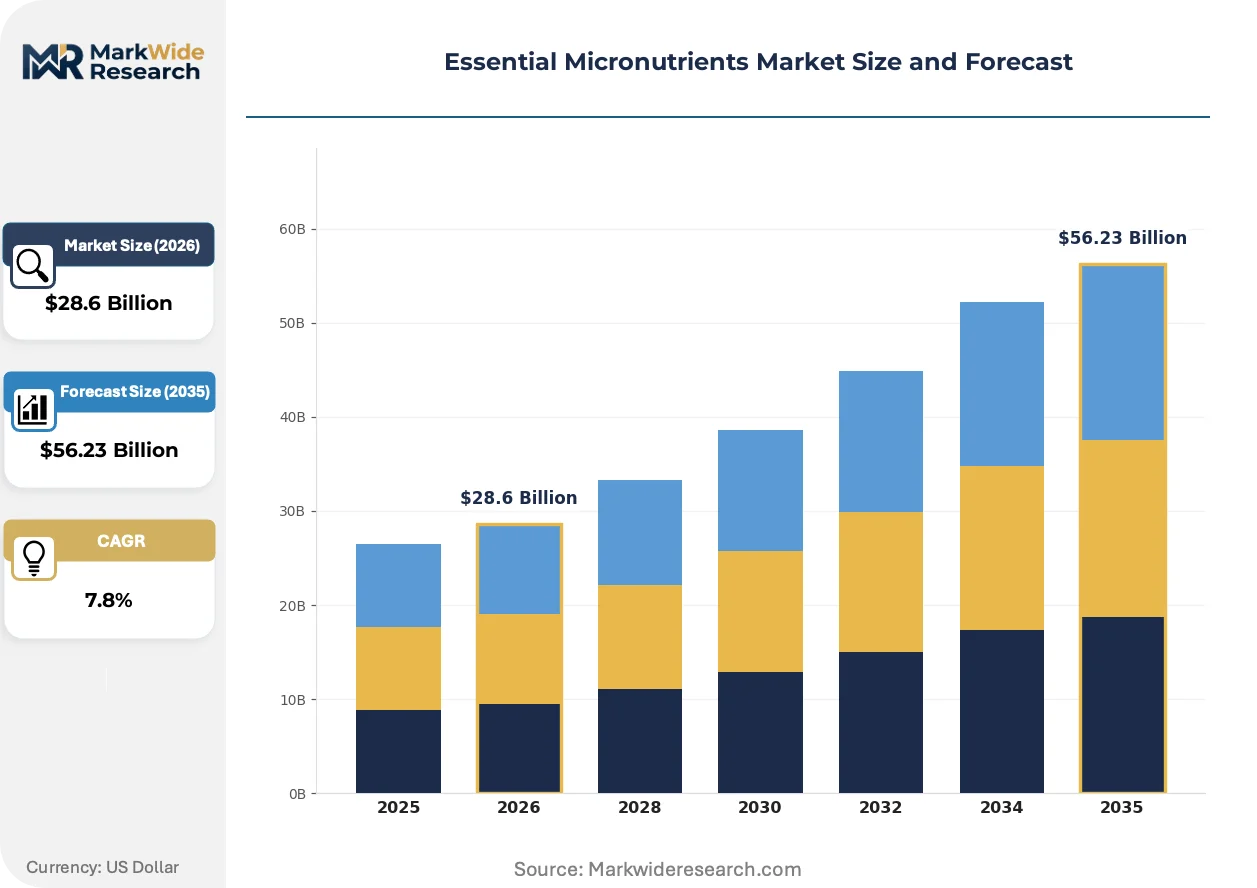
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Trace Elements, Antioxidants Application: Dietary Supplements, Functional Foods, Fortified Beverages, Animal Feed End User: Individuals, Healthcare Providers, Nutraceutical Companies, Food Manufacturers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | The Mosaic Company, Yara International ASA, Nutrien Ltd., Haifa Group, ICL Specialty Fertilizers, BASF SE, Koch Agronomic Services, Tessenderlo Kerley, Compass Minerals International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Micronutrients Market Evolving Landscape
Digital agriculture platforms and advanced delivery mechanisms are restructuring how micronutrients move from chemical synthesis to biological uptake, compressing the value chain and elevating technical performance metrics over commodity pricing.
Microencapsulation using lipid and polymer matrices is modularizing vitamin and mineral protection against oxidation, moisture, and gastric degradation. Nutraceutical manufacturers in Germany and Switzerland are adopting these systems for time-release supplement formulations. The technology is modularizing supplier relationships by enabling toll manufacturing agreements that separate R&D-intensive coating operations from bulk synthesis.
REACH restrictions on certain inorganic processing aids and carriers are compelling European premix suppliers to qualify alternative chelating agents and excipients. The ECHA framework now requires extended toxicological dossiers for zinc oxide and copper sulfate used in feed applications. Mineral premix formulators are responding by accelerating glycinate and protein-complexed mineral substitution programs ahead of sunset date timelines.
Livestock integrators are consolidating micronutrient procurement through direct contracts with specialty chemical producers, bypassing traditional distributor networks. This pattern concentrates specification-setting power with veterinary nutrition teams at large poultry and swine operations in Brazil and Thailand. The shift is most pronounced in markets where vertical coordination between genetics, feed, and processing has advanced furthest.
Essential Micronutrients Market Segmentation
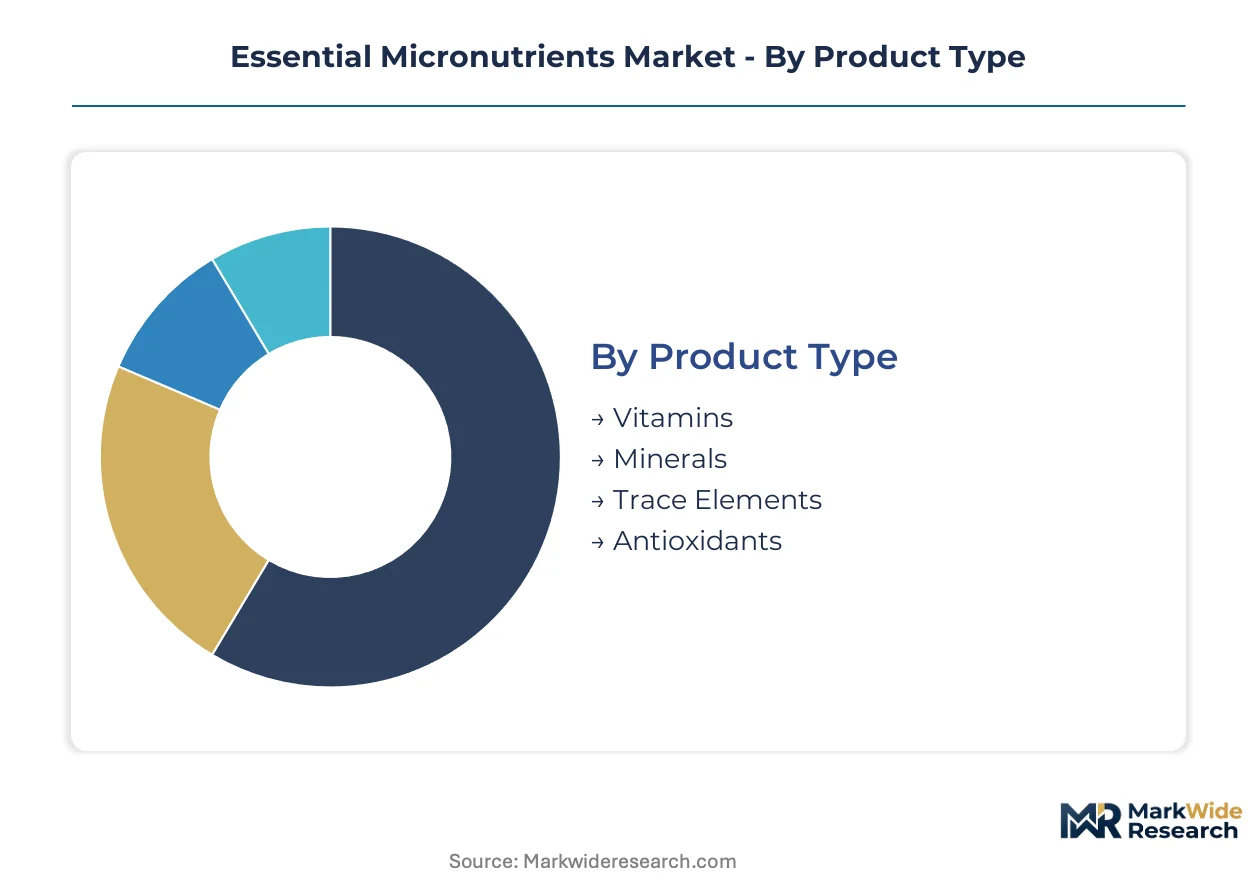
Micronutrient suppliers face divergent certification burdens across product tiers, with pharmaceutical-grade vitamins requiring GMP validation cycles of 18-24 months while agricultural-grade minerals operate under feed safety frameworks with shorter qualification timelines. Understanding how these regulatory layers map to segment economics determines capital allocation and margin capture strategies.
Product Type:
Vitamins carry the heaviest certification load, requiring FDA compliance under DSHEA and EFSA novel food assessments for new formulations, whereas trace elements navigate REACH authorization through ECHA with toxicological dossier requirements.
- Vitamins:Organic compounds including fat-soluble (A, D, E, K) and water-soluble (B-complex, C) molecules synthesized through fermentation or chemical processes. Demand concentrates in dietary supplements across Germany and Switzerland where preventive nutrition protocols drive premium formulation uptake, constrained by microencapsulation stability failures above 90°C in extruded feed applications.
- Minerals:Inorganic elements including macrominerals (calcium, phosphorus, magnesium, potassium) and microminerals supplied as sulfates, oxides, or carbonates. Livestock integrators in Brazil and Thailand are consolidating direct procurement contracts, bypassing distributors to capture specification-setting power through veterinary nutrition teams.
- Trace Elements:Metals required in microgram-to-milligram concentrations including iron, zinc, copper, manganese, selenium, iodine, and cobalt. Selenium and cobalt face supply interruptions when copper and nickel smelter output fluctuates with industrial demand cycles.
- Antioxidants:Compounds including vitamin E, selenium, carotenoids, and polyphenols that inhibit oxidative degradation in biological systems and formulated products.
Leading the category by volume: Minerals. Growing fastest: Vitamins.
Application:
Application segments stratify by margin structure, with pharmaceutical and nutraceutical channels commanding premium pricing against agricultural-scale economics in feed applications.
- Dietary Supplements:Capsules, tablets, powders, and liquids delivering concentrated micronutrient doses for individual consumption. Consumers across China are shifting from reactive healthcare to preventive nutrition protocols, accelerating incorporation into daily regimens.
- Functional Foods:Processed foods with added micronutrients beyond basic nutritional value, including fortified dairy, cereals, and bakery products. State-backed nutrition initiatives in China are accelerating micronutrient incorporation across food systems.
- Fortified Beverages:Liquid products including juices, dairy drinks, and functional waters with embedded vitamins and minerals. EFSA population reference intake revisions are compelling manufacturers to reformulate with standardized premixes.
- Animal Feed:Premixes and complete feeds for livestock, poultry, aquaculture, and companion animals. Precision livestock operations in the Netherlands and Denmark deploy sensor-driven feeding systems integrating trace mineral supplementation with real-time metabolic monitoring.
Dietary supplements capture the highest margin pool. Animal feed dominates volume throughput.
End User:
End user concentration determines specification complexity, with healthcare providers and nutraceutical companies demanding certificate-of-analysis documentation that individual consumers rarely require.
- Individuals:Direct consumers purchasing micronutrient products for personal or family use through retail and e-commerce channels. Online retail platforms in urban China are displacing traditional pharmacy distribution for repeat supplement purchases.
- Healthcare Providers:Hospitals, clinics, and practitioners prescribing or recommending therapeutic micronutrient protocols. Therapeutic dosing requirements in clinical settings demand pharmaceutical-grade purity with batch-level traceability.
- Nutraceutical Companies:Formulators combining micronutrients into branded supplement and functional food products. German and Swiss manufacturers are adopting lipid and polymer matrix microencapsulation for time-release formulations.
- Food Manufacturers:Industrial processors integrating micronutrient premixes into mass-market food and beverage production. Stricter FDA and EFSA fortification mandates are reshaping formulation requirements across export destinations.
Food manufacturers drive bulk volume procurement. Nutraceutical companies generate the steepest margin expansion.
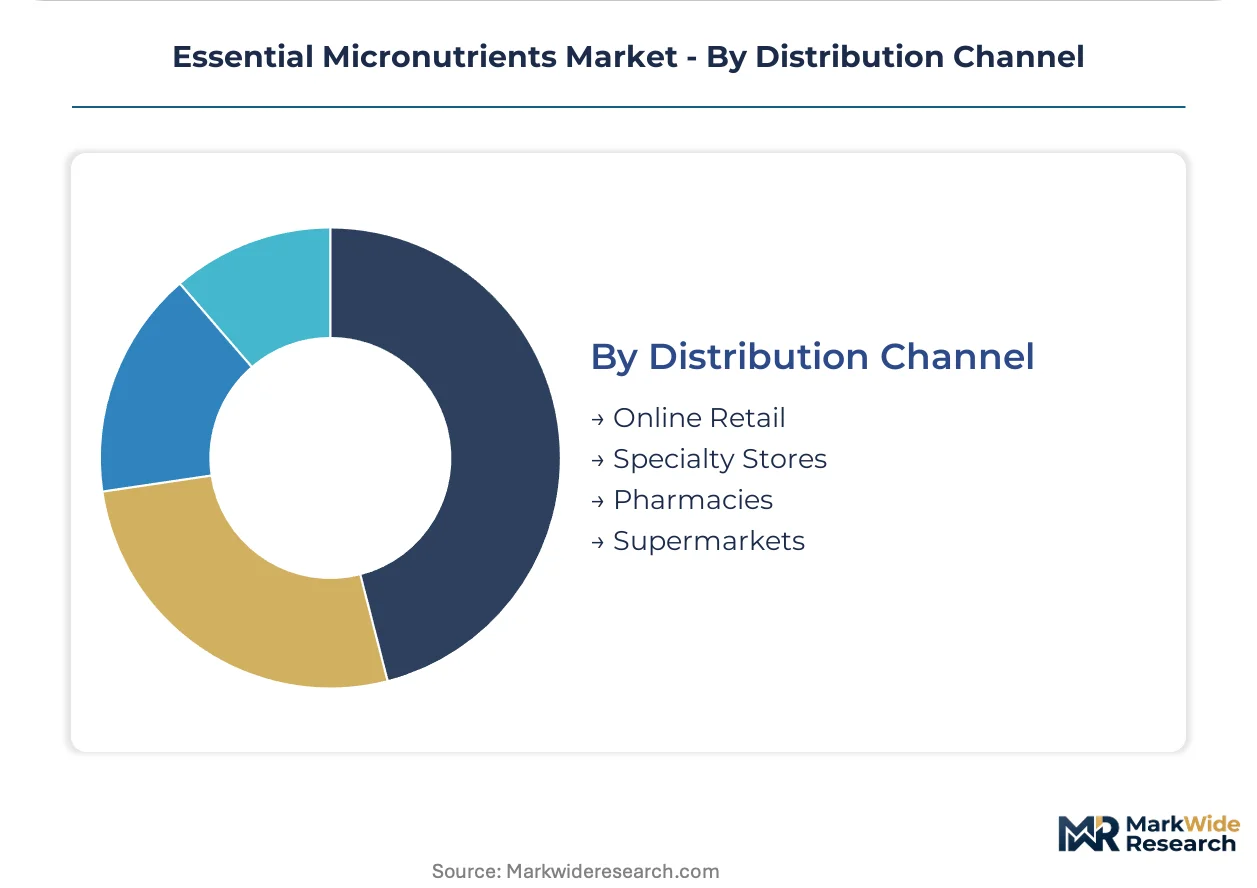
Distribution Channel:
Channel selection reflects customer sophistication and repurchase frequency, with pharmacies retaining clinical credibility while online platforms capture subscription-based replenishment.
- Online Retail:E-commerce platforms, direct-to-consumer brands, and marketplace sellers fulfilling home delivery. Subscription models are compressing customer acquisition costs for repeat vitamin purchases in digitally mature markets.
- Specialty Stores:Health food retailers, nutrition shops, and sports-focused outlets with trained staff consultation. Staff expertise justifies premium positioning for complex multi-nutrient formulations.
- Pharmacies:Licensed dispensaries with pharmacist oversight, particularly dominant for prenatal and therapeutic micronutrient categories. Regulatory qualification requirements limit new entrant penetration.
- Supermarkets:Mass-market grocery and hypermarket chains carrying fortified foods and basic supplement SKUs. Private label expansion is compressing branded margin pools in staple categories.
Supermarkets move the highest unit volumes. Online retail is climbing the fastest with subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shijiazhuang's industrial corridor anchors China's micronutrient production capacity, with state-backed nutrition initiatives accelerating incorporation across food and feed systems nationwide. Demand concentrates in coastal manufacturing zones serving both domestic consumption and export markets.
China
SAMR fortification mandates and expanding middle-class consumption drive micronutrient uptake across food processing. The dual carbon goals are reshaping mineral extraction and processing standards in northern industrial zones. Shandong Peninsula manufacturers are scaling chelated mineral output for aquaculture and livestock feed exports.
United States
FDA guidance under DSHEA and precision livestock adoption in Iowa and Nebraska drive differentiated demand patterns. The EPA coordinates with USDA on feed-grade mineral environmental discharge standards. California's Central Valley specialty crop producers are integrating foliar micronutrient delivery with controlled-release fertilizer platforms.
Germany
EFSA population reference intake revisions compel food manufacturers to reformulate with standardized premixes. REACH authorization requirements through ECHA force glycinate substitution programs ahead of sunset dates. Bavarian nutraceutical manufacturers are adopting lipid-matrix microencapsulation for time-release supplement formulations.
Brazil
Vertical coordination between genetics, feed, and processing concentrates specification-setting power with veterinary nutrition teams. ANVISA regulates therapeutic mineral dosing in livestock applications. São Paulo state poultry integrators are consolidating direct procurement contracts with specialty chemical producers, bypassing traditional distribution networks.
Netherlands
Sensor-driven feeding systems in dairy operations integrate trace mineral supplementation with real-time metabolic monitoring. EFSA standards drive premix qualification timelines for export-oriented food manufacturers. Wageningen University's research cluster is advancing precision livestock nutrition protocols adopted across Danish and German border regions.
Essential Micronutrients Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the micronutrient value chain, with integrated mining-chemical conglomerates controlling upstream mineral inputs while specialty formulators capture premium margins through technical performance. The supplier base stratifies into three tiers: bulk mineral processors operating on scale economics, chelation and microencapsulation specialists competing on bioavailability metrics, and precision agriculture platforms bundling nutrient delivery with digital farming tools. Dominant competitive moves include backward integration into captive sulfate and oxide sources outside Chinese supply chains, and technology licensing agreements that separate R&D-intensive coating operations from commodity synthesis.
Among North American integrated nutrient suppliers, Nutrien Ltd. and The Mosaic Company occupy positions that exemplify upstream control over potash and specialty mineral infrastructure. Yara International ASA anchors the European precision agriculture tier, while Haifa Group and ICL Specialty Fertilizers represent the water-soluble and controlled-release formulation specialists competing on technical performance rather than bulk volume throughput.
| Leading Market Players |
|---|
| The Mosaic Company |
| Yara International ASA |
| Nutrien Ltd. |
| Haifa Group |
| ICL Specialty Fertilizers |
| BASF SE |
| Koch Agronomic Services |
| Tessenderlo Kerley |
| Compass Minerals International |
| Others |
Value Network & Pricing Analysis
Livestock integrators in Brazil and Thailand concentrate procurement power through direct contracts with specialty chemical producers, anchoring the market on value-based pricing tied to animal performance outcomes rather than commodity mineral benchmarks. This buyer consolidation forces suppliers to demonstrate bioavailability metrics and environmental compliance premiums that standard-grade mineral processors cannot match.
Pricing Analysis
Value-based pricing anchored to feed conversion ratios and livestock mortality reduction dominates the premium tier, where chelated zinc glycinate and methionine-complexed copper command spreads over inorganic sulfates based on documented absorption rates. Pharmaceutical-grade vitamins carry GMP certification premiums that separate FDA-compliant manufacturers from agricultural-grade competitors, while commodity mineral sulfates face cost compression from Chinese sulfate exports and spot-market selenium volatility. Dairy operations in the Netherlands show least price sensitivity due to sensor-integrated nutrition systems that monetize micronutrient precision, whereas Southeast Asian aquaculture feed mills operate on thin specification margins that amplify volatility in cobalt and iodine sourcing.
Supply Chain Analysis
Reverse-logistics flows for expired pharmaceutical-grade vitamin batches and feed premix returns create secondary raw material streams that qualified processors reintegrate under GMP traceability protocols. Upstream mineral concentration rests in China for selenium and cobalt refining, Kazakhstan for sulfate processing, and Chile for copper-derived trace element extraction, with Chinese dominance in chelation technology creating single-source vulnerability for European premix formulators facing REACH authorization deadlines. Distribution runs through vertically coordinated livestock integrators in Brazil and precision agriculture platforms in the United States that bypass traditional distributor networks, compressing channel margins and accelerating direct specification-setting power with veterinary nutrition teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade GMP certification capacity operates as the binding constraint propping premium pricing, with 18-24 month validation cycles limiting new entrant supply expansion and protecting incumbent margin pools.
For Market Incumbents: Cement market position by accelerating captive sulfate and oxide sourcing in Kazakhstan and Chile ahead of Chinese supply chain reconfiguration disruptions, while investing in lipid-matrix microencapsulation R&D to defend against heat-stability failures in extruded feed applications above 90°C. Prioritize glycinate substitution programs ahead of ECHA sunset dates to preempt REACH-driven qualification losses. For New Entrants and Emerging Players: Begin with underpenetrated Sub-Saharan African markets where Nigeria, Kenya, and Ethiopia scale national food fortification programs for staple grain processing, offering standardized premix procurement contracts without incumbent distributor relationships. Target cultivated meat media formulation as a white-space application requiring custom micronutrient specifications distinct from conventional animal nutrition. For Investors and Strategic Acquirers: The window for entry favors specialty chelation and microencapsulation technology holders with existing EFSA and FDA qualification dossiers, positioned to consolidate as REACH restrictions force glycinate adoption timelines. Monitor ECHA authorization sunset date announcements and SAMR fortification mandate expansions as inflection signals for premium mineral premix demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Sulfate Sources | Kazakhstan and Chile mining partnerships reduce Chinese supply chain concentration risk for European premix exporters. |
| Glycinate Substitution Program Acceleration | EFSA and ECHA regulatory deadlines force mineral premix reformulation ahead of copper sulfate authorization withdrawals. |
| Precision Agriculture Platform Partnership | Yara International and similar digital farming bundling creates channel control over foliar micronutrient delivery in California and Morocco. |
| Sub-Saharan African Market Entry | Nigeria and Ethiopia national fortification programs offer first-mover premix procurement contracts without incumbent competition. |
| Cultivated Meat Media Formulation Development | Precision fermentation facilities require custom micronutrient specifications distinct from conventional livestock premix standards. |
Research Methodology
Multi-period observation of GMP certification timelines, REACH authorization sunset schedules, and livestock feed conversion ratio improvements anchored the trend analysis, supplemented by interviews with premix formulators, veterinary nutrition directors at Brazilian poultry integrators, pharmaceutical-grade vitamin plant managers, and EFSA regulatory affairs specialists. Secondary validation drew from ECHA toxicological dossier databases, FDA DSHEA guidance documents, SAMR fortification mandate filings, and customs trade data for sulfate and oxide mineral flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrix modeling connected raw mineral extraction through chelation processing to end-use application demand, with segmentation across product type, application channel, and end-user concentration determining volume and value allocation. CAGRs derived from regression analysis of historical qualification timeline compression, regulatory mandate adoption curves, and livestock productivity metric correlations. Forecast inputs incorporated sensor-driven feeding system penetration rates in Dutch dairy operations and cultivated meat facility construction pipelines.
Underlying measurement precision varies by segment; pharmaceutical-grade vitamins and chelated minerals carry tighter precision than commodity sulfate blends due to certification documentation density. Forecasts reflect documented assumptions regarding ECHA authorization timelines and SAMR mandate enforcement consistency. Practitioners should monitor EFSA population reference intake revision announcements and Chinese dual carbon policy implementation in Shandong Peninsula processing zones for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
Vitamin Premix Market