
 Asia-Pacific Methanol Market | 2026-2036
Asia-Pacific Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Methanol Market Insights
China's dual carbon goals is shifting methanol demand toward low-carbon and coal-chemical integration pathways. Sinopec leverages its massive refining-chemicals network to dominate coastal supply. Shenhua Ningxia Coal Industry Company anchors production in the northwest coal belt through gasification-based output. Baofeng Energy differentiates via backward integration into coal mining and captive power generation.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily from syngas derived via steam reforming of natural gas or coal gasification, serving as a foundational chemical intermediate and emerging fuel. Formaldehyde production occupies the largest demand share among product types due to its ubiquity in resins and construction materials. Fuel cell applications represent the fastest-expanding end-use segment as hydrogen-carrier chemistry gains traction in South Korean and Japanese mobility pilots. Steam reforming technology leads installed capacity, though biomass conversion is attracting investment as feedstock diversification intensifies.
China's MEE enforces emissions intensity benchmarks on coal-to-methanol plants, while South Korea's MFDS regulates methanol purity standards for fuel-cell grade applications. Japan's METI coordinates hydrogen-methanol cofiring trials under national decarbonization roadmaps. Stakeholders must track how carbon border adjustments and feedstock cost spreads between coal and natural gas reshape regional competitive advantage.
Market Dynamics
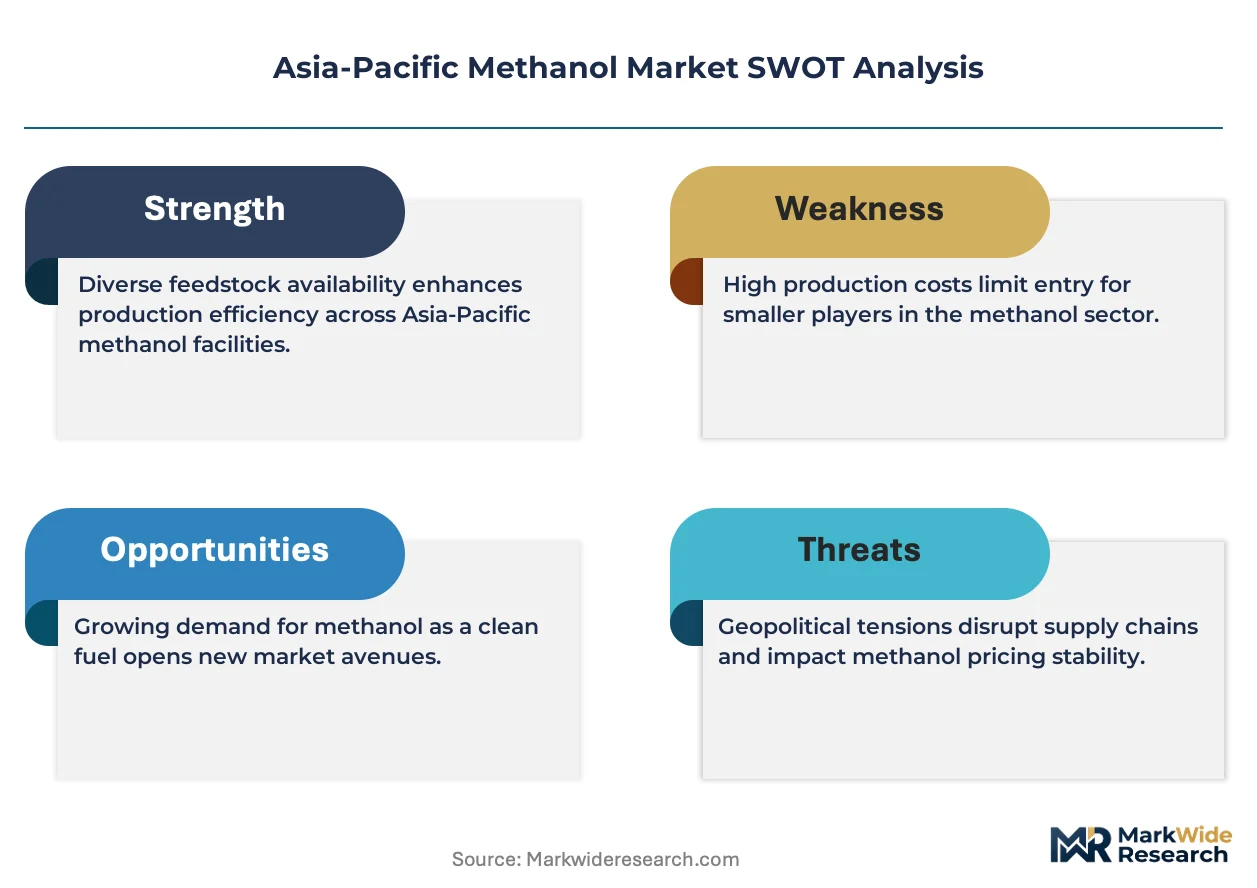
China's dual carbon goals are compressing coal-to-methanol economics while electrifying hydrogen-carrier chemistry across South Korean and Japanese mobility pilots. Feedstock cost spreads between domestic coal and imported natural gas now determine plant-level competitiveness in real time.
Growth Catalysts
- India's PLI scheme for clean fuels:Production-linked incentives are accelerating domestic capacity additions for fuel-grade methanol blending. The policy targets automotive and industrial offtake.
- Fuel cell mobility pilots:Hydrogen-carrier chemistry is electrifying demand in South Korean bus fleets and Japanese maritime trials. METI coordinates national cofiring roadmaps.
- Coal-chemical integration pathways:Northwest China's gasification corridor achieves syngas economies through captive mining and power generation. Ningxia anchors this supply concentration.
Market Restraints
- Coal price volatility:Domestic thermal coal benchmarks swing with power sector demand and import policy. Gasification plants face margin compression when coal rallies.
- Supply concentration in Shandong and Ningxia:Six producers control over half of China's merchant methanol output. Disruption at any major complex ripples through regional pricing.
- Natural gas import dependency:Steam reforming economics in South Korea and Japan hinge on LNG contract terms. Spot price spikes idle capacity.
Strategic Opportunities
- Biomass conversion technology:Agricultural residue gasification offers feedstock diversification for coastal provinces facing coal restrictions. Pilot plants in Jiangsu validate yields.
- Maritime fuel blending:IMO 2025 sulfur caps are opening vessel bunkering demand for methanol-diesel emulsions. Singapore and Rotterdam trials inform Asia-Pacific adoption.
- Carbon border adjustment positioning:EU CBAM implementation creates premium tiers for low-carbon methanol. Chinese exporters with CCS retrofits capture arbitrage.
Industry Challenges
- Gasification engineering talent scarcity:Experienced process designers for high-pressure coal slurry units command premium compensation. Training pipelines lag capacity expansion schedules.
- Fuel-cell grade certification timelines:MFDS purity standards require 18-24 month validation cycles. Developers face working capital strain during qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Methanol Market |
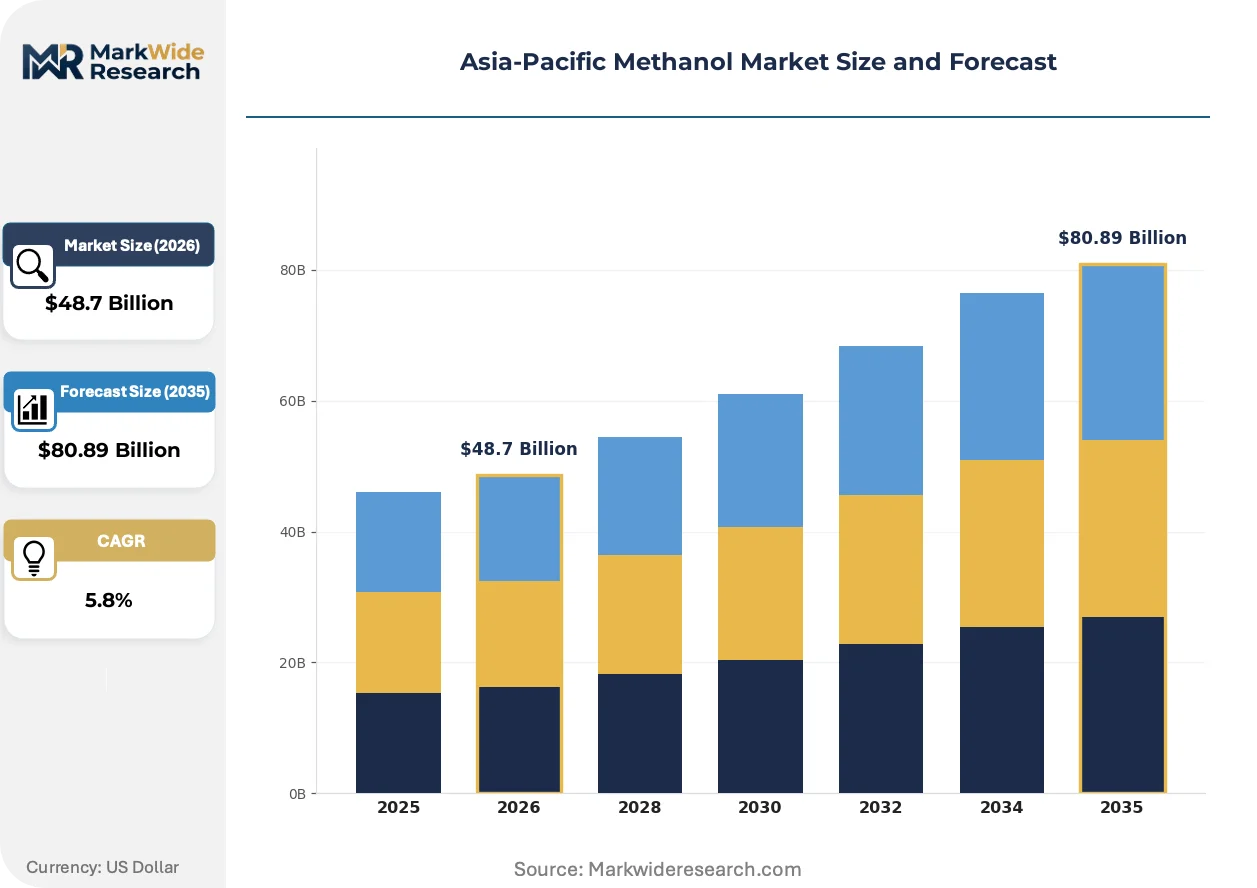
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Cell, Formaldehyde, Acetic Acid, Methyl Methacrylate End User: Chemical Industry, Automotive, Energy, Construction Application: Solvent, Antifreeze, Feedstock, Energy Storage Technology: Steam Reforming, Gasification, Catalytic Conversion, Biomass Conversion |
| Companies Covered | Baofeng Energy, Petronas, Sinopec, Shenhua Ningxia Coal Industry Company, Shanghai Huayi, CHN Energy, Zagros Petrochemical Company, Gujarat Narmada Valley Fertilizers and Chemicals Ltd, China Coal Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Methanol Market Trends and Innovations
Electrolysis-to-methanol synthesis is bridging renewable power and chemical production, while regulatory pressure on embodied carbon intensifies feedstock traceability requirements across the value chain.
Power-to-X methanol synthesis is electrifying project development in Australia's Pilbara and Chile's Atacama. Renewable hydrogen and captured CO₂ combine in modular reactors sized for stranded wind assets. Japanese trading houses anchor offtake for shipping decarbonization trials, compressing the cost gap with fossil routes faster than modelled.
China's MEE emissions intensity benchmarks are forcing coal-to-methanol plants toward carbon capture retrofits or closure. Plants exceeding 3.5 tonnes CO₂ per tonne methanol face production quotas and credit penalties. Ningxia's integrated complexes respond with pre-combustion capture and enhanced oil recovery offtake.
Long-term offtake contracting is displacing spot procurement for fuel-grade methanol in South Korean mobility clusters. Bus operators and hydrogen station developers seek ten-year supply certainty to underwrite infrastructure capex. The shift concentrates buyer power among three metropolitan consortia in Seoul, Busan, and Gwangju.
Asia-Pacific Methanol Market Segmentation
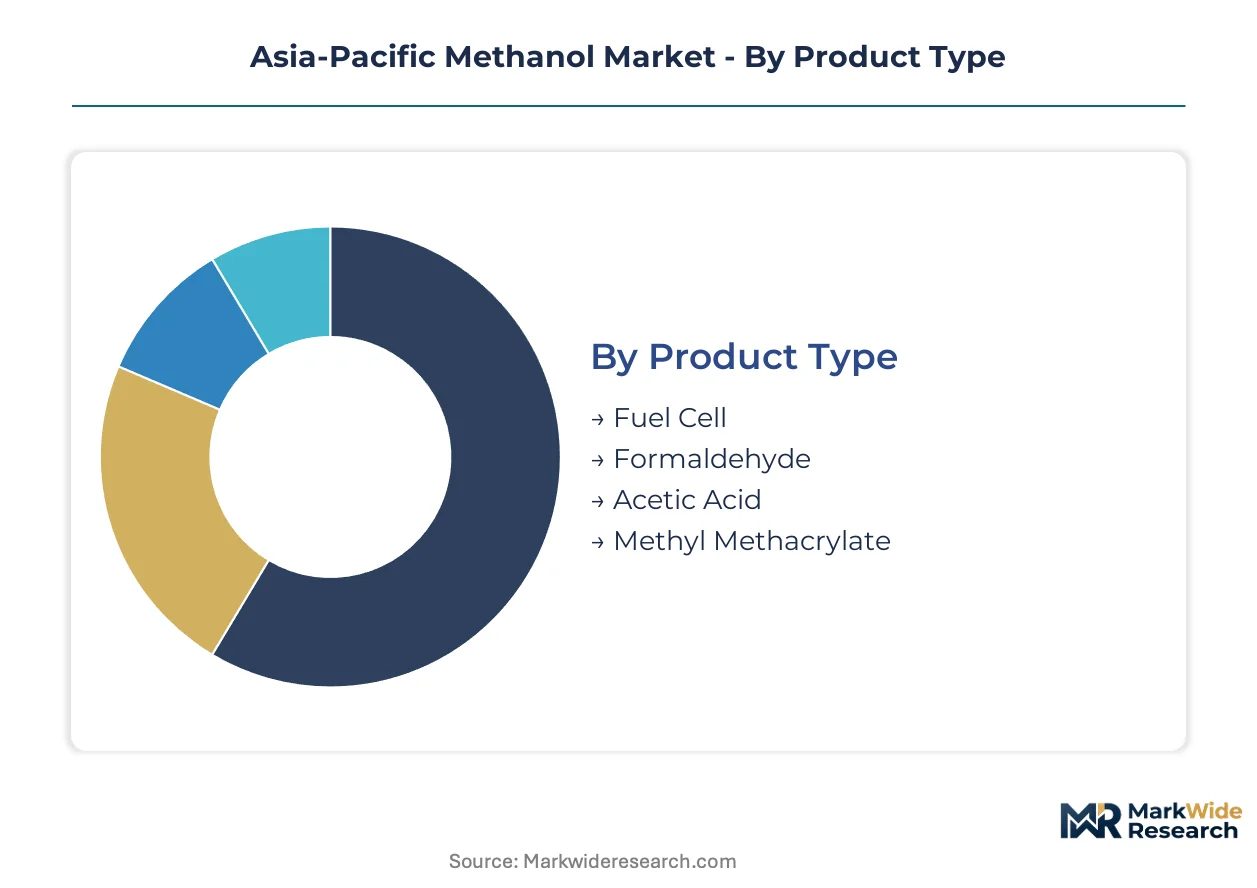
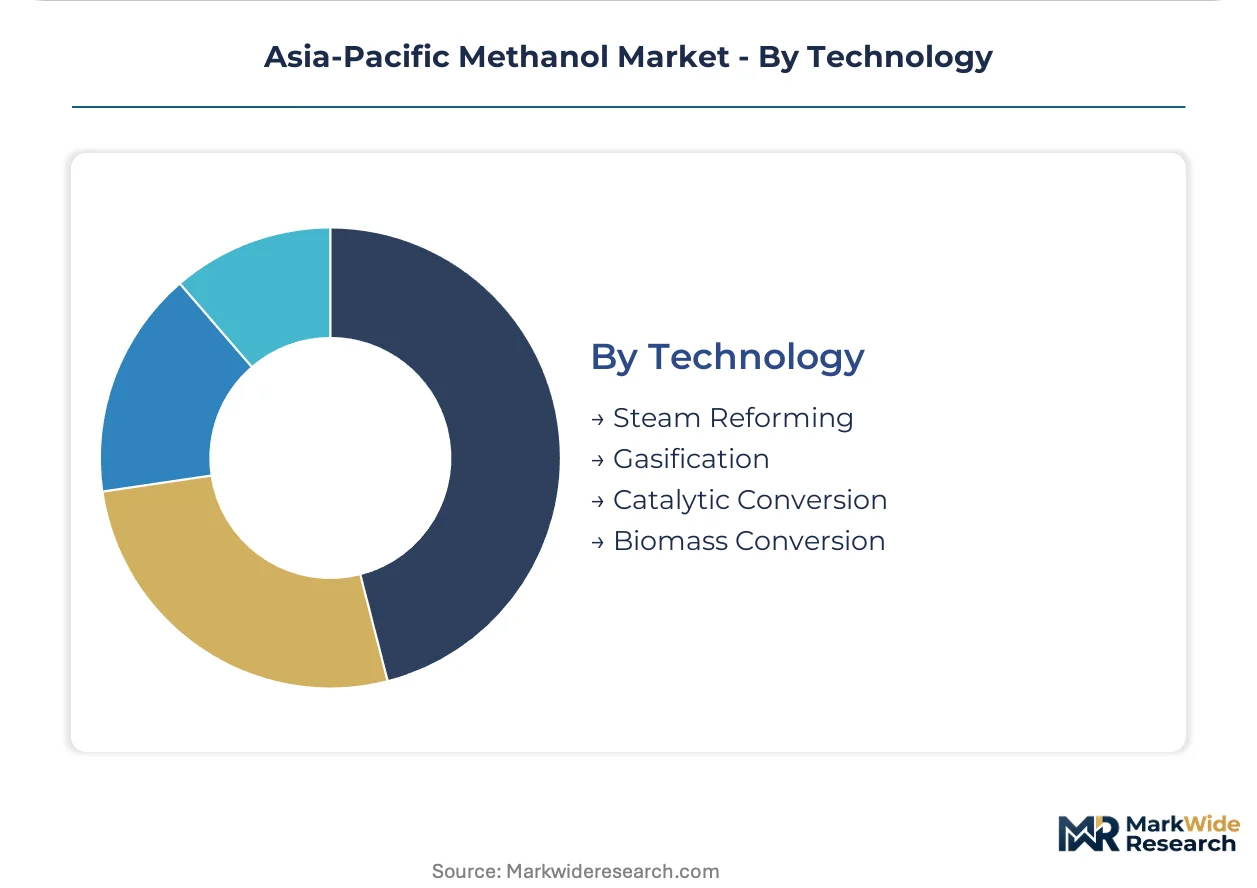
Segmentation in Asia-Pacific methanol reveals how feedstock pathways and end-use specifications fragment production economics. Each dimension—product chemistry, customer industry, functional application, and conversion technology—carries distinct margin profiles and regulatory exposure.
Product Type:
Standardization dominates fuel-grade and formaldehyde streams, while fuel-cell and specialty derivatives demand purity certification and custom synthesis protocols.
- Fuel Cell:Ultra-high purity methanol serves hydrogen-carrier chemistry for South Korean bus fleets and Japanese maritime pilots. MFDS certification requirements enforce 99.85% minimum purity with strict contaminant limits. Demand concentrates in metropolitan mobility clusters seeking ten-year supply certainty.
- Formaldehyde:Industrial-grade methanol feeds resin production for construction and furniture manufacturing across eastern China's chemical corridor. Sinopec and regional merchant producers supply this volume-dominant segment through pipeline and tanker networks.
- Acetic Acid:Carbonylation-grade methanol supplies vinyl acetate and PTA precursor chains.
- Methyl Methacrylate:Specialty-grade streams feed acrylic polymer production for automotive glazing and electronics.
Most installed capacity flows through Formaldehyde. Expansion is steepest in Fuel Cell.
End User:
Volume buyers in commodity chemicals contrast with specification-sensitive offtakers in automotive and energy storage.
- Chemical Industry:Formaldehyde, acetic acid, and solvent manufacturers absorb the majority of merchant methanol output. Ningxia's integrated coal-chemical complexes anchor supply to this segment through captive syngas economies.
- Automotive:Fuel blending and fuel-cell mobility pilots in China and India are accelerating fuel-grade offtake. India's PLI scheme for clean fuels targets automotive applications specifically.
- Energy:Power-to-X projects and hydrogen carrier applications are emerging offtake channels.
- Construction:Formaldehyde-based resins for plywood and insulation drive steady industrial demand.
Chemical Industry claims the largest volume share. Automotive is climbing the fastest.
Application:
Functional roles range from commodity solvent use to emerging energy storage chemistry with diverging margin structures.
- Feedstock:Intermediate chemical production consumes methanol at massive scale across China's coal-chemical belt. Gasification-based plants achieve cost advantages through backward integration into captive mining.
- Energy Storage:Hydrogen carrier and power-to-methanol applications are gaining traction in South Korean and Japanese decarbonization roadmaps. METI coordinates national cofiring trials.
- Solvent:Paint, coating, and pharmaceutical extraction applications require technical-grade specifications.
- Antifreeze:De-icing and coolant formulations represent stable seasonal demand.
Feedstock dominates current throughput. Energy Storage shows the steepest expansion trajectory.
Technology:
Capital intensity and carbon exposure separate established thermal routes from emerging low-carbon alternatives.
- Steam Reforming:Natural gas-based reforming dominates South Korean and Japanese capacity but faces LNG price volatility. Spot contract spikes idle plants and compress margins unpredictably.
- Gasification:Coal slurry gasification anchors northwest China's production base through Shenhua Ningxia and Baofeng Energy complexes. MEE emissions intensity benchmarks now force carbon capture retrofits or quota penalties.
- Catalytic Conversion:Syngas-to-methanol synthesis via copper-zinc oxide catalysts represents standard practice.
- Biomass Conversion:Agricultural residue gasification offers feedstock diversification for coastal provinces facing coal restrictions. Pilot plants in Jiangsu validate yields.
Gasification commands the largest installed base. Biomass Conversion is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China pioneered large-scale coal-to-methanol conversion during the 1990s energy security drive, establishing the technical foundation that now dominates Asia-Pacific supply. India and South Korea subsequently developed distinct demand centers around automotive blending and hydrogen-carrier chemistry.
China
Coal-chemical integration drives volume, with Sinopec's coastal refineries and Shenhua Ningxia's northwest gasification complexes anchoring supply. MEE emissions intensity benchmarks now force carbon capture retrofits or production quota penalties. The Ningxia-Shanghai corridor concentrates merchant output where six producers control majority share.
India
Automotive fuel blending and industrial solvent demand accelerate methanol consumption across Maharashtra and Gujarat manufacturing belts. The PLI scheme for clean fuels subsidizes domestic capacity additions targeting fuel-grade production. Reliance Industries and state-owned refiners anchor western coastal supply infrastructure.
Japan
Hydrogen-carrier chemistry and maritime decarbonization trials electrify demand through METI-coordinated cofiring roadmaps. Kansai and Chubu industrial clusters pilot methanol-to-hydrogen conversion for shipping fuel. Trading houses secure long-term offtake from Australian power-to-X projects.
South Korea
Fuel-cell bus fleets and hydrogen station networks in Seoul, Busan, and Gwangju metropolitan areas drive ultra-high purity methanol procurement. MFDS certification requirements enforce 99.85% minimum purity with extended validation cycles. Ten-year supply contracting now displaces spot procurement for mobility clusters.
Australia
Power-to-X methanol synthesis leverages Pilbara wind and solar assets for renewable hydrogen and captured CO₂ conversion. Japanese trading houses anchor offtake agreements for shipping decarbonization trials. Modular reactor sizing suits stranded renewable generation economics.
Asia-Pacific Methanol Market Competitive Landscape
Premium-margin players sit above commodity-margin players across carbon intensity and purity certification dimensions. The market structures around integrated coal-chemical conglomerates, state-owned energy majors, and emerging renewable synthesis specialists. Three archetypes dominate: backward-integrated miners with captive power, coastal refiners with syngas flexibility, and power-to-X developers with renewable offtake contracts. Capacity expansion and carbon capture retrofits constitute the primary competitive moves.
Among Chinese coal-chemical conglomerates, Baofeng Energy and Shenhua Ningxia Coal Industry Company exemplify the backward-integrated archetype through upstream mining and captive generation control. Sinopec occupies a position bridging coastal refining networks with chemical synthesis flexibility. These three entities anchor the merchant supply base that feeds formaldehyde, fuel-grade, and emerging hydrogen-carrier demand channels across the region.
| Leading Market Players |
|---|
| Baofeng Energy |
| Petronas |
| Sinopec |
| Shenhua Ningxia Coal Industry Company |
| Shanghai Huayi |
| CHN Energy |
| Zagros Petrochemical Company |
| Gujarat Narmada Valley Fertilizers and Chemicals Ltd |
| China Coal Group |
| Others |
Pricing and Supply Chain Analysis
Coal price volatility transmits directly through Ningxia's gasification complexes into fuel-grade methanol premiums, while LNG contract terms in South Korean steam reforming plants create divergent cost baselines across the region's two dominant production pathways. Buyers in automotive blending and hydrogen-carrier applications now face tiered exposure to these input swings.
Pricing Analysis
Contract-based long-term offtake agreements now dominate fuel-cell grade procurement, separating ultra-high purity volumes under MFDS certification from standard industrial grades. Price differentiation rests on purity thresholds and carbon intensity scores, with CCS-equipped Chinese plants commanding premiums against conventional coal routes. Cost compression in merchant formaldehyde streams is intensifying because MEE emissions quotas restrict high-carbon output. Chemical manufacturers show greatest price sensitivity, while mobility consortia in Seoul and Busan accept locked-in premiums for supply certainty.
Supply Chain Analysis
Experienced process designers for high-pressure coal slurry units face acute scarcity across Shandong and Ningxia manufacturing belts, constraining expansion timelines for gasification-based capacity. Supply concentrates in China's northwest coal belt and eastern chemical corridor, with South Korean and Japanese steam reforming plants drawing from Australian and Qatari LNG. Raw material dependencies span domestic thermal coal, imported natural gas, and agricultural residues for pilot biomass conversion. Single-source vulnerability runs through the six producers controlling majority merchant output. Distribution runs through pipeline networks to captive chemical complexes, supplemented by coastal tanker movements for fuel-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific methanol market reads as a late-cycle quality story where MFDS-certified fuel-cell grade and CCS-verified low-carbon volumes capture expanding premia against commodity formaldehyde streams.
For Market Incumbents: Cement backward integration into captive coal mining and power generation to defend margin position against feedstock volatility in Ningxia and Shandong. Prioritize carbon capture retrofits to meet MEE emissions intensity benchmarks and access EU CBAM-advantaged export tiers. Lock in ten-year offtake agreements with Korean mobility consortia before electrolysis-to-methanol routes achieve cost parity. For New Entrants and Emerging Players: Biomass conversion technology offers the most penetrable wedge for coastal Chinese provinces facing coal restrictions and emissions quotas. Target Jiangsu and Zhejiang pilot zones where agricultural residue gasification validates yields against MEE compliance requirements. Enter through tolling partnerships with stranded chemical assets seeking feedstock diversification. For Investors and Strategic Acquirers: Consolidation pressure builds where gasification engineering talent scarcity meets stranded conventional capacity facing MEE quota penalties. Long-term viability favors integrated coal-chemical complexes with pre-combustion capture and EOR offtake, or power-to-X developers with secured renewable hydrogen and Japanese trading house offtake. Watch electrolysis-to-methanol cost curves in Australia's Pilbara as inflection signal for fossil route obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | MEE emissions benchmarks force pre-combustion capture adoption to avoid production quota penalties. |
| Long-term Supply Agreement | Ten-year contracting with Seoul and Busan mobility consorties underwrites hydrogen station infrastructure capex. |
| Backward Integration | Baofeng Energy's captive coal mining and power generation achieves syngas cost advantages against merchant competitors. |
| Biomass Conversion Pilot | Jiangsu agricultural residue gasification validates feedstock diversification for coastal provinces facing coal restrictions. |
| Power-to-X Development | Pilbara renewable hydrogen and captured CO₂ synthesis secures Japanese trading house offtake for maritime decarbonization trials. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at coal-chemical complexes, procurement leads at downstream formaldehyde and acetic acid manufacturers, fuel supply specialists at Korean mobility consortia, and technical R&D directors at gasification engineering firms combined with secondary validation from customs and trade data, MEE emissions disclosures, SEC filings by listed producers, and MFDS certification registries. This triangulation ensures demand estimates from automotive blending, fuel-cell mobility, and chemical intermediate offtake align with verified capacity installations across China, South Korea, and Japan.
Historical trendline analysis of methanol-naphtha-gas price spreads and plant operating rate data established baseline growth patterns across the projection horizon. Segmentation modeling captured grade tier distinctions between fuel-cell, industrial, and formaldehyde specifications; end-use industry splits across chemical, automotive, and energy storage applications; and technology pathways spanning gasification, steam reforming, and emerging biomass conversion. CAGRs derived from capacity expansion schedules, policy incentive trajectories including India's PLI scheme, and offtake contracting velocity in Korean mobility clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrolysis cost reduction trajectories, EU CBAM implementation stringency, and Chinese coal import policy shifts. Forecasts reflect documented assumptions regarding MEE enforcement consistency, LNG contract renewal terms in Northeast Asia, and maritime fuel blending adoption rates under IMO sulfur caps. Material deviation in carbon border adjustment scope, renewable hydrogen production costs, or gasification engineering labor availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Perchloric Acid Market
Chemicals
Tromethamine Market
Chemicals
Pinoxaden Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Aerosol Insecticides Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Glyoxal Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Cummene Derivatives Market
Chemicals
Quaternium-15 Market
Chemicals
Global Cysteine Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Resorcinol Market