
 Global Syringaldehyde Market | 2026-2036
Global Syringaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Global Syringaldehyde Market Foresight
Green chemistry process intensification is tilting syringaldehyde production toward catalytic oxidation of lignin-derived precursors rather than petroleum-based routes. Merck KGaA leverages its European manufacturing base to supply high-purity crystalline grades for pharmaceutical intermediates. TCI Chemicals anchors Asia-Pacific distribution through its Tokyo-centered logistics network. Thermo Fisher Scientific Inc. competes by bundling syringaldehyde within broader research chemical portfolios for contract research organizations.
Syringaldehyde is a methoxy-substituted aromatic aldehyde with the molecular formula C9H10O3, typically synthesized via nitrobenzene oxidation or electrochemical conversion of syringol, and serves primarily as a precursor for vanillin, pharmaceutical intermediates, and polymer stabilizers. Crystalline powder grades command premium positioning due to stringent purity thresholds exceeding 99% for active pharmaceutical ingredient applications, while syrup formulations serve agrochemical and flavors producers with more tolerant specification bands. Pharmaceutical applications lead value capture given regulatory validation burdens, though polymer additives represent the fastest-growing demand pool as heat-stabilizer formulators seek bio-based aromatic structures.
EPA oversight under the Toxic Substances Control Act shapes import thresholds and purity documentation for syringaldehyde entering United States pharmaceutical supply chains, while REACH registration in the European Union imposes full substance dossier requirements on volumes exceeding one tonne annually. China's SAMR enforces GB standards for chemical intermediates that affect export competitiveness of domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost shifts and qualify alternative supply sources before specification mandates tighten.
Market Dynamics
Pharmaceutical procurement patterns are pulling syringaldehyde supply chains toward bio-based lignin oxidation routes as contract manufacturers in India and China face mounting purity documentation demands from European and North American regulators.
Growth Catalysts
- REACH substance dossier mandates:European chemical registration requirements exceeding one tonne annually are filtering out low-purity suppliers and consolidating demand around crystalline-grade producers capable of full traceability documentation.
- Vanillin synthesis demand:Natural flavor formulators are substituting petroleum-derived precursors with lignin-sourced syringaldehyde to meet clean-label specifications from multinational food manufacturers.
- Shanghai-Mumbai fine chemical clusters:Contract research organization density in these metropolitan manufacturing corridors is generating captive demand for high-purity pharmaceutical intermediates with validated synthesis protocols.
Market Restraints
- Guaiacol price volatility:Petroleum-derived precursor costs fluctuate with benzene feedstock markets, compressing margins for oxidation-route producers unable to secure long-term supply contracts.
- East Asian supply concentration:Overreliance on Chinese and Indian intermediate manufacturers creates vulnerability to export licensing delays and shipping disruptions affecting just-in-time pharmaceutical supply chains.
- Electrochemical conversion scale limits:Lignin-derived production methods face yield consistency barriers above pilot scale, constraining volume availability for polymer stabilizer formulators seeking bio-based alternatives.
Strategic Opportunities
- Brazilian agrochemical expansion:ANVISA-registered crop protection manufacturers represent underpenetrated demand for syrup-grade syringaldehyde in pesticide intermediate applications with tolerant purity bands.
- EU Green Deal bio-based mandates:European polymer additive formulators are qualifying lignin-derived aromatic aldehydes to meet renewable content thresholds in heat-stabilizer specifications.
- Direct-to-laboratory digital distribution:Research chemical platforms are bypassing traditional distributor markups for gram-scale crystalline orders from university and CRO synthesis laboratories.
Industry Challenges
- Pharmaceutical-grade certification timelines:Active pharmaceutical ingredient precursor qualification requires eighteen-to-twenty-four-month validation cycles with FDA and EMA, freezing supplier switching decisions.
- Electrochemical reactor capex intensity:Lignin oxidation scale-up demands specialized electrode infrastructure and membrane separation systems that strain mid-cap producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Syringaldehyde Market |
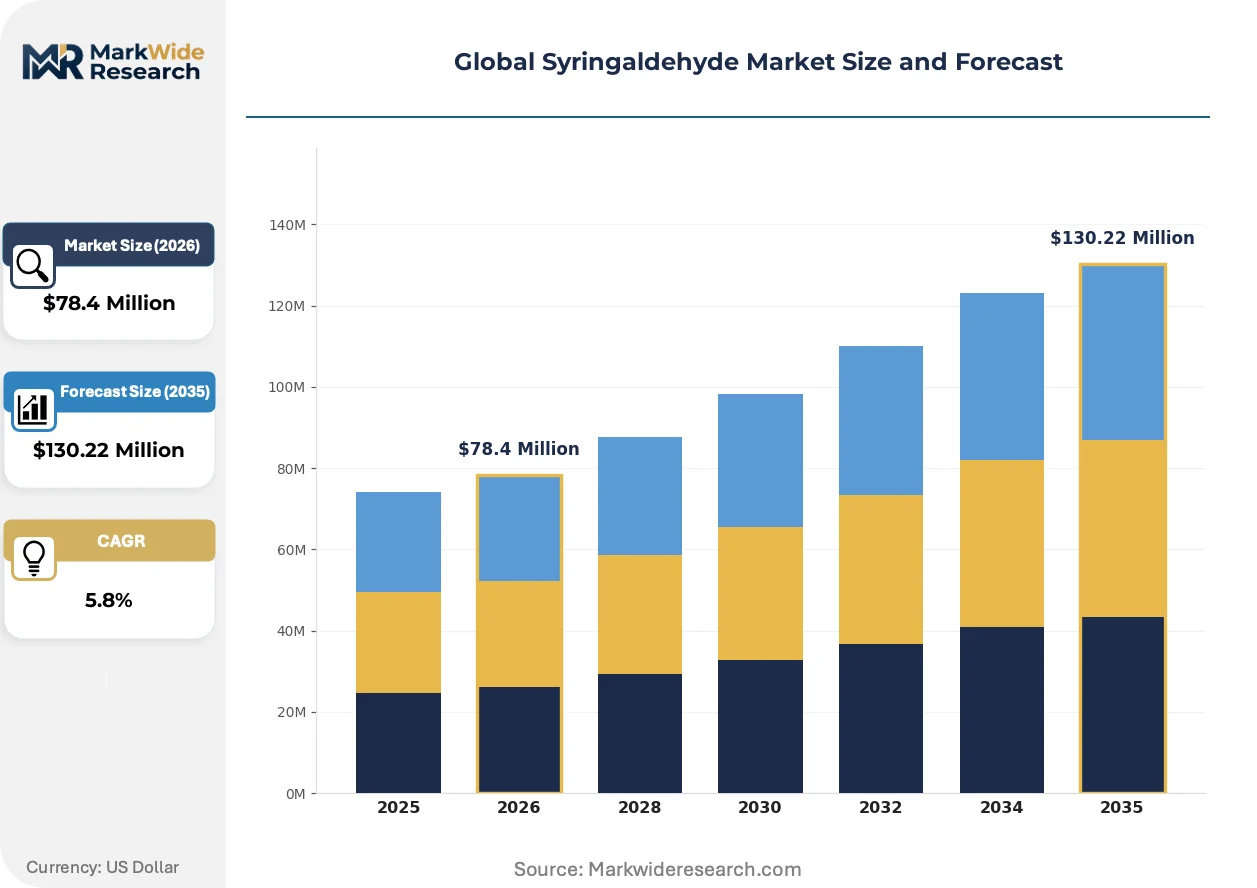
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $130.22 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Powder, Syrup, Solution, Fine Chemicals Application: Pharmaceuticals, Agrochemicals, Flavors & Fragrances, Polymer Additives End User Industry: Cosmetics Manufacturers, Chemical Intermediates Producers, Specialty Chemicals Firms, Herbicide Producers Packaging Type: Drums, Bottles, Bulk Containers, Fiber Drums |
| Companies Covered | TCI Chemicals, Sigma-Aldrich, Merck KGaA, Thermo Fisher Scientific Inc., Alfa Chemistry, Penta Manufacturing Company, AK Scientific, Target Molecule Corp, AA Blocks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Syringaldehyde Market Shifts & Advancements
Production technology and procurement architecture are simultaneously transforming as lignin valorization chemistry matures and buyer concentration forces supply chain restructuring around direct manufacturer relationships.
Catalytic oxidation systems are hybridizing electrochemical lignin depolymerization with continuous-flow reactor designs. Pharmaceutical intermediate manufacturers in Germany and Switzerland are piloting these integrated platforms to secure batch-to-batch consistency above 99.5% purity. The technology is hybridizing traditional nitrobenzene oxidation economics with bio-based feedstock claims, compressing the cost gap between petroleum and lignin routes.
EPA Toxic Substances Control Act import documentation requirements are tightening substance identity verification for syringaldehyde entering United States pharmaceutical supply chains. The agency's enhanced chemical data reporting rules are forcing foreign manufacturers to invest in analytical laboratory infrastructure or forfeit market access. Crystalline-grade importers are responding by pre-positioning certified inventory in domestic bonded warehouses to buffer customs clearance delays.
Contract research organizations are consolidating procurement around single-source manufacturer agreements with validated synthesis capabilities. Traditional research chemical distributors are losing share to direct-platform ordering from Tokyo, Shanghai, and Mumbai production facilities. This concentration is most visible in antibody-drug conjugate precursor programs where syringaldehyde-derived linkers require dedicated quality agreements with audit rights.
Global Syringaldehyde Market Segmentation
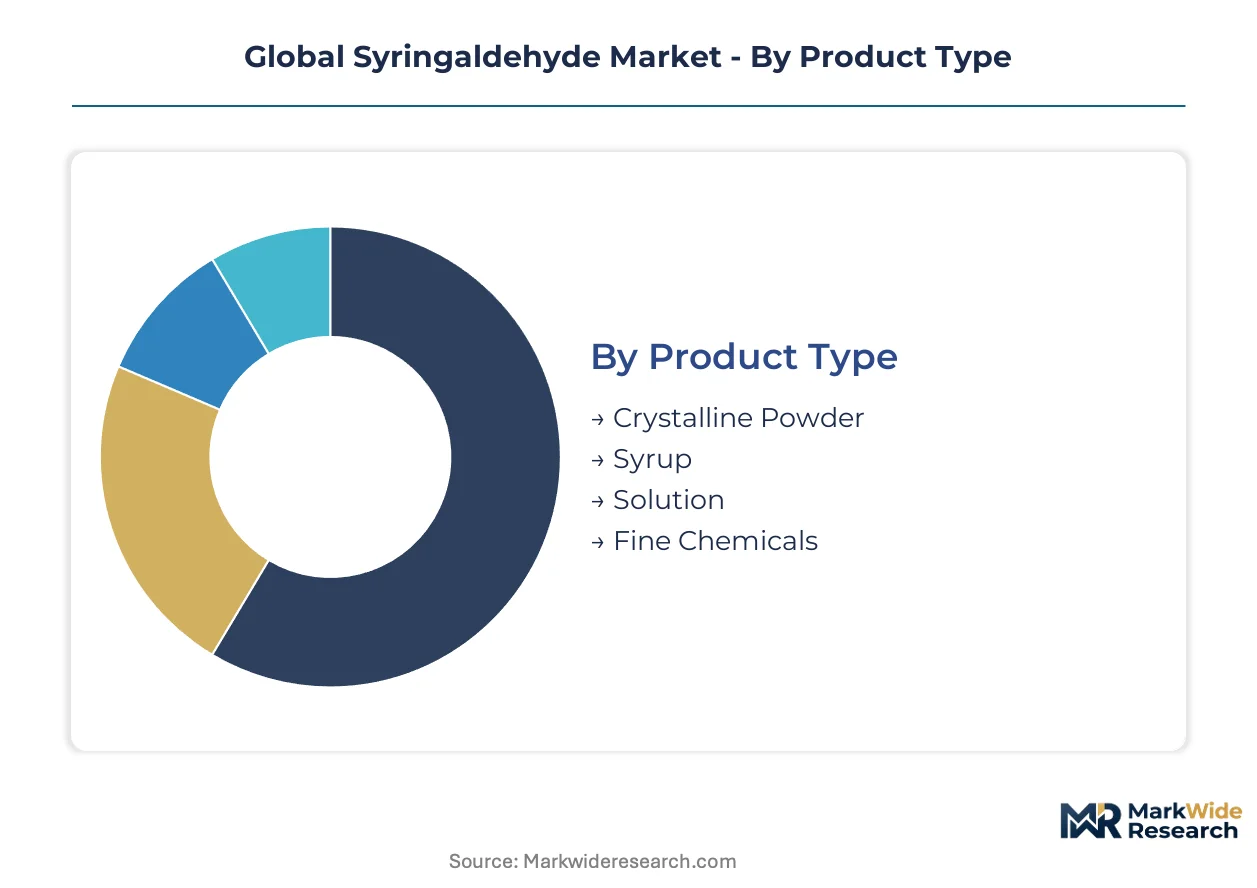
Syringaldehyde procurement patterns diverge sharply across purity grades and packaging formats. Pharmaceutical buyers demand validated crystalline supply chains with full traceability documentation, while agrochemical formulators prioritize cost-efficient syrup volumes in bulk configurations.
Product Type:
After-sales-service intensity varies dramatically across physical forms, with crystalline powder commanding dedicated technical support for synthesis troubleshooting and regulatory filing assistance.
- Crystalline Powder:High-purity solid exceeding 99% assay specifications serves active pharmaceutical ingredient precursor programs. Demand concentrates in Swiss and German pharmaceutical corridors where EMA validation protocols require batch-to-batch consistency documentation and dedicated quality agreements.
- Syrup:Aqueous or solvent-based liquid formulation with relaxed purity tolerances suits flavors and agrochemical intermediate applications. Procurement clusters around Mumbai and Shanghai contract manufacturers seeking just-in-time vanillin synthesis feedstock with minimal handling infrastructure.
- Solution:Pre-dissolved formulations in compatible solvents reduce handling complexity for small-scale research laboratories. Direct-platform distribution from Tokyo-centered logistics networks captures gram-scale orders from university synthesis programs.
- Fine Chemicals:Custom-specification grades tailored to proprietary synthesis protocols. Specialty chemical firms in Basel and Boston commission dedicated batches with modified particle size distributions.
Crystalline powder holds the largest share; momentum sits with syrup as lignin-derived production scales.
Application:
Cost tier stratification separates premium pharmaceutical validation from commodity agrochemical procurement, with polymer additives emerging as a mid-tier growth corridor.
- Pharmaceuticals:Antibiotic precursor and linker chemistry applications demand FDA and EMA-validated supply chains with eighteen-to-twenty-four-month qualification timelines. Swiss and Indian contract manufacturers anchor procurement concentration.
- Agrochemicals:Pesticide intermediate applications tolerate broader specification bands. Brazilian ANVISA-registered manufacturers represent expanding demand for syrup-grade material in crop protection synthesis.
- Flavors & Fragrances:Vanillin synthesis drives clean-label substitution toward lignin-derived syringaldehyde. European flavor houses qualify bio-based feedstocks to meet EU Green Deal renewable content thresholds.
- Polymer Additives:Heat stabilizer formulators seek aromatic aldehyde structures for bio-based plastic stabilization. German automotive suppliers are qualifying these grades for interior component specifications.
Pharmaceuticals capture the highest value per kilogram; polymer additives are expanding most quickly as automotive sustainability mandates tighten.
End User Industry:
Customer type fragmentation spans multinational pharmaceutical conglomerates, regional agrochemical blenders, and boutique cosmetic houses with divergent technical service expectations.
- Cosmetics Manufacturers:Fragrance compounders incorporate syringaldehyde derivatives into prestige perfume formulations. Paris and Grasse-based houses prioritize sustainable sourcing credentials for consumer-facing marketing.
- Chemical Intermediates Producers:Toll manufacturers and custom synthesis houses process syringaldehyde into downstream active pharmaceutical ingredients and agrochemical actives. East Asian clusters in Shanghai and Hyderabad dominate volume aggregation.
- Specialty Chemicals Firms:Diversified chemical companies bundle syringaldehyde within broader aromatic aldehyde portfolios for research and industrial applications. Direct manufacturer relationships are displacing traditional distributor channels.
- Herbicide Producers:Crop protection manufacturers integrate syringaldehyde into phenoxy herbicide synthesis pathways. Brazilian and Argentine agricultural chemical sectors drive seasonal demand spikes aligned with planting cycles.
Chemical intermediates producers hold the largest share; momentum sits with cosmetics manufacturers as clean beauty marketing intensifies.
Packaging Type:
Volume scale and handling infrastructure dictate packaging selection, with pharmaceutical precision favoring sealed bottles and agrochemical commodity flows absorbing bulk container economics.
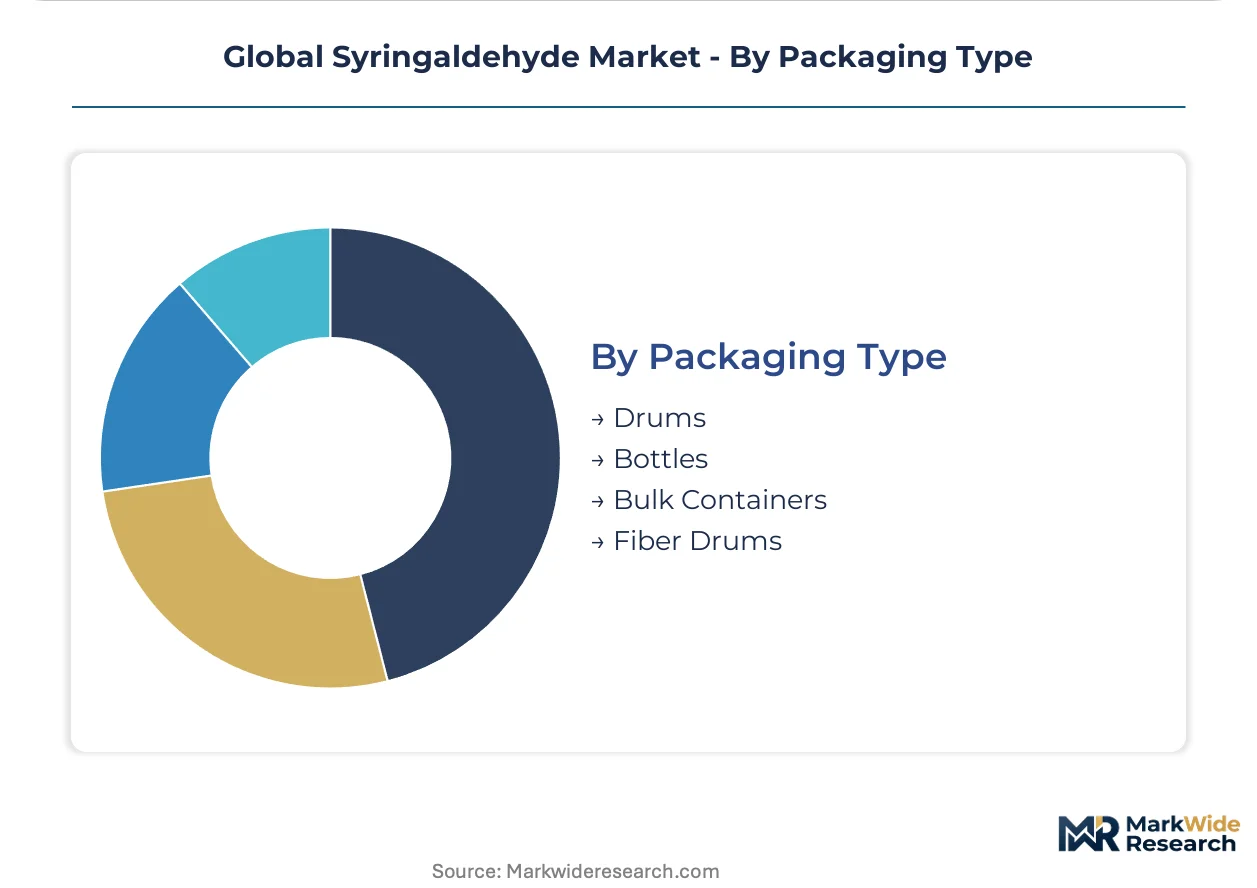
- Drums:Standard steel or plastic drums accommodate intermediate volumes for contract manufacturing operations. Mumbai and Shanghai logistics hubs maintain drum repackaging facilities for regional distribution.
- Bottles:Amber glass or fluorinated polymer bottles preserve purity for pharmaceutical and research applications. Gram-to-kilogram scales from Tokyo and Boston direct-platform suppliers bypass distributor markups.
- Bulk Containers:Intermediate bulk containers and tanker shipments serve high-volume vanillin and agrochemical intermediate producers. Chinese export infrastructure specializes in bulk consolidation for transoceanic shipment.
- Fiber Drums:Lightweight fiberboard drums with moisture barriers suit crystalline powder shipments to European and North American pharmaceutical facilities. Customs pre-clearance programs accelerate bonded warehouse release.
Drums hold the largest share; fiber drums are gaining share fastest as pharmaceutical air freight volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese syringaldehyde exports flow primarily to pharmaceutical intermediate manufacturers in Switzerland and Germany, while Indian producers supply vanillin synthesis operations across European flavor houses.
China
Shanghai-centered fine chemical clusters drive crystalline-grade production for antibiotic precursor programs. SAMR enforces GB standards on chemical intermediate exports that affect documentation burdens for European-bound shipments. Contract manufacturers in Jiangsu and Zhejiang provinces scale electrochemical lignin oxidation pilot lines to meet polymer additive specifications.
Germany
Basel-proximate pharmaceutical corridors anchor EMA-validated demand for high-purity syringaldehyde in linker chemistry applications. REACH substance dossier requirements exceeding one tonne annually filter supplier qualification toward full traceability documentation. Bavarian specialty chemical firms pilot catalytic oxidation systems integrating continuous-flow reactor designs.
Switzerland
Swissmedic oversight shapes import thresholds for active pharmaceutical ingredient precursors entering Basel and Geneva manufacturing zones. EU Green Deal bio-based mandates accelerate lignin-derived aromatic aldehyde qualification for renewable content thresholds. Contract research organizations in the Basel-Zurich corridor consolidate procurement around single-source manufacturer agreements.
India
Hyderabad and Mumbai chemical intermediate producers expand vanillin synthesis capacity for clean-label flavor substitution. CDSCO pharmaceutical regulations align with FDA precursor validation protocols for export-oriented antibiotic manufacturers. Maharashtra-based toll manufacturers aggregate syrup-grade volumes for agrochemical intermediate applications.
United States
EPA Toxic Substances Control Act import documentation tightens substance identity verification for pharmaceutical supply chain entry. Greater Boston and New Jersey research chemical clusters drive gram-scale crystalline orders through direct-platform distribution. Bonded warehouse pre-positioning accelerates customs clearance for validated inventory.
Global Syringaldehyde Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where distributor markups face displacement from direct manufacturer platforms. The vendor base separates into three strategic archetypes: diversified research chemical conglomerates bundling syringaldehyde within broader portfolios, purity-focused pharmaceutical-grade specialists, and regional intermediate producers serving commodity agrochemical applications. Dominant competitive moves include geographic expansion through logistics hub establishment and portfolio diversification into lignin-derived bio-based grades.
Among diversified research chemical suppliers, Merck KGaA, TCI Chemicals, and Thermo Fisher Scientific Inc. exemplify distinct archetype positions. Merck KGaA anchors European pharmaceutical-grade supply through its German manufacturing footprint. TCI Chemicals occupies the Asia-Pacific distribution vector with Tokyo-centered logistics networks serving gram-to-kilogram research scales. Thermo Fisher Scientific Inc. represents the bundled-portfolio approach, integrating syringaldehyde within broader aromatic aldehyde offerings for contract research organization procurement consolidation.
| Leading Market Players |
|---|
| TCI Chemicals |
| Sigma-Aldrich |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Alfa Chemistry |
| Penta Manufacturing Company |
| AK Scientific |
| Target Molecule Corp |
| AA Blocks |
| Others |
Supply & Pricing Matrix
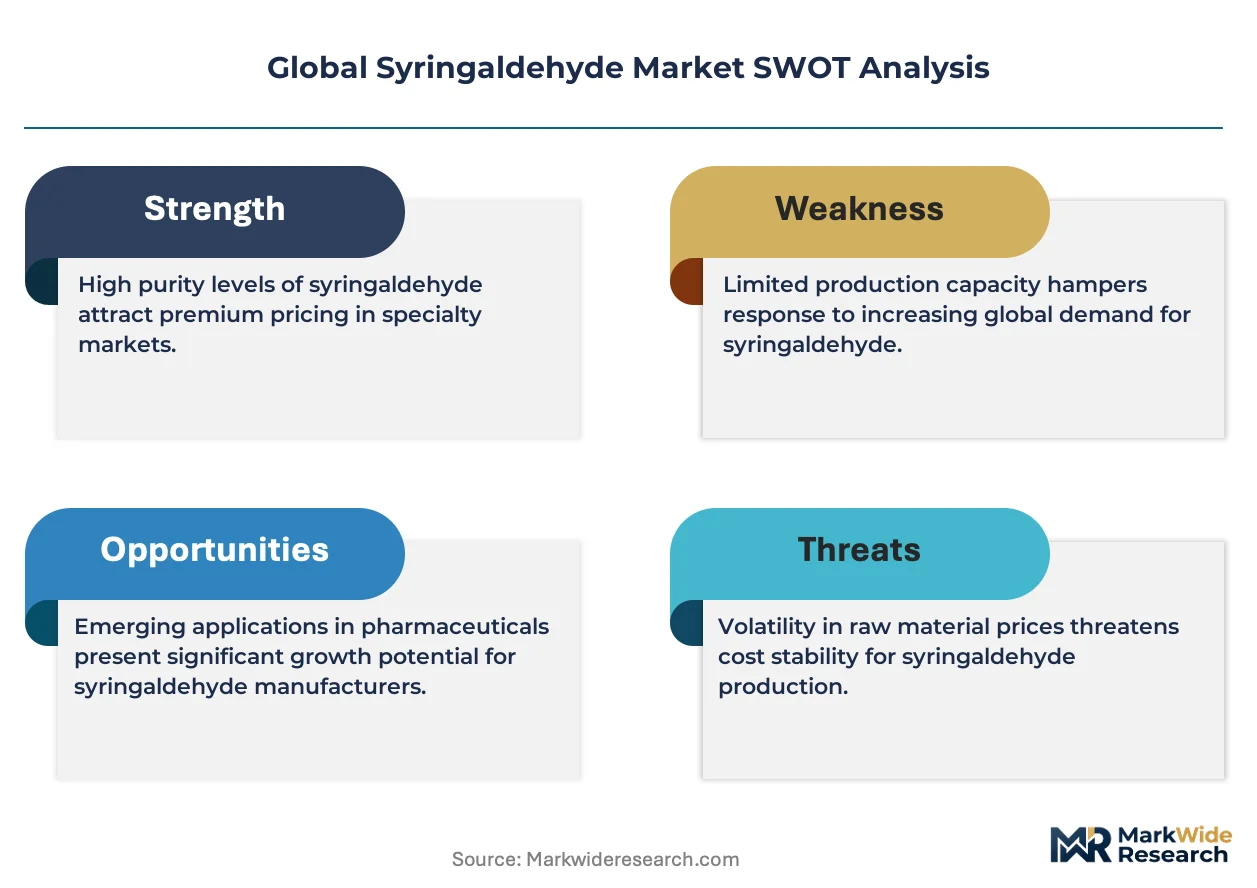
Undercapacity in Chinese electrochemical lignin oxidation facilities is compressing spot availability for crystalline-grade material and emboldening incumbent producers to extend quality-premium capture. This utilization squeeze simultaneously elevates buyer switching costs and rewards suppliers with validated EMA documentation.
Pricing Analysis
Petroleum-route versus lignin-route production technologies command divergent pricing bands, with nitrobenzene oxidation crystalline grades carrying legacy cost structures while electrochemical bio-based batches extract sustainability premiums. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and research-grade levels separates FDA-validated supply from commodity syrup volumes. Pricing pressure stems from guaiacol feedstock volatility squeezing oxidation-route margins. Agrochemical formulators exhibit highest price sensitivity; antibody-drug conjugate precursor buyers accept steep premiums for batch-to-batch consistency guarantees.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for crystalline-grade pharmaceutical shipments. Production concentrates in China, India, and Germany, with Shanghai and Mumbai anchoring intermediate manufacturing and Basel-proximate corridors hosting validation-intensive finishing. Raw material flows draw from lignin waste streams, petroleum-derived guaiacol, and nitrobenzene oxidation catalysts. Single-source vulnerability pervades EMA-validated supply chains where eighteen-to-twenty-four-month qualification timelines freeze supplier switching. Distribution runs through Tokyo-centered logistics networks for research scales and bulk container consolidation for vanillin synthesis feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Syringaldehyde procurement is becoming a service-attach business as regulatory filing assistance and synthesis troubleshooting expand faster than commodity chemical margins. Technical support contracts now capture value disproportionate to base material pricing.
For Market Incumbents: Entrench EMA-validated supply relationships by embedding quality agreement audit rights into multi-year pharmaceutical precursor contracts. Expand analytical laboratory infrastructure to preempt EPA Toxic Substances Control Act documentation demands. Backward integration into lignin feedstock sourcing secures bio-based grade claims against emerging electrochemical specialists. For New Entrants and Emerging Players: Brazilian agrochemical corridors offer underpenetrated demand for syrup-grade syringaldehyde in ANVISA-registered crop protection synthesis. Direct-platform digital distribution bypasses distributor markups for gram-scale crystalline orders from university laboratories. Qualify polymer additive specifications for German automotive heat-stabilizer applications as the fastest path to volume absorption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrochemical lignin oxidation scale-up as specialized electrode infrastructure and membrane separation systems strain mid-cap balance sheets. Target toll manufacturers with validated synthesis capabilities and existing quality agreements rather than greenfield production assets. Watch for FDA precursor validation timeline compression as the signal indicating supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Feedstock | Secures bio-based grade claims for EU Green Deal renewable content thresholds. |
| EMA Quality Agreement Expansion | Locks eighteen-to-twenty-four-month validation timelines against competitor switching. |
| Direct-to-Laboratory Digital Platform | Captures gram-scale crystalline demand from Tokyo and Boston research clusters. |
| Electrochemical Reactor Scale-Up | Bridges pilot-scale yield consistency barriers for polymer additive volume availability. |
| Bonded Warehouse Pre-Positioning | Buffers EPA customs clearance delays for validated pharmaceutical inventory. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical procurement managers, contract manufacturing executives, regulatory affairs specialists, and fine chemical distribution channel partners; and secondary validation drawing from EMA substance dossier filings, REACH registration databases, Chinese SAMR GB standard publications, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume aggregation across purity grades and packaging formats triangulated against top-down market sizing from trade flow analysis.
Forecast inputs considered pharmaceutical intermediate demand trajectories, vanillin synthesis substitution rates, and polymer additive qualification timelines across the projection horizon. Segmentation modeling spanned product type crystallinity tiers, application purity requirements, end-user industry regulatory intensity, and regional production hub concentration. CAGRs derived from weighted average growth assumptions calibrated to named capacity expansion announcements and validated supply chain documentation trends.
Macroeconomic conditions sit as an overlay; deviation in benzene feedstock pricing, ocean freight rate volatility, or European energy cost inflation would shift the trajectory. Forecasts reflect assumptions about electrochemical scale-up success rates and regulatory documentation burden stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
India Metal Treatment Chemical Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
North America Tartaric Acid Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Superplasticizer Market
Chemicals
Aluminum Chemicals Market
Chemicals
De-Icing Agents Market
Chemicals
Betaine Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Cummene Derivatives Market
Chemicals
Zinc Chemicals Market
Chemicals
Peracetic Acid Market
Chemicals
Ethanolamine Market