
 Asia-Pacific Surface Treatment Chemicals Market | 2026-2036
Asia-Pacific Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Surface Treatment Chemicals Market Outlook
The divergence between premium corrosion-protection chemistries and commodity pre-treatment formulations is realigning procurement priorities across the Asia-Pacific Surface Treatment Chemicals Market. Nippon Paint Holdings Co Ltd leverages its coatings R&D intensity to command specification-driven contracts with Japanese automotive OEMs. Henkel AG & Co KGaA anchors its regional position through backward integration into phosphate chemistry and captive supply of zirconium-based pre-treatments. NOF CORPORATION specializes in fluoropolymer surface modifiers for electronics applications, occupying a defensible niche against broader-line competitors.
Asia-Pacific surface treatment chemicals encompass formulated products including cleaners, pre-treatments, conversion coatings, and functional topcoats engineered to modify substrate adhesion, corrosion resistance, or electrical properties through controlled chemical reaction at metal or polymer interfaces. These formulations typically operate within specified pH ranges, bath temperature parameters, and immersion dwell times to achieve targeted coating weights or conversion layer thicknesses measured in micrometers. Pre-treatments and coatings dominate value capture, with phosphate and zirconium conversion coatings leading volume in automotive stamping and body-in-white lines while powder coating resins expand fastest in appliance and industrial equipment sectors where VOC regulations tighten application constraints. Electroplating technology retains entrenched positions in electronics connector finishing, though chemical conversion processes displace hexavalent chromium formulations across aerospace supply chains.
China's MEE enforces GB standards limiting hexavalent chromium and nickel discharge from plating operations, redirecting capital toward trivalent chromium and trivalent passivation chemistries. Japan's METI promotes JIS-compliant green plating initiatives that elevate barrier-to-entry for imported formulations lacking domestic certification. Australia's TGA and South Korea's MFDS coordinate less directly but propagate REACH-aligned substance restrictions through bilateral trade frameworks. Stakeholders must monitor regulatory divergence between China's national standards and emerging ASEAN harmonization proposals to avoid stranded formulation investments.
Market Dynamics
China's MEE enforcement of GB standards on heavy metal discharge is forcing simultaneous capital redeployment across phosphate conversion coating lines and plating bath reformulation, compressing supplier margins while elevating specification barriers for imported chemistries.
Growth Catalysts
- Automotive OEM expansion:Japanese and Korean automakers are extending phosphate coating warranties across Southeast Asian assembly plants, mandating higher-performance pre-treatment specifications that displace commodity formulations.
- MEE regulatory pressure:China's GB standard enforcement on hexavalent chromium and nickel discharge redirects investment toward trivalent passivation chemistries, creating specification-driven demand for compliant suppliers.
- Electronics miniaturization:Fluoropolymer surface modifiers are penetrating high-density connector finishing in Taiwan and South Korea semiconductor packaging facilities.
Market Restraints
- Phosphate raw material concentration:Captive phosphate rock supply in China's Guizhou and Yunnan provinces limits formulation cost transparency for non-integrated compounders.
- Zirconium precursor import dependence:Regional formulators rely on Australian and South African zirconium feedstock, exposing margin volatility to mineral concentrate shipping disruptions.
- Trivalent chromium technical ceiling:Aerospace fastener specifications in Japan and Australia still require hexavalent passivation for salt-spray performance, blocking full chemistry transition.
Strategic Opportunities
- Vietnam manufacturing migration:Electronics assembly relocation from China to Bac Ninh and Hai Phong industrial zones creates greenfield demand for electronics-grade conversion coatings.
- India PLI scheme alignment:Automotive component incentives under India's production-linked incentive framework attract phosphate line investments from tier-one stamping suppliers.
- Powder coating resin substitution:Tightening VOC regulations in Australia's TGA jurisdiction and South Korea's MFDS enforcement accelerate solvent-to-powder transitions in appliance finishing.
Industry Challenges
- Cross-border formulation registration:Divergent ASEAN national chemical inventories versus China's IECSC create multi-jurisdictional compliance timelines that delay product launches.
- Process engineer scarcity:Bath chemistry optimization for zirconium-based pre-treatments requires specialized expertise concentrated in Japanese and German technical service networks.
- Legacy hexavalent chromium line conversion:Aerospace suppliers face capital-intensive tank replacement and wastewater system reconfiguration to meet evolving JIS and GB certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Surface Treatment Chemicals Market |
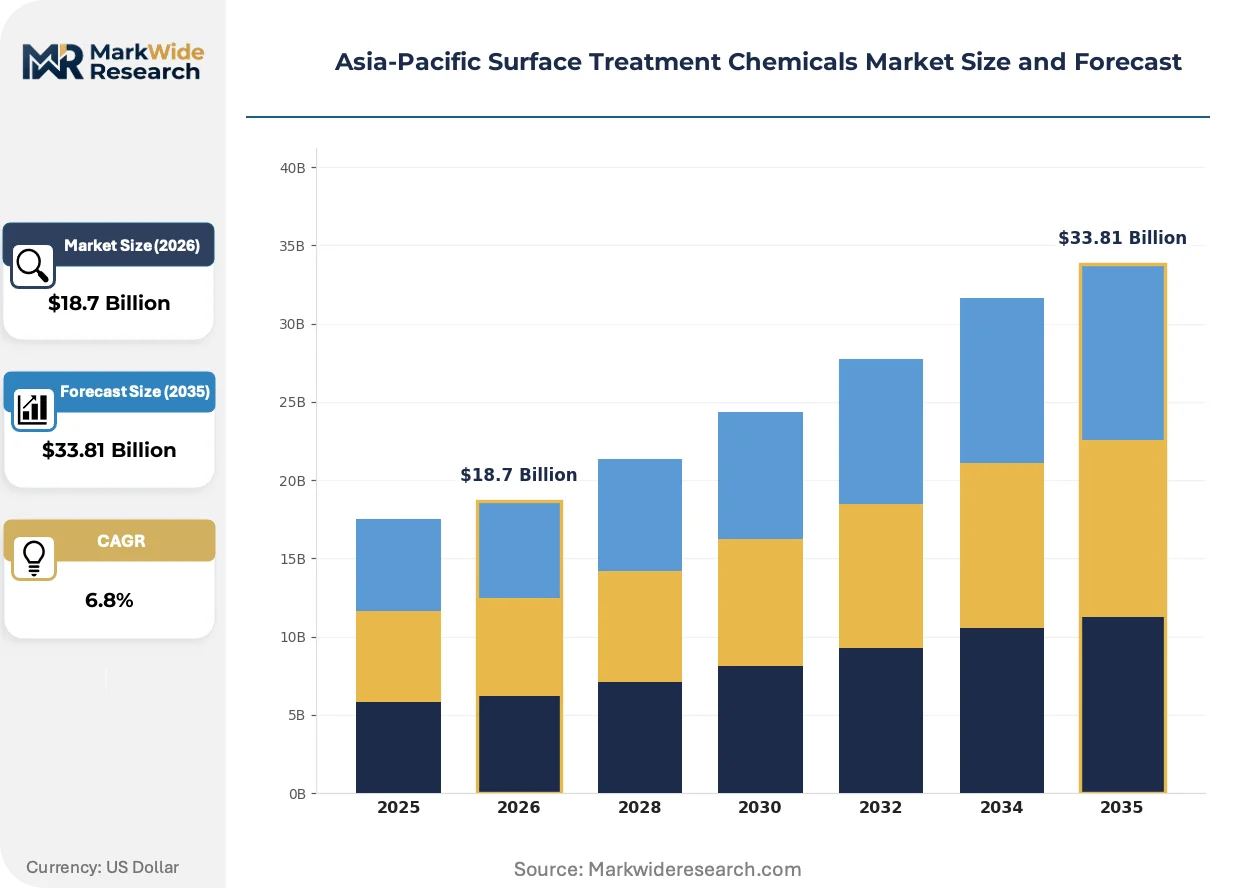
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Coatings, Cleaners, Pre-treatments Application: Aerospace, Automotive, Electronics, Industrial Equipment Technology: Electroplating, Anodizing, Powder Coating, Chemical Conversion End User: Manufacturers, Distributors, OEMs, Service Providers |
| Companies Covered | Nippon Paint Holdings Co Ltd, Nihon Parkerizing Co Ltd, Chemetall GmbH, The Sherwin-Williams Company, JCU CORPORATION, Henkel AG & Co KGaA, NOF CORPORATION, OC Oerlikon, PPG Industries Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Surface Treatment Chemicals Market Strategic Shifts
Formulation chemistry is pivoting toward low-temperature, low-sludge processes that reduce energy intensity and waste disposal burden while maintaining coating weight specifications. This shift is compressing the performance gap between established phosphate systems and emerging zirconium-silane hybrids.
Zirconium-based pre-treatment chemistry is overtaking traditional iron and zinc phosphate conversion coatings in automotive body-in-white applications. Korean and Japanese OEM stamping operations are specifying zirconium-silane systems for room-temperature operation and reduced sludge generation. This transition is overtaking incumbent phosphate compounders in specification-driven procurement decisions across the Yangtze River Delta manufacturing cluster.
METI's JIS-compliant green plating initiative is elevating certification barriers for imported surface treatment formulations lacking domestic verification infrastructure. The framework mandates third-party validation of hexavalent chromium alternatives, extending qualification timelines for non-Japanese suppliers. Electronics connector finishers in Osaka and Nagoya industrial corridors face compressed supplier lists as METI alignment becomes a de facto procurement prerequisite.
Specification-driven contracting is consolidating procurement authority at OEM central engineering functions, displacing distributed plant-level chemical purchasing. Tier-one automotive suppliers in Thailand and Indonesia now route formulation selection through parent-company technical committees in Tokyo or Seoul. This concentration is most visible in corrosion warranty negotiations, where coating weight guarantees now originate from headquarters metallurgy labs rather than regional quality departments.
Asia-Pacific Surface Treatment Chemicals Market Segmentation
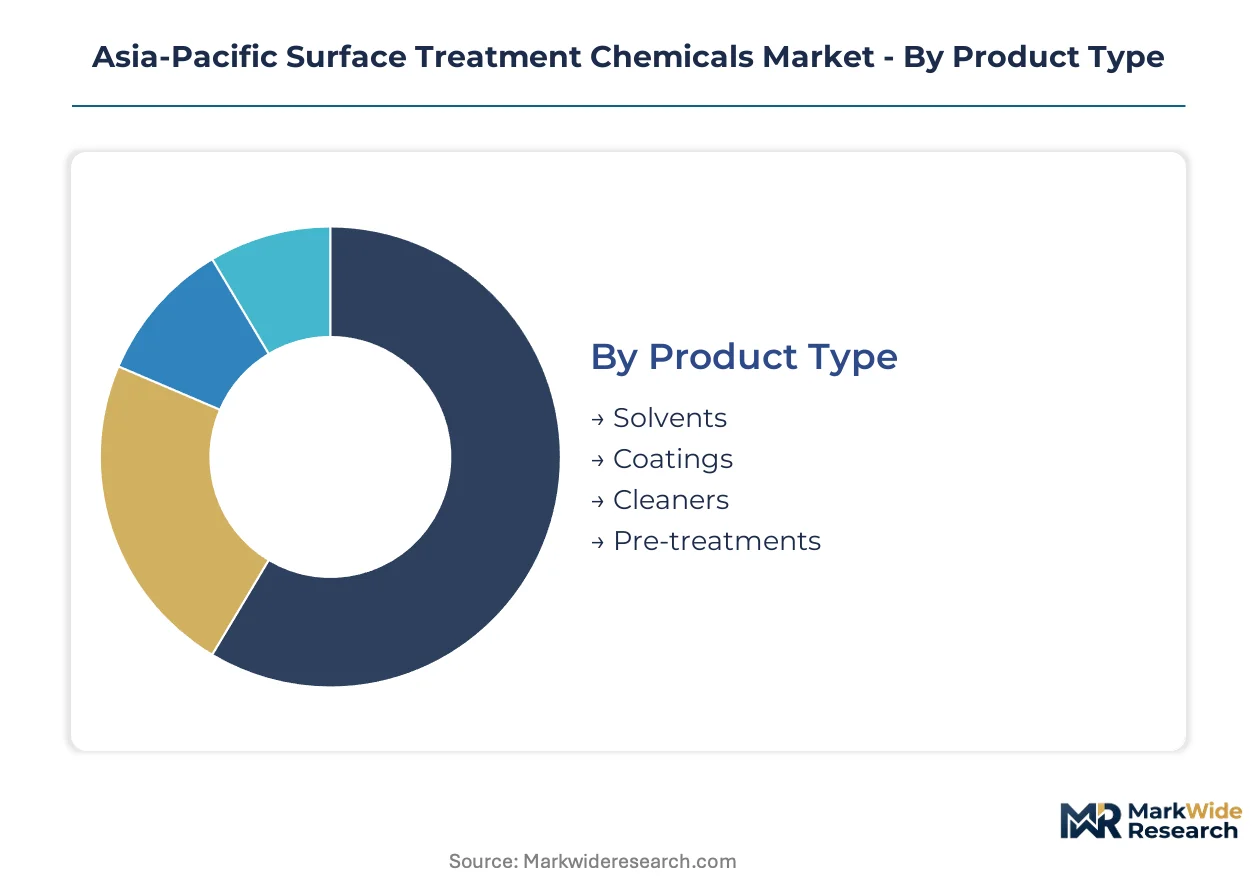
Surface treatment chemicals fragment across multiple technical dimensions that determine specification requirements, regulatory compliance burdens, and procurement authority. Understanding these divisions clarifies where formulation investments concentrate and which customer segments drive premium pricing.
Product Type:
Replacement cycles for legacy solvent-based systems are shortening as MEE-enforced VOC limits and powder coating substitutions accelerate reformulation roadmaps across the region.
- Pre-treatments:Phosphate and zirconium-silane conversion coatings dominate automotive body-in-white lines, with Yangtze River Delta stamping operations specifying room-temperature zirconium systems to reduce energy intensity and sludge disposal costs.
- Coatings:Functional topcoats including fluoropolymer modifiers for electronics connectors command specification-driven premiums in Taiwan and South Korea semiconductor packaging corridors where METI-aligned green plating certifications filter supplier lists.
- Cleaners:Alkaline and acid-based substrate preparation formulations serve plating line feedstocks across Japanese automotive supply chains.
- Solvents:Declining share in appliance finishing as Australia's TGA jurisdiction and South Korea's MFDS enforcement tighten VOC emission thresholds.
Pre-treatments sit at the top of the volume ranking, with coatings climbing the fastest.
Application:
Cost tier differentiation separates aerospace-certified formulations from commodity automotive pre-treatments, with certification overhead creating margin stratification across application segments.
- Automotive:Phosphate conversion coating warranties extended by Japanese and Korean OEMs across Southeast Asian assembly plants mandate higher-performance specifications that displace commodity formulations in Thailand and Indonesia stamping operations.
- Electronics:High-density connector finishing in Taiwan and South Korea drives fluoropolymer surface modifier demand for miniaturized semiconductor packaging applications.
- Aerospace:Fastener specifications in Japan and Australia still require hexavalent chromium passivation for salt-spray performance, blocking full chemistry transition despite MEE and METI pressure.
- Industrial Equipment:Powder coating resin substitution accelerates as solvent-based system operating costs rise under tightening regional VOC frameworks.
Automotive commands the largest revenue base, with electronics expanding most quickly.
Technology:
Application maturity determines where process engineer scarcity concentrates, with emerging zirconium-silane hybrids requiring technical service networks that lag behind established phosphate system support infrastructure.
- Chemical Conversion:Trivalent chromium and trivalent passivation chemistries capture redirected investment from hexavalent chromium lines as China's GB standards and Japan's JIS frameworks elevate compliance barriers.
- Powder Coating:Solvent-to-powder transitions accelerate in appliance and industrial equipment sectors where Australia's TGA and South Korea's MFDS enforcement tighten application constraints.
- Electroplating:Retains entrenched positions in electronics connector finishing despite regulatory pressure on heavy metal discharge.
- Anodizing:Aluminum substrate treatment for aerospace and industrial components operates within established technical service networks.
Chemical conversion leads by installed base, with powder coating gaining share fastest.
End User:
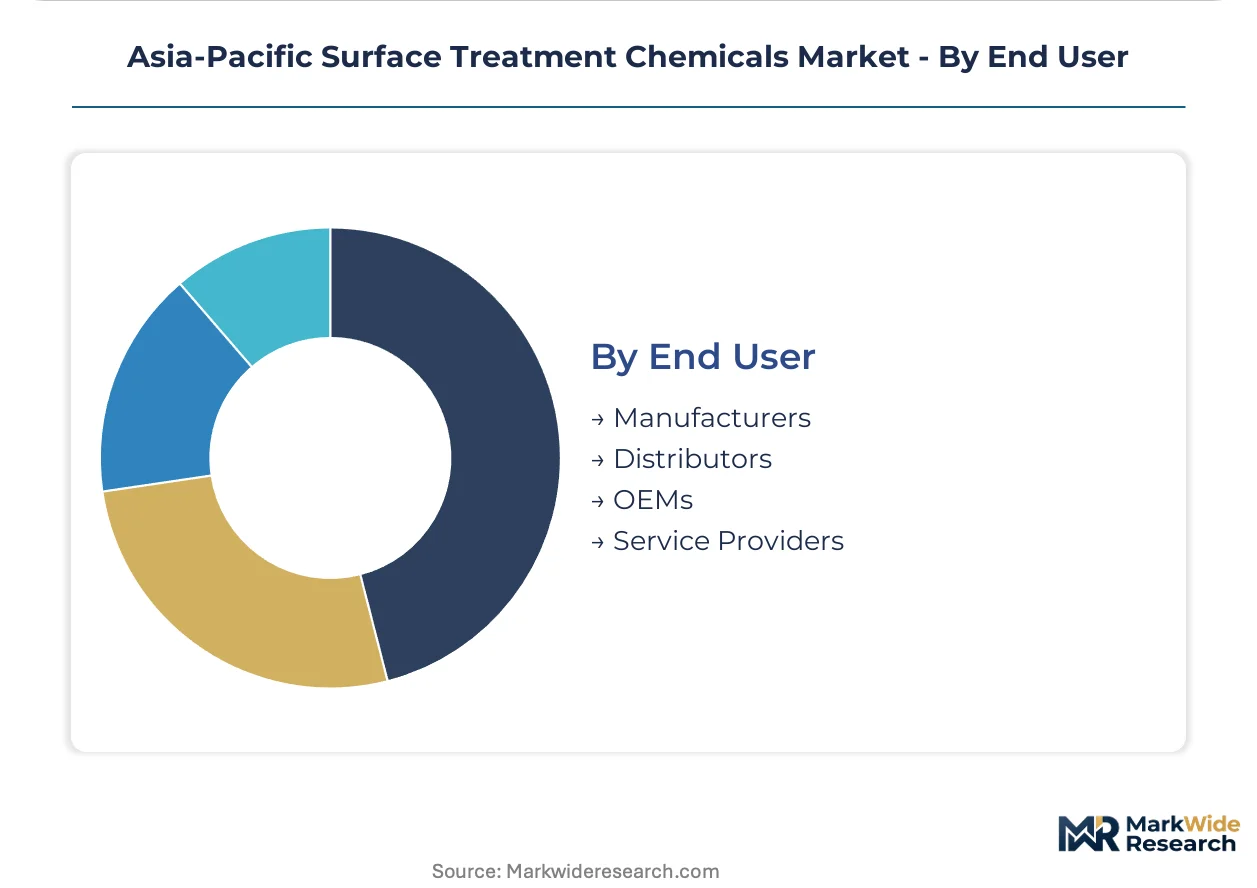
Customer type determines procurement authority concentration, with OEM central engineering functions displacing distributed plant-level purchasing across tier-one supplier networks.
- OEMs:Centralized specification authority in Tokyo and Seoul headquarters now controls formulation selection for Thailand and Indonesia tier-one suppliers, compressing regional quality department autonomy in corrosion warranty negotiations.
- Manufacturers:Yangtze River Delta and Bac Ninh industrial zone facilities drive volume demand for phosphate and electronics-grade conversion coatings.
- Distributors:Face margin compression as specification-driven contracting consolidates procurement channels.
- Service Providers:Plating job shops navigate multi-jurisdictional compliance timelines across divergent ASEAN national chemical inventories versus China's IECSC.
OEMs dominate specification authority, with manufacturers representing the steepest volume trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with zirconium-silane optimization expertise cluster in Japanese and German technical service networks, creating capability scarcity that shapes regional competitive dynamics across the Asia-Pacific Surface Treatment Chemicals Market.
China
Automotive OEMs in the Yangtze River Delta are expanding phosphate conversion coating lines to meet extended corrosion warranties. MEE enforcement of GB standards on hexavalent chromium discharge forces simultaneous plating bath reformulation and capital redeployment. Tier-one stamping suppliers in Shanghai and Suzhou anchor regional consumption of pre-treatment formulations.
Japan
METI's JIS-compliant green plating initiative elevates certification barriers for imported surface treatment chemistries lacking domestic verification. Electronics connector finishers in Osaka and Nagoya industrial corridors face compressed supplier lists as third-party validation becomes a procurement prerequisite. Automotive headquarters in Tokyo now control specification authority for Southeast Asian assembly plant procurement.
South Korea
MFDS enforcement tightens VOC emission thresholds in appliance finishing, accelerating solvent-to-powder coating transitions. Semiconductor packaging facilities in Gyeonggi Province drive fluoropolymer surface modifier demand for high-density connector applications. Busan-Ulsan industrial complexes host expanding automotive pre-treatment line investments from Korean OEMs.
Vietnam
Electronics assembly relocation from China to Bac Ninh and Hai Phong industrial zones generates greenfield demand for electronics-grade conversion coatings. Manufacturing migration attracts phosphate line investments from tier-one automotive suppliers seeking tariff-advantaged export platforms. Northern industrial provinces concentrate new surface treatment chemical consumption.
Australia
TGA jurisdiction propagates REACH-aligned substance restrictions through bilateral trade frameworks affecting chemical formulation imports. Aerospace fastener specifications in Melbourne and Sydney defense supply chains still require hexavalent chromium passivation, blocking full chemistry transition despite regulatory pressure. Industrial equipment powder coating substitution accelerates under tightening VOC frameworks.
Asia-Pacific Surface Treatment Chemicals Market Competitive Environment
Top-tier vendors anchor specification-driven procurement with OEM central engineering functions, while mid-tier compounders compete on reformulation speed for regulatory compliance. The vendor base stratifies across integrated phosphate producers, specialty fluoropolymer modifiers, and coatings-anchored chemical portfolios. Three archetypes dominate: backward-integrated phosphate compounders, electronics-focused surface modifier specialists, and coatings conglomerates leveraging R&D intensity for OEM specification capture. M&A activity concentrates on captive mineral supply access, while technology licensing partnerships address process engineer scarcity in emerging zirconium-silane applications.
Within the coatings-anchored tier, Nippon Paint Holdings Co Ltd and The Sherwin-Williams Company represent integrated formulation portfolios that span pre-treatments through functional topcoats. Henkel AG & Co KGaA exemplifies the backward-integrated archetype through captive phosphate chemistry and zirconium-based pre-treatment supply. NOF CORPORATION occupies a position among specialty modifiers focused on fluoropolymer surface chemistry for electronics applications. These three company structures illustrate how geographic origin and corporate form signal competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Nippon Paint Holdings Co Ltd |
| Nihon Parkerizing Co Ltd |
| Chemetall GmbH |
| The Sherwin-Williams Company |
| JCU CORPORATION |
| Henkel AG & Co KGaA |
| NOF CORPORATION |
| OC Oerlikon |
| PPG Industries Inc |
| Others |
Value Chain & Pricing Dynamics
Backward integration into phosphate rock supply in China's Guizhou and Yunnan provinces anchors both cost position and specification authority for compounders serving Yangtze River Delta automotive stamping operations. This captive mineral access separates integrated formulators from import-dependent competitors exposed to zirconium concentrate shipping disruptions.
Pricing Analysis
Bundled technical service contracts dominate specification-driven procurement, while unbundled commodity formulations compete on spot pricing for non-warranty applications. Three-tier pricing structure across aerospace-certified, automotive-warranty, and industrial-grade tiers reflects certification overhead and performance guarantees. Price differentiation hinges on METI JIS compliance and corrosion warranty backing. Cost compression in commodity phosphate pre-treatments is intensifying because Yangtze River Delta tier-one suppliers are consolidating procurement through headquarters metallurgy labs. Distributors and service providers face the steepest price sensitivity, while OEM central engineering functions prioritize specification compliance over unit cost.
Supply Chain Analysis
China's GB standards on heavy metal discharge and Japan's METI green plating mandates are reshaping sourcing toward domestically certified formulation partners. Geographic supply concentration centers on China for phosphate chemistry, Australia and South Africa for zirconium feedstock, and Japan for fluoropolymer surface modifiers. Raw material dependencies include phosphate rock concentrates, zirconium oxychloride precursors, and chromium compounds for trivalent passivation systems. Single-source vulnerability runs through South African zirconium concentrate shipping lanes. Distribution runs through technical service networks anchored in Japanese and German engineering hubs rather than traditional chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as automotive OEMs extend corrosion warranties and MEE enforcement elevates specification barriers above commodity competition.
For Market Incumbents: Lock in specification authority by deepening captive phosphate supply positions in Guizhou and accelerating METI JIS certification investments for electronics-grade formulations. Zirconium-silane technical service capability scarcity threatens margin capture for compounders lacking Japanese or German engineering networks. Capacity addition in Vietnam's Bac Ninh corridor captures electronics assembly migration before greenfield competitors establish beachheads. For New Entrants and Emerging Players: Regional distributors with plating job shop relationships offer the fastest path to specification trials without incumbent technical service overhead. White-space targets include India's PLI-aligned automotive component suppliers seeking phosphate line partnerships and Australian powder coating resin substitution demand under TGA VOC enforcement. Vietnam's Hai Phong industrial zone presents the most penetrable geography given simultaneous electronics and automotive investment inflows. A technical licensing partnership with established zirconium-silane process engineers bypasses capability buildout timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap phosphate compounders because MEE regulatory compliance costs are forcing fragmentation among non-integrated regional formulators unable to fund simultaneous bath reformulation and certification investments. Long-term viability favors targets with captive mineral positions and existing METI or GB standard alignment. The signal to watch is qualification timeline compression for trivalent chromium alternatives in Japanese aerospace fastener specifications, which would unlock full chemistry transition and stranded asset risk for hexavalent-dependent plating operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive Guizhou supply secures cost transparency against import-dependent competitors serving Yangtze Delta OEMs. |
| METI JIS Certification Investment | Third-party validation opens procurement channels at Osaka and Nagoya electronics connector finishers. |
| Vietnam Manufacturing Footprint | Bac Ninh and Hai Phong presence captures electronics assembly migration from tariff-exposed Chinese operations. |
| Zirconium-Silane Technical Licensing | Partnerships with Japanese or German process engineers address capability scarcity in room-temperature pre-treatment deployment. |
| Trivalent Chromium Reformulation | GB and METI-aligned chemistry redirection captures specification-driven demand as hexavalent lines face MEE enforcement. |
Study Parameters
Direct dialogue with plant managers at Yangtze River Delta stamping operations, procurement leads at Japanese automotive OEMs, distribution channel partners, and technical R&D directors at phosphate compounders grounded qualitative assessments. Secondary validation drew from China customs trade data, Japan METI green plating initiative documentation, SEC 10-K filings of coatings-anchored chemical portfolios, and ASEAN national chemical inventory registrations. Bottom-up demand modeling across pre-treatment, coating, cleaner, and solvent product types triangulated against top-down macroeconomic drivers.
Bottom-up volume builds aggregated segment outputs across automotive, electronics, aerospace, and industrial equipment applications, with technology splits for chemical conversion, powder coating, electroplating, and anodizing processes. Value projections incorporate grade-tier pricing stratification and regional production hub cost differentials. CAGRs derived from installed base replacement cycles, regulatory-driven reformulation timelines, and OEM warranty extension patterns. Forecast inputs include phosphate line capacity expansion announcements, semiconductor packaging facility buildouts in Gyeonggi Province, and PLI scheme automotive component investments in India.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN regulatory harmonization progress, zirconium concentrate shipping disruption frequency, and aerospace fastener specification relaxation permitting full trivalent chromium adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Periodic Acid Market
Chemicals
Vinyl Acetate Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Quaternium-15 Market
Chemicals
Diethyl Sulfate Market
Chemicals
Canada Methanol Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Global Construction Chemical Market
Chemicals
1, 4 Butanediol Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Sodium Cyanide Market
Chemicals
North America Methanol Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Betaine Market