
 Tuberose Extract Market | 2026-2036
Tuberose Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberose Extract Market Outlook
Synthetic tuberose aroma chemicals is broadening the addressable market for natural extract suppliers as clean-label preferences pull formulators back toward botanical sources. Givaudan SA leverages captive jasmine and tuberose farming in Grasse to secure raw material traceability. Robertet Group anchors its competitive stance through backward integration into Moroccan tuberose fields. Firmenich SA differentiates via biotechnology-derived precursors that complement traditional solvent extraction.
Tuberose extract is a concentrated aromatic material obtained from Polianthes tuberosa flowers through solvent extraction or enfleurage, yielding absolute or concrete forms with high levels of methyl benzoate, methyl anthranilate, and benzyl salicylate that impart a creamy floral odor profile prized in fine fragrance compounding. Essential oil and absolute grades command the deepest margin pools due to their irreplaceable complexity in luxury perfume formulations, while concrete serves as an intermediate feedstock for further refinement. Cosmetics and aromatherapy end-use segments absorb the largest volume share, though food and beverage applications are gaining traction as natural flavoring designations tighten regulatory scrutiny.
REACH registration requirements in Europe, FDA food additive regulations in the United States, and IFRA standards on fragrance allergen labeling collectively elevate compliance costs and favor suppliers with certified analytical laboratories. India's BIS quality marks and FSSAI flavoring substance approvals add further certification layers for export-oriented Indian processors. Stakeholders must monitor solvent residue limits and organic certification premiums as these parameters increasingly determine contract eligibility with multinational fragrance houses.
Market Dynamics
REACH compliance deadlines and FDA guidance revisions are compressing supplier margins while concentrating procurement among certified processors with captive analytical laboratories.
Growth Catalysts
- Clean-label fragrance reformulation:Synthetic tuberose aroma chemicals are pulling formulators back toward botanical sources as consumer transparency demands intensify across European and North American perfumery.
- India's FSSAI export pathway:Flavoring substance approvals for tuberose extract in food applications are unlocking new volume channels for Indian processors serving multinational flavor houses.
- Solvent extraction yield improvements:Advanced hexane recovery systems are reducing input waste and improving concrete-to-absolute conversion ratios in Egyptian and Indian processing facilities.
Market Restraints
- Input cost volatility:Polianthes tuberosa flower prices fluctuate with monsoon patterns in India's Karnataka and Tamil Nadu cultivation belts, squeezing processor margins during poor harvest cycles.
- Supply concentration risk:Over 70% of global tuberose concrete originates from solvent extraction clusters in Egypt's Nile Delta and India's Uttar Pradesh, creating single-point vulnerability.
- Substitution pressure:Biotechnology-derived tuberose precursors from fermentation platforms are capturing share in mid-tier fragrance formulations where odor fidelity requirements permit.
Strategic Opportunities
- Organic certification premium capture:EU organic farming standards and USDA NOP accreditation are enabling 15-25% price premiums for certified tuberose absolute in luxury perfumery channels.
- Aromatherapy diffusion expansion:Wellness retail chains in Germany and France are expanding botanical extract SKUs, creating direct-to-consumer volume for smaller Indian and Egyptian processors.
- Biotechnology convergence:Cell culture platforms combined with traditional enfleurage are enabling year-round raw material availability independent of seasonal flowering cycles.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry proficiency for methyl benzoate and benzyl salicylate quantification is concentrated among aging specialists in Grasse and Mumbai.
- Multi-jurisdiction certification timelines:Simultaneous REACH registration, IFRA compliance, and organic accreditation processes extend product launch cycles by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberose Extract Market |
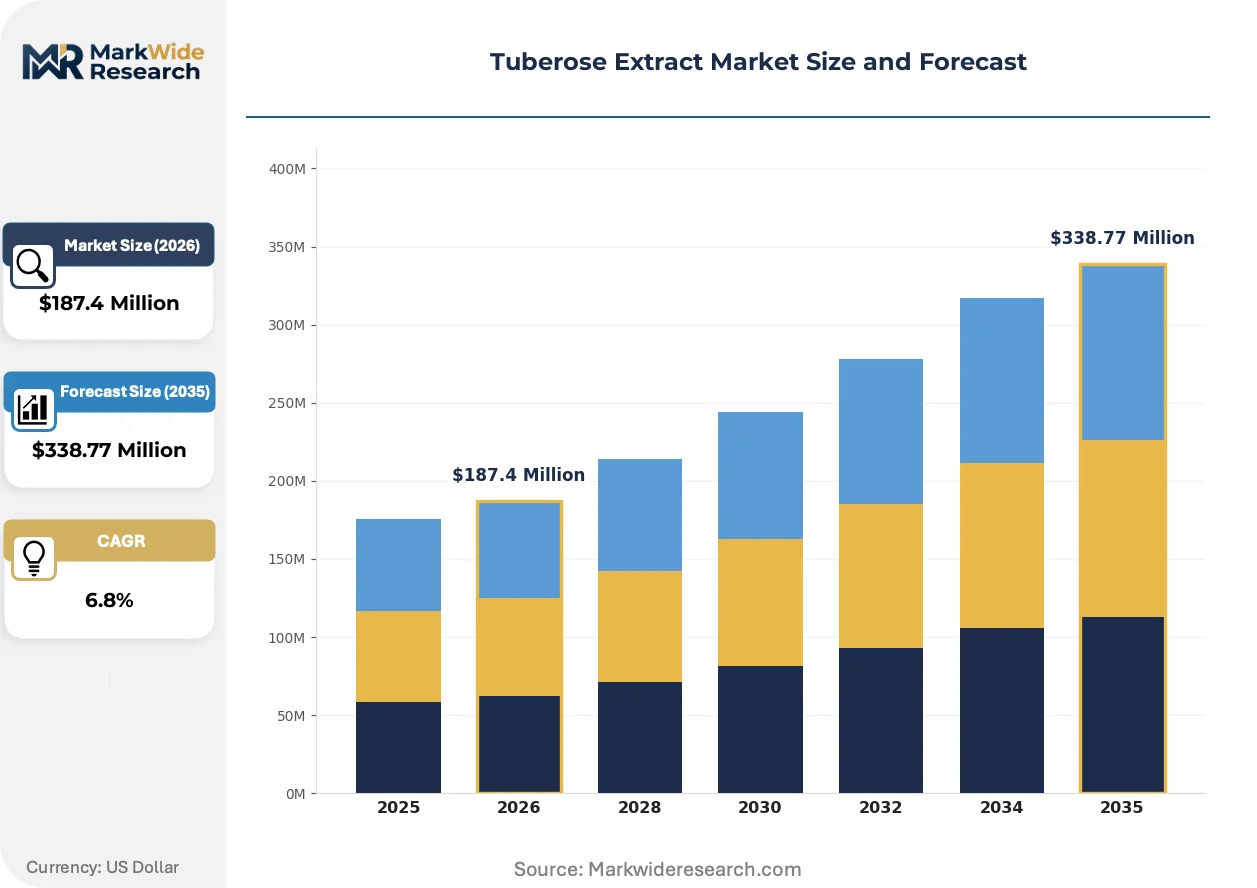
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Absolute, Concrete, Oil Blend End User: Cosmetics, Aromatherapy, Food & Beverage, Pharmaceuticals Form: Liquid, Solid, Powder, Concentrate Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | International Flavors & Fragrances Inc. (IFF), Synthite Industries Ltd., Firmenich SA, Aromaaz International, Albert Vieille SAS, Givaudan SA, Mane SA, Berje Inc., Robertet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberose Extract Market Strategic Shifts
Carbon dioxide extraction methods and biotechnology-derived precursors are fragmenting the traditional solvent-extraction value chain while regulatory disclosure requirements reshape competitive positioning.
Supercritical CO2 extraction is overtaking hexane-based solvent methods in premium fragrance applications. French and Italian perfumery houses are adopting CO2-derived tuberose extracts for cleaner odor profiles and zero solvent residue. This technology is compressing the addressable market for conventional concrete processors while expanding absolute-grade supply.
REACH Article 33 disclosure obligations and SCIP database requirements are mandating full supply chain transparency for fragrance allergens. European formulators must now document tuberose extract origin down to cultivation batch. Fine fragrance houses with captive farming operations are capturing compliance advantages over merchant market suppliers.
Direct farm-to-compound procurement is displacing traditional merchant intermediaries in high-volume contracts. Multinational fragrance houses in France and the United States are signing multi-year offtake agreements with Egyptian and Indian cultivation cooperatives. This pattern is most visible in absolute-grade supply chains where traceability documentation supports clean-label marketing claims.
Tuberose Extract Market Segmentation
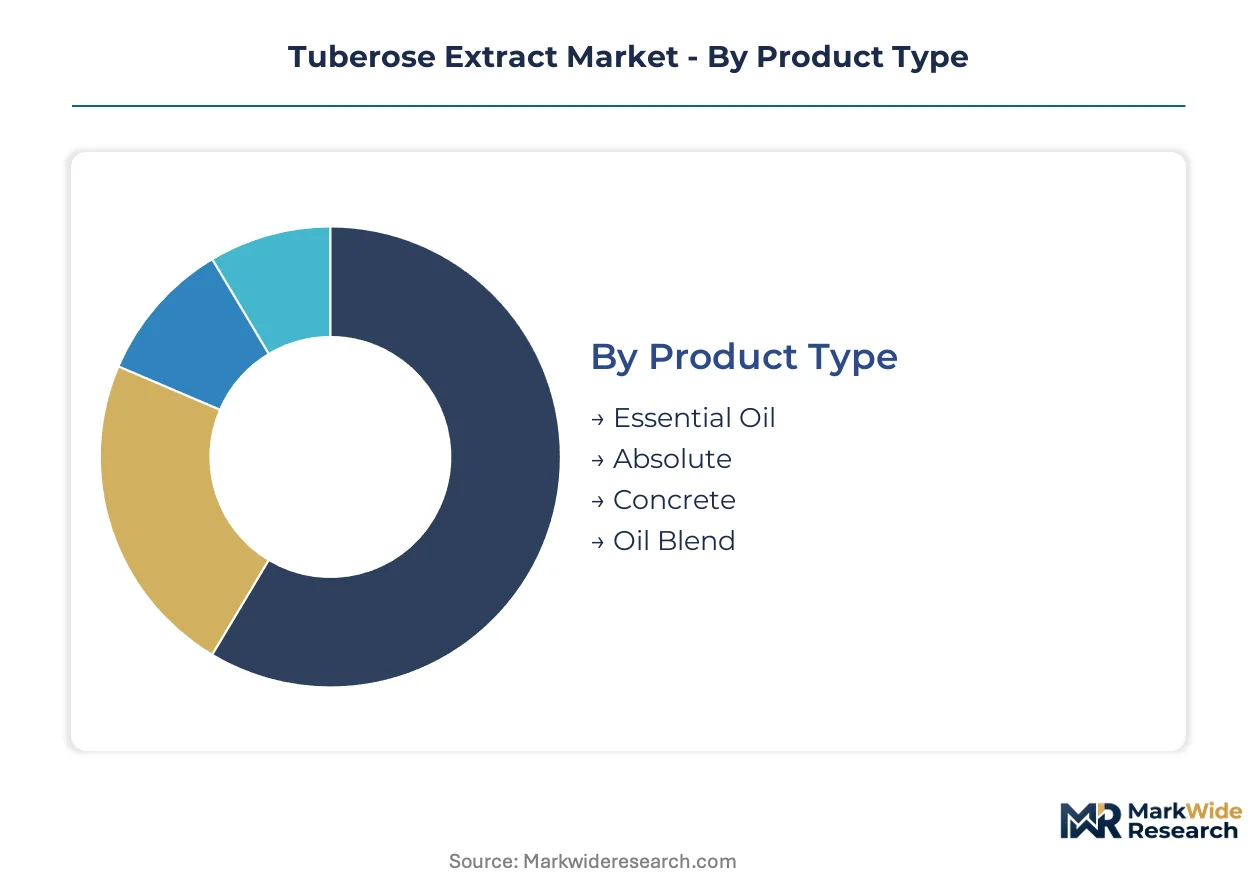
Tuberose extract segmentation reflects the tension between artisanal extraction methods and industrial scale requirements. Product grade and end-use specifications determine pricing power, regulatory pathway, and supply chain configuration across fragrance, wellness, and food applications.
Product Type:
Extraction technology and refinement depth create four distinct commercial tiers with divergent margin structures and customer bases.
- Absolute:The highest-refinement grade produced through alcohol washing of concrete, yielding methyl benzoate concentrations above 15% and zero solvent residue. French luxury perfumers in Grasse and Paris absorb the majority of absolute volume for high-concentration extrait formulations. REACH Article 33 disclosure requirements favor absolute suppliers with batch-level traceability documentation.
- Essential Oil:Steam-distilled or solvent-extracted oil carrying the full volatile complexity of Polianthes tuberosa flowers, including benzyl salicylate and methyl anthranilate signatures. Aromatherapy formulators in Germany and wellness brands in the United States drive essential oil procurement for diffusion and topical applications. IFRA allergen labeling standards elevate analytical certification costs for essential oil exporters.
- Concrete:The waxy intermediate produced through hexane extraction of fresh flowers, containing waxes and lipids alongside aromatic compounds. Egyptian and Indian processors dominate concrete production as feedstock for absolute refinement or lower-grade fragrance compounding.
- Oil Blend:Standardized dilutions of absolute or essential oil in carrier bases, targeting mid-tier cosmetics and massage oil manufacturers seeking cost-controlled floral notes.
Absolute leads on scale; essential oil leads on momentum.
End User:
Application-specific regulatory thresholds and odor fidelity requirements partition demand across four end-use verticals with distinct procurement patterns.
- Cosmetics:Skin care and fragrance manufacturers in France, the United States, and South Korea formulate tuberose absolute into premium perfumes and scented body products. EU Cosmetics Regulation (EC) No 1223/2009 mandates safety assessments for fragrance allergens, concentrating procurement among REACH-registered suppliers.
- Aromatherapy:Wellness retail chains and spa operators in Germany, France, and the United Kingdom source essential oil grades for diffusion and therapeutic applications. Organic certification premiums of 15-25% apply in this channel.
- Food & Beverage:Natural flavoring designations under FDA guidance and FSSAI approvals in India are expanding tuberose extract use in premium confectionery and beverages. Purity thresholds for food-grade methyl benzoate content limit supplier eligibility.
- Pharmaceuticals:Traditional medicine applications in India and emerging research into sedative compounds drive small-volume pharmaceutical procurement with stringent analytical documentation requirements.
Cosmetics commands the deepest margin pools; food and beverage applications are climbing the fastest.
Form:
Physical state determines handling economics, stability profiles, and compatibility with downstream manufacturing processes.
- Liquid:The dominant commercial form encompassing essential oils, absolutes, and oil blends. Liquid extracts integrate directly into fragrance compounding and cosmetic manufacturing workflows.
- Solid:Concrete and wax-based preparations requiring thermal processing before incorporation. Solid forms offer extended shelf stability for processors with in-house refinement capacity.
- Powder:Spray-dried or encapsulated extracts targeting food and beverage applications where dry blending is required. Powder production concentrates among Indian processors with FSSAI-compliant facilities.
- Concentrate:High-potency preparations for industrial flavor and fragrance houses seeking precise dosing control in large-batch compounding.
Liquid maintains volume leadership; powder formats are gaining share fastest in food applications.
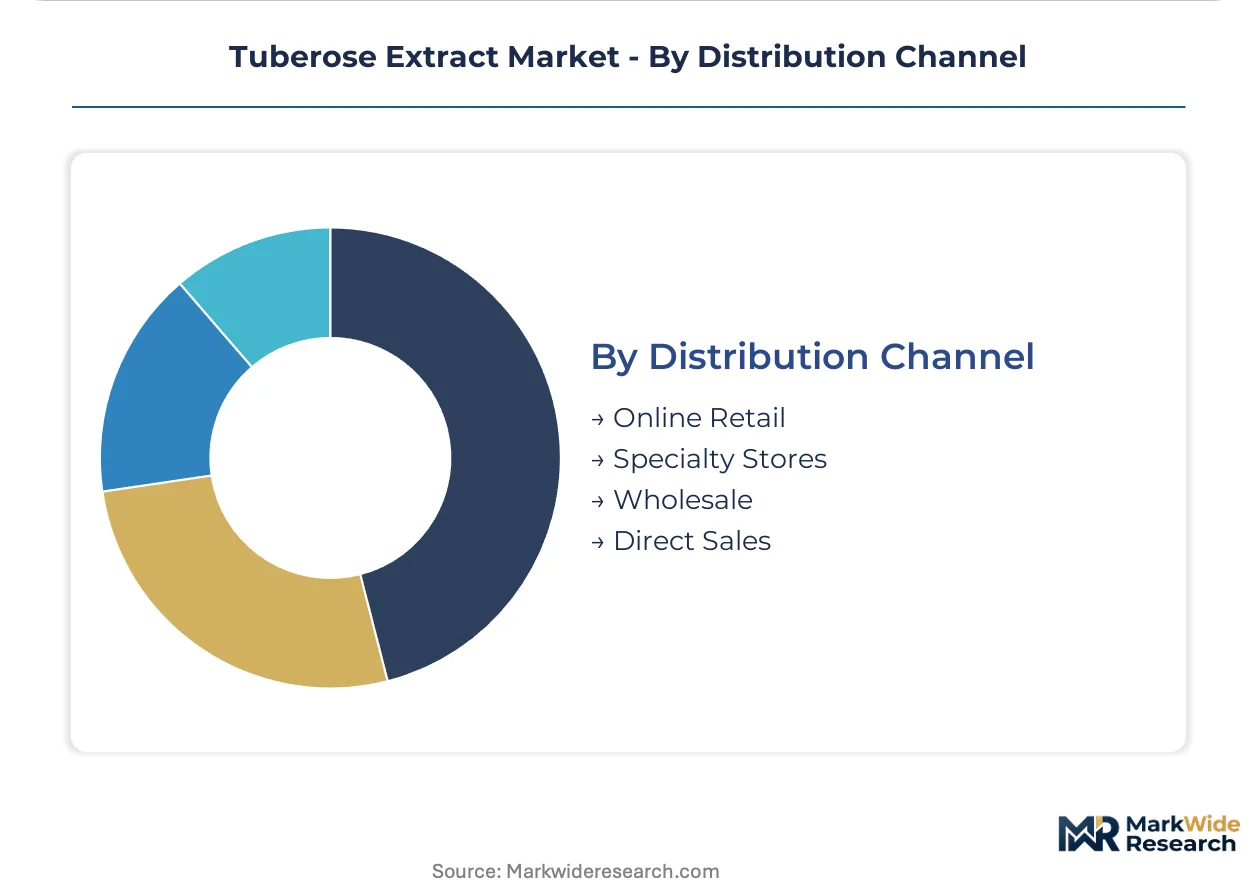
Distribution Channel:
Channel selection reflects order scale, certification requirements, and the need for technical support in extraction-grade procurement.
- Direct Sales:Multi-year offtake agreements between fragrance houses and Egyptian or Indian cultivation cooperatives. Direct procurement supports clean-label marketing claims through documented farm-to-compound traceability.
- Wholesale:Merchant intermediaries supplying mid-tier cosmetics manufacturers and regional flavor houses with standardized grades. Wholesale channels absorb concrete and lower-grade absolute volumes.
- Specialty Stores:Premium aromatherapy retailers and boutique perfumeries serving consumer and small-scale artisanal formulators.
- Online Retail:E-commerce platforms connecting Indian and Egyptian processors directly to wellness brands and independent cosmetics manufacturers, compressing traditional intermediary margins.
Direct sales anchors high-volume absolute procurement; online retail is expanding fastest for essential oil and oil blend segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse anchors the highest-value segment of tuberose extract commerce through its concentration of fine fragrance houses and captive cultivation operations. Procurement patterns diverge sharply between premium absolute grades serving luxury perfumery and commodity concrete volumes flowing through Egyptian and Indian processing clusters.
France
Grasse-based fragrance houses drive absolute-grade procurement for high-concentration extrait formulations. REACH Article 33 disclosure obligations mandate batch-level traceability documentation, favoring suppliers with captive farming operations. The Provence-Alpes-Côte d'Azur cluster concentrates enfleurage expertise and analytical laboratory capacity for methyl benzoate quantification.
United States
Premium cosmetics manufacturers in New York and Los Angeles formulate tuberose absolute into scented body products and fine fragrances. FDA guidance on natural flavoring substances tightens purity thresholds for food-grade applications. Direct farm-to-compound procurement agreements with Egyptian cooperatives are displacing traditional merchant intermediaries in high-volume contracts.
India
Karnataka and Tamil Nadu cultivation belts supply the majority of global concrete feedstock through solvent extraction clusters in Uttar Pradesh. FSSAI flavoring substance approvals unlock export pathways for food-grade methyl benzoate specifications. BIS quality marks and organic certification premiums enable 15-25% price uplifts for certified absolute in European aromatherapy channels.
Egypt
The Nile Delta concentrates hexane-based solvent extraction capacity serving merchant markets and absolute refinement operations. Monsoon-dependent flower pricing in Indian belts creates arbitrage opportunities during poor harvest cycles. Egyptian processors are advancing hexane recovery systems to improve concrete-to-absolute conversion ratios and reduce input waste.
Germany
Wellness retail chains in Munich and Berlin expand botanical extract SKUs for aromatherapy diffusion applications. EU Cosmetics Regulation safety assessments for fragrance allergens concentrate procurement among REACH-registered suppliers. German formulators leverage SCIP database compliance to document tuberose extract origin down to cultivation batch for clean-label marketing claims.
Tuberose Extract Market Competitive Environment
Global majors compete with regional champions across extraction technology and raw material traceability dimensions. The vendor base stratifies between integrated fragrance houses with captive farming, merchant processors with solvent extraction scale, and specialty distributors serving artisanal formulators. Three archetypes dominate: backward-integrated multinationals, export-oriented Indian and Egyptian processors, and biotechnology platforms developing fermentation-derived precursors. Capacity expansion in supercritical CO2 extraction and multi-year offtake agreements with cultivation cooperatives represent the dominant competitive moves.
Within the backward-integrated tier, Givaudan SA and Firmenich SA exemplify archetypes combining captive cultivation with analytical laboratory certification. Robertet Group occupies a position emphasizing upstream control over Moroccan tuberose fields. These entities anchor premium absolute supply chains where REACH compliance and organic accreditation determine contract eligibility with multinational fragrance houses.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. (IFF) |
| Synthite Industries Ltd. |
| Firmenich SA |
| Aromaaz International |
| Albert Vieille SAS |
| Givaudan SA |
| Mane SA |
| Berje Inc. |
| Robertet Group |
| Others |
Value Chain & Pricing Dynamics
Clean-label procurement mandates from French luxury perfumers are forcing Egyptian and Indian processors to upgrade solvent recovery systems and traceability documentation, compressing margins on concrete grades while widening absolute-grade premiums.
Pricing Analysis
Input-cost pass-through from monsoon-dependent Polianthes tuberosa flower prices in Karnataka and Tamil Nadu squeezes processor margins during poor harvest cycles. Pricing stratifies across absolute, essential oil, and concrete tiers, with REACH-registered absolute commanding the deepest premiums. Cost compression in concrete grades is intensifying because Egyptian hexane extraction clusters compete on yield efficiency. Mid-tier cosmetics manufacturers show the highest price sensitivity; Grasse-based fragrance houses demonstrate the least.
Supply Chain Analysis
Single-source vulnerability sits with Egypt's Nile Delta and India's Uttar Pradesh, where over 70% of global concrete originates from hexane extraction clusters. The supply chain draws from fresh flower cultivation belts, hexane solvent inputs, and alcohol washing capacity for absolute refinement. Tariff exposure on Indian exports to the EU creates structural risk for merchant processors. Distribution runs through direct farm-to-compound offtake agreements and wholesale merchant intermediaries serving mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Article 33 disclosure obligations function as a regulatory compounder, concentrating procurement among certified processors with captive analytical laboratories and batch-level traceability.
For Market Incumbents: Hedge against biotechnology-derived precursor substitution by deepening backward integration into Moroccan and Grasse cultivation belts. Invest in supercritical CO2 extraction capacity to capture premium absolute demand from clean-label fragrance reformulators. Secure multi-year offtake agreements with Egyptian cooperatives before direct procurement displaces merchant intermediaries entirely. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a technology-first wedge into premium absolute supply chains where zero solvent residue commands 15-25% organic certification premiums. Target German wellness retail chains and aromatherapy diffusion channels as the most penetrable end-use vertical. Pursue FSSAI flavoring substance approvals to unlock food and beverage applications with fewer incumbent lock-ins. For Investors and Strategic Acquirers: Asymmetric upside sits with Indian processors holding simultaneous BIS quality marks, FSSAI export pathways, and hexane recovery system investments. Long-term viability over a 5-10 year window favors entities combining cultivation control with REACH-registered laboratory capacity. Watch biotechnology platform partnerships with traditional enfleurage operators as the inflection signal for year-round raw material availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Givaudan SA's captive farming in Grasse secures raw material traceability for REACH compliance. |
| Supercritical CO2 Capacity Expansion | French perfumery houses adopt CO2-derived extracts for zero solvent residue profiles. |
| Organic Certification Program | USDA NOP and EU organic standards enable 15-25% price premiums in aromatherapy channels. |
| Long-term Supply Agreement | Direct farm-to-compound procurement with Egyptian cooperatives displaces merchant intermediaries. |
| Biotechnology Convergence | Cell culture platforms combined with enfleurage enable year-round production independent of flowering cycles. |
Study Parameters
Multiple input streams — primary interviews with fragrance house procurement directors, solvent extraction plant managers, and aromatherapy brand formulators; secondary validation through customs trade data, IFRA allergen disclosure databases, and REACH registration filings; plus FSSAI flavoring substance approval records — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from cultivation cooperatives and processing facility operators across the analysis window. Segmentation dimensions modeled include product grade tier, end-use vertical, physical form, and distribution channel structure. CAGRs were derived from slope analysis of annualized growth patterns, incorporating flower yield volatility indices and regulatory compliance cost curves as industry-specific forecast inputs.
The model holds under stable monsoon patterns and unchanged REACH disclosure thresholds; deviation in biotechnology platform adoption rates or EU organic farming standard revisions would shift absolute-grade supply projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Germany Protein Market
Ingredients
Europe Pea Starch Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Calendula Oil Market
Ingredients
Citrus Pectin Market
Ingredients
Fluid Lecithin Market
Ingredients
Agar Market
Ingredients
Instant Dry Yeast Market
Ingredients
Cooking Oil Market
Ingredients
Bromelain Ingredient Market
Ingredients
Pea Peptones Market
Ingredients
Africa Fats and Oil Market
Ingredients
North America Corn Starch Market
Ingredients
Pea Flour Market
Ingredients
Textured Soy Protein Market
Ingredients
Mustard Oil Market