
 Fermented Rennet Market | 2026-2036
Fermented Rennet Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Rennet Market Insights
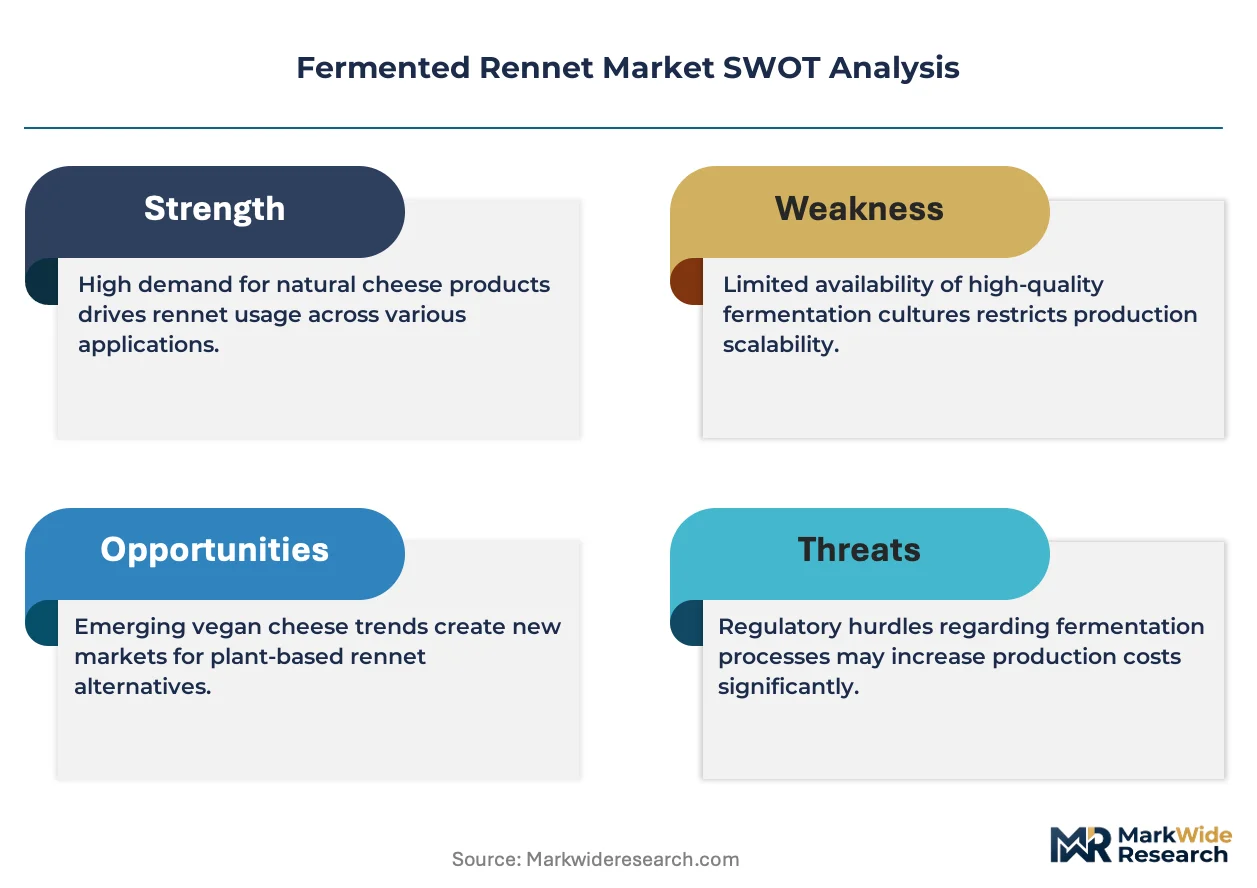
Microbial strain licensing and fermentation optimization services are pivoting how rennet suppliers capture recurring value. Chr. Hansen Holding leverages its culture collection depth to anchor premium positioning in liquid rennet formulations. Koninklijke DSM sustains R&D intensity across fungal-derived enzyme platforms. WalcoRen specializes in regional distribution networks across European cheese-producing clusters.
Fermented rennet comprises coagulating enzymes—principally chymosin and pepsin—produced via submerged fermentation of genetically modified microorganisms or native fungal strains, yielding standardized clotting activity measured in International Milk Clotting Units per gram for consistent cheese curd formation. Liquid rennet dominates commercial cheese manufacturing due to dosing precision and dissolution speed, while tablet rennet occupies the home cook and small-batch artisan segment where shelf stability matters. Microbial source categories lead volume growth as fungal and plant-based alternatives displace animal-derived rennet in kosher, halal, and vegetarian-certified production lines.
FDA GRAS notifications and USDA organic certification requirements shape enzyme labeling and processing aid disclosure standards in the United States. EFSA and EMA frameworks govern novel food enzyme approvals across EU member states, extending evaluation timelines for genetically modified microbial strains. Stakeholders must monitor evolving clean-label thresholds and enzyme origin transparency mandates that increasingly influence procurement decisions by multinational dairy cooperatives.
Market Dynamics
EU animal welfare directives are compressing animal-derived rennet availability, forcing cheese producers toward microbial fermentation alternatives and rewiring supplier-processor relationships across the value chain.
Growth Catalysts
- Regulatory displacement:EFSA novel food enzyme approvals for genetically modified microbial strains are accelerating substitution timelines in European cheese manufacturing corridors.
- Certification premiums:Kosher, halal, and vegetarian labeling requirements from dairy cooperatives in Germany and France are pulling microbial rennet into premium product lines.
- Process intensification:Submerged fermentation optimization is reducing clotting unit variability, enabling precision dosing in high-volume mozzarella and cheddar operations.
Market Restraints
- Input cost volatility:Fungal culture media and sterile fermentation vessel materials face price swings tied to pharmaceutical-grade stainless steel markets.
- Regulatory friction:EMA evaluation timelines for new microbial strains extend commercialization windows by 18-36 months versus animal-derived rennet grandfathered approvals.
- Technical limitation:Microbial chymosin exhibits broader proteolytic activity than calf rennet, producing bitter peptide accumulation in aged hard cheeses.
Strategic Opportunities
- Underpenetrated craft segment:Italian artisan pecorino and gorgonzola producers remain tethered to traditional animal rennet, representing conversion potential.
- Technology convergence:CRISPR-edited fungal strains combined with continuous fermentation bioreactors promise step-change yield improvements.
- Channel innovation:Direct-to-producer enzyme subscription models bypass traditional dairy supply distributors in North American craft dairy clusters.
Industry Challenges
- Skill scarcity:Fermentation scientists with dairy enzyme specialization command premium compensation, constraining mid-tier supplier scale-up.
- Certification timeline compression:Organic certification requirements from USDA and parallel EU organic frameworks demand dual-track documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Rennet Market |
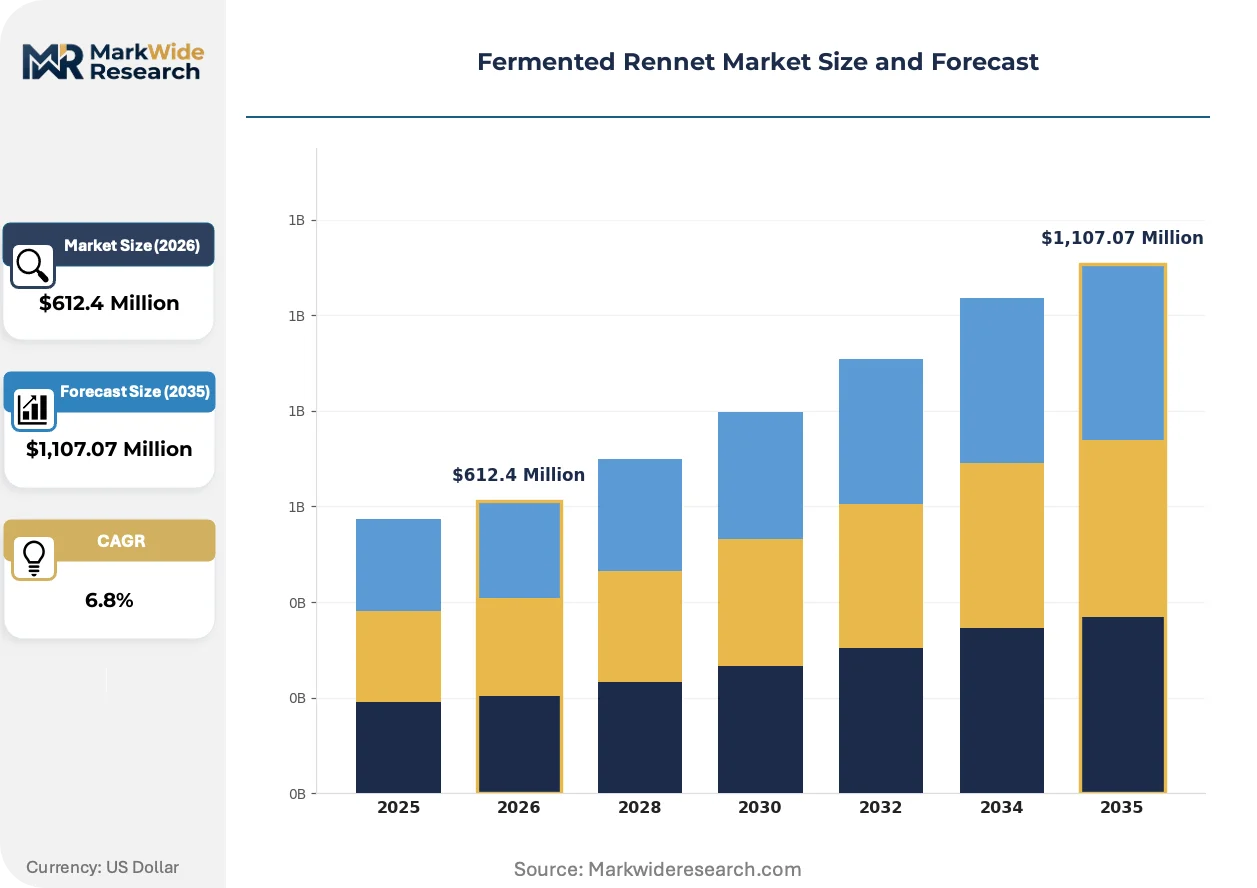
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
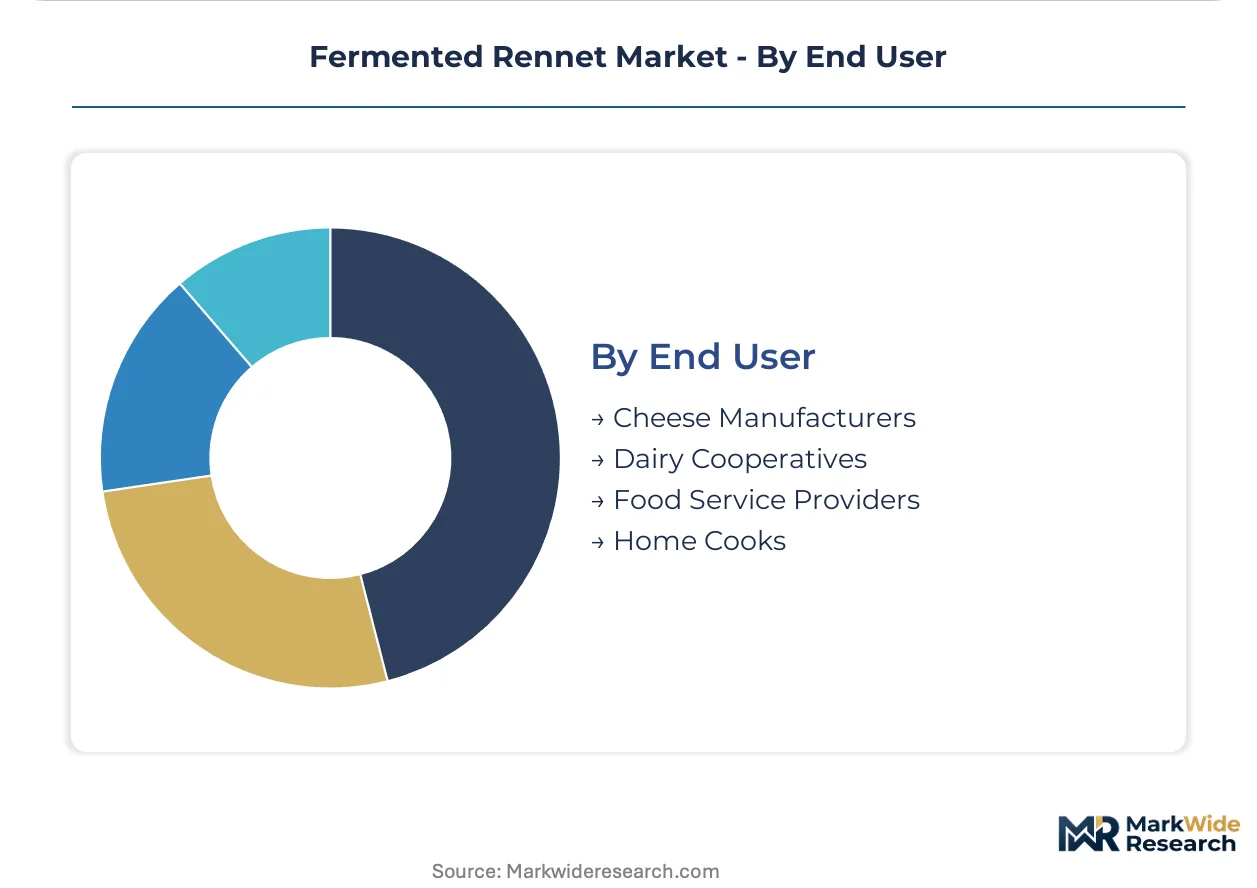
| Segmentation | Product Type: Liquid Rennet, Powdered Rennet, Tablet Rennet, Creamy Rennet Source: Microbial, Fungal, Plant-based, Animal-derived Application: Cheese Production, Dairy Processing, Gelatin Production, Confectionery End User: Cheese Manufacturers, Dairy Cooperatives, Food Service Providers, Home Cooks |
| Companies Covered | Chr. Hansen Holding, Koninklijke DSM, Nelson-Jameson, BIOTEC FERMENTI SRL, Sacco System, Clarion Casein Ltd, WalcoRen, RENCO New Zealand, International Flavors & Fragrances Inc. (IFF), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Rennet Market Trends and Innovations
Precision fermentation infrastructure is migrating from pharmaceutical contract manufacturing into food-grade enzyme production, collapsing historical barriers between industrial biotechnology and dairy processing inputs.
Recombinant chymosin production via Aspergillus niger host strains delivers standardized International Milk Clotting Units with batch-to-batch variance below 5%. Large-scale mozzarella manufacturers in Wisconsin and California are adopting these formulations at accelerated procurement cycles. This standardization is converging with automated cheese vat control systems to compress coagulation timing windows and reduce yield loss.
EFSA's 2023 updated guidance on food enzyme safety assessments requires expanded toxicological data packages for genetically modified production organisms. Small and mid-sized rennet suppliers face compliance cost burdens that favor consolidated culture collection holders. Hard cheese producers in the Netherlands and Denmark are prioritizing suppliers with pre-validated EFSA dossiers to de-risk supply continuity.
Artisan creameries are unbundling from traditional dairy cooperative enzyme procurement, establishing direct relationships with specialty fermentation houses. This disintermediation concentrates in Vermont, Quebec, and the Pacific Northwest where farmstead cheese operations value technical consultation alongside enzyme supply. These buyers now specify strain provenance and fermentation conditions in purchase agreements, shifting supplier accountability upstream.
Fermented Rennet Market Segmentation

Rennet form factors and enzyme origins dictate dosing precision, certification eligibility, and curd formation chemistry across commercial and artisan production tiers. Segment boundaries increasingly blur as microbial fermentation advances enable drop-in replacements for traditional animal-derived extracts.
Product Type:
Liquid formulations dominate precision manufacturing corridors where automated dosing systems require rapid dissolution and standardized clotting unit consistency.
- Liquid Rennet:Aqueous enzyme solutions deliver immediate dispersion in milk vats, enabling programmable coagulation timing. Wisconsin mozzarella plants and California cheddar operations prioritize liquid rennet for high-throughput continuous processing lines where batch-to-batch variance below 5% compresses yield loss.
- Tablet Rennet:Compressed enzyme matrices with extended shelf stability serve home cooks and farmstead creameries lacking refrigerated supply chains. Italian pecorino producers in Sardinia and Tuscan artisan clusters favor tablets for field-based production where cold storage infrastructure remains limited.
- Powdered Rennet:Lyophilized enzyme concentrates support export logistics and extended distribution networks across temperature-variable corridors.
- Creamy Rennet:Viscous suspensions blend coagulating enzymes with lipid carriers for specialty fresh cheese applications requiring modified texture profiles.
Mature deployment sits with Liquid Rennet. Newer deployment is concentrated in Creamy Rennet.
Source:
Enzyme provenance determines kosher, halal, and vegetarian certification pathways while shaping proteolytic activity profiles that influence aged cheese flavor development.
- Microbial:Genetically modified bacterial and yeast strains produce recombinant chymosin via submerged fermentation, delivering standardized International Milk Clotting Units. German and French dairy cooperatives are accelerating procurement of microbial sources to satisfy tightening EU animal welfare directives and vegetarian-label premiums in retail cheese lines.
- Fungal:Native and engineered Aspergillus strains secrete acid proteases with broader substrate specificity than calf chymosin. Dutch Gouda and Danish hard cheese producers increasingly specify fungal-derived enzymes for cost-sensitive volume production, accepting modified aging protocols to manage bitter peptide accumulation.
- Plant-based:Cynara cardunculus thistle extracts and fig tree latex provide traditional coagulants for Portuguese Serra da Estrela and select Spanish artisan cheeses.
- Animal-derived:Calf stomach extracts retain preference among PDO-protected European cheese appellations where traditional methods are codified in certification standards.
Volume leadership belongs to Microbial sources. Certification-driven substitution is expanding fastest in Fungal alternatives.
Application:
Coagulating enzyme deployment varies sharply across moisture content requirements and protein substrate specifications.
- Cheese Production:Curd formation across fresh, soft-ripened, semi-hard, and hard cheese categories consumes the majority of clotting enzyme volume, with mozzarella and cheddar manufacturing driving standardization demands.
- Dairy Processing:Whey protein concentrate and isolate production utilizes residual coagulating activity for fractionation control.
- Gelatin Production:Collagen extraction processes employ proteolytic enzymes for controlled hydrolysis in pharmaceutical and food-grade gelatin manufacturing.
- Confectionery:Gummy candy and marshmallow applications leverage enzyme-modified proteins for texture modification in specialized product lines.
Process optimization investment concentrates in Cheese Production. Technical enzyme substitution is advancing most quickly in Gelatin Production.
End User:
Procurement scale and technical support requirements segment the customer base across integrated manufacturing and distributed artisan operations.
- Cheese Manufacturers:Large-scale industrial processors with automated vat systems and quality laboratories demand validated enzyme dossiers and fermentation batch documentation for supply continuity assurance.
- Dairy Cooperatives:Member-owned processing entities in Normandy, Lombardy, and Vermont negotiate collective purchasing agreements while maintaining flexibility for seasonal milk supply variation.
- Food Service Providers:Restaurant groups and catering operations source pre-portioned rennet for in-house fresh cheese programs and menu differentiation.
- Home Cooks:Retail-packaged tablet and liquid rennet serves hobbyist cheesemakers through specialty food retailers and direct-to-consumer fermentation supply channels.
Supply contract sophistication is highest among Cheese Manufacturers. Direct purchasing disintermediation is gaining share fastest among Home Cooks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European cheese-producing corridors dominate fermented rennet consumption, while North American craft dairy operations accelerate microbial adoption. Supply chains concentrate around established dairy clusters where regulatory displacement and certification premiums reshape procurement patterns.
Germany
Dairy cooperatives in Bavaria and Lower Saxony drive microbial rennet procurement to satisfy vegetarian-label requirements in retail cheese lines. EFSA novel food enzyme approvals for genetically modified strains accelerate substitution timelines. Stuttgart-based ingredient distributors now maintain dedicated fermentation enzyme portfolios for mid-sized cheese manufacturers.
France
PDO-protected appellations in Normandy and Auvergne-Rhône-Alpes balance traditional animal rennet codification with expanding microbial alternatives for export-oriented production. ANSM frameworks govern enzyme safety assessments alongside EFSA coordination. Roquefort-sur-Soulzon producers increasingly specify pre-validated EFSA dossiers to secure supply continuity for aged cheese operations.
United States
Wisconsin mozzarella plants and California cheddar operations prioritize liquid rennet standardization for automated continuous processing lines. FDA GRAS notifications and USDA organic certification requirements shape enzyme labeling standards. Vermont farmstead creameries in the Northeast Corridor establish direct relationships with specialty fermentation houses, bypassing traditional dairy cooperative procurement channels.
Italy
Artisan pecorino and gorgonzola producers in Sardinia and Lombardy remain tethered to traditional animal rennet, representing significant conversion potential for microbial suppliers. EMA evaluation timelines for new strains extend commercialization windows, favoring incumbent culture collection holders. Parma's dairy technology corridor attracts precision fermentation infrastructure investment from pharmaceutical contract manufacturers pivoting to food-grade enzyme production.
Netherlands
Gouda manufacturers specify fungal-derived enzymes for cost-sensitive volume production, accepting modified aging protocols to manage proteolytic activity differences. EFSA's updated toxicological data requirements compress supplier margins. Wageningen's agri-food research cluster accelerates CRISPR-edited fungal strain development for continuous fermentation bioreactor applications.
Fermented Rennet Market Competitive Landscape
Top-tier vendors anchor consolidated culture collection holdings, while mid-tier regional distributors compete on technical consultation and certification documentation. The vendor base stratifies across integrated biotechnology conglomerates, specialized fermentation houses, and regional dairy supply distributors. Three archetypes dominate: precision fermentation platform operators, artisan-focused specialty suppliers, and cooperative-linked procurement intermediaries. Capacity expansion in pharmaceutical-grade bioreactors and strategic strain licensing agreements constitute the primary competitive vectors.
Among European biotechnology conglomerates, Chr. Hansen Holding and Koninklijke DSM occupy positions exemplifying precision fermentation platform depth, while WalcoRen represents the regional distribution archetype across cheese-producing clusters. These three entities anchor tiered competitive positioning where culture collection breadth, regulatory dossier validation, and geographic proximity to dairy cooperatives determine contract capture.
| Leading Market Players |
|---|
| Chr. Hansen Holding |
| Koninklijke DSM |
| Nelson-Jameson |
| BIOTEC FERMENTI SRL |
| Sacco System |
| Clarion Casein Ltd |
| WalcoRen |
| RENCO New Zealand |
| International Flavors & Fragrances Inc. (IFF) |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation infrastructure migration from pharmaceutical contract manufacturing collapses legacy cost structures while concentrating supply among culture collection holders with validated EFSA dossiers. This technological shift simultaneously compresses unit economics for recombinant chymosin and rewires procurement relationships toward direct producer-enzyme house partnerships.
Pricing Analysis
Cost-down pressure on standard-grade microbial rennet accelerates because EFSA's expanded toxicological data requirements compress margins for suppliers lacking pre-validated dossiers. Three-tier pricing structure across premium certified, standard industrial, and economy fungal-derived tiers separates buyers by certification complexity and volume scale. Price differentiation traces to EFSA validation status and organic certification tier, with German dairy cooperatives exhibiting highest sensitivity to vegetarian-label premiums while Dutch Gouda manufacturers prioritize cost minimization.
Supply Chain Analysis
EFSA and FDA certification gating concentrates supply among Netherlands, Denmark, and Wisconsin-based precision fermentation operators with pharmaceutical-grade bioreactor access. Production draws from pharmaceutical-grade stainless steel vessel markets, fungal culture media suppliers, and cryogenic strain preservation services. Single-source vulnerability persists where CRISPR-edited strain development rests on Wageningen agri-food research cluster partnerships. Distribution runs through regional dairy supply distributors in Europe and direct-to-producer channels in North American craft dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into strain development and fermentation capacity anchors competitive durability, with backward control over culture collections and bioreactor assets emerging as the decisive upstream lever.
For Market Incumbents: Cement dossier validation advantages by acquiring mid-sized fermentation houses with pending EFSA approvals, neutralizing regulatory friction that extends commercialization windows. Prioritize captive supply of pharmaceutical-grade stainless steel fermentation vessels to insulate against input cost volatility from medical device demand cycles.
For New Entrants and Emerging Players: Artisan creameries in Vermont, Quebec, and the Pacific Northwest represent the most penetrable channel partner type, with technical consultation bundled into enzyme supply contracts displacing traditional cooperative procurement. Target Italian pecorino and gorgonzola producers through strain provenance transparency and PDO-compliant aging protocol support.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision fermentation platform acquisitions by biotechnology conglomerates seeking EFSA-validated culture collections. Long-term viability favors suppliers with continuous fermentation bioreactor deployment and CRISPR-edited strain pipelines. Watch for EMA evaluation timeline compression as inflection signal accelerating consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Licensing Agreement | Chr. Hansen and DSM anchor premium positioning through exclusive culture collection depth. |
| Continuous Fermentation Scale-Up | Wageningen cluster partnerships enable step-change yield improvements for Aspergillus niger platforms. |
| Direct-to-Producer Channel Launch | Vermont farmstead creameries bypass dairy cooperatives via enzyme subscription models with technical consultation. |
| EFSA Dossier Pre-Validation | Roquefort-sur-Soulzon producers de-risk supply continuity through suppliers with completed safety assessments. |
| Backward Integration into Strain Development | Mid-tier suppliers acquire CRISPR-edited fungal strain capabilities to compress EMA evaluation timelines. |
Research Methodology
EFSA novel food enzyme filings, FDA GRAS notifications, and pharmaceutical-grade fermentation equipment trade data formed the secondary backbone, cross-referenced with primary interviews involving dairy cooperative procurement directors, artisan creamery operators, fermentation scientists, and specialty enzyme distributors. Bottom-up and top-down triangulation validated clotting enzyme volume estimates against mozzarella and cheddar production statistics from Wisconsin and California processing corridors.
Bottom-up modeling segmented the analysis window by rennet form factor, microbial source category, and cheese application tier, with value outputs derived from procurement contract benchmarking across German, French, and Italian dairy cooperatives. CAGRs were computed from standardized International Milk Clotting Unit pricing trajectories and precision fermentation capacity expansion announcements, incorporating EMA evaluation timeline assumptions for genetically modified strain approvals.
Caveats apply where EFSA toxicological data requirement expansions or pharmaceutical-grade stainless steel supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding EMA evaluation timeline stability and craft dairy direct purchasing momentum. A model refresh is warranted upon material change in EU animal welfare directive enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Millet Protein Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Commercial Amino Acids Market
Ingredients
Cocoa Maker Market
Ingredients
South America Malt Ingredient Market
Ingredients
Energy Ingredients Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Honey Powder Market
Ingredients
Durian Powder Market
Ingredients
Grape Seed Extracts Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Fermented Ingredients Market