
 India Food Acidulants Market | 2026-2036
India Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Acidulants Market Foresight
Clean-label fermentation technology is tilting acidulant production toward bio-based citric and lactic acid platforms that reduce petrochemical dependency. Corbion NV leverages microbial fermentation expertise to sustain premium positioning in natural acidulant supply. ADM anchors bulk supply agreements with pan-Indian beverage conglomerates through its extensive distribution infrastructure. Jungbunzlauer Suisse AG differentiates via specialized malic acid grades targeting confectionery and sports nutrition applications.
Food acidulants comprise organic compounds—primarily citric, lactic, malic, and tartaric acids—that impart tartness, regulate pH, and function as preservatives across processed food systems, typically manufactured through submerged fermentation or chemical synthesis with purity thresholds exceeding 99.5 percent for food-grade certification. Citric acid dominates volume throughput due to its universal applicability in beverages and dairy, while lactic acid captures expanding share in clean-label dairy applications where consumers reject synthetic preservatives. Malic acid commands margin premiums in confectionery and sports drinks, though tartaric acid remains a niche specialist confined to baking powder and wine adjunct formulations with limited volume scalability.
FSSAI mandates food-grade acidulant purity specifications under the Food Safety and Standards Act, while BIS certification requirements for imported acidulant raw materials shape procurement patterns among domestic compounders. The PLI scheme for food processing incentivizes backward integration into fermentation-based acidulant manufacturing, though state-level pollution control boards impose effluent discharge limits that constrain greenfield fermentation capacity expansion. Stakeholders must monitor evolving FSSAI additive codex amendments and state-level environmental clearances as decisive variables for capacity planning and import substitution strategies.
Market Dynamics
FSSAI purity mandates are compressing the supplier base as domestic compounders abandon low-grade import channels and invest in fermentation-based manufacturing capabilities that satisfy food-grade certification thresholds.
Growth Catalysts
- PLI scheme incentives:The food processing production-linked incentive scheme subsidizes backward integration into citric and lactic acid fermentation, reducing capital recovery periods for greenfield bioreactor installations.
- Beverage formulation intensity:Carbonated and functional drink manufacturers in Maharashtra and Gujarat are expanding acidulant procurement volumes to support pH stabilization in clean-label product lines.
- State cluster concentration:Processed food manufacturing hubs in Ahmedabad, Pune, and Mumbai generate concentrated demand pull that justifies dedicated distribution infrastructure and technical service presence.
Market Restraints
- Molasses feedstock volatility:Sugar industry supply fluctuations and ethanol diversion priorities create input cost instability for fermentation-based acidulant producers dependent on agricultural substrates.
- Import dependency for specialty grades:High-purity malic and tartaric acid requirements force reliance on Chinese and European suppliers, exposing compounders to currency and logistics risk.
- Effluent discharge constraints:State pollution control boards in Gujarat and Maharashtra enforce stringent COD and BOD limits that cap fermentation capacity expansion regardless of demand signals.
Strategic Opportunities
- Karnataka and Tamil Nadu penetration:Underdeveloped acidulant sourcing infrastructure in southern processed food corridors creates first-mover advantages for distributors establishing technical sales networks.
- Sports nutrition application expansion:Malic acid demand from electrolyte and endurance supplement manufacturers is outpacing supply, opening premium positioning for certified domestic producers.
- FSSAI additive codex alignment:Anticipated harmonization with Codex Alimentarius standards will enable export-qualified Indian acidulant manufacturers to access Middle Eastern and African markets.
Industry Challenges
- Fermentation microbiology expertise scarcity:Industrial strain optimization and bioprocess engineering talent pools remain shallow, forcing reliance on foreign technical consultants for scale-up operations.
- Multi-certification timeline compression:Simultaneous pursuit of FSSAI food-grade approval, BIS import substitution credentials, and export-market registrations strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Acidulants Market |
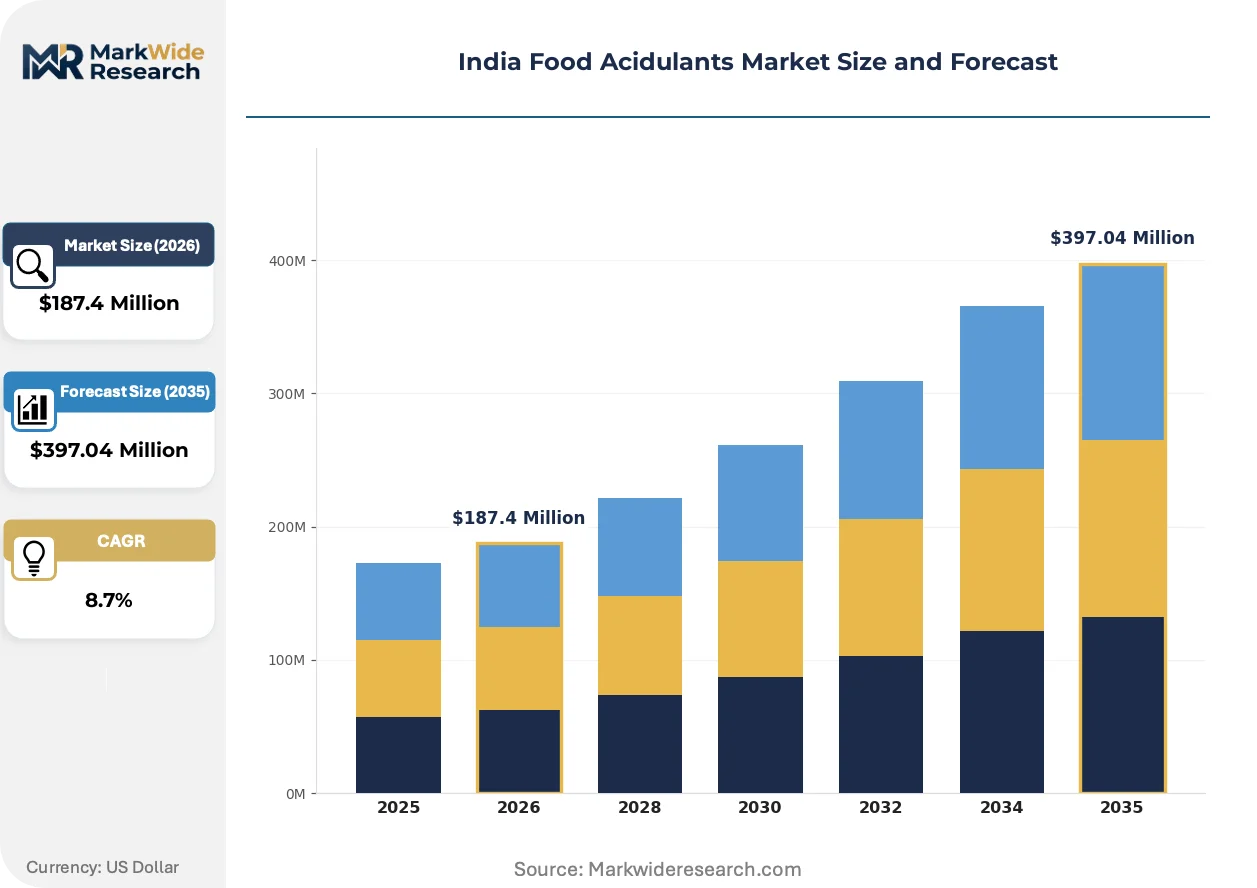
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Tartaric Acid Application: Beverages, Dairy Products, Confectionery, Snacks End User: Food Manufacturers, Beverage Producers, Snack Companies, Confectionery Makers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Brenntag AG, Corbion NV, ADM, Acuro Organics Limited, Parry Enterprises India Ltd, Cargill Inc, Jungbunzlauer Suisse AG, Hawkins Watts Ltd, Tate & Lyle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Acidulants Market Shifts & Advancements
Bio-based manufacturing platforms are displacing petrochemical synthesis routes as the dominant production paradigm, while regulatory tightening and buyer consolidation reshape competitive requirements across the value chain.
Submerged fermentation technology is migrating from batch to continuous processing architectures. Citric acid manufacturers are retrofitting bioreactor trains with cell retention systems that boost volumetric productivity. Beverage compounders in Gujarat are qualifying these higher-purity outputs for functional drink formulations. The shift is compressing unit economics for petrochemical-derived acidulant imports.
FSSAI's additive purity amendments under the Food Safety and Standards Act are mandating heavy metal thresholds below 10 ppm for all food-grade acidulants. Domestic fermentation operators are investing in chromatographic polishing and crystallization upgrades to meet these specifications. Maharashtra-based dairy processors are rejecting non-compliant imports, accelerating supplier qualification timelines.
Direct procurement relationships between acidulant manufacturers and large beverage conglomerates are displacing layered distributor networks. Compounders with annual offtake above 500 metric tons are negotiating annual framework agreements that bundle technical service, inventory management, and formulation support. This consolidation is most visible in the Ahmedabad-Mumbai corridor where processed food manufacturing density supports dedicated supply chain investments.
India Food Acidulants Market Segmentation
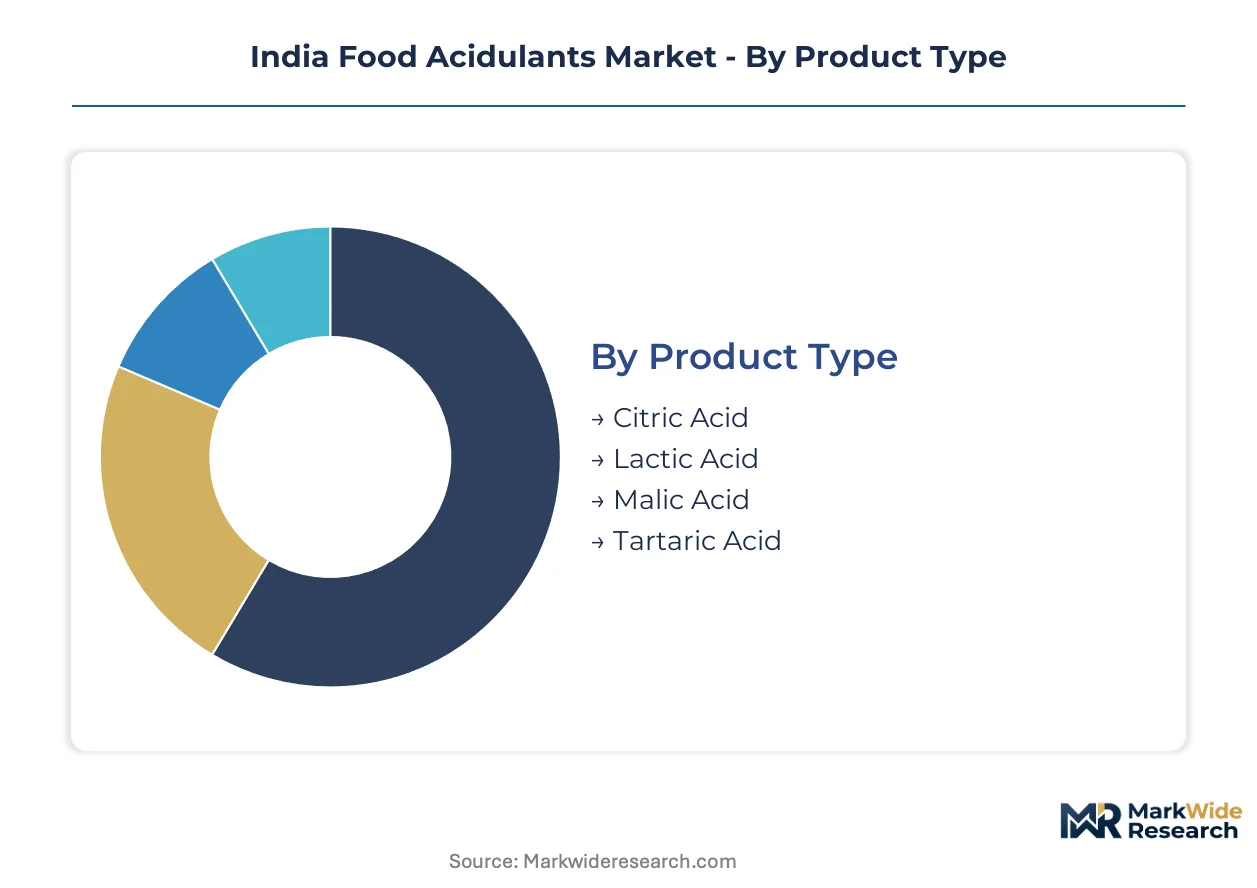
Segmentation in the India Food Acidulants Market reveals how procurement cycles, certification requirements, and application intensity vary across product chemistry and customer type. Manufacturers configure supply chain investments differently depending on whether they serve high-volume beverage contracts or specialty confectionery formulations.
Product Type:
Inventory velocity diverges sharply across acidulant chemistries, with citric acid turning over in weeks while tartaric acid moves in quarterly cycles tied to wine and baking seasonality.
- Citric Acid:Derived through submerged fermentation of Aspergillus niger on molasses substrate, this acidulant achieves food-grade purity above 99.5 percent. Maharashtra beverage conglomerates in the Mumbai-Pune corridor consume the bulk of national volume, driven by carbonated drink pH stabilization requirements and FSSAI-mandated preservative reductions in clean-label lines.
- Lactic Acid:Fermentation-produced from lactose or glucose feedstocks, this acidulant carries GRAS status with enhanced consumer acceptance in preservative-sensitive categories. Gujarat dairy processors in Ahmedabad cluster are expanding procurement for yogurt and cheese applications where synthetic additive rejection is accelerating format switches.
- Malic Acid:Commands premium positioning in sports nutrition and sour confectionery segments with sharper taste persistence than citric alternatives.
- Tartaric Acid:Grape-derived specialist confined to baking powder formulations and wine adjunct applications with limited domestic fermentation capacity.
Citric acid anchors the volume base while lactic acid gains share at the steepest rate.
Application:
Margin structures stratify across application tiers, with beverages extracting scale efficiencies and confectionery supporting price premiums through specialized grade requirements.
- Beverages:Carbonated and functional drink manufacturers deploy acidulants for pH buffering, flavor enhancement, and preservative synergy. The Ahmedabad-Mumbai manufacturing belt generates concentrated demand pull that justifies dedicated technical service teams and just-in-time inventory programs.
- Dairy Products:Clean-label fermentation acids replace synthetic preservatives in yogurt, cheese, and flavored milk applications. Karnataka dairy cooperatives are emerging as incremental demand centers as southern processed food infrastructure matures.
- Confectionery:Sour candy and gummy formulations require precise acidulant blends for controlled release and surface dusting applications.
- Snacks:Seasoning and coating applications for extruded and fried products utilize acidulants for flavor enhancement and shelf-life extension.
Beverages dominate procurement volumes while dairy applications expand most quickly on clean-label conversion.
End User:
Customer concentration patterns determine contract structure, with beverage producers consolidating procurement through annual framework agreements and snack companies maintaining fragmented spot-market purchasing.
- Food Manufacturers:Processed food compounders across Maharashtra and Gujarat integrate acidulants into sauce, dressing, and ready-meal formulations. FSSAI purity mandates are compressing their supplier base toward fermentation-certified domestic sources.
- Beverage Producers:Carbonated and functional drink specialists negotiate direct procurement relationships that bundle technical service and inventory management. Annual offtake thresholds above 500 metric tons trigger dedicated supply chain investments.
- Snack Companies:Seasoning and coating applications drive procurement with emphasis on cost-competitive citric acid grades.
- Confectionery Makers:Sour candy and gummy specialists require malic acid blends with precise particle size distribution for controlled release.
Beverage producers command the tightest supplier integration while food manufacturers drive the broadest certification upgrades.
Distribution Channel:
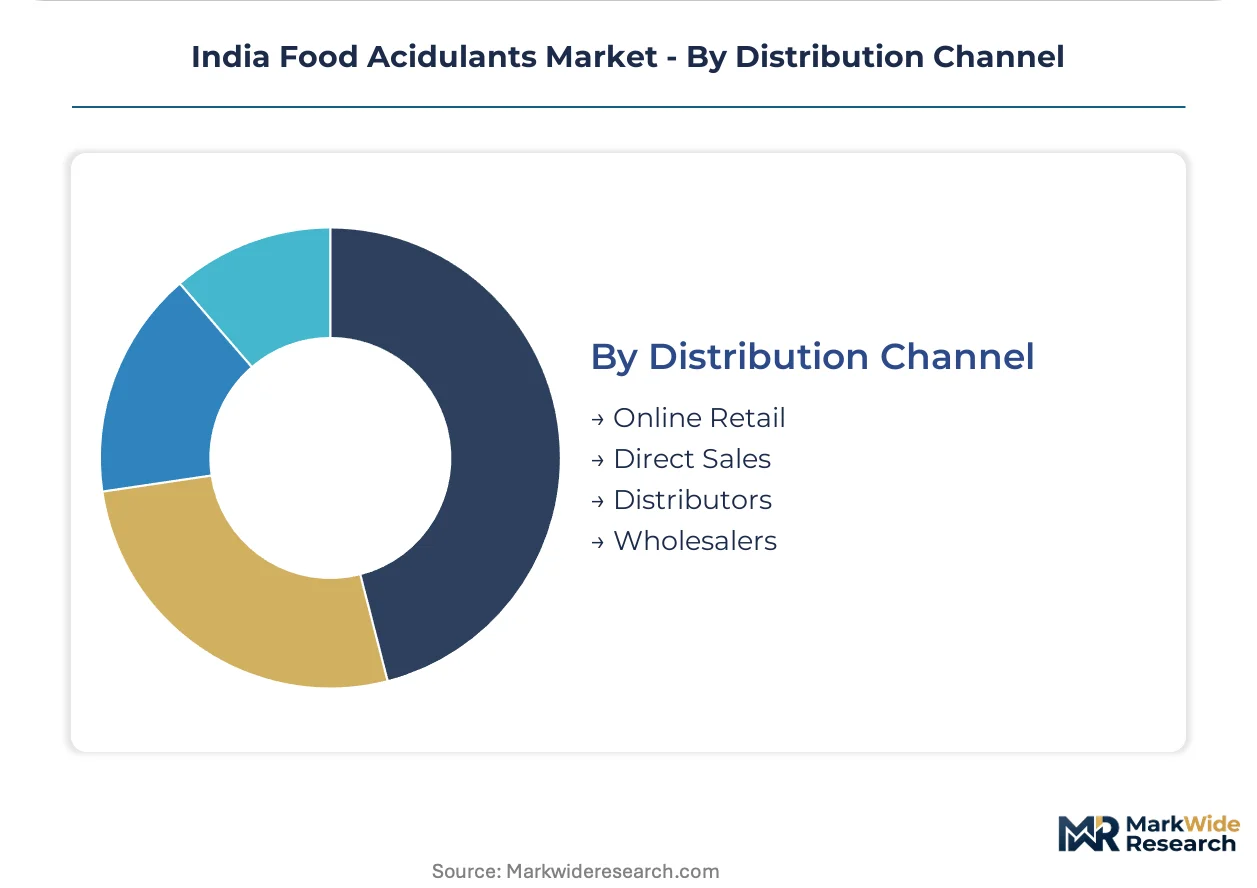
Channel economics reflect order fragmentation, with direct sales capturing consolidated volume and distributors serving geographically dispersed small and mid-scale compounders.
- Direct Sales:Large acidulant manufacturers bypass intermediary layers for annual framework agreements with beverage and dairy conglomerates exceeding 500 metric tons. Technical service bundling and inventory management integration characterize these relationships in the Ahmedabad-Mumbai corridor.
- Distributors:Regional chemical distributors serve fragmented snack and confectionery manufacturers with smaller lot sizes and irregular ordering patterns. Tamil Nadu and Karnataka penetration depends on distributor technical sales capacity.
- Online Retail:E-procurement platforms capture spot-market transactions for research and development quantities and small-batch artisanal producers.
- Wholesalers:Traditional bulk traders serve price-sensitive segments with limited technical service requirements.
Direct sales capture the volume concentration while distributor networks extend geographic coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese acidulant exports flow disproportionately into Maharashtra and Gujarat, where beverage manufacturing clusters absorb bulk fermentation-grade citric acid for carbonated drink formulations.
Maharashtra
Mumbai-Pune beverage corridors drive concentrated citric acid procurement for pH stabilization in clean-label carbonated lines. FSSAI purity mandates above 99.5 percent compel domestic compounders to abandon low-grade import channels. Nashik fermentation facilities are retrofitting bioreactor trains with cell retention systems to meet heavy metal thresholds below 10 ppm.
Gujarat
Ahmedabad dairy processors are expanding lactic acid procurement for yogurt and cheese applications where synthetic preservative rejection accelerates format switches. State pollution control boards enforce COD and BOD discharge limits that cap greenfield fermentation capacity regardless of demand signals. Sanand industrial estates host backward-integrated acidulant manufacturing subsidized under PLI scheme provisions.
Karnataka
Bengaluru-based sports nutrition manufacturers are qualifying malic acid grades for electrolyte and endurance supplement formulations. The state's emerging processed food infrastructure lacks dedicated acidulant distribution networks, creating first-mover advantages for technical sales entrants. Mysuru dairy cooperatives are emerging as incremental demand centers for clean-label fermentation acids.
Tamil Nadu
Chennai confectionery specialists require precise malic acid particle size distribution for controlled-release sour candy applications. Underdeveloped sourcing infrastructure forces reliance on spot-market procurement through regional chemical distributors. Coimbatore snack seasoning manufacturers are consolidating citric acid purchasing to secure volume pricing from direct suppliers.
India Food Acidulants Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational fermentation specialists and domestic compounders scrambling to meet FSSAI certification thresholds. Tier-one players anchor bulk supply agreements with annual offtake floors above 500 metric tons, while mid-scale operators serve fragmented confectionery and snack segments through distributor networks. Strategic archetypes include microbial fermentation platforms, petrochemical synthesis survivors, and import-dependent specialty grade traders. Capacity expansion into continuous bioreactor architectures and backward integration into molasses feedstock control dominate competitive moves.
Among European-headquartered specialists, Corbion NV and Jungbunzlauer Suisse AG occupy positions within the premium fermentation tier, representing microbial platform expertise and specialized acidulant grade development respectively. ADM anchors the scale-driven segment through extensive distribution infrastructure. Domestic compounders Acuro Organics Limited and Parry Enterprises India Ltd exemplify import-substitution aspirants pursuing FSSAI food-grade approval and BIS certification credentials simultaneously.
| Leading Market Players |
|---|
| Brenntag AG |
| Corbion NV |
| ADM |
| Acuro Organics Limited |
| Parry Enterprises India Ltd |
| Cargill Inc |
| Jungbunzlauer Suisse AG |
| Hawkins Watts Ltd |
| Tate & Lyle |
| Others |
Supply & Pricing Matrix
Molasses feedstock volatility determines both the premium spread between fermentation-derived and petrochemical acidulant grades and the geographic clustering of domestic bioreactor capacity around sugar belt states. FSSAI purity mandates compressing the supplier base amplify pricing power for certified domestic producers while exposing importers to rejection risk at Maharashtra and Gujarat processing gates.
Pricing Analysis
Batch fermentation versus continuous bioreactor technology drives the dominant pricing gap, with legacy batch operators commanding standard-tier rates while cell-retention retrofit facilities capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified fermentation grades from BIS-import substitution tiers and uncertified spot-market material. Cost compression in economy-tier citric acid intensifies because Chinese import diversion to ethanol production tightens global molasses availability. Snack seasoning manufacturers exhibit highest price sensitivity due to thin margin structures, while sports nutrition formulators show least sensitivity given malic acid's irreplaceable taste persistence.
Supply Chain Analysis
DGFT import licensing restrictions on Chinese acidulant consignments limit flows into Mumbai and Ahmedabad ports, forcing compounders toward domestic fermentation sourcing. Supply concentrates in Maharashtra, Gujarat, and Karnataka state clusters, with Nashik and Sanand bioreactor installations anchoring national capacity. Raw material dependencies center on sugar industry molasses, corn-derived glucose for lactic acid platforms, and imported grape must for tartaric acid production. Single-source vulnerability runs through Chinese malic and tartaric acid suppliers, exposing compounders to currency and logistics disruption. Distribution runs through direct annual framework agreements for beverage conglomerates exceeding 500 metric tons, with regional chemical distributors serving fragmented confectionery and snack segments in Tamil Nadu and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling and formulation support contracts expand faster than commodity acidulant sales, creating recurring-revenue attach opportunities for fermentation-certified suppliers. Inventory management integration and just-in-time delivery programs now command pricing premiums exceeding base chemical value.
For Market Incumbents: Pre-empt FSSAI codex harmonization with Codex Alimentarius by accelerating Middle East and Africa export registration timelines before domestic competitors qualify. Anchor backward integration into molasses feedstock through sugar mill offtake agreements in Uttar Pradesh and Maharashtra, neutralizing ethanol diversion risk. Defend against specialty-grade import substitution by chromatographic polishing investments that achieve heavy metal thresholds below 10 ppm. For New Entrants and Emerging Players: Karnataka and Tamil Nadu dairy cooperatives represent the most penetrable entry point given underdeveloped acidulant sourcing infrastructure and clean-label fermentation acid demand acceleration. Sports nutrition malic acid applications offer premium positioning with supply-constrained market dynamics favoring first-certified domestic producers. Pursue technical sales network establishment with distributor partnerships rather than direct sales infrastructure given fragmented order patterns. For Investors and Strategic Acquirers: FSSAI additive purity amendments reshaping the acquisition landscape toward fermentation-certified domestic compounders with simultaneous BIS and export-market registration pipelines. Five-to-ten-year viability favors microbial platform operators with continuous bioreactor retrofit capabilities over petrochemical synthesis survivors facing feedstock cost compression. Monitor PLI scheme disbursement velocity as inflection indicator for greenfield capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Retrofit | Cell retention systems boost volumetric productivity for Gujarat beverage compounders qualifying higher-purity outputs. |
| Backward Integration into Molasses | Sugar mill offtake agreements in Maharashtra secure feedstock priority over ethanol diversion channels. |
| FSSAI Export Registration Pipeline | Codex Alimentarius alignment enables Middle Eastern and African market access for Nashik fermentation facilities. |
| Technical Service Bundling | Formulation support and inventory management integration command pricing premiums from Ahmedabad-Mumbai beverage corridors. |
| Chromatographic Polishing Investment | Heavy metal thresholds below 10 ppm meet dairy processor rejection of non-compliant imports in Maharashtra. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI additive codex amendments, BIS certification registries, and PLI scheme disbursement records. Primary interviews engaged fermentation plant managers, beverage procurement leads at Maharashtra and Gujarat conglomerates, dairy processor technical directors, and regional chemical distributor principals. Secondary validation drew from customs import data, state pollution control board effluent discharge records, and sugar industry molasses supply reports. Bottom-up acidulant volume estimates triangulated against top-down processed food production capacity assessments.
Forecast inputs include fermentation capacity expansion timelines, FSSAI regulatory amendment trajectories, and molasses feedstock availability projections across the analysis window. Segmentation dimensions modeled encompass acidulant chemistry tier, application intensity by beverage-dairy-confectionery-snack categories, end-user procurement scale, and distribution channel structure. CAGRs derive from volume-demand elasticity against processed food output growth and substitution rates from synthetic to fermentation-derived preservatives. Industry-specific inputs incorporate PLI scheme incentive uptake rates and state-level environmental clearance velocity.
Practitioners should monitor FSSAI codex amendment timing, molasses diversion to ethanol production, and Chinese export licensing restrictions for early signals. Forecasts reflect assumptions regarding regulatory enforcement consistency and feedstock supply stability. Material shifts in PLI scheme disbursement rates or state pollution control board capacity clearance timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Africa Food Stabilizers Market