
 Spain Food Enzymes Market | 2026-2036
Spain Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Enzymes Market Analytics
The Spain food enzymes sector is pivoting around a widening split between premium specialty enzymes and commodity bulk grades. Kerry Group plc leverages its integrated ingredient platforms to dominate high-value bakery applications, while Novozymes Group anchors microbial fermentation capacity for industrial-scale dairy contracts. CYGYC BIOCON S.L. competes as a domestic specialist with concentrated regional distribution across northern Spain.
Food enzymes are protein-based biocatalysts, typically operating at 30–70°C and pH 4.0–8.5, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. Their primary commercial purpose spans starch hydrolysis, protein modification, lipid transformation, and cell wall degradation to improve processing efficiency and product quality. Proteases command the largest share of enzyme value in meat processing and cheese making, while lipases generate premium margins in dairy flavor enhancement and bakery shortening applications. Microbial-sourced enzymes outpace plant and animal alternatives due to scalable fermentation economics and stronger alignment with Spain's expanding vegan-label product lines.
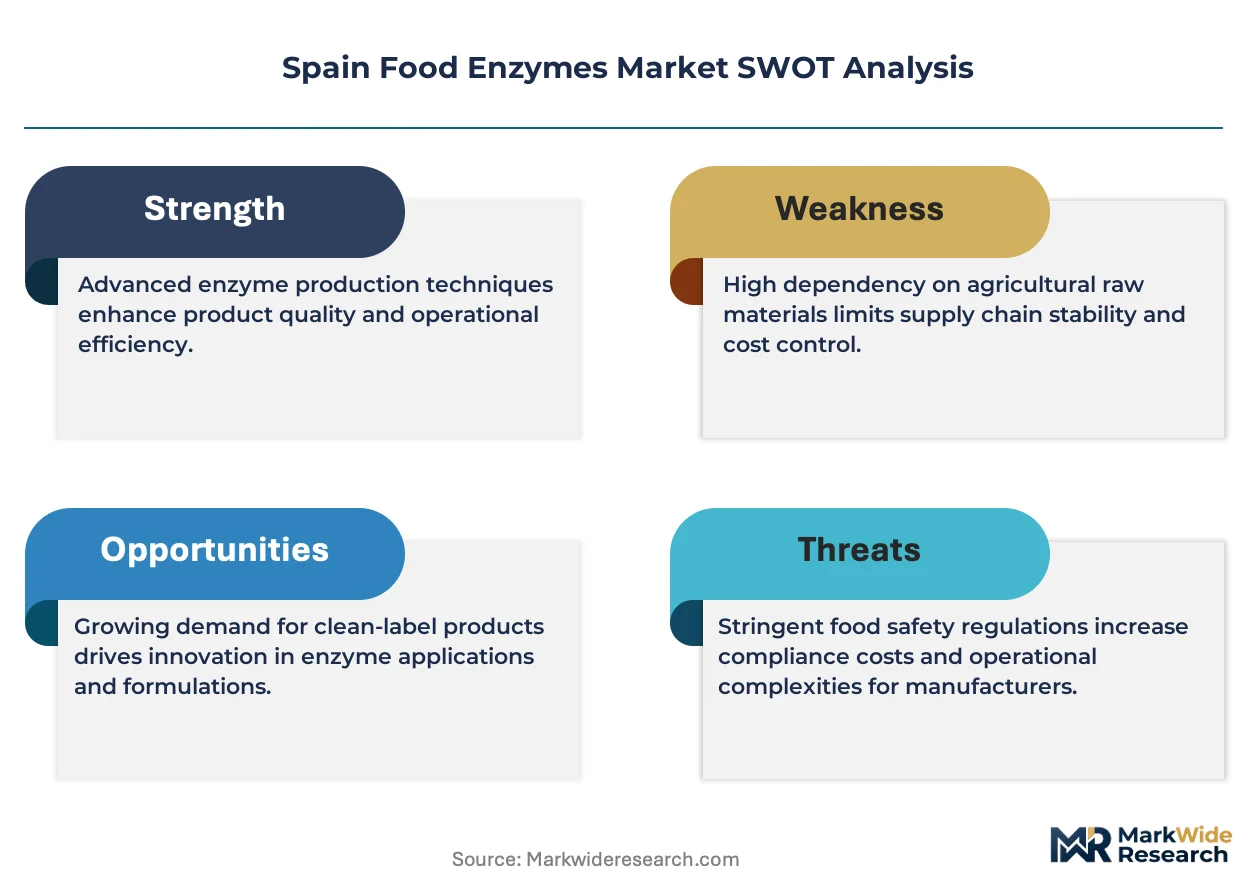
Spain's enzyme market operates under the EU's Food Enzyme Regulation (EC) 1332/2008, with EFSA evaluating safety dossiers for new enzyme preparations, while Banco de España tracks inflation impacts on imported fermentation feedstocks. Spanish manufacturers must reconcile EFSA positive-list requirements with AEMPS national enforcement on labeling and purity standards, creating compliance barriers for non-EU enzyme suppliers. Stakeholders should monitor how EFSA's ongoing reassessment of existing food enzymes reshapes approved-source lists and reformulation costs.
Market Dynamics
Spain's food enzymes market is bifurcating between commodity-grade bulk enzymes and precision-formulated specialty preparations, with AEMPS enforcement of EU labeling rules accelerating the shift toward microbial-derived, clean-label alternatives in industrial baking and dairy processing clusters.
Growth Catalysts
- EU Food Enzyme Regulation (EC) 1332/2008:EFSA's positive-list system creates compliance-driven demand for pre-approved microbial sources, advantaging domestic formulators with established safety dossiers over unlisted imports.
- Catalonia's industrial baking corridor:Dense concentration of automated bread and pastry manufacturers sustains concentrated procurement volumes for dough-conditioning enzyme blends with extended shelf-life functionality.
- Fermentation feedstock optimization:Advances in submerged cultivation of Aspergillus and Bacillus strains reduce unit production costs for carbohydrase and protease preparations targeting Spanish dairy processors.
Market Restraints
- EFSA reassessment timeline uncertainty:Ongoing safety reviews of existing food enzymes create reformulation risk for manufacturers dependent on legacy enzyme preparations awaiting reauthorization.
- Imported fermentation substrate volatility:Spain's reliance on foreign corn steep liquor and yeast extract supplies exposes enzyme producers to Banco de España-tracked inflation in agricultural commodity inputs.
- Plant-based enzyme substitution:Bromelain and papain extracts from tropical sources compete in specific bakery and meat-tenderizing applications where heat stability requirements are less stringent.
Strategic Opportunities
- Basque Country precision dairy:Underpenetrated artisanal cheese producers present white-space demand for lipase-based flavor enhancement systems beyond current industrial contract coverage.
- EU Green Deal bioprocessing incentives:Fermentation-based enzyme production qualifies for sustainability-linked financing, reducing capex barriers for capacity expansion in northern Spain.
- Direct-to-manufacturer digital procurement:Specialty enzyme distributors are bypassing traditional chemical wholesalers to serve mid-size Spanish meat processors with customized protease blends.
Industry Challenges
- EFSA dossier preparation expertise:Shortage of toxicologists and food safety assessors familiar with enzyme-specific submission requirements delays new product market entry for Spanish biotech startups.
- Legacy equipment incompatibility:Temperature-sensitive next-generation enzymes require retrofitting of existing spray-drying and granulation infrastructure at established Spanish ingredient plants.
- Cross-contamination prevention protocols:Allergen management systems must distinguish enzyme carriers from active proteins, complicating multi-product line operations under AEMPS inspection regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Enzymes Market |
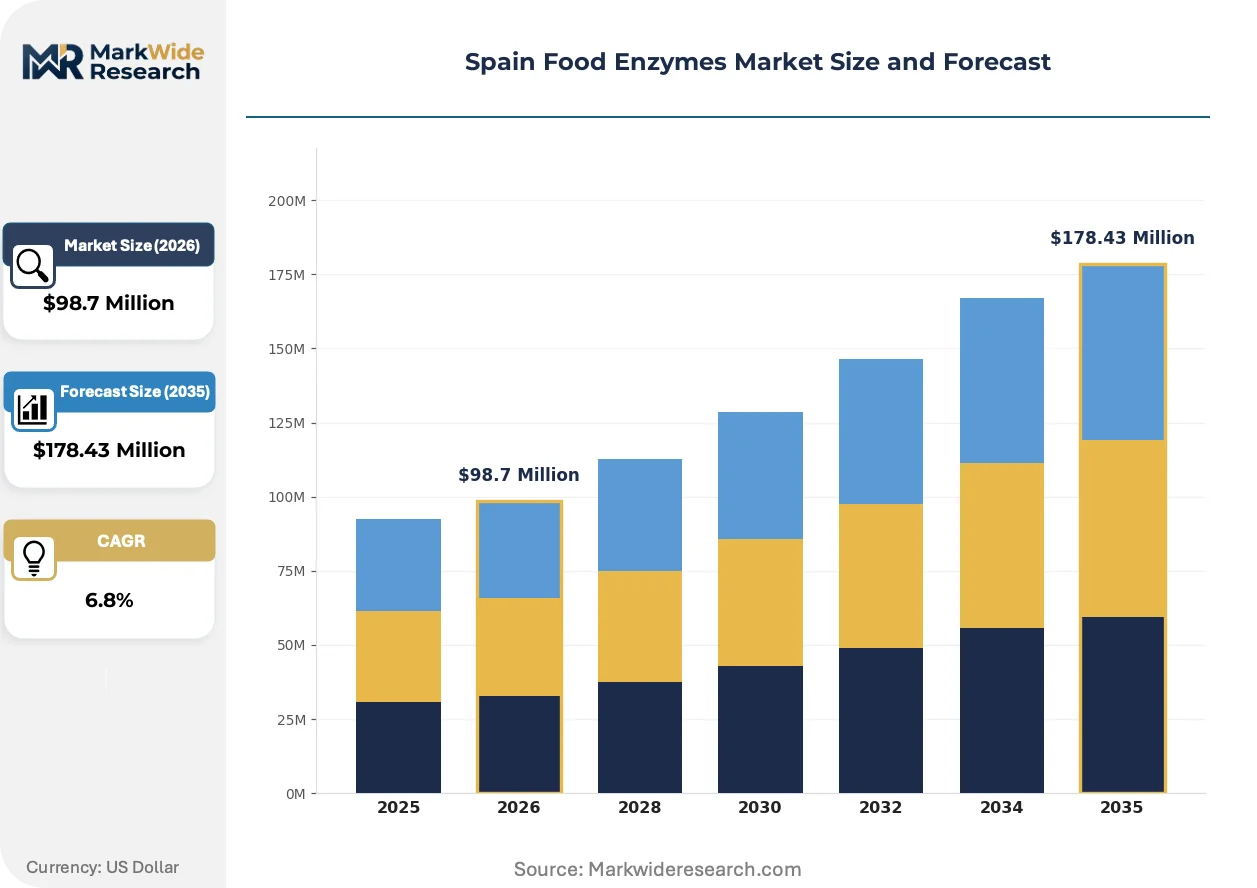
| Market Size in 2026 | $98.7 Million |
| Market Size in 2035 | $178.43 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Dairy Processing, Beverage Production, Meat Processing Source: Microbial, Plant-based, Animal-based, Fungal End User: Food Industry, Beverages Industry, Bakery Sector, Dairy Industry |
| Companies Covered | Kerry Group plc, Novozymes Group, Koninklijke DSM N.V., Chr. Hansen Holding GmbH, BASF SE, CYGYC BIOCON S.L., Novonesis AS, Lesaffre, Advanced Enzymes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Enzymes Market Evolving Landscape
Spanish food enzyme development is pivoting toward precision biocatalysis systems that reconcile processing efficiency gains with clean-label positioning, driven by AEMPS labeling scrutiny and industrial buyer consolidation in Catalonia and the Basque Country.
Immobilized enzyme reactor technology is expanding into continuous bread and beverage processing lines. Spanish industrial bakers in the Barcelona metropolitan area are retrofitting batch systems with fixed-bed glucose oxidase and transglutaminase configurations. This shift is compressing enzyme consumption per ton of output while stabilizing dough rheology across variable wheat harvests.
EFSA's 2023-2025 systematic re-evaluation of existing food enzymes is forcing reformulation cycles across Spanish dairy and meat processing sectors. Manufacturers dependent on legacy animal-derived rennet and lipase preparations face sourcing transitions toward microbial alternatives. The Basque Country's idiazábal and ossau-iraty cheese protected designation of origin producers are most exposed, accelerating domestic fermentation capacity investment.
Consolidated procurement by Spain's top-five bakery groups is displacing fragmented distributor relationships with direct technical partnerships. Large Catalan manufacturers now specify enzyme performance metrics rather than purchasing standardized grades. This behavioral shift concentrates supplier development resources on fewer accounts and marginalizes smaller Spanish enzyme traders lacking application laboratories.
Spain Food Enzymes Market Segmentation
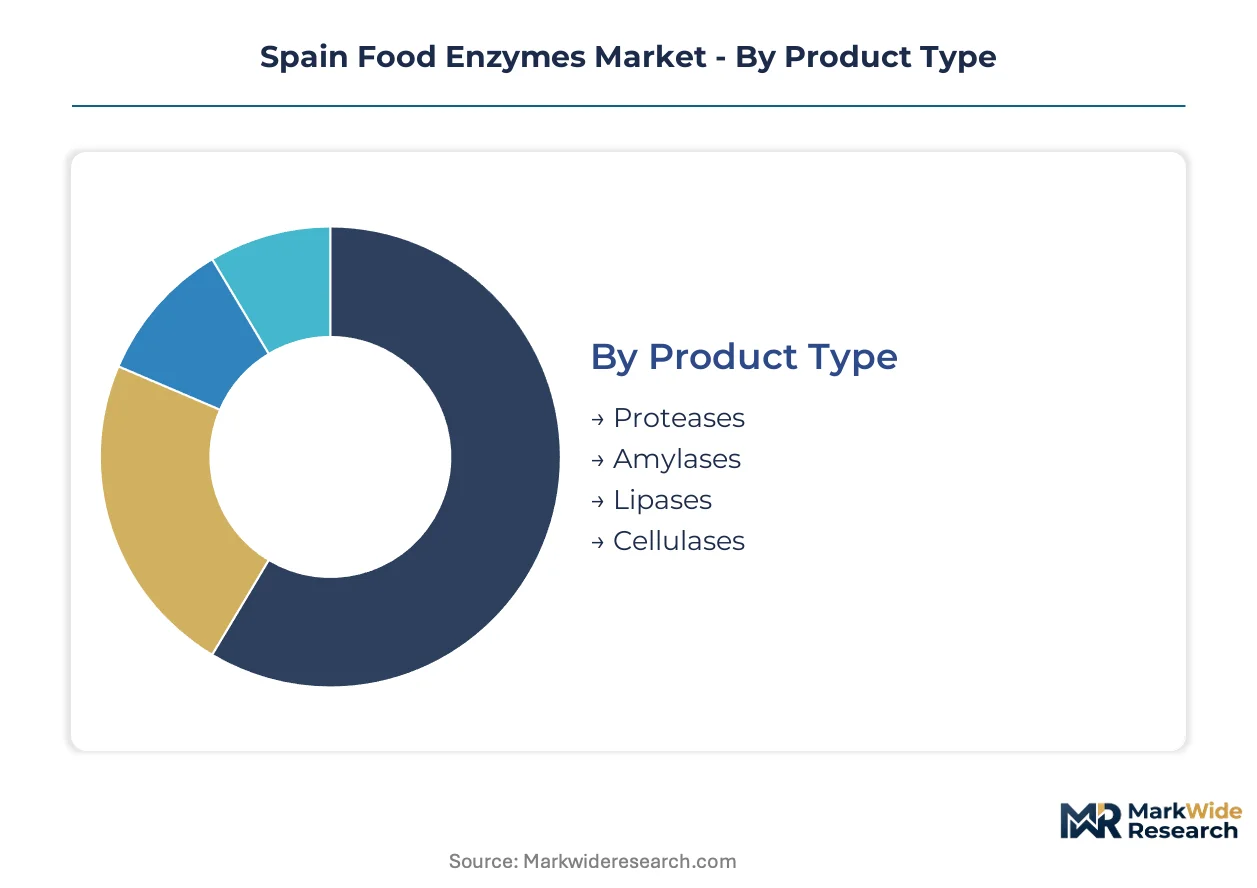
Enzyme procurement patterns in Spain diverge sharply across product categories and end-use applications. AEMPS labeling enforcement and EFSA positive-list compliance reshape how manufacturers prioritize segments by capital efficiency and reformulation risk.
Product Type:
Capital intensity peaks in segments requiring dedicated fermentation infrastructure and downstream purification systems.
- Proteases:Hydrolytic enzymes cleaving peptide bonds at specific amino acid residues, typically sourced from Bacillus subtilis or Aspergillus oryzae fermentation. Basque Country idiazábal and ossau-iraty PDO cheese producers anchor concentrated demand for microbial rennet alternatives as EFSA reassessment threatens legacy animal-derived preparations.
- Amylases:Starch-degrading enzymes operating via endo- and exo-hydrolysis mechanisms, with thermostable variants dominating industrial bread production. Catalonia's automated baking corridor sustains the densest procurement volumes for dough-conditioning blends that extend shelf-life without chemical preservatives.
- Lipases:Ester hydrolases catalyzing triglyceride breakdown for flavor development in dairy shortening and specialty fats.
- Cellulases:Complex multi-enzyme systems degrading β-1,4-glycosidic linkages in plant cell walls for fruit juice clarification and vegetable processing.
Most installed capacity flows through proteases. Expansion is steepest in amylases.
Application:
Application-level investment concentrates where processing scale and automation density justify dedicated enzyme dosing systems.
- Baking:Enzyme-mediated dough conditioning for rheology control, gas retention, and crumb structure optimization. Barcelona metropolitan area industrial bakers retrofit continuous lines with immobilized glucose oxidase and transglutaminase reactors, compressing enzyme consumption per ton while stabilizing output across variable wheat harvests.
- Dairy Processing:Milk protein hydrolysis, fat modification, and lactose conversion systems. Northern Spain's precision cheese producers drive specialized lipase demand for flavor-accentuated artisanal products beyond commodity industrial contracts.
- Beverage Production:Enzymatic clarification, filtration aid, and alcohol conversion in wine, beer, and fruit juice manufacturing.
- Meat Processing:Proteolytic tenderization and flavor precursor generation for cured and processed meat products.
Procurement scale concentrates in baking. Technical complexity and margin expansion are climbing fastest in dairy processing.
Source:
Source selection determines regulatory pathway length and clean-label positioning in AEMPS-inspected facilities.
- Microbial:Fermentation-derived enzymes from bacterial and fungal hosts, dominating commercial supply through scalable submerged cultivation economics. EFSA's positive-list system under Regulation (EC) 1332/2008 advantages pre-approved Aspergillus and Bacillus strains, disadvantaging novel microbial sources awaiting safety dossier evaluation.
- Plant-based:Bromelain from pineapple stems and papain from Carica papaya latex, competing in heat-stable meat tenderization and specific bakery applications where precision activity control matters less than cost.
- Animal-based:Traditional rennet from calf stomachs and pancreatic lipases, facing sourcing transition pressure as EFSA systematic re-evaluation progresses.
- Fungal:Dedicated category for Aspergillus-derived preparations with distinct pH-activity profiles optimized for acidic food matrices.
Production volume concentrates in microbial sources. Clean-label momentum is accelerating plant-based substitution fastest.
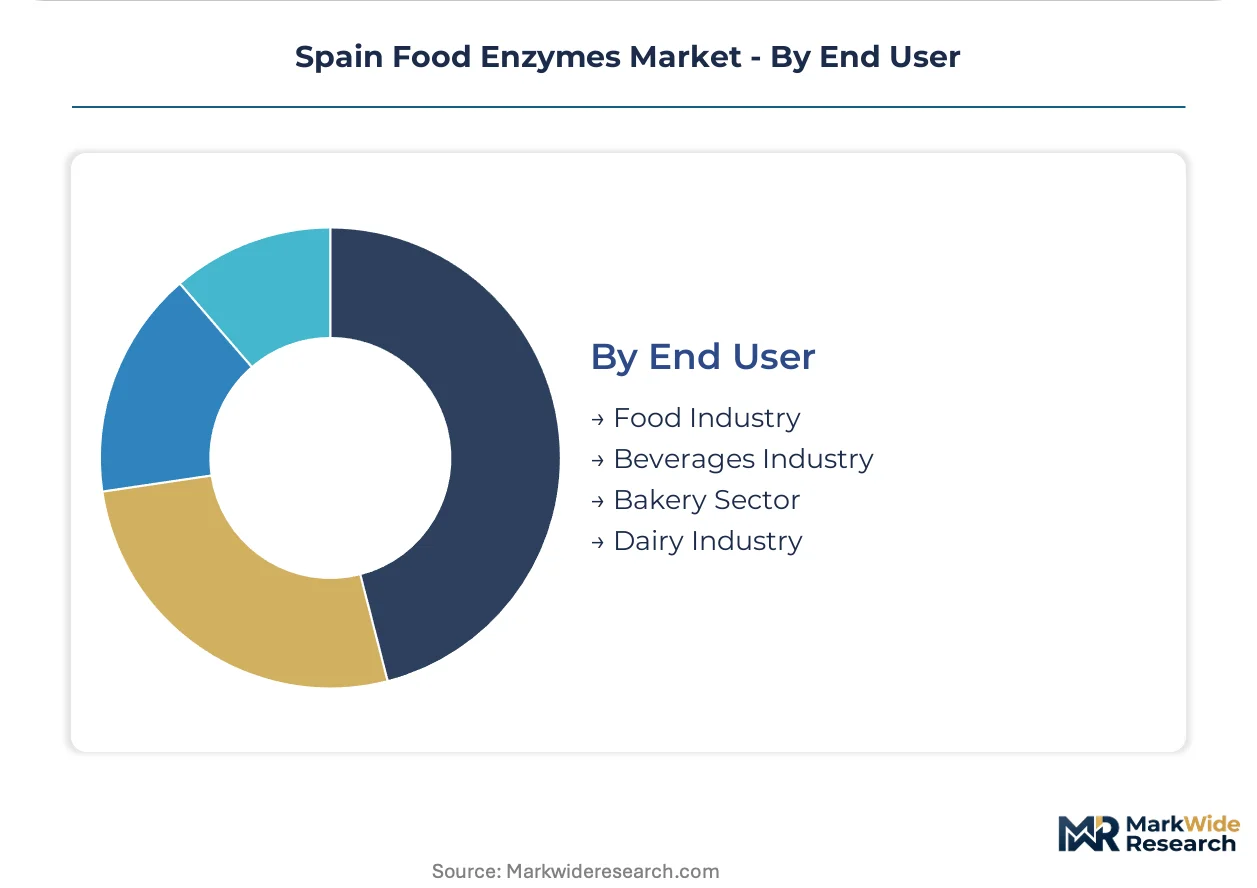
End User:
End-user structure reflects consolidation patterns and technical partnership depth across Spain's food manufacturing base.
- Food Industry:Broad processed food manufacturing encompassing sauces, dressings, and prepared meals with diverse enzyme requirements.
- Beverages Industry:Wine, beer, and spirits producers with seasonal procurement patterns and terroir-specific processing needs.
- Bakery Sector:Industrial bread, pastry, and biscuit manufacturers with highest enzyme dosing frequency and most sophisticated application laboratory relationships.
- Dairy Industry:Fluid milk, cheese, and fermented product processors balancing standardized industrial contracts with emerging artisanal specialty demand.
Transaction volume concentrates in the bakery sector. Relationship intensity and technical co-development are deepening fastest with the dairy industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's food enzymes sector concentrates specialized technical talent in Catalonia and the Basque Country, where industrial baking and precision dairy clusters anchor procurement density and supplier development resources.
Catalonia
Automated bread and pastry manufacturers in the Barcelona metropolitan area drive concentrated demand for dough-conditioning enzyme blends. AEMPS enforces EU labeling rules on enzyme carriers and active proteins. Immobilized glucose oxidase and transglutaminase reactor retrofits are compressing enzyme consumption per ton of bakery output.
Basque Country
Idiazábal and ossau-iraty PDO cheese producers anchor specialized lipase demand for flavor-accentuated artisanal products. EFSA's systematic re-evaluation of existing food enzymes threatens legacy animal-derived rennet preparations. Domestic fermentation capacity investment is accelerating to secure microbial alternative supply.
Madrid
Central Spain's meat processing corridor sustains protease procurement for tenderization and flavor precursor generation. The national food safety authority coordinates with EFSA on positive-list compliance for imported enzyme preparations. Mid-size processors are adopting direct-to-manufacturer digital procurement channels for customized protease blends.
Valencia
Citrus and fruit juice concentrators deploy cellulase systems for clarification and yield optimization. EU Green Deal bioprocessing incentives are reducing capex barriers for fermentation-based enzyme production expansion. Regional equipment suppliers are retrofitting spray-drying infrastructure for temperature-sensitive next-generation enzymes.
Andalusia
Olive oil and vegetable processing operations utilize pectinase and cellulase preparations for extraction efficiency. AEMPS inspection regimes enforce allergen management protocols distinguishing enzyme carriers from active proteins. Seville-based ingredient distributors are consolidating relationships with southern Spain's processed food manufacturers.
Spain Food Enzymes Market Competitive Landscape
Top-tier vendors anchor industrial-scale supply contracts, while regional specialists and distributor networks occupy mid-market and artisanal segments. The vendor base stratifies across integrated ingredient platforms, dedicated fermentation houses, and application-focused distributors. Three archetypes dominate: multinational biochemical conglomerates with broad enzyme portfolios, domestic biotech specialists with concentrated geographic coverage, and ingredient distributors with technical service laboratories. Competitive moves concentrate on direct technical partnerships with consolidated bakery groups and fermentation capacity expansion for microbial-derived alternatives.
Among Ireland-based integrated ingredient platforms, Kerry Group plc occupies a position exemplifying the multinational biochemical conglomerate archetype. Novozymes Group, a Danish fermentation house, represents the dedicated microbial enzyme specialist tier with industrial-scale capacity. CYGYC BIOCON S.L., a Spanish limited liability company, anchors the domestic specialist archetype with concentrated regional distribution across northern Spain. These three entities collectively illustrate the competitive structure spanning global scale, technical specialization, and local market intimacy.
| Leading Market Players |
|---|
| Kerry Group plc |
| Novozymes Group |
| Koninklijke DSM N.V. |
| Chr. Hansen Holding GmbH |
| BASF SE |
| CYGYC BIOCON S.L. |
| Novonesis AS |
| Lesaffre |
| Advanced Enzymes |
| Others |
Value Network & Pricing Analysis
EU Green Deal bioprocessing incentives gate qualified supply and premium-tier pricing access for Spanish enzyme producers, advantaging fermentation facilities with sustainability-linked financing while excluding conventional operations from high-margin clean-label contracts. AEMPS enforcement of EFSA positive-list compliance further stratifies the market, with pre-approved microbial sources commanding pricing premiums over legacy preparations awaiting reauthorization.
Pricing Analysis
Service bundling separates technical partnerships from commodity transactions in Spain's enzyme market. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA certification status and application laboratory depth. Pricing pressure stems from consolidated procurement by Catalonia's top-five bakery groups, which now specify performance metrics rather than purchasing standardized grades. Mid-size meat processors in Madrid exhibit highest price sensitivity due to direct-to-manufacturer digital procurement channels, while Basque Country PDO cheese producers show lowest sensitivity given flavor-accentuated artisanal positioning.
Supply Chain Analysis
EFSA positive-list qualification gates supply chain participation, restricting viable fermentation sources to pre-approved Aspergillus and Bacillus strains. Production concentrates in Denmark, the Netherlands, and domestic Spanish facilities in Catalonia and the Basque Country. Critical inputs draw from imported corn steep liquor and yeast extract supplies, exposing producers to Banco de España-tracked agricultural commodity inflation. Single-source vulnerability runs through foreign fermentation substrate dependencies. Distribution runs through integrated ingredient platforms for industrial accounts and specialized distributors serving artisanal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's food enzymes market operates as a stable compounder anchored by AEMPS enforcement of EU labeling rules, which perpetuates reformulation demand and sustains replacement cycles across dairy and baking sectors.
For Market Incumbents: Extend technical partnership depth with consolidated Catalan bakery groups to lock in specification-setting authority before Novonesis AS or Novozymes Group capture direct relationships. Secure backward integration into fermentation feedstock supply through long-term offtake agreements with corn steep liquor producers, mitigating Banco de España-tracked input volatility that threatens margin stability in commodity-grade segments. For New Entrants and Emerging Players: The premium-to-economy price gap in Basque Country artisanal cheese applications creates entry opportunity for lipase-based flavor enhancement specialists lacking industrial-scale capacity. Target underpenetrated idiazábal and ossau-iraty PDO producers with customized microbial rennet alternatives as EFSA reassessment forces sourcing transitions. Deploy application laboratory co-development model to bypass established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for domestic Spanish biotech specialists with concentrated northern distribution because AEMPS compliance expertise and EFSA dossier preparation capabilities constitute scarce, non-replicable assets. Acquisition focus should center on fermentation houses with approved-source microbial platforms. Watch EFSA's systematic re-evaluation timeline as inflection indicator for microbial alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | EU Green Deal financing reduces capex barriers for AEMPS-compliant facilities in northern Spain. |
| Application Laboratory Investment | Technical co-development with Catalan bakery groups displaces fragmented distributor relationships. |
| EFSA Dossier Preparation Capability | Toxicology and food safety assessment expertise accelerates new enzyme market entry timelines. |
| Immobilized Enzyme Reactor Deployment | Continuous processing retrofits in Barcelona metropolitan area compress consumption per ton output. |
| Direct-to-Manufacturer Digital Procurement | Mid-size Madrid meat processors adopt customized protease blend channels bypassing chemical wholesalers. |
Research Methodology
Direct dialogue with fermentation plant managers, enzyme procurement leads at Catalan bakery groups, AEMPS regulatory affairs specialists, and Basque Country cheese producer technical directors grounded qualitative findings. Secondary validation drew from EFSA safety dossier publications, Banco de España agricultural commodity price indices, EU customs trade data for enzyme preparations, and AEMPS enforcement bulletins. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with national consumption estimates.
Bottom-up modeling segmented volume and value across the projection horizon by enzyme type, application, source classification, and end-user concentration. The analytical framework incorporated EFSA positive-list status, AEMPS inspection intensity by region, and industrial buyer consolidation patterns as Spain-specific dimensions. CAGRs were derived from trend extrapolation of procurement volumes in Catalonia's automated baking corridor and Basque Country precision dairy clusters, cross-referenced with fermentation capacity expansion announcements.
The model assumes a particular technology adoption path for immobilized enzyme reactor retrofits; alternative pathways for batch processing optimization would alter the outlook for enzyme consumption intensity per ton of output. Forecasts reflect assumptions regarding EFSA reassessment timelines, AEMPS labeling enforcement consistency, and EU Green Deal bioprocessing incentive continuity. Deviation in EFSA's systematic re-evaluation schedule would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Granulated Tapioca Market