
 Acetylated Monoglycerides (AMG) Market | 2026-2036
Acetylated Monoglycerides (AMG) Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylated Monoglycerides (AMG) Market Analytics
Market Context with Strategic Players
Bakery and confectionery processing is pivoting toward cleaner-label emulsification, pulling acetylated monoglycerides into broader formulation portfolios. BASF SE leverages its global oleochemicals infrastructure to supply standardized AMG grades across European and Asian food corridors. Kerry Group anchors its position through integrated emulsifier-blend capabilities that bundle AMG with sister stabilizers for industrial bakeries. Palsgaard A/S differentiates through sustainability-certified supply chains that appeal to North American and Scandinavian brand owners.
Technical Definition and Structural Segments
Acetylated monoglycerides are partial esters of glycerol with fatty acids that undergo acetylation, yielding products with specific hydrophilic-lipophilic balance values typically between 3.5 and 4.5, functioning primarily as emulsifiers, stabilizers, and aerating agents in food matrices and topical preparations. Liquid AMG dominates volume throughput in industrial mayonnaise and margarine plants where pumpable delivery reduces handling costs, while powder formats command margin premiums in dry bakery premixes and pharmaceutical tablet coatings where shelf stability and dosing precision matter. Food and Beverage applications absorb the majority of output, though Cosmetics and Personal Care segments are expanding as formulators replace synthetic surfactants with acetylated monoglycerides in rinse-off and leave-on products.
Regulatory Frame and Forward-Looking Close
The U.S. FDA maintains AMG within its food additive inventory under specific conditions of use, while the EU EFSA evaluates acetylated monoglycerides within its reauthorization cycles for food emulsifiers under the EU food improvement agent framework. China's SAMR implements GB standards that govern acetylated monoglyceride specifications in domestic food manufacturing, creating compliance thresholds for imported and locally produced material alike. Stakeholders must monitor regulatory divergence across these jurisdictions, as tightening purity specifications or revised acceptable daily intake calculations would force reformulation investments and supplier qualification resets.
Market Dynamics
Acetylated monoglyceride supply chains are compressing as Chinese domestic producers scale acetylation capacity, reducing import dependency and rewiring traditional trade flows from European oleochemical hubs toward Asia-Pacific manufacturing clusters.
Growth Catalysts
- Clean-label emulsifier mandates:EFSA's ongoing reauthorization of food improvement agents is pushing European formulators toward acetylated monoglycerides with documented safety profiles, accelerating substitution of synthetic alternatives in bakery applications.
- Pharmaceutical excipient qualification:AMG's expanding use in tablet coatings and topical delivery systems is creating new volume pull from drug manufacturers seeking GRAS-status surfactants with proven biocompatibility.
- Mayonnaise and margarine automation:Liquid AMG grades integrate seamlessly with continuous-process equipment, cutting handling costs for industrial sauce producers in the United States and Southeast Asia.
Market Restraints
- Palm oil price volatility:Fatty acid feedstock costs fluctuate with Malaysian and Indonesian crude palm oil futures, compressing AMG producer margins during commodity spikes.
- Acetic anhydride supply concentration:The acetylation reagent concentrates among Chinese and North American chemical producers, creating input vulnerability for non-integrated AMG manufacturers.
- Functional equivalence of distilled monoglycerides:DMG alternatives achieve comparable emulsification in certain bakery matrices at lower unit cost, limiting AMG penetration in price-sensitive segments.
Strategic Opportunities
- Cosmetics surfactant replacement:Rinse-off and leave-on personal care formulators in South Korea and Japan are adopting acetylated monoglycerides to displace sulfate-based cleansers amid clean-beauty positioning.
- Plant-based meat texturization:Alternative protein manufacturers require aerating agents that stabilize fat-water interfaces without animal-derived inputs, opening formulation trials for AMG in extruded protein matrices.
- China's GB standard alignment:SAMR's evolving food additive specifications create first-mover advantages for suppliers achieving dual compliance with domestic and export-grade purity thresholds.
Industry Challenges
- Acetylation process engineering expertise:Qualified technicians capable of optimizing esterification degree and residual acetic acid levels remain scarce outside established oleochemical centers.
- Cross-jurisdictional dossier maintenance:Suppliers must simultaneously refresh FDA food additive petitions, EFSA reauthorization submissions, and SAMR registration files, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylated Monoglycerides (AMG) Market |
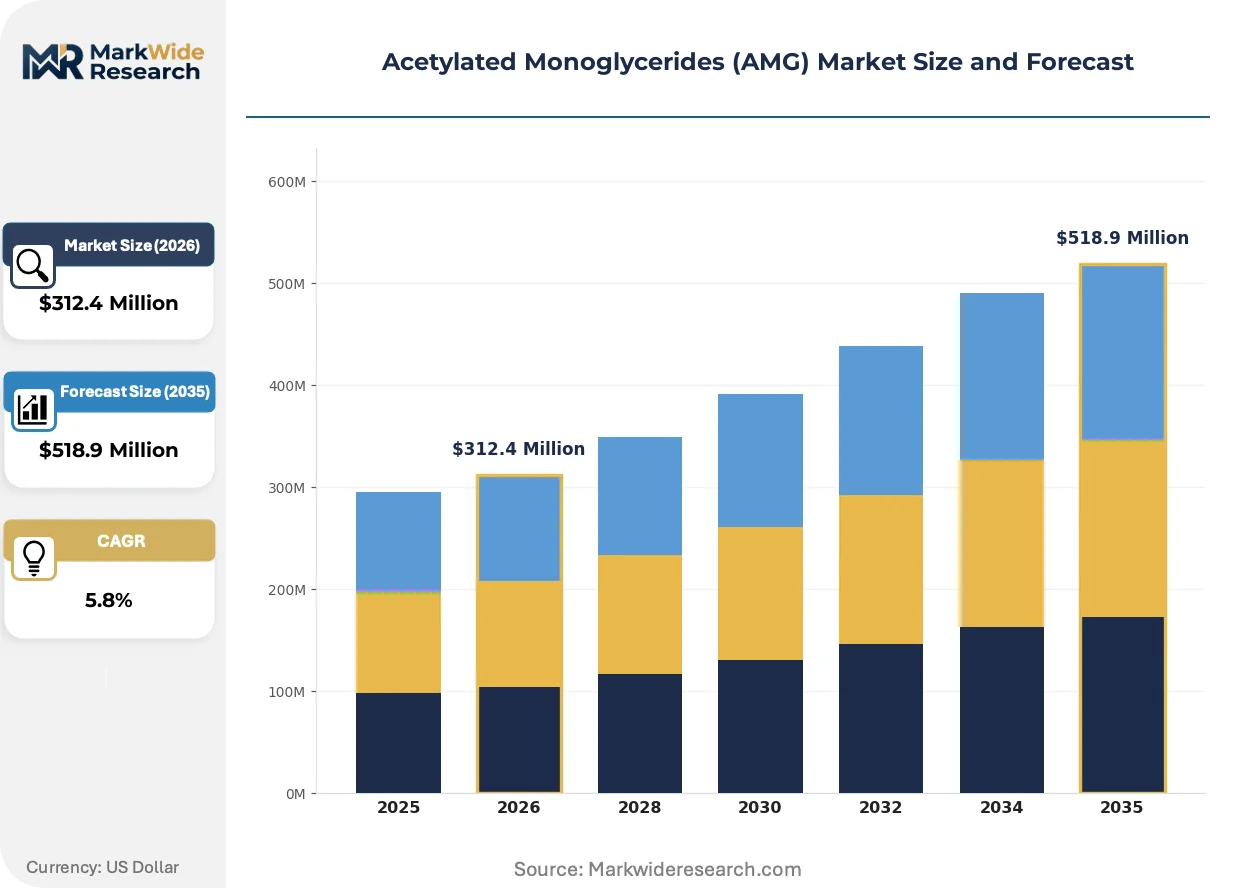
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Flake Application: Food & Beverage, Cosmetics, Pharmaceuticals, Personal Care End User: Manufacturers, Retailers, Distributors, Wholesalers Distribution Channel: Online, Offline, Direct Sales, Indirect Sales |
| Companies Covered | BASF SE, Fine Organics, Aspek Kimya, Palsgaard A/S, International Flavors & Fragrances Inc., Kerry Group, Musim Mas Group, Riken Vitamin Co., Ltd., Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylated Monoglycerides (AMG) Market Evolving Landscape
Enzymatic modification techniques and precision acetylation controls are redefining how AMG grades achieve differentiated hydrophilic-lipophilic balance values, enabling tighter performance specifications for demanding applications.
Continuous-flow acetylation reactor design is unifying temperature and residence time control across production scales. Mid-sized European oleochemical processors are retrofitting batch equipment with plug-flow modules to match the consistency of larger competitors. This technology is unifying quality variance between regional supply sources, reducing buyer qualification burdens for multinational food manufacturers.
REACH authorization timelines for acetic anhydride derivatives are tightening documentation requirements for EU-based AMG producers. The regulation forces investment in supply chain traceability systems and toxicological dossier updates. Pharmaceutical-grade AMG segments face the steepest compliance ramps as EMA cross-references ECHA substance evaluations.
Specification-driven purchasing is consolidating buyer power among industrial bakery and confectionery groups. Large manufacturers are bypassing distributor networks to contract directly with acetylated monoglyceride producers for tailored HLB grades and dedicated tanker delivery. This pattern is most pronounced in Germany and the Netherlands, where centralized procurement functions leverage volume commitments against spot-market alternatives.
Acetylated Monoglycerides (AMG) Market Segmentation
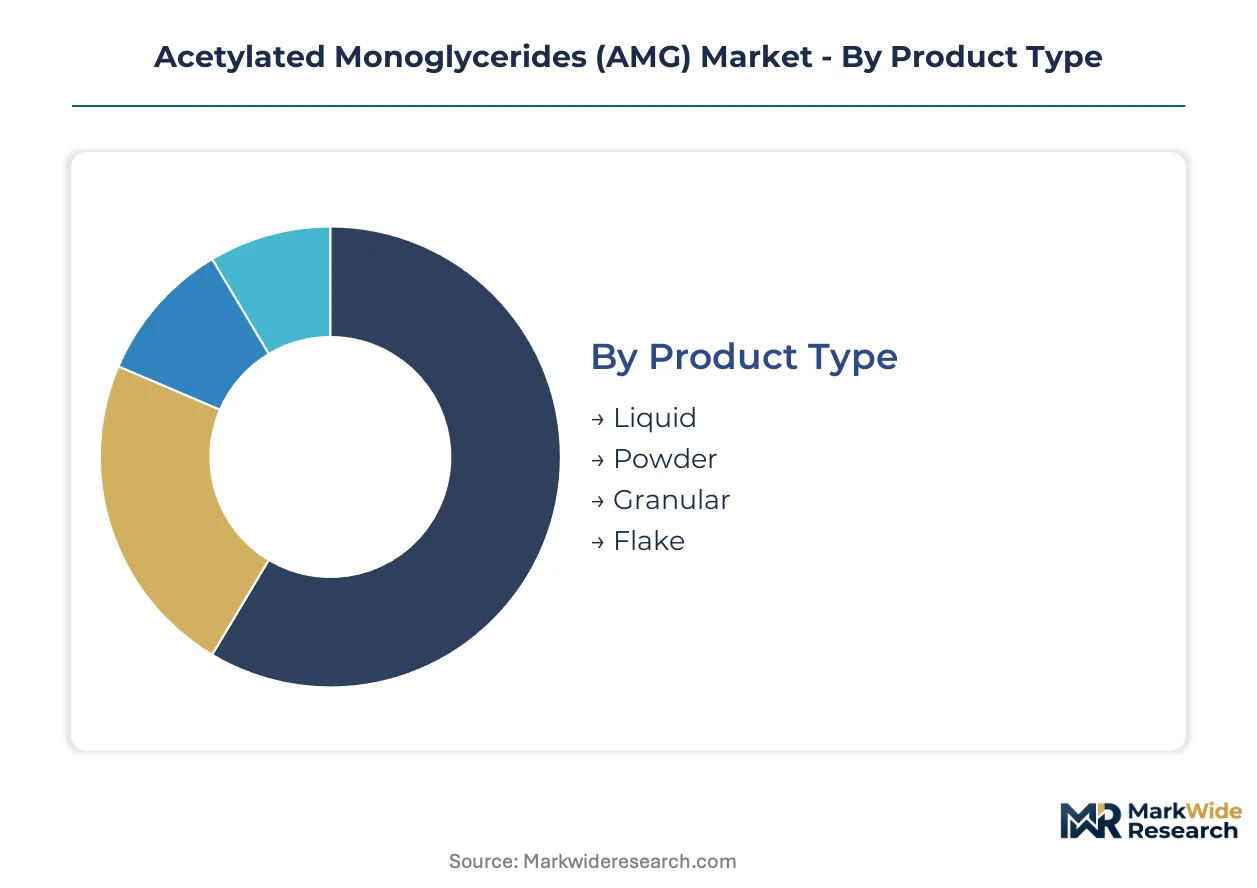
Acetylated monoglyceride procurement strategies diverge sharply across physical formats and end-use specifications, with pharmaceutical and food-grade certifications dictating supplier qualification requirements. Understanding segment-specific regulatory burdens enables buyers to optimize inventory allocation between standardized industrial grades and premium-certified variants.
Product Type:
FDA food additive petitions and EFSA reauthorization cycles impose distinct documentation requirements on liquid versus solid AMG formats, with pharmaceutical applications demanding additional USP-grade purity attestations.
- Liquid:Pumpable AMG grades with HLB values near 4.0 dominate industrial mayonnaise and margarine automation lines in Germany and the United States. Continuous-process equipment integration cuts handling costs for Southeast Asian sauce producers seeking seamless flow properties.
- Powder:Spray-dried AMG with sub-5% moisture content commands formulation precision in dry bakery premixes and pharmaceutical tablet coatings. Shelf stability requirements from Japan's PMDA and China's NMPA drive micronization standards for excipient-grade material.
- Granular:Intermediate particle size suits intermediate processing stages where dust control matters but full dissolution speed is secondary.
- Flake:Compressed AMG formats serve specialized confectionery tempering applications requiring controlled melt profiles.
Liquid sits at the top of the volume ranking, with Powder climbing the fastest.
Application:
Cost tier stratification separates commodity food emulsification from high-margin pharmaceutical excipient supply, with cosmetics surfactant replacement emerging as a mid-tier growth corridor.
- Food & Beverage:Bakery and confectionery formulators in the Netherlands and China specify acetylated monoglycerides for clean-label emulsification under tightening EFSA and SAMR frameworks. Distilled monoglyceride competition constrains AMG penetration in price-sensitive bread improver segments.
- Cosmetics:South Korean and Japanese rinse-off formulators adopt AMG to displace sulfate-based cleansers, with METI cosmetic safety standards governing surfactant substitution protocols.
- Pharmaceuticals:GRAS-status tablet coatings and topical delivery systems create volume pull from drug manufacturers seeking EMA-cross-referenced biocompatibility documentation.
- Personal Care:Leave-on applications demand lower residual acetic acid specifications than food-grade material, narrowing qualified supplier pools.
Food & Beverage captures the dominant value share, though Cosmetics is expanding most quickly amid clean-beauty positioning.
End User:
Customer type determines contract structure, with manufacturers seeking dedicated tanker delivery and long-term HLB customization while intermediaries prioritize spot-market flexibility.
- Manufacturers:Industrial bakery groups in Germany and centralized confectionery processors in China contract directly with oleochemical producers for tailored grades. Specification-driven purchasing consolidates buyer power among multinationals bypassing distributor networks.
- Retailers:Private-label food brands source AMG through qualified co-manufacturers rather than direct chemical procurement.
- Distributors:Regional chemical traders manage inventory buffers for mid-sized processors lacking tank storage infrastructure.
- Wholesalers:Bulk commodity handlers aggregate spot demand from price-sensitive segments where distilled monoglyceride substitution remains viable.
Manufacturers anchor procurement volume, with Distributors gaining relevance as Chinese domestic capacity reduces import dependency.
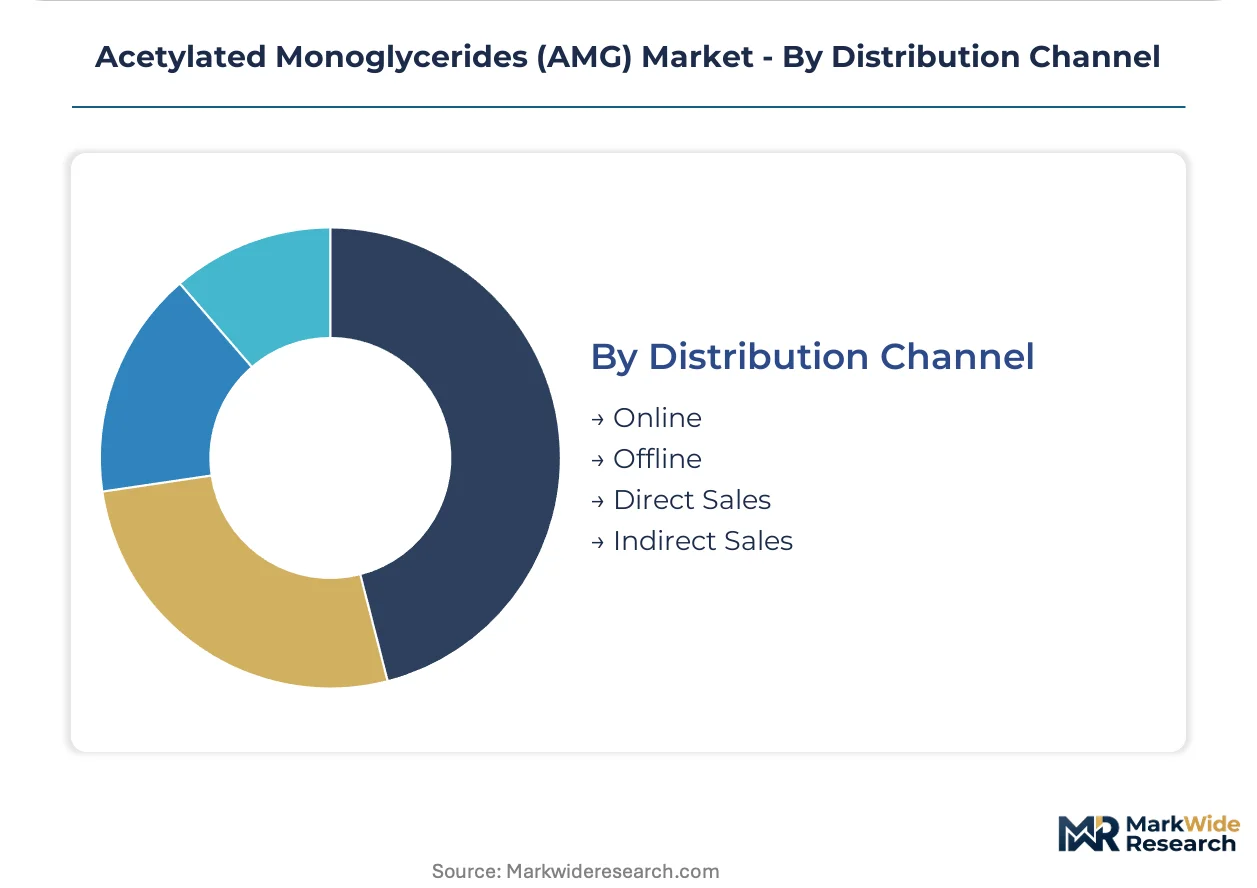
Distribution Channel:
Supply chain configuration separates bulk industrial flows from specialized pharmaceutical logistics, with direct relationships dominating high-certification segments.
- Online:Digital procurement platforms serve small-batch cosmetics formulators and research-scale pharmaceutical developers seeking rapid sample qualification.
- Offline:Traditional chemical distribution maintains dominance for tanker-scale food industry deliveries with established logistics protocols.
- Direct Sales:BASF SE and Kerry Group deploy technical sales teams for multinational bakery accounts requiring collaborative formulation development.
- Indirect Sales:Agent networks penetrate fragmented Asian food processing clusters where local relationship depth outweighs global supplier presence.
Direct Sales commands the steepest margin tier, with Online channels gaining traction among specialty cosmetics startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting acetylated monoglyceride production toward jurisdictions with streamlined food additive approval pathways, compressing lead times for new capacity deployment and reshaping traditional supply hierarchies.
China
Domestic food processing scale-up and local acetylation capacity expansion are displacing European imports. SAMR's GB standards govern additive specifications, creating compliance thresholds for both local and imported material. The Yangtze River Delta clusters around Shanghai and Jiangsu province concentrate new oleochemical investments as producers target bakery and confectionery formulators.
United States
Industrial mayonnaise and margarine automation lines drive liquid AMG consumption. FDA food additive inventory requirements shape permissible applications and labeling protocols. Midwest manufacturing corridors in Illinois and Ohio host centralized procurement functions for multinational bakery groups seeking dedicated tanker delivery contracts.
Germany
EFSA reauthorization cycles for food improvement agents accelerate substitution of synthetic emulsifiers. REACH authorization timelines for acetic anhydride derivatives tighten documentation requirements. The North Rhine-Westphalia chemical belt around Düsseldorf and Cologne anchors European oleochemical processing and technical sales infrastructure.
Japan
Cosmetics formulators adopt acetylated monoglycerides to displace sulfate-based surfactants under clean-beauty positioning. METI cosmetic safety standards govern rinse-off product substitution protocols. The Kansai region around Osaka concentrates personal care manufacturing trials for excipient-grade material with sub-5% moisture specifications.
South Korea
Pharmaceutical tablet coating applications create demand for GRAS-status surfactants with proven biocompatibility. MFDS pharmaceutical regulations cross-reference EMA substance evaluations for excipient qualification. Seoul Capital Area drug manufacturers source micronized AMG grades for topical delivery system development.
Acetylated Monoglycerides (AMG) Market Competitive Landscape
Capacity expansion dominates the current landscape as Chinese domestic producers scale acetylation infrastructure and European incumbents retrofit batch equipment with continuous-flow modules. The vendor base splits between integrated oleochemical majors with captive fatty acid supply and specialized emulsifier blenders serving formulation-heavy segments. Three archetypes define positioning: scale-driven feedstock-integrated producers, formulation-technical specialists, and sustainability-certified niche suppliers. Geographic expansion and portfolio diversification represent the primary competitive vectors as participants chase dual compliance with Chinese GB standards and Western pharmaceutical-grade certifications.
Within the integrated oleochemical tier, BASF SE and Kerry Group exemplify divergent approaches to market access. BASF SE leverages standardized grade supply across European and Asian corridors, while Kerry Group anchors positioning through bundled emulsifier-stabilizer combinations for industrial bakeries. Palsgaard A/S occupies a sustainability-certified niche that appeals to North American and Scandinavian brand owners seeking supply chain transparency documentation.
| Leading Market Players |
|---|
| BASF SE |
| Fine Organics |
| Aspek Kimya |
| Palsgaard A/S |
| International Flavors & Fragrances Inc. |
| Kerry Group |
| Musim Mas Group |
| Riken Vitamin Co., Ltd. |
| Dow |
| Others |
Value Network & Pricing Analysis
EFSA's ongoing reauthorization of food improvement agents gates qualified supply for European bakery formulators and anchors premium-tier pricing access for documented safety profiles, while SAMR's evolving GB standards create parallel compliance thresholds that segment Chinese domestic from export-grade material valuations.
Pricing Analysis
Distributor margins in liquid AMG grades absorb 12-18 percentage points before reaching industrial mayonnaise and margarine automation lines, while direct-to-OEM contracts for pharmaceutical-grade powder command steeper premiums based on USP certification and sub-5% moisture specifications. Three-tier pricing structure across premium, standard, and economy levels separates excipient-grade micronized material from food-grade liquid and commodity flake formats. Cost compression in standard food-grade tiers is intensifying because distilled monoglyceride alternatives achieve comparable emulsification at lower unit cost in price-sensitive bread improver segments. Wholesale buyers in Southeast Asian sauce production exhibit highest price sensitivity, whereas pharmaceutical tablet coating specialists demonstrate lowest sensitivity due to biocompatibility documentation requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Dutch industrial bakery groups, while distributor networks manage inventory buffers for mid-sized processors lacking tank storage infrastructure. Geographic concentration centers on China, Germany, and Malaysia, with Yangtze River Delta clusters scaling acetylation capacity fastest. Raw material dependencies rest on Malaysian and Indonesian crude palm oil for fatty acid feedstock, plus Chinese and North American acetic anhydride for the acetylation reagent. Single-source vulnerability in acetic anhydride supply concentrates input risk for non-integrated AMG manufacturers. Distribution runs through tanker-scale logistics for liquid grades and specialized pharmaceutical cold chains for excipient-grade powder.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EFSA's reauthorization cycles for food improvement agents driving sustained substitution demand from synthetic emulsifiers toward documented safety-profile alternatives.
For Market Incumbents: Extend certification breadth to capture dual-compliant positioning across SAMR GB standards and EMA-cross-referenced pharmaceutical documentation, while adding continuous-flow acetylation capacity in Jiangsu province to match Chinese domestic scale. Distilled monoglyceride price competition threatens margin position in commodity bread improver segments; defend through backward integration into fatty acid supply and dedicated tanker delivery contracts with centralized procurement functions at multinational bakery groups. For New Entrants and Emerging Players: The premium-economy price-point gap in pharmaceutical-grade AMG creates entry space for specialized micronization capabilities serving Seoul Capital Area drug manufacturers and Kansai region cosmetics formulators. Target cosmetics surfactant replacement in South Korea and Japan where METI cosmetic safety standards govern rinse-off product substitution protocols. Pursue qualification partnerships with established oleochemical distributors to bypass direct regulatory dossier maintenance burdens. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized European oleochemical processors retrofitting batch equipment with plug-flow modules, offering technology-transfer potential to Chinese domestic capacity buildouts. Long-term viability hinges on regulatory affairs capacity to simultaneously refresh FDA food additive petitions, EFSA reauthorization submissions, and SAMR registration files. Monitor ECHA substance evaluations cross-referenced by EMA as the inflection signal for pharmaceutical-grade compliance ramp steepness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Supply | Captive palm oil sourcing from Malaysian and Indonesian estates insulates margin volatility from commodity futures spikes. |
| Continuous-Flow Reactor Retrofit | Plug-flow modules unify temperature control across European batch equipment to match Chinese competitor consistency. |
| Dual Compliance Certification Investment | Simultaneous SAMR GB standard and USP-grade qualification opens pharmaceutical excipient premium tiers. |
| Direct Tanker Delivery Contracts | Long-term HLB customization agreements with German and Dutch centralized procurement functions bypass distributor markups. |
| Cosmetics Surfactant Partnership | Collaborative formulation development with South Korean rinse-off manufacturers accelerates sulfate displacement under METI protocols. |
Research Methodology
Coverage spans China, Germany, the United States, Japan, and South Korea, with primary inputs from each market combining interviews with oleochemical plant managers, procurement leads at industrial bakery groups, pharmaceutical regulatory affairs directors, cosmetics formulators, and distribution channel partners. Secondary validation draws from SAMR GB standard filings, EFSA food improvement agent reauthorization dossiers, FDA food additive petitions, customs and trade flow data, and SEC filings from listed oleochemical majors. Bottom-up volume estimates triangulate against top-down market sizing across physical formats and end-use applications.
Granularity-level modeling disaggregates volume and value across liquid, powder, granular, and flake formats; food and beverage, cosmetics, pharmaceutical, and personal care applications; and manufacturer, distributor, and direct sales channels. CAGRs derive from segment-specific growth drivers including clean-label emulsifier substitution rates, pharmaceutical excipient qualification timelines, and cosmetics surfactant displacement velocity. Industry-specific forecast inputs incorporate palm oil futures correlation coefficients and acetic anhydride supply concentration indices.
The model assumes a particular technology adoption path for enzymatic modification techniques; alternative pathways for precision acetylation control would alter the outlook for differentiated HLB grade availability. Forecasts reflect assumptions regarding EFSA reauthorization timing, SAMR GB standard evolution, and REACH authorization timelines for acetic anhydride derivatives, with palm oil price volatility and regulatory divergence representing primary revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market