
 Spain Food Acidulants Market | 2026-2036
Spain Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Acidulants Market Analytics
Food-grade acidulant specifications is unwinding legacy commodity dynamics across Spanish ingredient procurement. Tate & Lyle PLC leverages its European sweetener and acidulant integration to sustain supply security for Iberian beverage clients. Cargill Incorporated anchors its position through deep corn-derived citric acid fermentation infrastructure. Jungbunzlauer AG differentiates via biobased lactic acid platforms that compete on clean-label positioning.
Food acidulants comprise organic acids—citric, lactic, malic, and tartaric—typically produced through fermentation or chemical synthesis, functioning to lower pH, enhance flavor profiles, extend shelf stability, and control microbial activity in processed foods and beverages. Citric acid dominates volume flows given its versatility across beverages and confectionery, while lactic acid captures margin expansion from dairy and clean-label bakery applications. Tartaric acid maintains niche strength in wine-derived applications and specialized confectionery, with malic acid gaining traction in sour candy and functional drink formulations.
AESAN enforces EU-wide purity standards for food additives under Regulation 1333/2008, while BSI Group certification and ISO 22000 frameworks shape supplier qualification protocols for Spanish manufacturers. FSSAI-aligned import checks on non-EU acidulant shipments tighten traceability requirements for Spanish distributors sourcing from Asian fermentation hubs. Stakeholders must monitor evolving EU Green Deal pressures on fermentation carbon intensity and decide whether to invest in domestic biorefinery capacity or deepen reliance on imported feedstock streams.
Market Dynamics
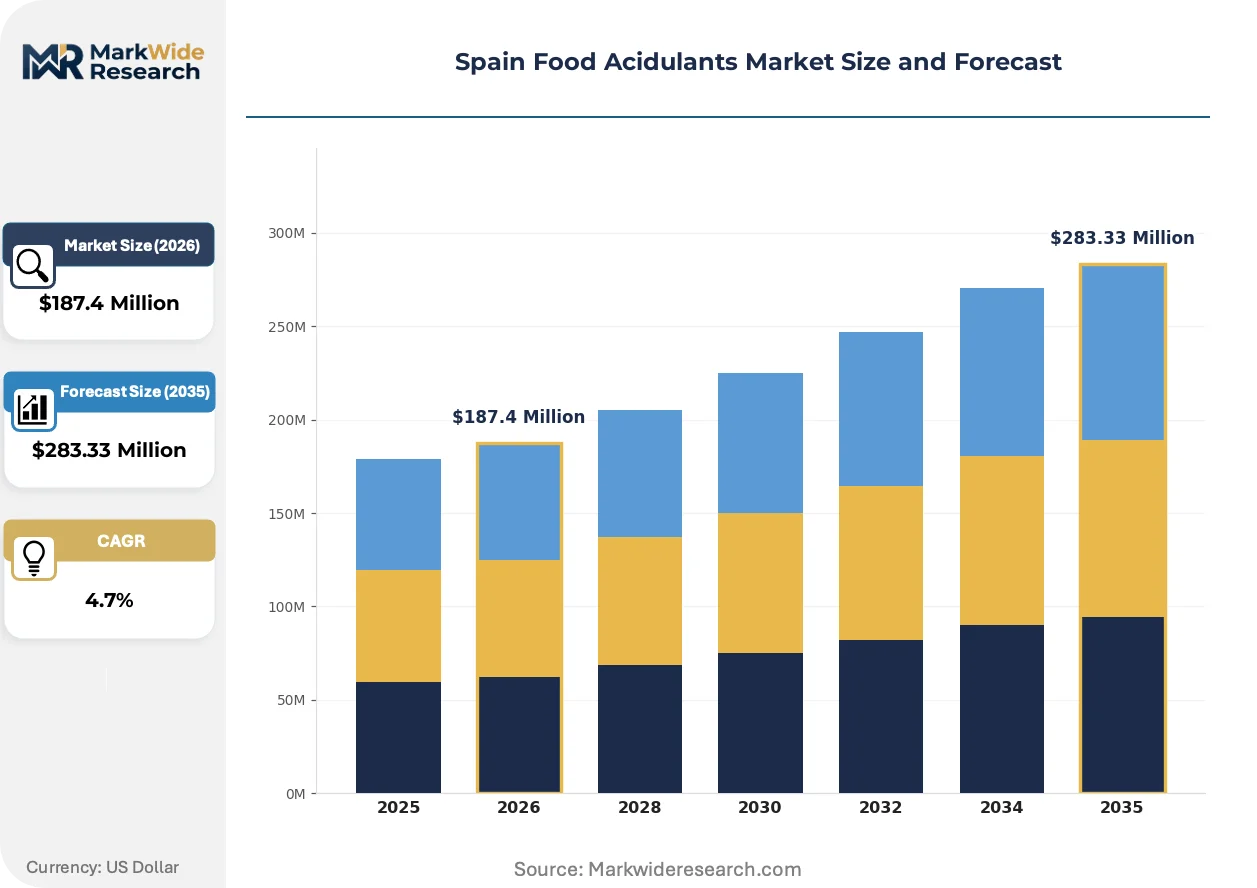
Spain's food acidulant sector is compressing around fermentation carbon intensity benchmarks mandated by the EU Green Deal, forcing processors to requalify supply chains or absorb compliance premiums that reshape procurement economics.
Growth Catalysts
- Functional beverage expansion:Spanish bottlers in Catalonia are expanding acidulant volumes for pH-stabilized sports and probiotic drinks, tightening specification tolerances.
- Regulation 1333/2008 alignment:AESAN's enforcement of EU-wide purity standards is disqualifying non-compliant imports, consolidating qualified supplier pools.
- Clean-label bakery migration:Lactic acid is displacing synthetic preservatives in Madrid and Barcelona artisan bread manufacturing.
Market Restraints
- Corn feedstock volatility:Cargill's citric acid fermentation depends on Ukrainian and Brazilian corn flows, exposing Spanish buyers to input cost swings.
- Asian supply concentration:Non-EU fermentation hubs in China dominate tartaric acid precursor chemicals, creating single-source vulnerability for Spanish distributors.
- Technical purity ceilings:AESAN's tightening heavy metal thresholds for wine-derived tartaric acid are rejecting legacy extraction batches.
Strategic Opportunities
- Andalusian biorefinery gap:Underpenetrated southern Spain lacks domestic lactic acid fermentation capacity, creating greenfield entry points.
- CSRD-aligned carbon accounting:Spanish acidulant suppliers can capture premium positioning by quantifying fermentation emissions for EU corporate buyers.
- Direct-to-brewery channels:Malic acid producers are bypassing distributors to contract directly with Basque cider houses and Galician wineries.
Industry Challenges
- Fermentation engineering talent scarcity:Spain's technical universities produce insufficient metabolic engineering graduates for biobased acidulant scale-up.
- ISO 22000 certification lag:Small Valencia citrus processors face 14-month audit timelines that freeze export eligibility.
- Legacy ERP integration friction:AESAN's traceability mandates require barcode-lot tracking that crashes older inventory systems at family-owned acidulant blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Acidulants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Tartaric Acid Application: Bakery, Beverages, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Producers, Restaurants, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Prayon S.A., Merck KGaA, Tate & Lyle PLC, Cargill Incorporated, ParaChem Chemicals L.P., Archer Daniels Midland Company, Jungbunzlauer AG, BRENNTAG SE, Corbion N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Acidulants Market Evolving Landscape
Fermentation-derived acidulant production is splitting between carbon-intensive legacy methods and precision bioprocessing, while regulatory pressure and buyer behavior shifts compress traditional supply arrangements.
Precision fermentation for lactic acid is bifurcating Spanish supplier tiers. Jungbunzlauer's biobased platforms capture clean-label premiums from Barcelona beverage formulators. Legacy chemical synthesis operations in Tarragona face margin compression as buyers demand batch-level carbon certificates. The technology is bifurcating procurement into certified-low-carbon and commodity-grade acidulant streams with diverging pricing power.
EU Green Deal carbon border adjustments are tightening documentation requirements for imported citric acid. Spanish distributors must now verify fermentation electricity sources for Asian-origin shipments. Basque food manufacturers are accelerating domestic supplier qualification to preempt customs delays at Bilbao and Barcelona ports.
Acidulant buyers are consolidating procurement around fewer qualified suppliers with integrated certification. Madrid-based confectionery groups are replacing spot-market purchasing with annual framework contracts tied to ISO 22000 and BSI Group audit scores. This concentration is visible in Catalonia's processed food cluster, where three large acidulant suppliers now capture expanded volume commitments from previously fragmented buyer bases.
Spain Food Acidulants Market Segmentation
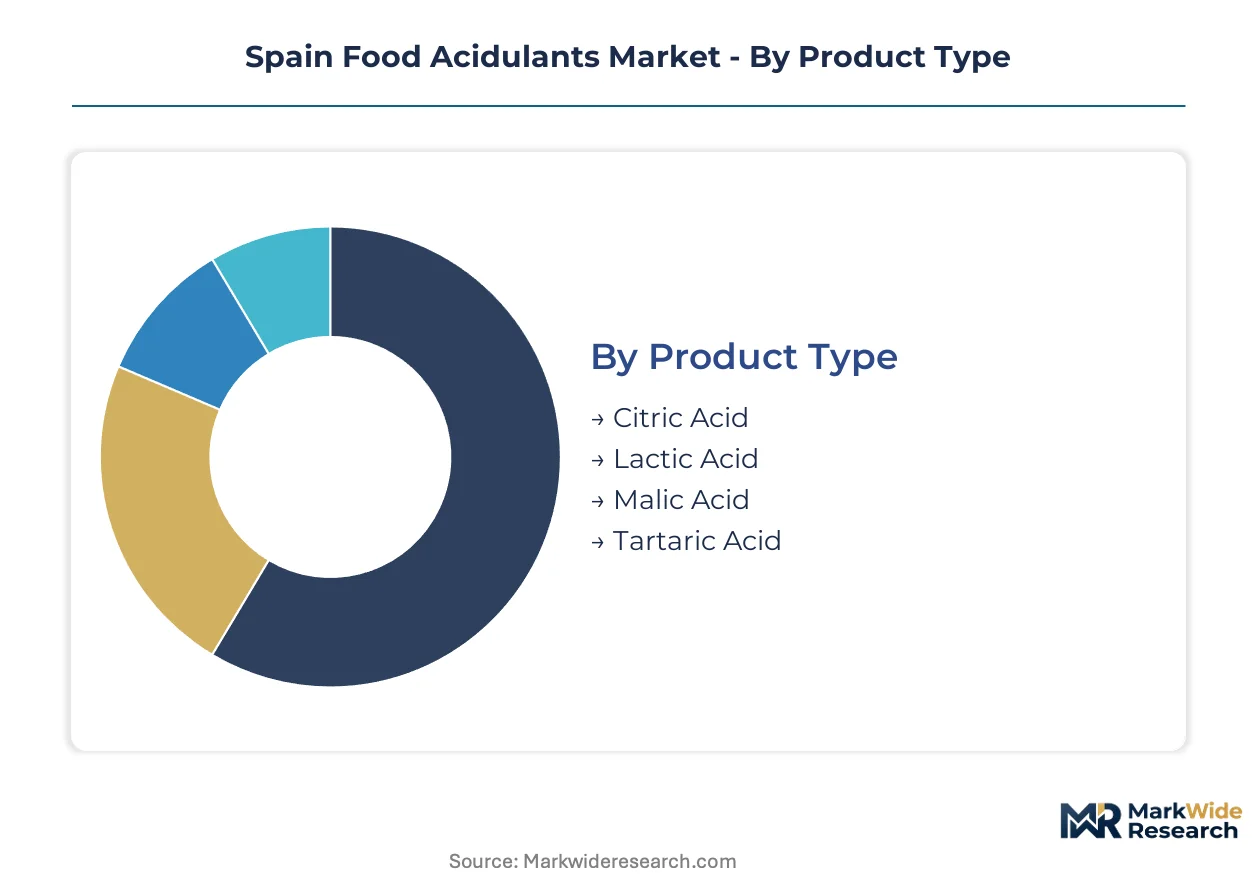
Acidulant procurement in Spain fragments across technical specifications, end-use requirements, and channel economics. AESAN's purity enforcement under Regulation 1333/2008 creates tiered compliance burdens that reshape how each segment competes for volume.
Product Type:
Regulatory differentiation separates fermentation-derived organic acids by carbon intensity documentation and heavy metal thresholds mandated for EU market access.
- Citric Acid:Produced primarily through Aspergillus niger fermentation of corn-derived glucose, this acid dominates pH adjustment in Spanish beverage manufacturing. Catalonia's concentrated bottling corridor around Barcelona absorbs the highest volumes, though corn feedstock volatility from Ukrainian and Brazilian supply corridors injects cost instability into procurement contracts.
- Lactic Acid:Biobased production platforms capture clean-label positioning in Madrid and Barcelona artisan bakeries displacing synthetic preservatives. Jungbunzlauer's fermentation infrastructure supplies Iberian dairy processors seeking batch-level carbon certificates for EU corporate sustainability reporting.
- Malic Acid:Synthetic and fermentation routes supply sour candy manufacturers and functional drink formulators in Basque Country.
- Tartaric Acid:Wine-derived extraction from La Rioja and Penedès grape processing sustains niche confectionery and oenological applications.
Citric acid handles the majority of throughput; lactic acid is expanding most quickly on share.
Application:
Cost tier stratification separates commodity-scale acidulant buyers from specification-intensive premium formulators.
- Beverages:pH stabilization and flavor enhancement drive the largest acidulant absorption in Spain. Sports and probiotic drink expansion in Catalonia tightens specification tolerances, with AESAN's additive enforcement consolidating procurement around qualified suppliers with integrated ISO 22000 certification.
- Confectionery:Sour candy manufacturing and gummy production in Valencia and Madrid demand precise acidulant blends for controlled release profiles. Clean-label migration pressures synthetic acid replacement with fermentation-derived alternatives.
- Bakery:Artisan bread producers in Madrid adopt lactic acid for mold inhibition without chemical preservative labeling.
- Dairy Products:Yogurt and fresh cheese applications in Galicia leverage acidulants for texture control and shelf extension.
Beverages command the steepest volume concentration; confectionery shows the strongest margin expansion trajectory.
End User:
Customer type determines contract structure, with large manufacturers demanding annual framework agreements while fragmented foodservice operates on spot purchasing.
- Food Manufacturers:Processed food conglomerates in Catalonia's industrial cluster around Barcelona negotiate multi-year acidulant supply contracts tied to BSI Group audit scores. AESAN traceability mandates force barcode-lot tracking integration that disadvantages smaller blenders with legacy ERP systems.
- Beverage Producers:Bottlers from multinational operations to regional mineral water brands specify acidulant grades by application, with functional drink lines requiring carbon-certified fermentation sources.
- Restaurants:High-volume kitchen operations in Madrid and Barcelona procure acidulant blends through distributor networks for sauce and marinade preparation.
- Catering Services:Institutional foodservice contracts with Spanish public sector and corporate dining demand cost-optimized acidulant solutions with basic purity compliance.
Food manufacturers anchor procurement volume; beverage producers are climbing fastest on specification intensity.
Distribution Channel:
Supply concentration in coastal logistics hubs shapes channel economics, with direct sales capturing premium accounts while retail intermediaries serve fragmented demand.
- Direct Sales:Large acidulant producers bypass distributor margins to contract directly with Basque cider houses, Galician wineries, and Catalonia's beverage conglomerates. Malic acid suppliers particularly favor this channel for specialized oenological applications requiring technical consultation.
- Supermarkets:Retail acidulant packaging for home bakers and small commercial kitchens concentrates in Carrefour, Mercadona, and Eroski private-label programs.
- Specialty Stores:Professional ingredient suppliers in Barcelona and Madrid serve artisan food producers demanding technical-grade acidulants with certification documentation.
- Online Retail:E-commerce penetration for acidulant procurement remains limited to specialty grades and small-format packaging, constrained by hazardous material shipping regulations.
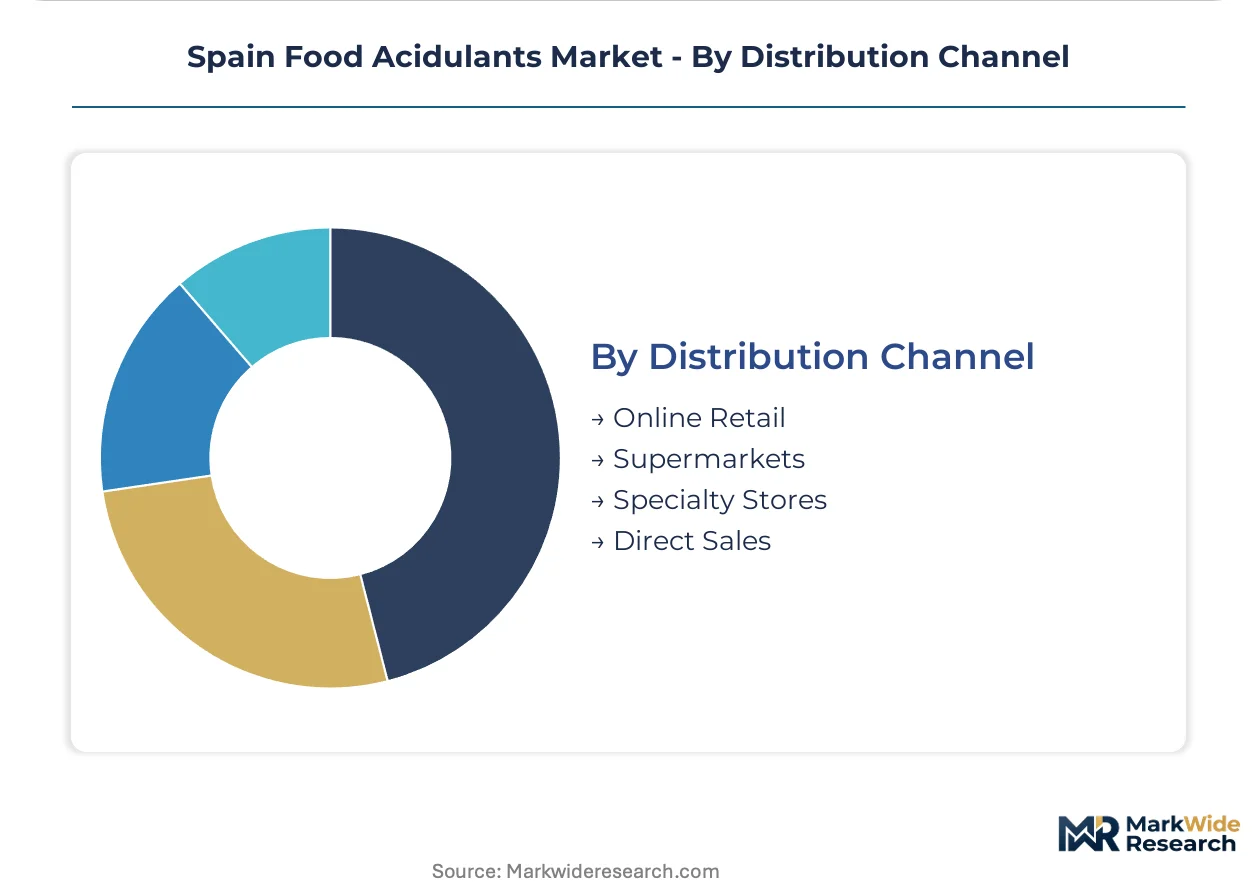
Direct sales capture the dominant share of industrial volume; specialty stores are gaining fastest on clean-label grade distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Spanish sub-regions. Catalonia's beverage conglomerates absorb specification premiums for carbon-certified acidulants, while Andalusian food manufacturers prioritize feedstock cost stability over certification tiers.
Catalonia
Barcelona's concentrated bottling corridor drives the steepest acidulant throughput in Spain. AESAN's additive enforcement under Regulation 1333/2008 consolidates procurement around ISO 22000-certified suppliers. The Penedès wine region sustains tartaric acid extraction for specialized confectionery applications.
Madrid
Artisan bakery migration toward clean-label preservatives accelerates lactic acid absorption in the capital's food manufacturing belt. Spain's national food safety agency tightens heavy metal thresholds for acidulant imports. The Madrid-Barcelona logistics axis anchors distribution infrastructure for peninsular supply.
Basque Country
Regional cider houses and mineral water bottlers specify malic acid grades for pH-stabilized formulations. EU Green Deal carbon border documentation requirements delay non-EU shipment clearances at Bilbao port. Direct supplier contracting bypasses distributor margins for oenological acidulant procurement.
Andalusia
Underpenetrated fermentation capacity creates greenfield entry opportunities for domestic lactic acid production. Spanish alignment with EU corporate sustainability reporting directives pressures southern food manufacturers to verify supply chain emissions. Seville's citrus processing infrastructure supports citric acid precursor availability.
Valencia
Confectionery manufacturers in the Levante region demand precise acidulant blends for controlled-release sour candy profiles. AESAN traceability mandates force 14-month ISO 22000 audit timelines that freeze smaller citrus processors from export eligibility. Legacy ERP systems at family-owned blenders crash under barcode-lot tracking requirements.
Spain Food Acidulants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Spain's acidulant procurement tiers. Fermentation carbon intensity capabilities separate premium-positioned suppliers from commodity-grade volume players. Three archetypes dominate: integrated European sweetener-acidulant platforms, deep corn-fermentation infrastructure operators, and biobased clean-label specialists. Competitive moves concentrate on backward integration into feedstock supply and CSRD-aligned carbon accounting certification.
Within the integrated European tier, Tate & Lyle PLC and Cargill Incorporated anchor supply security for Iberian beverage clients through continental production networks. Jungbunzlauer AG occupies the biobased specialization vector, exemplifying clean-label positioning that captures premium procurement from Barcelona formulators. These three entities represent the dominant competitive anchors shaping qualification protocols and contract structures across Catalonia's processed food cluster.
| Leading Market Players |
|---|
| Prayon S.A. |
| Merck KGaA |
| Tate & Lyle PLC |
| Cargill Incorporated |
| ParaChem Chemicals L.P. |
| Archer Daniels Midland Company |
| Jungbunzlauer AG |
| BRENNTAG SE |
| Corbion N.V. |
| Others |
Value Network & Pricing Analysis
Lactic acid displacement of synthetic preservatives in Madrid and Barcelona artisan bakeries simultaneously redraws procurement geography toward biobased fermentation hubs and compresses pricing premiums for carbon-certified grades. This substitution dynamic forces Spanish buyers to requalify supplier tiers around AESAN purity enforcement and EU Green Deal documentation requirements.
Pricing Analysis
After-sales technical service and carbon certificate bundling drive lifetime value for acidulant suppliers serving Catalonia's beverage conglomerates. Three-tier pricing structure across fermentation-carbon-certified, ISO 22000-compliant, and commodity-grade tiers separates qualified suppliers from spot-market blenders. Cost compression in commodity citric acid is intensifying because Ukrainian and Brazilian corn feedstock volatility injects margin uncertainty into Cargill's fermentation economics. Small Valencia citrus processors exhibit the steepest price sensitivity due to 14-month ISO 22000 audit timelines that freeze export eligibility, while Barcelona functional drink bottlers absorb specification premiums for batch-level traceability.
Supply Chain Analysis
Inventory lead times for tartaric acid precursors extend disproportionately because Chinese chemical synthesis hubs dominate precursor flows to Spanish distributors. Fermentation capacity concentrates in Germany, Austria, and Belgium for European-sourced lactic acid, while citric acid production draws from Chinese and Thai corn-fermentation infrastructure. Raw material dependencies center on Ukrainian and Brazilian corn glucose, La Rioja grape processing residues, and Asian-derived malic acid precursors. Single-source vulnerability for tartaric acid precursors creates structural risk exposure. Distribution runs through Bilbao and Barcelona port logistics corridors with direct sales bypassing distributor margins for Basque cider houses and Galician wineries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
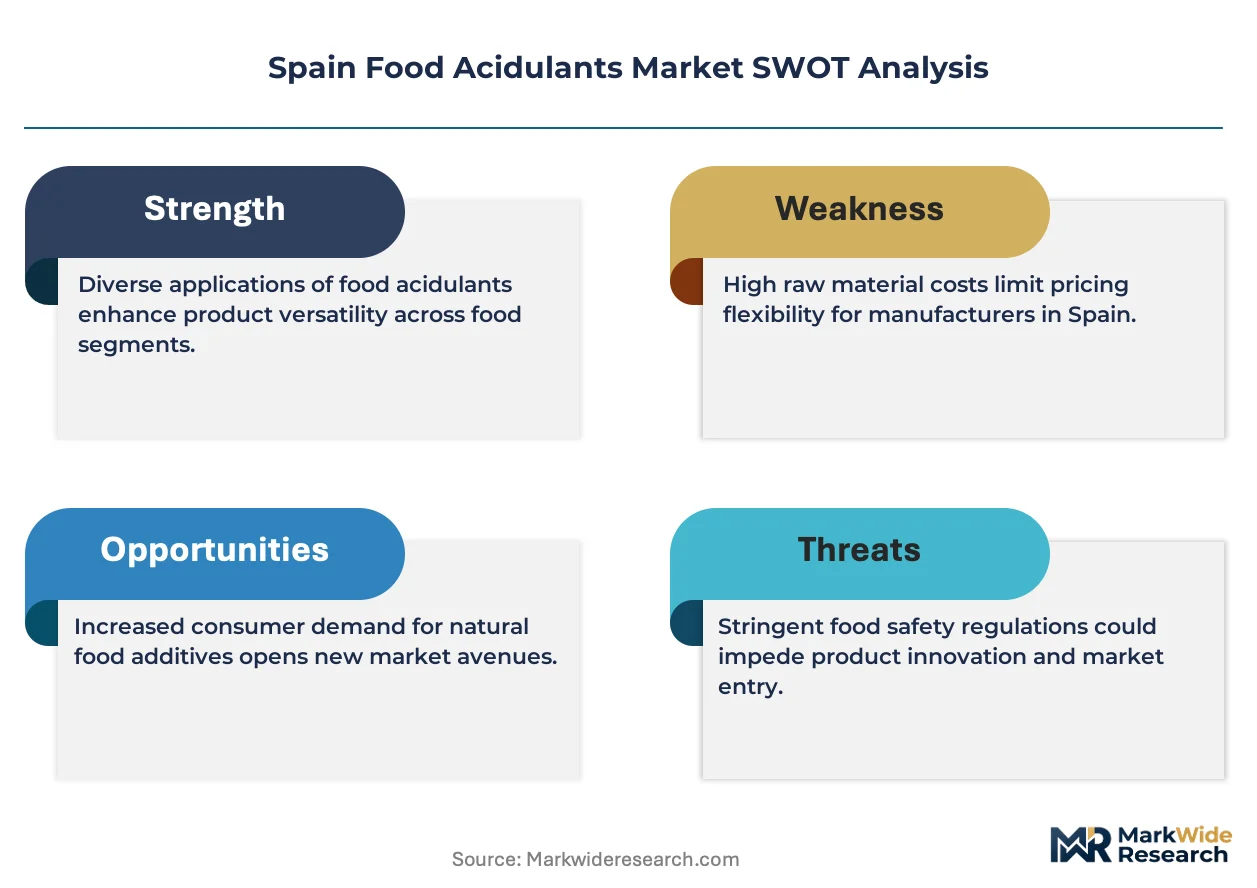
Fragmentation opportunity concentrates in southern Spain where Andalusian food manufacturers lack domestic lactic acid fermentation capacity, and clean-label bakery migration in Madrid creates specification-grade niches underserved by commodity suppliers.
For Market Incumbents: Fortify backward integration into corn feedstock supply chains to buffer Cargill-style exposure to Ukrainian and Brazilian input cost swings. Capture CSRD-aligned carbon accounting certification to preempt EU Green Deal border adjustment documentation requirements that disqualify non-compliant imports. Consolidate procurement relationships with Catalonia's beverage conglomerates through multi-year framework contracts tied to BSI Group audit scores. For New Entrants and Emerging Players: Anchor in Andalusia's underpenetrated fermentation capacity gap for greenfield lactic acid production serving southern Spanish food manufacturers. Target direct-to-brewery malic acid contracting with Basque cider houses and Galician wineries as the most penetrable channel bypassing established distributor networks. Pursue biobased platform differentiation to capture clean-label premiums from Barcelona artisan formulators. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-carbon-certified specialists with integrated EU regulatory compliance infrastructure. Long-term viability over the next decade hinges on domestic biorefinery capacity expansion rather than deepening reliance on Asian import streams. Acquisition target archetype: mid-scale Spanish acidulant blenders with legacy ERP systems requiring barcode-lot tracking upgrades for AESAN traceability mandates. Watch for EU Green Deal carbon border adjustment enforcement intensity as the inflection signal distinguishing qualified suppliers from disqualified commodity flows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill's corn-fermentation infrastructure anchors citric acid cost stability for Iberian beverage clients. |
| CSRD-Aligned Carbon Certification | Jungbunzlauer's biobased lactic acid platforms capture premium positioning from Barcelona clean-label formulators. |
| Direct-to-Brewery Channel Development | Malic acid suppliers bypass distributor margins to contract with Basque cider houses requiring technical consultation. |
| Andalusian Biorefinery Capacity Buildout | Greenfield lactic acid fermentation addresses southern Spain's supply gap for EU corporate sustainability reporting compliance. |
| ISO 22000 Certification Investment | Fourteen-month audit timelines at Valencia citrus processors freeze export eligibility without upgraded quality systems. |
Research Methodology
A spread of perspectives from fermentation plant managers, procurement leads at Catalonia beverage conglomerates, AESAN regulatory affairs specialists, and distribution channel partners converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from EU customs trade data, AESAN additive enforcement records, SEC filings of listed acidulant producers, and Corbion fermentation technology disclosures. Bottom-up volume modeling across product grades and top-down macroeconomic triangulation anchored the analytical framework.
Segmentation dimensions modeled span acidulant type, application intensity across beverages and bakery, end-user contract structure, and distribution channel economics. CAGRs were derived through growth rate convergence across the projection horizon, incorporating fermentation capacity expansion timelines and EU Green Deal compliance cost pass-through assumptions. Industry-specific forecast inputs include corn feedstock price volatility corridors and AESAN heavy metal threshold enforcement trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and functional beverage volume expansion; material deviation in corn supply disruption severity or carbon border adjustment implementation pace would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Powdered Fats Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market