
 Gardenia Food Color Market | 2026-2036
Gardenia Food Color Market Size, Share, and Industry Trends Forecast 2026-2036
Gardenia Food Color Market Analytics
Modular colorant kits combining liquid gardenia blue with pH stabilizers and encapsulation aids are recalibrating how beverage formulators approach natural color migration. DDW The Color House leverages captive extraction capabilities to sustain supply security across multiple gardenia cultivars. GNT Group anchors its position through vertically controlled spirulina and gardenia sourcing in the Netherlands and China. San-Ei Gen FFI dominates Japanese institutional channels with application-specific technical service teams.
Gardenia food color comprises water-soluble blue pigments extracted from Gardenia jasminoides fruit, primarily gardenoside derivatives that shift from blue to green depending on pH and protein content, with color values typically measured at E600-E640 nm absorbance ranges. These pigments serve commercial food systems requiring heat-stable, light-stable natural alternatives to synthetic Brilliant Blue FCF. Liquid colors lead volume throughput in high-speed beverage filling operations where pumpability and dispersion uniformity reduce batch-to-batch variation. Powdered colors command premium positioning in dry-mix applications such as bakery premixes and instant beverage bases where shelf stability and freight efficiency matter. Gel colors occupy a specialized niche in artisan confectionery and small-batch dairy decoration where viscosity control enables precise piping and marbling effects.
FDA color additive regulations under 21 CFR 73 govern gardenia blue's permitted use categories and purity specifications in the United States, while EFSA evaluates novel food and food additive dossiers for expanded European applications under the EU Food Improvement Agent Package. Japan's Ministry of Health, Labour and Welfare maintains positive-list standards for natural colorants that San-Ei Gen FFI and Natural Blue Japan navigate through ongoing specification submissions. Stakeholders must monitor regulatory divergence between jurisdictions where gardenia blue enjoys broad approval and markets where it remains under novel food assessment, as this gap determines priority sequencing for formulation investment and regional manufacturing placement.
Market Dynamics
Japan's Ministry of Health, Labour and Welfare expanded gardenia blue's positive list in 2023, triggering a cascade of formulation shifts across East Asian beverage manufacturing. This regulatory momentum is compressing the window for synthetic Brilliant Blue FCF substitution.
Growth Catalysts
- Clean-Label Migration:Beverage manufacturers in South Korea are reformulating functional drink lines to eliminate synthetic azo dyes ahead of MFDS disclosure mandates.
- SAMR Novel Food Expansion:China's State Administration for Market Regulation approved gardenia blue for expanded novel food categories, accelerating domestic sourcing investments.
- pH-Stabilized Liquid Concentrates:Encapsulation technology advances enable heat-stable blue pigments for UHT dairy applications previously closed to natural alternatives.
Market Restraints
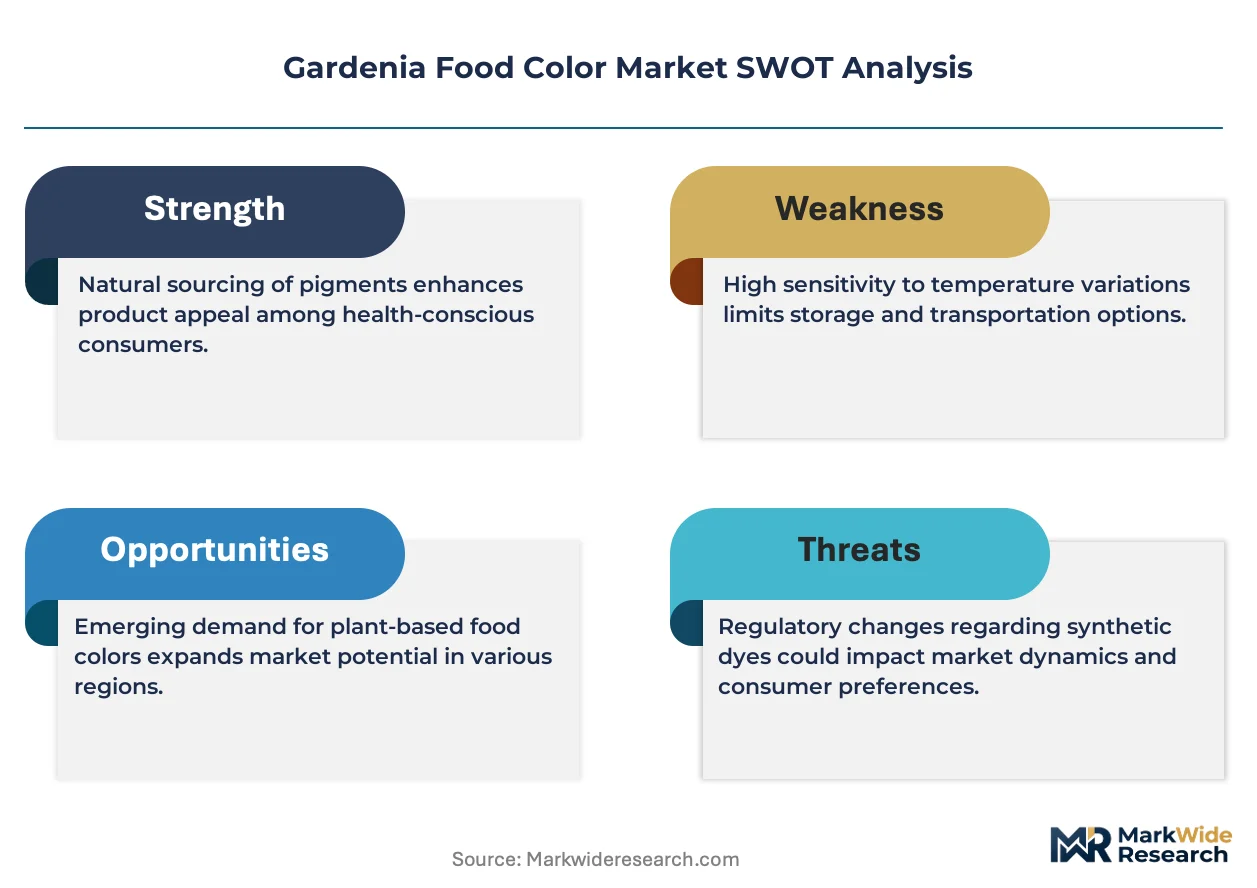
- Raw Material Concentration:Gardenia jasminoides cultivation clusters in Hunan and Sichuan provinces, exposing processors to regional weather volatility and procurement competition from traditional medicine buyers.
- Extraction Yield Variability:Genipin-to-gardenia blue conversion rates fluctuate 15-30% between harvest batches, compressing margin predictability for toll processors.
- Novel Food Assessment Bottlenecks:EFSA's pending evaluation of expanded food additive dossiers blocks European confectionery applications, diverting investment toward Asian markets.
Strategic Opportunities
- Underpenetrated North American Bakery:FDA 21 CFR 73 permits gardenia blue in select categories, but commercial penetration in artisanal frosting and fondant remains minimal versus synthetic dominance.
- Spirulina-Gardenia Blending:Hybrid natural blue formulations combining spirulina's stability with gardenia's cost position are opening premium pet food and nutraceutical gummy segments.
- Direct-to-Formulator Digital Channels:Specialty ingredient distributors are launching technical specification portals that bypass traditional broker networks for mid-size beverage developers.
Industry Challenges
- Colorist Technical Shortage:Formulation chemists capable of managing protein-interaction shifts and pH drift in complex matrices command premium compensation, constraining R&D bandwidth at emerging processors.
- Cross-Jurisdictional Compliance Complexity:Divergent purity specifications between Japan's positive list, China's GB standards, and FDA color additive regulations force parallel inventory management or geographic SKU fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gardenia Food Color Market |
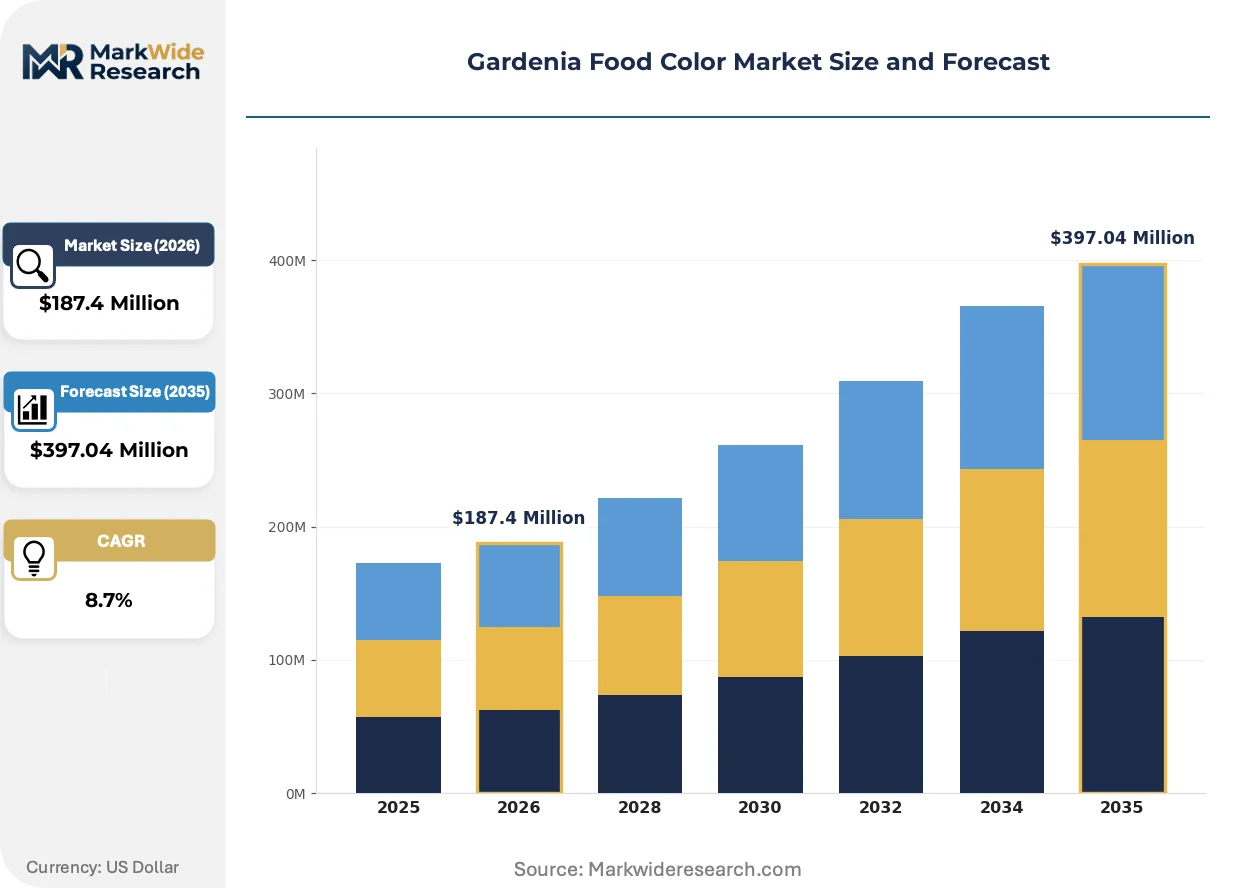
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Colors, Powdered Colors, Gel Colors, Emulsified Colors Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Catering Services, Retail Chains, Home Bakers Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | DDW The Color House, GNT Group, San-Ei Gen FFI, Naturex (Givaudan), Kalsec, Gardenia Blue Interest Group, Sensient Technologies, Chr. Hansen, Natural Blue Japan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gardenia Food Color Market Evolving Landscape
Encapsulation and stabilization chemistries are rewriting the technical boundaries of natural blue pigments in high-heat processing environments. These advances are collapsing the performance gap that previously protected synthetic alternatives.
Microencapsulated gardenia blue with modified starch shells is overtaking conventional liquid concentrates in retort beverage applications. Japanese sports drink manufacturers adopted this format for 2024 product lines after shelf-stability trials demonstrated 18-month color retention. The technology is compressing the addressable market for Brilliant Blue FCF in thermal processing above 85°C.
REACH registration requirements for imported botanical extracts are reshaping European supply chain configurations. ECHA's 2023 guidance on substance identity criteria for complex natural products forced reformulation of dossier strategies. Gardenia processors are responding by establishing EU-based toll extraction partnerships rather than direct export models.
Beverage formulators are consolidating supplier relationships around technical service capabilities rather than commodity pricing. Procurement teams at multinational CPG companies now require dedicated application laboratories within 500 kilometers of manufacturing sites. This pattern is most pronounced in China's Yangtze River Delta, where San-Ei Gen FFI and domestic competitors operate parallel technical centers.
Gardenia Food Color Market Segmentation
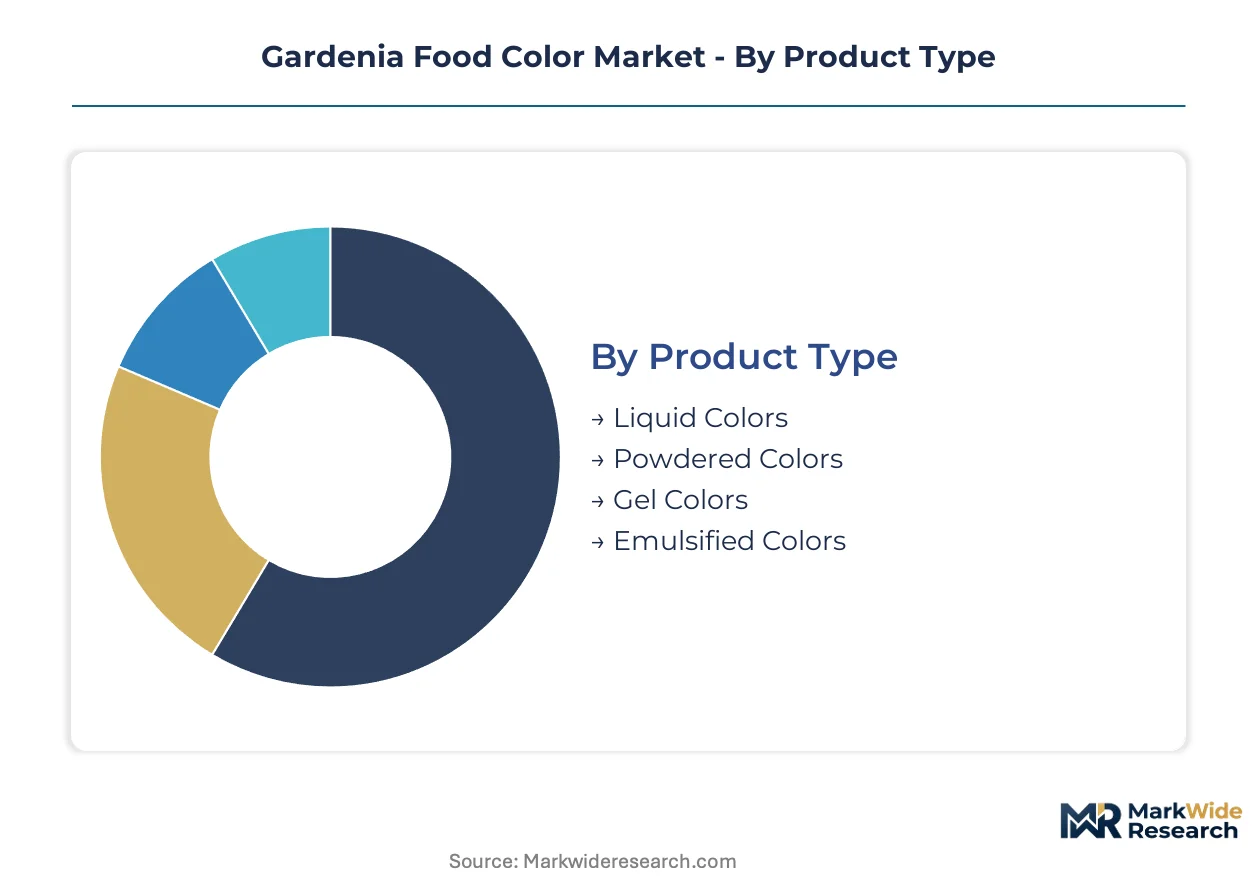
Gardenia food color procurement patterns diverge sharply across product formats and end-use channels, with beverage manufacturers driving volume while artisan bakers create margin concentration. Understanding these segment boundaries clarifies where formulation investment yields the highest competitive returns.
Product Type:
Manufacturers upgrade from legacy powder formats to stabilized liquid concentrates when reformulating for high-speed filling lines or heat-processed applications, triggering a replacement cycle that favors technical-service-intensive suppliers.
- Liquid Colors:Pumpable concentrates with pH stabilizers and encapsulation aids dominate high-speed beverage filling operations where dispersion uniformity cuts batch-to-batch variation. Japanese sports drink manufacturers adopted microencapsulated liquid formats for retort applications after shelf-stability trials demonstrated extended color retention.
- Powdered Colors:Spray-dried pigments command premium positioning in dry-mix applications including bakery premixes and instant beverage bases where shelf stability and freight efficiency outweigh hydration steps. China's SAMR approval of expanded gardenia blue usage accelerated domestic procurement of powdered formats for novel food categories.
- Gel Colors:Viscosity-controlled suspensions serve artisan confectionery and small-batch dairy decoration where precise piping and marbling effects require rheological tuning.
- Emulsified Colors:Oil-dispersible variants address fat-based matrices including compound coatings and aerated desserts where water-soluble pigments fail.
Liquid colors sit at the top of the volume ranking, with emulsified colors climbing the fastest as confectionery formulators tackle clean-label chocolate alternatives.
Application:
Cost tier differentiation separates commodity beverage coloring from premium confectionery and nutraceutical applications where stability specifications justify multi-layer supplier qualification.
- Beverages:Functional drink lines in South Korea and Japan drive procurement of heat-stable blue pigments ahead of MFDS disclosure mandates eliminating synthetic azo dyes. UHT dairy applications previously closed to natural alternatives now open through pH-stabilized liquid concentrates.
- Bakery Products:Artisanal frosting and fondant in North America remain underpenetrated versus synthetic Brilliant Blue FCF dominance, though FDA 21 CFR 73 permits gardenia blue in select categories.
- Dairy Products:Protein-interaction challenges constrain gardenia blue adoption in neutral pH yogurts and fresh cheeses where color shifts toward green.
- Confectionery:EFSA's pending novel food assessment blocks European applications, diverting investment toward Asian markets where Japan's positive list expansion triggered formulation cascades.
Beverages capture the dominant volume share, with confectionery expanding most quickly should EFSA dossier approvals unlock European gummy and hard candy segments.
End User:
Customer type determines technical service intensity, with food manufacturers demanding captive laboratory support while retail chains prioritize supply security and home bakers seek color consistency at small scale.
- Food Manufacturers:Multinational CPG procurement teams now require dedicated application laboratories within 500 kilometers of manufacturing sites, consolidating supplier relationships around technical capabilities rather than commodity pricing.
- Catering Services:Institutional channels in Japan favor application-specific technical service teams capable of managing batch-scale color matching for banquet and airline catering operations.
- Retail Chains:Private-label bakery and beverage programs source through specialty ingredient distributors launching technical specification portals that bypass traditional broker networks.
- Home Bakers:Gel color tubes and small-format liquid bottles distribute through craft store channels where viscosity control and ease of use outweigh cost per unit.
Food manufacturers anchor procurement volume, with retail chains gaining share fastest as private-label clean-label programs expand.
Distribution Channel:
Supply concentration in Hunan and Sichuan provinces shapes channel economics, with direct sales capturing bulk beverage accounts while online stores fragment small-lot procurement.
- Online Stores:Direct-to-formulator digital channels enable mid-size beverage developers to access technical specifications and small-batch samples without broker intermediation.
- Supermarkets:Mass-market gel and liquid formats for home bakers occupy shelf space adjacent to baking mixes, with seasonal color kits driving impulse purchases.
- Specialty Stores:Professional bakery and confectionery supply houses stock concentrated liquid and powdered formats with technical datasheets for artisan producers.
- Direct Sales:Bulk liquid and emulsified colors move through manufacturer-direct relationships with multinational food manufacturers requiring audit trails and specification lock.
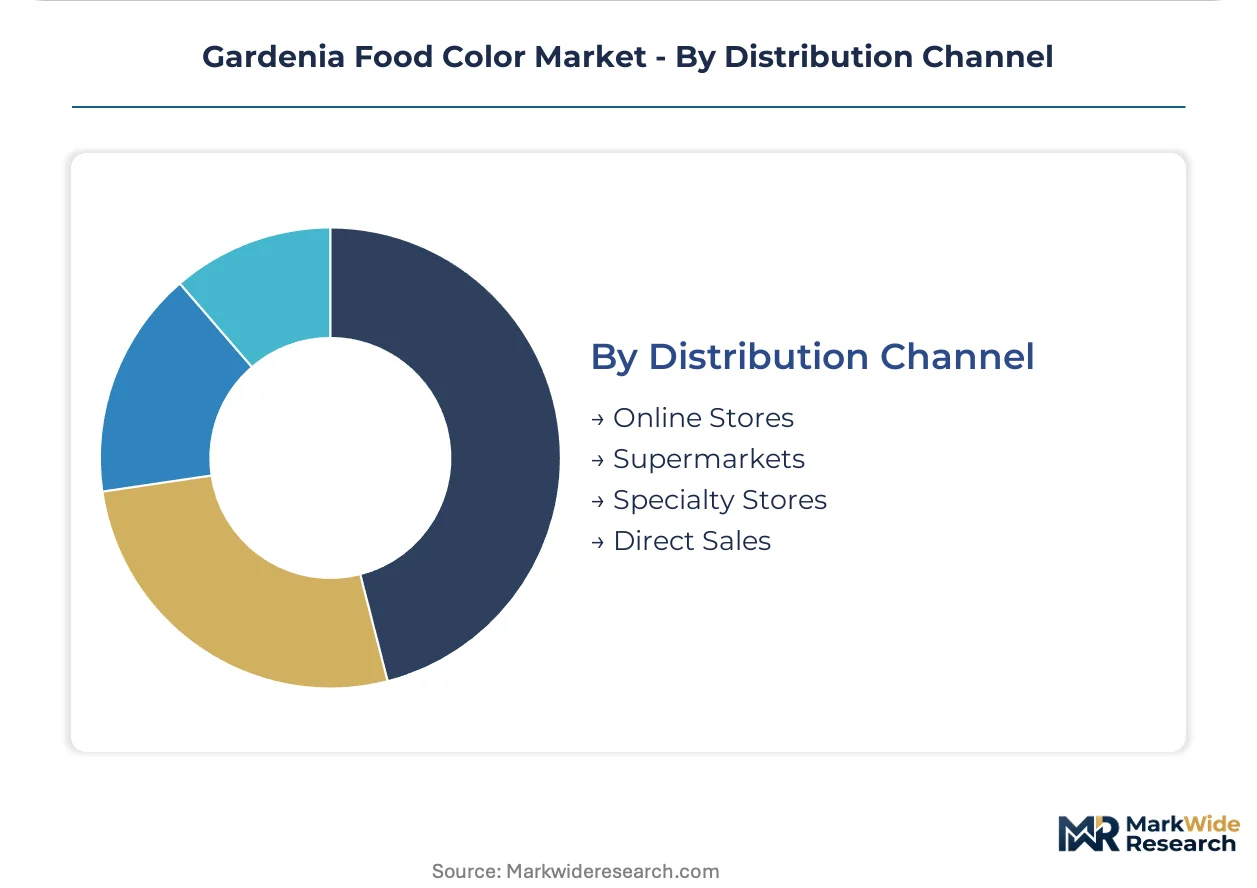
Direct sales lead volume throughput, with online stores climbing the fastest as digital procurement penetrates mid-tier formulator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gardenia cultivation and pigment extraction originated in East Asia, with traditional medicine systems driving early domestication before food color applications emerged. Commercial scale-up concentrated in China's Hunan and Sichuan provinces, where processing infrastructure now supplies international formulators.
China
Domestic beverage manufacturers are accelerating procurement of gardenia-derived pigments following SAMR's expanded novel food approvals for blue colorant applications. GB standards for natural food additives govern purity specifications that processors must meet for domestic distribution. Yangtze River Delta technical centers in Shanghai and Suzhou now host application laboratories serving multinational CPG procurement teams.
Japan
Functional drink lines at major beverage houses are eliminating synthetic azo dyes ahead of disclosure mandates, redirecting volume toward natural blue alternatives. The Ministry of Health, Labour and Welfare expanded gardenia blue's positive list in 2023, compressing substitution timelines for Brilliant Blue FCF. Kansai region processors around Osaka maintain institutional channel dominance through dedicated technical service teams for banquet and airline catering operations.
South Korea
MFDS disclosure requirements for synthetic dyes are forcing reformulation across sports drink and functional beverage portfolios. The national food and drug safety regulator maintains standards that gardenia-derived pigments increasingly satisfy. Seoul Capital Area manufacturing clusters are consolidating supplier relationships around captive laboratory support within 500 kilometers of filling operations.
United States
Artisanal frosting and fondant applications remain underpenetrated despite FDA 21 CFR 73 permitting gardenia blue in select food categories. The color additive regulations specify permitted use categories and purity specifications that constrain formulation flexibility. California and New York Metro area specialty distributors are launching direct-to-formulator digital channels that bypass traditional broker networks for mid-size developers.
Germany
REACH registration requirements for imported botanical extracts are reshaping supply chain configurations for natural colorant distributors. ECHA guidance on substance identity criteria for complex natural products has forced reformulation of dossier strategies. Toll extraction partnerships in North Rhine-Westphalia are replacing direct export models from Asian processors.
Gardenia Food Color Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service intensity and captive extraction capabilities. The market structures around three tiers: multinational color houses with vertical laboratory networks, regional specialists with cultivar-specific sourcing control, and toll processors exposed to raw material yield volatility. Three archetypes dominate: extraction-integrated pigment houses, application-technical service providers, and distribution-anchored specialty ingredient platforms. Competitive moves concentrate on M&A for laboratory footprint expansion and strategic partnerships for EU-based toll extraction capacity.
Among extraction-integrated specialists, DDW The Color House and GNT Group represent the captive supply archetype, with geographic naming indicating North American and European origins respectively. San-Ei Gen FFI occupies a position exemplifying the application-technical service model, with Japanese institutional channel density. These three sit within the premium tier where technical specification portals and proximity laboratory requirements determine procurement decisions.
| Leading Market Players |
|---|
| DDW The Color House |
| GNT Group |
| San-Ei Gen FFI |
| Naturex (Givaudan) |
| Kalsec |
| Gardenia Blue Interest Group |
| Sensient Technologies |
| Chr. Hansen |
| Natural Blue Japan |
| Others |
Value Network & Pricing Analysis
Genipin spot prices in Hunan province cascade through extraction tolling fees into three-tier pricing structure across premium, standard, and economy levels. Raw material yield variability compresses margin predictability and forces processors to index contracts against harvest quality differentials.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated liquid concentrates with technical service bundling from commodity powders and toll-processed intermediates. Price differentiation hinges on certification tier — Japan's positive list compliance commands premium positioning — and captive laboratory proximity. Pricing pressure stems from extraction yield variability as genipin-to-gardenia blue conversion rates fluctuate between harvest batches. Mid-size beverage developers show highest price sensitivity, while multinational CPG procurement teams prioritize technical service capabilities over unit cost.
Supply Chain Analysis
Spent gardenia pomace flows back into traditional medicine supply chains as a secondary revenue stream for processors managing extraction waste. Raw material cultivation clusters in China's Hunan and Sichuan provinces, with toll extraction partnerships emerging in Germany's North Rhine-Westphalia to satisfy REACH registration requirements. Gardenia jasminoides fruit supply draws from agricultural cooperatives competing with traditional medicine buyers for harvest volumes. Single-source vulnerability concentrates in Hunan's Yangtze River Delta processing corridor. Distribution runs through manufacturer-direct relationships for bulk liquid accounts and specialty ingredient distributors for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gardenia food color procurement functions as a geographic-arbitrage play between Asia's regulatory approval lead and Europe's pending EFSA evaluations, with cost differentials of technical service proximity driving manufacturing placement decisions.
For Market Incumbents: Anchor laboratory footprint expansion in China's Yangtze River Delta and South Korea's Seoul Capital Area to defend against emerging domestic processors capturing technical service-intensive accounts. Prioritize backward integration into Hunan cultivation contracts to secure genipin supply against traditional medicine buyer competition. Certification investment in Japan's positive list maintenance and SAMR GB standard compliance represents the critical defensive lever against substitute natural blue pigments. For New Entrants and Emerging Players: Direct-to-formulator digital channels offer the lowest-friction entry path into mid-size beverage developer accounts bypassing established broker networks. North American artisanal bakery applications remain the most penetrable white-space segment given FDA 21 CFR 73 permissibility and synthetic Brilliant Blue FCF dominance. Target private-label clean-label programs at retail chains seeking supply security alternatives to multinational color houses. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing cultivar-specific sourcing control and captive extraction capabilities in East Asian markets. Long-term viability across the analysis window depends on regulatory divergence between jurisdictions where gardenia blue enjoys broad approval and markets where novel food assessments remain pending. Acquisition target archetype: toll processors with established EU-based extraction partnerships navigating REACH substance identity requirements. Monitor EFSA novel food dossier approvals as the inflection indicator unlocking European confectionery segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply of Gardenia jasminoides fruit in Hunan province secures genipin feedstock against traditional medicine buyer competition. |
| EU Toll Extraction Partnership | North Rhine-Westphalia processing capacity satisfies ECHA REACH registration requirements for European natural colorant distribution. |
| Microencapsulation Technology Licensing | Modified starch shell patents enable heat-stable blue pigment penetration of UHT dairy retort applications. |
| Technical Service Laboratory Expansion | Proximity laboratories within 500 kilometers of Yangtze River Delta filling operations meet multinational CPG procurement mandates. |
| Direct-to-Formulator Digital Channel Launch | Technical specification portals bypass traditional broker networks for mid-size beverage developer account acquisition. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs and trade flow data, primary stakeholder interviews — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged extraction plant managers, beverage formulation chemists, procurement leads at multinational CPG companies, specialty ingredient distributors, and regulatory affairs specialists navigating Japan's positive list and SAMR novel food frameworks. Secondary validation drew from FDA color additive petitions, EFSA novel food dossier submissions, Japanese Ministry of Health positive list amendments, Chinese GB standard publications, and customs records tracking gardenia extract trade flows.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory approval timelines and substitution elasticity. Segmentation modeling spanned product format, application category, end-user type, and distribution channel across the analysis window. CAGRs were derived from supply-side capacity buildouts and demand-side formulation shift assumptions. Forecast inputs included genipin yield variability coefficients, pH-stabilized liquid concentrate adoption curves, and microencapsulation technology penetration rates in thermal processing applications.
The model assumes a particular technology adoption path; alternative pathways for spirulina-gardenia hybrid formulations would alter the outlook if stability specifications outperform standalone gardenia derivatives. Forecasts reflect assumptions regarding EFSA dossier approval sequencing, SAMR category expansion continuity, and MFDS disclosure mandate enforcement. Practitioners should monitor EFSA novel food evaluation progress, Hunan province harvest quality reports, and multinational CPG technical service procurement specifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Scrambled Egg Mix Market