
 Cocoglycerides Market | 2026-2036
Cocoglycerides Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoglycerides Market Outlook
Enzymatic interesterification is reshaping cocoglyceride production by replacing chemical catalysts with lipase-based systems that cut trans-fat residuals and sharpen molecular specificity. Cargill leverages its integrated oilseed processing network to secure feedstock cost advantages across North American and European plants. BASF SE anchors its position through pharmaceutical-grade certification programs that align with European Pharmacopoeia monographs. Kao Corporation dominates Asia-Pacific supply through dedicated fatty acid ester facilities in Japan and Malaysia.
Cocoglycerides comprise mono-, di-, and triglyceride mixtures derived from coconut oil through glycerolysis or direct esterification, functioning primarily as emulsifiers, emollients, and solubilizers in formulated products. Monoglycerides lead volume consumption due to their established role in food emulsification and extended shelf-life applications. Pharmaceutical-grade fractions command premium positioning as parenteral and topical drug delivery systems tighten excipient purity requirements. Powder and granular forms are gaining formulation share in cosmetics as dry-blend personal care products expand.
EMA excipient guidelines, FDA food additive regulations, and REACH chemical safety frameworks collectively elevate compliance costs while filtering non-certified suppliers from Western supply chains. ISO 22000 and HACCP protocols further condition market access for food-grade cocoglyceride producers serving multinational packaged goods accounts. Stakeholders must track evolving pharmacopeial harmonization between USP-NF and European Pharmacopoeia standards to anticipate reformulation mandates and qualification timelines.
Market Dynamics
Enzymatic interesterification is compressing chemical catalyst margins while elevating purity benchmarks across pharmaceutical and food-grade supply tiers, forcing producers to requalify process assets or exit certified segments entirely.
Growth Catalysts
- REACH chemical safety frameworks:Tightened purity specifications in Europe are filtering uncertified suppliers and consolidating demand around pharmacopeia-compliant producers.
- Personal care dry-blend formulations:Powder and granular cocoglyceride grades are capturing share in cosmetics manufacturing as brands reduce water content in finished goods.
- Japan and Malaysia production clusters:Dedicated fatty acid ester facilities in these markets anchor Asia-Pacific supply security for multinational pharmaceutical accounts.
Market Restraints
- Coconut oil feedstock volatility:Weather-driven supply disruptions in Southeast Asia propagate directly into cocoglyceride input cost instability.
- European Pharmacopoeia monograph alignment costs:Harmonization gaps between USP-NF and EP standards force dual qualification expenditures for cross-Atlantic suppliers.
- Phospholipid emulsifier substitution:Lecithin-derived alternatives are displacing monoglycerides in select food emulsification applications.
Strategic Opportunities
- Parenteral drug delivery systems:Injectable formulations are tightening excipient purity requirements and opening premium positioning for pharmaceutical-grade fractions.
- Bio-based solvent applications:Cocoglycerides are penetrating industrial cleaning and coatings sectors as VOC regulations tighten across manufacturing jurisdictions.
- ISO 22000 certification gaps:Mid-tier producers in India and Brazil lack food safety management credentials, creating acquisition targets for multinational packaged goods suppliers.
Industry Challenges
- Lipase enzyme procurement specialization:Qualified biocatalyst sourcing requires technical partnerships with specialized fermentation houses, constraining process conversion timelines.
- Pharmacopeial qualification duration:European Pharmacopoeia monograph updates trigger 18-24 month reformulation cycles for existing drug master files.
- Cross-contamination controls:Food-grade and pharmaceutical-grade production lines demand segregated facilities, doubling capital intensity for dual-segment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoglycerides Market |
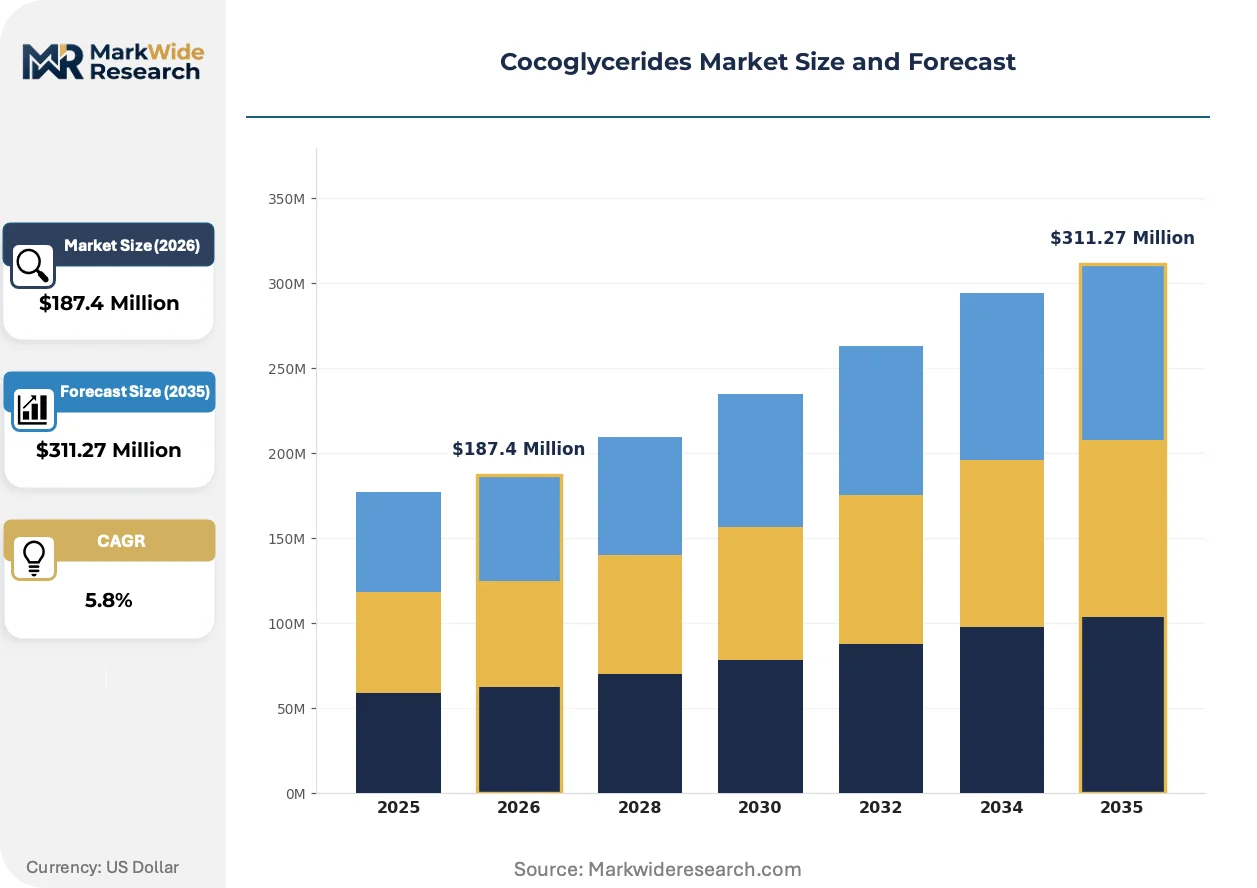
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoglycerides, Diglycerides, Triglycerides, Fractions Application: Food Industry, Cosmetics, Pharmaceuticals, Personal Care Form: Liquid, Semi-solid, Powder, Granular Grade: Food Grade, Cosmetic Grade, Pharmaceutical Grade, Industrial Grade |
| Companies Covered | Cargill, Archer Daniels Midland Company, BASF SE, Lonza Group Ltd., Stepan Company, Kao Corporation, KLK OLEO, Croda International Plc, DeWolf Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoglycerides Market Strategic Shifts
Process intensification and regulatory harmonization are compressing traditional production economics while opening formulation frontiers in high-purity pharmaceutical and bio-based industrial segments.
Supercritical CO2 extraction is hybridizing with conventional glycerolysis to deliver triglyceride fractions with residual solvent levels below pharmacopeial detection limits. Parenteral drug manufacturers in Germany and Switzerland are adopting these hybrid systems ahead of pending European Pharmacopoeia monograph revisions. The technology is hybridizing competitive positioning by enabling smaller producers to bypass capital-intensive molecular distillation assets.
REACH Annex XVII restrictions on residual glycerol and free fatty acid content are forcing reformulation of cosmetic-grade cocoglycerides across EU member states. The regulation is compressing margins for producers reliant on legacy chemical interesterification while accelerating lipase-based process investments. Fragrance and color cosmetics houses in France and Italy are responding by consolidating supplier bases around vertically integrated oleochemical processors with captive enzyme production.
Direct material sourcing from oleochemical processors is displacing distributor intermediaries among mid-scale personal care compounders in the United States. These buyers are negotiating multi-year offtake agreements with Malaysian and Indonesian producers to secure certified sustainable palm kernel oil feedstock chains. The shift is most visible in California and New Jersey formulation clusters where clean beauty brand marketing requires documented supply chain transparency.
Cocoglycerides Market Segmentation
Cocoglyceride specifications diverge sharply across end-use requirements, with pharmaceutical and food safety protocols dictating purity thresholds that reshape supplier economics. Manufacturers configure production assets around grade-specific certification programs rather than commodity volume positions.
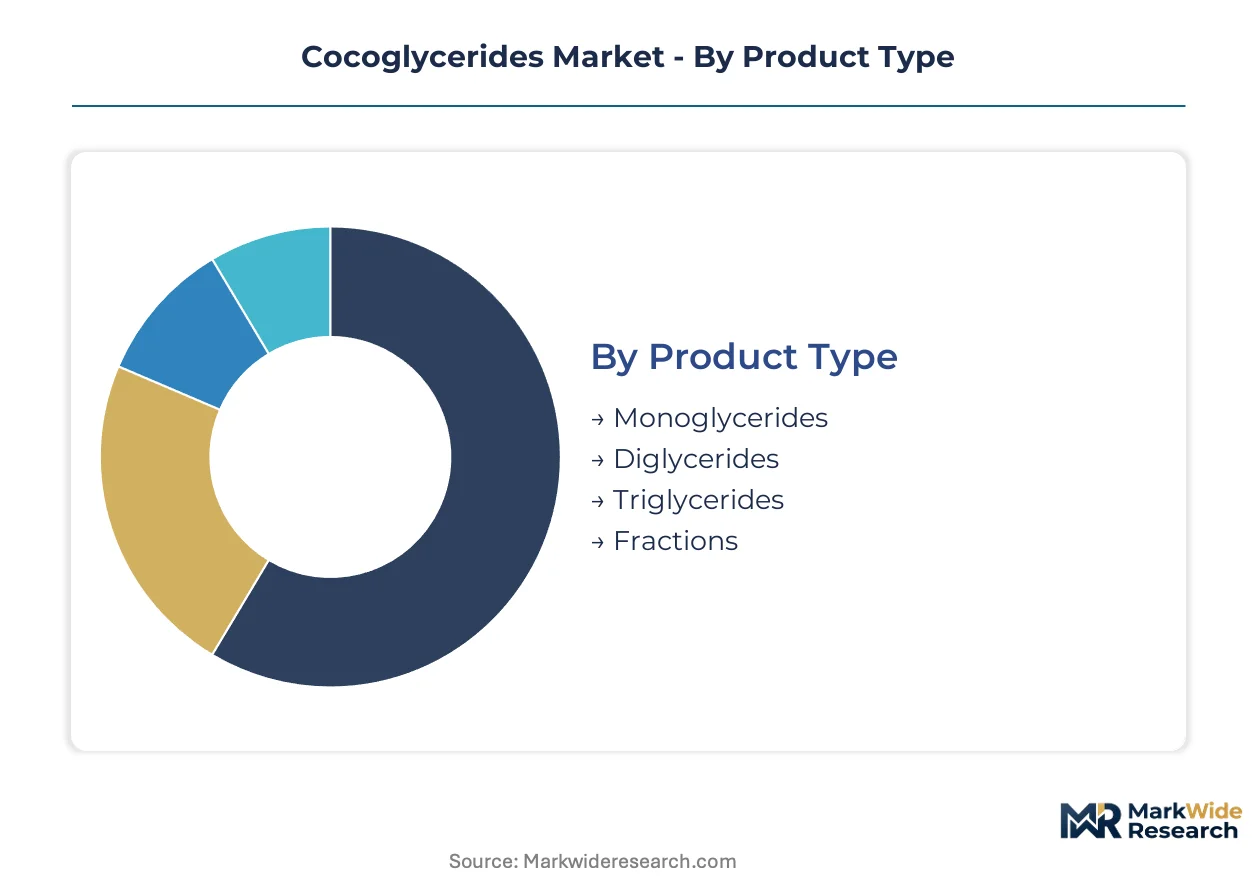
Product Type:
Composition determines functional performance in emulsification, stability, and bioavailability applications across regulated industries.
- Monoglycerides:Single fatty acid esters bound to glycerol backbone deliver superior emulsification efficiency in bakery and dairy systems. Food manufacturers in Germany and Japan specify these for extended shelf-life applications where moisture retention is critical. REACH-compliant producers command premium positioning as residual glycerol limits tighten.
- Triglycerides:Complete glycerol esterification yields neutral lipids optimized for cosmetic emollient and pharmaceutical solubilizer roles. Parenteral drug formulators in Switzerland source these fractions for injectable delivery systems demanding ultra-low peroxide values. Supercritical CO2 extraction investments are compressing traditional molecular distillation economics.
- Diglycerides:Partial esterification products bridge emulsification and texturizing functions in processed foods.
- Fractions:Distilled cuts tailored to specific carbon chain length distributions for specialized industrial applications.
Monoglycerides hold installed capacity. Triglycerides is rotating up the share rankings.
Application:
End-use specifications cascade backward into raw material sourcing and process validation requirements.
- Food Industry:Emulsification and anti-staling functions in baked goods, confectionery, and dairy systems drive volume consumption. FDA food additive regulations and EFSA specifications condition supplier qualification timelines for multinational packaged goods accounts. Enzymatic interesterification is displacing chemical catalyst systems to meet trans-fat labeling requirements.
- Pharmaceuticals:Excipient roles in oral, topical, and parenteral drug delivery demand pharmacopeial-grade certification. European Pharmacopoeia monograph alignment with USP-NF standards forces dual qualification expenditures for cross-Atlantic suppliers. Injectable applications are tightening purity thresholds fastest.
- Cosmetics:Emollient and stabilizer functions in skincare and color formulations.
- Personal Care:Solubilizer and texture modifier roles in hair care and hygiene products.
Food Industry maintains volume leadership. Pharmaceuticals is expanding most quickly.
Form:
Physical state determines handling economics and formulation flexibility in downstream manufacturing.
- Powder:Spray-dried or crystallized grades enable dry-blend cosmetics manufacturing and extended ambient storage. Clean beauty brands in California specify powder cocoglycerides to support water-free formulation marketing claims. Malaysian producers are expanding spray-drying capacity to serve this segment.
- Liquid:Bulk tanker delivery minimizes handling costs for high-volume food emulsifier applications.
- Semi-solid:Plastic-range textures for direct incorporation into anhydrous cosmetic bases.
- Granular:Free-flowing particles optimized for automated dosing in personal care compounding.
Liquid dominates tonnage throughput. Powder is climbing the fastest.
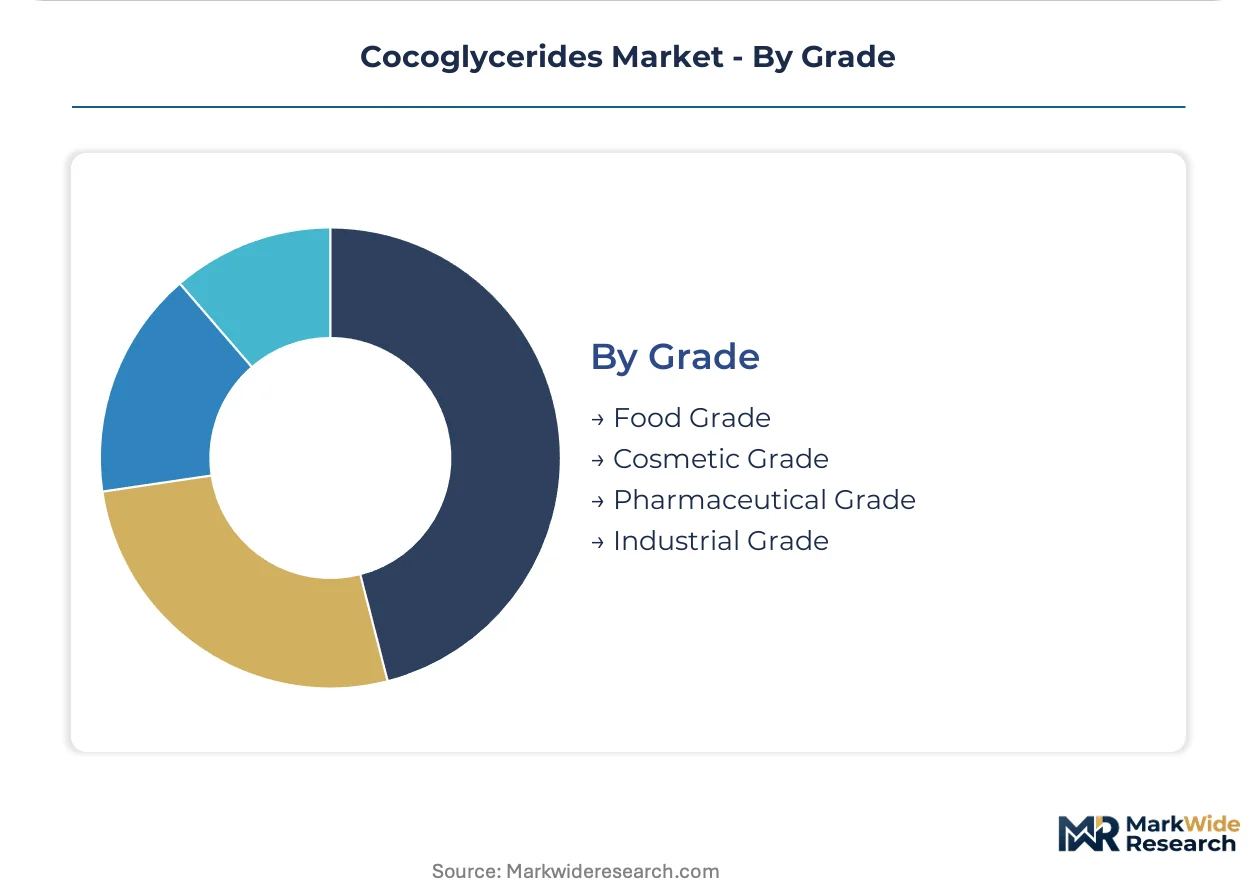
Grade:
Certification tier stratifies supplier bases and pricing structures across regulated supply chains.
- Pharmaceutical Grade:Compliance with European Pharmacopoeia and USP-NF monographs enables excipient qualification for drug master files. Parenteral applications demand residual solvent and heavy metal specifications below detection limits. Swissmedic and FDA inspections validate manufacturing sites for 18-24 month qualification cycles.
- Food Grade:ISO 22000 and HACCP protocols condition access to multinational packaged goods supply chains. EFSA and FDA dual compliance expands addressable market for integrated oleochemical processors.
- Cosmetic Grade:REACH Annex XVII compliance for residual contaminants in EU member states.
- Industrial Grade:Technical specifications for bio-based solvent and lubricant applications.
Food Grade holds installed capacity. Pharmaceutical Grade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic compounders and pharmaceutical excipient buyers cluster in Germany, the United States, and Japan, with each geography imposing distinct certification burdens that reshape supplier economics.
Germany
Personal care formulators in Hamburg and Düsseldorf drive demand for REACH-compliant emollient grades. ECHA enforcement of Annex XVII residual limits forces cosmetic-grade producers to revalidate glycerolysis processes. Bavarian pharmaceutical clusters near Munich source pharmacopeial-grade triglycerides for parenteral drug manufacturing.
United States
Clean beauty brands in California and New Jersey specify powder cocoglycerides for water-free formulation claims. FDA food additive regulations condition supplier qualification timelines for multinational packaged goods accounts. Direct sourcing agreements with Malaysian producers bypass traditional distributor channels.
Japan
Pharmaceutical manufacturers in Osaka and Tokyo demand ultra-low peroxide values for injectable delivery systems. METI industrial standards accelerate enzymatic interesterification adoption to meet trans-fat labeling requirements. Kao Corporation's dedicated fatty acid ester facilities anchor Asia-Pacific supply security.
Switzerland
Parenteral drug formulators near Basel adopt supercritical CO2 extraction systems ahead of pending European Pharmacopoeia revisions. Swissmedic inspections validate manufacturing sites for 18-24 month qualification cycles. These hybrid systems enable smaller producers to bypass capital-intensive molecular distillation assets.
Malaysia
Oleochemical processors in Klang Valley expand spray-drying capacity to serve dry-blend cosmetics manufacturing. ISO 22000 certification gaps among mid-tier producers create acquisition targets for multinational packaged goods suppliers. Captive enzyme production capabilities consolidate supplier bases around vertically integrated processors.
Cocoglycerides Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply chains. Integrated oleochemical processors with captive feedstock networks command premium positioning in certified-grade segments. Three archetypes dominate: vertically integrated oilseed processors, pharmaceutical-grade certification specialists, and regional fatty acid ester manufacturers. Capacity expansion in enzymatic interesterification and strategic partnerships for lipase enzyme procurement represent the dominant competitive vectors.
Among diversified agribusiness conglomerates, Cargill and Archer Daniels Midland Company exemplify feedstock-integrated archetypes with North American oilseed processing networks. BASF SE occupies a position within the pharmaceutical-grade certification tier, aligning with European Pharmacopoeia monographs. These three entities represent distinct strategic postures: upstream feedstock control, regulatory-grade qualification depth, and formulation-specific technical service.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| BASF SE |
| Lonza Group Ltd. |
| Stepan Company |
| Kao Corporation |
| KLK OLEO |
| Croda International Plc |
| DeWolf Chemical |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Singapore shipping corridor anchors feedstock cost dynamics for European and Asian cocoglyceride producers, concentrating pricing power among integrated processors with captive coconut oil sourcing while forcing distributor-dependent compounders into cost-plus pass-through structures. This logistics backbone feeds directly into three-tier pricing stratification across pharmaceutical, food, and cosmetic certification grades.
Pricing Analysis
Cost-plus contracts indexed to Malaysian palm kernel oil futures dominate long-term supply agreements between Southeast Asian producers and multinational packaged goods accounts. Price differentiation rests on pharmacopeial certification depth and ISO 22000 credential status, with pharmaceutical-grade fractions commanding substantial premiums over cosmetic-grade alternatives. Pricing pressure stems from enzymatic process investments required for REACH Annex XVII compliance, compressing margins for legacy chemical catalyst operators. Mid-scale personal care compounders exhibit highest price sensitivity, while parenteral drug manufacturers prioritize purity specifications over unit economics.
Supply Chain Analysis
Supplier-financing facilities extending payment terms to 90-120 days have become standard among Malaysian and Indonesian oleochemical processors seeking to lock in multinational offtake commitments. Raw material flows draw from coconut oil plantations in the Philippines and Indonesia, lipase enzyme fermentation houses in Denmark and Japan, and glycerol feedstock from biodiesel refineries in Germany and the Netherlands. Single-source vulnerability concentrates around qualified biocatalyst procurement, where technical partnerships with specialized fermentation houses constrain process conversion timelines. Distribution runs through direct material sourcing agreements displacing traditional distributor intermediaries among United States and European formulation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cocoglyceride markets are entering a cyclical recovery phase as pharmaceutical excipient demand rebounds from parenteral drug formulation expansion and REACH-driven supplier consolidation filters non-compliant competitors. Coconut oil feedstock volatility remains the cyclical anchor, with weather-driven supply disruptions in Southeast Asia propagating directly into input cost instability and pricing power rotation.
For Market Incumbents: Harden pharmacopeial qualification depth through dual USP-NF and European Pharmacopoeia alignment investments, defending against emerging enzymatic process specialists capturing share in high-purity segments. Prioritize backward integration into captive lipase enzyme production or exclusive fermentation partnerships to secure biocatalyst supply security. Expand spray-drying capacity in Malaysia and Indonesia to capture powder-grade demand from clean beauty formulation clusters in California and New Jersey.
For New Entrants and Emerging Players: Pursue ISO 22000 certification gaps among mid-tier Indian and Brazilian producers as acquisition or partnership entry points, targeting food-grade supply chain integration for multinational packaged goods accounts. White-space concentrates in bio-based solvent applications for industrial cleaning and coatings sectors, where VOC regulatory tightening creates formulation substitution opportunities. Lead with supercritical CO2 extraction technology partnerships to bypass capital-intensive molecular distillation barriers in pharmaceutical-grade positioning.
For Investors and Strategic Acquirers: Regional fatty acid ester manufacturers with captive feedstock networks and pending pharmacopeial qualifications represent the most compelling acquisition archetype for premium multiple expansion. Long-term viability hinges on enzymatic process conversion completion and European Pharmacopoeia monograph alignment timelines. Monitor lipase enzyme procurement specialization developments and pending monograph revision announcements as inflection signals for qualification cycle acceleration or delay.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Conversion | REACH Annex XVII compliance and trans-fat labeling requirements favor lipase-based systems over chemical catalysts. |
| Pharmacopeial Dual Qualification | USP-NF and European Pharmacopoeia alignment expands addressable market for cross-Atlantic pharmaceutical supply. |
| Spray-Drying Capacity Expansion | Powder-grade output serves clean beauty water-free formulation claims in California and European cosmetics clusters. |
| Captive Lipase Enzyme Production | Backward integration into biocatalyst supply secures process conversion timelines against qualified fermentation house constraints. |
| Direct Sourcing Agreement Negotiation | Multi-year offtake contracts with Malaysian producers bypass distributor intermediaries and secure certified sustainable feedstock chains. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at oleochemical processing facilities, procurement leads at multinational packaged goods and pharmaceutical companies, distribution channel partners in European and Asian logistics networks, and technical R&D directors specializing in enzymatic interesterification processes. Secondary validation drew from customs and trade data tracking coconut oil and palm kernel oil flows, SEC filings of integrated agribusiness conglomerates, European Pharmacopoeia and USP-NF monograph documentation, and REACH Annex XVII regulatory filings. Bottom-up capacity and consumption estimates were triangulated against top-down industry association aggregates from oleochemical processor federations.
Calibration against historical price realizations and capacity utilization rates informed projection modeling across the analysis window. Segmentation dimensions included product type composition, application-grade certification tier, physical form state, and regional production hub concentration. CAGRs were derived from regression-adjusted growth rate convergence incorporating enzymatic process adoption curves, pharmacopeial qualification timelines, and feedstock price elasticity assumptions specific to coconut oil supply volatility and substitute oilseed availability.
Sensitivities concentrate around European Pharmacopoeia monograph revision timing, lipase enzyme procurement bottlenecks, and coconut oil weather-driven supply disruptions. Forecasts reflect documented assumptions on process conversion rates, certification penetration trajectories, and regional demand clustering. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Bakery Release Agents Market