
 Plant-Based Emulsifiers Market | 2026-2036
Plant-Based Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Emulsifiers Market Analytics
ISO 22000 certification is unwinding competitive access across the plant-based emulsifiers landscape, filtering out smaller ingredient suppliers that lack integrated food safety management systems. Cargill, Incorporated leverages its oilseed crushing infrastructure to secure backward integration into lecithin supply chains. Palsgaard A/S anchors its position through specialized emulsifier-blend R&D facilities in Scandinavia. DuPont de Nemours, Inc. competes on enzymatic modification technologies that broaden protein-based emulsifier functionality.
Plant-based emulsifiers comprise amphiphilic molecules derived from vegetable oils, legumes, or cereals that reduce interfacial tension between immiscible phases such as water and lipids, typically functioning at concentrations of 0.1% to 5% by weight in finished formulations. These ingredients stabilize emulsions, control crystallization, and extend shelf life in processed goods where synthetic additives face mounting rejection. Lecithin dominates product-type revenue due to its decades-long track record in chocolate and margarine applications, though protein-derived emulsifiers are gaining fastest as allergen-friendly alternatives attract premium positioning. Within applications, food and beverages occupies the deepest margin pool, while personal care represents a smaller but higher-growth outlet as cosmetic formulators replace petrochemical surfactants.
FDA GRAS self-affirmation and EFSA novel food assessments shape which plant-derived molecules achieve commercial scale in the United States and Europe respectively, creating divergent approval timelines that fragment go-to-market strategies. REACH registration requirements in Europe further constrain suppliers lacking toxicological dossiers for their extraction byproducts. Stakeholders must monitor evolving EPA biofuel mandates and EU deforestation regulations, as these policies redirect oilseed flows that underpin emulsifier feedstock economics.
Market Dynamics
Clean-label mandates from European regulators and North American retailers are compressing synthetic emulsifier shelf space, forcing reformulation cycles that favor plant-derived alternatives with traceable supply chains.
Growth Catalysts
- EU Green Deal compliance:REACH registration deadlines for synthetic additives accelerate manufacturer transitions to lecithin and protein-based emulsifiers in chocolate and margarine production.
- Bakery sector reformulation:Clean-label bread and pastry applications pull volumes upward as industrial bakers replace DATEM and SSL with plant-based crystallization controllers.
- Enzymatic modification:Protein hydrolysis technologies broaden functionality in allergen-free emulsifiers, opening premium positioning in infant nutrition and clinical foods.
Market Restraints
- Soy lecithin price volatility:Argentine and Brazilian drought cycles create feedstock cost instability that compresses margins for standard-grade suppliers.
- EFSA novel food timelines:Extended safety assessments for new protein sources delay commercialization by 18-36 months versus FDA GRAS self-affirmation pathways.
- Synthetic emulsifier residual demand:Polyglycerol esters and sucrose esters retain cost advantages in mass-market confectionery, slowing full substitution.
Strategic Opportunities
- Personal care channel expansion:Cosmetic formulators in France and Germany replace petrochemical surfactants with plant-derived emulsifiers in premium skincare lines.
- EU deforestation regulation alignment:Certified sustainable palm-free lecithin from sunflower and rapeseed captures price premiums in ethical sourcing programs.
- Precision fermentation convergence:Microbially produced phospholipids bypass agricultural feedstock constraints, enabling supply security for pharmaceutical-grade applications.
Industry Challenges
- ISO 22000 implementation costs:Integrated food safety management systems require capital outlays that filter smaller ingredient suppliers from retail-facing contracts.
- Legacy equipment incompatibility:Protein-based emulsifiers demand modified processing temperatures and hydration protocols that disrupt established bakery and confectionery lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Emulsifiers Market |
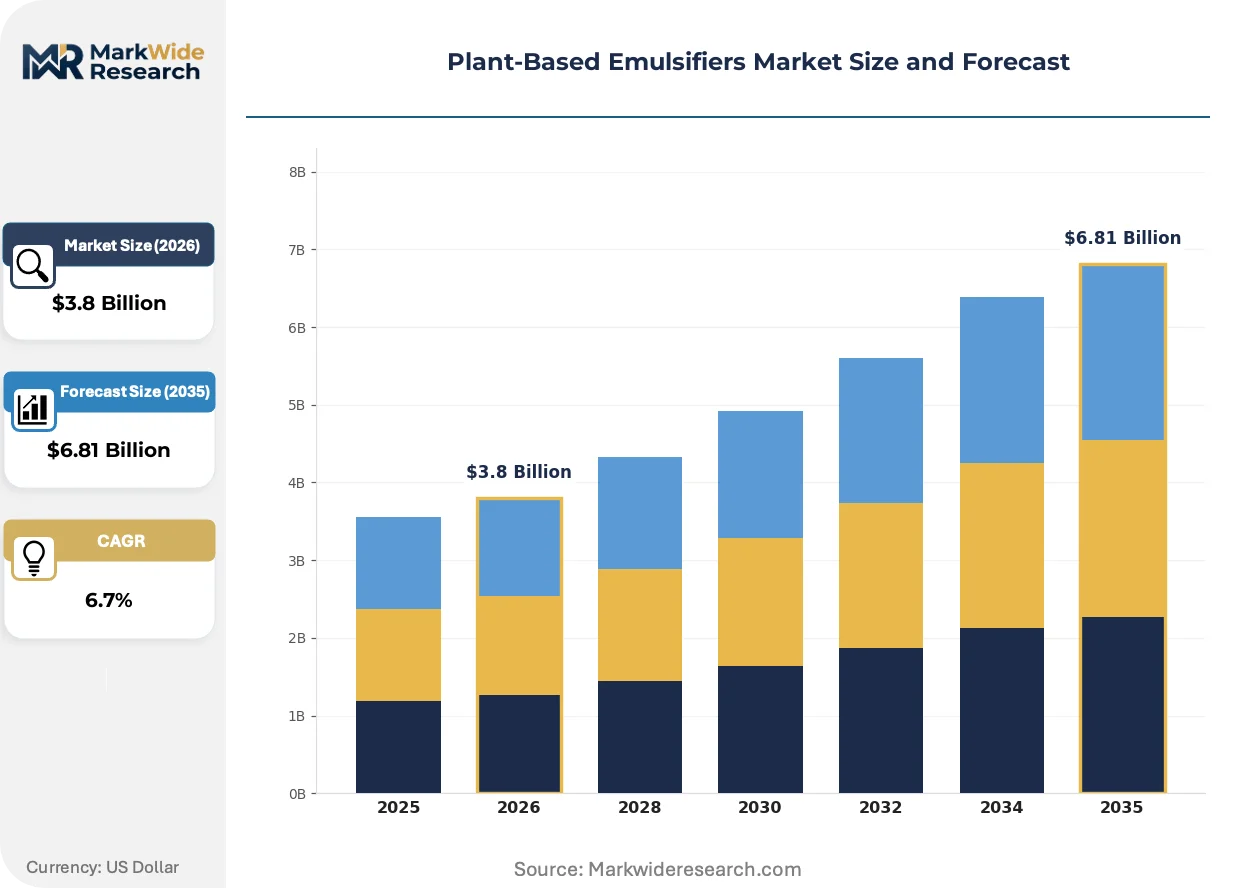
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Gums, Starches, Proteins Application: Food & Beverages, Personal Care, Pharmaceuticals, Nutraceuticals Form: Liquid, Powder, Granulated, Paste End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Dietary Supplement Producers |
| Companies Covered | DuPont de Nemours, Inc., Palsgaard A/S, Cargill, Incorporated, Bunge Limited, Tate & Lyle PLC, Archer Daniels Midland Company, Ingredion Incorporated, AAK AB, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Emulsifiers Market Evolving Landscape
Enzymatic processing and precision fermentation are redrawing technical boundaries between commodity lecithin and specialty protein emulsifiers, while regulatory divergence between FDA and EFSA pathways fragments commercialization strategies.
Enzymatic interesterification is fragmenting the traditional lecithin value chain by enabling customized phospholipid profiles without solvent extraction. Specialty chocolate manufacturers in Belgium and Switzerland adopt these modified lecithins for tempering control. The technology is fragmenting supply relationships as bakeries and confectioners bypass standard lecithin distributors to contract directly for enzymatically tailored grades.
REACH registration requirements for extraction byproducts are tightening toxicological documentation standards across European supply chains. Suppliers lacking dossiers for solvent residues and protein allergenicity face market exclusion. German and Dutch food manufacturers accelerate dual-sourcing strategies to secure compliant plant-based emulsifiers ahead of 2027 registration deadlines.
Direct procurement from crushing cooperatives is displacing traditional ingredient distributor relationships among mid-sized European bakery groups. Buyers in the Netherlands and Denmark establish long-term offtake agreements with sunflower and rapeseed processors. This pattern concentrates most visibly in organic and non-GMO certified segments where traceability commands measurable price premiums.
Plant-Based Emulsifiers Market Segmentation
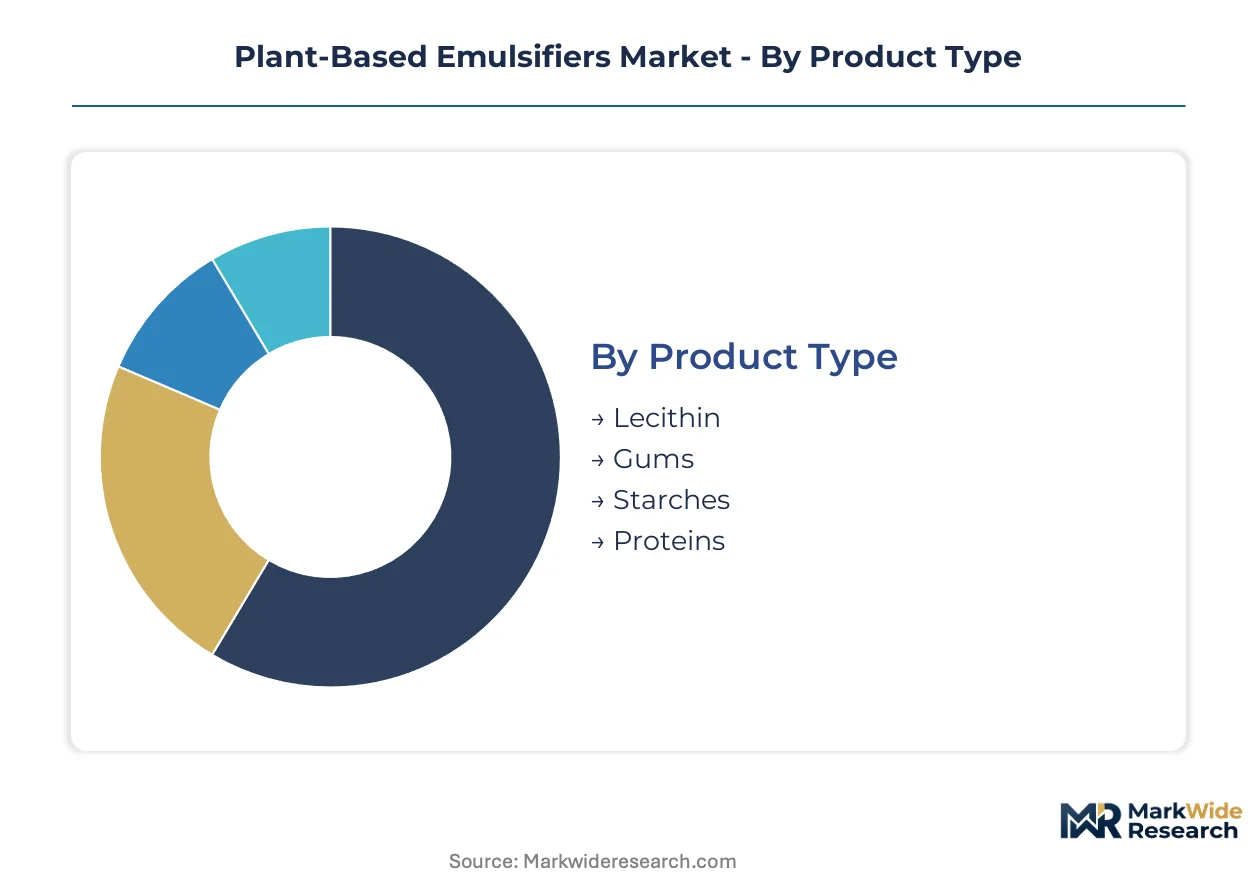
Plant-based emulsifier purchasing patterns diverge sharply across product chemistry and end-use specifications. Manufacturers configure supply chains differently for commodity lecithin versus specialty protein isolates, while regulatory compliance requirements fragment procurement strategies between food and pharmaceutical channels.
Product Type:
Lecithin commands the deepest margin pool due to decades of process optimization and established chocolate industry relationships, though protein-derived alternatives are capturing premium positioning in allergen-sensitive formulations.
- Lecithin:Phospholipid mixtures extracted from soybean, sunflower, or rapeseed oils function at 0.3% to 3% inclusion rates for emulsion stabilization and crystallization control. Industrial chocolate manufacturers in Belgium and Switzerland concentrate demand here, drawn by enzymatic modification technologies that enable customized phospholipid profiles without solvent residues.
- Proteins:Hydrolyzed plant proteins from pea, oat, or faba bean sources create amphiphilic structures through controlled enzymatic hydrolysis, expanding functionality in allergen-free infant nutrition. German and Dutch clinical food formulators rotate procurement toward these isolates as EFSA novel food approvals accumulate.
- Gums:Polysaccharide hydrocolloids from guar, locust bean, or acacia seeds provide viscosity modification and water-binding capacity in gluten-free bakery applications.
- Starches:Modified native starches from corn, tapioca, or potato sources deliver cost-effective emulsion stabilization in mass-market processed foods where label simplicity matters less.
Lecithin holds installed capacity. Proteins are rotating up the share rankings.
Application:
Volume concentration sits in food processing, though personal care applications generate steeper expansion trajectories as cosmetic formulators abandon petrochemical surfactants.
- Food & Beverages:Bread, confectionery, and dairy alternatives absorb the majority of plant-based emulsifier volumes, with clean-label reformulation cycles accelerating across European industrial bakeries. French and German manufacturers replace DATEM and SSL with plant-derived crystallization controllers to satisfy retailer mandates.
- Personal Care:Premium skincare and color cosmetic formulations in France and Germany substitute plant-derived emulsifiers for synthetic surfactants, with sunflower lecithin and saponified oils gaining traction in organic-certified product lines.
- Pharmaceuticals:Liposomal drug delivery systems and parenteral nutrition emulsions demand pharmaceutical-grade phospholipids with documented traceability and low endotoxin specifications.
- Nutraceuticals:Softgel encapsulation and functional beverage applications utilize lecithin as both emulsifier and active ingredient for choline supplementation.
Food and beverages anchor current procurement volumes. Personal care is climbing the fastest.
Form:
Processing economics and storage logistics determine form selection, with liquid formats dominating high-volume industrial contracts and powder specifications serving distributed manufacturing networks.
- Liquid:Fluid lecithin and oil-based emulsifier concentrates ship in bulk tankers to large-scale chocolate and margarine producers, minimizing handling costs for continuous processing lines.
- Powder:Spray-dried or plated formulations enable precise dosing in automated bakery premix operations and extended shelf stability for international distribution.
- Granulated:Free-flowing agglomerated particles reduce dust exposure and improve dispersion characteristics in high-shear mixing environments.
- Paste:Semi-solid emulsifier blends target artisanal and small-batch manufacturers lacking liquid handling infrastructure.
Liquid maintains throughput leadership. Powder is gaining share in premix channels.
End User:
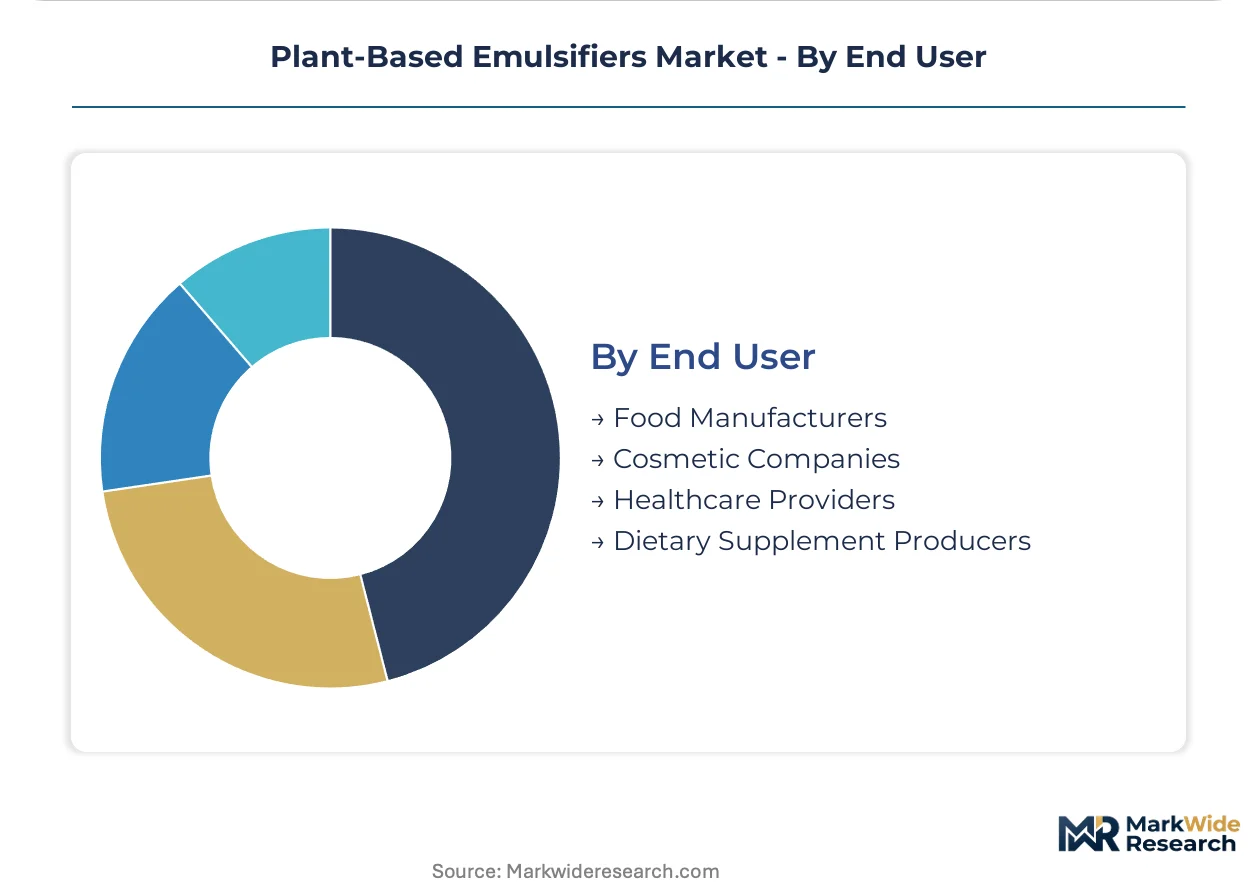
Contract specifications and certification requirements diverge sharply between food manufacturers seeking ISO 22000 compliance and pharmaceutical buyers demanding GMP documentation.
- Food Manufacturers:Industrial bakeries, confectioners, and dairy processors drive standard-grade lecithin consumption, with procurement teams prioritizing deforestation-free supply chain certification under EU regulation.
- Cosmetic Companies:Formulation houses in France and Germany specify organic-certified and palm-free emulsifiers for premium skincare lines, accepting price premiums for traceable sunflower and rapeseed origins.
- Healthcare Providers:Hospital nutrition services and clinical feeding programs source protein-based emulsifiers for hypoallergenic enteral formulas.
- Dietary Supplement Producers:Softgel manufacturers and functional food brands purchase lecithin as both processing aid and label-declared active ingredient.
Food manufacturers command existing contract volumes. Cosmetic companies are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery procurement teams in Germany, France, and the Netherlands concentrate the steepest demand for clean-label emulsifier transitions. REACH registration deadlines and EU Green Deal compliance requirements filter supplier access across these markets.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive reformulation away from DATEM and SSL toward plant-based crystallization controllers. ECHA's REACH registration requirements for synthetic additives accelerate manufacturer transitions to lecithin alternatives. Munich and Hamburg anchor chocolate and margarine production clusters where enzymatic modification technologies gain procurement priority.
France
Premium skincare formulators in Île-de-France substitute petrochemical surfactants with sunflower lecithin and saponified oils. ANSM cosmetic ingredient guidelines pressure synthetic emulsifier abandonment in organic-certified product lines. Lyon and Marseille concentrate contract manufacturing for export-oriented personal care brands seeking palm-free supply chains.
Netherlands
Mid-sized bakery groups establish direct procurement relationships with sunflower and rapeseed crushing cooperatives. EU deforestation regulation alignment demands certified sustainable feedstock documentation from Rotterdam and Amsterdam distribution hubs. Eindhoven's food technology corridor hosts emulsifier-blend R&D facilities serving Benelux industrial bakers.
Belgium
Specialty chocolate manufacturers in Flanders adopt enzymatically modified lecithins for precise tempering control. EFSA novel food assessment timelines for new protein sources delay commercialization versus FDA pathways, compressing innovation cycles. Brussels anchors regulatory compliance consulting for pan-European ingredient suppliers.
Switzerland
Pharmaceutical-grade phospholipid demand from Basel's drug delivery specialists concentrates premium lecithin procurement. Swissmedic's GMP documentation requirements exceed ISO 22000 standards, filtering supplier pools for liposomal formulation applications. Geneva's nutraceutical softgel manufacturers source traceable choline supplementation ingredients.
Plant-Based Emulsifiers Market Competitive Landscape
Player mix skews toward integrated agricultural processors and specialized emulsifier-blend formulators. Market structure concentrates around upstream oilseed crushers with captive lecithin extraction and downstream ingredient houses with enzymatic modification capabilities. Three archetypes dominate: backward-integrated agribusiness conglomerates, Scandinavian R&D-specialized emulsifier houses, and enzymatic technology licensors. Competitive moves center on direct procurement relationship displacement and precision fermentation capacity positioning.
Within the integrated processor tier, Cargill, Incorporated and Bunge Limited exemplify upstream control over oilseed crushing infrastructure that secures feedstock economics for standard-grade lecithin supply. Palsgaard A/S occupies a position among specialized Scandinavian formulators with dedicated emulsifier-blend research facilities. DuPont de Nemours, Inc. represents the enzymatic modification technology vector, anchoring protein-based emulsifier functionality expansion for allergen-sensitive applications.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Palsgaard A/S |
| Cargill, Incorporated |
| Bunge Limited |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| AAK AB |
| Kerry Group plc |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles at Rotterdam distribution hubs concentrate pricing power with crushing cooperatives holding certified sustainable feedstock stocks. Argentine drought-induced soy lecithin shortages tighten spot availability. German and Dutch manufacturers absorb cost pass-throughs through long-term offtake structures.
Pricing Analysis
Cost-plus contracts indexed to Rotterdam vegetable oil futures dominate industrial lecithin procurement. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications reflects certification burden and endotoxin documentation. Pricing pressure stems from sunflower and rapeseed premiums under EU deforestation regulation alignment. Mass-market confectioners exhibit highest price sensitivity; pharmaceutical buyers accept premiums for traceability.
Supply Chain Analysis
Inventory compression to forty-five days at Benelux bakery premix operations signals just-in-time adoption. Supply concentrates in Argentina, Brazil, and Ukraine for soybean feedstock; France and Germany for rapeseed and sunflower crushing. Phospholipid extraction draws from oilseed crushing byproducts, enzymatic modification catalysts, and solvent recovery systems. Single-source vulnerability runs through Argentine soy lecithin flows. Distribution runs through Rotterdam and Hamburg bulk liquid terminals to chocolate and margarine clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between FDA GRAS self-affirmation and EFSA novel food pathways fragments vendor selection criteria, creating specialist niches for compliance-native suppliers.
For Market Incumbents: Shield installed base relationships by accelerating ISO 22000 certification at co-manufacturing partners before 2027 REACH registration deadlines. Deepen backward integration into sunflower crushing in France and rapeseed processing in Germany to capture deforestation-free premiums. Precision fermentation capacity positioning defends against microbial phospholipid disruptors. For New Entrants and Emerging Players: Differentiate on enzymatic modification capabilities for customized phospholipid profiles in Belgian and Swiss specialty chocolate. Target personal care formulators in France seeking palm-free, organic-certified emulsifiers with traceable supply chains. Lead with direct procurement partnerships crushing cooperatives in the Netherlands to bypass established distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between FDA and EFSA approval timelines creates acquisition targets with stranded novel-food dossiers. Focus on Scandinavian R&D-specialized emulsifier houses with enzymatic technology platforms. Watch EFSA novel food approval velocity as inflection signal for protein-based emulsifier commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill leverages Argentine and Brazilian infrastructure to secure captive lecithin feedstock economics. |
| Enzymatic Modification Technology Licensing | DuPont deploys protein hydrolysis platforms to expand allergen-free emulsifier functionality in infant nutrition. |
| Precision Fermentation Capacity Buildout | Microbial phospholipid production bypasses agricultural drought exposure for pharmaceutical-grade supply security. |
| EU Deforestation Regulation Certification Program | Sunflower and rapeseed lecithin from French and German crushers captures ethical sourcing price premiums. |
| Direct Procurement Partnership with Cooperatives | Dutch bakery groups displace traditional distributors through long-term offtake agreements with regional crushers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food registers, REACH registration dossiers, and oilseed trade flow databases. Interview program covered emulsifier procurement managers at German industrial bakeries, formulation scientists at French cosmetic houses, regulatory affairs leads at ingredient suppliers, and crushing cooperative commercial directors. Secondary validation drew from ECHA substance registrations, EU customs declarations, and food manufacturer SEC filings. Bottom-up volume estimates triangulated against top-down oilseed processing capacity assessments.
Segmentation dimensions modeled span product chemistry (lecithin, proteins, gums, starches), application channel (food and beverages, personal care, pharmaceuticals, nutraceuticals), physical form (liquid, powder, granulated, paste), and end-user certification requirements (ISO 22000, GMP, organic, deforestation-free). CAGRs derived from weighted-average growth across application channels, with bakery sector reformulation velocity and personal care substitution rates as key demand-side inputs. Supply-side constraints incorporated oilseed yield volatility and enzymatic capacity expansion schedules.
Material uncertainties — Argentine drought recurrence, EFSA assessment timeline extensions, precision fermentation scale-up delays — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance deadlines and clean-label mandate adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
US Food Emulsifiers Market