
 Cakes, Pastries, and Sweet Pies Market | 2026-2036
Cakes, Pastries, and Sweet Pies Market Size, Share, and Industry Trends Forecast 2026-2036
Cakes, Pastries, and Sweet Pies Market Insights
European artisan bakeries is rebalancing toward scaled production without sacrificing craft positioning. Grupo Bimbo S.A.B. de C.V. leverages its pan-Regional American manufacturing footprint to standardize recipes across diverse markets. Yamazaki Baking Co., Ltd. anchors its strategy in Japanese convenience-store channels with shelf-stable innovation. McKee Foods Corporation specializes in long-tradition American snack cakes with deep grocery distribution.
Cakes, pastries, and sweet pies comprise flour-based baked goods leavened chemically or mechanically, filled or topped with sweet compositions, and finished through baking or chilling processes to achieve specified moisture content and structural stability. Their primary commercial purpose spans celebratory foodservice, retail impulse purchase, and home consumption occasions across demographic segments. Birthday cakes and cupcakes command the largest revenue pools in the product-type dimension, sustained by recurring personal celebrations and social-media-driven customization. The distribution-channel structure privileges supermarkets for volume while online retail captures the fastest incremental growth, particularly for occasion-based gifting.
The FDA governs ingredient declarations and allergen labeling for products entering the United States, while the EFSA enforces additive restrictions and nutritional-claim substantiation across European markets. Japan's Ministry of Health, Labour and Welfare administers food-sanitation standards that constrain import formulations and domestic production protocols. Stakeholders must monitor evolving sugar-tax proposals and front-of-pack labeling mandates that threaten margin structures in multiple developed markets.
Market Dynamics
Clean-label mandates from the FDA and EFSA are forcing wholesale recipe reformulation across premium bakery portfolios, compressing shelf-life targets while elevating ingredient costs for manufacturers serving developed markets.
Growth Catalysts
- Convenience-store channel expansion:Japanese retailers are scaling shelf-stable pastry assortments to capture impulse occasions outside traditional bakery hours.
- Front-of-pack labeling mandates:EU Green Deal nutritional transparency rules are accelerating clean-label R&D investment among reformulation teams.
- Social-media-driven customization:Visual-first cake design tools are pulling demand toward artisan-positioned products in urban United States markets.
Market Restraints
- Wheat and dairy input volatility:Commodity price swings compress margin structures for mid-tier producers lacking long-term supply contracts.
- Sugar-tax proposals:Legislative drafts in multiple United States statehouses threaten volume elasticity for mass-market sweet pie categories.
- Artisan production bottlenecks:Hand-finishing constraints limit output scaling for craft-positioned brands competing with industrial volumes.
Strategic Opportunities
- Untapped German convenience retail:Bakery chains can replicate Japanese shelf-stable models in underserved fuel-station and transit-hub channels.
- Plant-based fat systems:Converging enzyme technology with oleogel science enables clean-label alternatives to hydrogenated shortenings.
- Gifting platform integration:Direct-to-consumer occasion-based purchasing via specialized e-commerce portals bypasses supermarket slotting fees.
Industry Challenges
- Certified artisan credentialing delays:Third-party craft verification programs create compliance bottlenecks for scaled production facilities.
- Legacy ERP integration friction:Traceability software for allergen management conflicts with decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cakes, Pastries, and Sweet Pies Market |
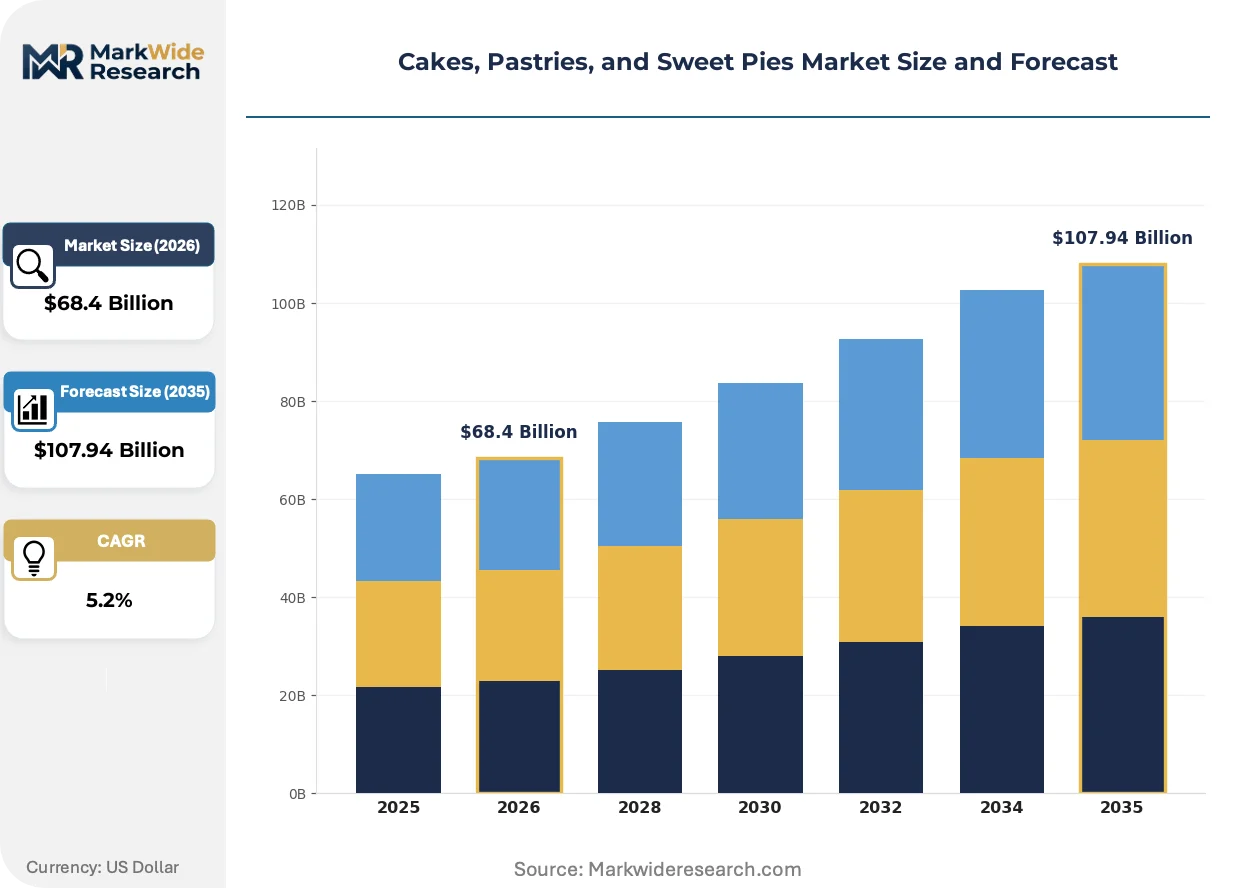
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Birthday Cakes, Cheesecakes, Cupcakes, Tarts Ingredient: Flour, Sugar, Eggs, Dairy Occasion: Weddings, Birthdays, Holidays, Celebrations Distribution Channel: Bakeries, Supermarkets, Online Retail, Cafés |
| Companies Covered | Finsbury Food Group, McKee Foods Corporation, Grupo Bimbo S.A.B. de C.V., General Mills Inc., Rich Products Corporation, Yamazaki Baking Co., Ltd., Mondelez International, Flower Foods, J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cakes, Pastries, and Sweet Pies Market Trends and Innovations
Active fermentation control systems and precision humidity baking are compressing production variance while enabling consistent artisan outputs at industrial scale.
Precision fermentation-derived dairy proteins are overtaking conventional butter and cream in premium layer cake formulations. United States craft bakeries with sustainability commitments are adopting these ingredients at accelerating rates. This shift is compressing the price premium between plant-forward and traditional dairy-based positioning.
EFSA additive restriction updates are narrowing the approved palette of emulsifiers and preservatives for cross-border European distribution. Industrial bakeries serving multiple member states are consolidating recipes around the strictest national interpretation. Frozen unbaked dough formats are gaining share as manufacturers defer final processing to in-country facilities.
Subscription-based cake gifting is displacing one-off retail purchases for milestone celebrations. United States millennials and Gen Z consumers are routing demand through specialized online portals that coordinate delivery logistics. This pattern concentrates volume with platforms possessing captive logistics networks rather than traditional grocery channels.
Cakes, Pastries, and Sweet Pies Market Segmentation
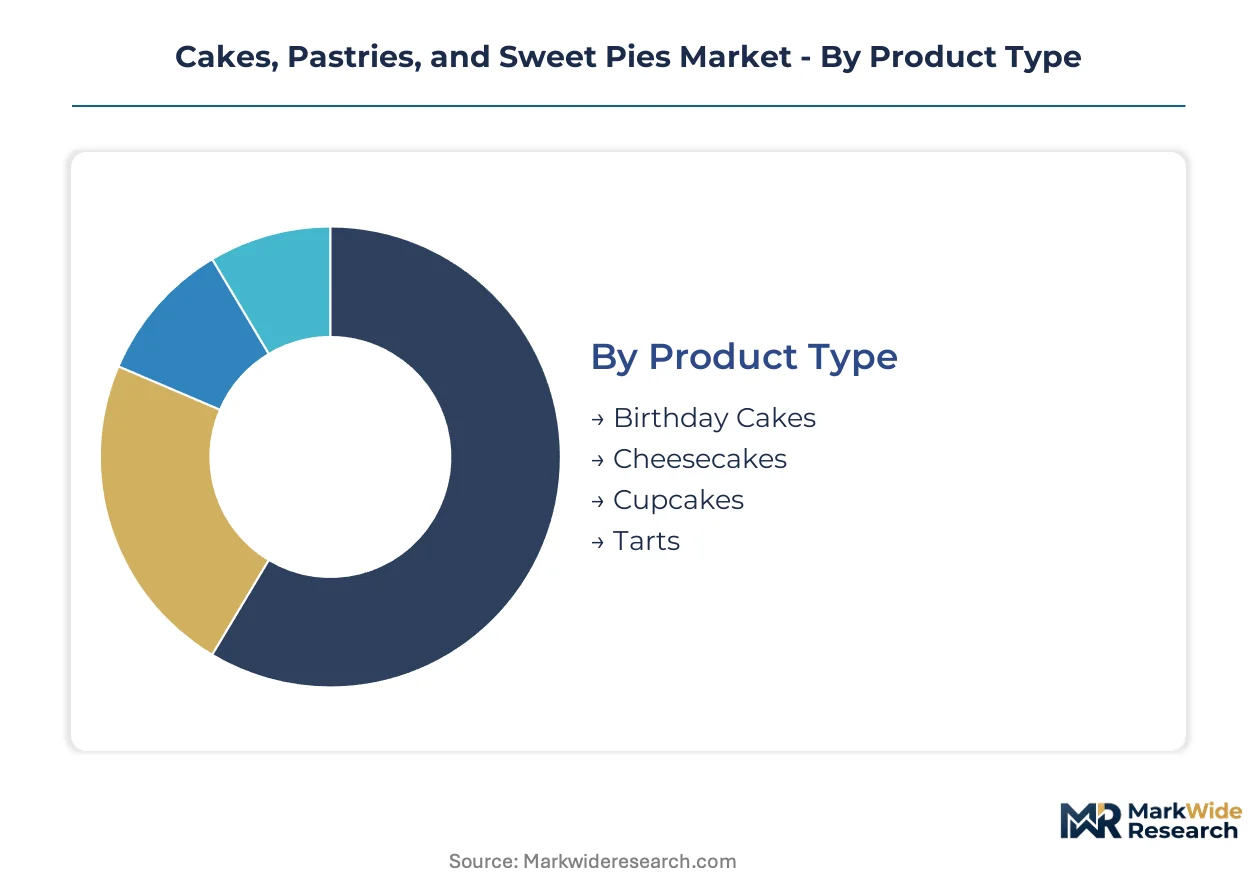
Segmentation in this market reveals distinct upgrade cycles across consumption occasions and channel preferences. Manufacturers calibrate formulation complexity and packaging formats to match the frequency and emotional intensity of specific use cases.
Product Type:
Replacement cycles accelerate where social-media visibility drives repeat purchase pressure.
- Birthday Cakes:Multi-layer sponge constructions with fondant or buttercream finishes dominate celebratory foodservice. United States urban markets concentrate demand for customized designs, with Instagram-worthy aesthetics commanding premium pricing over standard offerings.
- Cheesecakes:Dense curd-based formulations require precise temperature control and extended chilling protocols. Japanese convenience-store channels favor individual-portion formats with extended shelf stability, displacing traditional bakery purchases for impulse occasions.
- Cupcakes:Single-serve portion control aligns with grab-and-go retail strategies.
- Tarts:Shortcrust shells with fruit or custard fillings serve pastry-forward café menus.
Volume placements concentrate in birthday cakes; the faster expansion belongs to cheesecakes.
Ingredient:
Cost tier stratification separates commodity inputs from specialty sourcing that commands margin premiums.
- Flour:Wheat-based structures provide the gluten network essential for cake crumb and pastry lamination. German artisan bakeries are sourcing heritage grain varieties to differentiate craft positioning against industrial competitors.
- Sugar:Sucrose and alternative sweeteners influence moisture retention and browning chemistry. EFSA additive restrictions are forcing reformulation teams to reduce reliance on high-intensity sweeteners in cross-border European products.
- Eggs:Protein foam stability determines cake rise and meringue texture outcomes.
- Dairy:Butter and cream contribute fat structure and flavor depth to premium formulations.
Flour commands the largest procurement volumes; dairy ingredients are climbing the fastest as clean-label butter substitutes gain traction.
Occasion:
Application frequency determines production scheduling and inventory risk exposure for manufacturers.
- Weddings:Tiered fondant constructions with structural internal supports require specialized logistics and on-site assembly. United States metropolitan markets sustain year-round demand through destination wedding tourism and diverse cultural celebration calendars.
- Birthdays:Recurring annual demand provides predictable revenue baselines for retail bakeries. Japanese consumers are shifting toward pre-ordered customized designs through specialized online portals, reducing last-minute supermarket purchases.
- Holidays:Seasonal peaks strain production capacity and require temporary labor scaling.
- Celebrations:Corporate and milestone events drive large-format orders with extended lead times.
Birthday occasions anchor baseline production volumes; wedding applications are gaining share fastest through premium positioning.
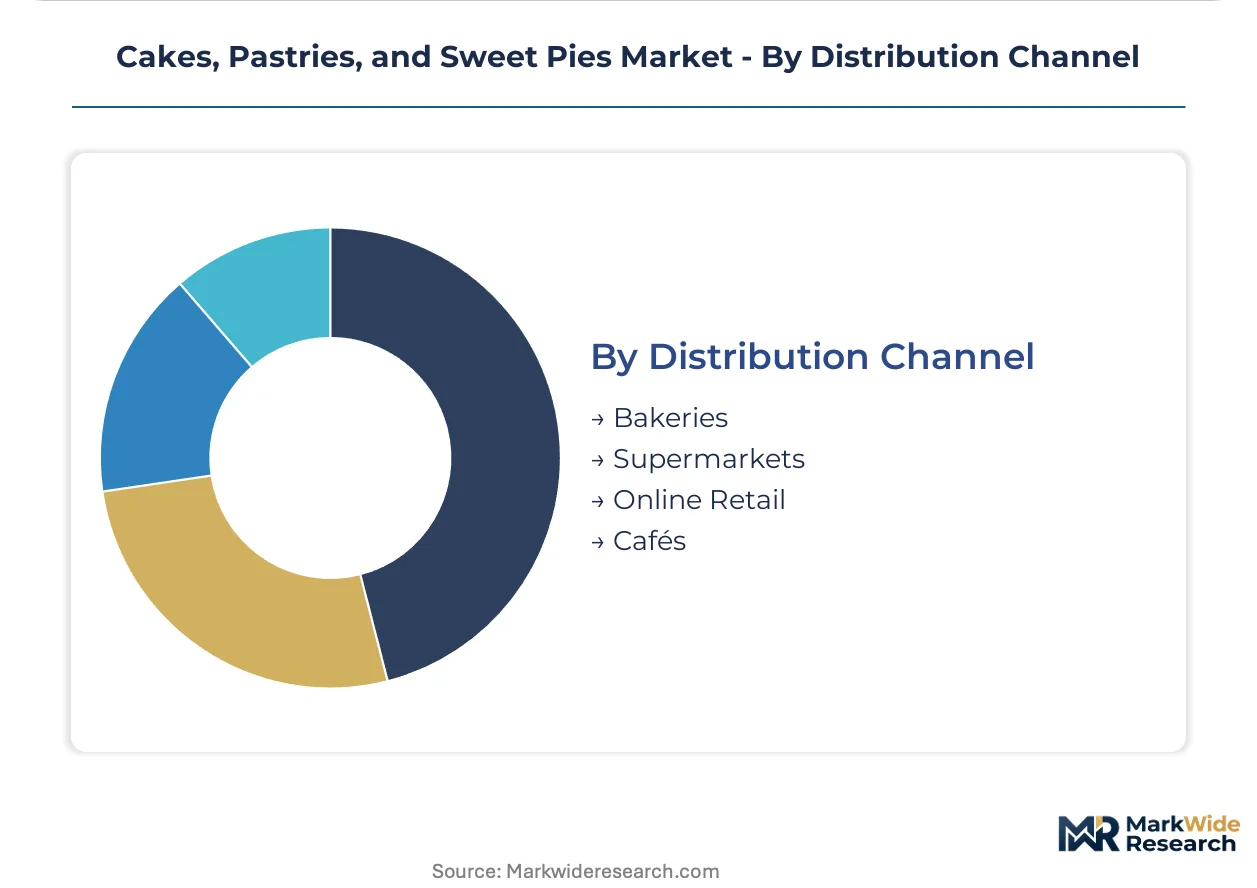
Distribution Channel:
Customer type fragmentation separates impulse purchasers from planned occasion buyers with divergent price sensitivities.
- Bakeries:Fresh-daily production with visible finishing operations supports artisan credentialing. German high-street locations are integrating mobile ordering to reduce queue abandonment during morning rush periods.
- Supermarkets:Centralized production with extended shelf-life packaging captures price-conscious household purchasing. United States mass retailers are expanding in-store bakery footprints to compete with specialty chains on convenience.
- Online Retail:Direct-to-consumer logistics coordinate delivery timing with celebration dates.
- Cafés:Companion purchase placement alongside beverage sales drives incremental pastry volume.
Supermarkets maintain the deepest volume penetration; online retail is expanding most quickly for gifting-oriented purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat cultivation in the North American Great Plains and the European Black Sea corridor anchors flour supply chains for industrial baking operations. Climate volatility across these breadbaskets is compressing harvest predictability and elevating procurement hedging costs for manufacturers.
United States
Urban millennials drive demand for Instagram-optimized cake customization through specialized e-commerce portals. The FDA enforces updated allergen labeling rules that compress reformulation timelines for cross-state distributors. Brooklyn and Los Angeles host dense clusters of craft bakeries scaling precision-fermentation dairy alternatives.
Germany
Heritage grain sourcing distinguishes artisan positioning against industrial competitors in saturated retail channels. EFSA additive restrictions under the EU Green Deal narrow approved emulsifier palettes for pan-European product lines. Munich and Hamburg convenience-store chains are piloting Japanese-style shelf-stable pastry formats.
Japan
Convenience-store channel penetration captures impulse occasions outside traditional bakery operating hours. The Ministry of Health, Labour and Welfare administers food-sanitation standards that constrain import formulation flexibility. Tokyo and Osaka anchor R&D activity for extended-shelf-life cheesecake portioning technologies.
United Kingdom
Subscription-based gifting platforms displace supermarket purchasing for milestone celebration occasions. Front-of-pack labeling mandates accelerate clean-label R&D investment among reformulation teams. London and Manchester concentrate venture-backed direct-to-consumer bakery logistics networks.
France
Destination wedding tourism sustains year-round demand for tiered fondant construction specialists. ANSM enforces strict additive notification requirements for imported confectionery formulations. Paris and Lyon high-street locations integrate mobile ordering to reduce queue abandonment during morning rush periods.
Cakes, Pastries, and Sweet Pies Market Competitive Landscape
Global majors compete with regional champions across distribution-channel access and formulation patent portfolios. Market structure fragments between pan-regional conglomerates with centralized manufacturing and national specialists with localized craft credentials. Three archetypes dominate: scale-driven industrial bakers, convenience-channel integrators, and artisan-positioned premium brands. Capacity expansion and strategic licensing agreements constitute the primary competitive vectors.
Within the scale-driven tier, Grupo Bimbo S.A.B. de C.V. and Yamazaki Baking Co., Ltd. exemplify geographic diversification strategies. McKee Foods Corporation occupies a position anchoring American snack-cake heritage positioning. Finsbury Food Group represents European specialist consolidation. General Mills Inc. and Mondelez International sit within the multinational packaged-foods archetype with cross-category leverage.
| Leading Market Players |
|---|
| Finsbury Food Group |
| McKee Foods Corporation |
| Grupo Bimbo S.A.B. de C.V. |
| General Mills Inc. |
| Rich Products Corporation |
| Yamazaki Baking Co., Ltd. |
| Mondelez International |
| Flower Foods |
| J.M. Smucker Company |
| Others |
Pricing and Supply Chain Analysis
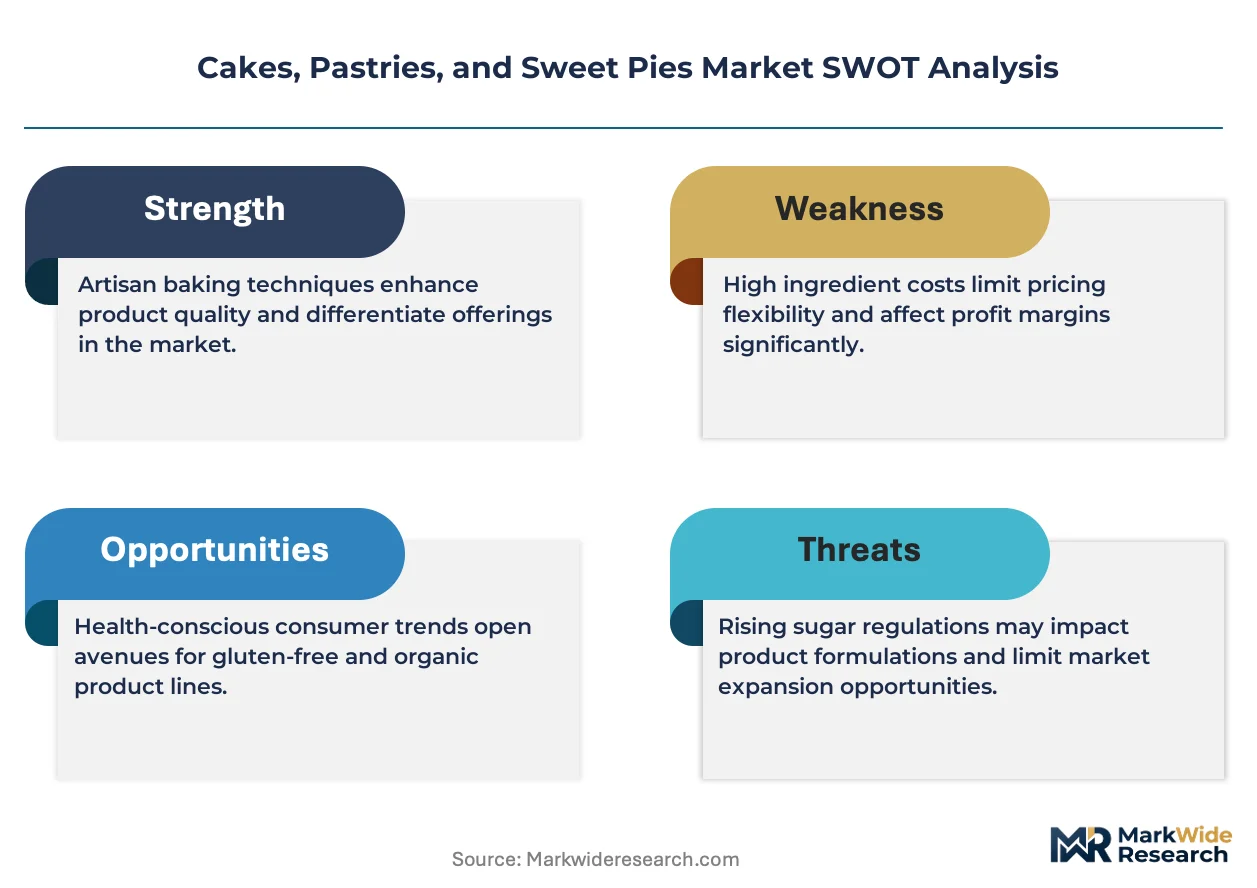
EU Green Deal nutritional transparency mandates gate qualified supply access and premium-tier pricing power for cakes, pastries, and sweet pies manufacturers. Reformulation compliance costs compress mid-tier margins while elevating clean-label product premiums in developed markets.
Pricing Analysis
Warranty-style freshness guarantees and unbundled customization fees structure transactional pricing across manufacturer tiers. Three-tier pricing separates artisan-credentialed offerings from standard retail formats from economy private-label lines. Price differentiation rests on clean-label certification grade and geographic delivery radius. Cost compression in economy tiers is intensifying because wheat and dairy commodity volatility erodes contract-based margin protection. Mass-market supermarket buyers exhibit highest price sensitivity; wedding and corporate celebration segments show lowest elasticity.
Supply Chain Analysis
Clean-label certification and third-party artisan credentialing gate supplier qualification for premium channel access. Wheat sourcing concentrates in the United States Great Plains and European Black Sea corridor; dairy inputs draw from New Zealand, Germany, and the Netherlands. Supply chain risk centers on single-source vulnerability for heritage grain varieties and precision-fermentation dairy proteins. Distribution runs through centralized industrial bakeries serving supermarket networks, with direct-to-consumer platforms capturing fastest incremental growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA additive restrictions under the EU Green Deal construct a cost-of-compliance moat that rewards pre-invested clean-label manufacturers and filters out undercapitalized competitors.
For Market Incumbents: Lock in multi-year heritage grain supply contracts before climate volatility escalates procurement hedging costs. Acquire precision-fermentation dairy technology capabilities to defend premium positioning against plant-forward entrants. Channel control through captive convenience-store partnerships in Japan and Germany limits competitor shelf access. For New Entrants and Emerging Players: FDA updated allergen labeling rules in the United States opens a window for specialized clean-label contract manufacturers serving mid-tier brands lacking reformulation infrastructure. Target German fuel-station and transit-hub channels with Japanese-style shelf-stable pastry formats. Pursue direct-to-consumer gifting platform partnerships to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Accelerating adoption of precision-fermentation dairy proteins by United States craft bakeries is the leading indicator that sustainability-committed premium positioning will consolidate market share. Five-to-ten year viability favors scaled manufacturers with backward-integrated ingredient supply and certified clean-label portfolios. Watch for sugar-tax legislative advancement in United States statehouses as volume elasticity inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA-compliant recipe consolidation enables pan-European distribution without national variation. |
| Heritage Grain Supply Contracting | Long-term offtake agreements with Black Sea and Great Plains growers hedge climate volatility exposure. |
| Precision-Fermentation Dairy Integration | In-house production of butter and cream alternatives compresses sustainability premium pricing gaps. |
| Convenience-Store Channel Expansion | Japanese-style shelf-stable formats in German transit hubs capture impulse occasions outside bakery hours. |
| Direct-to-Consumer Gifting Platform Launch | Specialized e-commerce portals bypass supermarket slotting fees for occasion-based celebration purchases. |
Research Methodology
Document review covered FDA filings, EFSA additive restriction updates, customs and trade data, and Nielsen retail audit records, complemented by interviews with bakery operations directors, retail category buyers, supply chain planners, and clean-label R&D leads. Bottom-up demand modeling triangulated against top-down macroeconomic indicators validated volume and value estimates across the analysis window.
Output projections span product type, ingredient tier, occasion category, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-level growth rate blending weighted by base-year revenue contribution. Model inputs incorporate wheat and dairy commodity price trajectories, regulatory compliance cost curves, and channel shift elasticity parameters specific to celebration-driven purchasing patterns.
The model assumes a particular technology adoption path; alternative pathways for precision-fermentation dairy protein scaling would alter the outlook for premium-tier margin compression. Forecasts reflect assumptions regarding EFSA enforcement consistency and United States state-level sugar-tax legislative progression. A model refresh is warranted upon material change in clean-label certification standard harmonization across European member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Matcha Cookie Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Frozen Bakery Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Teaseed Cake Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Pizza Crust Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Lentil Bread Market
Bakery Products
Toasted Flour Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
India Cake Market
Bakery Products
Low Fat Bran Muffins Market