
 One-Off Chopsticks Market | 2026-2036
One-Off Chopsticks Market Size, Share, and Industry Trends Forecast 2026-2036
One-Off Chopsticks Market Intelligence
Foodservice distribution through Asian wholesale supply networks is rewriting how one-off chopsticks reach end buyers. Besta Bamboo Machine Co. Ltd. leverages its machinery expertise to anchor production efficiency across Chinese manufacturing bases. Ngoc Chau Enterprise Pte competes through Vietnamese sourcing corridors that sustain cost advantages in bamboo raw material. Pacific East Company controls North American import channels, extending its reach into restaurant supply chains.
One-off chopsticks are single-use eating utensils typically measuring 210-240 millimeters in length, manufactured from bamboo splits, wood veneers, or molded pulp, designed for immediate disposal after one meal service. Bamboo material dominates commercial procurement due to its tensile strength and rapid regrowth cycle, while pulp alternatives gain traction where composting infrastructure exists. Disposable product types occupy the largest volume share across takeout usage segments, though biodegradable variants command margin premiums in regulated European markets. Wooden chopsticks retain stable demand within full-service restaurant channels where aesthetic presentation carries weight.
China's MEE enforces dual carbon goals that restrict virgin plastic in foodservice disposables, redirecting factory output toward certified bamboo and pulp substrates. The EU Green Deal and F-Gas Regulation indirectly pressure importers through embedded carbon accounting, while Japan's METI promotes JIS standards for imported wooden tableware. Stakeholders must monitor evolving compostability certifications and border carbon adjustments that will determine which material formats retain market access.
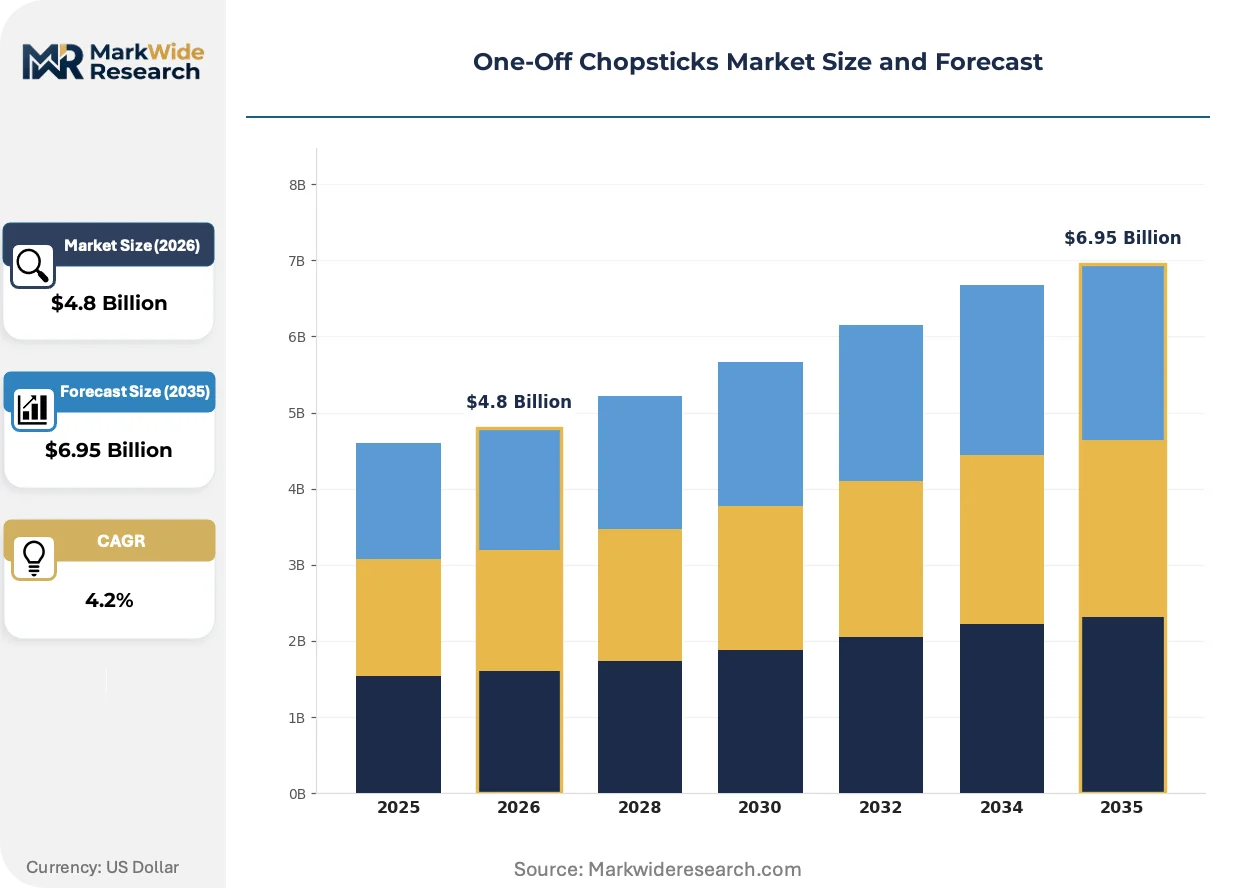
Market Dynamics
China's MEE dual carbon goals are compressing virgin plastic output across foodservice disposables, forcing factory retooling toward certified bamboo and molded pulp substrates while redirecting raw material procurement toward Vietnamese and Indonesian supply corridors.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian QSR chains are standardizing disposable utensil protocols across franchised locations, driving bulk procurement contracts for bamboo splits.
- EU Green Deal compliance pressure:Embedded carbon accounting under the EU Green Deal and F-Gas Regulation is filtering non-certified imports from European foodservice distribution channels.
- Composting infrastructure maturation:Municipal composting programs in regulated European markets are creating certified disposal pathways for pulp-based alternatives.
Market Restraints
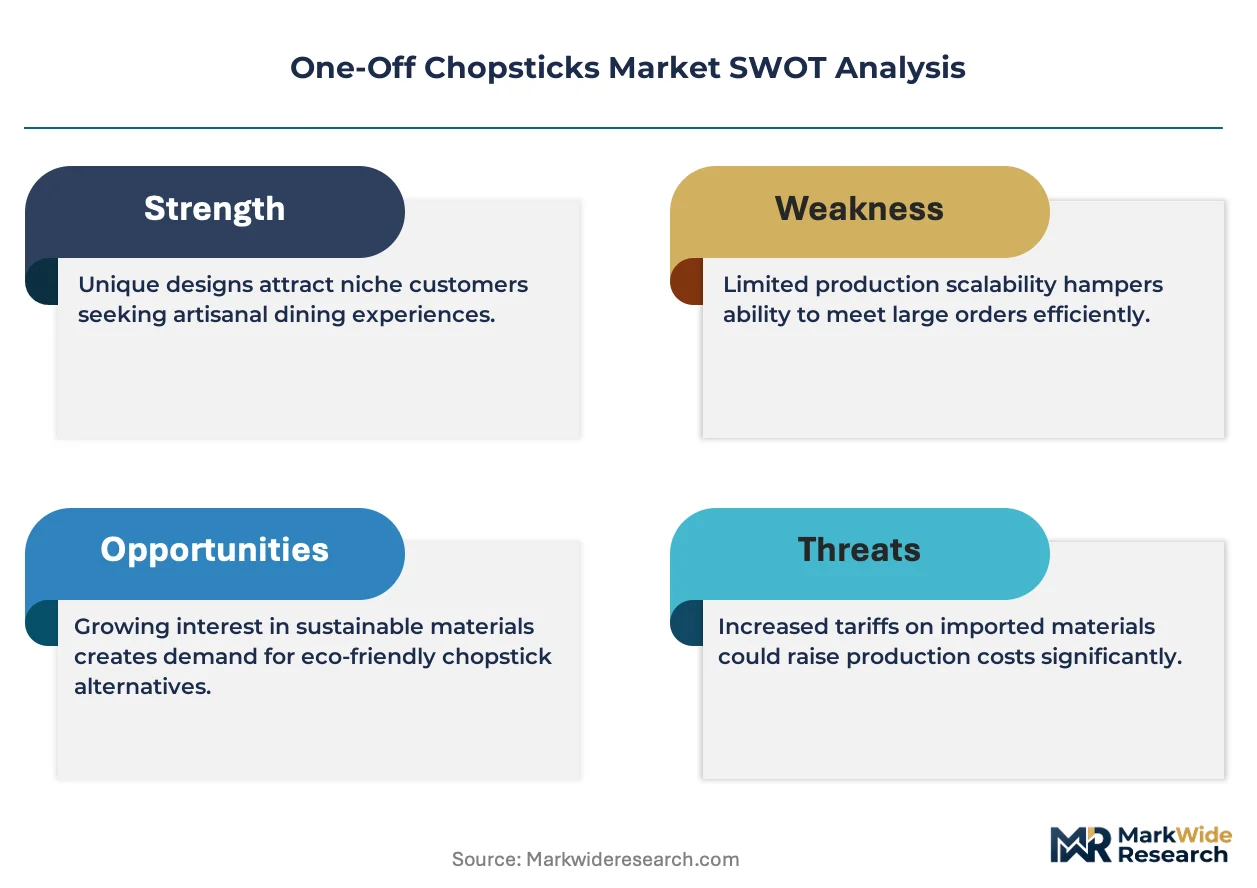
- Bamboo raw material cost volatility:Weather-driven supply fluctuations across Guangxi and Fujian provinces are compressing margins for manufacturers dependent on domestic Chinese splits.
- Supply concentration risk:Ho Chi Minh City manufacturing clusters control disproportionate export volume, exposing buyers to single-point disruption from Vietnamese logistics bottlenecks.
- Technical limitation in pulp durability:Molded pulp alternatives exhibit tensile weakness in high-temperature soup applications, restricting substitution in full-service Asian restaurant channels.
Strategic Opportunities
- Underpenetrated North African markets:Morocco and Tunisia's emerging Asian foodservice sectors lack established disposable utensil supply chains, creating first-mover distribution advantages.
- Regulatory tailwind from Japan's METI:JIS standard promotion for imported wooden tableware is opening certified procurement pathways for compliant Vietnamese and Chinese exporters.
- Direct-to-restaurant platform distribution:Digital wholesale platforms are disintermediating traditional import-distributor networks, enabling factory-direct relationships with mid-size restaurant groups.
Industry Challenges
- Certification timeline compression:EU compostability certification cycles under evolving EN standards are delaying product launches by 8-14 months for pulp substrate variants.
- Skilled machinery operation deficit:Automated bamboo splitting and veneer processing equipment requires specialized technicians scarce in emerging Vietnamese manufacturing zones.
- Supply chain reconfiguration friction:Redirecting pulp sourcing from plastic-dependent suppliers to bamboo and agricultural fiber networks demands working capital restructuring for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | One-Off Chopsticks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Biodegradable, Plastic, Wooden Material: Bamboo, Pulp, Polypropylene, Paper Usage: Takeout, Restaurant, Catering, Events Size: Standard, Mini, Jumbo, Custom |
| Companies Covered | Besta Bamboo Machine Co. Ltd., Nanchang Sanyou Eco Technology Co. Ltd., Ngoc Chau Enterprise Pte, Pacific East Company, Agri-Dom, Blooming Wave Co., Changsha Bin Hong Import and Export Co. Ltd., Huasheng Group, Ningbo Qingfeng Bamboo Products Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
One-Off Chopsticks Market Strategic Shifts & Innovations
Material science advances and regulatory carbon accounting are converging to redefine competitive advantage in disposable foodservice utensils, with certification compliance becoming a stronger differentiator than unit cost.
Laser-guided bamboo splitting automation is rendering obsolete manual veneer processing lines that dominated production for decades. Japanese and South Korean restaurant supply importers are adopting these systems at accelerated replacement cycles. The technology is compressing labor cost differentials between Chinese and Vietnamese manufacturing bases.
The EU Green Deal's embedded carbon requirements are reshaping import qualification protocols for Asian disposable tableware. Factory auditors now trace energy inputs through supply chains to verify renewable sourcing claims. Pulp-based chopstick categories face the steepest compliance burden under evolving F-Gas Regulation indirect pressure.
Consolidated procurement by multinational QSR chains is displacing fragmented restaurant-level purchasing across Southeast Asian markets. Centralized supply contracts now specify certified bamboo grades and compostable pulp alternatives in unified regional tenders. Vietnam and Thailand display the most visible concentration of this buyer-side consolidation.
One-Off Chopsticks Market Segmentation
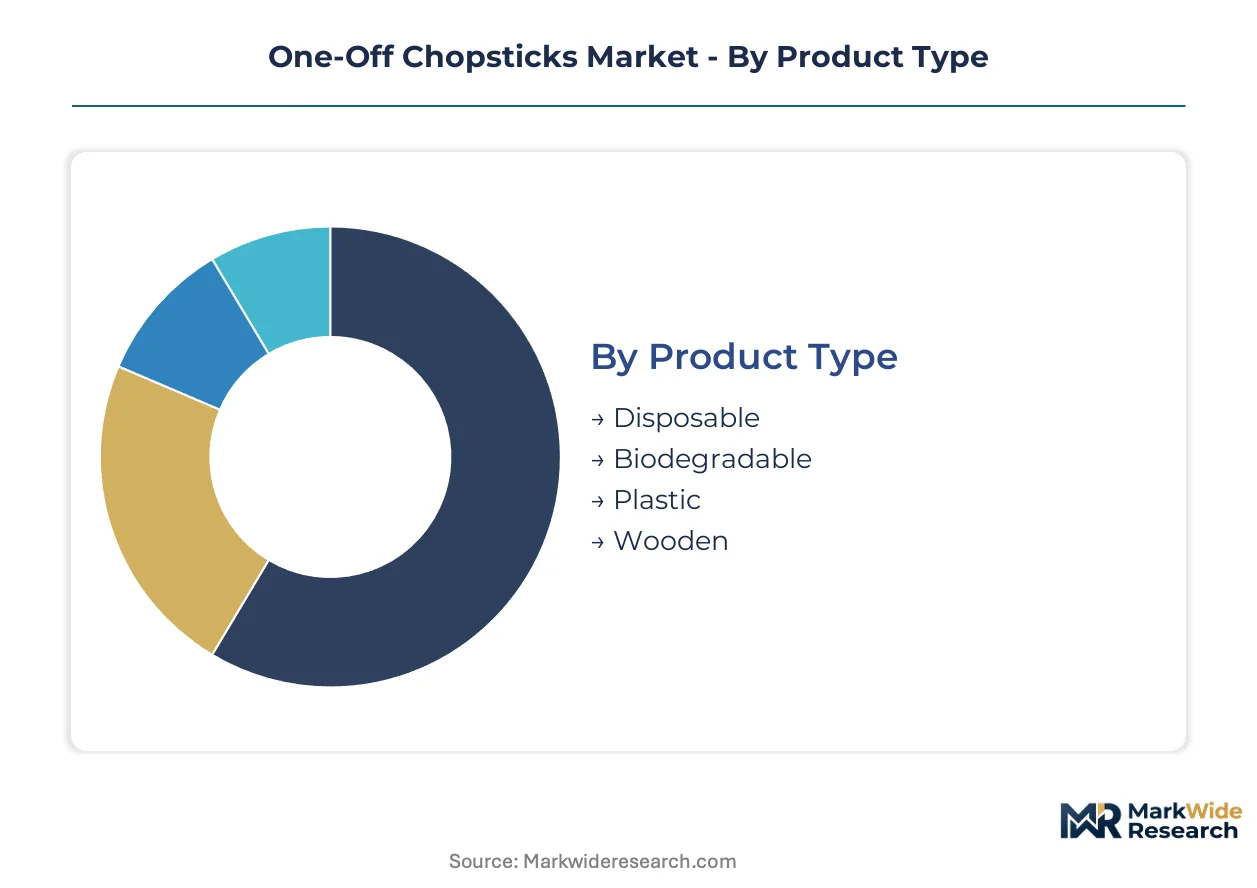
Material composition and disposal pathways determine margin structures across one-off chopstick procurement. Certification requirements and end-use durability demands fragment supply strategies by segment.
Product Type:
Cost tier stratification separates high-volume commodity supply from certified premium alternatives.
- Disposable:Single-use bamboo splits dominate QSR procurement across Southeast Asian franchised networks. Ho Chi Minh City manufacturing clusters supply standardized 210-240mm lengths under centralized regional contracts.
- Biodegradable:Molded pulp variants require EN compostability certification for EU market access. Municipal composting infrastructure in regulated European markets creates qualified disposal pathways that command procurement premiums.
- Plastic:Virgin polypropylene faces China's MEE dual carbon restrictions, compressing foodservice applications.
- Wooden:Veneer processing retains stable demand in full-service channels where aesthetic presentation influences table setting.
Disposable commands the established base. The steepest expansion runs through biodegradable.
Material:
Supply concentration shapes raw material procurement corridors and factory location decisions.
- Bamboo:Tensile strength and rapid regrowth cycles anchor commercial procurement. Guangxi and Fujian province weather fluctuations compress margins for domestic Chinese manufacturers.
- Pulp:Agricultural fiber sourcing demands working capital restructuring from plastic-dependent suppliers. F-Gas Regulation indirect pressure creates the steepest compliance burden under embedded carbon accounting.
- Polypropylene:Virgin plastic output faces MEE enforcement restricting foodservice disposables.
- Paper:Laminated constructions serve limited specialty applications with lower heat tolerance.
Bamboo anchors volume supply. Pulp is climbing the fastest on regulatory tailwinds.
Usage:
Application context dictates durability specifications and certification requirements.
- Takeout:High-volume standardized procurement by consolidated QSR chains displaces fragmented restaurant purchasing. Vietnam and Thailand display visible buyer-side concentration.
- Restaurant:Full-service channels specify aesthetic-grade wooden veneers or premium bamboo grades. JIS standards promoted by Japan's METI open certified pathways for compliant Vietnamese exporters.
- Catering:Event-scale bulk contracts prioritize unit cost over material certification.
- Events:Single-occasion procurement tolerates lower durability thresholds.
Restaurant usage maintains margin stability. Takeout is gaining share fastest on QSR expansion.
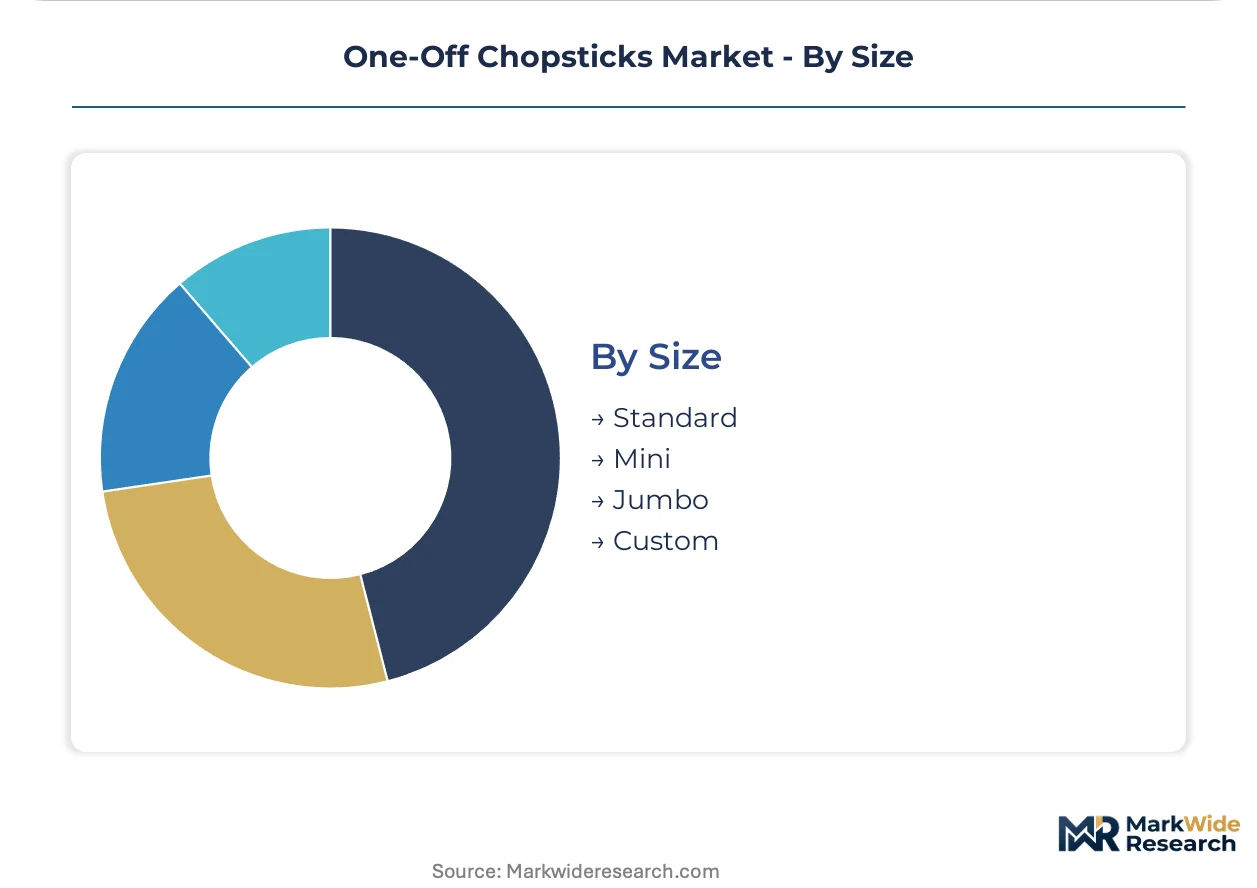
Size:
Dimensional specifications segment manufacturing equipment and raw material yield calculations.
- Standard:210-240mm lengths accommodate general foodservice applications across Asian and Western markets.
- Mini:Shortened formats serve dessert and appetizer courses in specialized restaurant segments.
- Jumbo:Extended lengths address cooking and serving functions beyond individual consumption.
- Custom:Branded or dimension-specific orders require flexible production lines with higher setup costs.
Standard sizes dominate production planning. Custom specifications carry the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors trans-Pacific container throughput for disposable bamboo tableware exports, while Vietnam's Cai Mep deepwater terminals handle Southeast Asian transshipment for Ho Chi Minh City manufacturing clusters.
China
Guangxi province bamboo plantations supply raw splits to Fujian processing mills under MEE dual carbon enforcement. The country's national environmental regulator restricts virgin plastic output across foodservice disposables, redirecting factory retooling toward certified substrates. Yangtze River Delta machinery manufacturers deploy laser-guided splitting automation that compresses labor cost differentials with Vietnamese competitors.
Vietnam
Ho Chi Minh City manufacturing clusters control disproportionate export volume for standardized 210-240mm bamboo chopsticks. The country's national trade and industry framework channels foreign direct investment toward bamboo processing zones near the Cambodian border. Binh Duong province industrial parks attract Chinese equipment transfers as manufacturers relocate from Guangxi.
Japan
METI JIS standards for imported wooden tableware open certified procurement pathways for compliant Vietnamese exporters. Tokyo and Osaka restaurant supply chains specify aesthetic-grade veneers in full-service channels. Kansai region import distributors consolidate purchasing power through centralized regional tenders.
United States
Pacific East Company controls West Coast import channels extending into restaurant supply chains across California and Washington. EPA state-level waste management frameworks create uneven composting infrastructure for pulp alternatives. Los Angeles and San Francisco Bay Area Asian foodservice corridors drive standardized disposable procurement.
Germany
EU Green Deal embedded carbon accounting filters non-certified imports through Rotterdam and Hamburg port gateways. ECHA REACH compliance documentation demands factory-level energy input tracing. Bavaria and North Rhine-Westphalia municipal composting programs create qualified disposal pathways for EN-certified pulp variants.
One-Off Chopsticks Market Key Industry Players
On the supply side, the industry is bifurcated between machinery-anchored Chinese manufacturers and sourcing-optimized Vietnamese exporters. Tiered competitive dynamics separate premium certified suppliers from commodity-grade volume producers. Strategic archetypes include equipment-integrated fabricators, raw material corridor controllers, and import channel specialists. Dominant competitive moves center on automated production line upgrades and backward integration into bamboo plantation assets.
Among Chinese machinery-integrated fabricators, Besta Bamboo Machine Co. Ltd. exemplifies equipment-driven production efficiency, while Nanchang Sanyou Eco Technology Co. Ltd. occupies a position within the certified substrate tier. Ngoc Chau Enterprise Pte represents Vietnamese sourcing corridor specialists that anchor cost advantages through proximity to Cambodian border plantations. Pacific East Company sits within the North American import channel archetype, controlling distribution pathways into restaurant supply networks.
| Leading Market Players |
|---|
| Besta Bamboo Machine Co. Ltd. |
| Nanchang Sanyou Eco Technology Co. Ltd. |
| Ngoc Chau Enterprise Pte |
| Pacific East Company |
| Agri-Dom |
| Blooming Wave Co. |
| Changsha Bin Hong Import and Export Co. Ltd. |
| Huasheng Group |
| Ningbo Qingfeng Bamboo Products Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Ho Chi Minh City manufacturing clusters compresses pricing power for buyers while amplifying margin volatility for producers across both premium certified and commodity disposable tiers. China's MEE dual carbon enforcement redirects raw material flows toward Vietnamese supply corridors, reshaping cost structures and procurement negotiations simultaneously.
Pricing Analysis
Volume-discount tiering structures separate multinational QSR procurement contracts from fragmented restaurant-level purchasing. Three-tier pricing stratifies across JIS-certified premium grades, standard bamboo splits, and economy pulp alternatives. Price differentiation hinges on compostability certification status and volume scale. Cost compression in standard disposable tiers intensifies because Guangxi weather fluctuations squeeze raw material yields. Mid-size restaurant groups exhibit highest price sensitivity, while full-service channels prioritize aesthetic-grade veneers over unit cost.
Supply Chain Analysis
Extended payment terms from consolidated QSR buyers strain working capital for mid-tier Vietnamese manufacturers lacking supply-chain finance facilities. Raw material procurement draws from Guangxi and Fujian province bamboo plantations, Cambodian border corridor splits, and Indonesian pulp fiber networks. Factory equipment sourcing rests on Yangtze River Delta machinery manufacturers. Single-source vulnerability concentrates in Ho Chi Minh City logistics chokepoints. Distribution runs through Pacific East Company-controlled West Coast channels and Rotterdam-Hamburg EU gateway ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quick-service restaurant standardization across Southeast Asian franchised networks signals early-cycle expansion, with municipal composting infrastructure maturation in regulated European markets accelerating certified product adoption.
For Market Incumbents: Insulate margin position through backward integration into Cambodian border bamboo plantation assets and laser-guided splitting automation that compresses labor cost differentials with Vietnamese competitors. MEE enforcement restricting virgin plastic output threatens traditional material suppliers. Certification investment in EN compostability standards opens premium procurement pathways. For New Entrants and Emerging Players: North African markets lack established disposable utensil supply chains despite emerging Asian foodservice sectors in Morocco and Tunisia. Direct-to-restaurant digital wholesale platforms enable factory-direct relationships disintermediating traditional import-distributor networks. Target certified pulp alternatives where municipal composting infrastructure creates qualified disposal pathways. For Investors and Strategic Acquirers: Machinery-anchored fabricators with automated production lines and equipment expertise represent compelling acquisition targets for portfolio exposure to efficiency-driven consolidation. Long-term viability centers on certification compliance capabilities rather than commodity volume scale. Monitor EU border carbon adjustment implementation as inflection indicator for material format market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Cambodian border bamboo corridors secure raw material cost advantages against Guangxi weather volatility. |
| Laser-Guided Splitting Automation Deployment | Yangtze River Delta machinery upgrades compress labor cost differentials with Vietnamese manufacturing bases. |
| EN Compostability Certification Investment | EU Green Deal embedded carbon accounting filters non-certified imports from Rotterdam and Hamburg gateways. |
| Direct-to-Restaurant Platform Distribution | Digital wholesale channels disintermediate Pacific East Company-controlled import-distributor networks. |
| JIS Standard Compliance Pathway | METI-promoted certification opens procurement access for Vietnamese exporters into Tokyo restaurant supply chains. |
Research Approach
Cross-validation between primary interviews with bamboo processing plant managers, QSR procurement leads, and EU import distributors anchors the qualitative findings against customs trade data, ECHA REACH compliance filings, and METI JIS standard documentation. Bottom-up volume modeling triangulates with top-down market sizing across material composition, product type, and usage segmentation dimensions.
Calibration against historical production capacity expansions and QSR franchise rollout trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, certification tier, end-use channel, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for MEE enforcement intensity and EU Green Deal implementation pace. Forecast inputs incorporate Ho Chi Minh City manufacturing cluster capacity utilization and municipal composting infrastructure deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive automation investment by Chinese machinery-integrated fabricators or sudden Vietnamese logistics disruption would shift outcomes. Macroeconomic deviation in Asian foodservice consumption, regulatory acceleration in carbon border adjustments, or breakthrough pulp durability technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Air Fryer Meal Kits Market
Food Service
Global Vending Machine Market
Food Service
Fast Food Market
Food Service
United States Full Service Restaurants Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Light Meal Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Food Delivery Services Market
Food Service
Food Away from Home Market
Food Service
Global Cafe and Bars Market
Food Service
India Quick Service Restaurant Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Food Contract Manufacturing Market
Food Service
Stirrers Market
Food Service
Global Food Retail Market