
 Europe Sustainable Office Furniture Market | 2026-2036
Europe Sustainable Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Office Furniture Market Foresight
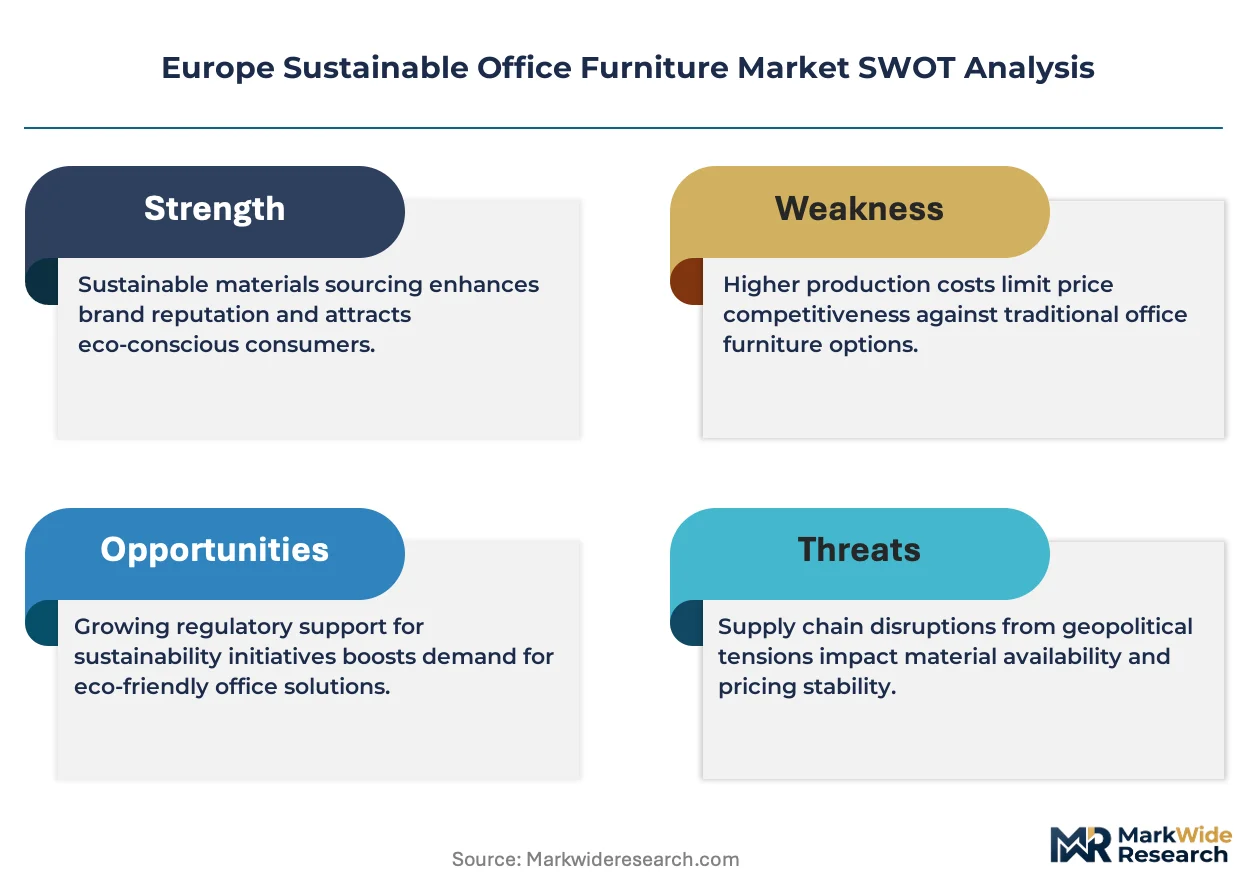
Green building certification expertise is bifurcating the competitive landscape into qualified and excluded suppliers. Kinnarps leverages its Nordic manufacturing footprint to dominate circular economy contracts in Scandinavia. Haworth Europe anchors its position through Cradle to Cradle certification depth across seating and desking lines. Vitra competes on design-architect relationships, sustaining premium positioning in cultural institution fit-outs.
Europe sustainable office furniture comprises workstations, seating, and storage systems manufactured with certified recycled content, low-emission finishes, and end-of-life recyclability protocols meeting EU Ecolabel criteria. Primary commercial purpose centers on reducing embodied carbon in commercial interiors while supporting WELL Building Standard indoor air quality targets. Recycled wood and steel materials command the deepest supply pools and tightest price transparency, while bioplastics occupy narrower but expanding niche applications. Modular design styles are capturing the fastest growth trajectory as corporations reconfigure floor plates for hybrid attendance patterns.
EU Green Deal implementation through Ecodesign for Sustainable Products Regulation and national building codes in Germany and France is mandating environmental product declarations and restricting hazardous substance thresholds. ECHA REACH compliance and FSC chain-of-custody certification now function as baseline market access requirements rather than differentiators. Stakeholders must monitor whether the EU AI Act extends into smart furniture sensor deployments and how CSRD reporting obligations reshape corporate buyer procurement scorecards.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is compressing certification timelines and forcing manufacturers to restructure supply chains around verified recycled content thresholds and digital product passports.
Growth Catalysts
- EU Green Deal procurement mandates:Public sector buyers in Germany and France now require EU Ecolabel compliance for furniture contracts above threshold values, redirecting institutional spend toward certified suppliers.
- Hybrid office reconfiguration cycles:Corporate real estate teams are replacing fixed workstations with modular systems that accommodate fluctuating attendance patterns and shorter lease commitments.
- WELL Building Standard adoption:Indoor air quality scoring is elevating demand for low-emission finishes and FSC-certified wood substrates in premium commercial fit-outs.
Market Restraints
- Recycled steel price volatility:Scrap metal supply fluctuations in Northern Europe are compressing margin predictability for desking and storage manufacturers.
- Baltic wood supply concentration:FSC-certified timber sourcing clusters in Estonia and Latvia create geographic vulnerability to shipping disruptions and certification audit backlogs.
- Bioplastic performance limitations:Bio-based polymers lack the structural durability for high-load seating applications, restricting their use to non-structural components.
Strategic Opportunities
- Netherlands circular economy infrastructure:Amsterdam and Rotterdam harbor zones offer established take-back and remanufacturing ecosystems for furniture-as-a-service models.
- CSRD reporting alignment:Corporate sustainability disclosure obligations are creating procurement scorecard demand for embodied carbon data that certified suppliers can monetize.
- Sensor-embedded furniture convergence:Integration of occupancy analytics with desking systems is opening premium pricing tiers for IoT-enabled sustainable workstations.
Industry Challenges
- EPD documentation bottlenecks:Third-party verified environmental product declarations require 8-14 month lead times, delaying contract eligibility for new product lines.
- Cross-border chain-of-custody complexity:FSC certification tracking across multi-country component sourcing is inflating compliance overhead for pan-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Office Furniture Market |
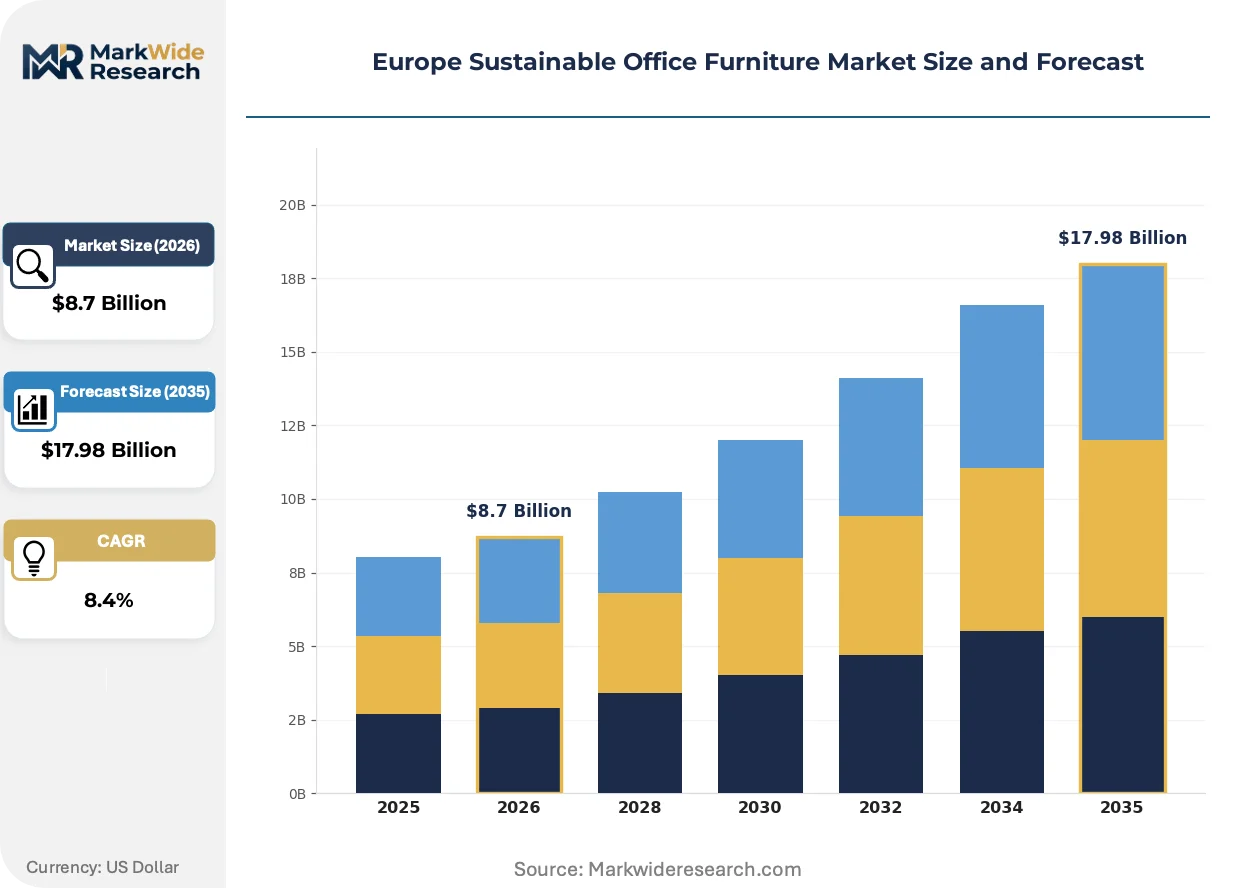
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units Material: Recycled Wood, Bamboo, Steel, Bioplastics Design Style: Modern, Minimalist, Ergonomic, Modular End User: Corporations, Startups, Educational Institutions, Home Offices |
| Companies Covered | Kinnarps, Haworth Europe, Herman Miller Europe, Vitra, Ahrend Group, Nowy Styl, Steelcase, Sedus Stoll, Inter Ikea Systems B V, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Office Furniture Market Shifts & Advancements
Digital product passports and modular design systems are converging to transform how furniture is specified, tracked, and recovered across commercial building lifecycles.
Embedded RFID and NFC tagging is miniaturizing across workstation and seating lines, enabling component-level tracking from manufacture through end-of-life recovery. Facility managers in Dutch and German corporate campuses are piloting these systems to automate inventory audits and remanufacturing scheduling. The technology is miniaturizing the cost and complexity of circular economy compliance, allowing mid-tier suppliers to compete for contracts previously reserved for vertically integrated manufacturers.
REACH authorization expansion for flame retardants and plasticizers is restricting chemical formulations used in upholstery foams and surface coatings. Manufacturers serving the French market face accelerated substitution timelines as ANSM enforces stricter substance thresholds than baseline EU requirements. Seating producers are responding by accelerating bio-based foam partnerships and reformulating finishes to preempt regulatory displacement.
Corporate buyers are unbundling furniture procurement from traditional dealer networks and contracting directly with manufacturers for multi-site fit-out programs. This disintermediation compresses margin capture for distribution intermediaries while rewarding suppliers with project management capabilities and carbon accounting transparency. The pattern is most pronounced in financial services and technology sector headquarters relocations across London, Frankfurt, and Paris.
Europe Sustainable Office Furniture Market Segmentation
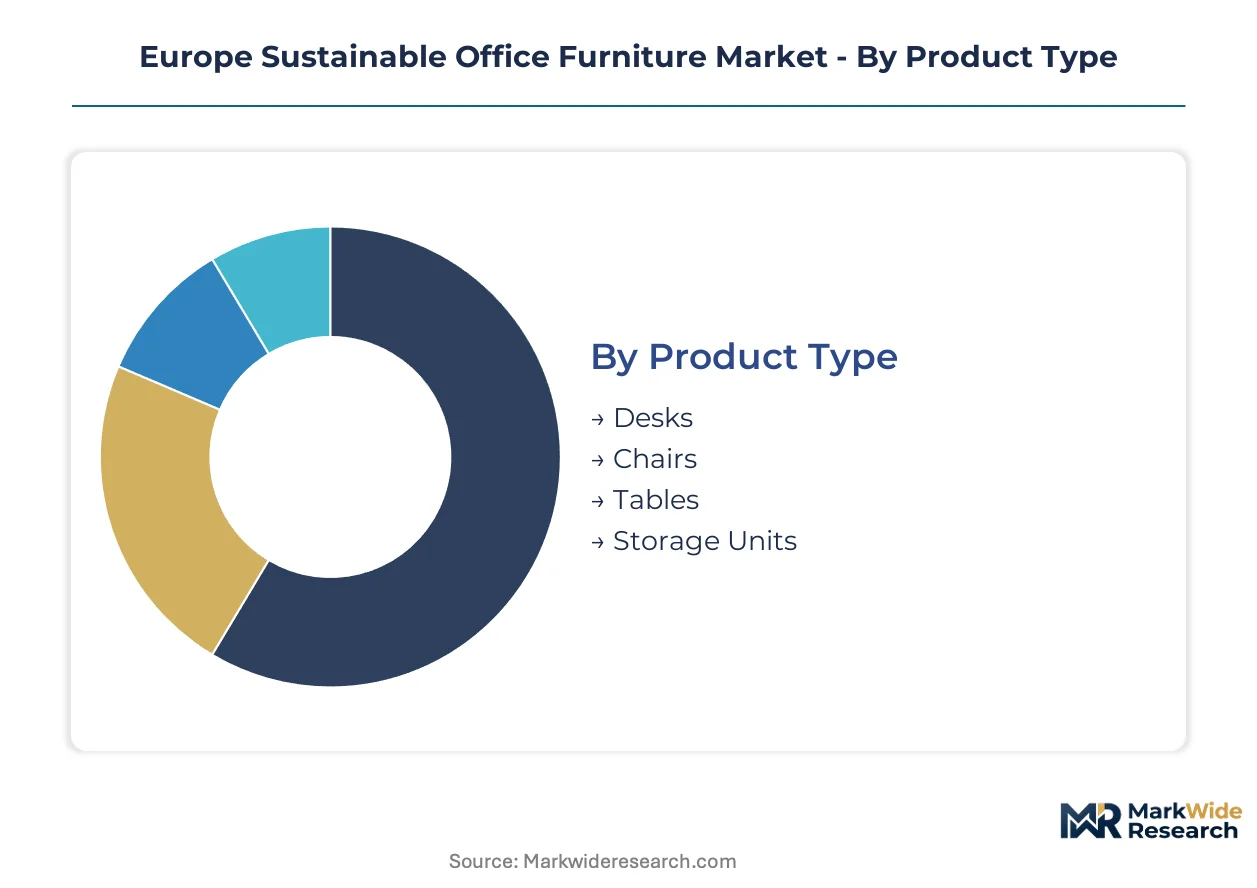
Segmentation reveals how EU Green Deal compliance requirements and hybrid work reconfiguration cycles are fragmenting procurement patterns across product categories. Material sourcing constraints and certification depth now determine which suppliers qualify for specific contract tiers.
Product Type:
German and French procurement teams dominate volume for desking and seating, while Nordic buyers lead storage system adoption through circular economy frameworks.
- Desks:Modular workstation systems with height-adjustable frames and FSC-certified substrates command premium positioning in Amsterdam and Frankfurt financial services fit-outs. Dutch corporate real estate teams specify these for WELL Building Standard compliance.
- Chairs:Task seating with Cradle to Cradle certification and bio-based foam upholstery concentrates demand in Paris and London headquarters relocations. ANSM's stricter flame retardant thresholds are accelerating reformulation timelines for French market entry.
- Tables:Conference and collaboration tables with recycled steel frames serve meeting room reconfigurations across Berlin and Munich corporate campuses.
- Storage Units:Filing and locker systems with end-of-life take-back protocols align with Netherlands circular economy infrastructure.
Desks command the established base. The steepest expansion runs through chairs as indoor air quality scoring intensifies.
Material:
Cost tier stratification separates certified recycled content from emerging bio-based alternatives, with price premiums widening for supply-constrained inputs.
- Recycled Wood:FSC-certified particleboard and solid timber from Baltic supply clusters dominate workstation substrates. Estonian and Latvian sourcing concentration creates vulnerability to shipping disruptions and audit backlogs.
- Steel:Recycled content desking and storage frames rely on Northern European scrap metal flows. Rotterdam harbor proximity enables margin efficiency for remanufacturing programs.
- Bamboo:Rapid-renewable grass substitutes serve non-structural surfaces and decorative elements in Dutch sustainable fit-outs.
- Bioplastics:Bio-based polymers from agricultural feedstocks occupy niche applications in non-load-bearing components due to structural durability limitations.
Recycled wood anchors volume leadership. Bioplastics gain share fastest as polymer science advances close performance gaps.
Design Style:
Application context determines specification priority, with cultural institutions demanding aesthetic differentiation and corporate buyers optimizing for spatial flexibility.
- Modular:Reconfigurable workstation and storage systems accommodate fluctuating hybrid attendance patterns in Frankfurt and London multi-site programs. Corporate real estate teams unbundle procurement from dealer networks for these fit-outs.
- Ergonomic:Biomechanically optimized seating with adjustable lumbar support concentrates in technology sector headquarters across Berlin and Paris.
- Modern:Clean-lined desking with low-emission finishes serves WELL-certified commercial interiors in Amsterdam and Copenhagen.
- Minimalist:Reduced-material aesthetic aligns with institutional cultural fit-outs in Basel and Milan.
Modular systems capture the dominant share trajectory. Ergonomic specifications expand most quickly as occupational health regulations tighten.
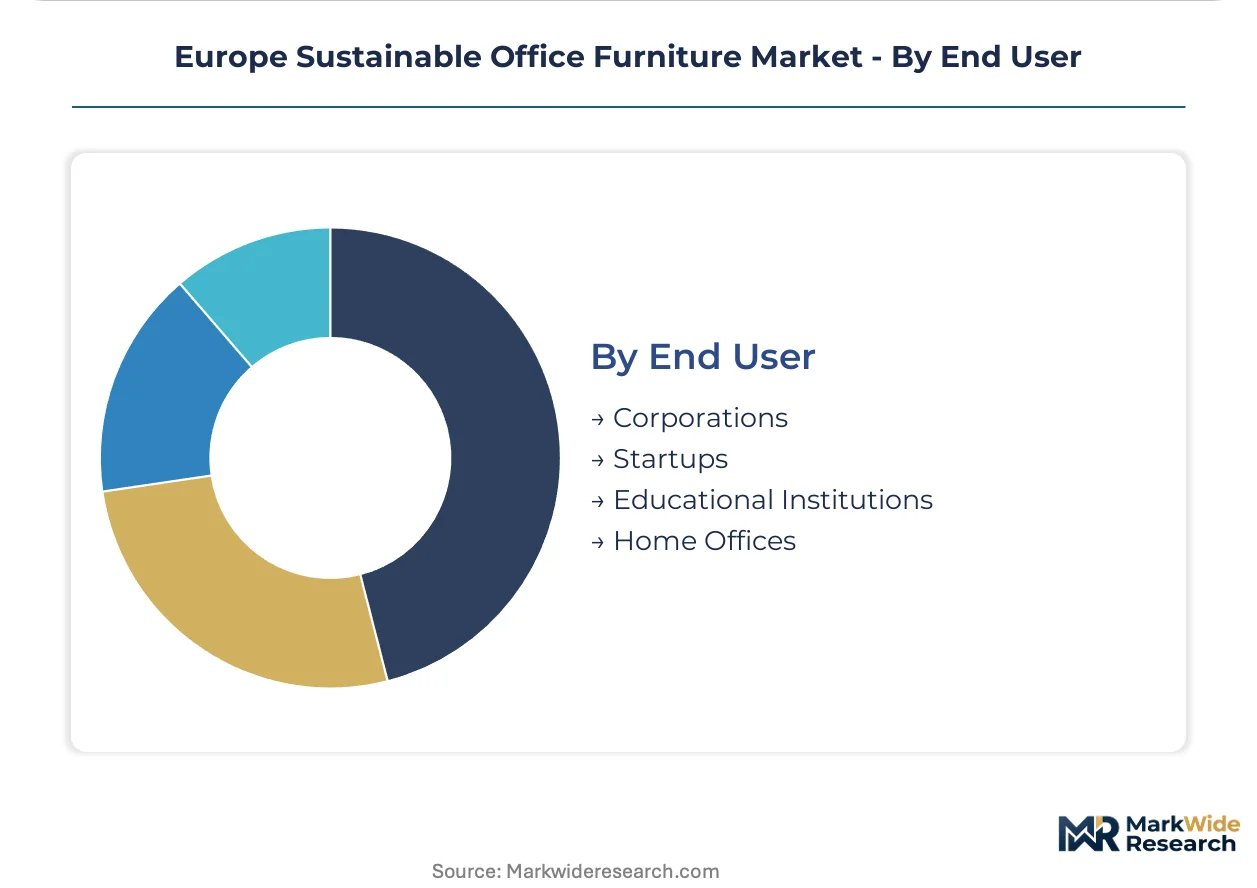
End User:
Customer type dictates contract scale and certification depth, with public sector mandates creating distinct qualification barriers.
- Corporations:Multi-site financial services and technology headquarters across London, Frankfurt, and Paris demand embodied carbon data for CSRD reporting alignment. Direct manufacturer contracting displaces traditional dealer relationships.
- Educational Institutions:Universities and research facilities in the Netherlands and Germany specify durable, repairable systems with extended warranty terms.
- Startups:Flexible lease commitments drive subscription-based furniture-as-a-service adoption in Berlin and Amsterdam coworking clusters.
- Home Offices:Individual procurement of certified seating and compact desking concentrates in Scandinavian remote work markets.
Corporations anchor revenue concentration. Educational institutions climb fastest as EU Ecolabel mandates expand to public sector contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance and the EU Green Deal are compressing certification timelines across European procurement markets. National building codes in Germany and France now mandate environmental product declarations for public sector furniture contracts. Corporate real estate teams in Amsterdam, Frankfurt, and Paris are unbundling procurement from traditional dealer networks.
Germany
Corporate headquarters relocations in Frankfurt and Berlin drive modular workstation demand for hybrid attendance patterns. The national building code mandates EPD documentation for federal procurement contracts above threshold values. Bavarian manufacturing clusters around Nuremberg supply FSC-certified substrates to desking manufacturers serving WELL-certified commercial interiors.
France
ANSM enforces stricter flame retardant thresholds than baseline EU requirements, accelerating upholstery foam reformulation timelines. The national green public procurement framework requires EU Ecolabel compliance for institutional furniture contracts. Paris-based financial services firms demand embodied carbon data for CSRD reporting alignment in headquarters fit-outs.
Netherlands
Amsterdam and Rotterdam harbor zones host established take-back and remanufacturing ecosystems for furniture-as-a-service models. The national circular economy strategy mandates extended producer responsibility protocols for commercial interiors. Randstad corporate campuses pilot RFID-embedded workstations to automate inventory audits and remanufacturing scheduling.
United Kingdom
London headquarters relocations in financial services and technology sectors concentrate demand for Cradle to Cradle certified seating. The Building Safety Regulator enforces stricter material disclosure requirements for commercial fit-outs. Scottish public sector procurement teams specify durable repairable systems with extended warranty terms for educational institutions.
Sweden
Nordic circular economy frameworks drive storage system adoption with end-of-life take-back protocols. The national procurement agency prioritizes EU Ecolabel compliance for public sector furniture contracts. Gothenburg manufacturing clusters leverage Baltic timber supply chains for FSC-certified workstation substrates.
Europe Sustainable Office Furniture Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the European sustainable office furniture market. The upper tier commands premium positioning through certification depth and project management capabilities for multi-site fit-out programs. Mid-tier specialists compete on modular design agility and regional supply chain proximity. Dominant competitive moves include direct manufacturer contracting with corporate buyers and backward integration into FSC-certified timber sourcing.
Within the integrated tier, Kinnarps leverages its Nordic manufacturing footprint to anchor circular economy contracts in Scandinavia. Haworth Europe and Vitra occupy positions at the premium-design intersection, with the former emphasizing certification depth and the latter sustaining architect relationships for cultural institution fit-outs. These companies exemplify how geographic origin and structural focus determine competitive positioning under tightening EU Ecodesign requirements.
| Leading Market Players |
|---|
| Kinnarps |
| Haworth Europe |
| Herman Miller Europe |
| Vitra |
| Ahrend Group |
| Nowy Styl |
| Steelcase |
| Sedus Stoll |
| Inter Ikea Systems B V |
| Others |
Supply & Pricing Matrix
Scale economies at Baltic timber processing clusters compress unit costs for FSC-certified substrates while simultaneously elevating price floors for smaller manufacturers lacking volume procurement leverage. Northern European scrap metal supply concentration and Rotterdam harbor logistics efficiency together determine margin structures across recycled steel desking lines.
Pricing Analysis
Amsterdam and Frankfurt command 15-20% premiums over Eastern European procurement markets for identical Cradle to Cradle certified seating specifications. Three-tier pricing structure across premium, standard, and economy levels separates WELL-certified architect-specified systems from EU Ecolabel baseline compliance and uncertified imports. Cost compression in standard tiers is intensifying as Baltic wood supply bottlenecks force mid-tier manufacturers to absorb input volatility. Educational institutions exhibit highest price sensitivity due to extended replacement cycles, while financial services headquarters demonstrate lowest sensitivity where CSRD reporting alignment commands premium positioning.
Supply Chain Analysis
Rotterdam and Hamburg port congestion cycles create 3-6 week inbound variability for FSC-certified timber arriving from Estonian and Latvian processing clusters. Manufacturing capacity concentrates in Sweden, Germany, and the Netherlands, with each national cluster drawing from distinct Baltic wood supply contracts and Northern European scrap metal flows. Single-source vulnerability runs through Estonian FSC audit backlogs that delay chain-of-custody documentation for German desking manufacturers. Distribution runs through direct manufacturer contracting with corporate real estate teams, displacing traditional dealer intermediaries in multi-site fit-out programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU Ecolabel and EPD documentation creates formidable switching costs for corporate buyers, embedding incumbent advantages through multi-year certification investments that new entrants cannot rapidly replicate.
For Market Incumbents: Consolidate backward integration into FSC-certified Baltic timber sourcing to defend margin position against scrap metal price volatility and Estonian supply disruptions. Deepen Cradle to Cradle certification portfolios across seating lines to preempt ANSM flame retardant threshold escalations. Lock in direct contracting relationships with financial services headquarters relocations before CSRD reporting obligations fully reshape procurement scorecards.
For New Entrants and Emerging Players: Anchor in Netherlands circular economy infrastructure where Amsterdam and Rotterdam harbor zones offer established take-back ecosystems without requiring captive remanufacturing capacity. Target startup and coworking segments in Berlin and Amsterdam with furniture-as-a-service subscription models that bypass capital-intensive certification barriers. Lead with sensor-embedded workstation pilots that monetize occupancy analytics premiums.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with furniture-as-a-service platforms integrated into Netherlands extended producer responsibility frameworks. Long-term viability hinges on certification depth rather than manufacturing scale, favoring acquisition targets with established EPD libraries and architect relationships. Watch for EU AI Act extensions into smart furniture sensor deployments as inflection indicator for IoT-enabled workstation premium tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FSC-Certified Timber | Estonian and Latvian supply concentration rewards captive sourcing for German desking manufacturers. |
| Digital Product Passport Deployment | RFID-embedded workstations automate circular economy compliance for Dutch corporate campus pilots. |
| Furniture-as-a-Service Platform Launch | Amsterdam harbor remanufacturing ecosystems enable subscription revenue conversion without asset-heavy infrastructure. |
| Cradle to Cradle Certification Expansion | ANSM flame retardant thresholds in France accelerate reformulation timelines for seating upholstery lines. |
| Direct Manufacturer Contracting Capability | CSRD reporting alignment demands embodied carbon transparency that displaces traditional dealer intermediaries. |
Research Methodology
A standing panel of corporate real estate procurement directors, sustainability compliance officers, furniture manufacturer product managers, and architect specification consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from EU EPD database filings, FSC chain-of-custody audit records, national building code procurement thresholds, and corporate sustainability disclosure reports. Bottom-up demand modeling across hybrid office reconfiguration cycles triangulated against top-down EU Green Deal implementation timelines.
Consistency checks validated volume and value outputs against external benchmarks including WELL Building Standard adoption curves and CSRD reporting obligation phase-ins across the analysis window. Segmentation modeling incorporated product type, material certification tier, design style modularity, and end-user procurement scale dimensions. CAGRs were derived from regression analysis of historical fit-out cycle frequencies and projected Ecodesign regulation compliance deadlines, with furniture-as-a-service penetration rates and bioplastic performance advances as key scenario variables.
Material uncertainties — Baltic wood supply disruptions, scrap metal price volatility, and EPD documentation bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions regarding EU Green Deal implementation pacing and corporate hybrid attendance stabilization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Kids Storage Furniture Market
Furniture
Armchair on Casters Market
Furniture
Lecterns Market
Furniture
France Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Global Furniture Fittings Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Entryway Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Europe Luxury Furniture Market
Furniture
Wood Furniture Market
Furniture
Plastic Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Global Folding Furniture Market