
 India Luxury Furniture Market | 2026-2036
India Luxury Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
India Luxury Furniture Market Foresight
Engineered wood and reclaimed teak is shifting cost structures across premium seating and storage categories, reducing dependence on imported hardwoods while preserving artisanal finishing standards. Godrej Interio leverages captive manufacturing facilities in Maharashtra to control quality across its luxury portfolio. Stanley Lifestyles anchors its position through exclusive showroom networks in South Indian metropolitan markets. Saraf Furniture differentiates via specialized solid-wood craftsmanship targeting heritage-inspired residential projects.
India luxury furniture comprises high-specification interior fixtures crafted from premium materials including teak, rosewood, full-grain leather, and tempered glass, typically featuring hand-finished joinery, custom upholstery, and bespoke dimensions for residential and commercial environments. Sofas and beds command the largest share of consumer expenditure, reflecting priority allocation to living and sleeping spaces in upscale home design. The hospitality end-user segment is expanding fastest as boutique hotels and premium serviced residences commission custom fittings, while wood-based materials retain margin dominance due to cultural preference and durability perception.
BIS timber grading standards and the PLI scheme for domestic manufacturing shape product compliance and sourcing economics, requiring importers to document chain-of-custody certification while incentivizing local mill investment. State-level zoning regulations in Maharashtra and Karnataka govern showroom expansion and warehouse licensing for luxury retail operators. Stakeholders must monitor evolving ESG disclosure requirements under the CSRD alignment trajectory and assess whether captive upholstery production or outsourced specialist partnerships offer superior margin protection.
Market Dynamics
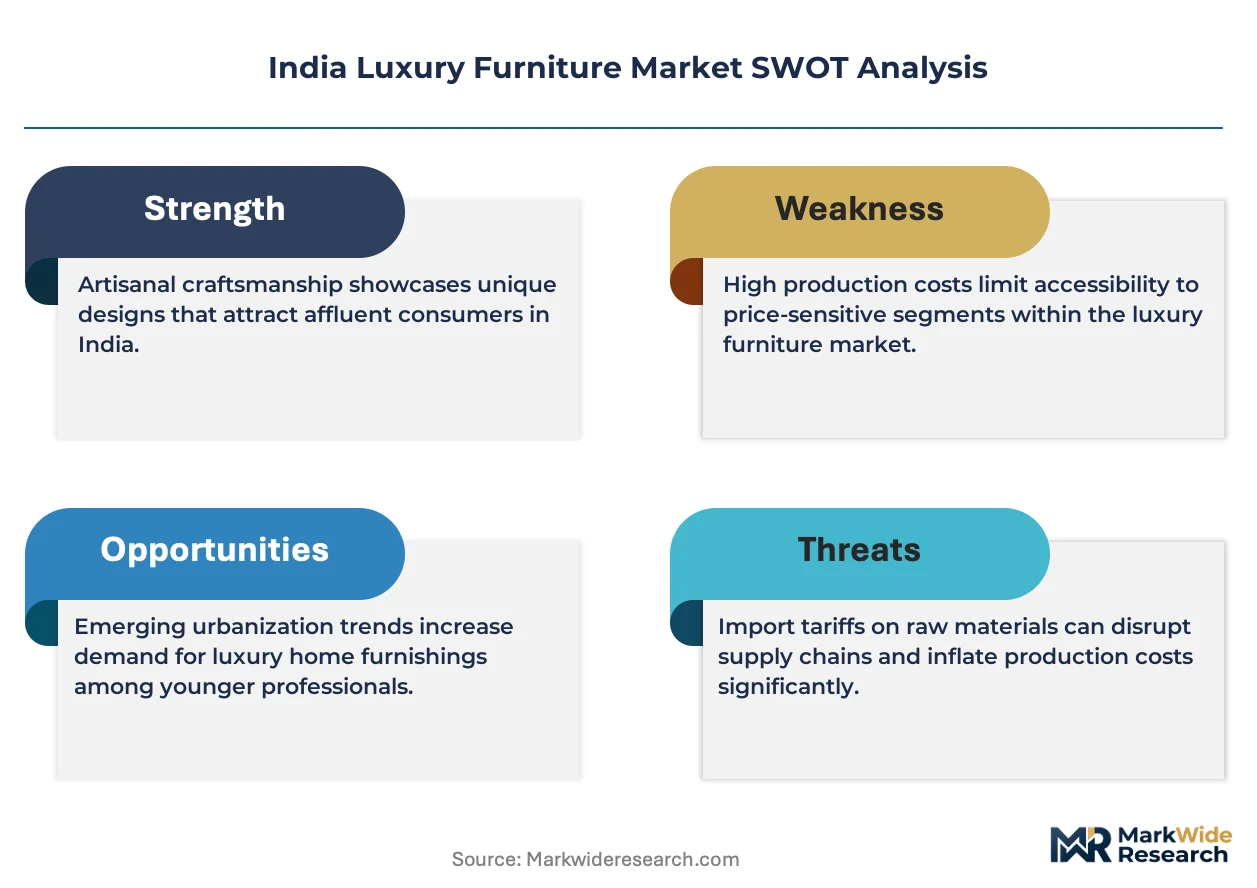
PLI scheme incentives and BIS timber certification requirements are restructuring sourcing economics, pushing domestic mill investment while raising compliance barriers for imported hardwood supply chains.
Growth Catalysts
- PLI Manufacturing Incentives:Production-linked incentive schemes for domestic furniture manufacturing are accelerating capital deployment into Maharashtra and Karnataka mill facilities.
- Hospitality Sector Expansion:Boutique hotel and premium serviced residence development across Mumbai and Delhi is generating custom fixture commissions at scale.
- Engineered Wood Adoption:Reclaimed teak and engineered wood processing technologies are reducing import dependency while preserving artisanal finishing standards.
Market Restraints
- Imported Hardwood Cost Volatility:BIS chain-of-custody documentation requirements for Burmese teak and African mahogany are inflating landed costs and extending procurement cycles.
- Artisan Labor Concentration:Master craftspeople specializing in hand-finished joinery cluster in Jodhpur and Saharanpur, creating geographic supply bottlenecks.
- Substitute Material Threat:High-grade aluminum and carbon-fiber composite fixtures from Italian and German suppliers are capturing share in ultra-premium commercial interiors.
Strategic Opportunities
- Karnataka Secondary Cities:Bengaluru's peripheral luxury real estate corridors in Whitefield and Electronic City present underdeveloped showroom infrastructure for bespoke collections.
- CSRD-Aligned ESG Positioning:Carbon disclosure readiness and certified sustainable sourcing are creating procurement preference among hospitality groups with European parent companies.
- Direct-to-Architect Channel:Bypassing traditional retail through exclusive designer studio partnerships is capturing specification authority earlier in residential project timelines.
Industry Challenges
- Master Craftsman Succession:Traditional woodworking apprenticeship pipelines in Rajasthan and Uttar Pradesh are failing to replenish retiring artisan cohorts with comparable skill depth.
- BIS Certification Timelines:Timber grading laboratory capacity constraints are extending product approval cycles by four to six months for imported material categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Luxury Furniture Market |
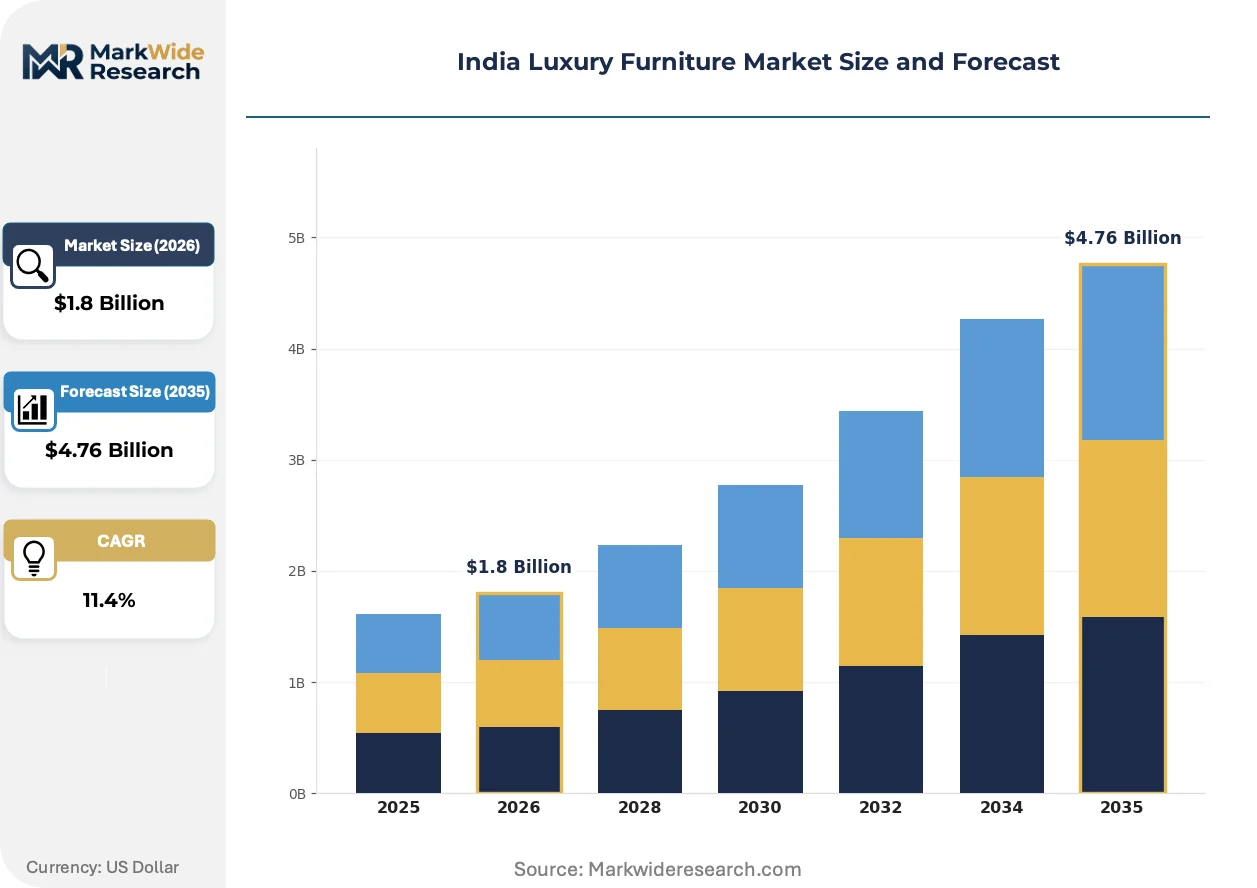
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Dining Tables, Cabinets Material: Wood, Leather, Metal, Glass End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Retail, Direct Sales, Showrooms |
| Companies Covered | Urban Ladder, Woodensure, Godrej Interio, Saraf Furniture, Stanley Lifestyles, Durian, Pepperfry, WoodenStreet, IKEA India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Luxury Furniture Market Shifts & Advancements
Material science advances and procurement digitization are compressing traditional supply hierarchies, enabling faster customization cycles while embedding compliance documentation deeper into production workflows.
CNC-assisted hand-finishing is expanding into premium seating manufacturing, blending robotic precision with artisanal surface treatment. South Indian luxury residential developers are specifying these hybrid-production sofas for phased villa deliveries. The technology is expanding into mid-premium price tiers previously served by pure handcrafted output.
BIS timber grading standards now mandate third-party chain-of-custody verification for all imported hardwood categories. Domestic mills with integrated certification capabilities are capturing specification preference from hospitality procurement teams. Maharashtra-based manufacturers with captive forestry partnerships are responding fastest to documentation requirements.
Architect-led specification is displacing retail showroom selection for residential projects above defined value thresholds. Mumbai and Delhi design studios are consolidating purchase authority through exclusive mill partnerships. This pattern is most visible in gated community developments where single-source contracting reduces coordination friction.
India Luxury Furniture Market Segmentation
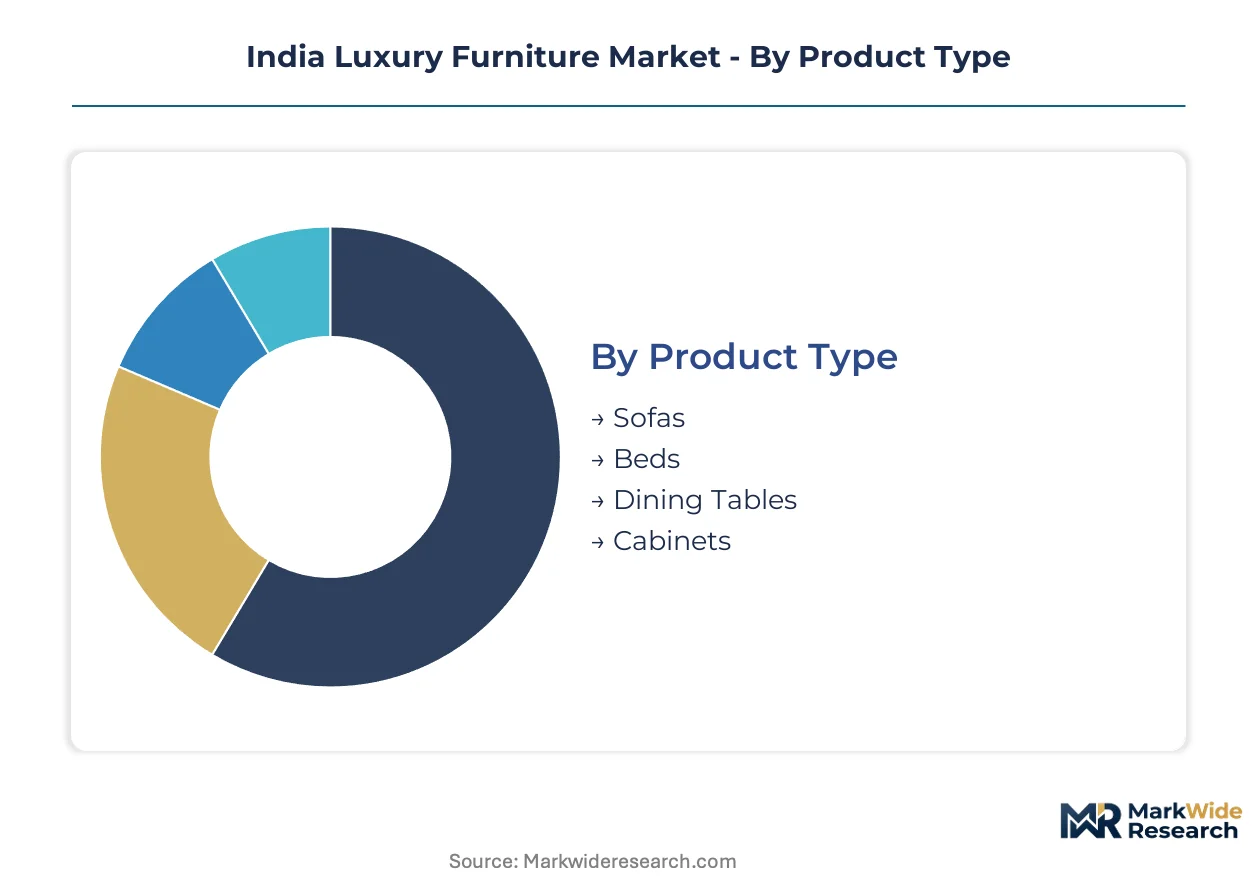
Buyer priorities in India's luxury furniture market diverge sharply across living spaces, material preferences, and procurement channels. Segmentation reveals where specification authority concentrates and which supply configurations capture margin.
Product Type:
Purchase sequence and room hierarchy dictate allocation patterns in residential and commercial fit-outs.
- Sofas:Living room seating commands the largest share of consumer expenditure, with bespoke upholstery and modular configurations specified for Mumbai and Delhi high-net-worth residences. Hand-finished joinery and full-grain leather wrapping preserve artisanal standards while engineered wood cores reduce hardwood import dependency.
- Beds:Master bedroom collections absorb premium material budgets, featuring solid teak headboards and custom mattress integration for gated community developments across Maharashtra and Karnataka. Hospitality procurement teams specify these for boutique hotel suites.
- Dining Tables:Heritage-inspired solid-wood craftsmanship anchors family gathering spaces, with Rajasthan and Uttar Pradesh artisan clusters supplying hand-carved bases.
- Cabinets:Storage systems integrate tempered glass and reclaimed teak for residential libraries and executive office environments.
Sofas lead on scale; beds lead on momentum.
Material:
Cost structures and certification requirements reshape sourcing economics across premium categories.
- Wood:Teak and rosewood retain cultural preference and durability perception, though BIS chain-of-custody documentation inflates landed costs for Burmese and African imports. Domestic mills with captive forestry partnerships in Maharashtra capture specification preference from hospitality procurement teams.
- Leather:Full-grain upholstery commands premium positioning in seating and bedroom collections, with Italian tannery partnerships differentiating South Indian manufacturers.
- Metal:High-grade aluminum fixtures from European suppliers threaten wood dominance in ultra-premium commercial interiors.
- Glass:Tempered glass surfaces integrate with wood and metal substrates for contemporary residential and office specifications.
Wood dominates current revenue; metal is gaining share fastest in commercial segments.
End User:
Project scale and specification authority determine channel access and customization depth.
- Residential:Individual buyers in Mumbai and Delhi commission bespoke dimensions and hand-finished joinery for villa and apartment fit-outs.
- Commercial:Corporate headquarters and co-working spaces specify standardized premium collections with shorter lead times.
- Hospitality:Boutique hotels and premium serviced residences across Mumbai and Delhi generate custom fixture commissions at scale, with European parent companies demanding CSRD-aligned ESG documentation.
- Office:Executive suites and boardrooms prioritize ergonomic seating and statement storage systems.
Residential leads on absolute volume; hospitality climbs the fastest.
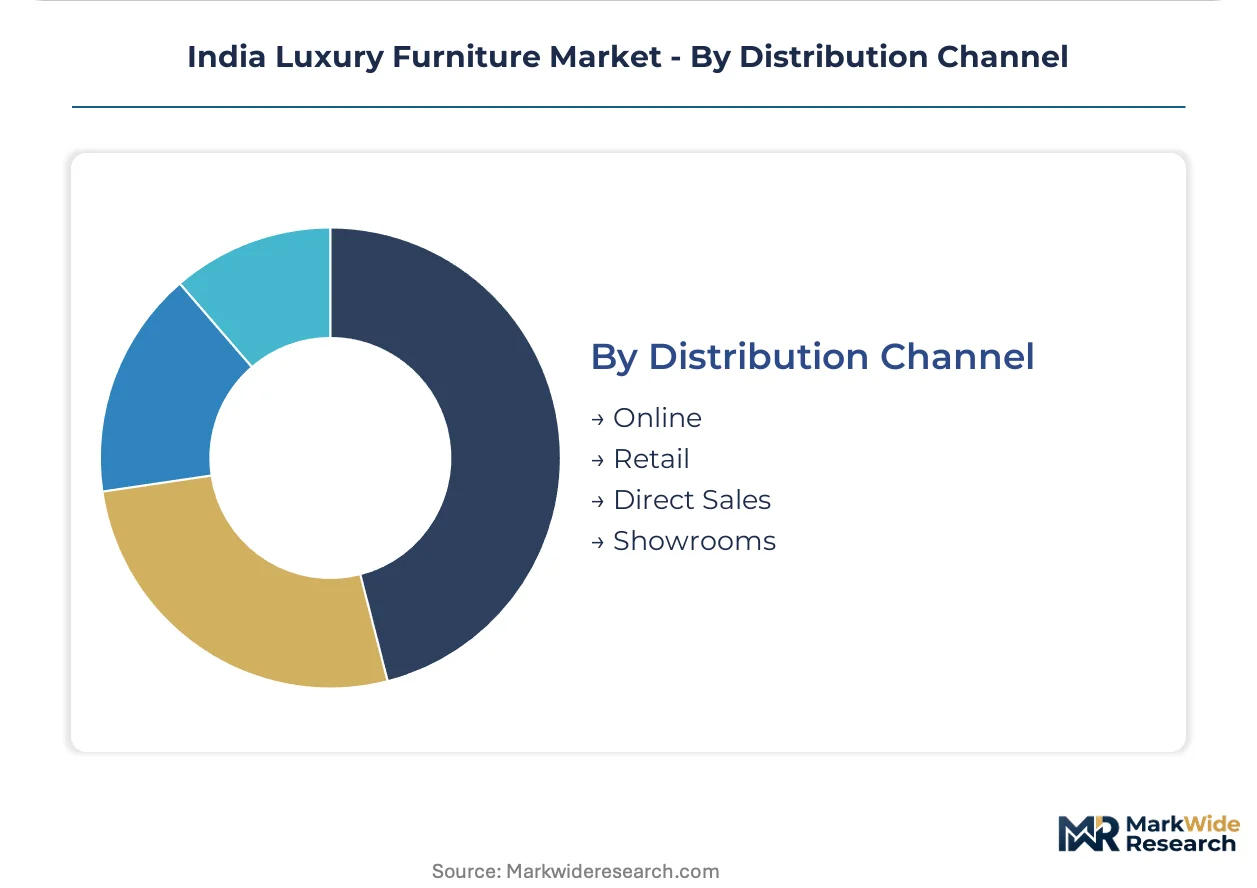
Distribution Channel:
Channel selection determines margin capture and customer relationship depth.
- Online:Digital catalogs with augmented visualization tools penetrate tier-2 cities, though high-value transactions still close through physical verification.
- Retail:Multi-brand outlets in Bengaluru and Chennai serve mid-premium segments with curated collections.
- Direct Sales:Architect and designer studio partnerships in Mumbai and Delhi consolidate purchase authority for gated community developments.
- Showrooms:Exclusive branded galleries in South Indian metropolitan markets anchor brand positioning and enable tactile material assessment.
Showrooms lead on transaction value; direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's furniture manufacturing corridor anchors India's luxury segment, with Mumbai's high-net-worth residential clusters and Pune's mill infrastructure driving specification demand for bespoke teak and engineered wood collections.
Maharashtra
Mumbai's luxury real estate developments in South Mumbai and Bandra-Kurla Complex commission custom living room and bedroom collections for villa and penthouse fit-outs. BIS timber grading standards mandate chain-of-custody documentation for all imported hardwood, favoring domestic mills with captive certification capabilities. Pune-based manufacturing facilities supply precision-engineered cores to South Indian metropolitan markets.
Karnataka
Bengaluru's peripheral luxury corridors in Whitefield and Electronic City generate underdeveloped showroom infrastructure demand for bespoke collections targeting gated community developers. The state's PLI scheme incentives accelerate capital deployment into mill facilities with integrated upholstery production. Artisan clusters in Mysuru supply hand-finished joinery for heritage-inspired residential specifications.
Delhi-NCR
Gurugram and Noida's premium serviced residence developments drive hospitality procurement for custom fixture commissions at scale. DGFT documentation requirements for imported Burmese teak inflate landed costs, pushing specification toward domestic rosewood alternatives. Jodhpur-based craftsman networks supply hand-carved dining bases for Delhi's architect-led residential projects.
Tamil Nadu
Chennai's design studio partnerships consolidate purchase authority for coastal luxury villa developments. Italian tannery partnerships differentiate local manufacturers supplying full-grain leather upholstery to South Indian hospitality groups. Coimbatore's engineered wood processing facilities reduce hardwood import dependency for mid-premium seating categories.
Telangana
Hyderabad's HITEC City corporate headquarters specify standardized premium collections for executive office environments. State-level warehouse licensing regulations govern showroom expansion for luxury retail operators targeting the city's emerging ultra-high-net-worth enclaves. Local fabricators leverage CNC-assisted production for faster customization cycles in commercial fit-outs.
India Luxury Furniture Market Competitive Landscape
Global majors compete with regional champions across distribution depth and artisanal craftsmanship integration, producing a tiered structure where scale-driven portfolios coexist with heritage-specialist positioning. The vendor base separates into three strategic archetypes: diversified domestic conglomerates with captive manufacturing, South Indian showroom-anchored lifestyle brands, and Rajasthan-focused solid-wood craftsmanship specialists. Dominant competitive moves include exclusive architect studio partnerships and backward integration into certified timber sourcing.
Among diversified domestic manufacturers, Godrej Interio exemplifies the conglomerate archetype through Maharashtra-based captive production facilities. Stanley Lifestyles occupies a position within the South Indian showroom-anchored tier, while Saraf Furniture represents the heritage craftsmanship specialist archetype targeting solid-wood residential specifications. These three anchors illustrate the competitive spectrum from scale-driven standardization to artisanal differentiation.
| Leading Market Players |
|---|
| Urban Ladder |
| Woodensure |
| Godrej Interio |
| Saraf Furniture |
| Stanley Lifestyles |
| Durian |
| Pepperfry |
| WoodenStreet |
| IKEA India |
| Others |
Supply & Pricing Matrix
CNC-assisted hand-finishing adoption across Maharashtra and Karnataka mill facilities compresses production cycles while concentrating margin capture among capital-equipped manufacturers, simultaneously lowering per-unit labor costs and raising barriers for pure artisan-dependent competitors.
Pricing Analysis
Imported Burmese teak and African mahogany landed costs pass through directly to end pricing following BIS chain-of-custody documentation requirements, with certification-grade differentiation separating hospitality procurement tiers from residential retail. Three-tier pricing structure across premium bespoke, standard designer, and economy mid-premium levels reflects customization depth and after-sales service bundling. Pricing pressure stems from engineered wood substitution in seating cores as domestic mills achieve comparable finish quality at reduced hardwood dependency. Hospitality buyers with European parent companies exhibit lowest price sensitivity due to CSRD-aligned ESG procurement mandates, while individual residential buyers in tier-2 cities demonstrate highest elasticity.
Supply Chain Analysis
Inland freight costs from Jodhpur and Saharanpur artisan clusters to Mumbai and Delhi distribution nodes inflate delivered pricing for hand-finished joinery components, favoring regional mill concentration in Maharashtra and Karnataka. Geographic supply concentrates in India domestic production, with residual dependency on Myanmar and African hardwood imports for solid-teak specifications. Raw material sourcing draws from certified domestic forestry partnerships, Italian tannery leather imports, and tempered glass domestic fabrication. Single-source vulnerability sits with master craftsman geographic concentration in Rajasthan and Uttar Pradesh. Distribution runs through exclusive branded showrooms in South Indian metropolitan markets, architect studio direct partnerships in Mumbai and Delhi, and augmented-reality-enabled digital catalogs penetrating tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India luxury furniture market operates as a regulatory compounder where BIS timber grading standards and PLI manufacturing incentives continuously reshape competitive economics, with compliance investment now determining specification access to hospitality procurement channels.
For Market Incumbents: Anchor defensive positioning through captive certification capabilities and backward integration into Maharashtra-based engineered wood processing, neutralizing artisan labor bottleneck risks while capturing hospitality procurement preference. Deepen showroom infrastructure in Bengaluru peripheral corridors before secondary city saturation accelerates. Prioritize CSRD-aligned carbon disclosure readiness to secure European parent company hospitality contracts. For New Entrants and Emerging Players: Begin with Karnataka secondary city showroom gaps in Whitefield and Electronic City luxury real estate corridors, where gated community developer relationships remain underdeveloped. Target direct-to-architect channel partnerships in Mumbai and Delhi design studios as the most penetrable specification entry point, bypassing entrenched retail networks. Leverage CNC-assisted production for faster customization cycles against incumbent artisan-dependent lead times. For Investors and Strategic Acquirers: Valuations sit cheapest among Rajasthan-focused solid-wood craftsmanship specialists facing succession pipeline failures, presenting consolidation opportunities for platform builds. Long-term viability across the analysis window favors manufacturers with integrated BIS certification capabilities and captive forestry partnerships. Monitor PLI scheme beneficiary announcements as inflection indicators for production capacity repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Captive BIS Certification Investment | Maharashtra-based mills secure hospitality procurement preference through integrated chain-of-custody documentation capabilities. |
| Architect Studio Partnership Expansion | Mumbai and Delhi design studios consolidate purchase authority for gated community developer specifications. |
| Engineered Wood Processing Scale-Up | Domestic facilities reduce Burmese teak import dependency while preserving artisanal finishing standards. |
| Karnataka Secondary City Showroom Buildout | Whitefield and Electronic City corridors present underdeveloped infrastructure for bespoke collection penetration. |
| CSRD-Aligned ESG Disclosure Program | Carbon certification readiness captures procurement preference from European parent company hospitality groups. |
Research Methodology
Bottom-up residential and hospitality procurement modeling reconciled against top-down Maharashtra and Karnataka mill capacity tracking forms the analytical core, combining primary interviews with luxury real estate developers, hospitality procurement managers, furniture manufacturing executives, and artisan cooperative representatives with secondary validation from BIS certification registries, PLI scheme beneficiary disclosures, DGFT timber import records, and state-level warehouse licensing databases.
Input-output matrices map engineered wood processing capacity, artisan labor availability, and showroom distribution density against hospitality project pipelines and gated community development schedules across the projection horizon. Segmentation dimensions encompass product type, material grade, end-user category, and distribution channel, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs include PLI incentive disbursement trajectories and BIS laboratory certification throughput constraints.
Several conditions sit outside the modeled scope, including abrupt DGFT timber import restriction changes, artisan labor migration disruptions, and hospitality sector demand shocks from macroeconomic contraction. Forecasts reflect documented assumptions regarding regulatory stability and capital deployment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Laminated Door Market
Furniture
UAE Luxury Furniture Market
Furniture
Plastic Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Italy Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Italy Home Furniture Market
Furniture
Salon Chairs Market
Furniture
Europe Smart Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Contract Furniture and Furnishing Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Study Carrels Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market