
 Global Folding Furniture Market | 2026-2036
Global Folding Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Folding Furniture Market Foresight
Subscription-based furniture rental and maintenance services is consolidating vendor relationships around folding furniture portfolios, shifting purchase logic from one-time transactions to lifecycle contracts. Inter IKEA Systems B.V. leverages its flat-pack logistics infrastructure to dominate urban delivery networks. Ashley Furniture Industries anchors its position through hardwood folding table specialization. Leggett & Platt, Inc. sustains component supply advantages in foldable bed mechanisms.
Folding furniture encompasses collapsible seating, surfaces, and storage systems engineered with hinged joints, telescoping frames, or detachable panels to enable compact stowage and rapid deployment, typically constructed from engineered wood, tubular steel, or high-density polyethylene rated for repeated cycle testing. The primary commercial purpose centers on maximizing usable floor area in space-constrained environments while preserving ergonomic function. Metal-framed folding chairs lead volume due to institutional procurement scale and durability requirements, while composite-material portable cabinets represent the fastest-expanding margin pool as outdoor recreation and van-life applications multiply. Residential use commands value share, though educational institutions and event venues drive replacement frequency through intensive utilization cycles.
EPA formaldehyde emission standards constrain engineered wood sourcing for US-bound production, while EU REACH and F-Gas Regulation govern adhesive chemistry and foam-blowing agents in upholstered foldable beds. China's GB standards and SAMR quality certification shape export-competitive manufacturing benchmarks. Stakeholders must monitor regulatory divergence between California Air Resources Board thresholds and EU ECHA substance restrictions as dual compliance costs redefine supplier qualification criteria.
Market Dynamics
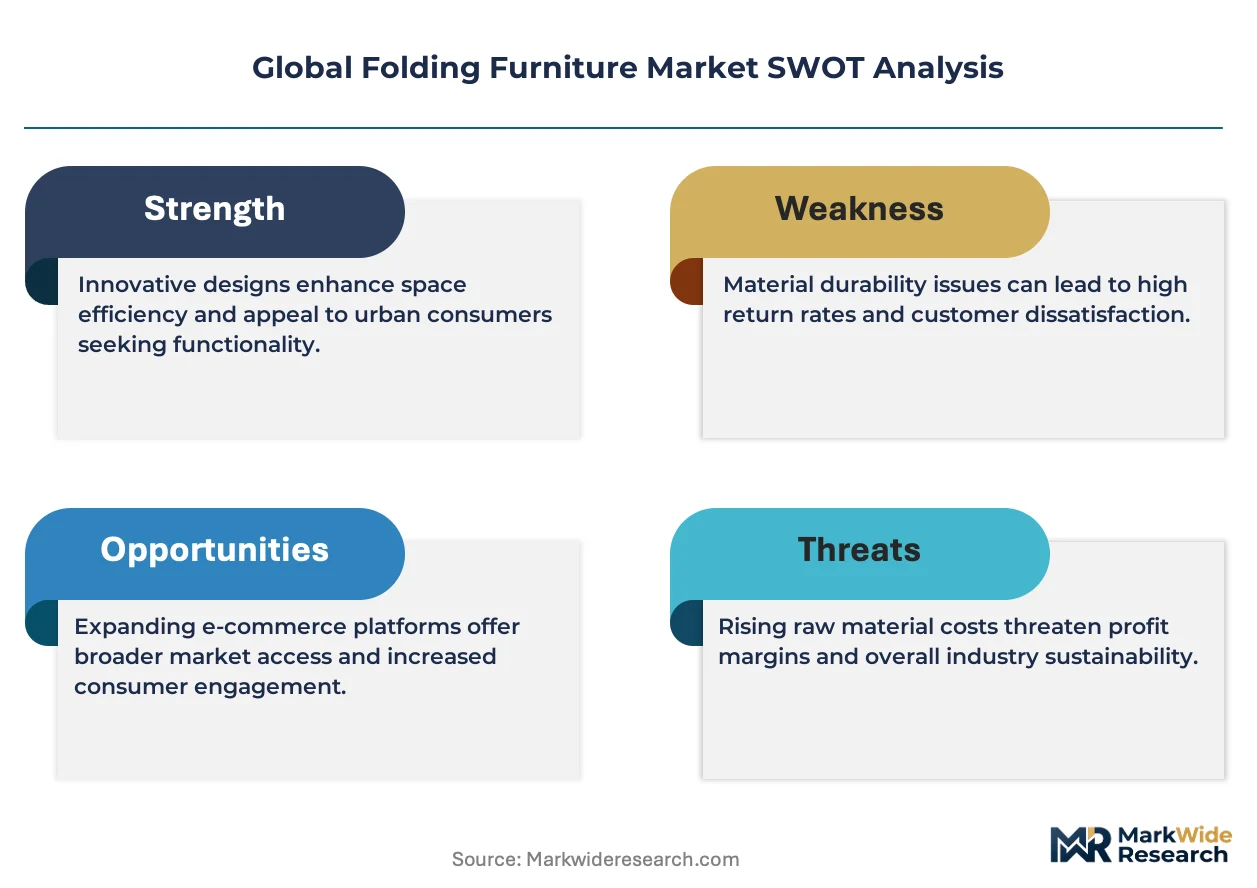
Urban densification in megacities from Lagos to São Paulo is compressing residential floor plans below 400 square feet, forcing furniture purchasing toward modular systems that collapse for daily storage cycles.
Growth Catalysts
- REACH Phase-In Restrictions:EU ECHA substance screening is accelerating R&D into bio-based adhesives for engineered wood laminates, pushing manufacturers toward closed-loop material certification.
- Van-Life and Mobile Recreation:Remote work permanence is expanding demand for vehicle-integrated folding bed systems and telescoping storage units rated for highway vibration loads.
- Institutional Procurement Scale:India's Smart Cities Mission mandates multi-use community halls in 100 urban clusters, creating standardized tender volumes for metal-framed stackable seating.
Market Restraints
- Tubular Steel Input Volatility:Scrap metal price swings and Indonesian nickel export licensing delays are squeezing margin on metal-framed chair production.
- Guangdong Supply Concentration:Seventy percent of global hinge mechanism forging capacity sits within 200 kilometers of Foshan, exposing buyers to single-region weather and labor disruption.
- Formaldehyde Emission Compliance Friction:Divergent EPA CARB Phase 2 and EU E1 thresholds force dual-sku production runs for US-bound versus European-bound engineered wood panels.
Strategic Opportunities
- Indonesia Underpenetration:Jakarta's vertical housing boom lacks domestic folding furniture manufacturing, creating import substitution potential for Malaysian and Vietnamese exporters.
- IoT-Enabled Inventory Tracking:RFID-embedded rental furniture fleets allow real-time location monitoring, unlocking subscription pricing for co-living operators in Berlin and Barcelona.
- India PLI Scheme Extension:Production-linked incentives for furniture manufacturing could offset 15-20 percent of capital equipment costs for mechanized folding bed assembly lines.
Industry Challenges
- Cycle Testing Certification Bottlenecks:ISO 7170 and EN 1728 durability validation requires 12-18 month laboratory queues at accredited facilities in Stuttgart and Shanghai.
- Legacy ERP Integration:Made-to-measure folding furniture configurators struggle to sync with wholesale distributors' AS400-based procurement portals, delaying order-to-delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Folding Furniture Market |
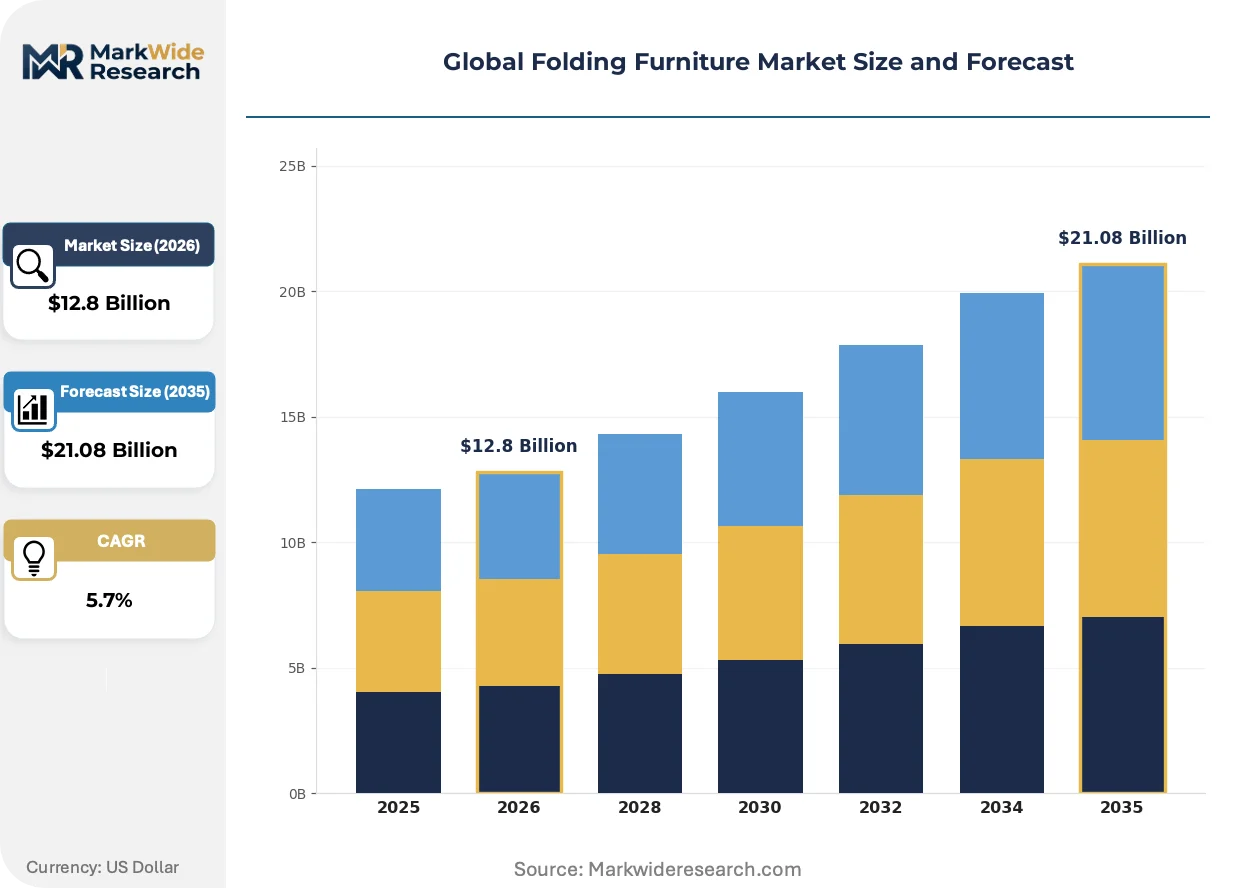
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Chairs, Folding Tables, Foldable Beds, Portable Cabinets, Collapsible Desks Material: Wood, Metal, Plastic, Fabric, Composite Application: Residential Use, Commercial Offices, Educational Institutions, Event Venues, Outdoor Activities End User: Homeowners, Office Administrators, Schools, Event Planners, Camping Enthusiasts |
| Companies Covered | Inter IKEA Systems B.V., Ashley Furniture Industries, Dorel Industries Inc., Flexsteel Industries, Inc., Haworth Inc., Meco Corporation, Leggett & Platt, Inc., La-Z-Boy Inc., Lifetime Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Folding Furniture Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry constraints are converging to redefine structural performance benchmarks across residential, institutional, and mobile applications.
Thermoplastic composite laminates are replacing traditional plywood in high-cycle folding table surfaces, delivering 40 percent weight reduction without sacrificing load ratings. University dining services and municipal event venues in Denmark and the Netherlands are specifying these materials for procurement tenders. The technology is absorbing premium positioning in segments where transport labor costs exceed material outlays.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon blowing agents from polyurethane foam cores in upholstered folding beds. Manufacturers serving German and French markets are retrofitting production lines with water-blown or CO2-based alternatives. Upholstered sleep products for the European contract hospitality segment face reformulation deadlines that outpace current supplier qualification timelines.
Corporate real estate departments are unbundling furniture ownership from facility management contracts, pivoting toward full-service leasing with refresh guarantees. WeWork competitors and enterprise satellite office networks in London and Singapore are driving this specification shift. The model compresses capital expenditure recognition while extending vendor relationships across 36-60 month service horizons.
Global Folding Furniture Market Segmentation
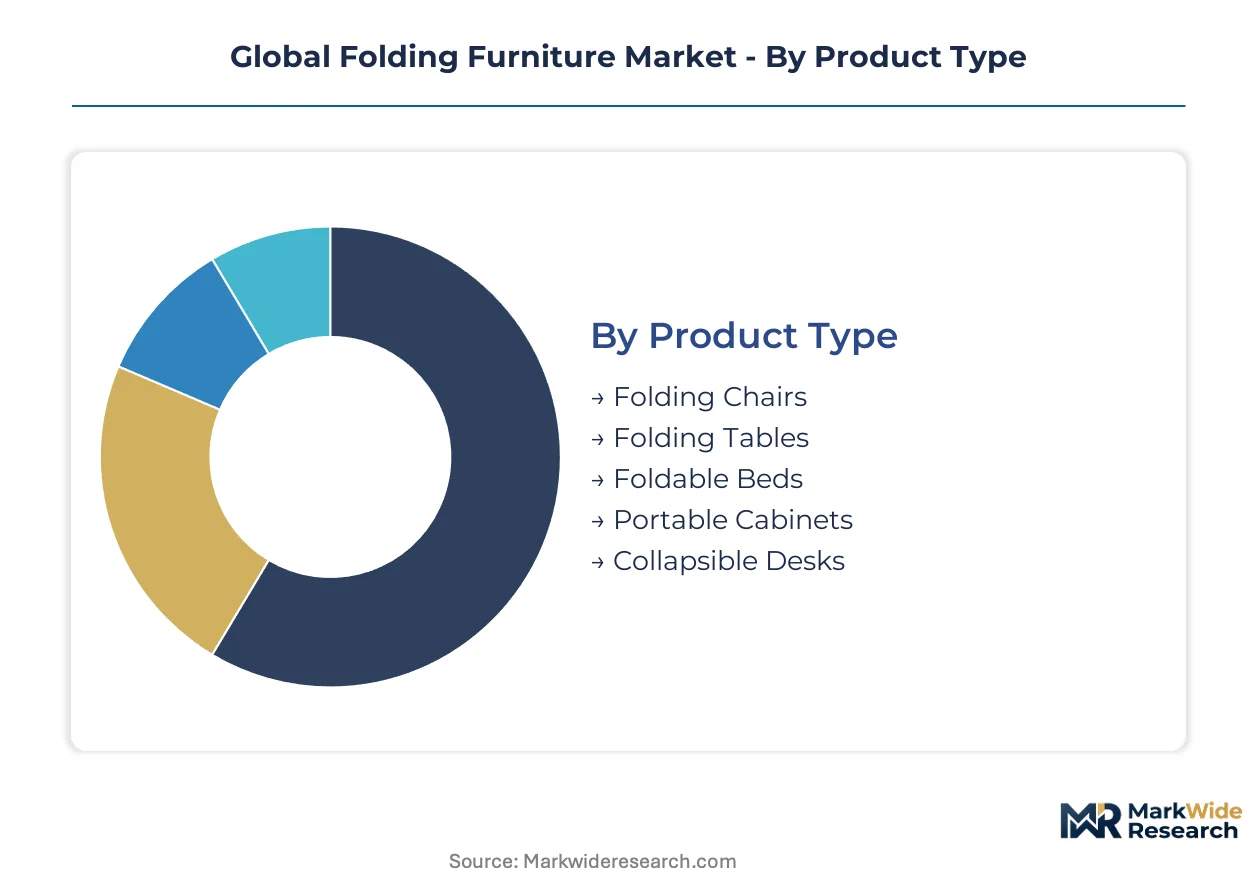
Segmentation in folding furniture reveals how procurement cycles, material specifications, and end-use durability requirements fragment vendor strategies. Upgrade frequencies vary dramatically between institutional buyers replacing metal-framed seating every 3-5 years and residential consumers holding composite storage units for 10+ years.
Product Type:
Replacement-cycle intensity distinguishes segments, with high-frequency institutional procurement creating volume anchors versus low-frequency residential purchases driving margin capture.
- Folding Chairs:Tubular steel frames with polypropylene seats dominate institutional tenders. India's Smart Cities Mission procurement and US school district bulk orders sustain forging capacity utilization in Guangdong clusters. Metal input volatility directly squeezes contract pricing.
- Folding Tables:Engineered wood laminates face dual compliance friction between EPA CARB Phase 2 and EU E1 emission thresholds. Thermoplastic composite surfaces are displacing plywood in Danish university dining tenders where transport labor exceeds material costs.
- Foldable Beds:Mechanism durability ratings determine hospitality contract eligibility. Water-blown foam cores are replacing HFC-blown alternatives ahead of EU F-Gas Regulation deadlines.
- Portable Cabinets:HDPE and composite shells serve van-life and outdoor recreation demand rated for highway vibration loads.
- Collapsible Desks:Telescoping aluminum frames target sub-400 square foot urban residential units from São Paulo to Lagos.
Volume placements concentrate in Folding Chairs; the faster expansion belongs to Portable Cabinets.
Material:
Cost tier positioning separates commodity inputs from certified specialty grades that unlock institutional tender eligibility.
- Wood:Engineered panels face REACH substance screening accelerating bio-based adhesive R&D. Formaldehyde compliance divergence forces dual-SKU production for US-bound versus European-bound shipments.
- Metal:Scrap price swings and Indonesian nickel export licensing delays compress margin on tubular chair frames. Foshan forging concentration exposes buyers to single-region disruption.
- Plastic:High-density polyethylene dominates outdoor recreation applications with cycle-tested durability ratings.
- Fabric:Upholstery specifications in contract hospitality require fire-safety certification alignment with evolving standards.
- Composite:Thermoplastic laminates deliver 40 percent weight reduction for high-cycle table surfaces. Netherlands municipal venues specify these materials where handling labor costs dominate.
Metal commands institutional volume share; composite materials are climbing the fastest on margin contribution.
Application:
Customer-type procurement scale determines whether vendors prioritize capital sale models or subscription-based service contracts.
- Residential Use:Space-constrained urban housing in China, India, and Germany drives modular system adoption. Floor plans below 400 square feet force daily collapse-and-deploy cycles.
- Commercial Offices:Corporate real estate departments are unbundling ownership from facility management. London and Singapore satellite office networks drive full-service leasing with refresh guarantees.
- Educational Institutions:Intensive utilization cycles drive replacement frequency. ISO 7170 durability validation queues at Stuttgart and Shanghai laboratories create certification bottlenecks.
- Event Venues:Stackable seating specifications concentrate demand in metal-framed products with rapid deployment requirements.
- Outdoor Activities:Van-life permanence expands vehicle-integrated bed systems and telescoping storage rated for highway vibration.
Educational Institutions anchor replacement-driven volume; Commercial Offices show steepest expansion trajectory as service contracts displace capital sales.
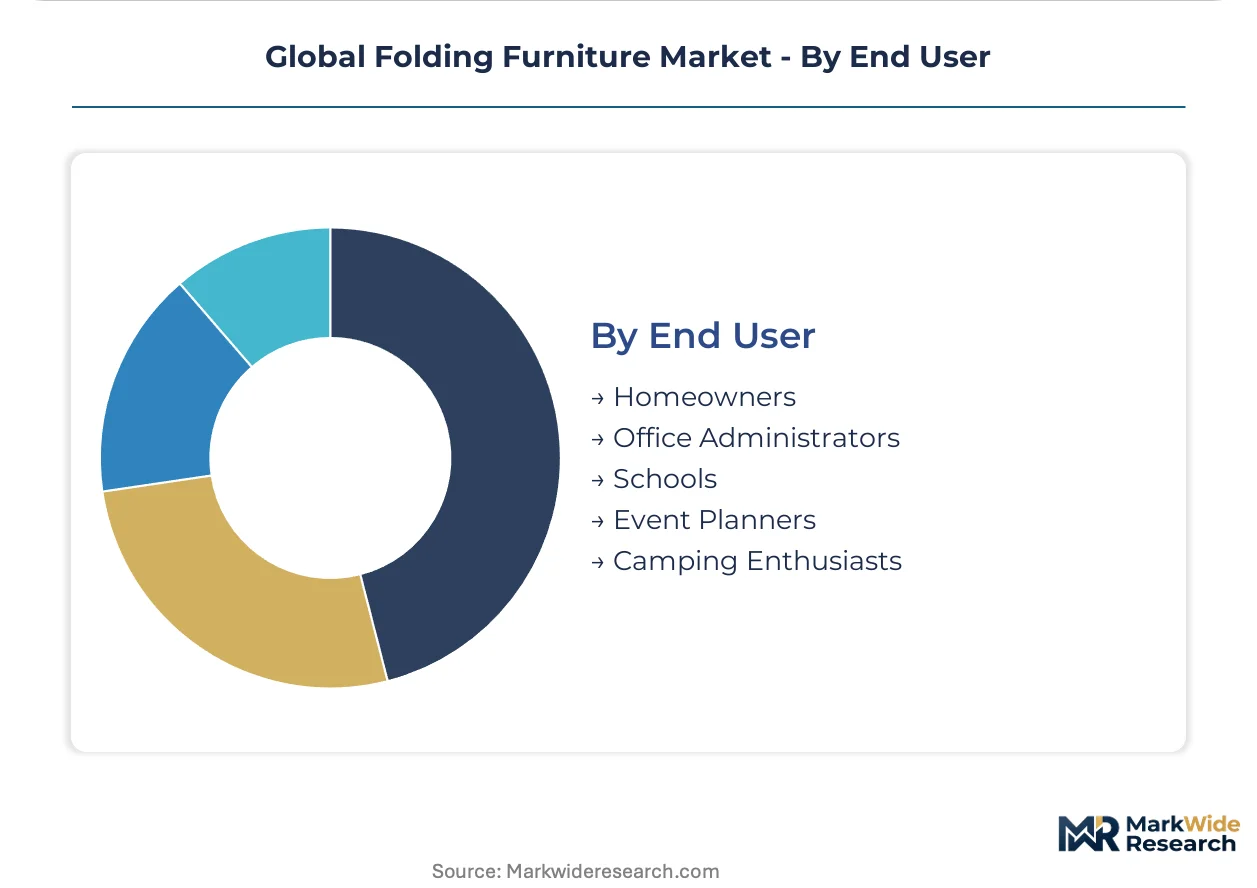
End User:
Decision-maker sophistication separates price-sensitive bulk procurement from specification-driven premium selection.
- Homeowners:E-commerce configurators and flat-pack logistics networks dominate purchase pathways. Inter IKEA Systems B.V. infrastructure shapes delivery expectations.
- Office Administrators:Facility management contracts increasingly incorporate furniture-as-a-service terms. Berlin and Barcelona co-living operators pilot RFID-embedded fleet tracking.
- Schools:Standardized tender volumes under India's Smart Cities Mission create procurement scale for metal-framed seating.
- Event Planners:Rental fleet economics favor rapid-deployment metal products with minimal setup labor.
- Camping Enthusiasts:Weight-rated composite materials command premium positioning in outdoor recreation segments.
Schools drive standardized volume; Office Administrators are gaining share fastest as subscription models consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates forging capacity for hinge mechanisms while Germany and India absorb finished goods. Consumption clusters in dense metropolitan housing markets where floor-plan compression drives modular adoption. Regulatory divergence between EPA thresholds and EU REACH substance lists shapes dual-track production strategies.
China
Guangdong Province hosts seventy percent of global hinge mechanism forging capacity within 200 kilometers of Foshan. GB standards and SAMR quality certification govern export-competitive manufacturing benchmarks for engineered wood laminates. Shenzhen and Guangzhou furniture clusters face weather and labor disruption risks that expose buyers to single-region concentration.
Germany
EU ECHA substance screening accelerates R&D into bio-based adhesives for residential compact living solutions. REACH Phase-In Restrictions and F-Gas Regulation phase-down schedules eliminate hydrofluorocarbon blowing agents from upholstered foldable beds. Stuttgart laboratories queue ISO 7170 durability validation for 12-18 month certification cycles.
India
Smart Cities Mission mandates multi-use community halls in 100 urban clusters, creating standardized tender volumes for metal-framed stackable seating. PLI scheme extensions for furniture manufacturing offset 15-20 percent of capital equipment costs for mechanized folding bed assembly lines. Mumbai and Delhi vertical housing booms compress residential floor plans below 400 square feet.
United States
EPA formaldehyde emission standards constrain engineered wood sourcing for domestic production. California Air Resources Board Phase 2 thresholds diverge from EU E1 benchmarks, forcing dual-SKU production runs for US-bound versus European-bound panels. Remote work permanence expands demand for vehicle-integrated folding bed systems in Colorado and California van-life markets.
Indonesia
Jakarta's vertical housing boom lacks domestic folding furniture manufacturing, creating import substitution potential for Malaysian and Vietnamese exporters. Nickel export licensing delays squeeze margin on tubular steel chair production. The country's national quality regulator shapes import standards for institutional procurement.
Global Folding Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the folding furniture value chain. The market structure fragments between integrated manufacturers controlling forging and laminating operations and brand licensors outsourcing production to contract fabricators. Three archetypes dominate: flat-pack logistics specialists, hardwood mechanism specialists, and component supply houses. Capacity expansion and strategic partnerships represent the dominant competitive moves as vendors secure hinge mechanism supply and certified laboratory queue positions.
Among North American fabricators, Ashley Furniture Industries and La-Z-Boy Inc. occupy positions in the hardwood and upholstered mechanism tier. Inter IKEA Systems B.V. exemplifies the flat-pack logistics archetype with its infrastructure for urban delivery networks. Leggett & Platt, Inc. anchors the component supply segment through its position in foldable bed mechanisms. These three companies represent distinct strategic vectors: brand-licensed retail distribution, integrated manufacturing, and captive component supply.
| Leading Market Players |
|---|
| Inter IKEA Systems B.V. |
| Ashley Furniture Industries |
| Dorel Industries Inc. |
| Flexsteel Industries, Inc. |
| Haworth Inc. |
| Meco Corporation |
| Leggett & Platt, Inc. |
| La-Z-Boy Inc. |
| Lifetime Products Inc. |
| Others |
Supply & Pricing Matrix
Scrap metal price index volatility cascades through tubular steel chair production into three-tier pricing structure across premium, standard, and economy levels, with Indonesian nickel export licensing delays amplifying cost compression in metal-framed segments while bio-based adhesive premiums reshape engineered wood laminates for EU-bound shipments.
Pricing Analysis
Margin tightening in standard-tier metal-framed seating reflects scrap price swings and Guangdong forging concentration. Pricing stratifies across premium, standard, and economy tiers based on ISO 7170 certification status and after-sales service bundling. Cost-down pressure on economy-tier polypropylene seating accelerates because Indonesian nickel licensing delays squeeze contract pricing. Educational institutions exhibit highest price sensitivity through bulk tender volumes; hospitality buyers show lowest sensitivity for mechanism-rated foldable beds.
Supply Chain Analysis
Workforce availability constraints in Guangdong Province and Foshan hinge-forging clusters tether production schedules to regional labor migration patterns. Supply concentrates in China, Vietnam, and Malaysia for finished goods assembly. Raw material dependencies center on Indonesian nickel, engineered wood laminates, and thermoplastic composites. Single-source vulnerability from seventy percent global hinge capacity within 200 kilometers of Foshan exposes buyers to weather and labor disruption. Distribution runs through flat-pack logistics networks and institutional procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Phase-In Restrictions and divergent formaldehyde compliance thresholds between EPA CARB Phase 2 and EU E1 benchmarks erect compliance moats that favor incumbent manufacturers with certified laboratory queue positions and dual-track production capabilities.
For Market Incumbents: Deepen backward integration into hinge mechanism forging to offset Guangdong supply concentration risk. Secure captive bio-based adhesive supply chains ahead of REACH substance screening deadlines. Capacity addition in Vietnam or Malaysia diversifies geographic exposure against single-region disruption threats.
For New Entrants and Emerging Players: Office administrators in Berlin and Barcelona co-living networks represent underserved buyer archetype for RFID-embedded furniture-as-a-service contracts. Jakarta vertical housing boom offers import substitution entry point for Malaysian exporters. Subscription pricing with refresh guarantees provides differentiated go-to-market angle against transactional incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mechanized folding bed assembly lines in India with PLI scheme qualification. Long-term viability hinges on certification backlog resolution and regulatory chemistry adaptation. Watch ISO 7170 laboratory queue clearance rates as inflection indicator for mechanism-rated product availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hinge Forging | Captive supply of Foshan-grade mechanisms insulates against nickel price volatility and labor disruption. |
| Bio-Based Adhesive R&D Investment | REACH-compliant chemistry unlocks EU institutional tender eligibility ahead of phase-in deadlines. |
| RFID Fleet Tracking Deployment | Real-time inventory monitoring enables subscription pricing for Berlin and Barcelona co-living operators. |
| Dual-Certification Production Lines | Parallel EPA CARB Phase 2 and EU E1 compliance eliminates dual-SKU friction for export-bound panels. |
| India PLI-Qualified Capacity Buildout | Mechanized folding bed assembly offsets capital costs through production-linked incentives for Smart Cities procurement. |
Research Methodology
Multi-period observation of scrap metal price indices, laboratory certification queue lengths, and institutional tender volumes anchored the trend analysis, supplemented by interviews with plant managers at Guangdong forging clusters, procurement leads at Indian municipal corporations, R&D directors at engineered wood laminate manufacturers, and facility managers at Berlin co-living operators. Secondary validation drew from customs trade data, SAMR quality certification records, EU ECHA substance screening updates, and SEC 10-K filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, material grade, application intensity, and end-user sophistication shaped the analytical framework. Modeled dimensions included replacement-cycle frequency, certification tier, and geographic regulatory cluster. CAGRs derived from regression analysis of historical procurement patterns and projected urban densification trajectories. Forecast inputs incorporated van-life vehicle registration trends and Smart Cities Mission tender release schedules.
Revisions become necessary when REACH substance screening accelerates beyond current R&D timelines, nickel export licensing regimes shift, or laboratory certification queues extend beyond operational planning horizons. Forecasts reflect documented assumptions regarding regulatory stability and raw material supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Australia Smart Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Italy Luxury Furniture Market
Furniture
Fireplace Mantels Market
Furniture
Salon Chairs Market
Furniture
GCC Smart Furniture Market
Furniture
Saudi Arabia Furniture Market
Furniture
Wooden Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
US Multifunctional Furniture Market
Furniture
Brazil Furniture Market
Furniture
Kids Table and Chair Market
Furniture
Indonesia Furniture Market
Furniture
Germany Home Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market