
 Europe Sustainable Furniture Market | 2026-2036
Europe Sustainable Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Furniture Market Foresight
Direct-to-contractor channels is reconfiguring how sustainable furniture reaches commercial buyers across Europe. IKEA Group leverages its captive supply of certified timber and flat-pack logistics to dominate mass-market distribution. Vitra International AG anchors its position through deep integration with Swiss and German design studios. Grüne Erde differentiates via strict organic material sourcing that commands premium placement in specialty retail.
Europe sustainable furniture encompasses seating, storage, and surface products manufactured with Forest Stewardship Council-certified wood, recycled metals, or bio-based composites meeting EU Ecolabel criteria, serving residential, commercial, and hospitality interiors where lifecycle carbon accounting now governs procurement. Recycled wood leads material value pools due to established certification infrastructure and builder familiarity, while eco-friendly composite posts the fastest structural ascent as petrochemical alternatives mature. The office end user segment sustains above-average specification rates because corporate ESG mandates embed furniture purchasing into scope-three reduction programs.
REACH, the EU Green Deal, and the Ecodesign for Sustainable Products Regulation collectively mandate chemical disclosure, recycled content minimums, and digital product passports that reshape competitive access across member states. ECHA substance restrictions now extend to flame retardants and finishes common in upholstered goods, forcing reformulation investments. Stakeholders must monitor how the CSRD's supply-chain reporting requirements will cascade into furniture vendor qualification criteria before the next procurement cycle closes.
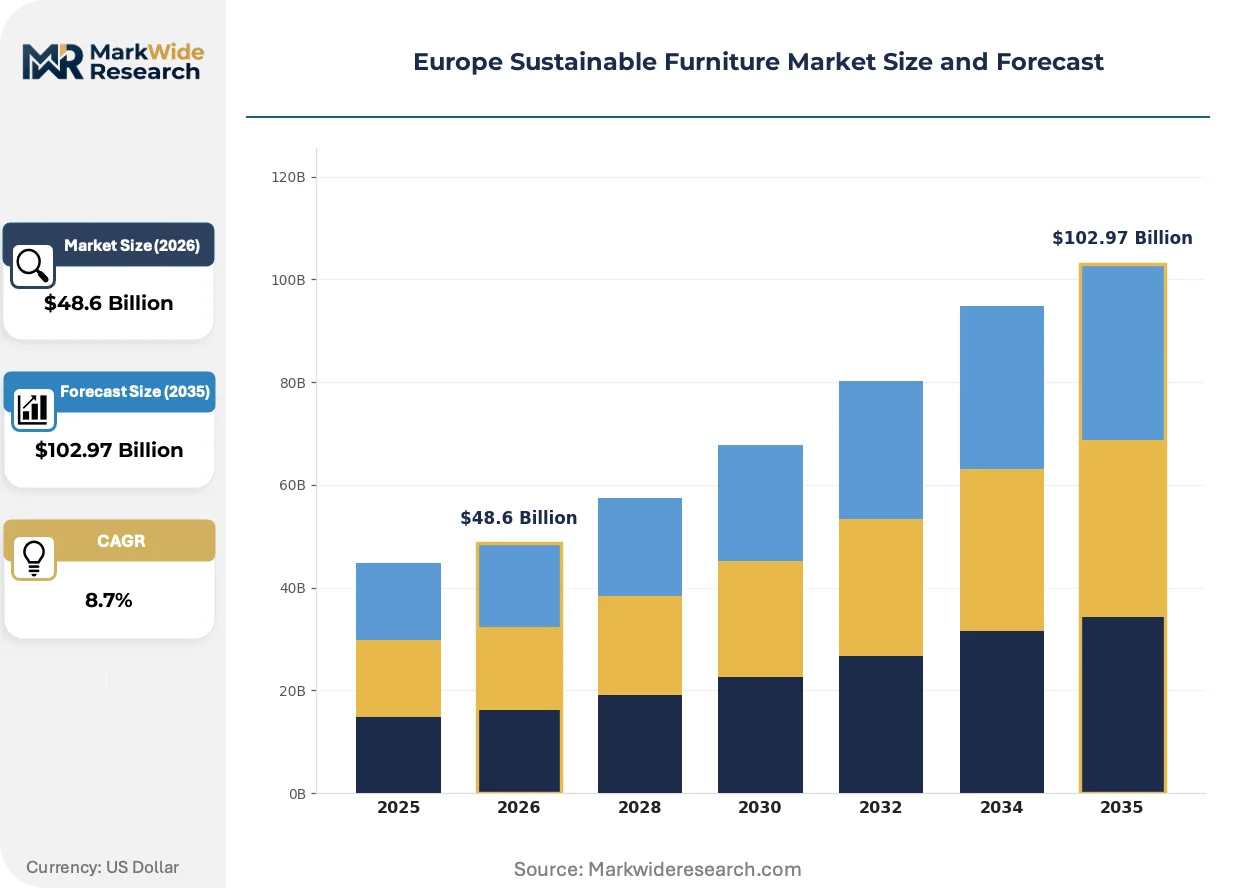
Market Dynamics
Digital product passports mandated by the Ecodesign for Sustainable Products Regulation are compressing certification timelines and forcing upstream material disclosure from Baltic timber suppliers through German upholstery finishers.
Growth Catalysts
- EU Green Deal procurement mandates:Public sector buyers in Denmark and the Netherlands now require Ecolabel-certified furniture for office fit-outs above threshold contract values.
- Bio-based composite maturation:Mycelium and hemp-based alternatives to polyurethane foam are reaching production scale in Portuguese manufacturing clusters.
- Hospitality ESG integration:Nordic hotel chains embed lifecycle carbon accounting into FF&E specifications, pulling certified seating and surface products through specification channels.
Market Restraints
- Certified timber supply concentration:FSC-controlled wood flows disproportionately through Baltic states, creating chokepoint vulnerability for German and Polish manufacturers.
- REACH chemical reformulation costs:ECHA restrictions on halogenated flame retardants force upholstery producers to retool finishing lines without guaranteed performance equivalence.
- Recycled metal price volatility:Scrap aluminum and steel input costs fluctuate with energy-intensive reprocessing economics, compressing margin predictability for frame producers.
Strategic Opportunities
- Digital product passport services:Compliance software vendors can capture recurring revenue from mid-tier manufacturers lacking in-house traceability infrastructure.
- Circular take-back programs:Furniture-as-a-service models in Dutch and Belgian commercial real estate create recurring revenue streams and material recovery control.
- Eastern European manufacturing expansion:Romanian and Bulgarian production zones offer proximity to raw material clusters with lower labor cost structures than Western European competitors.
Industry Challenges
- Lifecycle assessment talent scarcity:Manufacturers struggle to hire analysts capable of modeling scope-three carbon for complex multi-material products.
- Legacy ERP integration friction:Existing inventory systems lack granularity to track batch-level certification data required for digital passports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Furniture Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $102.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Recycled Wood, Bamboo, Metal, Eco-Friendly Composite Product Type: Chairs, Tables, Cabinets, Sofas End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online Retail, Specialty Stores, Furniture Chains, Direct Sales |
| Companies Covered | IKEA Group, Vitra International AG, Steelcase Inc., Herman Miller Inc., Haworth Inc., Grüne Erde, Bolia, Ekomia, Poltrona Frau, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Furniture Market Shifts & Advancements
Material traceability infrastructure and circular service models are converging to reshape how furniture value is captured and measured across European supply chains.
Blockchain-enabled supply chain verification is digitizing timber provenance documentation from forest harvest through mill processing. German and Austrian office furniture manufacturers are piloting these systems to satisfy corporate buyer audit requirements. The technology is digitizing compliance workflows that previously required manual certificate aggregation across multi-tier supplier networks.
The Ecodesign for Sustainable Products Regulation mandates recycled content minimums and material disclosure thresholds that phase in through 2027. Upholstered goods producers face particular pressure as foam and textile layers fall under expanded substance restriction schedules. French and Italian luxury seating manufacturers are accelerating reformulation programs to maintain premium positioning under tightened chemical compliance.
Corporate buyers now unbundle specification authority from traditional dealer networks, engaging manufacturers directly for large-scale fit-out programs. Facility management teams in London and Frankfurt financial services are consolidating vendor panels to reduce transaction overhead. This concentration is most visible in commercial office verticals where procurement functions centralize across multinational footprints.
Europe Sustainable Furniture Market Segmentation
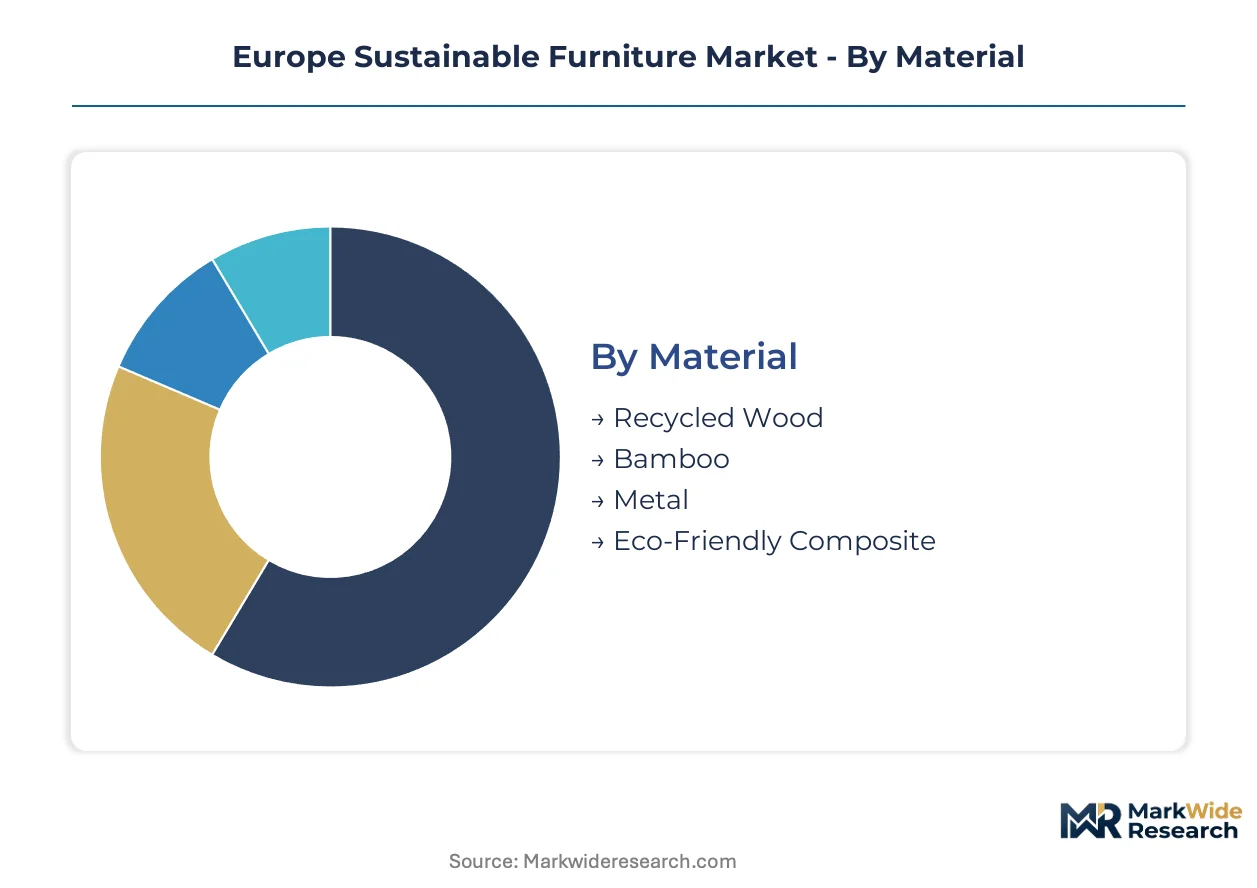
Material certification tiers, product complexity, and procurement channel structure each reshape margin capture and compliance burden for sustainable furniture suppliers across Europe. Understanding how demand fragments across these dimensions reveals where specification authority concentrates and where reformulation investments yield competitive defense.
Material:
Cost tier determines certification infrastructure requirements and supplier qualification timelines for European manufacturers.
- Recycled Wood:FSC-certified reclaimed timber and post-industrial wood waste dominate specification sheets for German office fit-outs. Baltic suppliers control the majority of certified feedstock flows, creating chokepoint vulnerability for Polish and Czech manufacturers dependent on traceable inputs.
- Eco-Friendly Composite:Mycelium binders, hemp fiber matrices, and bio-based resins replace petroleum-derived components in Portuguese pilot facilities. Nordic hospitality chains are pulling these materials through specification channels as lifecycle carbon accounting tightens procurement criteria for FF&E programs.
- Bamboo:Rapid-renewable grass species processed into panel and veneer products serves mid-market residential demand through Dutch and Belgian retail channels.
- Metal:Recycled aluminum and steel frames meet durability requirements for commercial seating, though scrap input price volatility compresses margin predictability for frame producers.
Recycled wood commands the established base. The steepest expansion runs through eco-friendly composite.
Product Type:
Application complexity dictates the depth of material disclosure and the intensity of chemical compliance scrutiny under REACH schedules.
- Chairs:Task seating and visitor chairs incorporate multi-material assemblies—frames, foam, textiles, and finishes—that trigger comprehensive substance restriction protocols. Corporate ESG mandates in London and Frankfurt financial services are embedding these products into scope-three reduction programs.
- Sofas:Upholstered goods face expanded ECHA restrictions on halogenated flame retardants, forcing French and Italian luxury manufacturers to accelerate reformulation timelines. The foam and textile layers in these products fall under the most demanding disclosure thresholds.
- Tables:Surface products with simpler material assemblies—primarily wood, metal, or composite tops with leg structures—navigate lighter compliance burdens.
- Cabinets:Storage systems for residential and commercial interiors balance material volume against functional standardization.
Chairs anchor specification volume across corporate procurement panels. Sofas are climbing the fastest as hospitality ESG integration deepens.
End User:
Customer type determines whether purchasing authority centralizes through facility management functions or fragments across individual decision-makers.
- Office:Corporate real estate and procurement teams in multinational financial services consolidate vendor panels to reduce transaction overhead. Ecolabel certification is now embedded into threshold contract values for fit-out programs above public sector mandates in Denmark and the Netherlands.
- Hospitality:Nordic hotel chains are unbundling specification authority from traditional dealer networks, engaging manufacturers directly for large-scale FF&E programs. Lifecycle carbon accounting governs these procurement decisions.
- Residential:Individual consumers purchase through retail channels where organic material sourcing and premium positioning differentiate specialty offerings.
- Commercial:Mixed-use real estate and co-working operators balance cost control against certification requirements in flexible lease structures.
Office end users anchor centralized procurement volume. Hospitality is expanding most quickly as direct manufacturer engagement displaces traditional dealer intermediation.
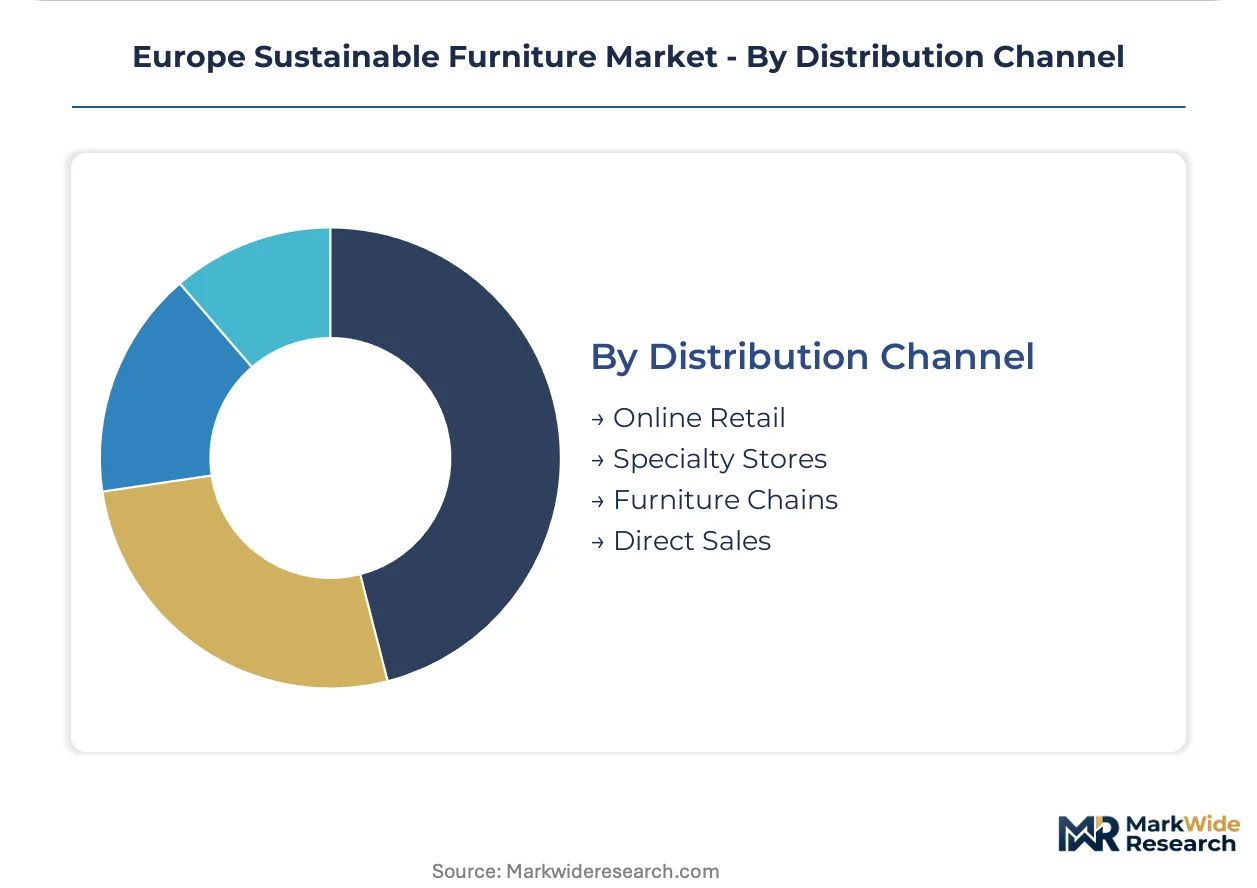
Distribution Channel:
Supply concentration shapes how certification data flows from Baltic timber suppliers through to final specification authorities.
- Direct Sales:Facility management teams in Frankfurt and London financial services are consolidating vendor relationships for multinational footprint efficiency. This channel captures the deepest material disclosure and batch-level certification data required for digital product passports.
- Furniture Chains:IKEA Group leverages captive certified timber supply and flat-pack logistics to dominate mass-market distribution across Northern Europe.
- Specialty Stores:Grüne Erde and comparable operators command premium placement through strict organic material sourcing and design studio integration.
- Online Retail:Digital channels serve price-sensitive residential demand with limited certification transparency.
Furniture chains hold the volume base. Direct sales is gaining share fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command premium pricing power over Polish competitors due to tighter Ecodesign compliance infrastructure and direct corporate procurement relationships. Baltic timber flows concentrate specification authority in Hamburg and Berlin clusters. Southern European producers face margin compression from slower digital passport adoption timelines.
Germany
Corporate ESG mandates from Frankfurt financial services and Hamburg hospitality procurement drive specification volume. The Ecodesign for Sustainable Products Regulation forces upstream material disclosure from upholstery finishers. Berlin circular economy clusters host mycelium composite pilot facilities serving Nordic hotel chains.
Netherlands
Public sector procurement mandates require Ecolabel-certified furniture for office fit-outs above threshold contract values. The EU Green Deal procurement rules accelerate specification authority consolidation. Rotterdam logistics hubs integrate digital product passport workflows for Baltic timber imports.
Sweden
Nordic hotel chains embed lifecycle carbon accounting into FF&E specifications, pulling certified seating through direct manufacturer channels. REACH chemical restrictions force reformulation of halogenated flame retardants in upholstered goods. Stockholm design studios anchor premium positioning for bio-based composite seating.
Italy
French and Italian luxury seating manufacturers accelerate foam reformulation programs under tightened ECHA compliance schedules. The CSRD supply-chain reporting requirements cascade into vendor qualification criteria. Milan furniture districts face compressed timelines for digital passport integration.
Poland
Manufacturers dependent on Baltic FSC-certified feedstock face chokepoint vulnerability from concentrated supplier geography. Polish upholstery producers absorb REACH reformulation costs without guaranteed performance equivalence. Warsaw production zones compete on labor cost structures against Western European specification leaders.
Europe Sustainable Furniture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying certified timber and bio-based foams to finished goods assemblers. The vendor base stratifies across three tiers: mass-market distributors with captive logistics networks, premium design houses with studio integration, and mid-tier manufacturers racing to deploy traceability infrastructure. Two dominant competitive moves define current positioning: direct-to-contractor channel expansion displacing traditional dealer networks, and circular take-back program deployment capturing recurring revenue streams.
Among mass-market platform operators, IKEA Group exemplifies scale-driven supply chain control through flat-pack logistics and certified timber integration. Vitra International AG and Grüne Erde occupy differentiated positions at opposite ends of the premium spectrum—Vitra anchoring Swiss-German design studio relationships, Grüne Erde representing strict organic material sourcing archetypes that command specialty retail placement.
| Leading Market Players |
|---|
| IKEA Group |
| Vitra International AG |
| Steelcase Inc. |
| Herman Miller Inc. |
| Haworth Inc. |
| Grüne Erde |
| Bolia |
| Ekomia |
| Poltrona Frau |
| Others |
Supply & Pricing Matrix
Overcapacity in Baltic FSC-certified timber processing is compressing supplier margins while concentrating pricing power among German manufacturers with direct corporate procurement relationships. Utilization rates below break-even thresholds in Estonian and Latvian sawmills are forcing extended payment terms and selective order fulfillment that reshape downstream contract negotiations.
Pricing Analysis
Configured-to-order pricing commands a 25-40% premium over standard catalog configurations across commercial seating and storage systems. Pricing stratifies across premium, standard, and economy tiers based on certification grade and customization level. Cost compression in mid-tier upholstered goods is intensifying because REACH reformulation investments are not yet recoverable through volume scale. Corporate procurement panels in Frankfurt and London show lowest price sensitivity, while Dutch and Belgian co-working operators exhibit highest sensitivity to per-unit landed cost.
Supply Chain Analysis
Extended payment terms from Baltic timber suppliers are cascading liquidity pressure through Polish and Czech upholstery finishers. Supply concentrates in Estonia, Latvia, and Lithuania for certified wood feedstock, with Portuguese clusters emerging for mycelium composite production. The chain rests on FSC-controlled timber, bio-based foam precursors, and recycled aluminum frame stock. Single-source vulnerability runs through concentrated Baltic sawmill geography. Distribution runs through direct sales channels for corporate fit-outs and flat-pack logistics for mass-market retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
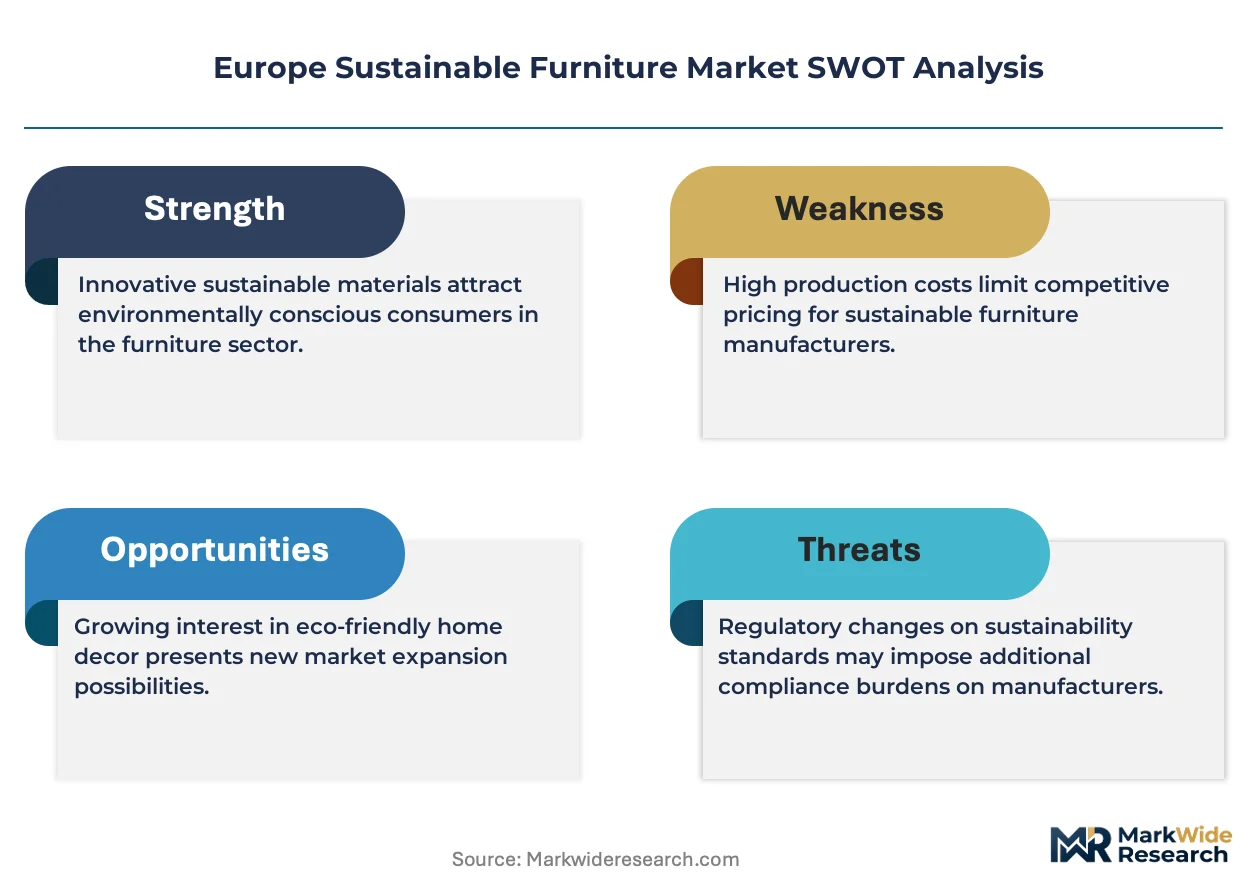
The Europe sustainable furniture market is entering a cyclical recovery phase driven by corporate real estate refresh cycles delayed during prior uncertainty. Public sector procurement mandates in Denmark and the Netherlands are accelerating specification volume through threshold contract triggers.
For Market Incumbents: Build certification infrastructure moats by embedding digital product passport capabilities ahead of Ecodesign phase-in deadlines. Deepen backward integration into Baltic timber sourcing to secure FSC-controlled feedstock against chokepoint vulnerability. Acquire mid-tier upholstery finishers in Poland and Romania to capture cost-advantaged production capacity before CSRD reporting requirements cascade into vendor consolidation. For New Entrants and Emerging Players: Eastern European manufacturing zones offer underpenetrated access to corporate procurement panels seeking alternative suppliers to German incumbents. Target Romanian and Bulgarian production bases with lower labor cost structures and proximity to raw material clusters. Penetrate the hospitality FF&E segment through direct manufacturer engagement models that bypass traditional dealer networks. Lead with circular take-back program offerings that align with Nordic hotel chain ESG mandates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among furniture-as-a-service operators with embedded material recovery control. Long-term viability over the next decade favors platform integrators with captive supply chain infrastructure over pure-play component assemblers. Monitor acquisition targets among Portuguese mycelium composite pilot facilities and mid-tier manufacturers with deployed traceability infrastructure. The signal to watch is CSRD supply-chain reporting adoption rates among German corporate buyers, which will trigger vendor panel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Deployment | Captures compliance software revenue from Ecodesign-mandated material disclosure requirements. |
| Backward Integration into Certified Timber | Secures FSC-controlled Baltic feedstock against supply chokepoint vulnerability. |
| Circular Take-Back Program Launch | Generates recurring revenue streams aligned with Nordic hospitality ESG integration. |
| Eastern European Manufacturing Expansion | Accesses lower-cost Romanian and Bulgarian production zones with raw material proximity. |
| Direct-to-Contractor Channel Buildout | Displaces traditional dealer intermediation in Frankfurt and London financial services procurement. |
Research Methodology
A standing panel of procurement directors at multinational financial services firms, sustainability officers at Nordic hospitality chains, upholstery production managers in Poland and Portugal, and facility management executives in Dutch commercial real estate provided ongoing calibration across the study. Primary interviews combined with secondary validation from EU Ecolabel certification databases, ECHA substance restriction filings, Baltic timber trade flow records, and corporate ESG disclosure reports. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Scenario-bracketing framed optimistic and conservative demand trajectories across the projection horizon. Segmentation dimensions modeled include material certification tier, product complexity class, end-user procurement structure, and distribution channel concentration. CAGRs derived from fitted growth curves applied to baseline and scenario-adjusted demand estimates. Industry-specific inputs encompassed corporate fit-out cycle timing, REACH reformulation cost pass-through elasticity, and digital passport adoption rates by manufacturer tier.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Baltic timber suppliers or accelerated CSRD enforcement by EU member states would shift outcomes. Macroeconomic deviation, regulatory timeline acceleration, or breakthrough bio-based composite cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Home Furniture Market
Furniture
North America School Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
US School Furniture Market
Furniture
Russia Home Furniture Market
Furniture
Bamboo Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
Exam Tables Market
Furniture
Japan Home Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Brazil Furniture Market
Furniture
Luxury Furniture Market
Furniture
US Secondary Wood Products Market