
 Lecterns Market | 2026-2036
Lecterns Market Size, Share, and Industry Trends Forecast 2026-2036
Lecterns Market Analytics
LEED v4.1 certification for commercial interiors is recalibrating material specifications across institutional furniture procurement. AmpliVox leverages its domestic manufacturing footprint to meet stringent volatile organic compound limits for educational sector bids. Intelligent Lectern Systems anchors its competitive position through integrated cable management and universal mounting standards. Heckler Design specializes in aluminum enclosures that satisfy both thermal performance and recyclability thresholds for corporate clients.
A lectern is a raised stand designed to support reading materials, presentation devices, or audio-visual equipment during speeches, lectures, or ceremonies, typically constructed with steel framing, engineered wood surfaces, or thermoformed acrylic shells and rated for load capacities between 50 and 150 pounds depending on integrated equipment specifications. Portable lecterns lead volume shipments due to flexible deployment in multi-use conference and worship spaces, while digital lecterns with embedded touch panels and HDMI connectivity represent the fastest-expanding margin pool as hybrid event formats persist. Wood materials sustain premium positioning in judicial and ceremonial applications where aesthetic gravitas commands higher procurement budgets.
The EPA Toxic Substances Control Act governs composite wood product formaldehyde emissions, directly constraining particleboard and medium-density fiberboard sourcing for domestic manufacturers. ISO 14001 environmental management certification functions as a de facto gate for contract eligibility within Fortune 500 corporate procurement frameworks. Stakeholders must monitor evolving e-waste directives affecting digital lectern retrofit cycles and embedded battery disposal pathways.
Market Dynamics
LEED v4.1 material specifications and hybrid event infrastructure requirements are restructuring procurement criteria across institutional furniture channels, compressing vendor qualification timelines while elevating integrated AV compatibility demands.
Growth Catalysts
- EPA TSCA Title VI formaldehyde limits:Composite wood emission standards are accelerating certified particleboard substitution with low-emitting alternatives in educational sector bids.
- State university system modernization:Public higher education capital programs in the United States are expanding smart classroom deployments with universal mounting standards.
- Thermoformed acrylic shell fabrication:Advances in vacuum-forming precision are enabling lighter load-bearing surfaces with integrated cable channels.
Market Restraints
- Aluminum alloy price volatility:LME aluminum fluctuations compress margin stability for metal-frame producers serving corporate clients.
- Domestic engineered wood supply concentration:Pacific Northwest mill capacity constraints create sourcing bottlenecks during Q3 institutional procurement peaks.
- HDMI standard obsolescence cycles:Digital connectivity protocol turnover forces premature retrofit costs for embedded touch-panel installations.
Strategic Opportunities
- Municipal government procurement digitization:E-procurement platform adoption in mid-sized US cities opens direct vendor access previously gated by distributor networks.
- Worship space multi-use conversion:Portable lectern demand is expanding in non-denominational venues seeking rapid reconfiguration capability.
- ISO 14001 certification arbitrage:Environmental management credentialing creates Fortune 500 contract eligibility for mid-tier domestic manufacturers.
Industry Challenges
- AV integration technician scarcity:Shortage of certified low-voltage installers delays digital lectern commissioning in hybrid event rollouts.
- E-waste directive compliance complexity:Embedded battery disposal pathways for touch-panel units require reverse logistics infrastructure most vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lecterns Market |
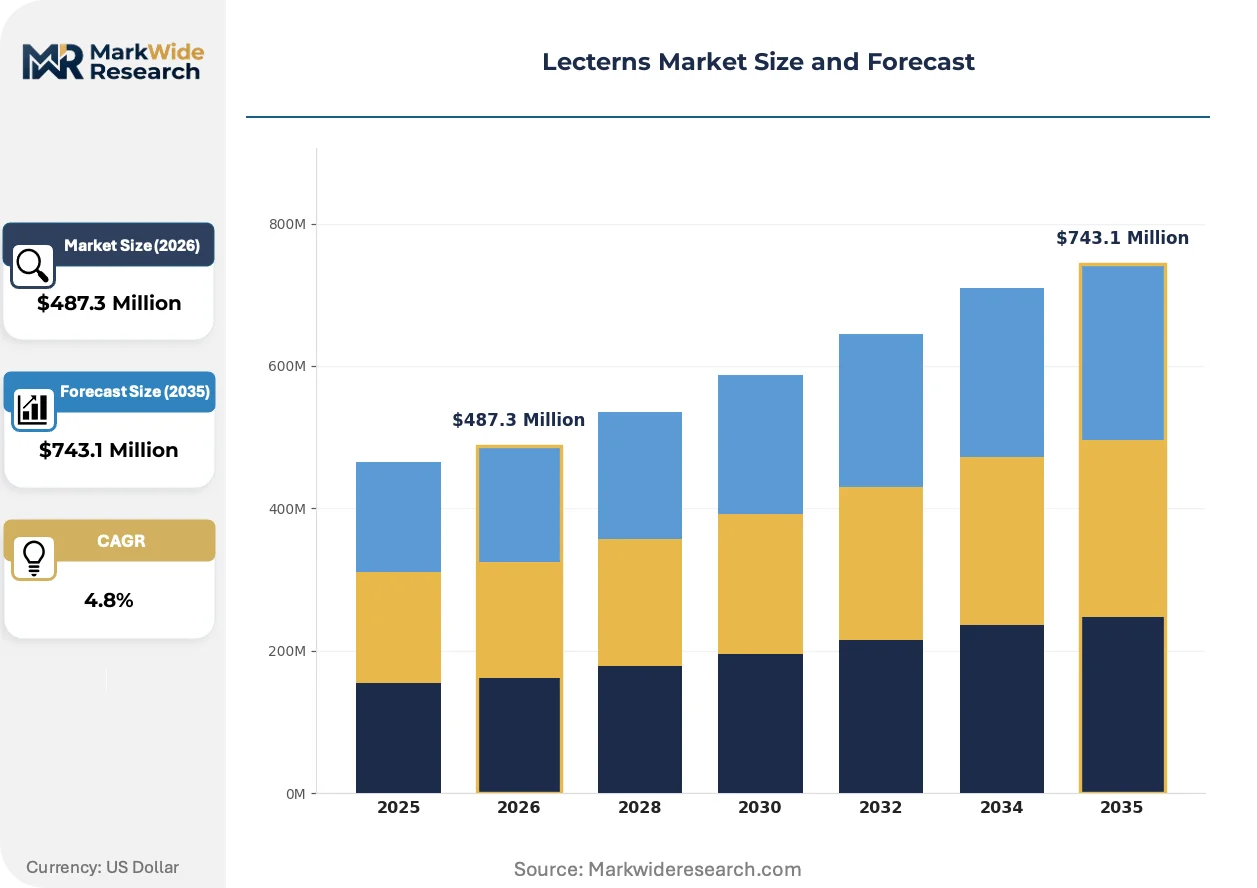
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Lecterns, Portable Lecterns, Digital Lecterns, Multi-Media Lecterns Material: Wood, Metal, Acrylic, Plastic End User: Educational Institutions, Corporate Offices, Government Agencies, Religious Organizations Feature: Height Adjustable, Built-in Sound System, Integrated Lighting, Lockable Storage |
| Companies Covered | Heckler Design, Intelligent Lectern Systems, AmpliVox, Du-Go, Soundfold, Avant, OCS, GF Podiums, Studio-RTA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lecterns Market Evolving Landscape
Material science advances and connectivity standard evolution are redefining product architecture, with sustainability credentials and modular adaptability emerging as primary competitive differentiators across institutional buyer segments.
Touch-panel interfaces with embedded HDMI 2.1 and USB-C connectivity are converging with steel-framing thermal management systems to enable all-in-one presentation hubs. State university systems are specifying these integrated units for new construction at accelerating rates. The technology is converging with cable management standards to compress installation timelines from days to hours.
REACH SVHC candidate list expansion is restricting chromate conversion coatings on aluminum enclosures across EU-bound shipments. German corporate procurement frameworks now mandate full material disclosure for furniture assemblies. Metal finish suppliers are accelerating trivalent chromium and zirconium-based pretreatment qualification to maintain contract eligibility.
Direct-to-institution sales channels are displacing traditional furniture dealer networks for digital lectern categories. Higher education facilities management departments are building in-house AV specification expertise to bypass markup layers. This pattern is most visible in University of California and Texas A&M system procurement, where centralized IT-facilities coordination is consolidating vendor pools.
Lecterns Market Segmentation
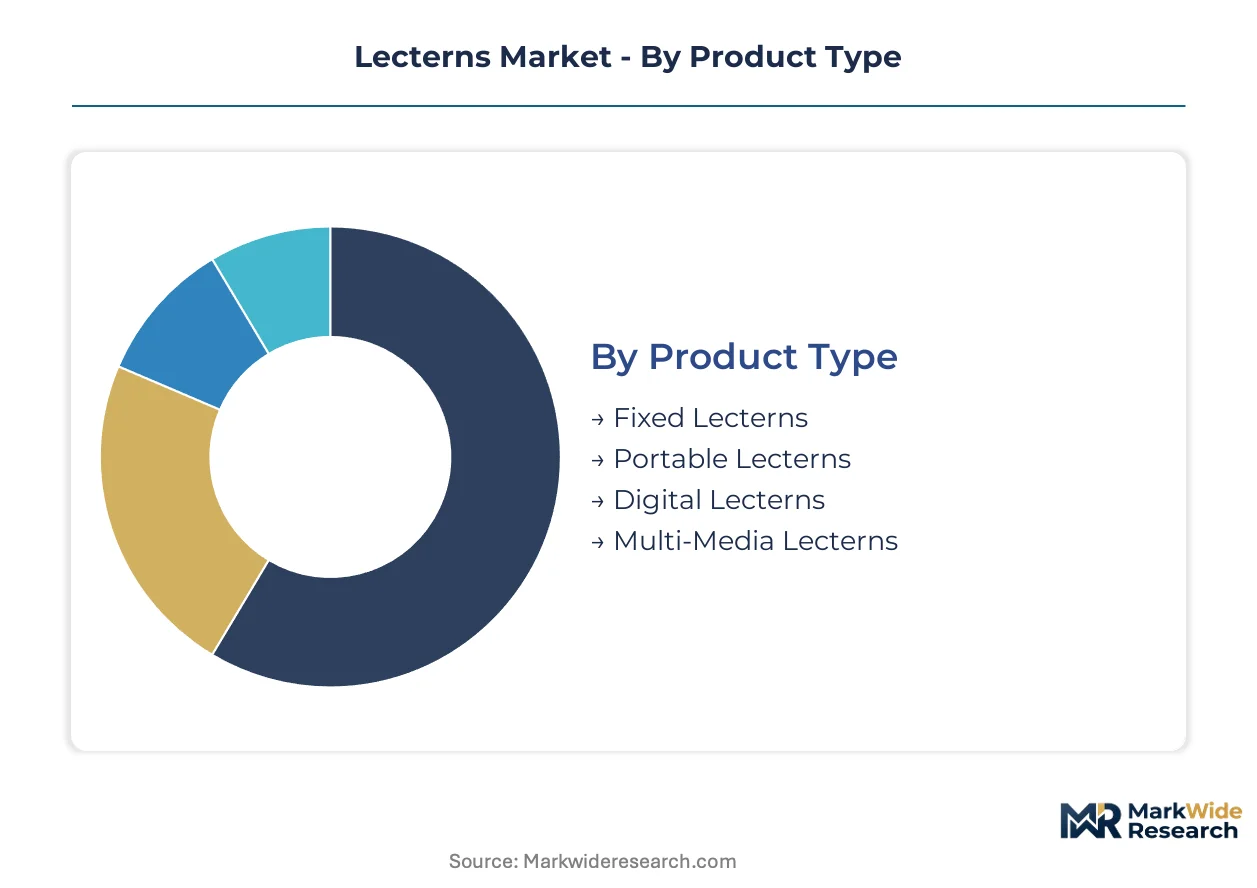
Product architecture in the lecterns market splits sharply between commodity volume plays and specification-driven premium tiers. Procurement channels favor different segment combinations depending on end-use durability requirements and AV integration complexity.
Product Type:
Volume leadership sits with portable units, while margin concentration follows embedded digital capabilities.
- Fixed Lecterns:Permanent steel-framed installations rated for 100-150 pound load capacities anchor judicial chambers and ceremonial halls. State university systems specify these for new lecture hall construction where structural integration with room architecture is required.
- Portable Lecterns:Lightweight aluminum or thermoformed acrylic designs with folding mechanisms dominate multi-use worship spaces and conference centers. Non-denominational venues in mid-sized US cities drive replacement cycles as rapid reconfiguration capability becomes standard.
- Digital Lecterns:Embedded touch panels with HDMI 2.1 and USB-C connectivity command premium positioning. Hybrid event infrastructure requirements are accelerating adoption across corporate training facilities.
- Multi-Media Lecterns:Integrated cable management and universal mounting standards serve smart classroom deployments. Higher education IT-facilities coordination is consolidating vendor pools around these all-in-one units.
Today's leader: Portable Lecterns. Tomorrow's challenger: Digital Lecterns.
Material:
Cost structure and certification compliance divide sourcing strategies across institutional buyer segments.
- Wood:Engineered hardwood and veneer surfaces sustain premium positioning where aesthetic gravitas commands procurement priority. Judicial applications and ceremonial settings specify sustainably sourced options to meet LEED v4.1 interior certification.
- Metal:Aluminum enclosures with trivalent chromium finishes satisfy thermal performance and recyclability thresholds. Corporate clients specify these for durability in high-frequency use environments.
- Acrylic:Thermoformed shells enable lighter load-bearing surfaces with integrated cable channels. Vacuum-forming precision advances are compressing production costs for mid-tier educational bids.
- Plastic:High-density polyethylene and polypropylene variants serve budget-conscious municipal procurement. EPA TSCA Title VI formaldehyde limits constrain composite wood substitution toward these polymer alternatives.
Wood commands specification authority. Metal captures volume scalability.
End User:
Procurement sophistication varies dramatically across institutional buyer maturity.
- Educational Institutions:Public higher education capital programs specify universal mounting standards and integrated AV compatibility. University of California and Texas A&M system procurement is consolidating vendor pools through centralized IT-facilities coordination.
- Corporate Offices:Fortune 500 frameworks mandate ISO 14001 environmental management certification as contract eligibility gate. Aluminum enclosure specifications prioritize thermal performance and recyclability credentials.
- Government Agencies:Municipal procurement digitization in mid-sized US cities opens direct vendor access previously gated by distributor networks. E-procurement platform adoption is compressing qualification timelines.
- Religious Organizations:Non-denominational venues seek rapid reconfiguration capability for multi-use space conversion. Portable lectern demand is expanding fastest in this segment.
Educational Institutions set technical specifications. Religious Organizations are expanding most quickly.
Feature:
Functional differentiation separates specification winners from commodity suppliers.
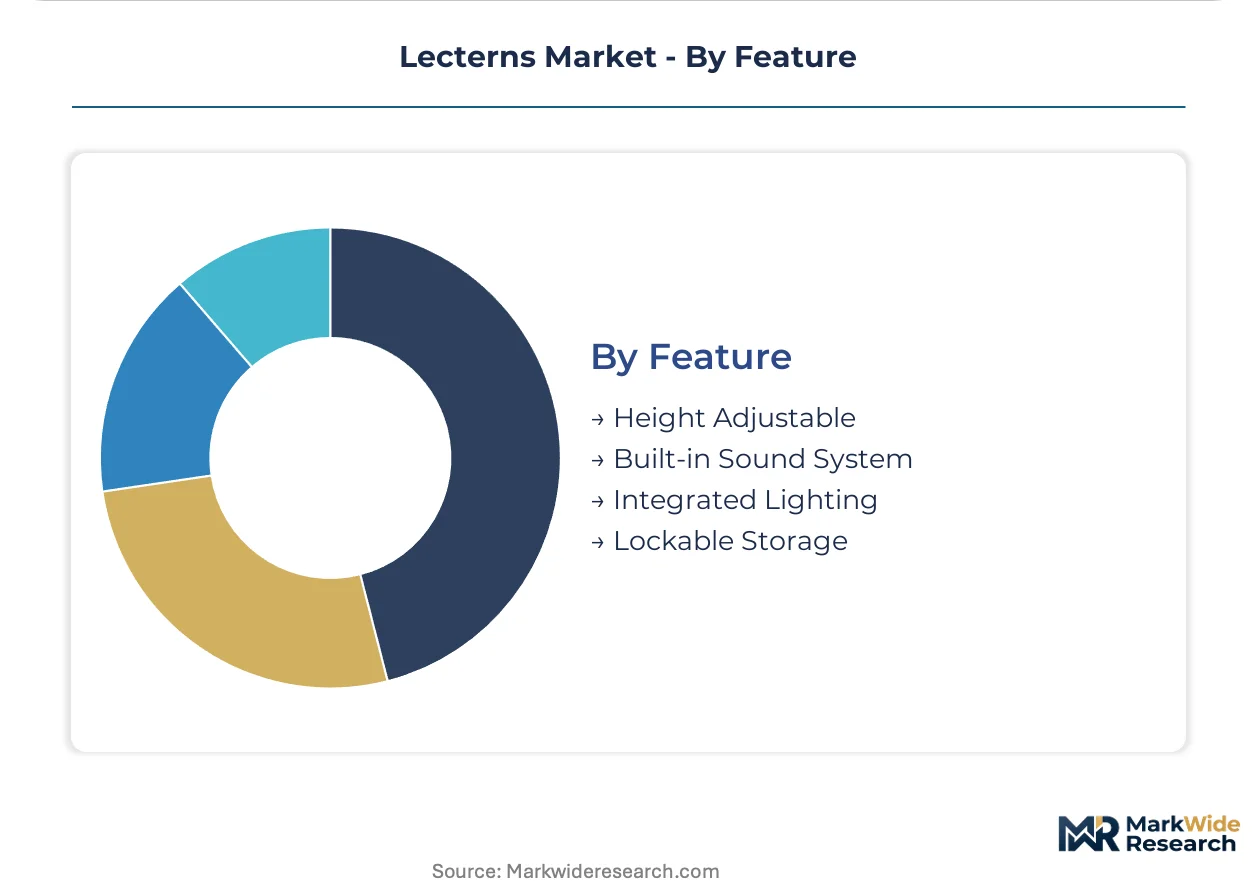
- Height Adjustable:Pneumatic or electric lift mechanisms accommodate presenter ergonomics across diverse user populations. ADA compliance requirements in public university systems mandate these specifications.
- Built-in Sound System:Integrated amplifier and microphone arrays reduce external AV dependency. Hybrid event formats are accelerating demand for self-contained audio solutions.
- Integrated Lighting:LED task illumination supports low-ambient presentation environments. Corporate training facilities specify these for video recording quality.
- Lockable Storage:Secure compartments protect embedded electronics and presentation materials. Government agency procurement prioritizes these for equipment security protocols.
Height Adjustable features dominate current specifications. Built-in Sound Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lectern industry traces its modern procurement scale to post-war American university expansion, with institutional furniture manufacturing consolidating around Great Lakes industrial centers before dispersing to specialized fabrication clusters across three continents.
United States
State university system capital programs in California and Texas anchor institutional demand, with centralized IT-facilities coordination consolidating vendor pools around universal mounting standards. EPA TSCA Title VI formaldehyde emission limits constrain composite wood sourcing, accelerating certified particleboard substitution in educational sector bids. The Pacific Northwest faces engineered wood supply bottlenecks during Q3 procurement peaks as mill capacity strains against institutional ordering cycles.
Germany
REACH SVHC candidate list expansion restricts chromate conversion coatings on aluminum enclosures, forcing metal finish suppliers toward trivalent chromium and zirconium-based pretreatment qualification. Corporate procurement frameworks now mandate full material disclosure for furniture assemblies bound for EU markets. The Rhine-Ruhr industrial corridor hosts specialized metal fabrication clusters serving Fortune 500 contract eligibility requirements.
China
Dual carbon policy targets are recalibrating export-oriented furniture manufacturing toward low-emission finishing processes and sustainably sourced wood certification. GB standards for indoor air quality in educational facilities increasingly mirror international emission protocols. The Yangtze River Delta concentration of thermoforming precision equipment enables lighter load-bearing surface production for mid-tier export bids.
United Kingdom
Higher education facilities management departments in London and the Southeast are building in-house AV specification expertise to bypass traditional furniture dealer networks. The country's national environmental regulator enforces volatile organic compound limits that align with LEED v4.1 interior certification thresholds. Midlands-based manufacturing clusters serve hybrid event infrastructure rollouts across corporate training facilities.
India
Bureau of Indian Standards certification for educational furniture is tightening formaldehyde emission benchmarks in public procurement tenders. State-level higher education modernization programs in Maharashtra and Karnataka are expanding smart classroom deployments with integrated cable management specifications. The Delhi-NCR corridor concentrates import-substitution manufacturing for digital lectern categories serving South Asian institutional buyers.
Lecterns Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and AV integration complexity, with the vendor base organizing into three discernible tiers. Domestic manufacturers with ISO 14001 environmental management credentials occupy the middle tier, capturing Fortune 500 contract eligibility previously gated by scale requirements. Strategic archetypes include integrated AV specialists, sustainable material fabricators, and portable equipment pure-plays. Competitive moves concentrate on direct-to-institution sales channel establishment and municipal e-procurement platform qualification.
Within the sustainable fabrication tier, AmpliVox and Heckler Design exemplify divergent material strategies, with the former representing domestic manufacturing footprint leverage and the latter anchoring aluminum enclosure specialization. Intelligent Lectern Systems occupies a position within the integrated AV tier, reflecting universal mounting standard adoption patterns visible across state university system procurement. These three entities collectively illustrate how certification compliance and connectivity specification depth determine contract access across institutional buyer segments.
| Leading Market Players |
|---|
| Heckler Design |
| Intelligent Lectern Systems |
| AmpliVox |
| Du-Go |
| Soundfold |
| Avant |
| OCS |
| GF Podiums |
| Studio-RTA |
| Others |
Value Network & Pricing Analysis
State university system procurement concentration anchors contract-based pricing structures across the institutional furniture channel, with bulk tender specifications compressing margin pools for commodity-grade portable units while premium digital lecterns sustain value-based positioning through AV integration complexity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates digital lecterns with embedded touch panels from multi-media units with cable management, then from basic portable designs. Price differentiation hinges on ISO 14001 certification status and volume scale, with Fortune 500 frameworks paying sustainability premiums. Cost compression in the economy tier is intensifying because EPA TSCA Title VI compliance adds certified particleboard sourcing overhead. Municipal government buyers exhibit highest price sensitivity, while corporate training facilities show lowest.
Supply Chain Analysis
Direct-to-institution sales channels handle higher education and Fortune 500 demand, bypassing traditional furniture dealer markups. Manufacturing concentrates in the United States, China, and Germany, with Pacific Northwest mill capacity constraining engineered wood availability. Raw material sourcing draws from aluminum alloy markets, thermoforming equipment clusters in the Yangtze River Delta, and sustainably harvested timber certified to LEED v4.1 thresholds. Single-source vulnerability sits with chromate conversion coating suppliers facing REACH SVHC restrictions. Distribution runs through municipal e-procurement platforms and centralized university system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the lecterns market rests on thermoformed acrylic shell fabrication advances that compress production costs for mid-tier educational bids, while digital lectern premiums widen through hybrid event infrastructure requirements.
For Market Incumbents: Anchor competitive position through backward integration into thermoforming equipment and captive supply of low-emitting engineered wood certified to EPA TSCA Title VI limits. Defend against emerging AV integration specialists by deepening universal mounting standard adoption across state university system contracts. Prioritize ISO 14001 credential maintenance for Fortune 500 eligibility gates.
For New Entrants and Emerging Players: Enter via municipal e-procurement platform qualification in mid-sized US cities, where distributor network displacement creates direct vendor access. Target non-denominational worship spaces seeking rapid reconfiguration capability, the most penetrable segment for portable lectern pure-plays. Pursue go-to-market positioning around ADA-compliant height adjustable specifications for public university system tenders.
For Investors and Strategic Acquirers: Integrated AV specialists with embedded touch-panel capabilities are the most active acquirer in this space, consolidating vendor pools as higher education IT-facilities coordination accelerates. Long-term viability favors manufacturers with environmental management certification and domestic fabrication footprints. Monitor HDMI standard obsolescence cycles as inflection indicator for premature retrofit cost exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Institution Channel Establishment | Bypasses furniture dealer markups in University of California and Texas A&M system procurement. |
| ISO 14001 Certification Investment | Opens Fortune 500 contract eligibility previously gated by scale requirements. |
| Backward Integration into Thermoforming | Captures vacuum-forming precision advances for lighter load-bearing surface production. |
| Municipal E-Procurement Platform Qualification | Compresses vendor qualification timelines in mid-sized US city government channels. |
| Universal Mounting Standard Adoption | Accelerates installation timeline compression from days to hours in smart classroom deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facilities management directors at state university systems, AV integration technicians, procurement officers at Fortune 500 corporate real estate divisions, and municipal government contract administrators with secondary validation against EPA TSCA filings, LEED project databases, SEC 10-K disclosures from publicly traded furniture manufacturers, and customs trade records for aluminum alloy and engineered wood imports. Bottom-up shipment data triangulated against top-down institutional capital expenditure budgets.
Segment-weighting applied differential growth assumptions across product type, material, end user, and feature dimensions, with portable lecterns receiving distinct trajectory parameters from digital lecterns over the projection horizon. CAGRs derived from historical shipment correlations with higher education construction permits and corporate training facility buildout rates. Forecast inputs incorporated REACH SVHC list expansion timelines and HDMI connectivity protocol turnover patterns.
Inputs from university procurement databases and municipal contract registries were available through the study window; gaps in real-time aluminum LME pricing and Pacific Northwest mill capacity utilization introduce uncertainty bands around margin projections. Forecasts reflect assumptions about hybrid event format persistence and LEED v4.1 adoption velocity across institutional buyers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
GCC Smart Furniture Market
Furniture
Global Furniture Fittings Market
Furniture
Japan Furniture Market
Furniture
Wooden Furniture Market
Furniture
Canada Home Furniture Market
Furniture
Children Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Bounding Table Market
Furniture
Massive Wood Slabs Market
Furniture
Germany Furniture Market
Furniture
Netherlands Home Furniture Market
Furniture
Asia-Pacific Contract Furniture Market