
 Banquet Carts and Heated Cabinets Market | 2026-2036
Banquet Carts and Heated Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Banquet Carts and Heated Cabinets Market Analysis
Stainless steel is decoupling from premium-only positioning as aluminum alloys and reinforced polymer composites penetrate mid-tier banquet cart production. Alto-Shaam leverages vertical integration across its Wisconsin manufacturing footprint to control thermal system quality. Carter-Hoffmann anchors its position through specialized heated cabinet engineering for healthcare and institutional channels. Cambro Manufacturing dominates mobile cart distribution through deep channel relationships with broadline foodservice dealers.
Banquet carts and heated cabinets are thermally insulated mobile or stationary units designed to maintain prepared food within safe temperature ranges, typically incorporating electric heating elements, humidity controls, and caster-based mobility systems for commercial foodservice operations. Heated cabinets with precision thermostatic control and programmable humidity settings command the strongest margin pools, while mobile carts face commoditization pressure in the standard-duty segment. Stainless steel construction leads material preference for durability and sanitation compliance, though aluminum gains traction in weight-sensitive catering applications where transport frequency is high.
The U.S. FDA Food Code and NSF International standards govern hot-holding equipment sanitation and thermal performance, compelling manufacturers to certify products for commercial kitchen compliance. The EPA Energy Star program and DOE commercial kitchen equipment standards are tightening efficiency requirements for electrically heated cabinets, reshaping R&D priorities toward reduced power consumption. Buyers must evaluate total cost of ownership across energy, maintenance, and replacement cycles rather than acquisition price alone as regulatory thresholds stiffen.
Market Dynamics
Energy efficiency mandates from the EPA and DOE are compressing thermal system design cycles, forcing manufacturers to reengineer heating elements and insulation packages before equipment reaches end-of-life replacement windows.
Growth Catalysts
- FDA Food Code hot-holding updates:Thermostatic precision requirements are pulling healthcare and institutional buyers toward certified cabinets with continuous temperature logging.
- Catering transport intensity:Weight-optimized aluminum alloy construction is automating fleet replacement cycles for mobile operators running high-frequency event schedules.
- Florida-Nevada-California corridor expansion:Convention center and resort construction in these states is concentrating large-format banquet equipment procurement.
Market Restraints
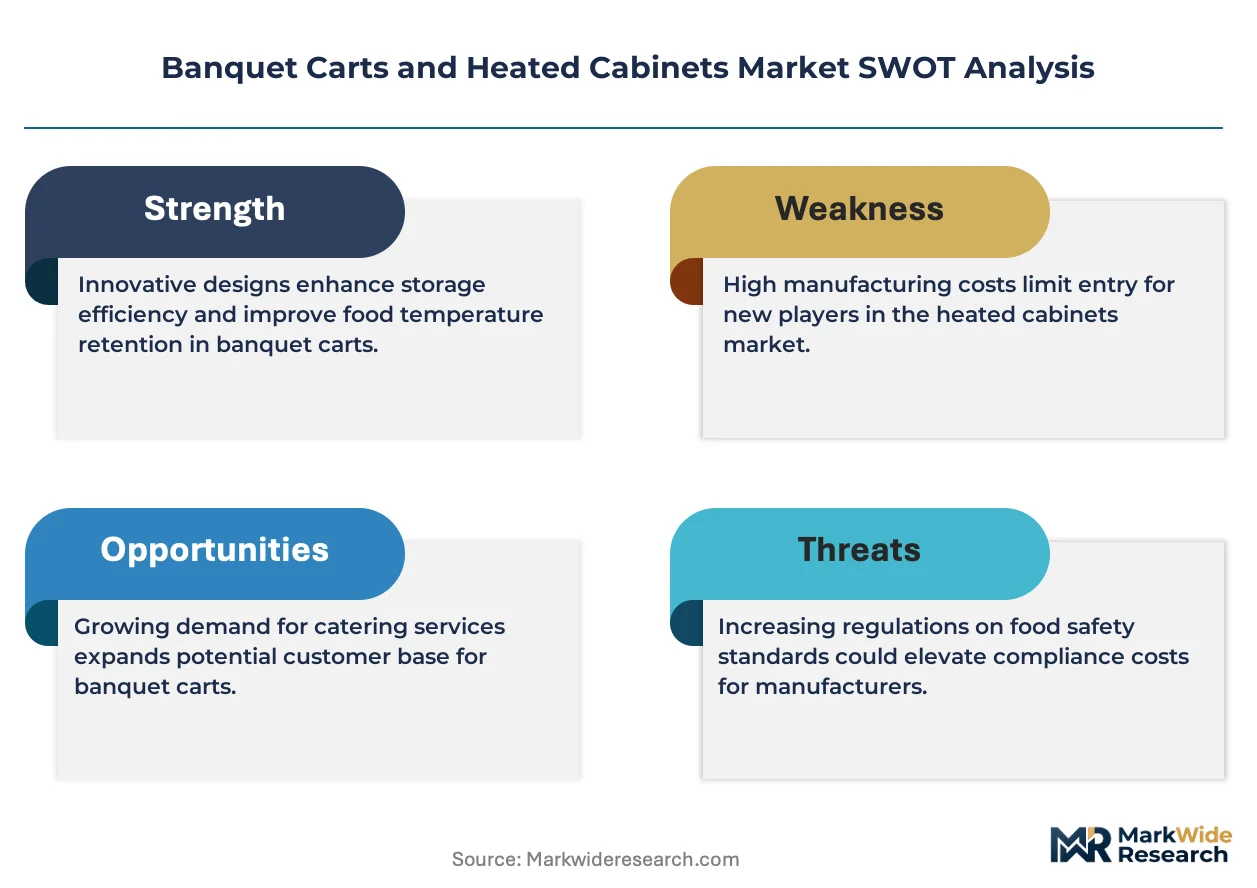
- Stainless steel input volatility:Nickel price swings compress margin predictability for premium cabinet fabricators locked into long-term hospitality contracts.
- Supply concentration in Wisconsin thermal component manufacturing:Geographic clustering of heating element production creates single-source vulnerability for mid-tier assemblers.
- Electric load capacity limits:Legacy hotel electrical infrastructure caps simultaneous deployment of high-wattage heated cabinets during peak banquet service.
Strategic Opportunities
- Healthcare channel underpenetration:Patient meal delivery systems in acute care facilities remain underserved by precision humidity-controlled holding equipment.
- EPA Energy Star certification tailwind:Utility rebate programs for efficient commercial kitchen equipment are shortening payback periods for premium cabinet upgrades.
- IoT-enabled remote monitoring convergence:Cloud-connected temperature logging is automating HACCP documentation for multi-unit operators.
Industry Challenges
- NSF certification timeline compression:Sanitation testing backlogs delay new product launches by six to nine months.
- Integration friction with legacy kitchen display systems:Heated cabinet control interfaces lack standardized APIs for enterprise inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banquet Carts and Heated Cabinets Market |
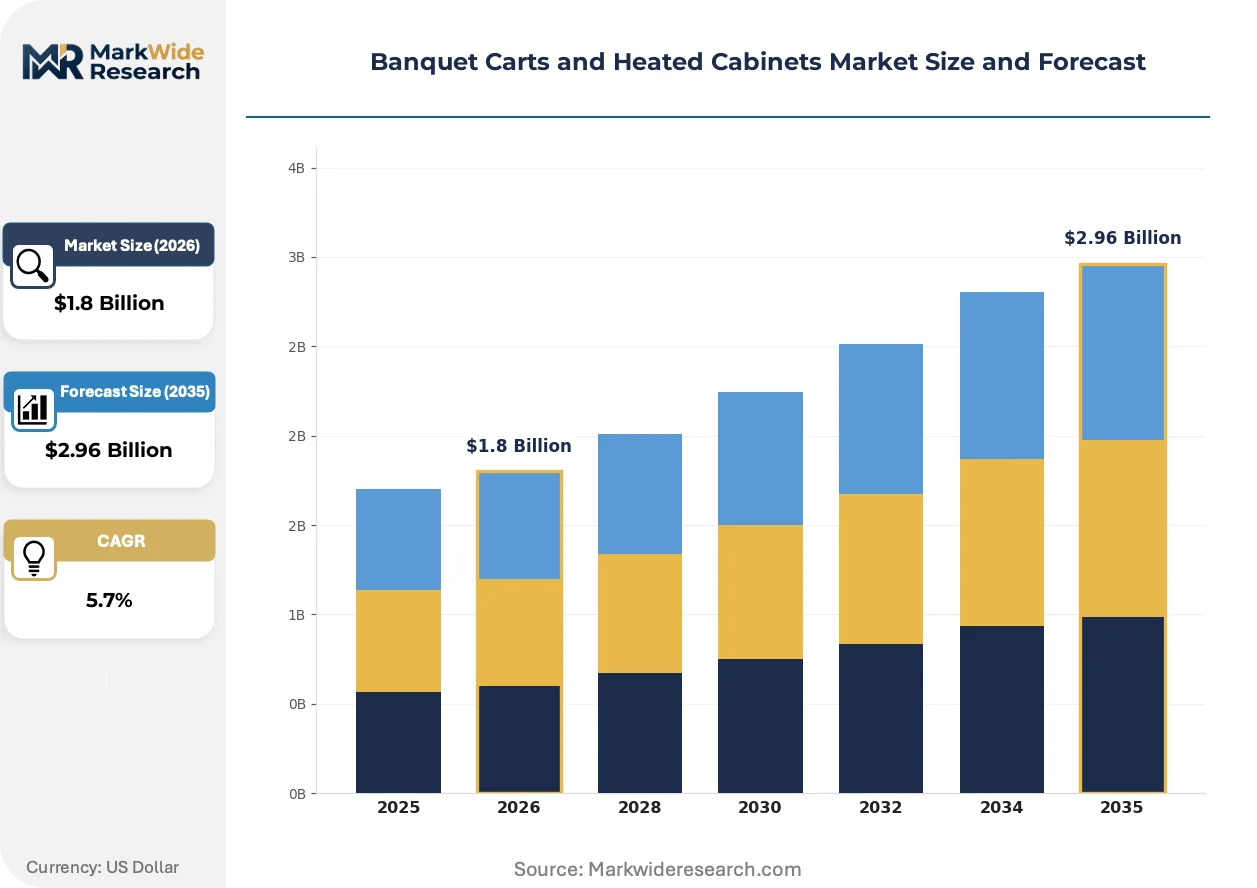
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Carts, Heated Cabinets, Display Carts, Utility Carts End User: Restaurants, Catering Services, Hotels, Institutional Foodservice Material: Stainless Steel, Aluminum, Plastic, Wood Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Cambro Manufacturing, Alto-Shaam, Carter-Hoffmann, FWE (Food Warming Equipment Company), Metro, Lakeside Manufacturing, Vollrath, Cres Cor, Winholt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banquet Carts and Heated Cabinets Market Emerging Trajectories
Active thermal management and connectivity layers are displacing passive holding equipment across commercial foodservice, compressing replacement cycles and rewriting service contract structures.
Precision humidity control systems using multi-sensor feedback loops are automating texture preservation for extended holding periods. Casino resort operators running 24-hour banquet programs are adopting these units fastest. The technology is automating labor redeployment from manual quality checks to guest-facing service roles.
EPA Energy Star Version 3.0 commercial kitchen equipment standards are tightening standby power limits for electrically heated cabinets. Manufacturers must redesign thermal insulation packages and heating element duty cycles to maintain certification eligibility. Healthcare and institutional segments face the steepest compliance recertification burdens.
Equipment-as-a-service financing is displacing capital purchase models among multi-property hospitality groups. Broadline foodservice dealers are building subscription offerings around maintenance-inclusive heated cabinet fleets. California and Florida resort operators show highest uptake of usage-based contracting structures.
Banquet Carts and Heated Cabinets Market Segmentation
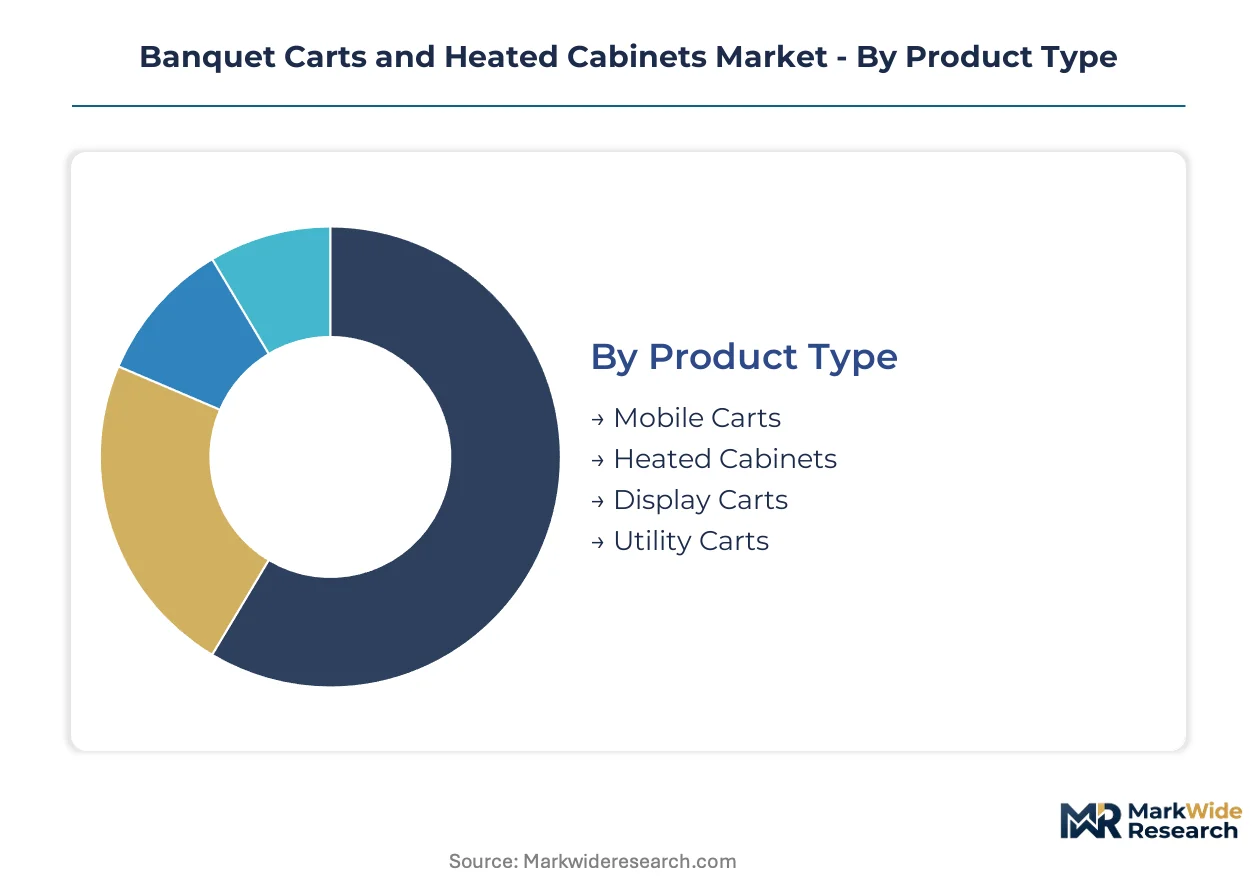
Segmentation in banquet carts and heated cabinets reveals how equipment specifications align with operational intensity across foodservice environments. Procurement patterns diverge sharply between high-frequency mobile operators and stationary holding applications.
Product Type:
Standalone mobile units dominate transport-intensive operations, while embedded heated cabinets integrate into fixed kitchen lines requiring precision temperature maintenance.
- Mobile Carts:Caster-mounted thermal units with electric heating elements and insulation packages designed for event-to-event transport. Caterers running Florida-Nevada-California corridor schedules specify aluminum alloy construction to reduce crew fatigue during high-frequency loading cycles.
- Heated Cabinets:Stationary or semi-stationary thermostatically controlled enclosures with programmable humidity systems for extended holding periods. Casino resort operators in Las Vegas and Atlantic City deploy these for 24-hour banquet programs requiring texture preservation across extended service windows.
- Display Carts:Glass-enclosed mobile units combining thermal holding with visual merchandising for front-of-house service.
- Utility Carts:Non-heated transport platforms for ambient-temperature equipment and supplies.
Heated cabinets lead volumes today; mobile carts are gaining share fastest.
End User:
Customer type determines whether procurement prioritizes capital efficiency or operational flexibility in equipment specification.
- Restaurants:Full-service and limited-service operators with moderate banquet capacity needs.
- Catering Services:Mobile foodservice operators managing off-premise events across dispersed locations. Independent caterers in California and Florida are consolidating fleet purchases through equipment-as-a-service financing to preserve working capital for event staffing.
- Hotels:Full-property foodservice operations with integrated banquet and room service functions. Resort properties along the I-4 corridor in Orlando specify large-format heated cabinets with IoT-enabled temperature logging to automate HACCP documentation for multi-kitchen compliance.
- Institutional Foodservice:Healthcare, education, and correctional facilities with regulated meal delivery requirements. Acute care hospitals face FDA Food Code hot-holding mandates that pull procurement toward NSF-certified cabinets with continuous temperature monitoring and automated alarm systems.
Hotels lead volumes today; institutional foodservice is climbing the fastest.
Material:
Material selection trades off sanitation compliance, weight reduction, and input cost volatility across operating environments.
- Stainless Steel:Corrosion-resistant alloy construction meeting NSF sanitation standards for commercial kitchen durability. Premium cabinet fabricators locked into long-term hospitality contracts face margin compression from nickel price swings in raw material procurement.
- Aluminum:Lightweight alloy formulations reducing transport crew fatigue in high-frequency catering applications. Weight-optimized aluminum construction is automating fleet replacement cycles for mobile operators running intensive event schedules in Nevada and California.
- Plastic:Reinforced polymer composites penetrating mid-tier banquet cart production for cost-sensitive segments.
- Wood:Aesthetic-focused construction for front-of-house display applications with minimal thermal performance requirements.
Stainless steel leads volumes today; aluminum is expanding most quickly.
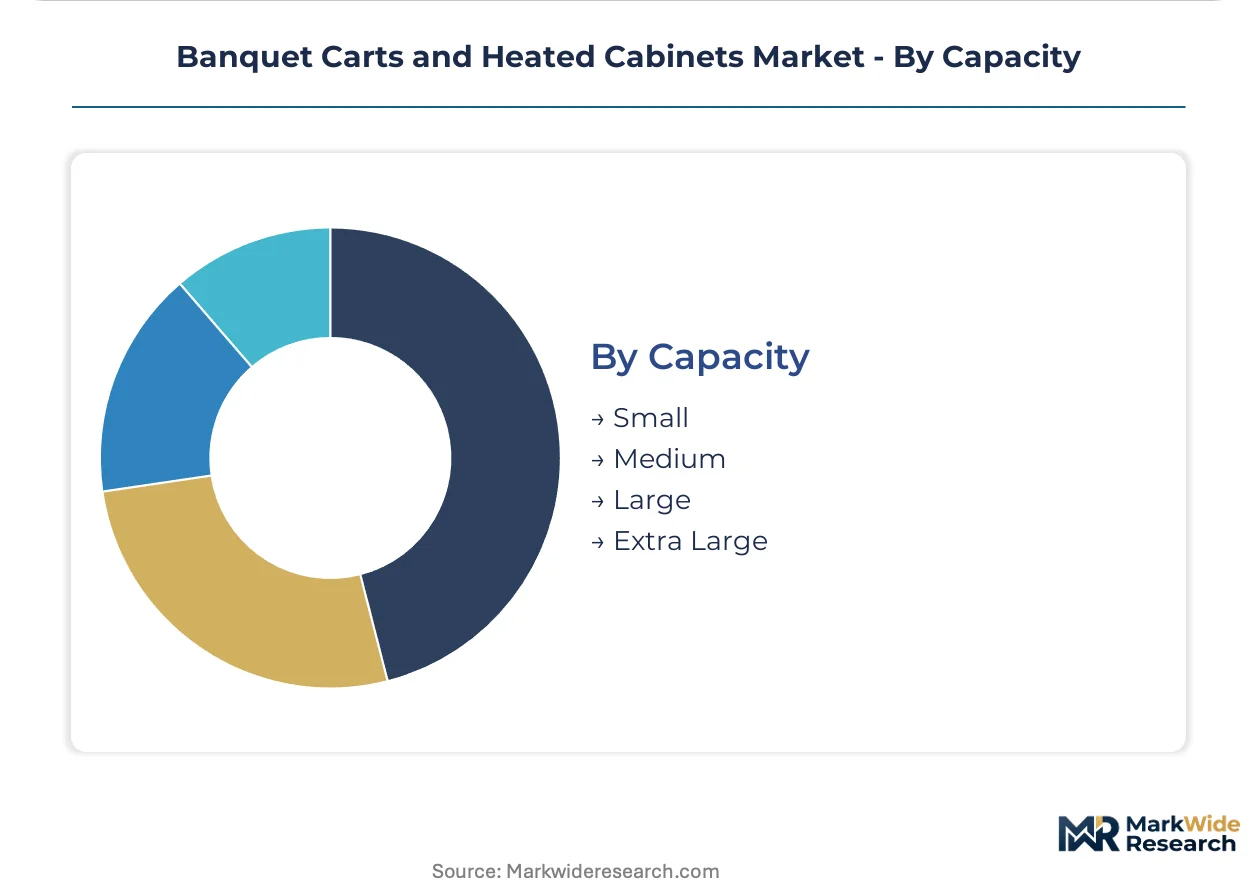
Capacity:
Unit sizing correlates with event scale and electrical infrastructure constraints in deployment locations.
- Small:Compact units for limited-service operations and satellite kitchen applications.
- Medium:Mid-scale capacity for independent restaurants and boutique catering operations.
- Large:High-volume configurations for hotel banquet departments and institutional commissaries. Convention center kitchens in Florida and California specify large-capacity heated cabinets to manage simultaneous service for multi-thousand-attendee events.
- Extra Large:Industrial-scale units for central commissary production feeding multiple satellite locations.
Large capacity leads volumes today; extra large is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's thermal component manufacturing belt anchors production capacity for electrically heated foodservice equipment, with supply chains radiating toward hospitality corridors in Florida, Nevada, and California where convention center construction drives procurement intensity.
United States
Florida, Nevada, and California hospitality corridors concentrate demand from resort and convention center operators. The FDA Food Code hot-holding temperature mandates pull procurement toward NSF-certified cabinets with continuous monitoring. Orlando's I-4 corridor properties specify large-format heated cabinets with IoT-enabled HACCP documentation.
Germany
Commercial kitchen equipment fabricators serve central European institutional foodservice through precision-engineered thermal systems. The EU Ecodesign Directive and national efficiency standards reshape heating element specifications. Baden-Württemberg manufacturing clusters specialize in stainless steel fabrication for healthcare and hospitality channels.
China
Coastal manufacturing provinces supply cost-optimized aluminum alloy components for export-oriented mobile cart assembly. GB standards for commercial kitchen equipment sanitation govern domestic certification requirements. Guangdong and Zhejiang production zones concentrate mid-tier fabricators serving Asia-Pacific catering markets.
Japan
Compact urban hospitality operations drive demand for space-efficient heated cabinet configurations. METI energy efficiency guidelines for commercial equipment tighten standby power thresholds. Osaka-Kansai industrial districts house thermal system specialists supplying precision humidity control technology.
United Arab Emirates
Dubai and Abu Dhabi luxury hospitality developments import premium heated holding equipment for large-scale banquet operations. The country's national food safety regulator mandates HACCP-aligned temperature monitoring for commercial foodservice. Jebel Ali logistics corridors facilitate distribution across Gulf Cooperation Council markets.
Banquet Carts and Heated Cabinets Market Vendor Landscape
Global majors compete with regional champions across thermal system engineering and channel access dimensions, producing a tiered structure where scale-driven manufacturers coexist with specialized healthcare and hospitality fabricators. The vendor base separates into three strategic archetypes: vertically integrated thermal system producers, regional stainless steel fabricators, and broadline foodservice equipment distributors. Dominant competitive moves include backward integration into heating element production and equipment-as-a-service financing partnerships with multi-property hospitality groups.
Within the vertically integrated tier, Alto-Shaam anchors thermal system quality control through its Wisconsin manufacturing footprint. Carter-Hoffmann occupies a position exemplifying specialized heated cabinet engineering for healthcare and institutional channels. Cambro Manufacturing represents the distribution-focused archetype, with its channel relationships anchoring mobile cart penetration across broadline foodservice dealer networks.
| Leading Market Players |
|---|
| Cambro Manufacturing |
| Alto-Shaam |
| Carter-Hoffmann |
| FWE (Food Warming Equipment Company) |
| Metro |
| Lakeside Manufacturing |
| Vollrath |
| Cres Cor |
| Winholt |
| Others |
Supply Flow & Price Mechanics
Nickel alloy pricing volatility cascades from commodity exchanges through Wisconsin-based thermal component fabricators into tiered equipment pricing for hospitality procurement teams. Stainless steel input swings compress margin pools for premium cabinet manufacturers locked into multi-year resort contracts, while aluminum alloy alternatives attract mid-tier buyers seeking transport efficiency without NSF-grade certification premiums.
Pricing Analysis
Input-cost pass-through from nickel and aluminum markets shapes three-tier pricing stratification across premium NSF-certified cabinets, standard commercial units, and economy-grade polymer-composite carts. Price differentiation hinges on thermostatic precision certification and humidity control sophistication, with FDA Food Code compliance tiers commanding substantial premiums. Pricing pressure intensifies in the standard-duty mobile segment as reinforced polymer alternatives displace metal construction. Independent caterers in high-frequency transport corridors exhibit greatest price sensitivity, while casino resort operators prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Regional distribution centers in Wisconsin's thermal manufacturing belt anchor hub-and-spoke patterns radiating toward Florida, Nevada, and California hospitality corridors. Supply concentration in Wisconsin heating element production and Guangdong aluminum alloy component sourcing creates geographic dependency for mid-tier assemblers. Raw material inputs draw from nickel mining operations, aluminum smelting capacity, and electric heating element ceramics. Single-source vulnerability in Wisconsin thermal component manufacturing presents structural risk. Distribution runs through broadline foodservice dealer networks with equipment-as-a-service financing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Banquet Carts and Heated Cabinets Market functions as a regulatory compounder where FDA Food Code hot-holding temperature mandates continuously upgrade equipment replacement cycles across healthcare and institutional channels.
For Market Incumbents: Anticipate margin compression from aluminum alloy substitution in mid-tier mobile carts by accelerating backward integration into captive heating element production. Wisconsin-based manufacturers should diversify thermal component sourcing beyond single-region clustering to mitigate geographic concentration risk. NSF certification investment remains essential for defending hospitality channel position against emerging polymer-composite entrants. For New Entrants and Emerging Players: E-commerce direct-to-caterer platforms offer lower customer acquisition cost than traditional broadline dealer networks for independent operators in California and Florida. Healthcare acute care facilities represent the most penetrable segment given underinvestment in precision humidity-controlled patient meal delivery systems. Target equipment-as-a-service financing partnerships with multi-property resort groups to bypass capital purchase cycle friction. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier fabricators lack thermal system engineering depth and NSF certification infrastructure. Long-term viability favors vertically integrated producers with Wisconsin manufacturing footprints and healthcare channel specialization. Acquisition target archetype: regional stainless steel fabricators with FDA compliance capabilities but limited distribution scale. Watch EPA Energy Star Version 3.0 recertification timelines as inflection indicator for R&D spending intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Wisconsin manufacturers secure thermal quality control against supply concentration risk. |
| IoT-Enabled Temperature Logging Deployment | Cloud connectivity automates HACCP documentation for Orlando I-4 corridor resort operators. |
| Equipment-as-a-Service Financing Launch | California and Florida caterers preserve working capital through subscription-based fleet models. |
| Healthcare Channel Certification Investment | NSF-certified precision humidity systems capture acute care facility upgrade cycles. |
| Aluminum Alloy Product Line Expansion | Weight-optimized construction addresses Nevada and California high-frequency transport demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement directors, resort banquet operations managers, healthcare facility engineering heads, and broadline dealer category buyers with secondary validation. Sources included FDA Food Code regulatory filings, NSF International certification databases, EPA Energy Star commercial kitchen equipment standards, and hospitality construction permit records. Bottom-up segment enumeration and top-down macroeconomic anchoring provided cross-verification.
Segment-weighting approaches distributed value and volume across product type, end user category, material construction, and capacity tier dimensions. CAGRs were derived from installed base turnover analysis, regulatory compliance upgrade cycles, and regional hospitality construction pipelines. Forecast inputs incorporated electric load capacity constraints in legacy hotel infrastructure and nickel price trajectory assumptions from commodity market tracking.
The model assumes a particular technology adoption path; alternative pathways for IoT-enabled remote monitoring convergence would alter the outlook if cloud platform integration costs decline faster than projected. Forecasts reflect documented assumptions about EPA Energy Star compliance timelines and FDA Food Code enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Quartz Sink Market