
 North America Furniture Market | 2026-2036
North America Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Furniture Market Analytics
Direct-to-consumer upholstery customization is fragmenting as legacy manufacturers and digital natives compete for margin pools once captured by wholesale intermediaries. Ashley Furniture Industries anchors its position through captive manufacturing scale across Mississippi and North Carolina assembly plants. Wayfair competes via algorithmic demand forecasting that compresses inventory cycles for third-party suppliers. Steelcase specializes in commercial workspace systems that leverage ergonomic research to sustain premium pricing against import alternatives.
North America furniture encompasses movable objects constructed from wood, metal, plastic, or upholstered composites, designed to support human activities including seating, storage, sleeping, and working surfaces, with specifications typically addressing load-bearing capacity, dimensional stability, and finish durability under ANSI/BIFMA test protocols. The primary commercial purpose spans residential dwelling outfitting, corporate workspace configuration, hospitality venue furnishing, and institutional facility equipping. Sofas and upholstered seating command the largest revenue share within product type segments, reflecting higher unit values and replacement frequency in residential channels. Wood material sourcing faces structural pressure from certified sustainable supply constraints, while metal and plastic alternatives gain share in commercial and outdoor applications. Online distribution channels are capturing the fastest volume growth, though offline retail still controls the majority of transaction value through tactile purchasing behavior in furniture categories.
The EPA regulates composite wood product formaldehyde emissions under TSCA Title VI, compelling manufacturers to verify supply chain compliance through third-party certification. California's Air Resources Board maintains stricter CARB Phase 2 standards that de facto shape national product specifications for brands distributing across state lines. The Consumer Product Safety Commission oversees flammability testing requirements that influence foam and fabric selection in upholstered furniture production. Stakeholders must monitor evolving state-level chemical disclosure mandates and freight cost volatility as they calibrate sourcing strategies between domestic manufacturing and import-dependent supply models.
Market Dynamics
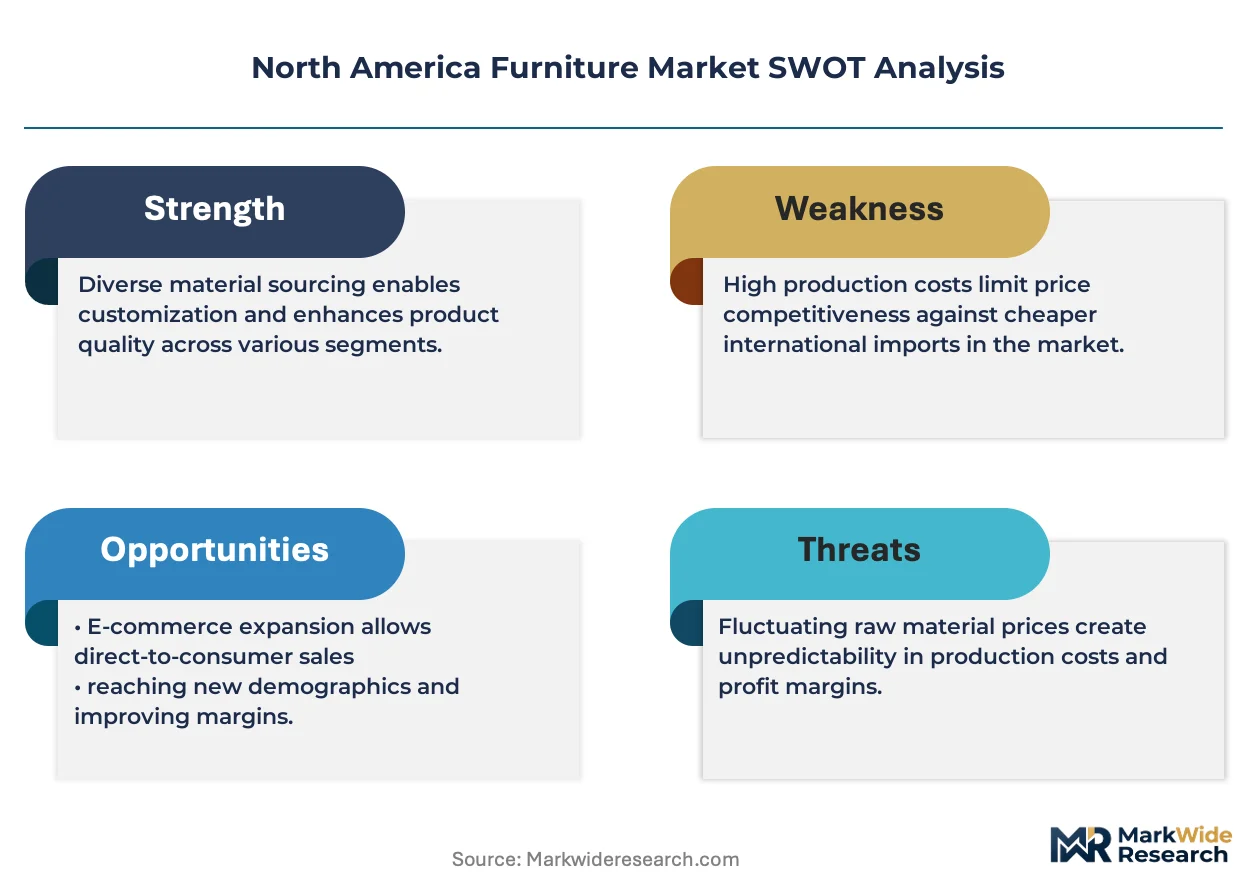
EPA formaldehyde emission standards under TSCA Title VI are restructuring material sourcing across domestic manufacturing, compelling supply chain verification and reshaping competitive cost structures for wood-based furniture producers.
Growth Catalysts
- Suburban Home Office Expansion:Residential buyers in exurban zones are expanding orders for dedicated workspace collections, pulling upholstered seating and modular storage systems into higher replacement cycles.
- CARB Phase 2 De Facto National Standard:California Air Resources Board emission limits shape product specifications for brands distributing across state lines, creating compliance-driven demand for certified composite wood substrates.
- Southeast Production Cluster Density:Mississippi and North Carolina anchor upholstered and wood furniture assembly, concentrating skilled labor pools and reducing inbound freight costs for domestic manufacturers.
Market Restraints
- Certified Sustainable Wood Supply Constraints:FSC and SFI chain-of-custody certification bottlenecks limit raw material availability, forcing substitution to metal and plastic alternatives in outdoor and commercial applications.
- Foam and Fabric Flammability Compliance Costs:Consumer Product Safety Commission testing requirements for upholstered furniture elevate R&D expenditure and extend product development timelines.
- Import Dependency for Hardware and Mechanisms:Precision metal components for adjustable seating and motion furniture concentrate sourcing in Asian manufacturing zones, exposing margins to ocean freight volatility.
Strategic Opportunities
- Algorithmic Demand Forecasting Adoption:Digital-native retailers compress inventory cycles for third-party suppliers, creating white space for manufacturers with responsive production systems to capture wholesale margin pools.
- Outdoor Living Collection Expansion:Residential channel buyers are extending furnishing budgets to exterior spaces, opening volume growth in weather-resistant materials and modular patio systems.
- State-Level Chemical Disclosure Mandates:Emerging transparency requirements in California and New York create first-mover advantage for manufacturers with pre-positioned supply chain documentation systems.
Industry Challenges
- Ergonomic Research Integration Complexity:Commercial workspace producers must embed biomechanical findings into product development without extending certification timelines that disadvantage domestic producers against import competitors.
- Legacy ERP System Modernization:Mid-scale manufacturers face capital intensity in migrating from on-premise inventory management to cloud-based demand-planning platforms that interface with retail partner data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Furniture Market |
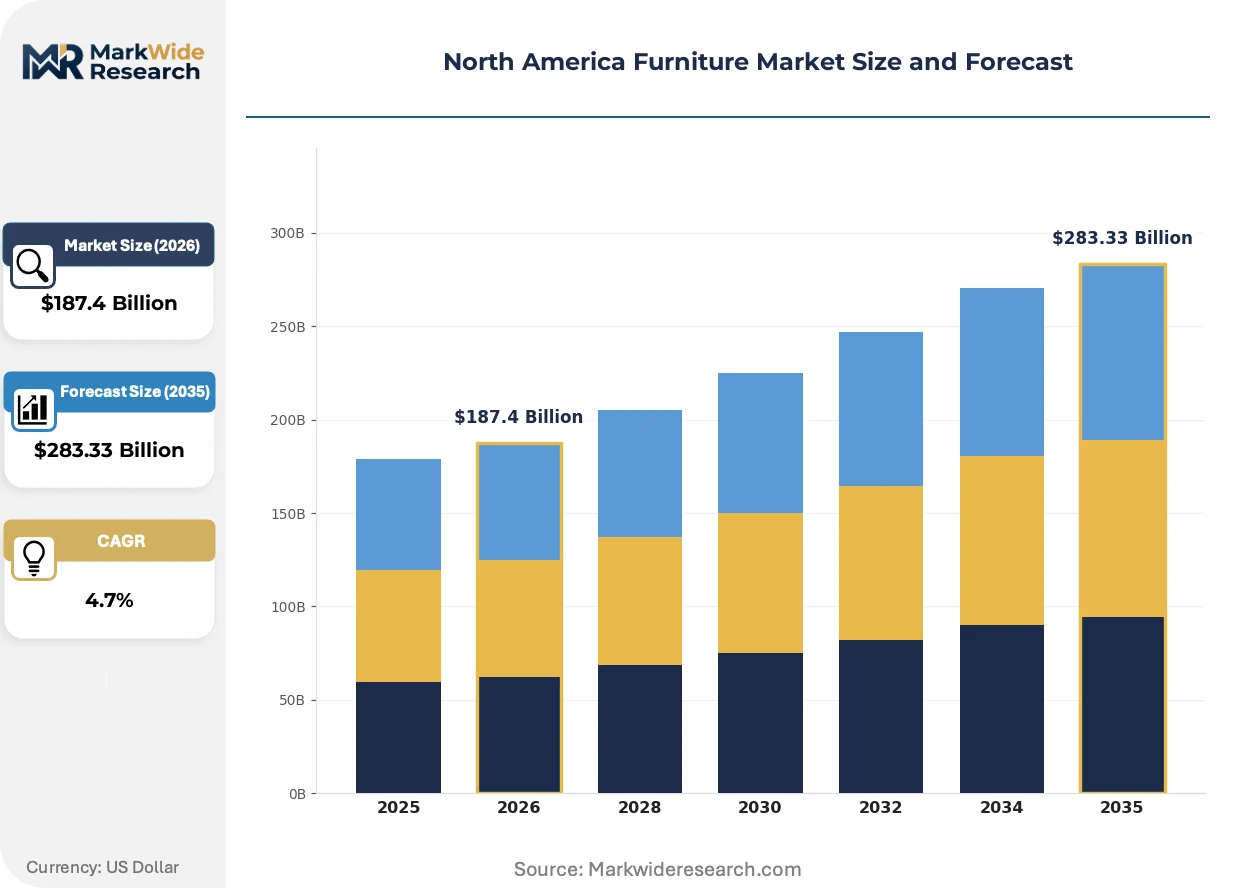
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Plastic, Upholstery Distribution Channel: Online, Offline, Direct Sales, Wholesale Customer Type: Residential, Commercial, Educational, Hospitality |
| Companies Covered | Williams-Sonoma, Wayfair, Ashley Furniture Industries, Haworth, La-Z-Boy, Steelcase, HNI Corporation, Restoration Hardware, Herman Miller, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Furniture Market Evolving Landscape
Digital distribution infrastructure is compressing traditional wholesale intermediation, while material science advances and regulatory transparency mandates reshape how furniture specifications travel from factory floor to residential and commercial end-users.
Mass-customization software platforms are migrating from experimental retail interfaces to core operational infrastructure. These systems enable real-time upholstery configuration and dimensional modification for residential buyers. Large-format manufacturers in North Carolina assembly plants adopt these tools to defend margin position against direct-to-consumer entrants. The technology is migrating from showroom novelty to back-end production scheduling systems that synchronize cutting and sewing operations with individual order specifications.
TSCA Title VI third-party certification requirements are formalizing supply chain documentation as a competitive differentiator. The EPA mandates verified formaldehyde testing for composite wood products, with penalties attaching to non-compliant distribution. Domestic manufacturers in the US Southeast are responding by consolidating supplier relationships around certified panel producers, while import-dependent brands face extended customs clearance scrutiny.
Commercial buyers are unbundling furniture procurement from facilities management contracts, creating discrete specification authority for workspace systems. Corporate real estate departments now source ergonomic seating and modular workstation components through dedicated procurement functions rather than bundled service agreements. This pattern is most visible in technology sector headquarters expansions across Texas and Colorado, where tenant improvement allowances flow directly to furniture capital expenditure lines.
North America Furniture Market Segmentation
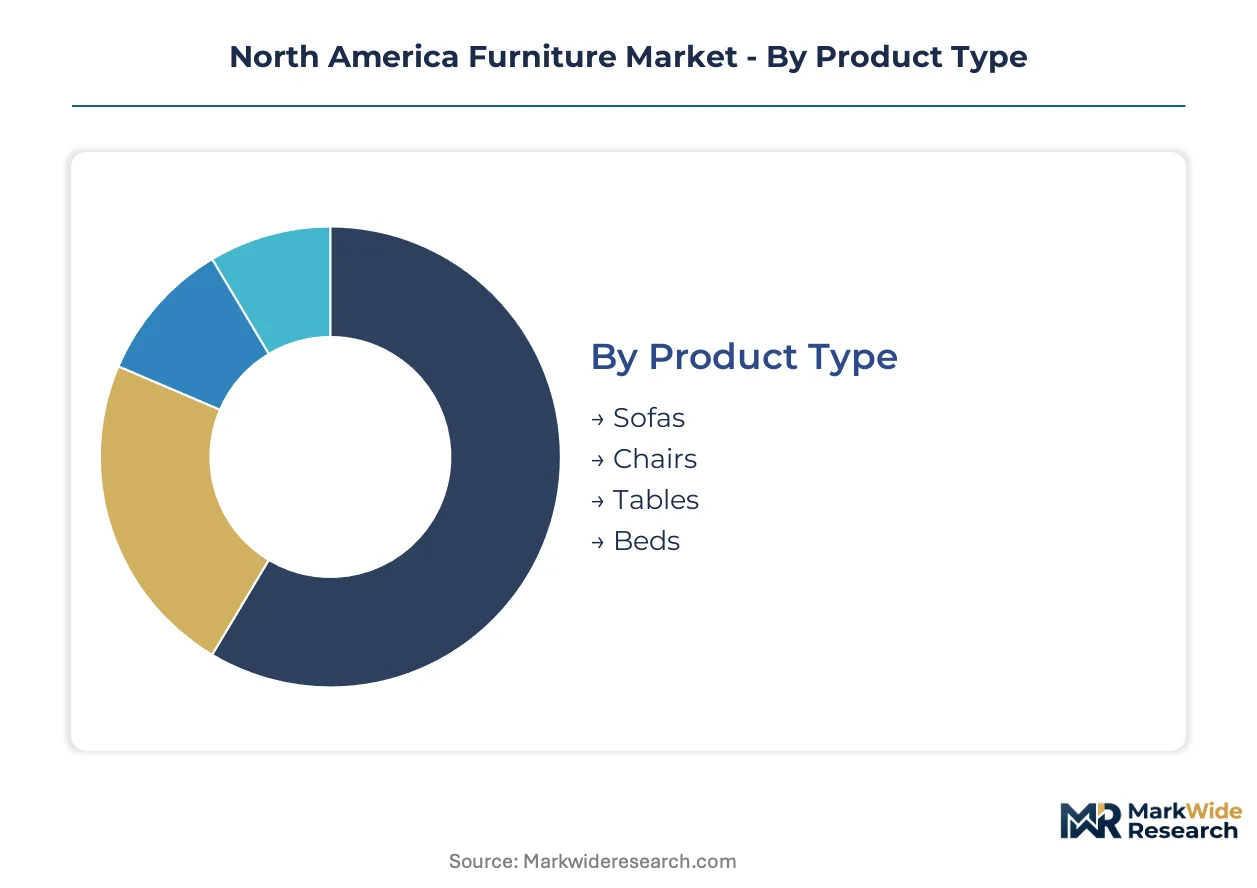
Segmentation in North American furniture reveals divergent replacement cycles and margin structures across product categories. Understanding these patterns allows manufacturers to align production capacity with demand velocity and regulatory exposure.
Product Type:
Replacement frequency varies dramatically across furniture categories, with upholstered seating turning over fastest due to wear patterns and style obsolescence while case goods endure longer in residential inventories.
- Sofas:Multi-seat upholstered units with foam cushioning and fabric or leather coverings, typically replaced every 7-10 years in residential settings. Demand concentrates in exurban zones where home office expansion drives companion seating purchases alongside dedicated workspace chairs.
- Chairs:Single-seat variants spanning dining, accent, and task configurations. Ergonomic task seating commands premium pricing in Texas and Colorado technology sector headquarters where tenant improvement allowances flow directly to furniture capital expenditure lines.
- Tables:Horizontal work and dining surfaces in wood, metal, or composite construction. Dining tables face slower replacement cycles tied to housing turnover rather than wear.
- Beds:Sleeping platforms including frames, headboards, and foundations. Mattress replacement outpaces frame turnover, creating aftermarket attachment opportunities for manufacturers with modular headboard systems.
Sofas anchor the volume base while chairs gain share at the steepest rate driven by distributed work arrangements.
Material:
Cost tiers separate material categories, with certified sustainable wood commanding premium positioning against metal and plastic alternatives that dominate commercial and outdoor specifications.
- Wood:Solid lumber and engineered panel products subject to TSCA Title VI formaldehyde emission verification. FSC and SFI chain-of-custody certification bottlenecks constrain supply, forcing substitution in price-sensitive segments.
- Metal:Steel and aluminum framing for commercial and outdoor applications. Precision hardware and adjustable mechanisms concentrate sourcing in Asian manufacturing zones, exposing margins to ocean freight volatility.
- Plastic:Polymer composites for weather-resistant outdoor collections and institutional seating. Residential buyers extending furnishing budgets to exterior spaces drive volume expansion in modular patio systems.
- Upholstery:Fabric, leather, and synthetic coverings over foam cushioning. CPSC flammability testing requirements elevate R&D expenditure and extend product development timelines for domestic producers.
Wood materials dominate transaction value while plastic alternatives expand most quickly in outdoor living applications.
Distribution Channel:
Channel economics reflect inventory risk allocation, with digital platforms compressing cycles for third-party suppliers while offline retail retains tactile purchasing advantages in high-consideration categories.
- Online:Digital-native retail interfaces with algorithmic demand forecasting. These platforms compress inventory cycles for third-party suppliers, creating white space for manufacturers with responsive production systems.
- Offline:Brick-and-mortar showrooms and furniture galleries. Tactile purchasing behavior in upholstery categories sustains majority transaction value despite slower volume growth.
- Direct Sales:Manufacturer-owned channels bypassing wholesale intermediation. North Carolina and Mississippi assembly plants leverage captive production scale to defend margin position against direct-to-consumer entrants.
- Wholesale:Third-party distribution through furniture retailers and buying groups. Margin pools here face fragmentation as legacy manufacturers and digital natives compete for position once captured by intermediaries.
Offline channels retain the largest value share while online distribution climbs the fastest on volume metrics.
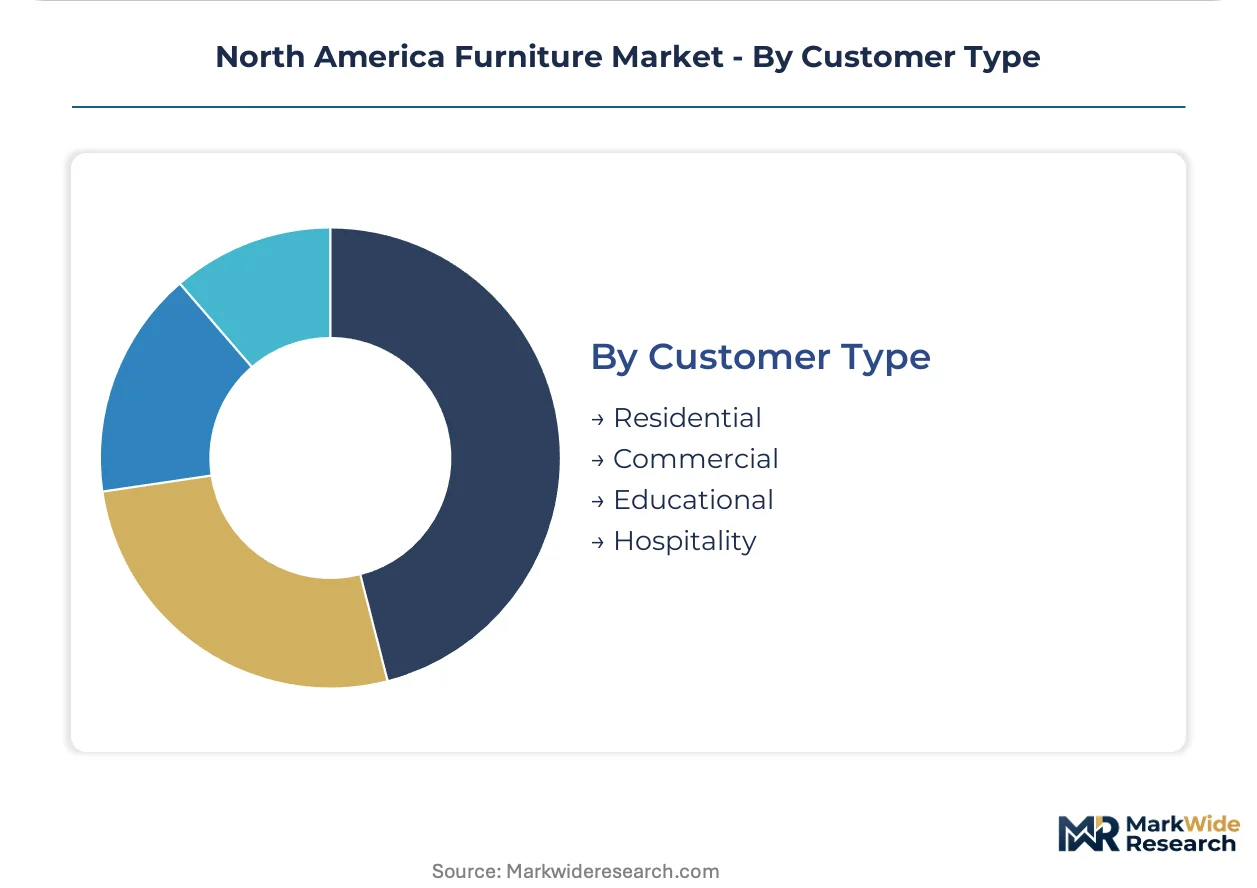
Customer Type:
Application context determines specification authority, with residential buyers prioritizing aesthetics and replacement frequency while institutional purchasers emphasize durability certification and lifecycle costing.
- Residential:Individual dwelling outfitment across single-family and multifamily housing. Suburban and exurban zones drive expansion in home office and outdoor living collections with higher replacement cycles.
- Commercial:Corporate workspace configuration including ergonomic seating and modular systems. Real estate departments in technology sector headquarters now source through dedicated procurement functions rather than bundled facilities management contracts.
- Educational:K-12 and higher education facility equipping. Institutional procurement emphasizes durability certification and lifecycle costing over style turnover.
- Hospitality:Hotel, restaurant, and venue furnishing with high-wear specifications. Design refresh cycles tied to property renovation schedules create predictable demand windows for contract manufacturers.
Residential buyers anchor volume demand while commercial procurement expands most rapidly through unbundled specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North American geographies, with United States buyers prioritizing home office and outdoor living expansion while Canadian procurement emphasizes commercial workspace durability and Mexican manufacturing serves cross-border assembly demand.
United States
Exurban residential zones in Texas and Colorado drive upholstered seating and modular storage demand as distributed work arrangements persist. EPA formaldehyde emission standards under TSCA Title VI compel domestic manufacturers to verify supply chain compliance through third-party certification. North Carolina and Mississippi anchor production clusters where assembly plants concentrate skilled labor pools for wood and upholstered furniture.
Canada
Commercial real estate departments in Toronto and Vancouver technology corridors source ergonomic workspace systems through discrete procurement functions rather than bundled facilities contracts. Health Canada maintains alignment with EPA emission benchmarks while provincial building codes influence material specifications for institutional furniture. Ontario and Quebec host manufacturing operations serving both domestic distribution and United States cross-border fulfillment.
Mexico
Export-oriented assembly operations in Nuevo León and Baja California supply precision metal components and upholstered frames to United States distribution channels. Mexican labor cost advantages attract North Carolina and Mississippi manufacturers seeking nearshore capacity expansion. The Secretariat of Economy oversees maquiladora program compliance as cross-border freight integration deepens with Texas and California logistics corridors.
North America Furniture Market Competitive Landscape
Capability concentration sits with specialized ergonomic research firms; scale advantage sits with vertically integrated manufacturers with captive assembly networks. The vendor base stratifies across three tiers: mass-market producers with regional distribution density, premium-positioned specialists leveraging biomechanical R&D, and digital-native platforms compressing inventory cycles through algorithmic demand forecasting. Dominant competitive moves include backward integration into certified wood panel supply and strategic partnerships with third-party logistics providers for last-mile delivery compression.
Among United States-based fabricators, Ashley Furniture Industries exemplifies scale-driven vertical integration through Mississippi and North Carolina assembly plant networks. Wayfair occupies a position as the algorithmic demand forecasting archetype, compressing inventory cycles for third-party suppliers. Steelcase represents the ergonomic research specialization tier, sustaining premium positioning through biomechanical product development.
| Leading Market Players |
|---|
| Williams-Sonoma |
| Wayfair |
| Ashley Furniture Industries |
| Haworth |
| La-Z-Boy |
| Steelcase |
| HNI Corporation |
| Restoration Hardware |
| Herman Miller |
| Others |
Value Network & Pricing Analysis
North Carolina and Mississippi assembly plant networks concentrate upholstered and wood furniture capacity, translating captive production scale into pricing power against import-dependent competitors facing ocean freight volatility and extended customs clearance scrutiny.
Pricing Analysis
Long-term offtake contracts dominate commercial workspace procurement, particularly for ergonomic seating systems in technology sector headquarters, while residential channels favor spot purchasing with higher price sensitivity. Price differentiation separates certified sustainable wood products commanding premium positioning from metal and plastic alternatives in outdoor applications. Pricing pressure stems from certified sustainable wood supply constraints forcing substitution in price-sensitive segments. Commercial buyers exhibit lowest price sensitivity due to tenant improvement allowances flowing directly to furniture capital expenditure lines.
Supply Chain Analysis
Extended payment terms from large-format retailers concentrate working capital pressure on third-party suppliers, accelerating consolidation around manufacturers with captive financing capacity. Raw material sourcing draws from United States domestic panel producers for TSCA Title VI compliance, Asian manufacturing zones for precision metal hardware and adjustable mechanisms, and Canadian operations for cross-border fulfillment. Single-source vulnerability concentrates in precision metal components for motion furniture, exposing margins to ocean freight volatility. Distribution runs through direct-to-consumer digital platforms compressing inventory cycles alongside traditional brick-and-mortar galleries retaining tactile purchasing advantages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as commercial real estate departments unbundle furniture procurement from bundled facilities management contracts, fragmenting specification authority and intensifying price competition across vendor tiers.
For Market Incumbents: Build certification moats around TSCA Title VI third-party verification and FSC chain-of-custody documentation to defend against direct-to-consumer entrants lacking supply chain transparency infrastructure. Consolidate supplier relationships around certified composite wood panel producers to secure raw material access as sustainable supply constraints intensify. Deepen backward integration into upholstery cutting and sewing operations synchronized with mass-customization software platforms.
For New Entrants and Emerging Players: Pursue algorithmic demand forecasting partnerships with digital-native retailers to compress inventory cycles and capture wholesale margin pools abandoned by legacy manufacturers. Target outdoor living collections as the most penetrable residential segment, where weather-resistant material expertise creates differentiation against established indoor-focused producers. Deploy direct-to-consumer configuration interfaces as the primary go-to-market angle, leveraging real-time upholstery customization to bypass traditional showroom intermediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with pre-positioned supply chain documentation systems responding to emerging state-level chemical disclosure mandates in California and New York. Long-term viability over the projection horizon hinges on regulatory compliance infrastructure rather than pure production scale. Acquisition targets should demonstrate responsive production systems interfacing with retail partner data feeds. The signal to watch is accelerated customs clearance scrutiny for import-dependent brands lacking verified formaldehyde testing documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Wood Panel Supply | TSCA Title VI compliance secures raw material access against FSC certification bottlenecks constraining competitors. |
| Mass-Customization Software Platform Deployment | Real-time upholstery configuration synchronizes cutting and sewing with individual order specifications. |
| Direct-to-Consumer Channel Launch | Algorithmic demand forecasting compresses inventory cycles and captures margin pools from wholesale intermediaries. |
| Ergonomic Research Partnership | Biomechanical product development sustains premium pricing against import alternatives in commercial workspace systems. |
| Nearshore Capacity Expansion | Nuevo León and Baja California assembly operations reduce ocean freight exposure for precision metal components. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, CARB Phase 2 compliance databases, and ANSI/BIFMA test protocol documentation. Primary interviews engaged furniture manufacturing executives, commercial real estate procurement directors, retail category buyers, supply chain compliance officers, and upholstery production managers. Secondary validation incorporated customs and trade data, SEC 10-K filings from publicly traded manufacturers, and state-level chemical disclosure mandate tracking. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, distribution channel, and customer type segmentation dimensions.
Forecast inputs include residential replacement cycle velocity for upholstered seating, commercial workspace unbundling trends in technology sector headquarters, and regulatory compliance cost trajectories under TSCA Title VI enforcement. Segmentation modeling spans product type, material category, distribution channel, and customer application context. CAGRs were derived from demand elasticity analysis calibrated to observed volume shifts across the projection horizon. Industry-specific inputs incorporate EPA formaldehyde emission standard enforcement intensity and certified sustainable wood supply availability curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer digital natives or nearshore assembly operators would shift outcomes. Macroeconomic deviation in housing turnover rates, regulatory expansion of state-level chemical disclosure mandates, or breakthroughs in sustainable material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Metal Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
Italy Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
United Arab Emirates Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Saudi Arabia Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Kids and Nursery Furniture Market
Furniture
United States Luxury Furniture Market
Furniture
Home Furnishings Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Global Folding Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Rattan Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market