
 Global Furniture Market | 2026-2036
Global Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Furniture Market Analysis
Aftermarket service revenue is reshaping how furniture brands capture lifetime value from commercial clients. Steelcase leverages its workplace consulting arm to extend relationships beyond initial fit-out cycles. Herman Miller anchors its premium positioning through certified refurbishment programs that compete with new-product sales. IKEA dominates the residential segment by controlling in-house production of flat-pack components across captive supply networks.
Furniture comprises movable objects engineered for human support, storage, and spatial organization, typically fabricated through CNC machining, joinery, molding, or upholstery processes using dimensional tolerances suited to residential and commercial interiors. Wood material categories sustain margin pools in handcrafted and solid-wood segments where supply scarcity supports pricing power. Upholstery product types lead volume in residential channels, while metal frames specialize in commercial and hospitality applications requiring fire-resistance certification and extended duty cycles.
EPA formaldehyde emission standards and California Air Resources Board (CARB) Phase 2 compliance shape North American market access for composite wood products, while REACH and EU Ecolabel criteria govern chemical content in European upholstered goods. The EU Deforestation Regulation is forcing supply-chain documentation for timber sourcing across tropical supplier bases. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility frameworks in Germany are redrawing cost structures for cross-border furniture trade.
Market Dynamics
Carbon accounting mandates and deforestation traceability requirements are forcing furniture manufacturers to restructure supplier relationships and material certification workflows across tropical timber basins and synthetic polymer supply chains.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation documentation for timber sourcing is accelerating investment in blockchain-enabled chain-of-custody systems across European import channels.
- Hospitality sector expansion:Branded interiors programs at hotel chains are pulling demand for certified fire-resistant upholstery and custom millwork through specification-driven procurement.
- Digital fabrication:CNC machining and robotic joinery are compressing production lead times for mass-customization programs in residential seating and storage systems.
Market Restraints
- Formaldehyde emission compliance:EPA standards and CARB Phase 2 certification create cost barriers for composite wood producers serving North American distribution.
- Vietnam-Indonesia supply concentration:Export-oriented manufacturing clusters face disruption risk from port congestion and energy rationing in Southeast Asian industrial zones.
- Recycled fiber performance limits:Mechanical recycling of polyester textiles produces staple length degradation that restricts application in high-wear commercial upholstery.
Strategic Opportunities
- India residential market:Urbanization and mortgage penetration in tier-2 cities are expanding addressable demand for flat-pack and ready-to-assemble furniture.
- Extended producer responsibility:Germany's packaging and end-of-life mandates are creating service revenue pools for take-back and refurbishment operators.
- Biomaterial hybridization:Mycelium-based foams combined with flax fiber composites are opening performance tiers between petroleum synthetics and natural latex.
Industry Challenges
- Master craftsperson scarcity:Traditional joinery and hand-finishing skills are contracting in European and North American manufacturing bases as vocational pipelines narrow.
- Multi-certification timelines:Simultaneous pursuit of FSC chain-of-custody, OEKO-TEX, and BIFMA compliance extends product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Furniture Market |
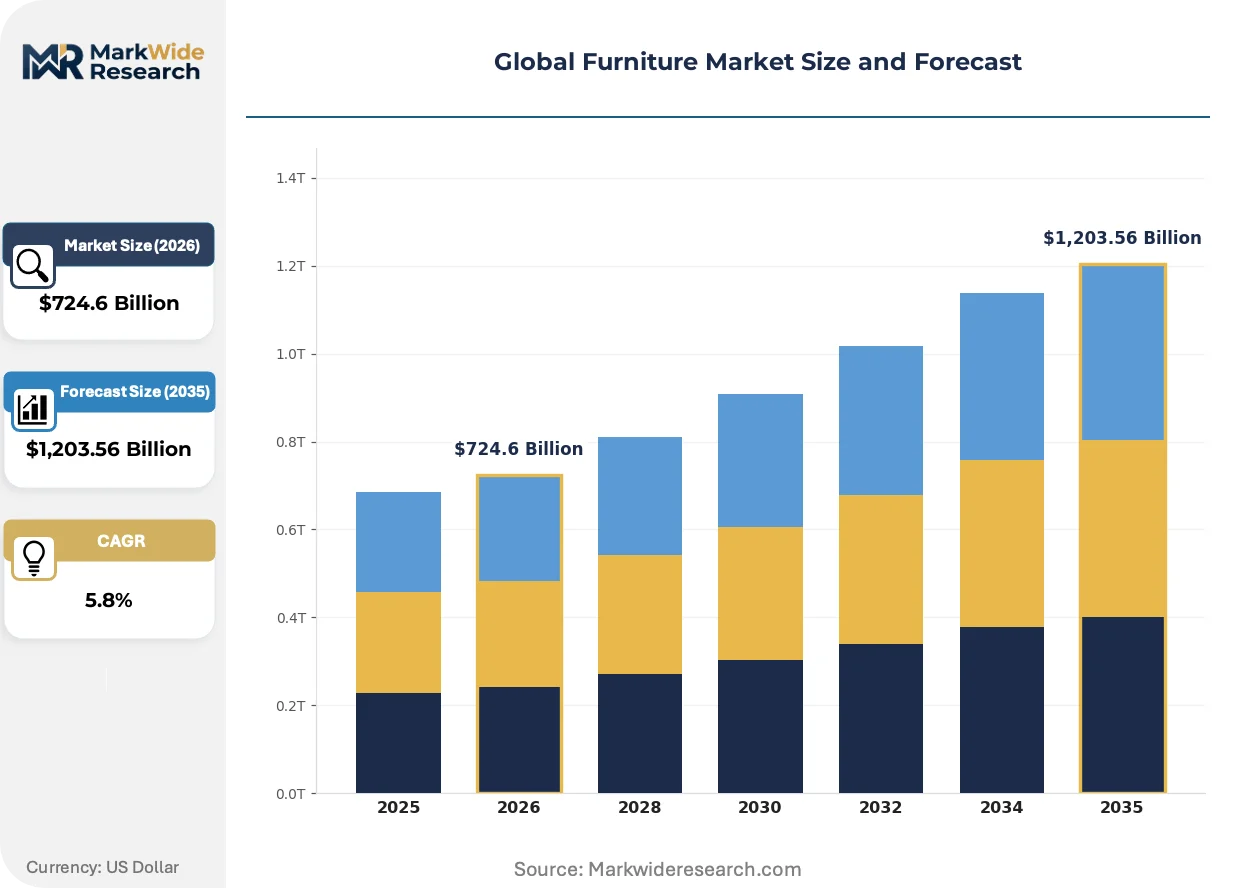
| Market Size in 2026 | $724.6 Billion |
| Market Size in 2035 | $1,203.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Plastic, Upholstery End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Williams-Sonoma, Herman Miller, IKEA, Haworth, La-Z-Boy, Wayfair, Steelcase, RH (Restoration Hardware), Ashley Furniture Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Furniture Market Emerging Trajectories
Material science breakthroughs and circular economy frameworks are converging to redefine value capture models across furniture manufacturing, with particular intensity in upholstery chemistry and end-of-life logistics.
Water-based polyurethane finishes are migrating from niche artisan applications to mainstream residential production. Large-format Italian upholstery manufacturers are adopting these systems to meet REACH chemical restrictions without sacrificing abrasion resistance. The technology is migrating from premium positioning toward mid-market accessibility as application equipment costs decline.
REACH chemical disclosure requirements are tightening allowable substance thresholds in European upholstered goods. ECHA substance evaluations are driving reformulation of flame retardant packages and plasticizer chemistries across supplier tiers. Contract furniture specification in Germany, France, and the Netherlands now prioritizes full material health documentation over single-attribute certifications.
Direct-to-manufacturer procurement platforms are compressing traditional wholesale and retail markups in commercial project channels. Facility managers and interior design firms are accessing factory pricing through vertical sourcing tools that bypass regional distribution. This pattern is most pronounced in North American and Australian hospitality and workplace fit-out markets where project scale justifies container-direct logistics.
Global Furniture Market Segmentation
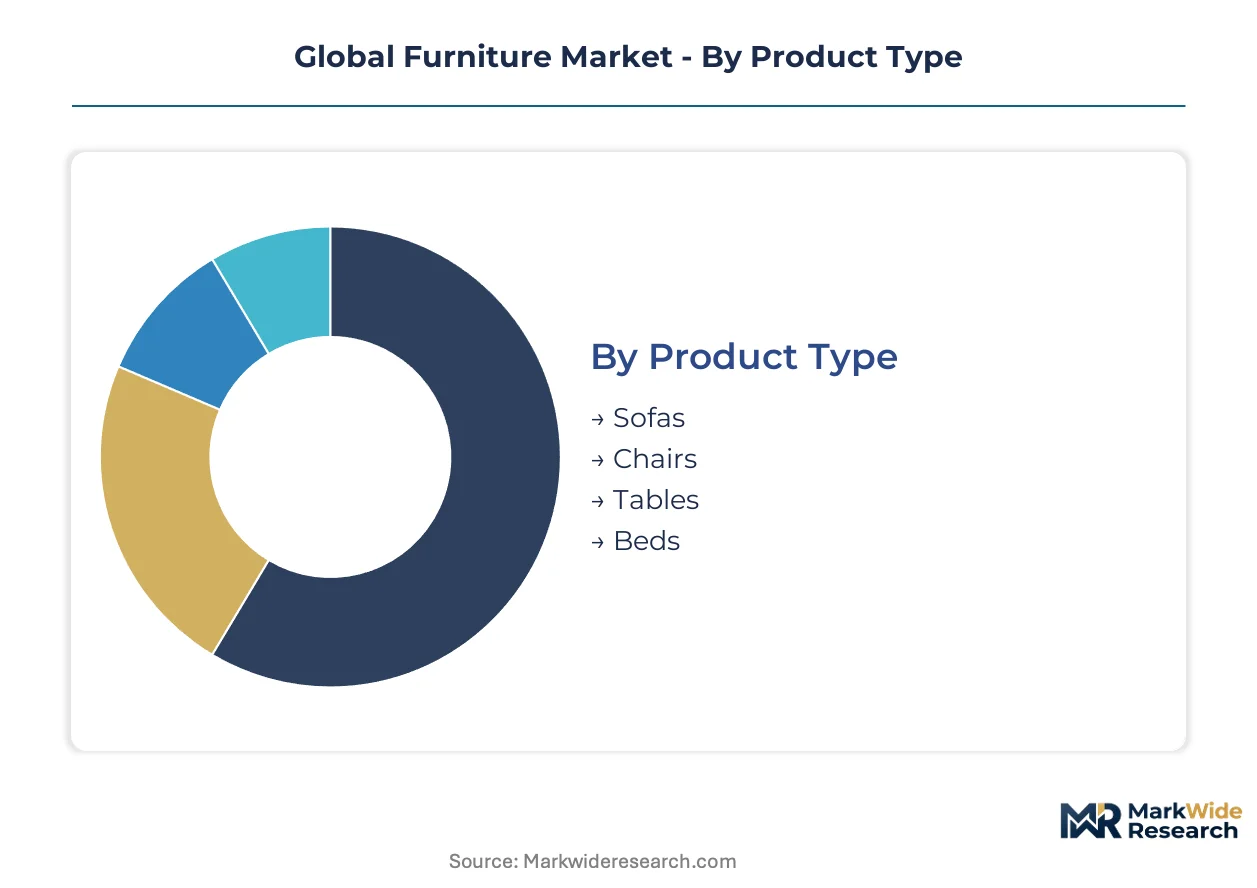
Furniture segmentation reveals how specification requirements diverge across residential comfort, commercial durability, and hospitality fire-safety standards. Material chemistry and distribution economics create distinct margin architectures within each slice.
Product Type:
Seating and surface products span radically different engineering tolerances from lounge comfort to structural load-bearing.
- Sofas:Multi-seat upholstered frames with suspension systems and cushion cores engineered for deflection recovery. Hospitality procurement in Dubai and Miami drives demand for contract-grade foam densities and ignition-resistant fabrics.
- Chairs:Single-occupancy seating ranging from task ergonomics to accent aesthetics. German workplace specification prioritizes DIN-certified lumbar support and 8-hour duty cycle testing.
- Tables:Horizontal work and dining surfaces spanning cantilever, pedestal, and trestle structures.
- Beds:Sleep systems integrating platform, panel, and adjustable base configurations.
The dominant share belongs to Sofas, while Chairs is closing the gap fastest.
Material:
Cost tiers separate scarce solid-wood heirloom positioning from mass-market engineered substrates.
- Wood:Solid timber and engineered panels governed by FSC chain-of-custody and EUDR geolocation mandates. Vietnamese export manufacturers are absorbing compliance costs for EU market access.
- Metal:Steel and aluminum framing for commercial duty cycles and fire-rating requirements. Indian hospital and airport procurement specifies powder-coated tubular construction.
- Plastic:Injection-molded and rotationally formed polymers for outdoor and educational segments.
- Upholstery:Fabric, leather, and synthetic coverings over foam and fiber padding systems.
Wood commands the largest volume position, though Metal is expanding most quickly in commercial fit-out channels.
End User:
Customer type determines warranty terms, replacement cycles, and specification authority structures.
- Residential:Individual household purchase with discretionary replacement timelines. Brazilian mortgage expansion in São Paulo and Rio de Janeiro is pulling demand for entry-level bedroom and dining sets.
- Commercial:Corporate and institutional procurement with depreciation schedules and bulk purchasing. Australian federal government workplace standards mandate sit-stand desking and ergonomic task seating.
- Hospitality:Hotel, cruise, and food-service operators with branded interiors programs and rapid refresh cycles.
- Office:Dedicated workplace environments with open-plan and private office configurations.
Residential maintains volume leadership, yet Hospitality is climbing the fastest on chain expansion in the Middle East and Southeast Asia.
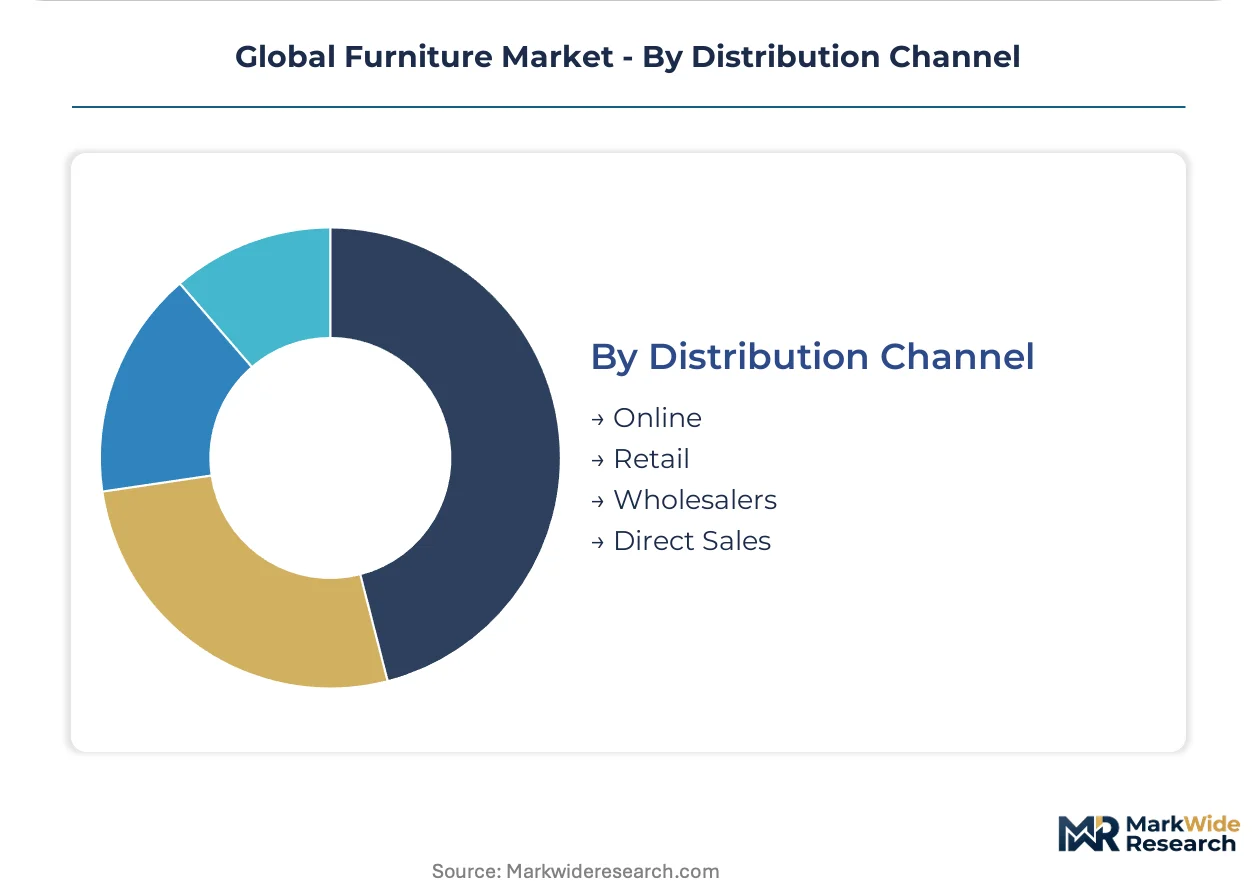
Distribution Channel:
Supply concentration varies from captive retail networks to fragmented wholesale intermediaries.
- Online:Direct-to-consumer platforms with augmented reality visualization and flat-pack logistics. UK and Netherlands consumers show highest conversion rates for unassisted sofa purchases.
- Retail:Brick-and-mortar showrooms with tactile evaluation and immediate fulfillment. Indonesian mall operators in Jakarta and Surabaya are expanding furniture-dedicated floor space.
- Wholesalers:Regional distributors serving independent furniture stores and interior designers.
- Direct Sales:Factory-direct procurement for project-scale commercial and hospitality contracts.
Retail still holds the dominant position, while Online is gaining share fastest on logistics improvements and return-policy standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for certified sustainable furniture, while Indian and Vietnamese consumers prioritize cost efficiency over material provenance. The United States occupies a middle position where brand reputation moderates sensitivity. This divergence shapes regional go-to-market architectures.
United States
Corporate workplace refurbishment and single-family residential construction drive demand for ergonomic seating and modular storage systems. EPA formaldehyde emission standards and CARB Phase 2 compliance create certification barriers for imported composite wood products. Manufacturing concentrates around High Point, North Carolina, where showroom complexes and distribution infrastructure support contract furniture specification.
Germany
Extended producer responsibility frameworks and circular economy procurement mandates accelerate demand for take-back and refurbishment services. REACH chemical disclosure requirements enforced by ECHA tighten allowable substance thresholds in upholstered goods. Industrial clusters in North Rhine-Westphalia host specialized metal framing and task seating manufacturers serving pan-European workplace fit-out channels.
China
Urban residential upgrading and hospitality chain expansion in tier-2 cities sustain volume demand for mid-market sofas and dining systems. Dual carbon goals and MEE enforcement are restructuring energy-intensive manufacturing in the Pearl River Delta. Zhejiang province furniture exporters are absorbing compliance costs for EU Deforestation Regulation geolocation documentation requirements.
Vietnam
Export-oriented production for North American and European retailers dominates output, with flat-pack and upholstered categories leading volume. Port congestion and industrial zone energy rationing disrupt just-in-time delivery commitments. Manufacturing concentrates around Ho Chi Minh City and Binh Duong province, where foreign-invested facilities integrate FSC chain-of-custody certification for EU market access.
India
Mortgage penetration in tier-2 cities and urban household formation expand addressable demand for ready-to-assemble bedroom and dining furniture. BIS quality standards and DGFT import regulations shape competitive dynamics against Southeast Asian suppliers. Industrial corridors in Gujarat and Tamil Nadu are attracting organized retail and e-commerce fulfillment infrastructure for furniture distribution.
Global Furniture Market Vendor Landscape
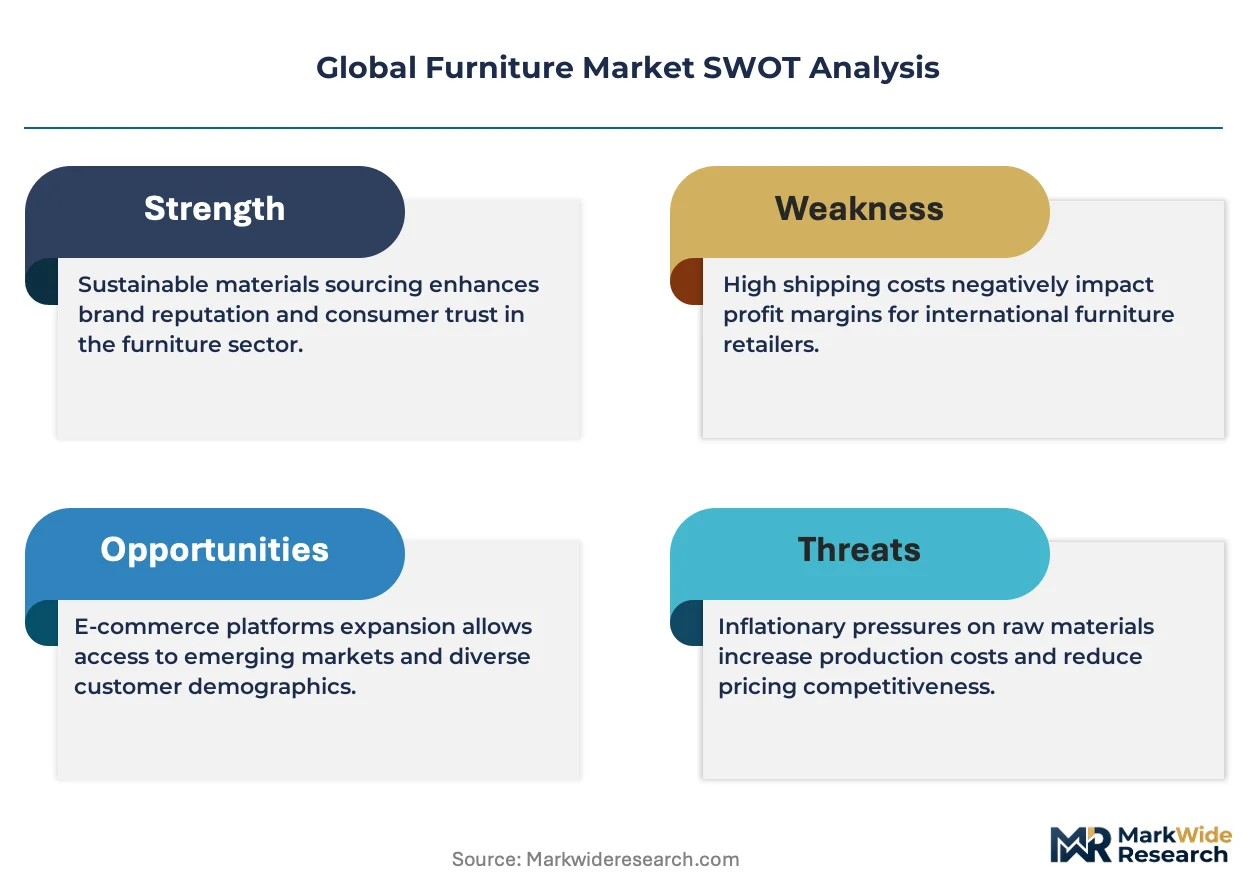
Capability concentration sits with heritage European and North American specialists commanding premium specification channels; scale advantage sits with Asian flat-pack manufacturers optimizing logistics density. The market structures around three tiers: integrated retailers controlling captive supply networks, workplace consultants bundling furniture with change-management services, and pure-play e-commerce platforms disintermediating wholesale markups. Dominant competitive moves include backward integration into component manufacturing and strategic partnerships with hospitality brand owners for interiors program exclusivity.
Among heritage North American specialists, Herman Miller and Steelcase exemplify the workplace-consulting archetype, anchoring premium positioning through certified refurbishment and ergonomic research capabilities. IKEA represents the integrated-retail tier, controlling in-house production of flat-pack components across captive supply networks spanning multiple continents. Williams-Sonoma occupies a position within the lifestyle-brand segment, leveraging catalog and digital channels to capture residential furniture demand alongside complementary home goods.
| Leading Market Players |
|---|
| Williams-Sonoma |
| Herman Miller |
| IKEA |
| Haworth |
| La-Z-Boy |
| Wayfair |
| Steelcase |
| RH (Restoration Hardware) |
| Ashley Furniture Industries |
| Others |
Supply Flow & Price Mechanics
Vietnamese flat-pack component manufacturing anchors margin capture for European and North American retailers, concentrating assembly cost advantages in Ho Chi Minh City industrial zones while premium upholstery fabrication retains pricing power in Italian and German heritage clusters.
Pricing Analysis
Refurbishment and take-back service contracts drive lifetime value capture in commercial seating. Three-tier pricing structure across certified sustainable, standard performance, and entry-level economy levels separates hospitality procurement from residential channels. Cost compression in Southeast Asian export manufacturing intensifies as EUDR compliance documentation adds administrative overhead. Hospitality buyers in Dubai and Miami demonstrate lowest price sensitivity, while Indian tier-2 city residential purchasers prioritize cost efficiency over material provenance.
Supply Chain Analysis
EU Deforestation Regulation geolocation mandates function as de facto export controls on tropical timber flows, restricting uncertified wood sourcing from Indonesian and Malaysian supplier bases. Manufacturing gravity centers on Vietnam, Indonesia, and China for flat-pack and upholstered export production, drawing from FSC-certified timber, high-density polyurethane foam, and fire-resistant synthetic textiles. Single-source vulnerability concentrates in Ho Chi Minh City port infrastructure and Binh Duong province energy supply. Distribution runs through captive retail networks, direct-to-manufacturer platforms, and container-direct project logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Furniture Market sits in early-cycle expansion, with hospitality chain branded interiors programs and residential mortgage penetration in emerging urban centers driving adoption velocity ahead of replacement-cycle saturation.
For Market Incumbents: Harden certification moats by accelerating FSC chain-of-custody and OEKO-TEX Standard 100 investment ahead of REACH substance restriction tightening. Deepen backward integration into foam and fabric component manufacturing to defend margin position against direct-to-manufacturer platform disintermediation. Steelcase and Herman Miller demonstrate workplace consulting bundling as a defensive lever against pure-play e-commerce entrants.
For New Entrants and Emerging Players: Build out India residential market presence targeting tier-2 city flat-pack and ready-to-assemble furniture demand, where mortgage expansion and urban household formation outpace organized retail penetration. Prioritize augmented reality visualization tools and return-policy standardization to capture UK and Netherlands online sofa purchase conversion patterns. Direct-to-consumer platforms with captive last-mile logistics represent the most penetrable channel architecture.
For Investors and Strategic Acquirers: Capital is best deployed toward certified refurbishment operators and take-back service platforms in Germany and France, where extended producer responsibility mandates create structural revenue pools. Long-term viability favors asset-light service architectures over capital-intensive manufacturing across the five-to-ten year window. Monitor EUDR enforcement intensity and blockchain chain-of-custody adoption rates as inflection signals for compliance cost redistribution across supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Refurbishment Program Launch | Captures circular economy service revenue pools under Germany's packaging and end-of-life mandates. |
| Blockchain Chain-of-Custody Implementation | Satisfies EU Deforestation Regulation geolocation documentation for tropical timber sourcing compliance. |
| Direct-to-Manufacturer Platform Integration | Compresses wholesale markups in North American hospitality and workplace fit-out procurement channels. |
| Water-Based Polyurethane Finish Adoption | Meets REACH chemical restrictions without sacrificing abrasion resistance in Italian upholstery manufacturing. |
| Biomaterial Hybridization R&D Partnership | Opens performance tiers between petroleum synthetics and natural latex through mycelium-foam development. |
Methodological Framework
Initial hypotheses were tested against primary input from furniture manufacturing executives, hospitality procurement directors, retail category buyers, and sustainability compliance officers and refined through secondary validation against customs trade data, SEC 10-K filings, FSC chain-of-custody databases, and ECHA substance restriction notifications. Bottom-up demand modeling across product type, material category, end-user segment, and distribution channel triangulated with top-down macroeconomic indicators.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation dimensions including seating versus surface products, wood versus metal versus upholstery materials, residential versus commercial versus hospitality end users, and online versus retail versus direct sales channels. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted penetration assumptions, incorporating hospitality chain expansion pipelines, mortgage penetration curves, and regulatory compliance cost pass-through rates as industry-specific inputs.
Stress conditions across port congestion severity, energy rationing intensity, and REACH substance restriction scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding supply chain restructuring timelines and certification adoption rates. Cross-checking against IEA industrial energy data and UN Comtrade furniture export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
High Density Fiberboard (HDF) Market
Furniture
Cabinet Market
Furniture
Ergonomic Chair Market
Furniture
Global Smart Furniture Market
Furniture
Australia Smart Furniture Market
Furniture
Global Folding Furniture Market
Furniture
Contract Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Luxury RTA (Ready-To-Assemble) Furniture Market
Furniture
Canada Home Furniture Market
Furniture
North America Slide Rails Market
Furniture
Taiwan Home Furniture Market
Furniture
Upholstered Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
North America Smart Furniture Market