
 Portering Chair Market | 2026-2036
Portering Chair Market Size, Share, and Industry Trends Forecast 2026-2036
Portering Chair Market Analytics
Hospital procurement channels is tilting toward direct manufacturer relationships as group purchasing organizations lose leverage over specialized mobility equipment. Stryker Corporation leverages its integrated hospital supply contracts to sustain volume commitments across North American health systems. Accora Ltd anchors its position through bariatric specialization, while Roma Medical competes on National Health Service framework agreements in the United Kingdom.
A portering chair is a wheeled patient transport device, typically constructed from aluminum or steel tubing with fabric or synthetic seating surfaces, designed to move non-ambulatory individuals within healthcare facilities or during emergency transfer. Load capacity, foldability, and brake mechanisms constitute critical functional parameters for clinical acceptance. Transport chairs lead product type demand due to their prevalence in emergency departments, while stretcher chairs capture premium margin pools from ambulance retrofit programs. Aluminum material selection dominates new procurement as facilities prioritize maneuverability compliance under manual handling regulations.
The FDA Center for Devices and Radiological Health classifies portering chairs as Class I medical devices, requiring adherence to quality system regulations that shape manufacturer market access timelines. ISO 13485 certification and EU MDR technical documentation obligations further filter supplier participation in transatlantic trade. Stakeholders must monitor evolving patient-lifting directives from OSHA and the EU's Machinery Directive amendments, as these frameworks increasingly mandate powered-assist features that could reshape product development priorities and supplier qualification thresholds.
Market Dynamics
Hospital procurement teams are abandoning group purchasing organizations for direct manufacturer relationships in specialized mobility equipment, a structural shift that compresses distributor margins while rewarding suppliers with integrated service capabilities.
Growth Catalysts
- EU Machinery Directive amendments:The revised directive mandates powered-assist features for patient-handling equipment, compelling fleet upgrades across German and French health systems and opening specification windows for compliant suppliers.
- Aluminum-frame adoption:Emergency medical services in the United States prioritize weight-reduction protocols for manual handling compliance, driving replacement cycles for legacy steel-frame inventory.
- Bariatric patient volumes:Obesity prevalence in the United Kingdom National Health Service expands demand for 250kg+ load-capacity transport chairs, a segment underserved by standard-configuration manufacturers.
Market Restraints
- Aluminum price volatility:LME aluminum futures fluctuations squeeze mid-tier manufacturer margins, particularly for suppliers without long-term smelter contracts or hedging programs.
- ISO 13485 certification backlog:Notified body capacity constraints in Europe extend technical documentation review timelines, delaying market access for new entrants by 8-14 months.
- Powered stretcher substitution:Ambulance retrofit programs in North America increasingly specify full-electric stretchers rather than manual portering chairs for inter-facility transfers.
Strategic Opportunities
- India hospital infrastructure:The country's PLI scheme for medical devices creates tariff and incentive advantages for domestic manufacturing of transport chairs targeting tier-2 and tier-3 city hospitals.
- Rental and subscription models:Home healthcare agencies in Japan are piloting per-use pricing for bariatric portering chairs, reducing capital barriers for smaller operators.
- EU MDR technical documentation:Early compliance with the regulation's post-market surveillance requirements positions suppliers for preferred vendor status in framework agreements.
Industry Challenges
- Biomechanical engineering talent scarcity:Manufacturers struggle to recruit specialists capable of integrating powered-assist mechanisms with manual handling compliance protocols.
- Legacy fleet interoperability:Hospital systems demand backward-compatible accessories and replacement parts, constraining design freedom for next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portering Chair Market |
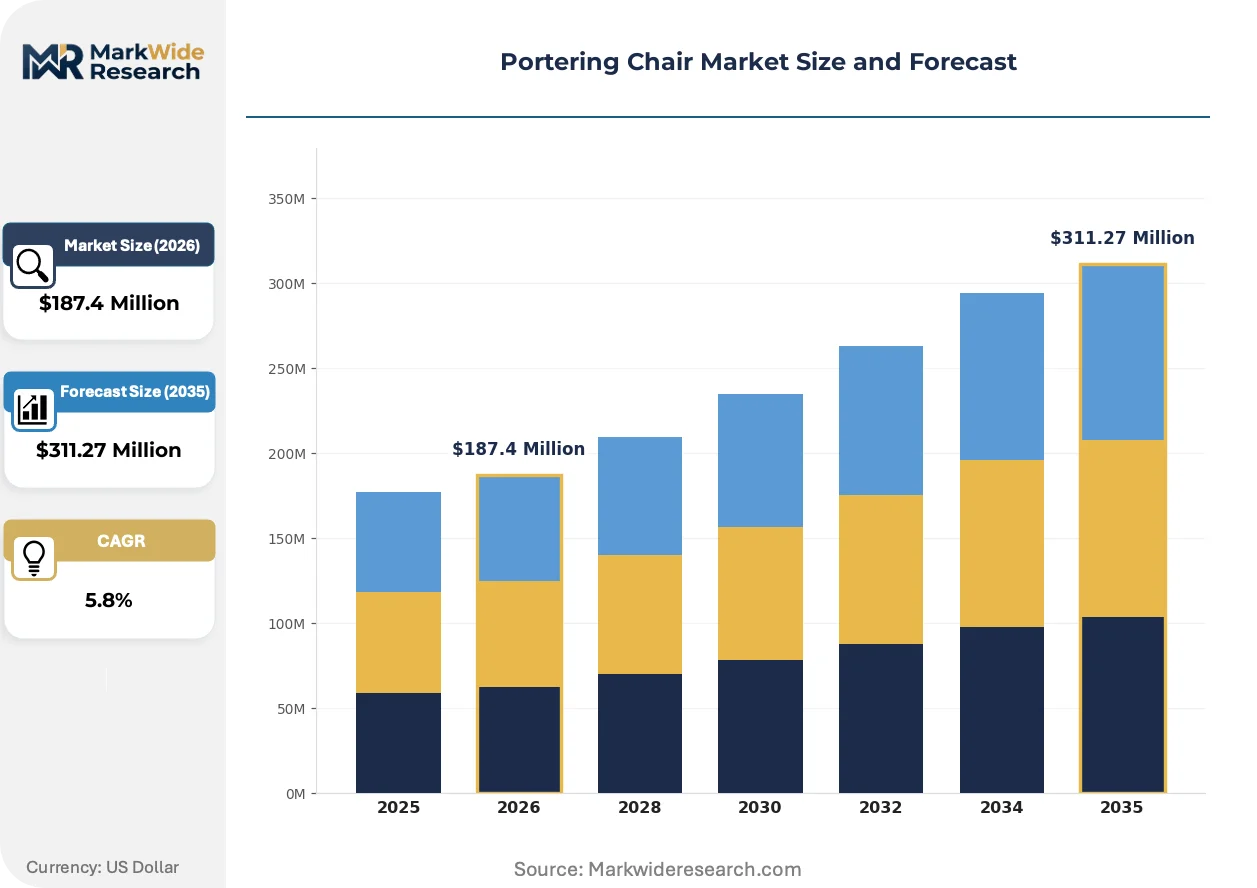
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transport Chairs, Wheelchairs, Geriatric Chairs, Stretcher Chairs Application: Hospitals, Nursing Homes, Ambulance Services, Rehabilitation Centers End User: Healthcare Professionals, Caregivers, Patients, Emergency Responders Material: Aluminum, Steel, Fabric, Plastic |
| Companies Covered | Stryker Corporation, Accora Ltd, Roma Medical, Bristol Maid, Promotal, Antano Group, G & J Logistics Limited, Welco, Acime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portering Chair Market Evolving Landscape
Electrification of manual handling equipment is compressing product lifecycles while regulatory mandates accelerate specification turnover across emergency medical services and acute care settings.
Carbon fiber-reinforced polymer seating structures are collapsing the weight-performance tradeoff that has constrained aluminum-frame designs for two decades. Emergency departments in Sweden and Denmark are specifying sub-6kg transport chairs for corridor maneuverability compliance. This material transition is collapsing the premium tier price floor, forcing aluminum specialists to defend positioning through integrated braking systems rather than weight claims alone.
The EU Medical Device Regulation's post-market clinical follow-up requirements are extending technical documentation obligations for Class I devices previously exempt from systematic surveillance. Manufacturers must now maintain clinical evidence portfolios for portering chair safety claims, a burden that favors larger suppliers with regulatory affairs infrastructure. German and Dutch health systems are prioritizing MDR-compliant suppliers in procurement evaluations, creating qualification thresholds that filter smaller competitors.
Direct contracting between manufacturers and hospital supply chain directors is displacing distributor-mediated purchasing for high-volume mobility fleets. Group purchasing organizations lose leverage when specialized equipment requires customization, training, and preventive maintenance bundling. This channel compression is most visible in United States health systems with dedicated patient-handling safety officers who specify equipment directly.
Portering Chair Market Segmentation
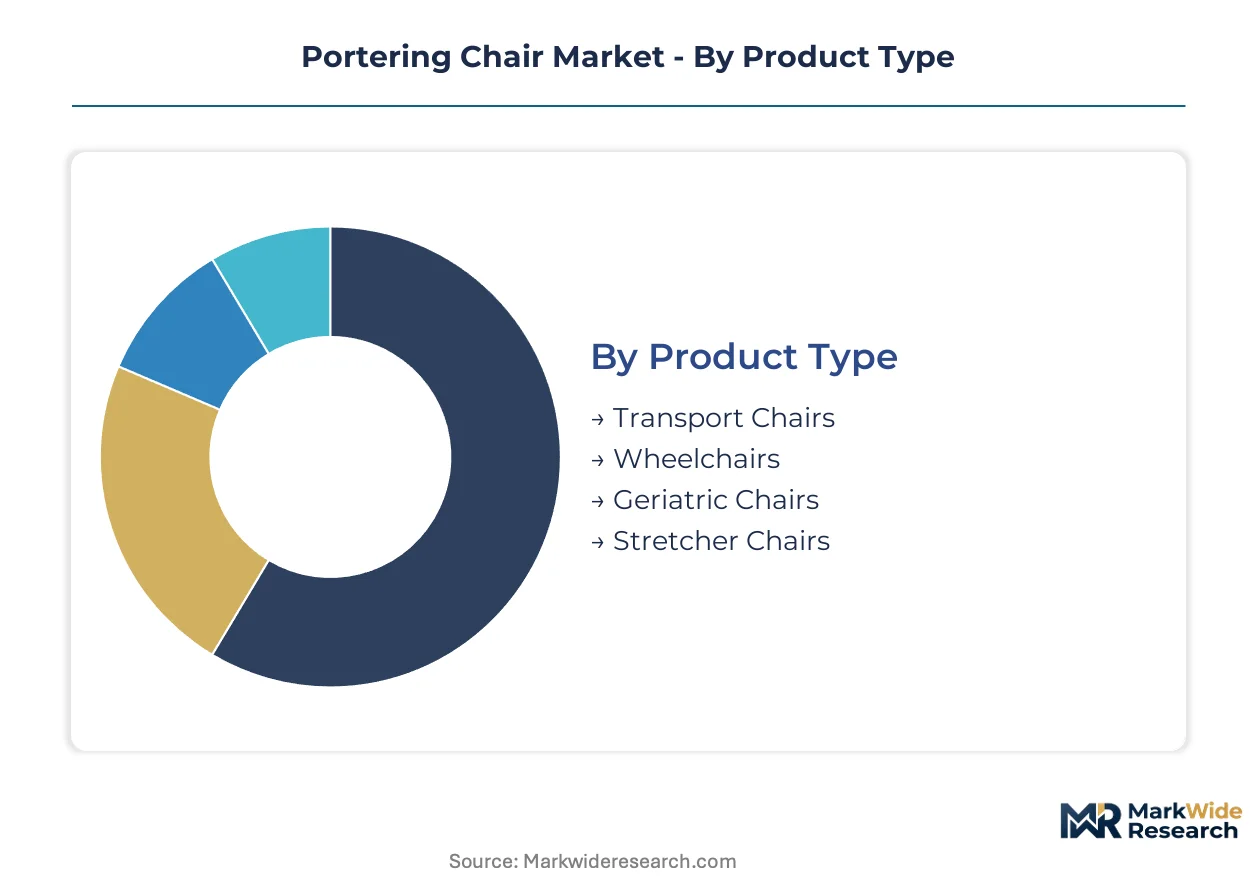
Segmentation in the portering chair market reveals how procurement priorities diverge across care settings and user capabilities. Product specifications, material selection, and end-user ergonomics determine contract outcomes in hospital fleet tenders and emergency medical services retrofit programs.
Product Type:
Cost tier differentiation separates high-rotation emergency equipment from specialized bariatric platforms with extended service intervals.
- Transport Chairs:Lightweight aluminum or steel frames with folding mechanisms dominate emergency department corridors and inter-ward transfers. Demand concentrates in United States health systems updating manual handling compliance protocols, where OSHA injury reduction mandates accelerate fleet replacement cycles.
- Stretcher Chairs:Height-adjustable platforms bridge ambulance gurneys and examination tables, commanding premium positioning through integrated hydraulic or powered lift mechanisms. Ambulance retrofit programs in Germany and France prioritize these units under EU Machinery Directive amendments requiring powered-assist features for patient-handling equipment.
- Wheelchairs:Self-propelled and attendant-propelled configurations serve extended mobility needs in rehabilitation and long-term care settings.
- Geriatric Chairs:Reclining backrests and pressure-redistribution seating address extended sitting protocols in nursing facilities.
Transport chairs command the established base. The steepest expansion runs through stretcher chairs as regulatory mandates reshape ambulance specifications.
Application:
Volume concentration varies sharply by care setting, with acute facilities prioritizing throughput metrics and long-term operators emphasizing durability amortization.
- Hospitals:High-frequency deployment corridors demand rapid-sanitization surfaces and corrosion-resistant frame coatings. Procurement teams in the United Kingdom National Health Service framework agreements specify aluminum construction for maneuverability compliance, while North American systems bundle preventive maintenance contracts with direct manufacturer relationships.
- Ambulance Services:Inter-facility transfer protocols require load capacities exceeding 200kg and compatibility with vehicle-mounted fastening systems. Emergency medical services in Sweden and Denmark are specifying sub-6kg carbon fiber-reinforced units for corridor maneuverability, collapsing the weight-performance tradeoff that constrained aluminum designs.
- Nursing Homes:Extended-use environments prioritize pressure-relief seating and fall-risk containment features.
- Rehabilitation Centers:Therapy-integrated models require adjustable positioning for progressive mobility training.
Hospitals anchor procurement volume. Ambulance services are climbing the fastest as regulatory retrofit windows open across European emergency fleets.
End User:
Customer type determines ergonomic specification priorities, with professional users demanding institutional durability and caregivers requiring lightweight maneuverability.
- Healthcare Professionals:Hospital nursing staff and patient transport teams operate equipment through 12-hour shifts, driving demand for brake mechanisms accessible from multiple positions and antimicrobial surface treatments. The FDA Center for Devices and Radiological Health Class I device classification shapes training documentation requirements for institutional purchasers.
- Emergency Responders:Paramedics and emergency medical technicians require single-operator loading capabilities and compact folded footprints for vehicle stowage. Field conditions in United States emergency services prioritize corrosion resistance and rapid decontamination protocols.
- Caregivers:Home health aides and family members need intuitive folding mechanisms and manageable transport weights for vehicle loading.
- Patients:Limited direct purchasing; specifications influenced through accessibility advocacy and reimbursement pathway requirements.
Healthcare professionals command the established base. Emergency responders are expanding most quickly as powered-assist mandates reshape field equipment standards.
Material:
Supply concentration and price volatility in raw material markets directly constrain manufacturer margin structures and procurement timing.
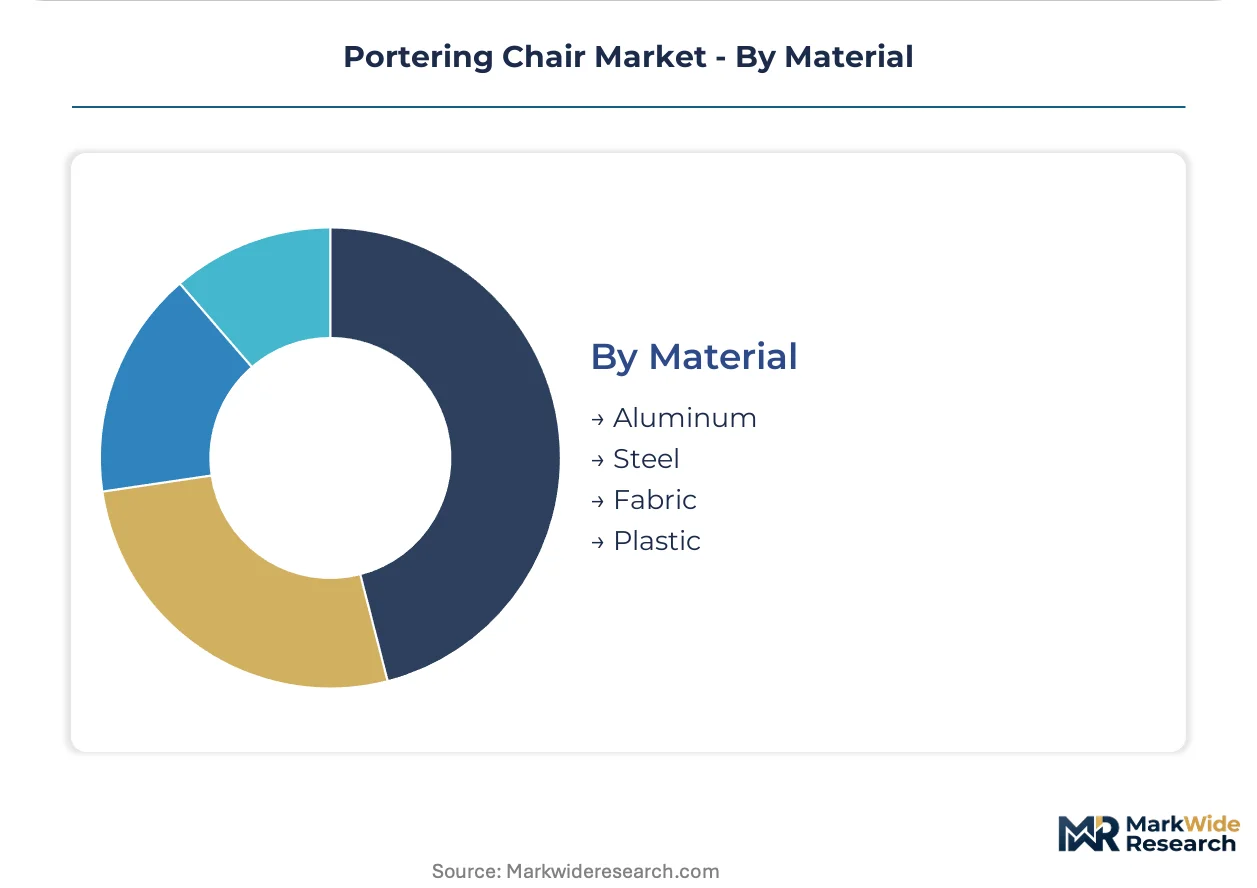
- Aluminum:Alloy tubing delivers the strength-to-weight ratio that manual handling regulations demand, with 6061-T6 and 7005 series dominating structural applications. LME aluminum futures volatility squeezes mid-tier manufacturers lacking long-term smelter contracts, while emergency medical services in the United States prioritize weight-reduction protocols for OSHA compliance.
- Steel:Chromoly and carbon steel frames persist in budget-tier institutional procurement and bariatric load-capacity segments where absolute strength outweighs weight considerations.
- Fabric:Vinyl-coated polyester and antimicrobial mesh seating surfaces balance sanitization protocols with patient comfort in extended transfers.
- Plastic:Glass-reinforced nylon components reduce part count in folding mechanisms and brake housings.
Aluminum commands the established base. Carbon fiber-reinforced polymers are gaining share fastest as Swedish and Danish health systems specify sub-6kg emergency transport units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics corridor underwrites the Netherlands' role in European portering chair distribution, connecting German manufacturing clusters to United Kingdom health system procurement channels.
United States
OSHA injury reduction mandates accelerate fleet replacement cycles across health systems, while the FDA Center for Devices and Radiological Health maintains Class I device classification with quality system regulation requirements. Emergency medical services in Texas and California prioritize weight-reduction protocols, driving aluminum-frame procurement for manual handling compliance.
Germany
The EU Machinery Directive amendments mandate powered-assist features for patient-handling equipment, compelling fleet upgrades across Bavarian and North Rhine-Westphalian health systems. German hospital procurement teams specify ISO 13485-certified suppliers in framework agreements, with technical documentation review timelines filtering market access for new entrants.
United Kingdom
Obesity prevalence in National Health Service facilities expands demand for bariatric transport chairs exceeding 250kg load capacity. The NHS framework agreements prioritize aluminum construction for maneuverability compliance, with procurement concentrated through Greater London and Midlands hospital trusts updating patient-handling safety protocols.
India
The PLI scheme for medical devices creates tariff advantages for domestic manufacturing of transport chairs targeting tier-2 and tier-3 city hospitals. Maharashtra and Karnataka health infrastructure expansions drive procurement from emerging domestic fabricators, while CDSCO device registration requirements shape supplier qualification timelines.
Sweden
Emergency medical services specify sub-6kg carbon fiber-reinforced transport chairs for corridor maneuverability compliance, collapsing the weight-performance tradeoff that constrained aluminum designs. Stockholm and Copenhagen health systems lead specification shifts, with procurement prioritizing rapid-sanitization surfaces for emergency department deployment.
Portering Chair Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: integrated hospital supply contractors, bariatric specialists, and regional framework agreement competitors. Tier-one players leverage direct manufacturer relationships with health systems, while mid-tier suppliers compete on National Health Service and European public procurement frameworks. The dominant competitive moves involve portfolio diversification into powered-assist mechanisms and geographic expansion through distributor network compression.
Among United States-based integrated suppliers, Stryker Corporation exemplifies the hospital supply contract archetype, while Accora Ltd represents bariatric specialization positioning. Roma Medical occupies a position within United Kingdom framework agreement competition, anchoring the regional public procurement tier alongside European specialists.
| Leading Market Players |
|---|
| Stryker Corporation |
| Accora Ltd |
| Roma Medical |
| Bristol Maid |
| Promotal |
| Antano Group |
| G & J Logistics Limited |
| Welco |
| Acime |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's medical device logistics corridor anchors European portering chair distribution, connecting German aluminum alloy suppliers to United Kingdom National Health Service procurement channels. This geographic concentration grants Dutch and German manufacturers pricing leverage over United Kingdom and Nordic buyers dependent on just-in-time fleet replenishment.
Pricing Analysis
Volume-discount tiering structures separate premium powered-assist stretcher chairs from standard aluminum transport frames and economy-grade steel configurations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and bundled preventive maintenance contracts. Cost compression in mid-tier aluminum frames is intensifying because LME futures volatility squeezes manufacturers lacking long-term smelter agreements. Home healthcare agencies exhibit highest price sensitivity, while hospital systems with dedicated patient-handling safety officers prioritize compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for component sourcing. Manufacturing concentrates in China, Germany, and the United States, with aluminum alloy tubing drawing from Chinese smelters and German extrusion specialists. Supply chains rest on vinyl-coated polyester seating fabrics and glass-reinforced nylon folding mechanisms vulnerable to petrochemical price swings. Distribution runs through direct manufacturer relationships with hospital procurement teams, compressing traditional medical device distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portering chair demand sits in early-cycle expansion as EU Machinery Directive amendments mandate powered-assist fleet upgrades across German and French health systems. This regulatory tailwind accelerates specification turnover and opens contract windows for compliant suppliers.
For Market Incumbents: Build regulatory certification moats through early EU MDR technical documentation compliance and ISO 13485 portfolio expansion. Secure long-term aluminum supply contracts to hedge against LME volatility threatening mid-tier competitors. Acquire carbon fiber-reinforced polymer seating specialists before Swedish and Danish procurement specifications collapse the premium aluminum price floor. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 city hospital infrastructure under the PLI scheme's tariff advantages. Target bariatric transport chairs exceeding 250kg load capacity, a segment underserved by standard-configuration incumbents in United Kingdom National Health Service frameworks. Deploy rental and subscription pricing models proven in Japanese home healthcare pilots to reduce capital barriers for smaller operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers bundling preventive maintenance with direct hospital contracts. Five-to-ten year viability favors vertically integrated manufacturers with captive aluminum sourcing and regulatory affairs infrastructure. Watch for carbon fiber-reinforced polymer adoption rates in Scandinavian emergency medical services as the inflection signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Compliance | Positions suppliers for preferred vendor status in German and Dutch framework agreements. |
| Powered-Assist Mechanism Integration | Meets EU Machinery Directive mandates while opening premium pricing tiers in ambulance retrofit programs. |
| Carbon Fiber-Reinforced Polymer Adoption | Enables sub-6kg emergency transport specifications driving Swedish and Danish procurement shifts. |
| Direct Hospital System Partnership | Bypasses group purchasing organizations to capture higher margins through bundled service contracts. |
| India PLI Scheme Manufacturing Localization | Creates tariff advantages for domestic production targeting tier-2 and tier-3 city hospital expansions. |
Research Methodology
A spread of perspectives from hospital procurement directors, biomedical engineers, emergency medical services fleet managers, and group purchasing organization contract specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, and National Health Service framework agreement records. Hospital procurement databases, aluminum futures market data, and CDSCO device registration filings anchored bottom-up and top-down triangulation across the analysis window.
Demand-supply-balance framing modeled volume and value outputs across product type, material composition, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from replacement cycle analysis tied to OSHA injury reduction mandates and EU Machinery Directive compliance deadlines. Forecast inputs incorporated aluminum price trajectory scenarios and powered-assist technology adoption curves in ambulance retrofit programs.
Sensitivities concentrate around LME aluminum volatility, notified body capacity constraints extending ISO 13485 certification timelines, and carbon fiber-reinforced polymer cost curves enabling Scandinavian specification shifts. Forecasts reflect assumptions about regulatory implementation pacing and hospital capital expenditure cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Laminated Door Market
Furniture
Italy Furniture Market
Furniture
Recliner Chair Market
Furniture
Ergonomic Chair Market
Furniture
China Upholstered Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Chaises Longue Market
Furniture
Global Multifunctional Furniture Market
Furniture
United Kingdom Home Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Taiwan Home Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
Furniture Laminate Market
Furniture
School Furniture Market
Furniture
North America Home Furniture Market