
 Vietnam Furniture Market | 2026-2036
Vietnam Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Furniture Market Outlook
Hospitality procurement is decoupling from traditional residential channels as hotel chains expand across Da Nang and Phu Quoc. A.A. Corporation leverages its integrated manufacturing base to supply large-scale commercial fit-outs. Truong Thanh Furniture anchors its position through sustained export relationships with Japanese and Australian buyers. Evergreen Home Furnishings differentiates via specialized outdoor and resort-grade collections targeting coastal developments.
Vietnam furniture comprises assembled and knock-down products crafted from solid timber, engineered wood, metal framing, and upholstery textiles, with finishing processes spanning lacquering, veneering, and powder coating for durability and aesthetic compliance in residential and contract environments. Wood material segments dominate export value due to Vietnam's access to plantation acacia and rubberwood feedstocks, while metal and fabric categories expand fastest in urban apartment and co-working fit-outs. Online retail channels capture growing share among domestic millennials, though showrooms and wholesale direct sales sustain margin pools in project-based hospitality and office verticals.
Vietnam's Ministry of Agriculture and Rural Development enforces VPA-FLEGT timber legality assurance, while the General Department of Vietnam Customs coordinates export documentation with EU market access requirements. BIS-equivalent national standards for product safety and the country's national quality regulator shape domestic manufacturing compliance and testing protocols. Stakeholders must monitor evolving EU deforestation regulation alignment and southern province industrial zoning changes to secure supply chain continuity and certification validity.
Market Dynamics
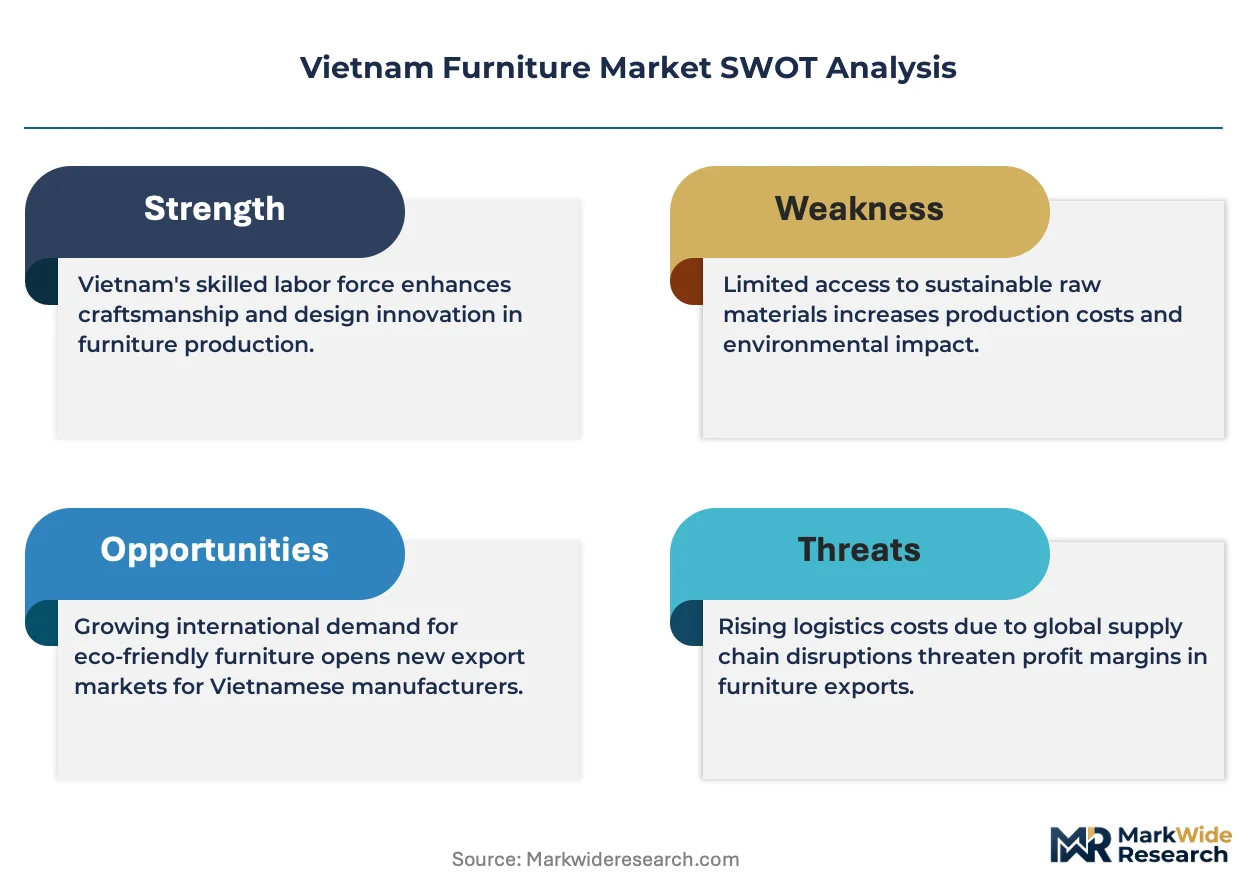
Vietnam's furniture sector faces mounting pressure from EU deforestation regulation alignment, forcing exporters to restructure timber sourcing around certified plantation networks rather than conventional supply bases.
Growth Catalysts
- VPA-FLEGT timber legality framework:Vietnamese authorities tightened verification protocols, accelerating certified supply chain adoption among export-oriented manufacturers.
- Hotel chain expansion:Coastal developments in Da Nang and Phu Quoc generated specialized hospitality procurement channels distinct from residential distribution.
- Plantation acacia feedstock access:Domestic rubberwood and acacia plantations reduced raw material import dependency for solid timber product lines.
Market Restraints
- Input cost volatility:Engineered wood panel prices fluctuate with adhesive resin and energy input movements, compressing margin predictability for knock-down furniture exporters.
- Supply concentration risk:Southern industrial corridor dependence—Ho Chi Minh City to Binh Duong—creates flood and logistics disruption exposure during monsoon periods.
- Regulatory friction:EU Deforestation Regulation documentation requirements extend compliance timelines for small and mid-scale exporters lacking traceability systems.
Strategic Opportunities
- Central Highlands underpenetration:Gia Lai and Dak Lak provinces offer untapped plantation-to-factory integration potential for firms seeking captive timber supply.
- Co-working fit-out vertical:Metal framing and modular fabric systems for urban office spaces represent faster-expanding categories than traditional residential wood furniture.
- Online retail channel innovation:Domestic millennial buyers increasingly purchase through e-commerce platforms, opening direct-to-consumer paths bypassing wholesale intermediaries.
Industry Challenges
- Certification timeline compression:FSC and PEFC chain-of-custody audits require 12-18 month implementation windows that delay EU market re-entry for transitioning suppliers.
- Skilled finishing technician scarcity:Lacquering and veneering craft expertise concentrates among aging workforces in Binh Duong, constraining quality-scaling for new factory investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Furniture Market |
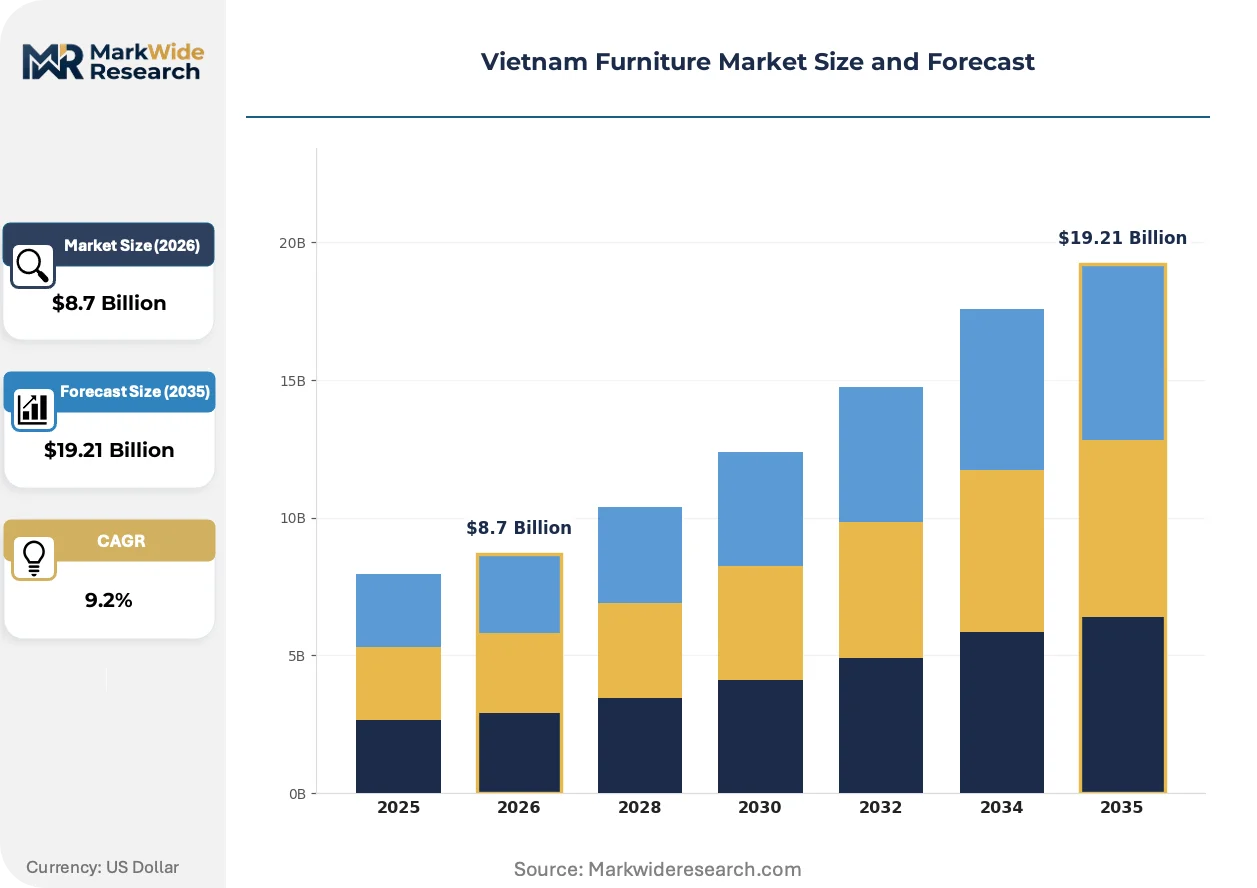
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Plastic, Fabric End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online Retail, Showrooms, Wholesale, Direct Sales |
| Companies Covered | Vina Arya Furniture, Remacro, Primo Sourcing, Misamex Furniture, Evergreen Home Furnishings, A.A. Corporation, Hiệp Long, Canadian Wood, Truong Thanh Furniture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Furniture Market Strategic Shifts
Digital manufacturing tools and regulatory traceability requirements are restructuring how Vietnamese furniture producers design, source, and certify products for export markets.
CNC machining and robotic sanding systems are converging with traditional joinery methods in Binh Duong factories. Large-scale hospitality manufacturers deploy automated cutting for standardized resort furniture components. This convergence is compressing production cycle times for bulk commercial orders while maintaining hand-finish quality tiers.
Vietnam's Ministry of Agriculture and Rural Development enforces VPA-FLEGT legality assurance protocols aligned with EU market access requirements. Exporters must document timber origin through every supply chain tier. Small and mid-scale manufacturers face disproportionate compliance burden relative to integrated plantation-to-factory operators.
Hotel procurement teams now specify certified sustainable materials as mandatory bid criteria rather than optional preferences. Traditional showroom-based specification is giving way to direct manufacturer engagement with hospitality project developers. This pattern is most visible in Phu Quoc and Da Nang resort construction pipelines.
Vietnam Furniture Market Segmentation
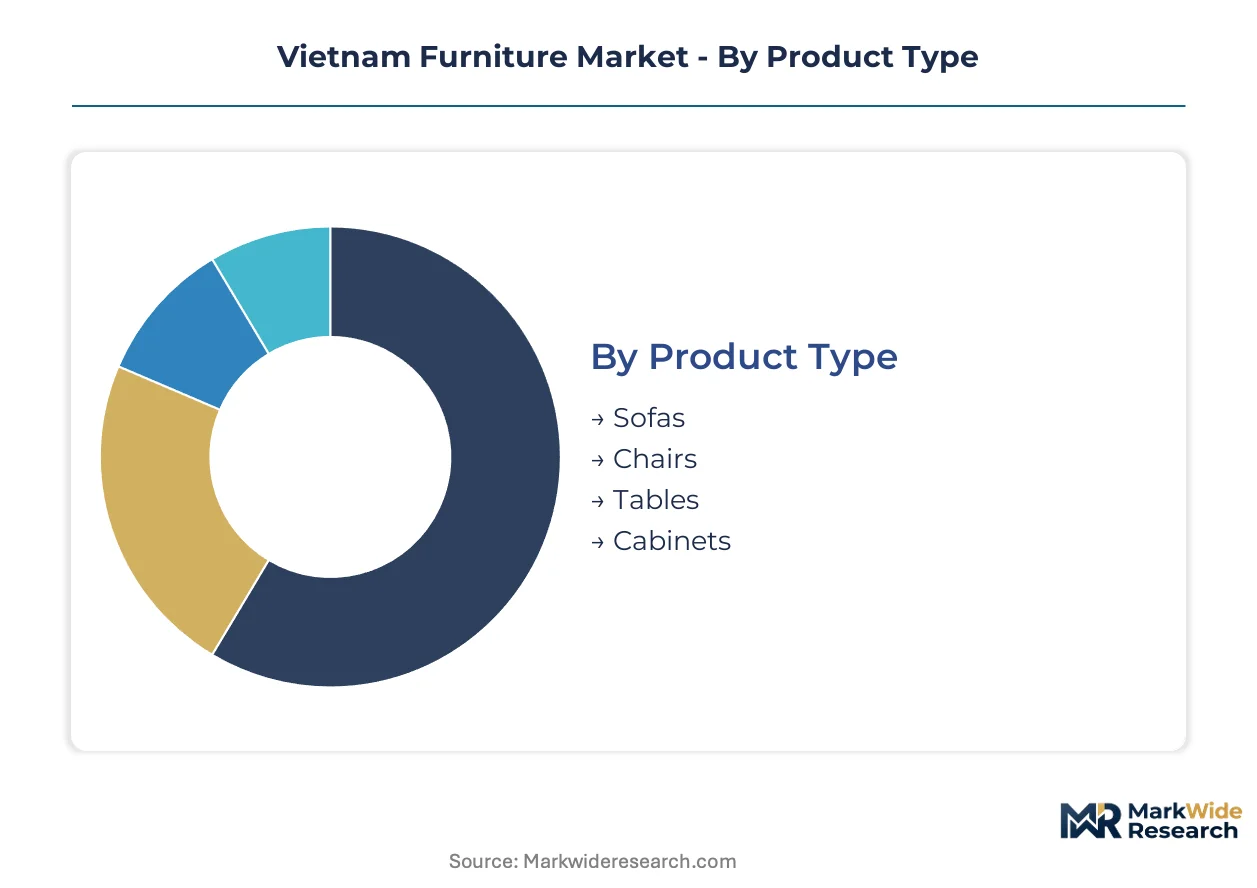
Vietnam's furniture sector demands granular segmentation due to divergent capital requirements across material processing and end-use specifications. Procurement patterns in hospitality and residential channels operate on fundamentally different margin and certification timelines.
Product Type:
Capital intensity varies sharply across assembly complexity and finishing labor requirements.
- Sofas:Multi-component construction integrating hardwood frames, suspension systems, and upholstery layers demands the highest upfront tooling investment. Demand concentrates in Ho Chi Minh City apartment developments and Da Nang resort fit-outs, where developers specify fire-retardant fabric grades.
- Chairs:CNC-machined joinery and automated sanding lines reduce per-unit labor content for standardized hospitality seating. Binh Duong factories deploy robotic cells to serve bulk orders from expanding co-working operators.
- Tables:Surface area scaling drives material cost sensitivity; plantation acacia dominates dining and conference specifications.
- Cabinets:Knock-down flat-pack formats minimize shipping cube but require precision hinge hardware sourcing.
Sofas absorb the bulk of installed capacity; chairs are expanding most quickly.
Material:
Feedstock access and regulatory traceability requirements segment operational risk profiles.
- Wood:Solid timber and engineered panels anchor export value, with VPA-FLEGT documentation mandatory for EU-bound shipments. Rubberwood and acacia plantations in the Central Highlands supply captive raw material to integrated manufacturers.
- Metal:Powder-coated steel and aluminum framing systems serve urban office and outdoor furniture verticals with shorter production cycles than timber curing.
- Plastic:Injection-molded polypropylene components target mass-market outdoor and children's furniture segments.
- Fabric:Upholstery textiles span solution-dyed acrylics for coastal humidity resistance to commercial-grade synthetics for hospitality durability standards.
Wood commands the dominant share of production asset deployment; metal is climbing the fastest on urban fit-out demand.
End User:
Specification authority and certification stringency differentiate procurement behavior.
- Residential:Individual buyers prioritize aesthetic variety and price accessibility through showroom and online channels.
- Commercial:Corporate procurement teams negotiate volume contracts with direct manufacturer engagement.
- Hospitality:Resort developers in Phu Quoc and Da Nang mandate FSC-certified materials and custom finishes as non-negotiable bid criteria.
- Office:Co-working operators in Ho Chi Minh City specify modular metal-framed systems for rapid space reconfiguration.
Residential channels sustain the widest factory output volumes; hospitality is gaining share fastest on coastal development pipelines.
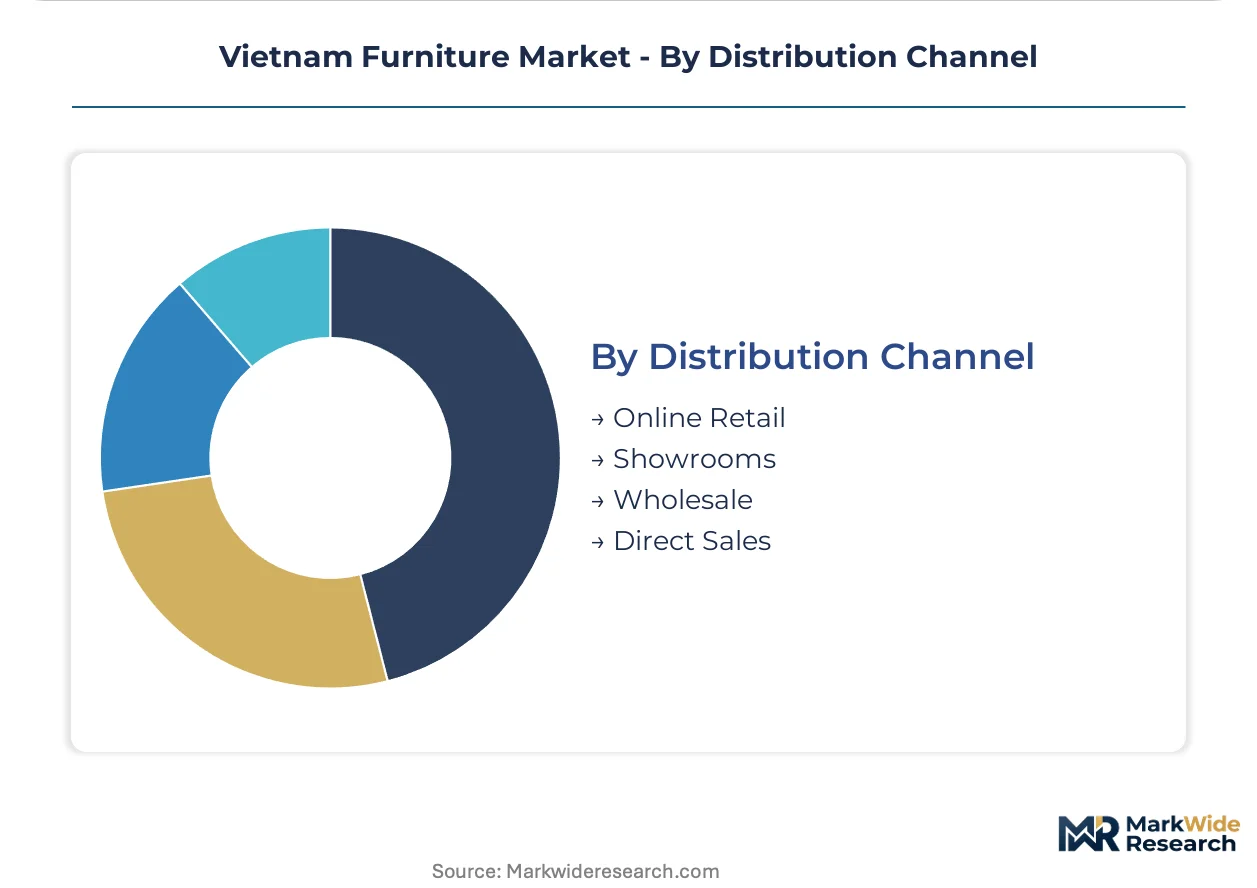
Distribution Channel:
Margin capture and customer relationship depth vary by intermediation level.
- Online Retail:Domestic millennial buyers drive platform growth, though logistics complexity limits bulky furniture penetration.
- Showrooms:Tactile specification remains critical for premium residential and hospitality project decisions.
- Wholesale:Export-oriented manufacturers maintain long-term relationships with Japanese and Australian importers.
- Direct Sales:Large hospitality developers bypass intermediaries to negotiate directly with Binh Duong integrated producers.
Wholesale channels handle the greatest shipment volumes; direct sales is expanding most quickly on hospitality project scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's furniture production concentrates in the southern industrial corridor while domestic consumption spreads across emerging urban centers. Export demand pulls manufacturing toward coastal provinces with port access. Regional development patterns reveal divergent specialization across five key sub-regions.
Southeast Region
Ho Chi Minh City and Binh Duong province anchor national output through integrated manufacturing clusters. The Ministry of Agriculture and Rural Development enforces VPA-FLEGT timber legality protocols across export facilities in this zone. Binh Duong's factory network processes plantation acacia into knock-down furniture for EU and Japanese buyers.
South Central Coast
Da Nang and Khanh Hoa provinces generate hospitality-driven demand from resort construction pipelines. Local authorities coordinate industrial zone permits with coastal environmental standards. Nha Trang's emerging furniture hub supplies Phu Quoc island developments with certified timber products.
Central Highlands
Gia Lai and Dak Lak provinces hold untapped plantation-to-factory integration potential. Provincial governments promote rubberwood processing investments through land-use incentives. Pleiku's underdeveloped industrial base offers captive timber supply for vertically integrated entrants.
Mekong Delta
Long An and Tien Giang provinces support secondary processing and logistics functions. The General Department of Vietnam Customs operates clearance facilities at Cat Lai port serving this zone. Can Tho's distribution network feeds domestic retail channels in southern provinces.
Northern Region
Hanoi and Hai Phong concentrate administrative functions and northern port access. Red River Delta provinces absorb limited furniture manufacturing due to land cost premiums. Hai Duong's industrial parks host import-dependent processors serving northeastern consumer markets.
Vietnam Furniture Market Competitive Environment
Top-tier vendors anchor integrated manufacturing, while mid-scale fabricators compete on specialized export niches. The market exhibits tiered concentration around plantation-backed producers and hospitality-focused specialists. Three archetypes dominate: vertically integrated timber processors, hospitality contract specialists, and export-oriented wholesale suppliers. Competitive moves center on FSC certification acquisition and direct developer relationships bypassing traditional distribution.
Among integrated Vietnamese producers, A.A. Corporation and Truong Thanh Furniture exemplify scale-driven manufacturing archetypes with plantation supply access. Evergreen Home Furnishings occupies a position within the hospitality-specialist tier. These three entities represent contrasting strategic positions: integrated manufacturing base, sustained export relationships, and resort-grade collection focus respectively.
| Leading Market Players |
|---|
| Vina Arya Furniture |
| Remacro |
| Primo Sourcing |
| Misamex Furniture |
| Evergreen Home Furnishings |
| A.A. Corporation |
| Hiệp Long |
| Canadian Wood |
| Truong Thanh Furniture |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-caps in Binh Duong and Ho Chi Minh City anchor production capacity, linking plantation feedstock control to pricing discipline through captive acacia supply and direct hospitality contract engagement.
Pricing Analysis
Margin tightening in standard-grade knock-down furniture reflects adhesive resin cost volatility and energy input movements. Three-tier pricing structure across FSC-certified premium, VPA-FLEGT-compliant standard, and uncertified economy levels separates hospitality developers from residential wholesalers. Cost-down pressure on economy-tier exporters accelerates because EU Deforestation Regulation documentation burdens fall disproportionately on small-scale operators lacking traceability systems. Hospitality procurement teams show least price sensitivity, accepting 15-40% premiums for certified materials and custom finishes.
Supply Chain Analysis
Skilled finishing technician scarcity concentrates in aging Binh Duong workforces, constraining quality-scaling for new factory investments. Vietnam's furniture supply chain draws from domestic rubberwood and acacia plantations in the Central Highlands, engineered wood panel imports from China and Malaysia, and hardware components from Taiwan and South Korea. Single-source vulnerability runs through the southern industrial corridor's flood-exposed logistics nodes during monsoon periods. Distribution runs through Cat Lai port clearance facilities serving wholesale export channels, with direct manufacturer engagement bypassing intermediaries for large hospitality developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where plantation-to-factory control determines certification velocity and margin capture against regulatory compliance timelines.
For Market Incumbents: Deploy FSC chain-of-custody certification investment to defend EU market access against emerging integrated entrants from Gia Lai and Dak Lak. Secure captive acacia supply through Central Highlands plantation leases before land-use incentives expire. Reinforce direct developer relationships in Phu Quoc and Da Nang to lock hospitality procurement channels against wholesale competitors. For New Entrants and Emerging Players: Capture co-working fit-out verticals in Ho Chi Minh City through metal-framed modular systems with shorter production cycles than timber curing. Target Central Highlands underpenetration for plantation-to-factory integration, leveraging provincial government land-use incentives. Build go-to-market through e-commerce platforms serving domestic millennial buyers with flat-pack formats optimized for urban apartment logistics. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale exporters lacking traceability systems in Binh Duong, where EU Deforestation Regulation compliance burdens force asset sales. Long-term viability centers on 5-10 year plantation concession security and hospitality direct-contract pipelines. Watch FSC audit completion rates as inflection indicator for EU market re-entry capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Plantation-to-Factory Integration | Captive acacia supply from Gia Lai plantations secures VPA-FLEGT documentation for EU-bound exports. |
| FSC Certification Acquisition | Chain-of-custody audits enable hospitality bid participation where certified materials are mandatory criteria. |
| Direct Developer Engagement | Bypassing wholesale intermediaries captures margin pools in Phu Quoc and Da Nang resort construction pipelines. |
| Co-Working Vertical Specialization | Metal-framed modular systems address Ho Chi Minh City office reconfiguration demand faster than traditional wood furniture. |
| E-Commerce Channel Buildout | Platform direct sales access domestic millennial buyers without showroom infrastructure investment. |
Study Parameters
Document review covered Vietnam Customs export documentation, Ministry of Agriculture and Rural Development VPA-FLEGT implementation reports, and EU Deforestation Regulation guidance, complemented by interviews with factory operations directors, hospitality procurement managers, plantation concession holders, and Binh Duong industrial zone authorities. Secondary validation drew from customs trade data, FSC certification registry updates, and provincial investment promotion materials. Bottom-up capacity assessments triangulated with top-down export value reconstructions.
Segment-level demand projections across product type, material grade, end-user vertical, and distribution channel fed into analytical framework outputs across the projection horizon. CAGRs derived from regression against plantation expansion rates, coastal development permit issuances, and certification audit completion trajectories. Model inputs incorporated hospitality pipeline tracking in Da Nang and Phu Quoc, co-working space absorption in Ho Chi Minh City, and EU market access timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU regulatory enforcement intensity and Central Highlands infrastructure buildout pace. Projections reflect assumptions around VPA-FLEGT alignment maintenance and plantation concession renewal terms. Material deviation in EU deforestation documentation requirements or monsoon logistics disruption frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Europe Sustainable Home Furniture Market
Furniture
Study Carrels Market
Furniture
Chair Hardware Market
Furniture
Armchairs with Footrest Market
Furniture
Contract Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
United Arab Emirates Furniture Market
Furniture
Italy Office Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
India Home Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
School Furniture Market
Furniture
China Home Furniture Market
Furniture
Portering Chair Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Canada Home Furniture Market