
 Betaine Market | 2026-2036
Betaine Market Size, Share, and Industry Trends Forecast 2026-2036
Betaine Market Intelligence
The increasing pressure to reduce synthetic methionine in animal feed formulations is shifting demand toward natural alternatives like betaine. In this context, BASF SE specializes in high-purity grades suitable for sensitive applications in personal care and pharmaceuticals. Associated British Foods plc leverages its extensive agricultural supply chain for raw material access, ensuring cost competitiveness. Meanwhile, Sunwin Biotech Shandong Co., Ltd. dominates production in China, serving the vast domestic animal nutrition market.
Betaine is a modified amino acid, specifically trimethylglycine, derived primarily from sugar beet molasses. Its primary biological function is as a methyl donor and an osmoprotectant, helping cells maintain water balance under stress. While the animal nutrition application constitutes the largest volume segment, personal care formulations provide higher margin opportunities for specialized grades like betaine anhydrous. The powder form remains the most common for its stability and ease of handling in feed and cosmetic manufacturing.
Regulatory frameworks like the U.S. FDA's GRAS notifications and the European Food Safety Authority's (EFSA) opinions govern its use in food and feed. In China, GB standards dictate purity requirements for both domestic production and imports. Navigating these disparate regional compliance requirements is critical for market participants. The key decision for suppliers revolves around balancing investment in commodity-grade capacity versus developing high-purity specialty products.
Market Dynamics
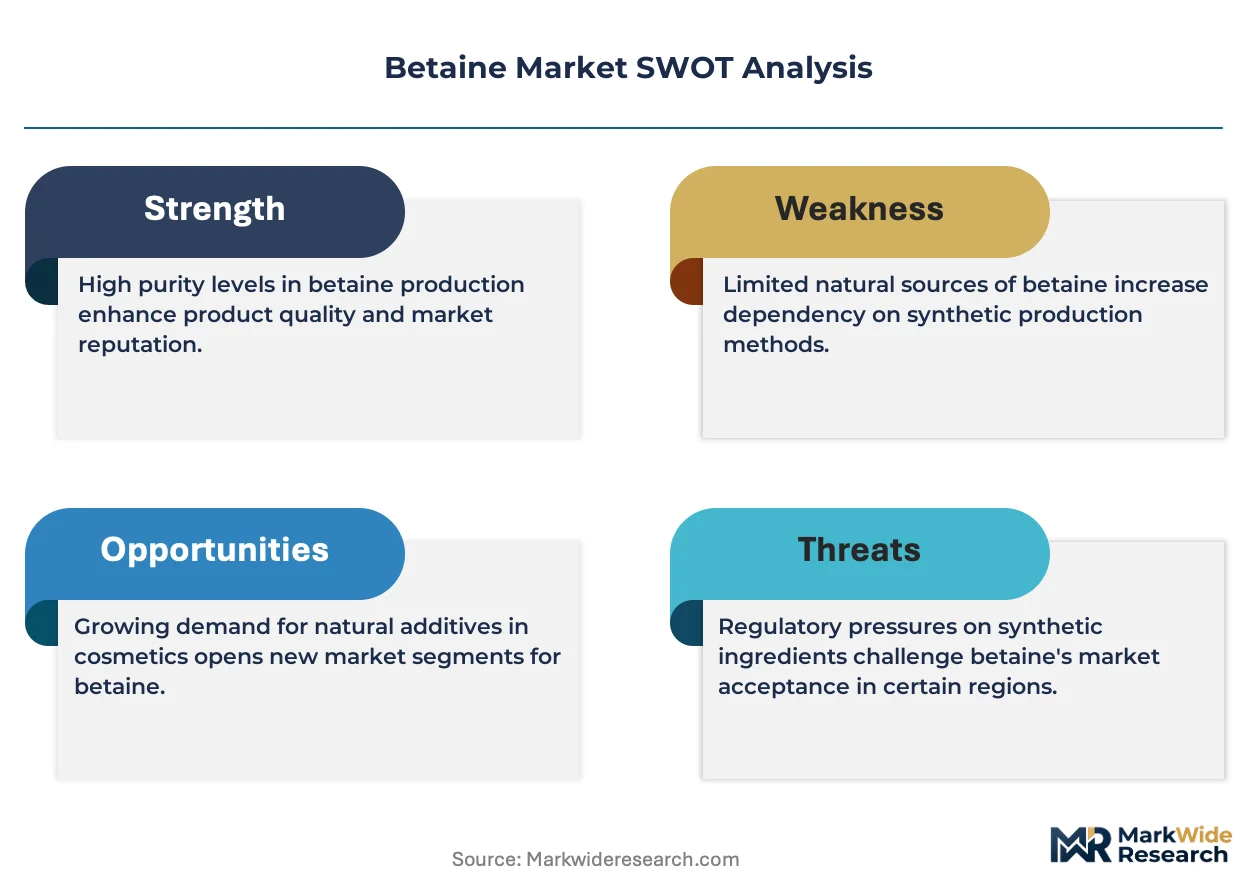
The central structural force is the sustained pressure from regulators and consumers to reduce synthetic additives in animal nutrition. This movement, particularly against synthetic methionine, creates a significant demand vacuum that natural, functional ingredients like betaine are uniquely positioned to fill.
Growth Catalysts
- Sustainable Agriculture Policy:The EU Green Deal and similar initiatives promote feed efficiency and the use of natural additives, directly stimulating demand for betaine as a methyl donor in poultry and swine diets to improve nutrient absorption.
- Aquaculture Intensification:China's large-scale aquaculture industry seeks performance-enhancing ingredients to manage osmotic stress in fish and shrimp, driving significant volume demand for betaine as an effective osmoprotectant.
- Functional Superiority:Betaine's dual function as both a methyl donor and an osmolyte provides a distinct advantage over single-function additives, encouraging its inclusion in feed formulations for animals under heat or metabolic stress.
Market Restraints
- Raw Material Volatility:Betaine production is heavily dependent on sugar beet molasses, making its cost structure vulnerable to fluctuations in sugar beet crop yields, agricultural policies, and global sugar prices.
- Substitution from Synthetics:Synthetic methionine remains a lower-cost and widely accepted alternative, presenting a significant price-based substitution threat, especially in cost-sensitive livestock production systems outside of heavily regulated markets.
- Geographic Supply Concentration:A high concentration of commodity-grade betaine production within China creates potential supply chain risks for global buyers, including geopolitical tensions, logistical disruptions, and regional regulatory changes.
Strategic Opportunities
- High-Purity Personal Care Grades:Formulating specialized, high-purity betaine anhydrous for cosmetic and personal care products as a humectant and anti-irritant offers significantly higher profit margins compared to the commodity feed-grade market.
- Food and Beverage Fortification:Leveraging the U.S. FDA's GRAS (Generally Recognized as Safe) notifications allows for the expansion of betaine into functional foods and sports nutrition beverages as an osmolyte to aid hydration.
- Latin American Livestock Expansion:The growing poultry and aquaculture sectors in countries like Brazil and Mexico represent an underpenetrated market for betaine, where it can improve feed efficiency and performance in hot climates.
Industry Challenges
- Navigating Disparate Regulations:Manufacturers face the complex and costly challenge of ensuring product compliance across multiple regulatory frameworks, including EFSA opinions in Europe, FDA notifications in the US, and GB standards in China.
- High-Purity Production Investment:The significant capital expenditure required to establish and certify production facilities for pharmaceutical or cosmetic-grade betaine presents a high barrier to entry for smaller or commodity-focused players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betaine Market |
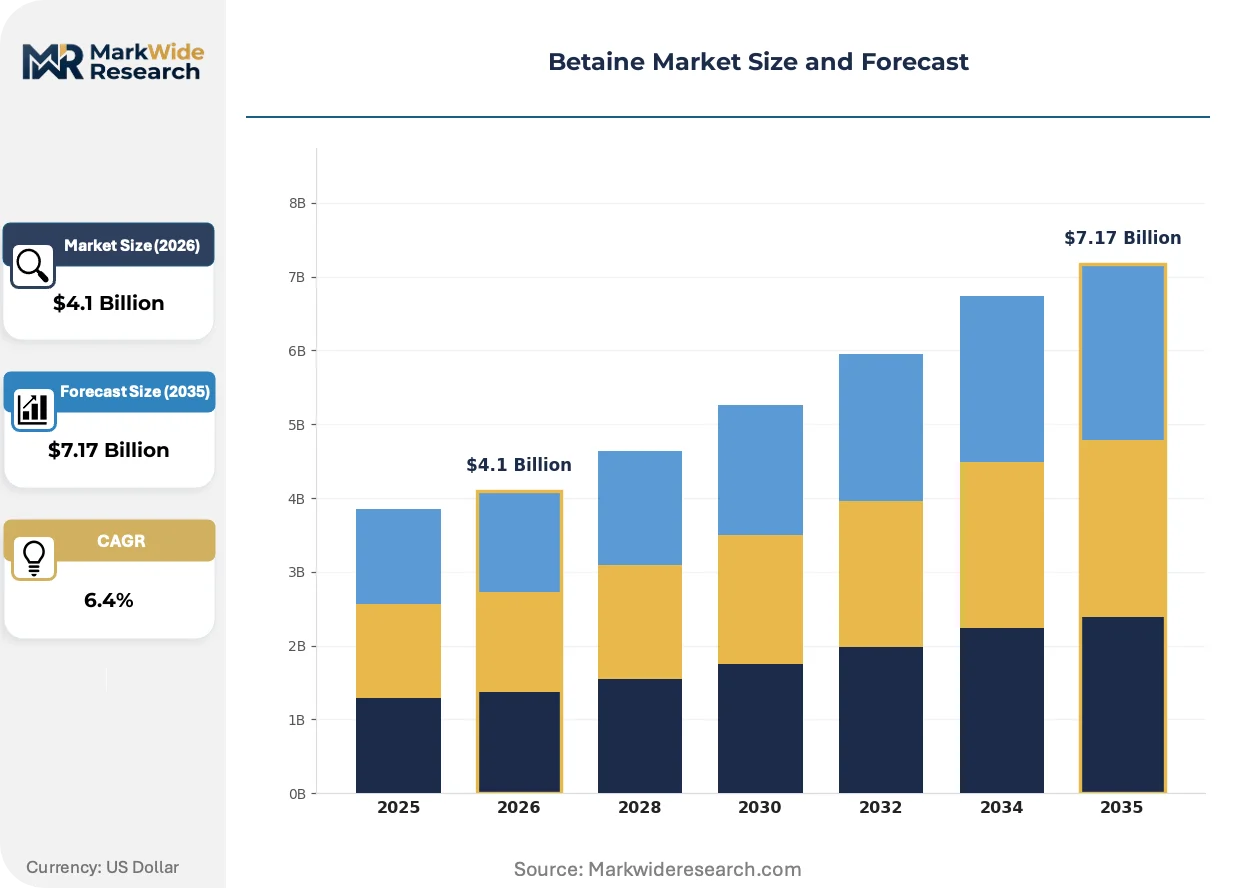
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trimethylglycine, Betaine Anhydrous, Betaine Hydrochloride, Derived Betaine, Hydrogenated Betaine Salt Application: Animal Nutrition, Personal Care, Pharmaceutical Formulations, Food & Beverage Additives, Agricultural Chemicals End User Industry: Feed Manufacturers, Cosmetic Producers, Pharmaceutical Companies, Food Processing Units, Agrochemical Firms Form: Powder, Liquid Concentrate, Granules, Crystalline, Flakes |
| Companies Covered | Associated British Foods plc, Sunwin Biotech Shandong Co., Ltd., BASF SE, Stepan Company, Solvay, Evonik Industries AG, Kao Corporation, AMINO GmbH, Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betaine Market Strategic Shifts & Innovations
The market's evolution is defined by a divergence between high-volume, performance-driven applications in animal feed and the pursuit of high-value, functional benefits in specialized sectors like personal care. This split is driving innovation in both production technology and application development.
Advanced purification technologies, such as multi-stage crystallization and chromatography, are enabling the production of betaine anhydrous with exceptional purity. Pharmaceutical and cosmetic formulators are the primary adopters, demanding consistency and minimal impurities for use in sensitive skin and oral care products. This technology is automating quality assurance processes, ensuring batch-to-batch uniformity that was previously difficult to achieve at scale.
China's MEE (Ministry of Ecology and Environment) enforcement of stricter industrial effluent standards is impacting production. This forces betaine manufacturers, particularly those using molasses-based fermentation, to invest in advanced wastewater treatment systems. The animal nutrition sector is most affected, as these added operational costs are passed through, narrowing the price gap with synthetic alternatives.
A notable shift in purchasing criteria is evident among large-scale integrators in the poultry industry. Buyers are moving beyond simple cost-per-kilogram metrics to evaluate betaine based on its proven impact on feed conversion ratios and reduced mortality rates under stress conditions. This disrupts traditional commodity-based sales and favors suppliers offering documented performance data. This behavior is most prominent in North America and Europe.
Betaine Market Segmentation
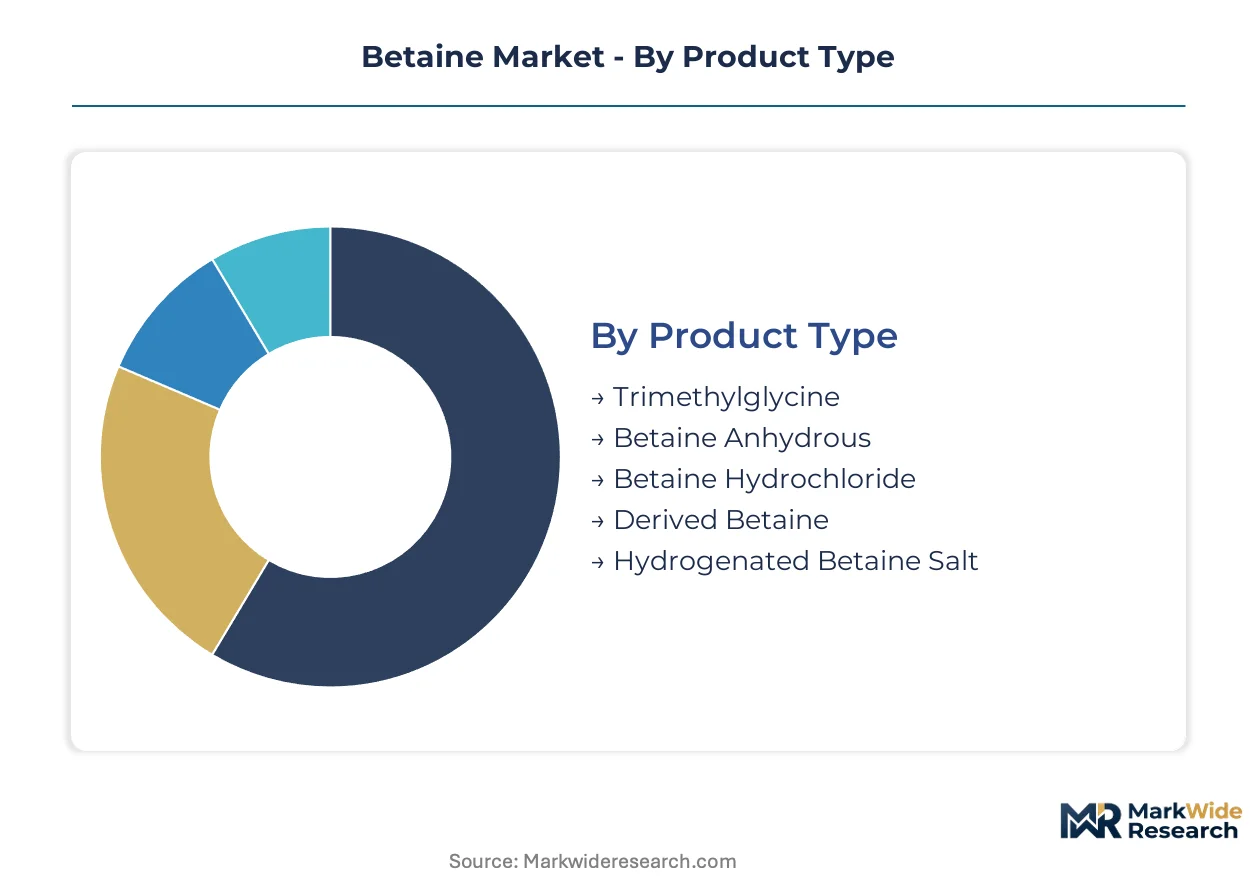
The Betaine market's segmentation highlights the diverse applications and product forms driving its expansion across various industries. Understanding these distinct segments is crucial for identifying targeted growth strategies and navigating specific market dynamics.
Product Type:
The production of specific betaine product types often concentrates in regions with abundant raw material supply, influencing global availability and pricing structures.
- Trimethylglycine:This foundational betaine molecule functions as a methyl donor and osmoprotectant, widely used in animal nutrition. Demand for trimethylglycine concentrates heavily within China's animal nutrition sector, driven by large-scale livestock and aquaculture industries seeking feed efficiency.
- Betaine Anhydrous:This highly purified, water-free form of betaine serves as a humectant and anti-irritant in sensitive formulations. Demand for betaine anhydrous is concentrating in Europe and North America for high-margin personal care and pharmaceutical applications due to stringent quality requirements.
- Betaine Hydrochloride:This acid salt form of betaine is primarily utilized as a feed additive to support digestive health in livestock.
- Derived Betaine:These chemically modified betaine derivatives are engineered for specialized industrial applications requiring specific functional properties.
- Hydrogenated Betaine Salt:This specialized betaine variant finds application in niche chemical and industrial processes due to its unique characteristics.
Today's leader: Trimethylglycine. Tomorrow's challenger: Betaine Anhydrous.
Application:
The diverse applications of betaine underscore its functional versatility across multiple industrial sectors, each with distinct performance requirements.
- Animal Nutrition:This segment utilizes betaine as a methyl donor and osmoprotectant in feed, primarily for poultry, swine, and aquaculture. Demand is concentrating in China and Brazil, driven by the need for improved feed conversion ratios and stress mitigation in intensive farming.
- Personal Care:Betaine functions as a humectant, moisturizer, and anti-irritant in cosmetics, skincare, and hair care products. European and North American markets show high demand for betaine in premium personal care formulations, due to consumer preference for natural ingredients.
- Pharmaceutical Formulations:Betaine is incorporated into medications for its metabolic and osmoprotective properties, supporting various therapeutic applications.
- Food & Beverage Additives:This application uses betaine as a functional ingredient in sports nutrition and health supplements to aid hydration and performance.
- Agricultural Chemicals:Betaine acts as a plant growth regulator and stress protectant in certain agricultural formulations to enhance crop resilience.
Animal Nutrition represents the largest volume segment, while Personal Care is expanding most quickly.
End User Industry:
Specific end-user industries drive distinct demand profiles for betaine, influencing product specifications and distribution channels significantly.
- Feed Manufacturers:These companies integrate betaine into animal feed to enhance nutrient absorption and reduce the need for synthetic methionine. Demand from feed manufacturers concentrates in Southeast Asia and Latin America, driven by expanding livestock and aquaculture operations.
- Cosmetic Producers:Formulators in this industry utilize betaine for its hydrating and skin-conditioning benefits in various personal care products. European and Japanese cosmetic producers exhibit strong demand for high-purity betaine, aligning with clean label trends.
- Pharmaceutical Companies:These firms incorporate betaine as an active ingredient or excipient in therapeutic drugs, adhering to stringent regulatory standards.
- Food Processing Units:Betaine is added to functional foods and beverages by these units for its osmoprotective qualities and nutritional benefits.
- Agrochemical Firms:These companies use betaine in formulations designed to improve crop resilience and yield under environmental stress conditions.
Feed Manufacturers remain the primary volume leader, with Cosmetic Producers showing significant growth in value.
Form:
The physical form of betaine often dictates its ease of handling, storage, and integration into diverse manufacturing processes, reflecting market maturity and application needs.
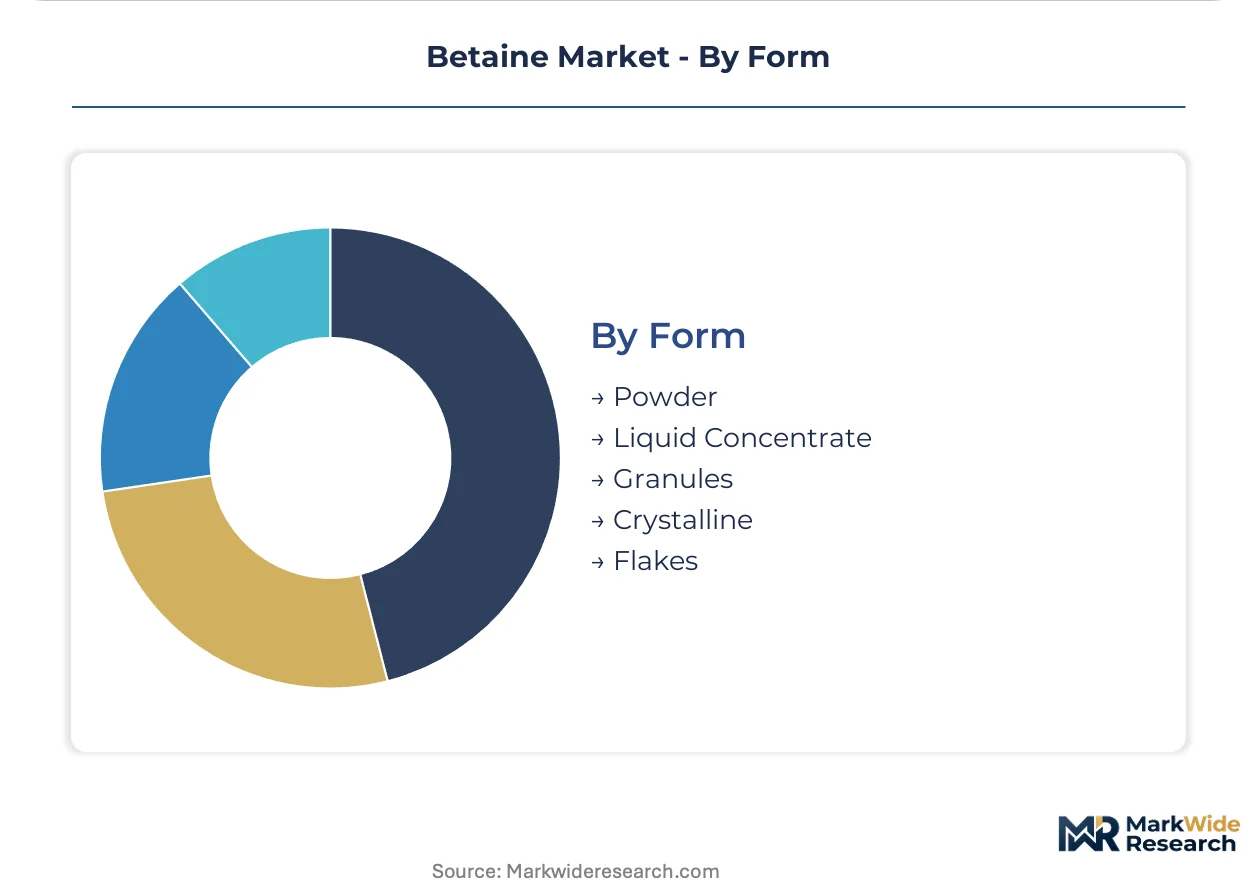
- Powder:This solid form offers stability and ease of handling, making it the most common form for animal feed and cosmetic manufacturing. Global demand for powder betaine remains high, particularly across Asian markets for its cost-effectiveness in large-scale applications.
- Liquid Concentrate:This aqueous solution provides convenience for precise dosing and homogeneous mixing in liquid formulations or spray applications. European pharmaceutical and personal care sectors increasingly demand liquid betaine concentrates for streamlined production processes.
- Granules:Granular betaine offers improved flowability and reduced dust during handling, making it suitable for specific industrial applications.
- Crystalline:This highly pure form is favored for specialized pharmaceutical and research applications due to its precise composition.
- Flakes:Flake betaine provides an alternative physical form with specific dissolution characteristics for certain industrial uses.
Powder remains the dominant form for bulk applications, while Liquid Concentrate gains traction for specialized uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The betaine industry historically scaled in Europe, leveraging abundant sugar beet molasses from the continent's established agricultural sector. This early foundation provided raw material access for initial industrial applications. Today, diverse regional dynamics shape betaine demand and production capabilities across the globe.
China
China's vast animal nutrition sector drives immense demand for betaine as a feed additive for livestock and aquaculture. GB standards dictate purity requirements for both domestic production and imports of betaine. Shandong province, home to major producers like Sunwin Biotech Shandong Co., Ltd., concentrates significant betaine manufacturing capacity.
United States
The United States market sees betaine demand from functional food and sports nutrition applications, leveraging its osmolyte properties. U.S. FDA's GRAS notifications facilitate betaine's integration into food and beverage products. California's robust health and wellness industry fosters innovation in betaine-fortified functional beverages.
Germany
Germany's chemical and pharmaceutical industries demand high-purity betaine grades for sensitive personal care and therapeutic uses. EFSA opinions and the EU Green Deal promote natural additives, influencing feed formulations across Europe. The Rhine-Main region, a hub for chemical giants like BASF SE, specializes in advanced betaine purification.
Brazil
Brazil's expanding poultry and aquaculture sectors represent a significant growth area for betaine, improving feed efficiency. ANVISA regulations govern the use of feed additives, ensuring product safety and efficacy for livestock. São Paulo state, a central hub for agricultural processing, sees increasing adoption of betaine in animal feed formulations.
Japan
Japanese cosmetic producers exhibit strong demand for high-purity betaine, aligning with clean label trends. PMDA ensures stringent quality for pharmaceutical applications, while JIS standards guide industrial betaine production. The Kanto region, home to major cosmetic and food manufacturers, drives innovation in betaine-based formulations.
Betaine Market Key Industry Players
Capital-heavy producers compete with asset-light designers, shaping the betaine market's competitive dynamics. The market exhibits a tiered structure, with large chemical conglomerates alongside specialized biotech firms and regional players. Strategic archetypes include integrated chemical producers, specialized ingredient suppliers, and regional commodity manufacturers. Geographic expansion, portfolio diversification, and strategic partnerships represent dominant competitive moves among market participants.
Germany-based BASF SE exemplifies the integrated chemical producer archetype, focusing on high-purity betaine grades suitable for sensitive personal care and pharmaceutical applications. Associated British Foods plc, a UK-headquartered conglomerate, leverages its extensive agricultural supply chain to ensure cost-competitive raw material access for its betaine operations. Sunwin Biotech Shandong Co., Ltd., a Chinese company, occupies a position as a leading regional manufacturer, anchoring the vast domestic animal nutrition market with its commodity-grade production. These players collectively represent the diverse strategic approaches within the global betaine landscape.
| Leading Market Players |
|---|
| Associated British Foods plc |
| Sunwin Biotech Shandong Co., Ltd. |
| BASF SE |
| Stepan Company |
| Solvay |
| Evonik Industries AG |
| Kao Corporation |
| AMINO GmbH |
| Nutreco |
| Others |
Cost & Logistics Intelligence
Vertical integration into sugar beet processing anchors Associated British Foods plc's supply position, enabling cost-competitive betaine production and influencing global pricing power. This integration strategy provides stability against raw material volatility.
Pricing Analysis
Contract-based long-term offtake agreements dominate for commodity-grade betaine in animal nutrition, while premium-mid-economy pricing differentiation applies to specialized grades. Price differentiation stems from purity levels, regulatory certifications like U.S. FDA GRAS, and volume commitments. Pricing pressure stems from increased operational costs due to stricter environmental regulations in China, narrowing the gap with synthetic alternatives. Animal nutrition buyers exhibit high price sensitivity, contrasting with lower sensitivity in pharmaceutical and personal care sectors.
Supply Chain Analysis
Direct-to-manufacturer channels serve large-scale integrators and cosmetic producers, ensuring specialized delivery for high-volume and high-purity betaine. Geographic supply concentration centers in China for commodity grades and Europe for specialized production. The betaine supply chain heavily relies on sugar beet molasses, making it vulnerable to commodity price volatility from agricultural policies and crop yields. This concentration creates potential supply chain risks for global buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Betaine market acts as a stable compounder, driven by sustained demand from the animal nutrition sector for feed efficiency. This foundational demand provides consistent growth across the forecast period.
For Market Incumbents:Anchor existing market share by investing in advanced purification technologies for betaine anhydrous, securing high-margin opportunities in personal care and pharmaceuticals. Incumbents should also pursue backward integration into sugar beet processing to mitigate raw material volatility and counter price-based substitution from synthetic methionine. Investing in U.S. FDA GRAS notifications and European EFSA opinions strengthens market position for sensitive applications.
For New Entrants and Emerging Players:Begin with targeted entry into underpenetrated Latin American livestock markets, specifically Brazil and Mexico, focusing on betaine's osmoprotectant benefits in hot climates. A go-to-market angle emphasizing documented performance data, such as improved feed conversion ratios and reduced mortality rates, will differentiate offerings. This strategy bypasses the capital-intensive high-purity production for initial market penetration.
For Investors and Strategic Acquirers:Roll-up economics work for specialized ingredient suppliers because of the market's clear value divergence between commodity and high-purity betaine. Long-term viability is strong, driven by betaine's dual functional superiority and regulatory support for natural additives. Investors should target regional commodity manufacturers with robust raw material access or those with advanced purification IP. The signal to watch is the impact of China's MEE enforcement on commodity production costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China and Europe | Addresses growing demand in animal nutrition and secures market share. |
| Advanced Purification Technology Investment | Unlocks higher-margin personal care and pharmaceutical applications for BASF SE. |
| Long-term Raw Material Supply Agreements | Mitigates volatility from sugar beet molasses price fluctuations for Associated British Foods plc. |
| Regulatory Certification Pursuit (U.S. FDA GRAS) | Facilitates market entry into functional food and beverage sectors in the United States. |
| Application-Specific R&D for Osmoprotection | Enhances betaine's value proposition in aquaculture and stress-prone livestock in Brazil. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. The analysis included discussions with feed formulation specialists, cosmetic R&D chemists, and agricultural policy analysts. Secondary data sources comprised EFSA opinions, U.S. FDA GRAS notifications, and customs trade data, supporting both bottom-up and top-down triangulation for comprehensive market sizing.
Comparable historical periods anchored the forecast window, establishing baseline growth trajectories for betaine. The analytical framework modeled dimensions including product type, application, end-user industry, and form, alongside regional regulatory patterns. Compound annual growth rates were derived from these segmented projections. Key industry-specific forecast inputs included sugar beet molasses supply trends and synthetic methionine pricing dynamics.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts impacting trade routes or rapid agricultural policy changes affecting raw material supply. Forecasts reflect current market dynamics and regulatory landscapes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fluorene Market
Chemicals
Deicing Fluid Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Methanol Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Maleic Acid Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Hexamine Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Periodic Acid Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Flatting Agents Market
Chemicals
Phenothiazine Market
Chemicals
Xanthates Market
Chemicals
Quaternium-15 Market
Chemicals
Dicaprylyl Carbonate Market