
 Methanol Market | 2026-2036
Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Methanol Market Analysis
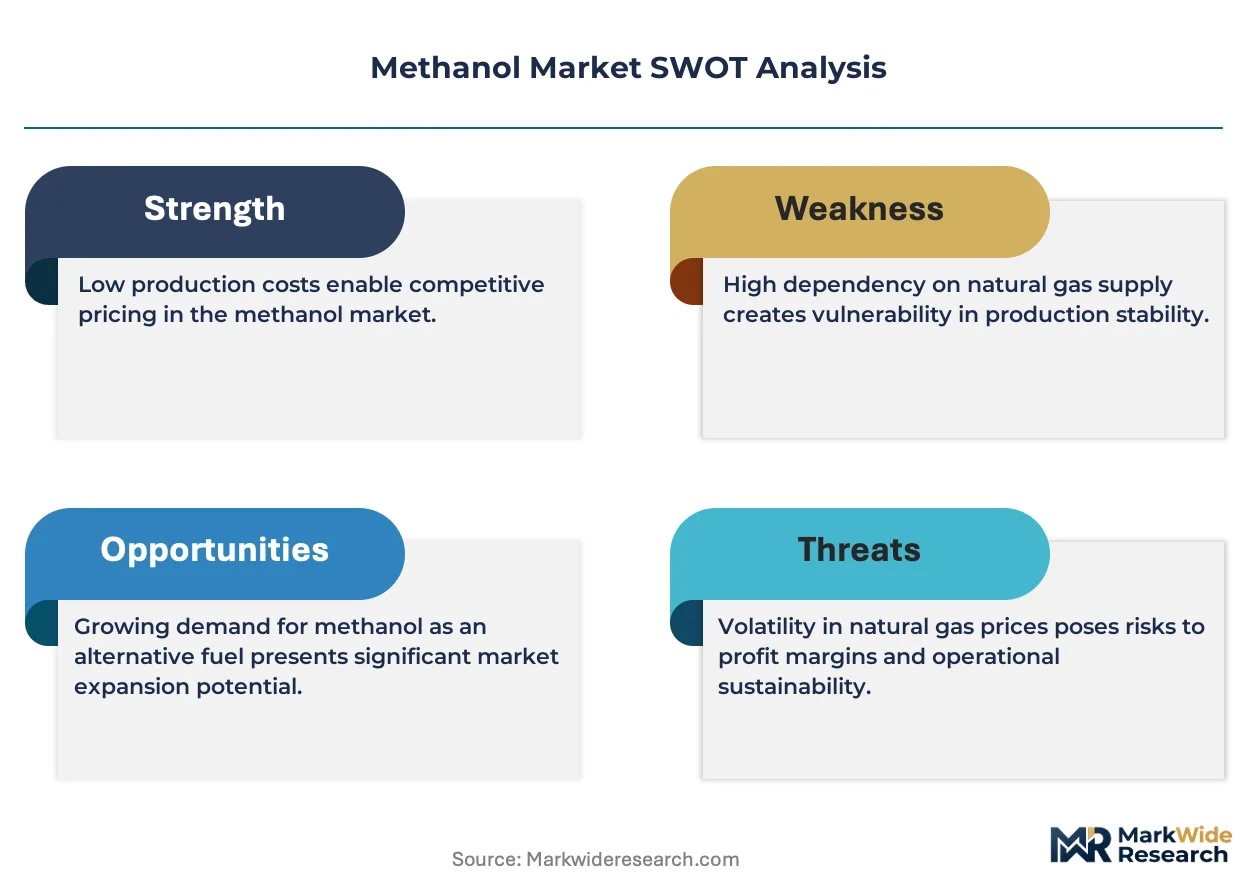
Buyer concentration in chemical manufacturing is broadening as large processors consolidate long-term offtake agreements while specialty solvent users fragment across smaller regional distributors. Methanex Corporation leverages its global marine logistics network to sustain supply continuity across multiple continents. SABIC anchors methanol output within its integrated petrochemical complex in Jubail, achieving feedstock-to-derivative cost efficiencies. BASF SE differentiates through R&D intensity in high-purity reagent grades for European pharmaceutical and electronics customers.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily through steam methane reforming of natural gas or coal gasification, with a boiling point of 64.7°C and energy density of 15.6 MJ/L; it serves as a fundamental chemical building block for formaldehyde, acetic acid, and methyl tert-butyl ether synthesis, while emerging as a marine fuel and hydrogen carrier. Industrial grade methanol dominates volume flows into formaldehyde and acetic acid plants, though margin pools are shifting toward bio-methanol as EU FuelEU Maritime regulations and IMO decarbonization targets create certified-low-carbon fuel premiums. Fuel grade applications represent the fastest-expanding demand segment, driven by methanol-to-gasoline processes and dual-fuel vessel engines, while reagent grade maintains stable pricing power in analytical laboratories and semiconductor fabrication.
EPA standards under the Clean Air Act limit methanol emissions from production facilities, while the EU F-Gas Regulation and REACH framework govern chemical handling and carbon intensity reporting for imported methanol derivatives. China's MEE enforces coal-to-chemical emissions caps that favor natural gas-based and biomass-sourced methanol capacity expansions. Stakeholders must monitor evolving carbon border adjustment mechanisms and low-carbon fuel certification schemes to secure market access and premium pricing in regulated jurisdictions.
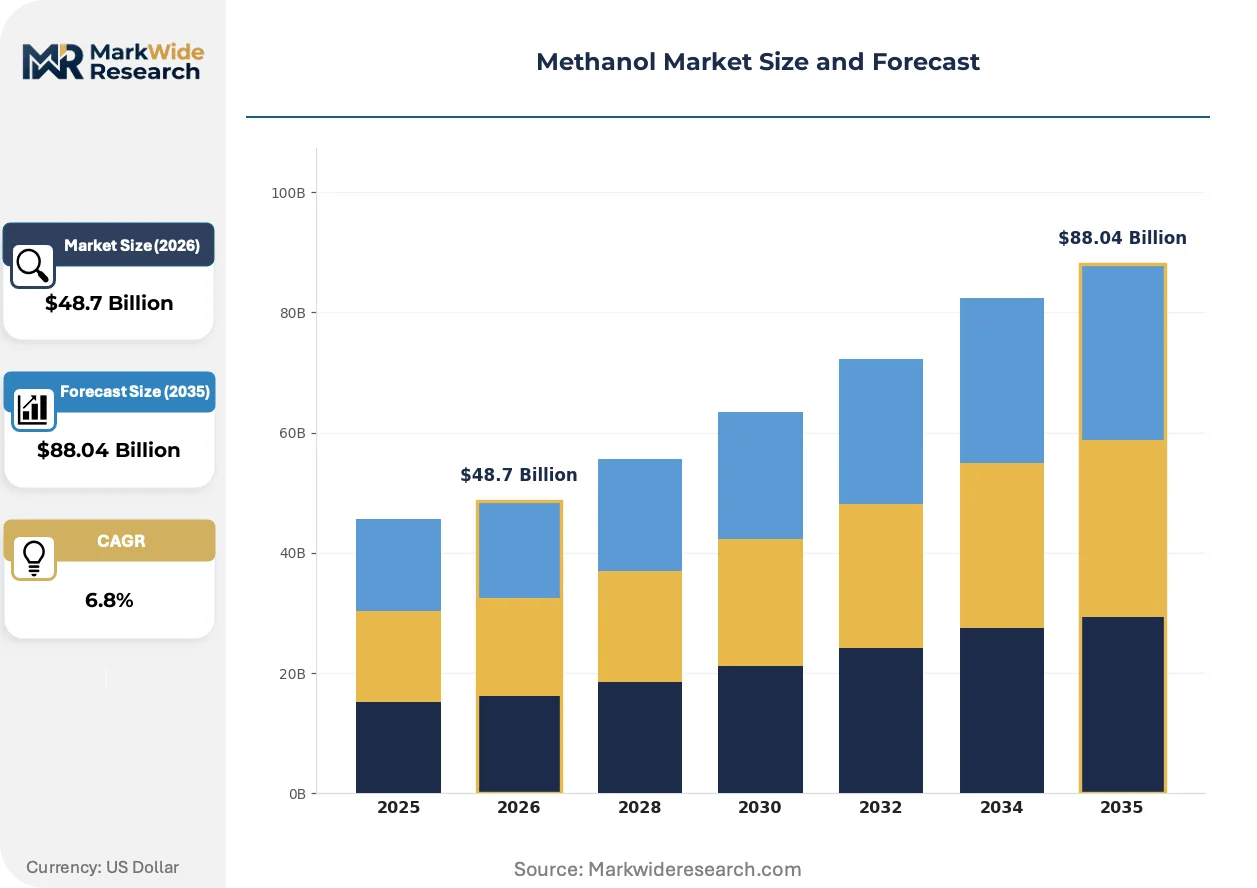
Market Dynamics
Chemical manufacturing buyers are consolidating procurement contracts for methanol feedstock, redirecting capacity toward low-carbon production pathways as China's dual carbon goals and MEE emissions rules reshape supplier economics.
Growth Catalysts
- FuelEU Maritime regulations:EU shipping decarbonization mandates are creating certified-low-carbon fuel premiums that pull bio-methanol capacity expansions into marine fuel certification schemes.
- Ningbo and Nanjing chemical clusters:East China demand concentration is concentrating methanol offtake around integrated formaldehyde and acetic acid plants with captive consumption.
- Dual-fuel vessel engines:Marine engine technology is accelerating methanol adoption in deep-sea shipping routes where bunkering infrastructure investments are co-locating with port industrial zones.
Market Restraints
- Natural gas price volatility:Steam methane reforming feedstock costs swing with LNG spot markets, compressing margins for merchant methanol producers without long-term gas supply contracts.
- Coal gasification capacity concentration:China's MEE emissions caps are idling high-carbon production assets in Shanxi and Inner Mongolia, tightening regional supply during policy transition periods.
- Green hydrogen cost floor:Bio-methanol and e-methanol pathways face persistent cost disadvantages against fossil-derived production, limiting certified fuel scale without subsidy bridges.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM phase-in is creating compliance-driven demand for lifecycle-certified methanol in formaldehyde and acetic acid derivative exports.
- Methanol-to-gasoline processes:Emerging market fuel blending regulations are opening stationary applications where methanol substitutes for gasoline in internal combustion adaptations.
- Integrated carbon capture:Blue methanol production combining SMR with CCUS is attracting project finance in jurisdictions with 45Q-style production tax credits.
Industry Challenges
- Low-carbon fuel certification timelines:ISCC and RSB verification processes for bio-methanol extend 12-18 months, delaying offtake contract execution against regulatory deadlines.
- Marine bunkering infrastructure capex:Port storage and fueling systems for methanol require capital deployment ahead of vessel fleet conversion, creating coordination risk between fuel suppliers and ship operators.
- Process safety expertise gaps:Methanol's toxicity and flammability profile demands specialized handling protocols that exceed standard petrochemical training in emerging market terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methanol Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Bio-Methanol, Fuel Grade End Use Industry: Automotive, Chemical Manufacturing, Energy, Electronics Application: Fuel, Solvent, Antifreeze, Feedstock Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | Methanex Corporation, SABIC, Celanese Corporation, BASF SE, Mitsubishi Gas Chemical Company, OCI N.V., Petronas, Yankuang Energy Group, Zagros Petrochemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methanol Market Emerging Trajectories
Production technology maturation and regulatory carbon accounting are converging to restructure how methanol is sourced, certified, and consumed across chemical and fuel applications.
Electrolytic hydrogen integration with carbon capture is consolidating e-methanol production economics. Nordic project developers are piloting 100 MW-scale facilities combining offshore wind with direct air capture. This pathway is consolidating first-mover advantage in European marine fuel contracting.
China's MEE emissions enforcement is tightening coal-to-chemical emissions caps. Natural gas-based and biomass-sourced capacity expansions are capturing permitting priority in Jiangsu and Zhejiang provinces. Chemical manufacturing clusters in these provinces are securing pipeline-connected supply against import price volatility.
Long-term offtake contracting is displacing spot market purchasing among formaldehyde and acetic acid producers. Large processors are locking five-year supply agreements with fixed-price escalators. This pattern concentrates procurement power with integrated petrochemical complexes in Jubail and Rotterdam.
Methanol Market Segmentation
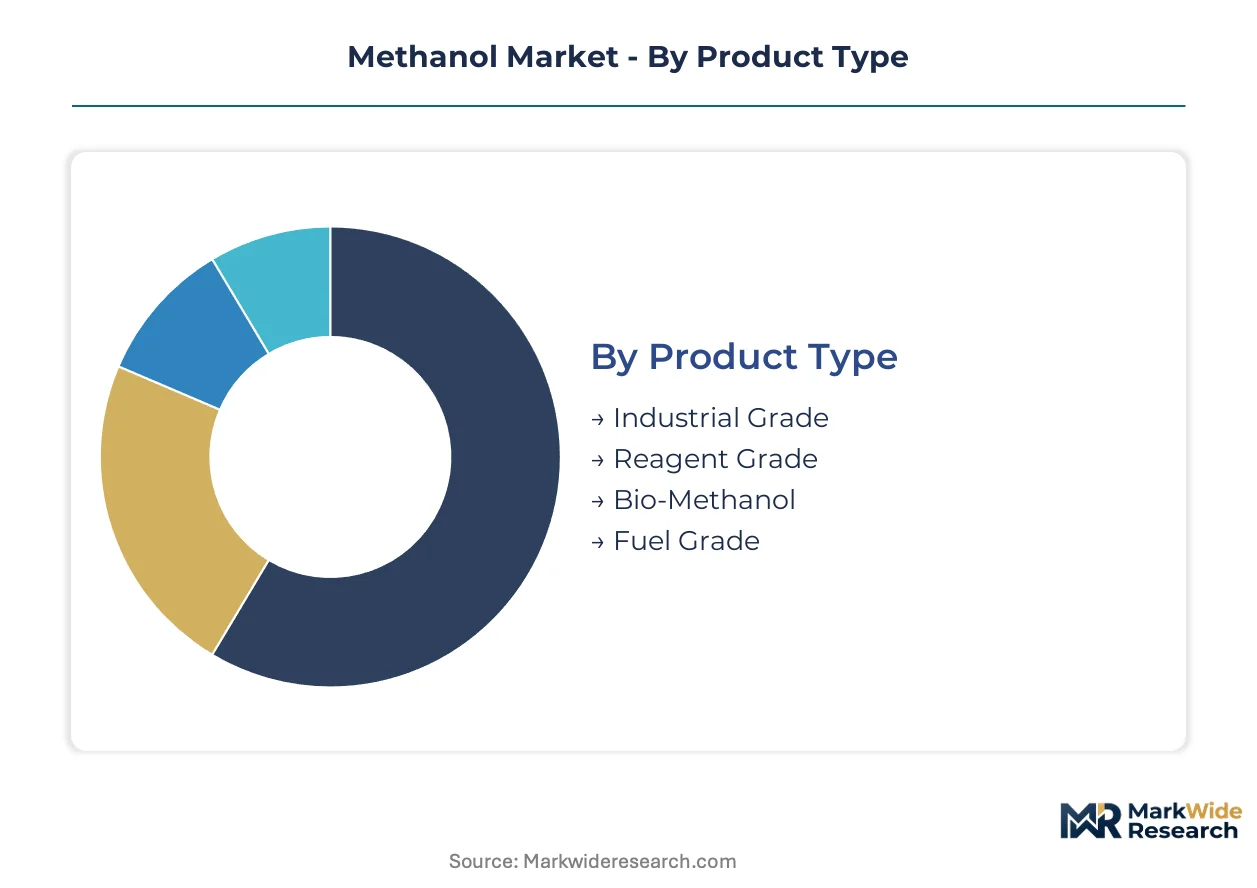
Methanol's diverse purity specifications and emerging fuel applications create distinct margin pools that reward precise segment targeting. Producers must align certification investments with the regulatory intensity of each end-use pathway.
Product Type:
Customization intensity spans from bulk commodity grades to certified-low-carbon fuels with traceability requirements.
- Industrial Grade:Standard purity methanol (99.85% minimum) serves formaldehyde and acetic acid synthesis with established ASTM D1152 specifications. Demand concentrates in East China's Ningbo and Nanjing chemical clusters where captive consumption by integrated formaldehyde plants absorbs pipeline-connected supply. MEE emissions enforcement is redirecting procurement toward natural gas-based production with lower carbon intensity profiles.
- Fuel Grade:Denatured methanol meeting ISO 8217 marine fuel standards supports dual-fuel vessel engines and methanol-to-gasoline processes. EU FuelEU Maritime regulations are pulling capacity expansions into ISCC certification schemes, creating premium pricing tiers against fossil-derived alternatives. Rotterdam and Singapore bunkering infrastructure investments are concentrating offtake around deep-sea shipping routes.
- Reagent Grade:High-purity specification (99.9%+) for analytical laboratories and semiconductor fabrication with stringent water content controls.
- Bio-Methanol:Biomass-sourced production certified under RSB or ISCC standards for EU marine fuel compliance and carbon border adjustment mechanisms.
Leading the category by volume: Industrial Grade. Growing fastest: Fuel Grade.
End Use Industry:
Margin stability varies with customer concentration and contract duration across these demand pools.
- Chemical Manufacturing:Formaldehyde, acetic acid, and methyl tert-butyl ether producers consume methanol as primary feedstock with long-term offtake contracting displacing spot purchasing. Large processors in Jubail and Rotterdam are locking five-year supply agreements with fixed-price escalators, concentrating procurement power with integrated petrochemical complexes.
- Energy:Methanol-to-gasoline processes and marine fuel applications represent emerging demand with regulatory-driven growth. FuelEU Maritime mandates and IMO decarbonization targets are accelerating certified-low-carbon fuel premiums that reward bio-methanol and e-methanol production pathways.
- Automotive:Fuel blending applications in emerging markets where methanol substitutes for gasoline in internal combustion adaptations.
- Electronics:High-purity reagent demand for semiconductor fabrication and display manufacturing with stable pricing power.
Dominant by contract value: Chemical Manufacturing. Steepest expansion trajectory: Energy.
Application:
Volume scale inversely correlates with certification burden across these usage modes.
- Feedstock:Chemical synthesis applications in formaldehyde, acetic acid, and olefin production represent baseline demand with established logistics infrastructure. China's dual carbon goals and MEE emissions rules are reshaping supplier economics toward lower-carbon production pathways.
- Fuel:Marine bunkering, methanol-to-gasoline, and stationary power generation applications face infrastructure coordination risk between fuel suppliers and vessel operators. Port storage and fueling systems require capital deployment ahead of fleet conversion.
- Solvent:Paint, coating, and adhesive formulations with stable demand in specialty chemical processing.
- Antifreeze:De-icing and coolant applications in automotive and aviation sectors with seasonal demand patterns.
Highest throughput: Feedstock. Gaining share fastest: Fuel.
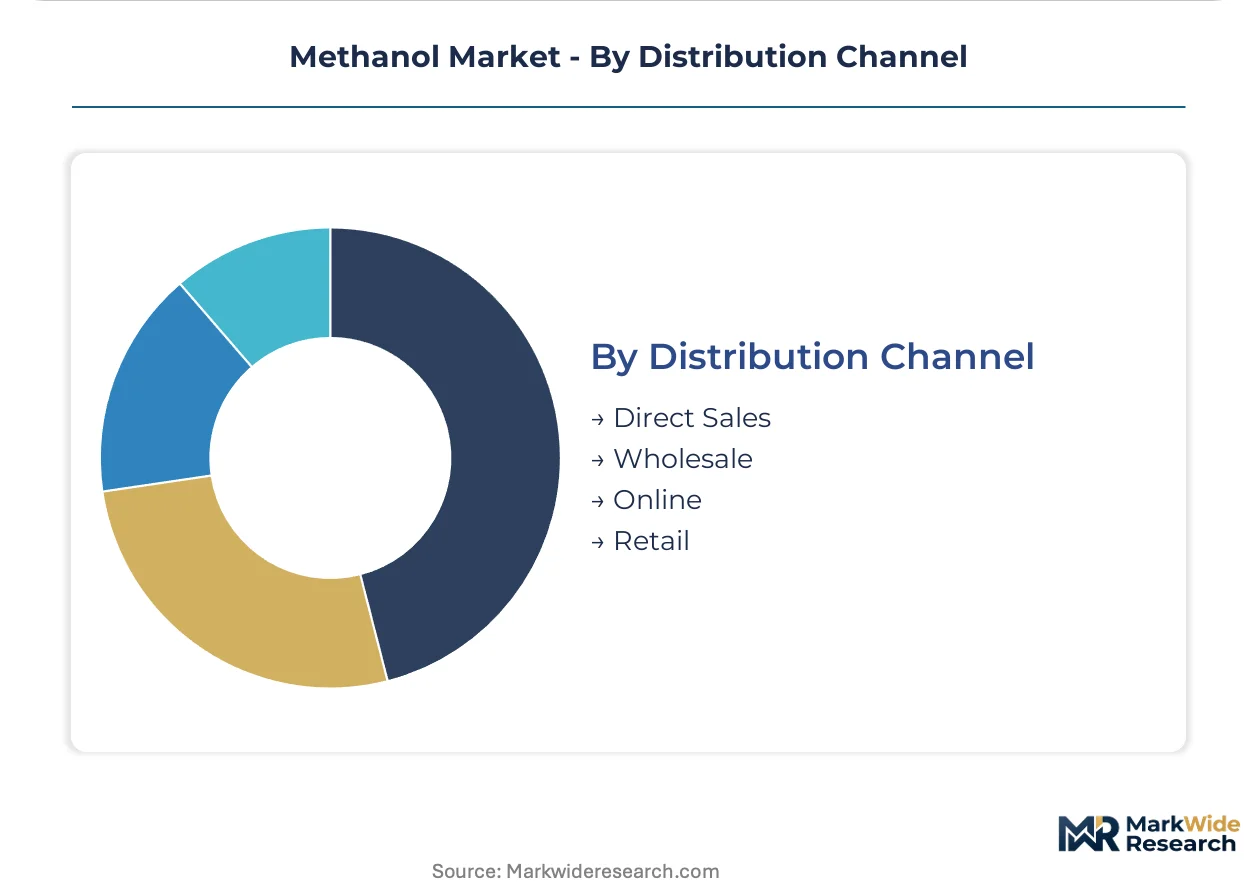
Distribution Channel:
Relationship intensity and technical service requirements shape channel selection.
- Direct Sales:Long-term supply contracts with integrated chemical complexes and marine fuel suppliers requiring dedicated logistics coordination. Methanex Corporation leverages global marine logistics networks to sustain supply continuity across multiple continents.
- Wholesale:Regional distributors serving fragmented specialty solvent users with smaller volume requirements and shorter lead times.
- Online:Reagent grade procurement for analytical laboratories with specification documentation and certificate of analysis requirements.
- Retail:Small-volume packaging for maintenance, repair, and operations applications in industrial facilities.
Controlling volume share: Direct Sales. Expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for methanol concentrates in East China around the Ningbo and Nanjing chemical clusters, with procurement patterns shifting toward low-carbon production pathways under tightening emissions enforcement.
China
Formaldehyde and acetic acid plants in Jiangsu and Zhejiang provinces drive captive consumption of pipeline-connected supply. MEE emissions caps are idling high-carbon coal gasification assets in Shanxi and Inner Mongolia while favoring natural gas-based and biomass-sourced capacity expansions. Chemical manufacturing clusters in Ningbo and Nanjing are securing long-term offtake agreements against import price volatility.
United States
Gulf Coast methanol producers leverage abundant shale gas feedstock for steam methane reforming operations. EPA standards under the Clean Air Act limit facility emissions while 45Q-style production tax credits attract project finance for blue methanol with integrated carbon capture. Houston and Beaumont industrial corridors host expanding capacity serving domestic formaldehyde and export fuel markets.
Germany
Ruhr Valley chemical complexes anchor European demand for high-purity reagent grades in pharmaceutical and electronics applications. EU F-Gas Regulation and REACH framework govern carbon intensity reporting for imported methanol derivatives. Rotterdam bunkering infrastructure investments are concentrating marine fuel offtake for dual-fuel vessel engines on deep-sea shipping routes.
Saudi Arabia
Jubail integrated petrochemical complexes achieve feedstock-to-derivative cost efficiencies through captive methanol output. Domestic demand from formaldehyde and methyl tert-butyl ether synthesis absorbs regional production. SABIC anchors output within this complex, sustaining supply continuity across multiple derivative chains.
South Korea
Ulsan and Yeosu industrial zones host methanol-consuming olefin production and marine fuel blending operations. MFDS oversees chemical handling standards while domestic shipyards accelerate dual-fuel vessel construction. Port storage and fueling system investments are co-locating with industrial zones to serve emerging bunkering demand.
Methanol Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certified-low-carbon fuel certification and e-methanol pathways. The supplier base consolidates around integrated petrochemical complexes with captive consumption and merchant producers with global marine logistics networks. Three archetypes dominate: Gulf Coast gas-based operators, East Asian coal-to-chemical incumbents, and European bio-methanol specialists. Competitive moves center on long-term offtake contracting with fixed-price escalators and ISCC certification investments for EU marine fuel compliance.
Within the integrated complex tier, Methanex Corporation and SABIC exemplify divergent geographic strategies. Methanex leverages global marine logistics networks to sustain supply continuity across multiple continents. SABIC anchors output within its Jubail integrated complex, achieving feedstock-to-derivative cost efficiencies. BASF SE occupies a position in the high-purity specialty tier, serving European pharmaceutical and electronics customers through R&D-intensive reagent grades.
| Leading Market Players |
|---|
| Methanex Corporation |
| SABIC |
| Celanese Corporation |
| BASF SE |
| Mitsubishi Gas Chemical Company |
| OCI N.V. |
| Petronas |
| Yankuang Energy Group |
| Zagros Petrochemical Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracting by formaldehyde and acetic acid producers is compressing spot market liquidity and forcing merchant suppliers toward fixed-price escalator structures. This procurement consolidation redirects supply chain investment toward pipeline-connected capacity in Ningbo and Nanjing chemical clusters.
Pricing Analysis
Volume flows through industrial grade methanol at commodity spot benchmarks while margin pools concentrate in certified-low-carbon fuel grades. Price differentiation hinges on ISCC certification status for EU marine fuel compliance and carbon intensity scores for CBAM-covered derivative exports. Pricing pressure stems from natural gas feedstock volatility in steam methane reforming economics. Chemical manufacturing buyers exhibit highest price sensitivity due to feedstock-to-derivative margin compression, while marine fuel suppliers absorb premiums for certified bio-methanol.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke methanol logistics for marine bunkering and chemical feedstock delivery. Geographic supply concentration centers on China, the United States, and Saudi Arabia. Raw material dependencies draw from natural gas reserves, coal deposits, and biomass feedstocks. Single-source vulnerability runs through Strait of Malacca shipping lanes for Asia-Europe methanol trade. Distribution runs through dedicated tanker fleets and pipeline networks serving captive consumption at integrated petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methanol sector is becoming a vertical-integration race as producers pursue captive consumption through downstream formaldehyde and acetic acid assets to lock in offtake volumes.
For Market Incumbents: Hedge against coal-to-chemical margin erosion by securing natural gas supply contracts in the US Gulf Coast and Jiangsu province. Prioritize ISCC certification investments to capture EU marine fuel premiums before regulatory deadlines tighten. Backward integration into carbon capture equipment protects against MEE emissions enforcement in China. For New Entrants and Emerging Players: The price-point gap between fossil-derived industrial grade and certified bio-methanol creates entry space for e-methanol specialists with offshore wind partnerships. Target Nordic project development zones where electrolytic hydrogen economics are maturing fastest. Lead with lifecycle carbon accounting transparency to differentiate against incumbent spot suppliers. For Investors and Strategic Acquirers: The window for entry favors integrated petrochemical complexes with captive methanol consumption and established marine logistics networks. Long-term viability rests on positioning for FuelEU Maritime compliance tiers and CBAM-adjusted derivative exports. Watch for MEE permitting decisions in Jiangsu and Zhejiang as inflection signals for Chinese supply reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Capture | Blue methanol production with 45Q tax credit eligibility secures project finance in US Gulf Coast corridors. |
| Long-term Supply Agreement | Five-year fixed-price escalators with Ningbo formaldehyde plants reduce spot market exposure for merchant producers. |
| Green Certification Program | ISCC and RSB verification unlocks premium pricing tiers for EU marine bunkering contracts under FuelEU Maritime. |
| Joint Venture | Partnerships with ship operators co-locate port storage investments ahead of dual-fuel vessel fleet conversion. |
| Capacity Expansion | Natural gas-based methanol additions in Jubail and Rotterdam reinforce feedstock-to-derivative cost efficiencies. |
Methodological Framework
Independent corroboration across primary interviews with plant managers, procurement leads at downstream formaldehyde producers, marine fuel supply specialists, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE emissions disclosure databases. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates baseline chemical feedstock demand from regulatory-driven fuel grade acceleration. Segmentation dimensions include product grade tier, end-use industry, application mode, and regional production hub. CAGRs derive from production capacity buildout schedules, regulatory implementation timelines, and substitution elasticity estimates for marine fuel applications. Forecast inputs incorporate MEE enforcement intensity projections and EU CBAM phase-in schedules.
Inputs from primary stakeholder interviews and disclosed regulatory filings were available through the study window; gaps in real-time bunker fuel pricing and vessel fleet conversion rates introduce uncertainty bands around marine demand projections. Forecasts reflect documented assumptions regarding carbon border adjustment mechanisms and low-carbon fuel certification adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methylamines Market
Chemicals
Flooring Chemicals Market
Chemicals
Quaternium-15 Market
Chemicals
Global Glycol Ether Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
North America Tartaric Acid Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Inorganic Chemicals Market
Chemicals
Potassium Fluoride Market
Chemicals
Welding Chemicals Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Trimethylamine Market
Chemicals
Coal Tar Market
Chemicals
Coagulant Market