
 North America Methanol Market | 2026-2036
North America Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Methanol Market Intelligence
Market Context
A wide capital-intensity divergence between integrated producers and merchant suppliers is redrawing competitive boundaries across the North America Methanol Market. Koch Methanol St. James leverages its captive natural gas supply and Gulf Coast logistics to sustain cost leadership at its Louisiana complex. Methanex Corporation anchors its position through long-term offtake contracts and methanol-to-olefins integration, while Celanese Corporation differentiates via downstream acetyl chain specialization that consumes captive methanol volumes.
Technical and Segment Dynamics
Methanol is a light, volatile alcohol with molecular formula CH₃OH, produced primarily through steam reforming of natural gas at temperatures exceeding 800°C and pressures around 50-100 bar, serving as a foundational feedstock for formaldehyde, acetic acid, and methyl tert-butyl ether synthesis. Chemical grade methanol dominates volume throughput due to its role in formaldehyde and acetic acid manufacturing, while bio-methanol represents the fastest-expanding product category as renewable natural gas and biomass gasification pathways achieve commercial scale. Fuel grade applications occupy a narrower but strategically significant margin pool, particularly where methanol functions as a marine fuel alternative and hydrogen carrier for hard-to-abate transport segments.
Regulatory Outlook
The EPA administers Renewable Fuel Standard obligations and tailpipe emissions benchmarks that directly shape methanol blending economics and low-carbon fuel qualification pathways across the United States. OSHA enforces workplace exposure limits at 200 ppm for methanol vapor, constraining handling protocols and storage infrastructure design at production and distribution facilities. Stakeholders must monitor evolving state-level low-carbon fuel standards in California and Oregon, where credit mechanisms increasingly reward carbon intensity reductions in fuel feedstocks.
Market Dynamics
The North America Methanol Market faces structural pressure from EPA Renewable Fuel Standard obligations that mandate escalating low-carbon fuel volumes, forcing producers to reconfigure feedstock sourcing and carbon intensity accounting across Gulf Coast manufacturing corridors.
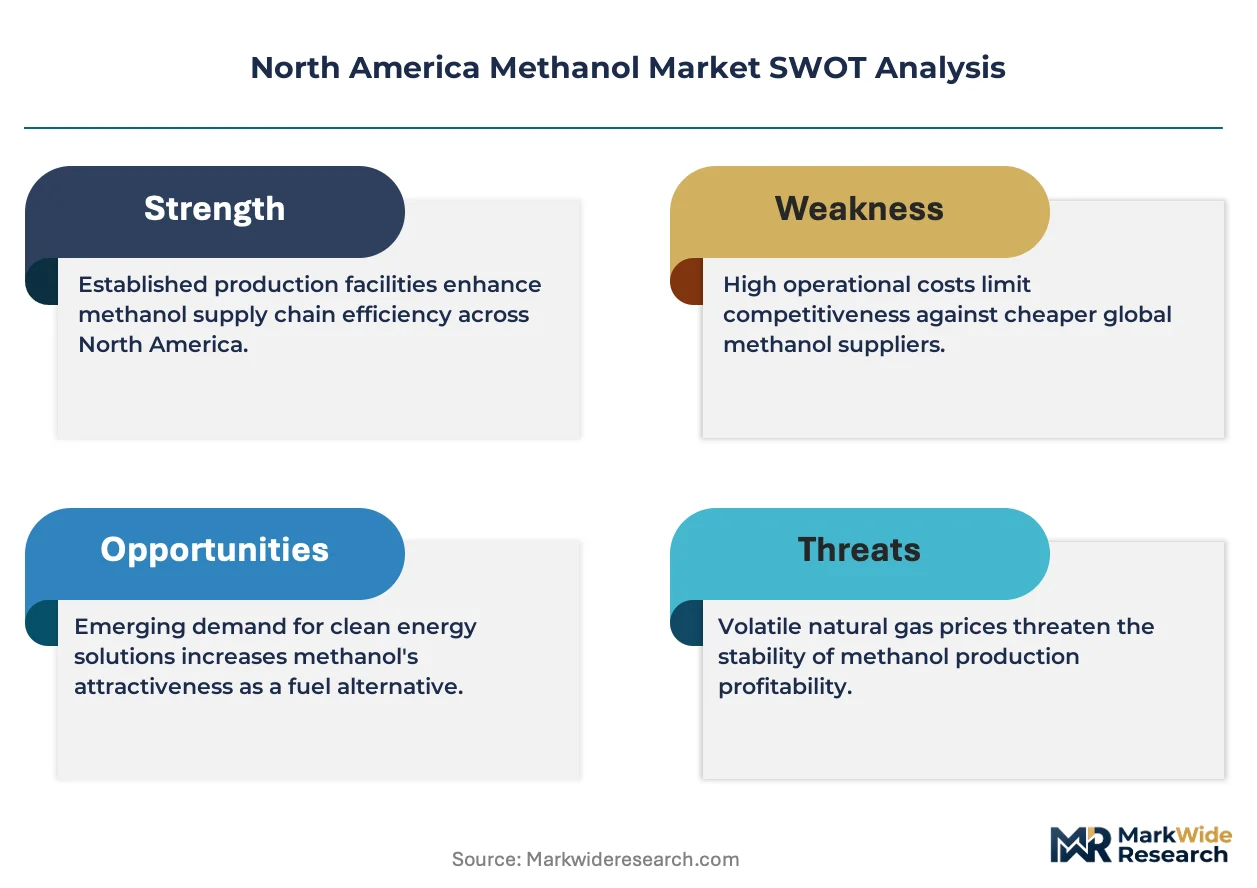
Growth Catalysts
- Marine Fuel Mandates:The International Maritime Organization's carbon intensity regulations are pulling methanol into bunkering applications at Port of Houston and Port of Long Beach terminal networks.
- Low-Carbon Fuel Standard Credits:California LCFS credit mechanisms reward carbon-negative methanol pathways derived from renewable natural gas and biomass gasification feedstocks.
- Hydrogen Carrier Economics:Methanol's liquid-state transport advantages are accelerating its adoption as a hydrogen carrier for fuel cell deployment in heavy-duty trucking corridors.
Market Restraints
- Natural Gas Price Volatility:Henry Hub price swings directly compress methanol production margins at Gulf Coast steam reforming facilities.
- Supply Concentration Risk:Texas and Louisiana host over 80 percent of North American methanol nameplate capacity, creating hurricane exposure and logistics bottlenecks.
- Electrolysis Substitution:Green hydrogen produced via renewable-powered electrolysis threatens methanol's role as a hydrogen carrier in long-haul transport applications.
Strategic Opportunities
- Canadian Carbon Capture Integration:Alberta's carbon capture utilization and storage infrastructure offers low-carbon methanol production pathways for US West Coast fuel markets.
- Methanol-to-Jet Fuel:Emerging sustainable aviation fuel specifications are opening methanol-to-kerosene synthesis routes for airline offtake contracts.
- Biogas Feedstock Convergence:Anaerobic digester methane combined with electrolytic hydrogen enables carbon-negative methanol production qualifying for Oregon Clean Fuels Program credits.
Industry Challenges
- Process Safety Expertise Gap:OSHA Process Safety Management compliance for methanol vapor handling requires specialized chemical engineering talent scarce across Louisiana and Texas petrochemical corridors.
- Carbon Intensity Certification Timeline:Third-party lifecycle carbon accounting for bio-methanol pathways faces 18-24 month validation delays at California Air Resources Board.
- Legacy Storage Infrastructure:Existing methanol tank farms at Gulf Coast terminals require corrosion-resistant lining upgrades to handle blended bio-methanol chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Methanol Market |
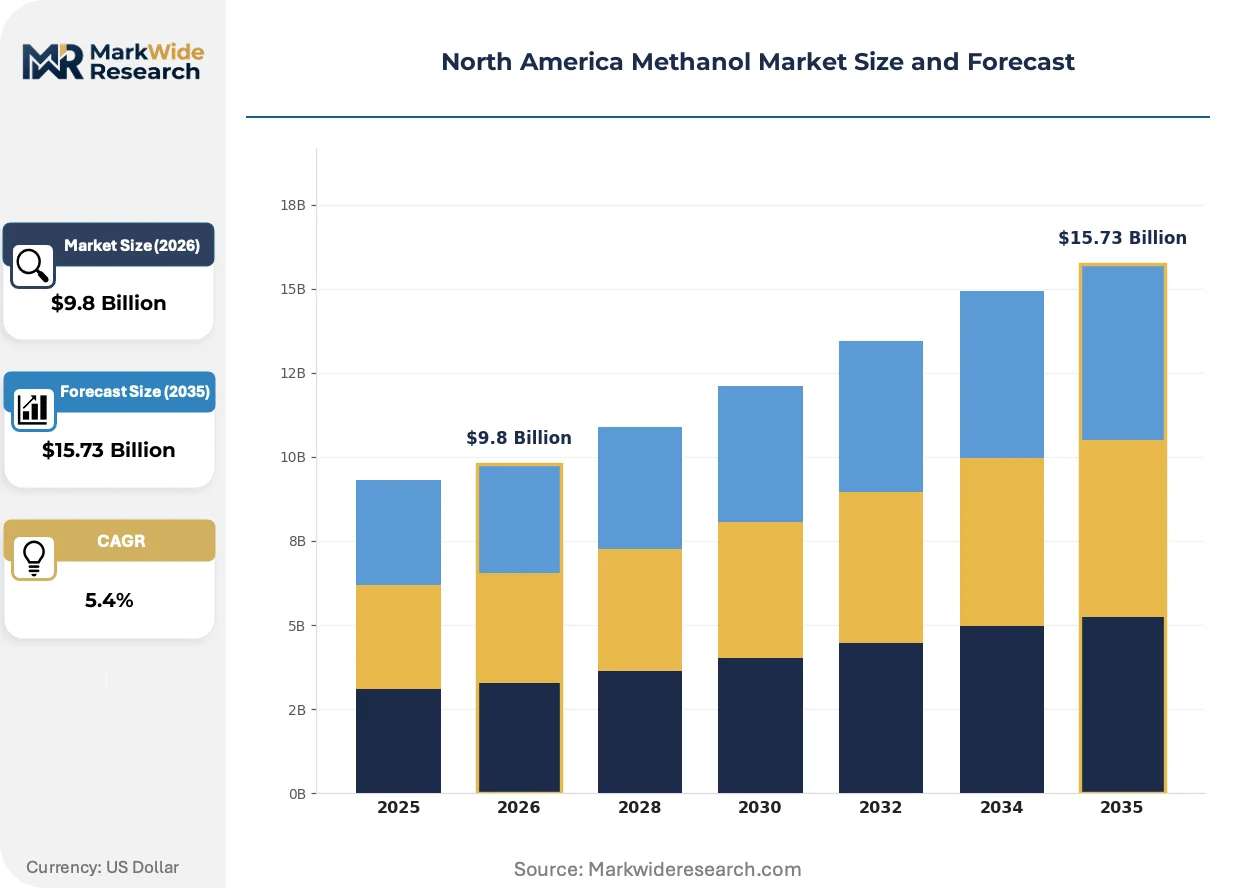
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Grade, Chemical Grade, Bio-Methanol, Specialty Methanol End User: Automotive, Chemical Industry, Energy Sector, Construction Application: Solvent, Fuel, Antifreeze, Feedstock Technology: Steam Reforming, Gas-to-Liquid, Direct Air Capture, Carbon Capture |
| Companies Covered | Koch Methanol St. James, Celanese Corporation, Methanex Corporation, Nacero, Westlake Corporation, Proman, Bia Energy, Mitsubishi Gas Chemical, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Methanol Market Strategic Shifts & Innovations
Electrolytic hydrogen integration is restructuring methanol production economics across North America, blurring boundaries between petrochemical manufacturing and power-to-x energy storage systems.
Biomass gasification combined with carbon capture is decomposing the traditional natural gas feedstock monopoly in methanol synthesis. Pulp and paper producers in the Pacific Northwest are piloting black liquor gasification pathways at commercial scale. This technology is decomposing the Gulf Coast's historical cost advantage by enabling distributed production near biomass sources.
EPA tailpipe emissions benchmarks are tightening particulate matter and nitrogen oxide limits for heavy-duty diesel engines. Methanol blending into compression-ignition fuels offers compliance pathways without aftertreatment hardware proliferation. Fleet operators in California's San Joaquin Valley are retrofitting existing diesel infrastructure for methanol dual-fuel operation.
Long-term offtake contracting is displacing spot market exposure for methanol purchasers. Chemical manufacturers consuming formaldehyde and acetic acid feedstocks are locking in decade-long supply agreements with fixed carbon intensity clauses. This pattern concentrates most visibly among specialty chemical producers in Texas Gulf Coast industrial clusters seeking supply security against natural gas price volatility.
North America Methanol Market Segmentation
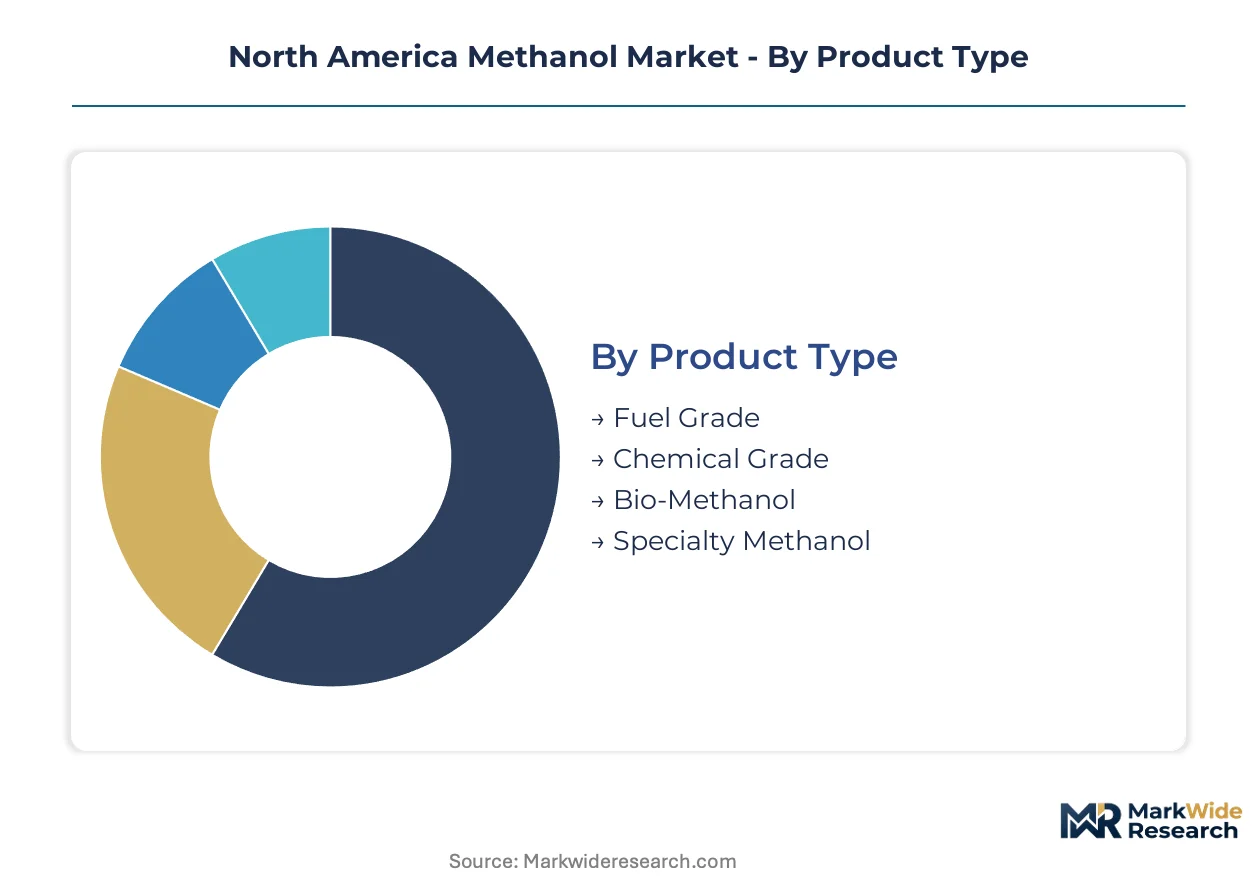
Segmentation reveals how methanol flows through distinct commercial channels in North America. Product grade determines terminal infrastructure requirements. End-use concentration shapes regional production location decisions across Texas and Louisiana corridors.
Product Type:
Fuel grade methanol moves through marine bunkering terminals and hydrogen carrier distribution networks. Chemical grade dominates pipeline flows to Gulf Coast petrochemical complexes. Bio-methanol channels through California LCFS credit verification systems before reaching West Coast fuel markets.
- Chemical Grade:Purity specifications exceed 99.85% for formaldehyde and acetic acid synthesis. Demand concentrates at Texas Gulf Coast industrial clusters where Celanese and LyondellBasell operate integrated acetyl chain facilities. OSHA storage protocols govern tank farm design at these locations.
- Fuel Grade:Blending specifications accommodate 5-15% methanol content in compression-ignition engines. California's San Joaquin Valley fleet operators represent the primary demand concentration, driven by EPA tailpipe emissions compliance for heavy-duty diesel retrofits.
- Bio-Methanol:Renewable natural gas and biomass gasification pathways qualify for Oregon Clean Fuels Program credits. Pacific Northwest pulp and paper producers pilot black liquor gasification at commercial scale.
- Specialty Methanol:Ultra-high purity grades serve pharmaceutical and electronics applications requiring sub-ppm contaminant thresholds. Distribution runs through dedicated chemical distributor networks rather than commodity terminals.
By volume, Chemical Grade leads. By growth pace, Bio-Methanol is ahead.
End User:
Cost tier differentiation separates commodity chemical buyers from premium fuel applications. Automotive and energy sector procurement patterns reflect carbon intensity accounting requirements absent in construction and basic chemicals.
- Automotive:Heavy-duty trucking corridors in California deploy methanol dual-fuel retrofits for EPA compliance. Fleet operators negotiate long-term offtake contracts with fixed carbon intensity clauses.
- Chemical Industry:Formaldehyde and acetic acid manufacturers consume captive methanol volumes at integrated Gulf Coast complexes. Methanex and Koch Methanol St. James anchor supply through decade-long agreements.
- Energy Sector:Hydrogen carrier applications for fuel cell deployment concentrate at Port of Houston bunkering terminals. International Maritime Organization regulations pull methanol into marine fuel blending.
- Construction:Formaldehyde-based resins for engineered wood products drive steady demand. This segment accepts wider specification tolerances than pharmaceutical or fuel applications.
Automotive procurement carries the steepest carbon intensity requirements. Construction maintains the most price-sensitive buying patterns.
Application:
Volume concentration favors feedstock applications, while margin pools concentrate in fuel and solvent specialties where regulatory compliance creates pricing power.
- Feedstock:Steam reforming output flows primarily to formaldehyde, acetic acid, and methyl tert-butyl ether synthesis. Gulf Coast petrochemical infrastructure supports 80% of North American nameplate capacity.
- Fuel:Marine bunkering at Port of Long Beach and Port of Houston expands rapidly under International Maritime Organization carbon intensity regulations. Methanol-to-hydrogen conversion for heavy-duty trucking follows California LCFS credit mechanics.
- Solvent:Paint and coating formulations require technical grade specifications. Demand tracks construction activity cycles in Texas and California metropolitan areas.
- Antifreeze:Seasonal demand peaks concentrate in Midwest and Northeast distribution networks. This application competes directly with ethylene glycol on price.
Feedstock absorbs the largest volume share. Fuel applications show the steepest expansion trajectory.
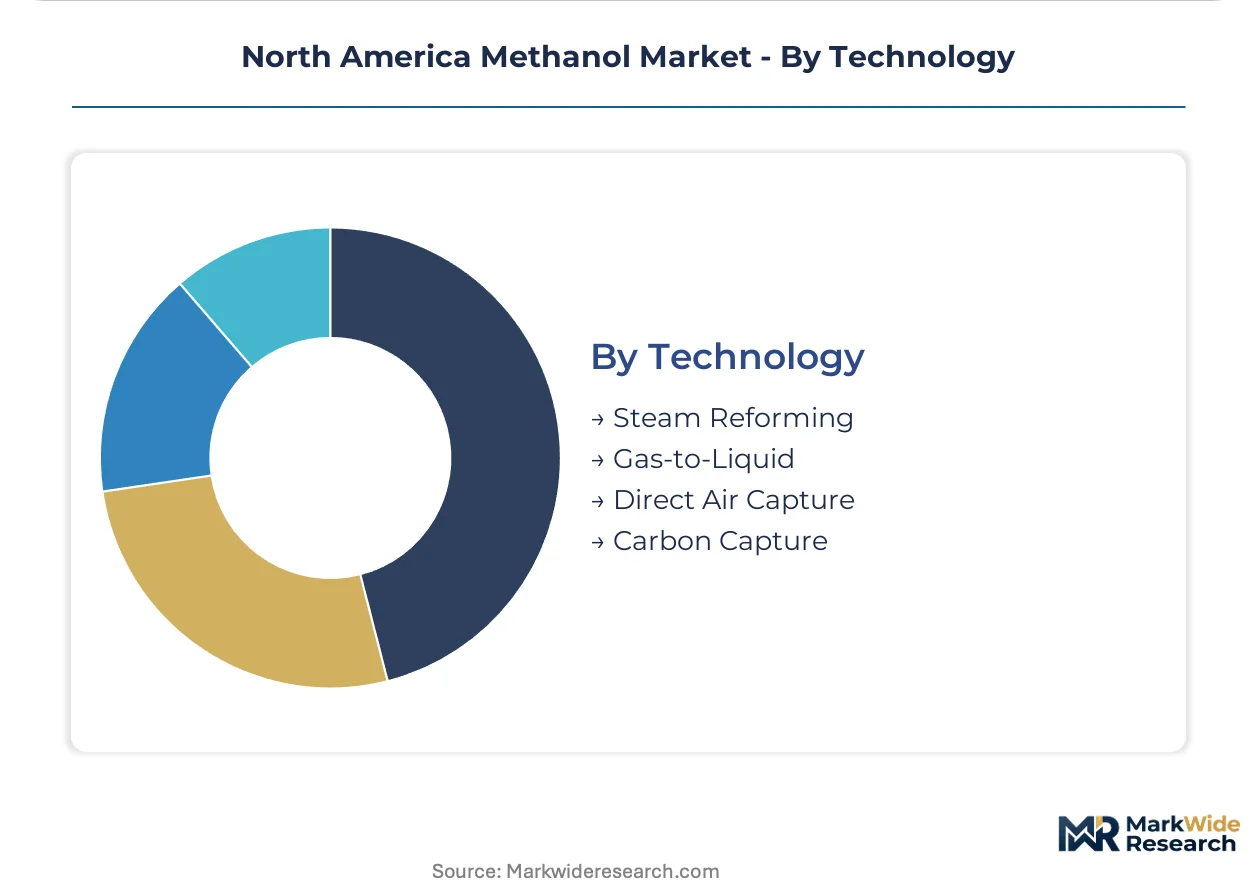
Technology:
Supply concentration in steam reforming creates vulnerability to Henry Hub price volatility. Emerging technologies fragment production geography toward biomass sources and carbon capture hubs.
- Steam Reforming:Natural gas feedstock processing at 800°C+ and 50-100 bar dominates Gulf Coast manufacturing. Koch Methanol St. James leverages captive gas supply for cost leadership.
- Gas-to-Liquid:Small-scale distributed production enables stranded gas monetization. Alberta oilfield operators pilot modular units for remote flare gas conversion.
- Carbon Capture:Alberta's carbon capture utilization and storage infrastructure enables low-carbon methanol pathways for US West Coast fuel markets. Third-party lifecycle validation faces 18-24 month delays at California Air Resources Board.
- Direct Air Capture:Power-to-x integration with electrolytic hydrogen remains pre-commercial. Pacific Northwest renewable power availability supports pilot scale deployment.
Steam Reforming retains volume leadership. Carbon Capture offers the most rapid pathway to LCFS credit qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates methanol consumption through chemical feedstock demand, while Canada and Mexico pursue divergent pathways centered on carbon capture integration and industrial fuel substitution respectively.
United States
EPA Renewable Fuel Standard obligations and California LCFS credit mechanisms pull methanol into marine bunkering at Port of Houston and hydrogen carrier deployment in San Joaquin Valley trucking corridors. OSHA Process Safety Management compliance constrains storage infrastructure design across Texas and Louisiana petrochemical clusters. Gulf Coast manufacturing corridors host over 80 percent of North American nameplate capacity, with Koch Methanol St. James leveraging captive natural gas supply for cost leadership.
Canada
Alberta's carbon capture utilization and storage infrastructure enables low-carbon methanol production pathways targeting US West Coast fuel markets. Federal clean fuel regulations and provincial carbon pricing systems reward carbon-negative production routes. Pacific Northwest pulp and paper producers pilot black liquor gasification at commercial scale, decomposing traditional Gulf Coast cost advantages through distributed biomass-based manufacturing.
Mexico
Industrial fuel substitution in manufacturing corridors drives methanol demand for process heating and captive power generation. Energy sector liberalization programs and industrial development initiatives in northern border states support petrochemical infrastructure expansion. Monterrey-based industrial clusters increasingly source methanol for formaldehyde resin production serving construction and automotive supply chains.
North America Methanol Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Gulf Coast petrochemical infrastructure determining competitive positioning. The market structure concentrates around natural gas supply access and long-term offtake contracting. Three archetypes dominate: integrated chemical conglomerates with captive methanol consumption, dedicated methanol producers with merchant market exposure, and emerging low-carbon specialists pursuing bio-methanol pathways. Capacity expansion and strategic partnerships constitute the primary competitive moves, with carbon intensity certification increasingly shaping partnership selection.
Within the integrated chemical tier, Celanese Corporation exemplifies downstream acetyl chain specialization that consumes captive methanol volumes. Methanex Corporation anchors the dedicated producer archetype through long-term offtake arrangements and methanol-to-olefins integration. Koch Methanol St. James occupies a distinctive position combining captive natural gas supply with Gulf Coast logistics infrastructure for cost leadership.
| Leading Market Players |
|---|
| Koch Methanol St. James |
| Celanese Corporation |
| Methanex Corporation |
| Nacero |
| Westlake Corporation |
| Proman |
| Bia Energy |
| Mitsubishi Gas Chemical |
| SABIC |
| Others |
Cost & Logistics Intelligence
California LCFS credit mechanisms gate both supply qualification and price differentiation across North American methanol channels, rewarding carbon-negative pathways with premium valuations while excluding conventional steam-reformed volumes from West Coast fuel markets. EPA Renewable Fuel Standard obligations compound this bifurcation, forcing producers to choose between commodity chemical pricing and certified low-carbon premiums.
Pricing Analysis
Long-term offtake contracts dominate procurement between Gulf Coast producers and formaldehyde manufacturers, locking in decade-long supply agreements with fixed carbon intensity clauses that insulate buyers from Henry Hub volatility. Spot market exposure concentrates among marine bunkering terminals at Port of Houston, where IMO compliance deadlines compress pricing windows. Price differentiation separates bio-methanol qualifying for Oregon Clean Fuels Program credits from chemical grade volumes tied to acetic acid margins. Fleet operators in California's San Joaquin Valley exhibit the steepest price sensitivity, while specialty chemical producers accept wider specification tolerances for supply security.
Supply Chain Analysis
Hurricane exposure across the Houston Ship Channel creates a chokepoint that can sever methanol flows to Atlantic Coast terminals for weeks, amplifying price spikes during storm seasons. Production concentrates in the United States, Canada, and Mexico, with over 80 percent of nameplate capacity clustered in Texas and Louisiana Gulf Coast corridors. Feedstock dependence draws from Henry Hub-indexed natural gas, renewable natural gas from anaerobic digesters, and black liquor gasification at Pacific Northwest pulp facilities. Tariff exposure on Canadian carbon-captured methanol threatens West Coast supply diversification. Distribution runs through dedicated chemical terminals at Port of Long Beach and dedicated pipeline networks to Gulf Coast petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine fuel mandates from the International Maritime Organization signal early-cycle expansion for methanol bunkering infrastructure, with adoption curves steepening at Port of Houston and Port of Long Beach terminal networks.
For Market Incumbents: Shield integrated acetyl chain positions by securing captive renewable natural gas supply for bio-methanol qualification pathways, while adding corrosion-resistant tank lining capacity at Gulf Coast terminals to handle blended bio-methanol chemistries. Electrolytic hydrogen substitution for long-haul hydrogen carrier applications demands defensive certification investment in carbon capture integration. For New Entrants and Emerging Players: Differentiate on black liquor gasification feedstocks in the Pacific Northwest, where pulp and paper producers can pilot commercial-scale production without competing for Gulf Coast natural gas supply. The most penetrable white space sits in Oregon Clean Fuels Program credit qualification, with anaerobic digester methane combined with electrolytic hydrogen enabling carbon-negative production. A go-to-market angle anchored in sustainable aviation fuel offtake contracts with West Coast airlines bypasses entrenched chemical grade competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular gas-to-liquid units, enabling stranded gas monetization by Alberta oilfield operators and distributed production economics. Long-term viability favors acquisition targets with certified low-carbon pathways and existing California Air Resources Board validation timelines rather than conventional steam-reforming assets. The signal to watch is third-party lifecycle carbon accounting approval delays, which currently stretch 18-24 months and gate premium pricing realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Natural Gas | Secures bio-methanol feedstock supply qualifying for California LCFS credits. |
| Carbon Capture Integration | Enables low-carbon methanol production pathways targeting US West Coast fuel markets. |
| Long-term Supply Agreement | Locks in decade-long offtake with chemical manufacturers consuming formaldehyde feedstocks. |
| Joint Venture | Combines pulp producer biomass access with methanol synthesis expertise for black liquor gasification. |
| Green Certification Program | Accelerates Oregon Clean Fuels Program credit qualification through third-party carbon intensity validation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including plant managers at Gulf Coast steam reforming facilities, procurement leads at formaldehyde and acetic acid manufacturers, marine bunkering terminal operators at Port of Houston, and regulatory affairs specialists navigating California Air Resources Board certification timelines. Secondary validation drew from EPA Renewable Fuel Standard filings, EIA natural gas price data, IMO marine fuel regulations, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up volume estimates from individual production facilities were triangulated against top-down demand assessments from end-use consumption patterns.
Across the analysis window, the forecasting framework modeled methanol flows through segmentation dimensions spanning product grade tier, end-use industry concentration, application type, and regional production hub configuration. CAGRs were derived from regression analysis of historical capacity additions correlated with natural gas price trajectories and regulatory credit value evolution. Industry-specific inputs included Henry Hub forward curves, California LCFS credit price volatility, and IMO carbon intensity reduction timelines for marine vessels.
The analysis sits within stated boundaries; outcomes outside sustained California LCFS credit premiums or stable Henry Hub pricing would require recalibration. Forecasts reflect assumptions regarding EPA tailpipe emissions enforcement continuity and third-party carbon accounting validation throughput at state regulatory bodies. Practitioners should keep alternative scenarios live as International Maritime Organization marine fuel mandate implementation timelines and electrolytic hydrogen cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Hexachloroethane Market
Chemicals
Xanthates Market
Chemicals
Thioacetic Acid Market
Chemicals
Chemical As a Service Market
Chemicals
Glyoxal Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Welding Chemicals Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Global Pine Chemicals Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Lanthanum Nitrate Market